
 North America Thermoformed Plastics Market | 2026-2036
North America Thermoformed Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Thermoformed Plastics Market Intelligence
Multi-source resin procurement is hardening across the North American thermoforming base as converters buffer against polypropylene supply volatility. Pactiv Evergreen leverages its integrated fiber and plastics network to sustain packaging volume commitments to quick-service restaurant chains. Sonoco Products anchors its position through captive recycling streams that feed thin-gauge sheet extrusion. Genpak competes aggressively in the clamshell segment, where price transparency and tooling amortization cycles determine contract renewals.
Thermoformed plastics are sheet-based thermoplastic articles shaped by vacuum, pressure, or mechanical forming above glass-transition temperature, typically produced from roll-fed stock ranging from 0.005 to 0.500 inches thick and selected for barrier properties, clarity, or impact resistance depending on end-use. Their primary commercial purpose spans protective packaging, food service disposables, and sterile medical containment where unit cost and part-to-part consistency outweigh structural performance. Polypropylene sheet leads material consumption due to its balance of chemical resistance and microwave compatibility, though polyethylene gains ground in cold-chain applications where flexibility and sealability matter more than heat tolerance. Thin gauge dominates production volume across blister packs and trays, but thick gauge thermoforming in industrial pallets and dunnage commands margin pools that offset slower line speeds and custom tooling burdens.
The US FDA regulates food-contact notifications for all virgin and post-consumer recycled resins entering thermoformed food packaging, while EPA emissions standards constrain solvent-based printing and adhesive operations at conversion facilities. Health Canada and PMRA coordinate cross-border chemical approvals that affect resin formulations sold into Ontario and Quebec processing plants. Stakeholders must monitor state-level extended producer responsibility legislation advancing in California, Oregon, and Colorado, where recycled content mandates will reshape material qualification timelines and supplier certification requirements.
Market Dynamics
Polypropylene supply volatility is forcing North American thermoformers to reconfigure resin procurement networks, with converters diversifying feedstock sources to maintain thin-gauge sheet extrusion continuity.
Growth Catalysts
- Food packaging substitution:Quick-service restaurant chains across the United States and Mexico are replacing rigid containers with thermoformed trays to reduce shipping cube and improve microwave compatibility.
- Recycled content mandates:Extended producer responsibility legislation advancing in California, Oregon, and Colorado creates compliance-driven demand for post-consumer recycled resin qualification.
- Captive recycling infrastructure:Integrated fiber and plastics networks enable converters to secure food-grade recycled feedstock streams that bypass virgin resin spot markets.
Market Restraints
- Propylene monomer volatility:Crude-linked feedstock pricing and refinery output fluctuations destabilize polypropylene sheet cost structures for thin-gauge converters.
- FDA notification timelines:Food-contact substance review periods for novel recycled resins extend material qualification cycles, delaying new product commercialization.
- Alternative substrate competition:Molded fiber and aluminum trays capture premium food-service segments where heat tolerance exceeds thermoplastic limits.
Strategic Opportunities
- Medical sterile containment:Hospital systems and pharmaceutical distributors seek barrier-optimized thermoformed trays for surgical kit packaging and device protection.
- Cold-chain polyethylene expansion:E-commerce grocery fulfillment centers in the Great Lakes corridor drive demand for flexible, sealable polyethylene formats over rigid alternatives.
- State-level EPR tailwinds:Colorado's recycled content mandates and California's plastic pollution reduction requirements create preferential procurement channels for certified post-consumer resin suppliers.
Industry Challenges
- Tooling amortization compression:Clamshell contract renewals demand shorter payback periods on custom molds, squeezing converter margins on medium-volume programs.
- Cross-border chemical harmonization:Health Canada and PMRA coordination delays create formulation bottlenecks for resins sold into Ontario and Quebec processing plants.
- Emissions compliance retrofit costs:EPA standards for solvent-based printing operations require capital expenditure at conversion facilities with legacy adhesive systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Thermoformed Plastics Market |
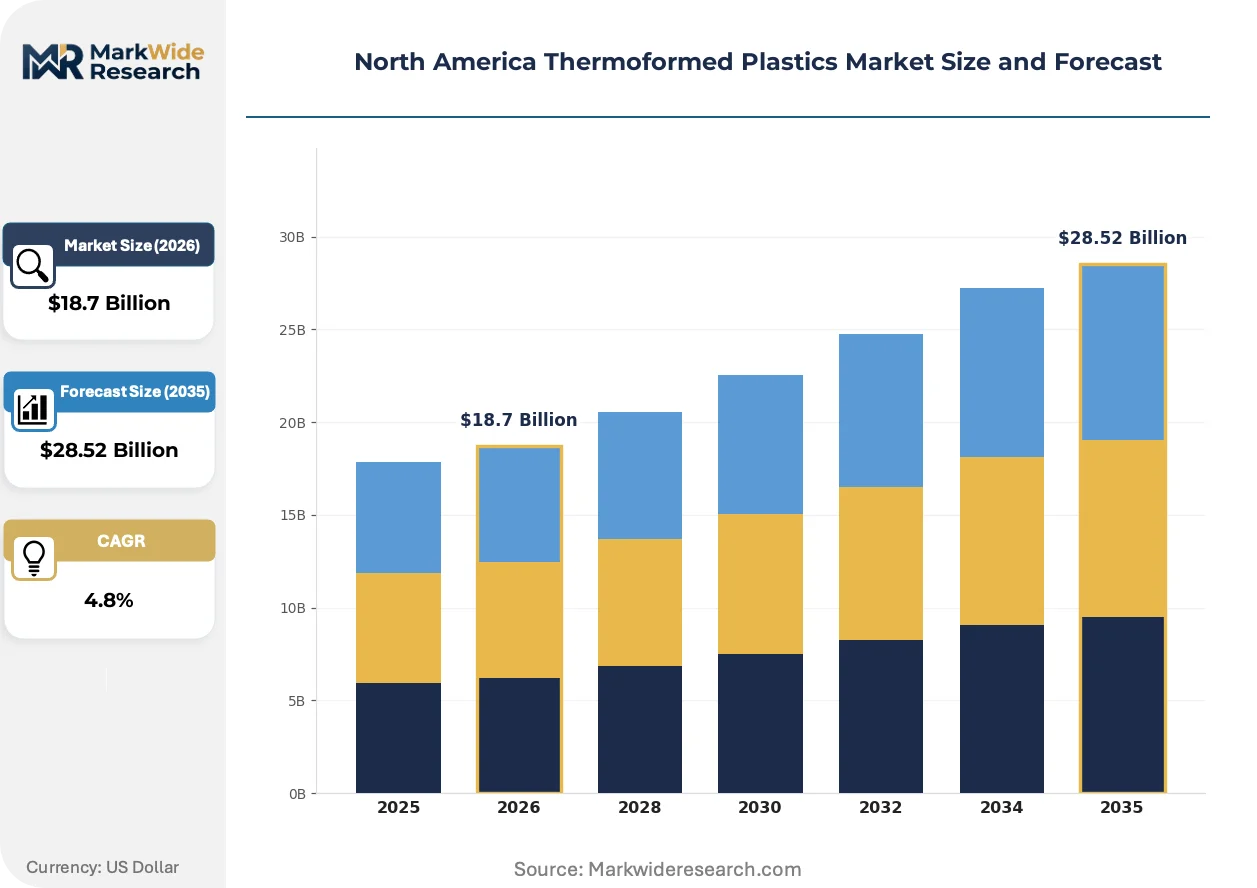
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Clamshells, Trays, Containers Material: Polyethylene, Polypropylene, Polystyrene, ABS End User: Food Packaging, Consumer Goods, Electronics, Medical Thickness: Thin Gauge, Medium Gauge, Thick Gauge, Ultra-Thin |
| Companies Covered | Pactiv Evergreen, Genpak, Sonoco Products, Packaging Corp of America, Placon, Brentwood Industries, Palram Industries, CM Packaging, Greiner Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Thermoformed Plastics Market Strategic Shifts & Innovations
Digital tooling workflows and advanced thermoforming controls are compressing product development cycles, while regulatory pressure on recycled content reshapes material specifications across food and medical packaging.
In-line sheet extrusion with real-time thickness gauging is consolidating control over gauge consistency and barrier uniformity. Medical device manufacturers and food processors are adopting these integrated lines to reduce lot-to-lot variation. The technology is consolidating smaller converters' ability to compete on specification-grade contracts that previously required dedicated quality infrastructure.
California's plastic pollution reduction requirements and extended producer responsibility frameworks in Oregon and Colorado are tightening recycled content thresholds for food-contact applications. Thermoformers must now maintain dual qualification tracks for virgin and post-consumer resin streams. The Great Lakes manufacturing corridor faces the steepest compliance burden as the densest concentration of food packaging conversion capacity.
Quick-service restaurant chains are consolidating supplier relationships around multi-year volume commitments with tooling cost recovery mechanisms. Single-source procurement models with penalty clauses for supply interruption are displacing spot-market purchasing for tray and container programs. This concentration is most visible in the Michigan-Ohio-Illinois cluster where equipment density supports just-in-time delivery requirements.
North America Thermoformed Plastics Market Segmentation
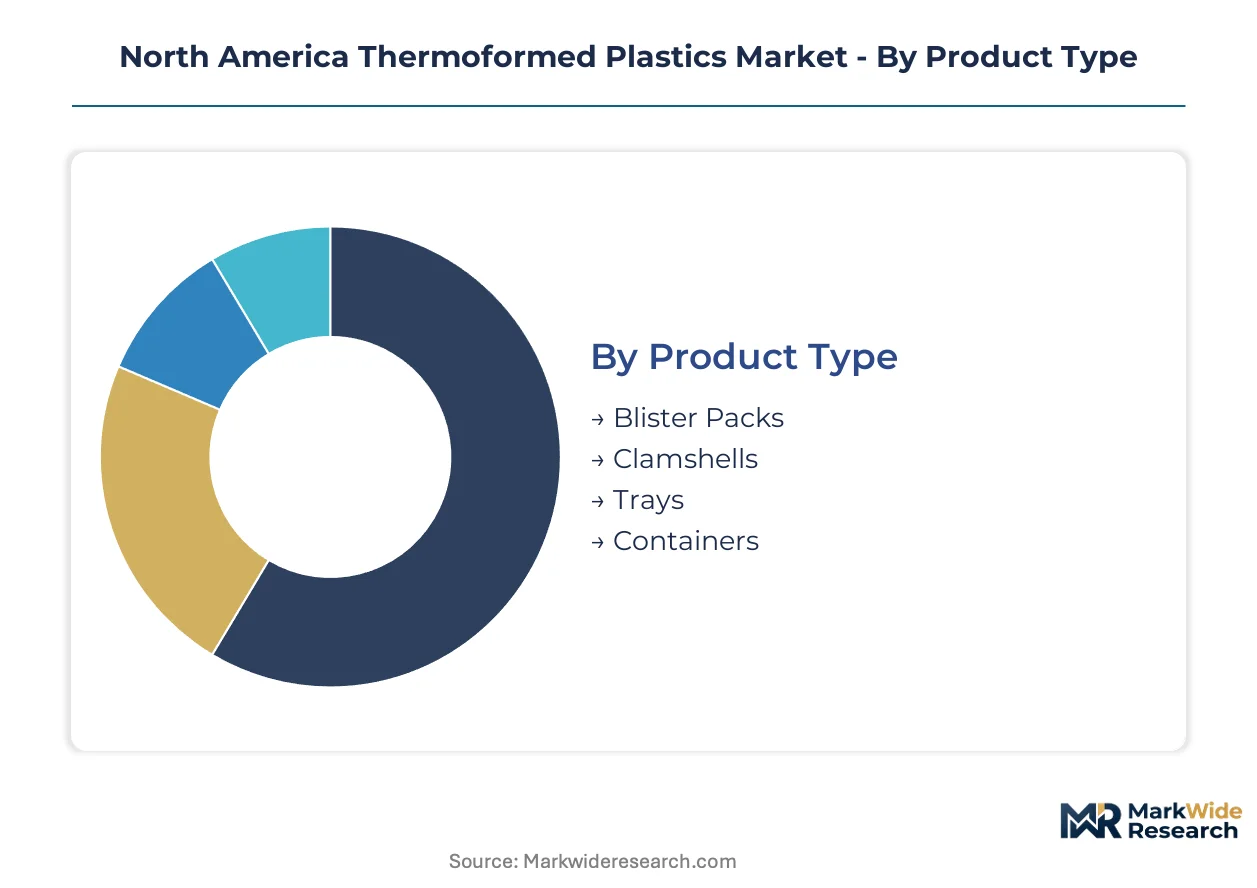
Thermoformed plastics demand fragments across specification axes that determine tooling investment, line speed economics, and regulatory qualification burdens. Each segmentation dimension carries distinct margin profiles and competitive intensity patterns.
Product Type:
Forming method and part geometry dictate tooling complexity and cycle time economics across the converter base.
- Trays:Roll-fed vacuum forming produces shallow-draw configurations with minimal draft angles for food service and medical kit containment. Quick-service restaurant chains across Michigan, Ohio, and Illinois consolidate procurement around multi-year tray programs with integrated recycling commitments.
- Clamshells:Twin-sheet pressure forming creates hinged containers with snap-fit closures for retail display protection. Price transparency and compressed tooling amortization cycles dominate contract negotiations in consumer electronics packaging.
- Blister Packs:Clear PVC or PETG cavities sealed to printed cards protect pharmaceuticals and small consumer goods.
- Containers:Deep-draw pressure-formed vessels with integral handles serve industrial and food storage applications.
Trays lead on scale; clamshells lead on momentum.
Material:
Resin selection balances chemical resistance, thermal tolerance, and recycled content compliance against FDA notification requirements.
- Polypropylene:Semicrystalline thermoplastic with broad chemical resistance and microwave compatibility dominates food-contact applications. Supply volatility across propylene monomer markets forces converters toward multi-source procurement strategies.
- Polyethylene:Flexible, sealable grades capture cold-chain logistics demand from e-commerce grocery fulfillment centers in the Great Lakes corridor.
- Polystyrene:Amorphous resin selected for clarity and printability in retail display packaging.
- ABS:Engineering thermoplastic with impact resistance serves industrial dunnage and durable goods protection.
Polypropylene commands volume concentration; polyethylene gains share fastest.
End User:
Application-specific barrier and sterility requirements segment qualification timelines and certification burdens.
- Food Packaging:FDA food-contact substance notifications govern all virgin and post-consumer recycled resin streams. California, Oregon, and Colorado extended producer responsibility mandates reshape material qualification priorities.
- Medical:Sterile barrier systems for surgical kits and device protection demand validated forming processes with lot traceability.
- Consumer Goods:Visual merchandising requirements drive clarity and printability specifications in retail display.
- Electronics:Static-dissipative formulations protect sensitive components through distribution.
Food packaging anchors capacity utilization; medical commands premium positioning.
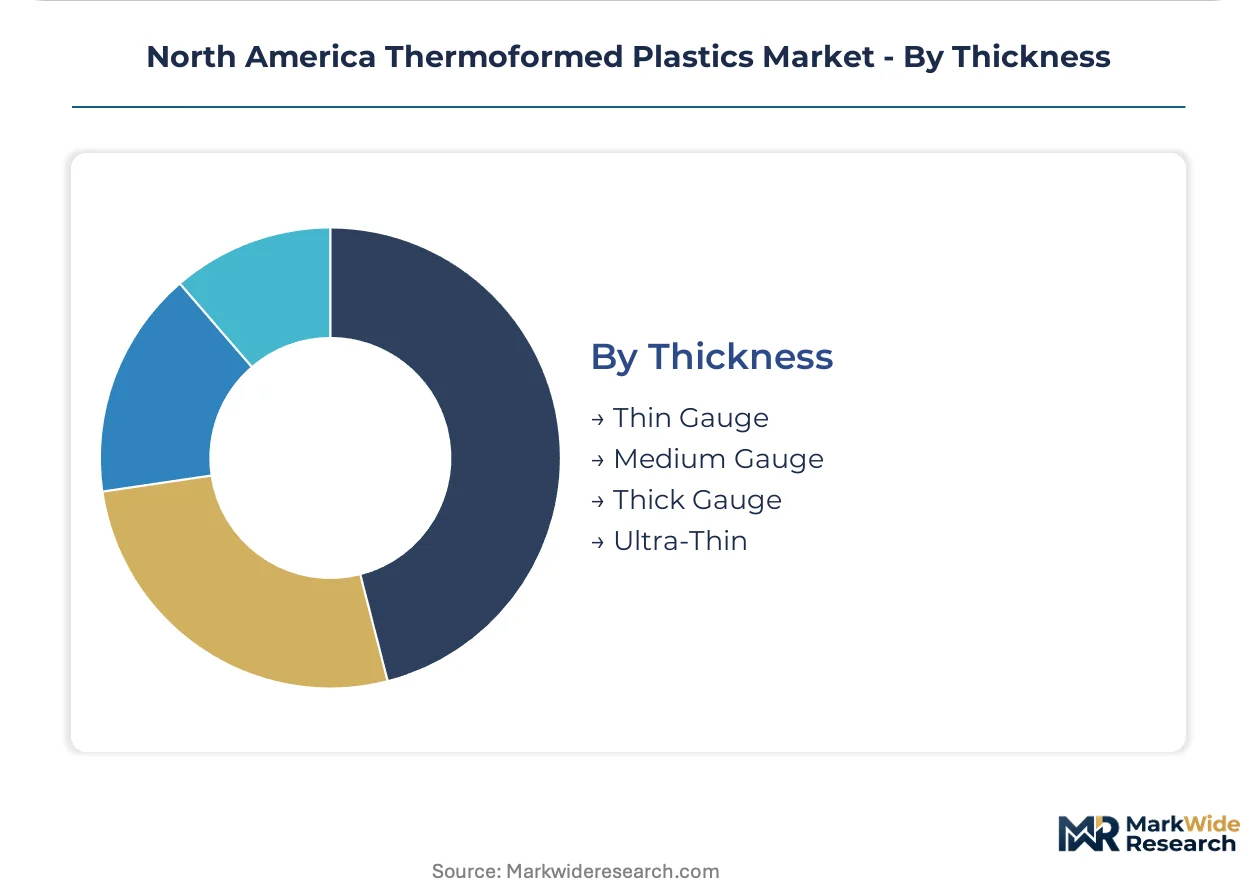
Thickness:
Gauge selection determines line speed, material yield, and structural performance tradeoffs.
- Thin Gauge:Sheet stock from 0.005 to 0.060 inches enables high-speed roll-fed forming for blister packs and shallow trays. Real-time thickness gauging systems consolidate quality control for specification-grade contracts.
- Thick Gauge:Material from 0.120 to 0.500 inches produces industrial pallets and dunnage with load-bearing capacity. Slower line speeds and custom tooling burdens concentrate production among specialized converters.
- Medium Gauge:Intermediate thickness balances forming speed with structural rigidity.
- Ultra-Thin:Minimal-gauge formats reduce material intensity in single-use disposables.
Thin gauge dominates production velocity; thick gauge captures margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes manufacturing corridor spanning Michigan, Ohio, and Illinois anchors North American thermoformed plastics capacity, where resin distribution infrastructure and equipment density cluster to serve food packaging and medical containment demand.
United States
Quick-service restaurant chains across the Midwest and Southeast are consolidating multi-year tray procurement contracts with integrated recycling commitments. The FDA's updated food-contact substance notifications are extending qualification timelines for post-consumer recycled resins entering food packaging streams. The Michigan-Ohio-Illinois corridor maintains the densest concentration of thin-gauge sheet extrusion and thermoforming equipment, supporting just-in-time delivery to food processors and medical device manufacturers.
Canada
Ontario and Quebec processing plants are scaling output for cross-border food packaging supply chains serving US retail and foodservice distributors. Health Canada and PMRA coordinate chemical approval frameworks that create formulation bottlenecks for resin suppliers seeking dual-market qualification. The Greater Toronto Area hosts specialized converters serving pharmaceutical sterile barrier applications with validated forming processes and lot traceability systems.
Mexico
Food packaging buyers are accelerating thermoformed tray and container procurement to replace rigid alternatives in quick-service restaurant and retail fresh produce segments. Mexican regulators align with US FDA notification requirements for food-contact materials while maintaining distinct labeling standards for domestic consumption. The Mexico City Metro and Nuevo León industrial zones concentrate conversion capacity serving both domestic demand and export-oriented maquiladora operations.
North America Thermoformed Plastics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialty medical and cold-chain formats to differentiate beyond commodity food packaging. The North American thermoformed plastics base exhibits moderate consolidation, with integrated fiber-plastics networks and captive recycling streams creating defensive moats around volume commitments. Three strategic archetypes dominate: resin-integrated conglomerates with backward control over sheet extrusion, recycling-focused specialists with food-grade post-consumer feedstock capabilities, and precision-forming shops targeting medical sterile barrier contracts. Capacity expansion and strategic partnerships represent the dominant competitive moves, as converters seek to secure resin supply continuity and lock in multi-year customer commitments.
Among US-based packaging conglomerates, Pactiv Evergreen and Sonoco Products exemplify the integrated archetype, leveraging captive supply networks to sustain volume commitments through resin spot market volatility. Genpak occupies a position within the specialty forming tier, competing in clamshell segments where tooling amortization cycles and price transparency determine contract renewal outcomes. These three companies anchor the competitive structure, with their strategic postures reflecting broader industry patterns of supply security pursuit and customer concentration.
| Leading Market Players |
|---|
| Pactiv Evergreen |
| Genpak |
| Sonoco Products |
| Packaging Corp of America |
| Placon |
| Brentwood Industries |
| Palram Industries |
| CM Packaging |
| Greiner Packaging |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up thermoforming specialists have consolidated fragmented converter capacity across the Great Lakes corridor, tightening working capital discipline and enforcing contract-based pricing structures that buffer resin spot volatility through multi-year offtake commitments with quick-service restaurant chains.
Pricing Analysis
Input-cost pass-through from propylene monomer markets dominates pricing mechanics, with converters indexing sheet extrusion contracts to weekly resin spot benchmarks. Price differentiation separates FDA-cleared food-grade resin formulations from general-purpose grades, while volume scale determines tooling amortization recovery timelines. Pricing pressure stems from compressed clamshell contract renewals demanding shorter mold payback periods. Quick-service restaurant chains exhibit highest price sensitivity through consolidated procurement, whereas medical sterile barrier buyers prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Michigan, Ohio, and Illinois operate hub-and-spoke patterns feeding just-in-time delivery to food processors and medical device manufacturers. Geographic supply concentrates in the United States, Canada, and Mexico, with resin compounding tethered to Gulf Coast petrochemical infrastructure and cross-border sheet extrusion. Raw material dependencies span polypropylene pellets, calcium carbonate fillers, and colorant masterbatches. Single-source vulnerability runs through propylene monomer supply from integrated refinery operations. Distribution runs through converter-direct models with limited third-party logistics penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Thermoformed Plastics Market functions as a stable compounder, with food packaging substitution and extended producer responsibility mandates delivering predictable replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Acquire captive recycling infrastructure to secure food-grade post-consumer resin streams that bypass virgin spot markets. Consolidate thin-gauge sheet extrusion capacity in the Michigan-Ohio-Illinois corridor to defend against emerging entrants with regional distribution advantages. Backward integration into resin compounding offsets propylene monomer volatility threatening margin stability. For New Entrants and Emerging Players: Quick-service restaurant chains represent the most penetrable channel partner type for specialty tray formats with integrated recycling commitments. Cold-chain polyethylene applications in e-commerce grocery fulfillment offer white-space expansion with lower FDA qualification burdens than food-contact polypropylene. Target medical sterile barrier contracts where lot traceability requirements deter commodity converters. For Investors and Strategic Acquirers: Valuations sit cheapest among recycling-focused specialists with food-grade post-consumer feedstock capabilities and validated FDA notification portfolios. Long-term viability centers on dual-track qualification infrastructure for virgin and recycled resin streams. Watch California, Oregon, and Colorado extended producer responsibility implementation timelines as inflection indicators for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Recycling Infrastructure Acquisition | Secures food-grade post-consumer resin streams that bypass volatile virgin polypropylene spot markets. |
| Thin-Gauge Sheet Extrusion Capacity Expansion | Consolidates control over gauge consistency for FDA-cleared food packaging contracts in the Great Lakes corridor. |
| Medical Sterile Barrier Certification Investment | Unlocks premium positioning in surgical kit packaging with validated forming processes and lot traceability. |
| Multi-Source Resin Procurement Network | Buffers against propylene monomer volatility through diversified feedstock qualification across Gulf Coast suppliers. |
| Extended Producer Responsibility Compliance Program | Positions converters for preferential procurement channels under California, Oregon, and Colorado recycled content mandates. |
Research Approach
Bottom-up food packaging and medical containment modeling reconciled against top-down resin consumption tracking forms the analytical core. Primary interviews with thermoforming plant managers, procurement leads at quick-service restaurant chains, FDA regulatory consultants, and medical device packaging engineers combined with secondary validation from FDA food-contact substance notification databases, EPA emissions compliance filings, ACC resin production reports, and state-level extended producer responsibility legislative records.
Input-output matrices map propylene monomer supply through sheet extrusion to end-use consumption across the projection horizon. Segmentation dimensions span forming method, resin chemistry, end-use application, gauge thickness, and geographic production cluster. CAGRs derive from resin demand elasticity modeling and substitution rate analysis for rigid container replacement. Forecast inputs incorporate FDA notification timeline assumptions and state-level recycled content mandate phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to propylene monomer price volatility and extended producer responsibility implementation timing. Forecasts reflect documented assumptions around resin qualification timelines and regulatory harmonization between US FDA and Health Canada frameworks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
AI in Precision Medicine Market
Others
Global Compact Wheel Loaders Market
Others
Food Technology Market
Others
Wood Stoves Market
Others
Vegetable Carbon Market
Others
Latin America Travel Retail Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Storage Dewars Market
Others
Underwater Lighting Market
Others
Gas Holders Market
Others
Solid White Films Market
Others
Idaas Market
Others
Hearables Market
Others
Military Sensors Software Market
Others
Surface Green Mining Market
Others
Receiving Scales Market