
 Integrated CMOS Tri-Gate Transistor Market | 2026-2036
Integrated CMOS Tri-Gate Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated CMOS Tri-Gate Transistor Market Foresight
The capital-intensity divergence between players is bifurcating competitive dynamics across the Integrated CMOS Tri-Gate Transistor landscape. TSMC anchors the foundry segment through unmatched leading-edge capacity deployment in Hsinchu and Tainan. Intel differentiates via in-house fabrication and design integration, sustaining process roadmaps that target gate-all-around transitions beyond current tri-gate nodes. Samsung Electronics competes aggressively on memory-logic convergence, leveraging its Pyeongtaek complex to bundle DRAM and tri-gate logic for AI accelerators.
An integrated CMOS tri-gate transistor employs a three-dimensional gate structure wrapping the channel on three sides, enabling superior electrostatic control at sub-7nm nodes with leakage currents below planar CMOS thresholds; this geometry powers high-performance logic in processors where power efficiency and switching speed determine commercial viability. FinFET technology occupies the mature volume tier as the workhorse for consumer electronics and mainstream computing, while logic devices command the dominant revenue share given their centrality to GPU and CPU architectures. Memory chips represent the fastest-expanding product category as HBM stacking requirements drive tri-gate adoption in memory controllers and interface logic.
FDA oversight of medical device processors and FCC emissions standards for consumer electronics create dual compliance burdens for tri-gate suppliers serving regulated end markets. The EPA's emerging framework for semiconductor manufacturing emissions is pressuring fabs to adopt cleaner etching chemistries and water recycling systems. Stakeholders must monitor gate-all-around readiness timelines, as the transition beyond tri-gate architectures will reshape foundry customer commitments and capital allocation priorities.
Market Dynamics
Gate-all-around process roadmaps are compressing tri-gate technology lifecycles as foundries race to secure customer commitments before architectural obsolescence. This transition pressure concentrates capital allocation decisions among the three dominant fabrication ecosystems.
Growth Catalysts
- EU Chips Act capital redirection:Sovereign semiconductor programs in Germany and France are funding domestic wafer fabrication capacity for tri-gate logic devices.
- AI inference accelerator demand:Cloud providers are retrofitting data center infrastructure with tri-gate-based processor cards to handle machine learning workloads.
- HBM stacking requirements:High-bandwidth memory controllers require tri-gate interface logic, pulling memory segment adoption upward.
Market Restraints
- EUV lithography equipment scarcity:ASML's extreme ultraviolet tool output limits leading-edge tri-gate capacity expansion regardless of capital availability.
- Fluorinated gas supply concentration:Etching chemistry inputs for sub-7nm fabrication concentrate among Japanese and Belgian specialty gas suppliers.
- Gate-all-around substitution timeline:Samsung and Intel process roadmaps threaten to shorten tri-gate payback periods before depreciation cycles complete.
Strategic Opportunities
- Automotive edge AI processors:NHTSA autonomous vehicle guidance and EPA emissions tracking mandates are creating qualification pathways for tri-gate automotive silicon.
- India PLI scheme wafer incentives:Domestic fabrication subsidies under the country's semiconductor mission could establish new tri-gate foundry capacity outside East Asian concentration.
- Chiplets and 3D stacking convergence:Disaggregation of processor designs into tile-based architectures extends tri-gate relevance in interposer and bridge die applications.
Industry Challenges
- Process engineer talent scarcity:Sub-7nm transistor design and yield optimization expertise concentrates among veterans of Taiwan and South Korean fabrication complexes.
- Multi-jurisdiction certification timelines:FDA medical device processor validation and FCC Part 15 emissions testing create sequential approval bottlenecks for regulated end markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated CMOS Tri-Gate Transistor Market |
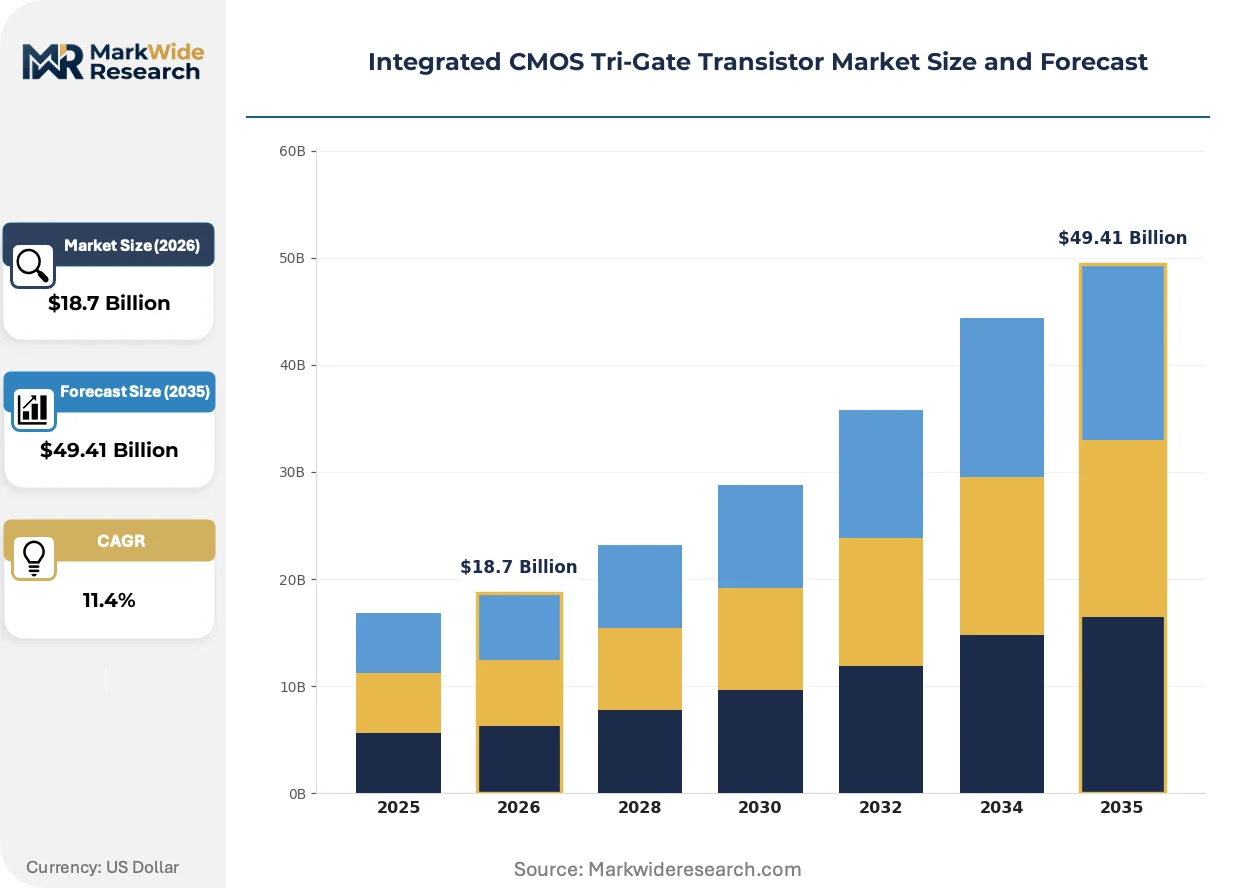
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: FinFET, Bulk CMOS, SOI, Others Product Type: Logic Devices, Memory Chips, Analog Components, Mixed-Signal Processors End User: Consumer Electronics, Automotive Systems, Industrial Applications, Aerospace Form Factor: Chip-on-Board, Surface Mount, Through-Hole, Embedded |
| Companies Covered | NVIDIA, Texas Instruments, Intel, Qualcomm, Analog Devices, TSMC, Broadcom, AMD, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated CMOS Tri-Gate Transistor Market Shifts & Advancements
Architectural transitions in logic fabrication are redrawing competitive boundaries between process generations. Three forces are actively restructuring how tri-gate technology deploys across end-use segments.
Gate-all-around nanosheet architectures are supplanting fin-based tri-gate structures at the 2nm node boundary. Samsung Foundry and Intel Foundry Services are accelerating customer tape-outs for GAA-based designs. This technology shift compresses the revenue window for legacy tri-gate nodes while forcing foundries to dual-source process development.
EPA's emerging semiconductor manufacturing emissions framework is pressuring fabs to adopt fluorinated gas abatement systems and closed-loop water recycling. The regulatory consequence elevates operating costs for US-based fabrication while creating compliance differentiation for early adopters. Memory controller suppliers serving data center customers are prioritizing EPA-aligned facilities in procurement qualifications.
Cloud hyperscalers are consolidating processor procurement around custom silicon programs rather than merchant GPU volumes. This buyer concentration shifts design influence toward Microsoft, Amazon, and Google engineering teams. Taiwan's Hsinchu corridor remains the primary beneficiary as these customers reserve leading-edge tri-gate capacity years in advance.
Integrated CMOS Tri-Gate Transistor Market Segmentation
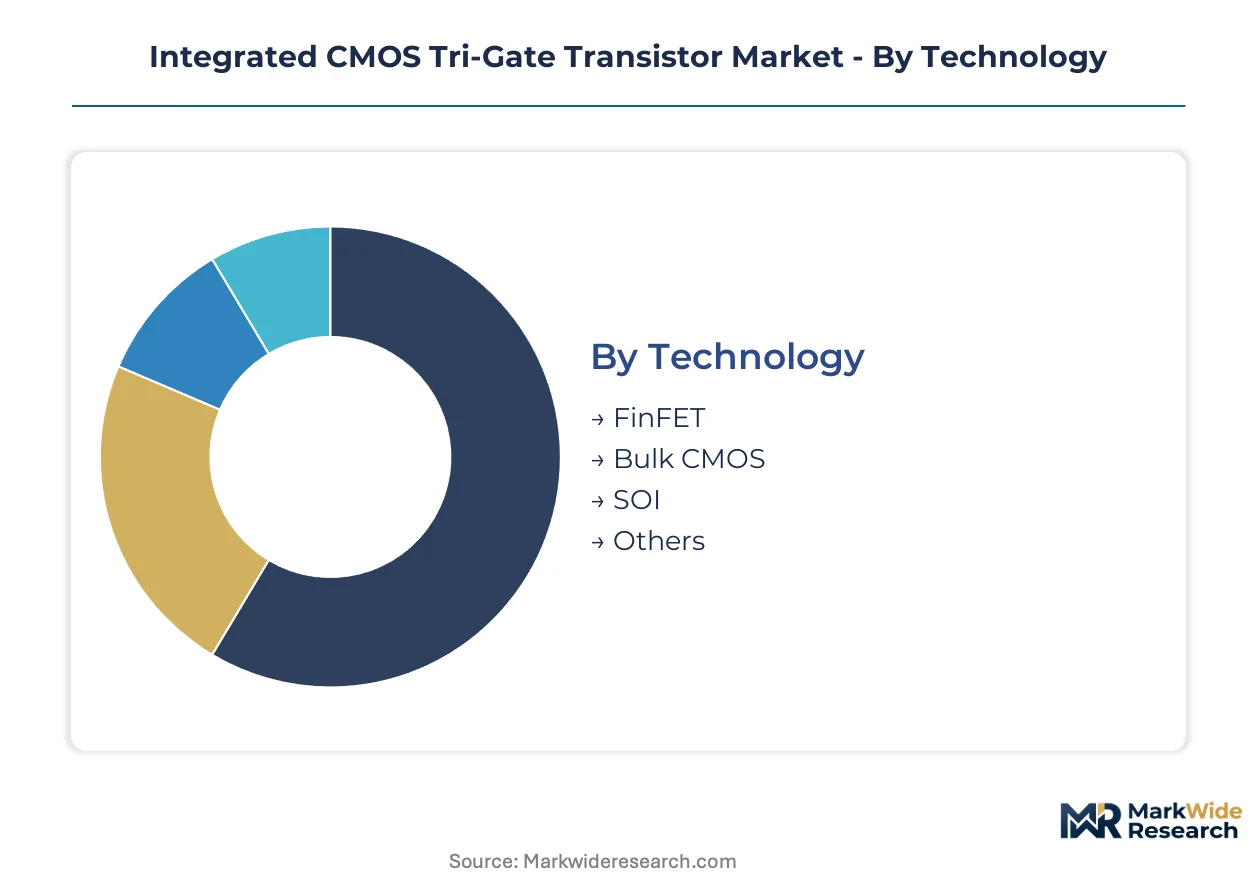
Tri-gate transistor segmentation reveals how process geometry, device function, and mounting technology intersect to determine procurement channels. Foundries route high-performance logic through direct cloud-provider contracts while memory and analog segments flow through tiered distribution networks.
Technology:
Channel mix varies sharply by process maturity: FinFET volumes move through established semiconductor distributors serving consumer OEMs, while SOI and emerging geometries route through foundry-direct models for defense and aerospace contractors.
- FinFET:The dominant three-dimensional gate architecture wraps the channel on three sides, delivering electrostatic control at nodes from 22nm down to 5nm. Demand concentrates in Taiwan's Hsinchu corridor where TSMC deploys leading-edge capacity for NVIDIA and AMD GPU accelerators, constrained by ASML EUV tool allocation bottlenecks.
- SOI:Silicon-on-insulator substrates reduce parasitic capacitance and improve RF performance through buried oxide isolation layers. RF front-end module suppliers in South Korea and Japan prioritize SOI for 5G mmWave beamforming chips, pulled by smartphone OEM qualification timelines.
- Bulk CMOS:Conventional planar substrates remain viable for mature nodes above 28nm where cost-per-transistor dominates design decisions.
- Others:Experimental geometries including nanosheet precursors and fork-sheet architectures occupy R&D pipelines at Samsung and Intel.
By volume, FinFET leads. By growth pace, SOI is climbing the fastest.
Product Type:
Cost tier stratification separates premium logic from commodity analog: data center processors command wafer-level pricing while mixed-signal and analog components compete on assembly efficiency.
- Logic Devices:CPU, GPU, and AI accelerator cores implement the most aggressive tri-gate geometries. Cloud hyperscalers in the United States reserve Hsinchu foundry capacity years ahead, locking in allocation through prepayment structures.
- Memory Chips:High-bandwidth memory controllers and interface logic require tri-gate transistors for signal integrity at stacked die interfaces. HBM3E and forthcoming HBM4 generations pull adoption upward as SK Hynix and Micron expand TSV-based packaging.
- Analog Components:Power management ICs and sensor interfaces employ relaxed geometries where voltage tolerance outweighs switching speed.
- Mixed-Signal Processors:Data converters and RF transceivers blend precision analog with digital logic on unified tri-gate process nodes.
Logic Devices capture the dominant revenue share. Memory Chips are expanding most quickly.
End User:
Application-specific qualification requirements create divergent sales cycles: consumer electronics move through quarterly design wins while automotive and aerospace demand multi-year certification tracks.
- Consumer Electronics:Smartphones, tablets, and wearables drive the largest unit volumes. Apple and Samsung smartphone SoC programs in Taiwan and South Korea set the pace for node migration.
- Automotive Systems:NHTSA autonomous vehicle guidance and EPA emissions tracking mandates create qualification pathways for tri-gate silicon in ADAS processors and battery management systems.
- Industrial Applications:Factory automation and power grid infrastructure tolerate longer procurement cycles in exchange for extended temperature range specifications.
- Aerospace:Satellite and avionics programs require radiation-hardened tri-gate variants with extended qualification timelines.
Consumer Electronics leads by volume. Automotive Systems are gaining share fastest.
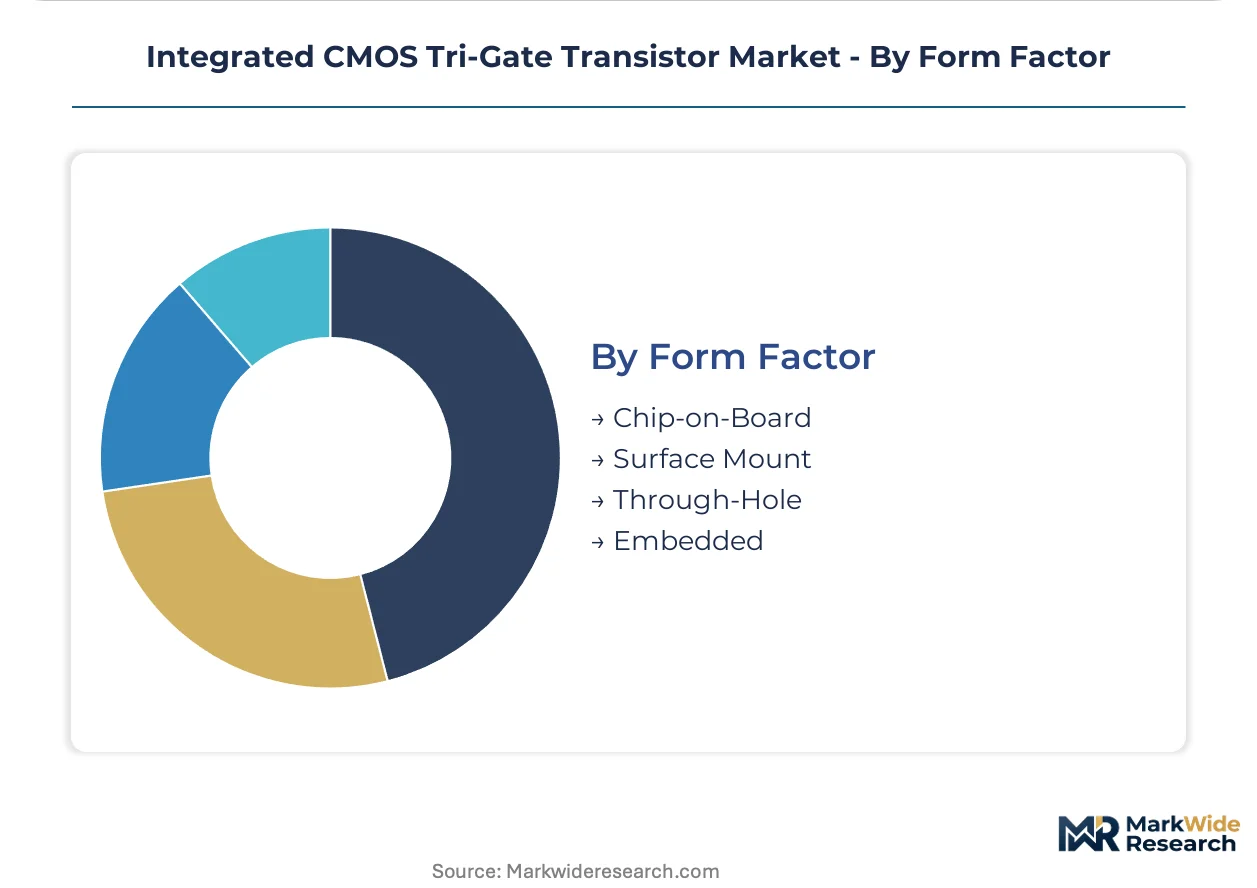
Form Factor:
Mounting technology determines supply chain depth: surface mount devices flow through high-volume electronics manufacturing services while embedded and through-hole formats retain specialized distribution.
- Surface Mount:QFN, BGA, and WLCSP packages dominate smartphone and laptop motherboard assembly. Foxconn and Pegatron facilities in Shenzhen and Zhengzhou process billions of units annually.
- Chip-on-Board:Bare die attachment for space-constrained wearables and hearing aids requires precision wire bonding infrastructure concentrated in Malaysia and Vietnam.
- Through-Hole:Legacy industrial and military equipment sustains demand for socketed packages with field-replaceable characteristics.
- Embedded:Die-level integration into substrates and interposers serves chiplet-based processor disaggregation.
Surface Mount leads by volume. Embedded formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry pricing power in Taiwan's Hsinchu corridor exceeds contract rates in German facilities by margins reflecting EUV tool concentration and yield mastery. This asymmetry shapes capital flows as sovereign subsidy programs attempt to replicate East Asian manufacturing density.
United States
Cloud hyperscalers in Virginia and Oregon drive tri-gate demand for AI training clusters. The CHIPS and Science Act directs funding toward domestic foundry construction in Arizona and Texas. Intel's fabrication complex in Hillsboro anchors West Coast process development activity.
Taiwan
TSMC's Hsinchu and Tainan facilities process the majority of leading-edge tri-gate wafers for NVIDIA and AMD accelerators. The National Development Council coordinates water and power allocation for science park expansion. Kaohsiung's emerging fab cluster attracts packaging and testing ecosystem migration.
South Korea
Samsung Electronics bundles DRAM and tri-gate logic for AI accelerator customers from its Pyeongtaek complex. The Ministry of Trade, Industry and Energy subsidizes materials localization to reduce Japanese etching gas dependence. Seongnam's R&D corridor hosts process engineer training institutes.
China
SMIC and Hua Hong Semiconductor advance domestic tri-gate capability despite equipment access constraints under US export controls. MIIT's 14th Five-Year Plan prioritizes semiconductor self-sufficiency timelines. Shanghai's Zhangjiang Hi-Tech Park concentrates design house and foundry joint ventures.
Germany
Automotive OEMs in Stuttgart and Munich qualify tri-gate silicon for ADAS processors and battery management systems. The EU Chips Act funds Dresden's Silicon Saxony expansion for automotive-grade foundry capacity. Infineon's Villach-Austria proximity creates cross-border packaging cluster effects.
Integrated CMOS Tri-Gate Transistor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Integrated CMOS Tri-Gate Transistor landscape. Foundry specialists concentrate process mastery and capital deployment, while integrated device manufacturers retain design-fabrication coordination advantages. Three archetypes dominate: pure-play foundries with unmatched leading-edge capacity, IDMs defending vertical integration, and fabless designers capturing algorithm-specific silicon value. Competitive moves center on EUV tool reservation wars and gate-all-around process readiness racing.
Among pure-play foundries, TSMC anchors the leading-edge segment through Hsinchu and Tainan capacity concentration. Samsung Electronics occupies a position bridging memory-logic integration for AI accelerator bundles. Intel represents the IDM archetype attempting foundry services expansion while sustaining in-house design roadmaps.
| Leading Market Players |
|---|
| NVIDIA |
| Texas Instruments |
| Intel |
| Qualcomm |
| Analog Devices |
| TSMC |
| Broadcom |
| AMD |
| Samsung Electronics |
| Others |
Supply & Pricing Matrix
TSMC's Hsinchu capacity utilization above ninety percent creates asymmetric pricing power that smaller foundries cannot replicate, compressing margin structures for trailing-edge suppliers while elevating wafer-level premiums for leading-edge tri-gate allocation. This scale concentration forces buyers into multi-year prepayment commitments that lock in price floors regardless of subsequent demand fluctuations.
Pricing Analysis
The customization-premium spread between standard FinFET catalog pricing and configured-to-order tri-gate logic separates merchant GPU contracts from hyperscaler custom silicon programs. Pricing stratifies across premium, standard, and economy tiers based on EUV tool allocation priority and automotive-grade certification status. Cost compression in mature FinFET nodes is intensifying because Chinese foundries are expanding 28nm capacity despite equipment access constraints. Fabless AI chip designers exhibit the highest price sensitivity, while cloud hyperscalers prioritize allocation security over unit economics.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for leading-edge tri-gate logic, with the Hsinchu corridor and Samsung's Pyeongtaek complex processing the majority of sub-5nm output. The supply chain draws from fluorinated etching gases concentrated among Japanese and Belgian specialty chemical suppliers, plus EUV lithography equipment where ASML maintains single-source dominance. Tariff exposure on semiconductor manufacturing equipment imports into China threatens to fragment procurement channels for domestic foundries. Distribution runs through foundry-direct contracts for logic devices and tiered semiconductor distributors serving consumer OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
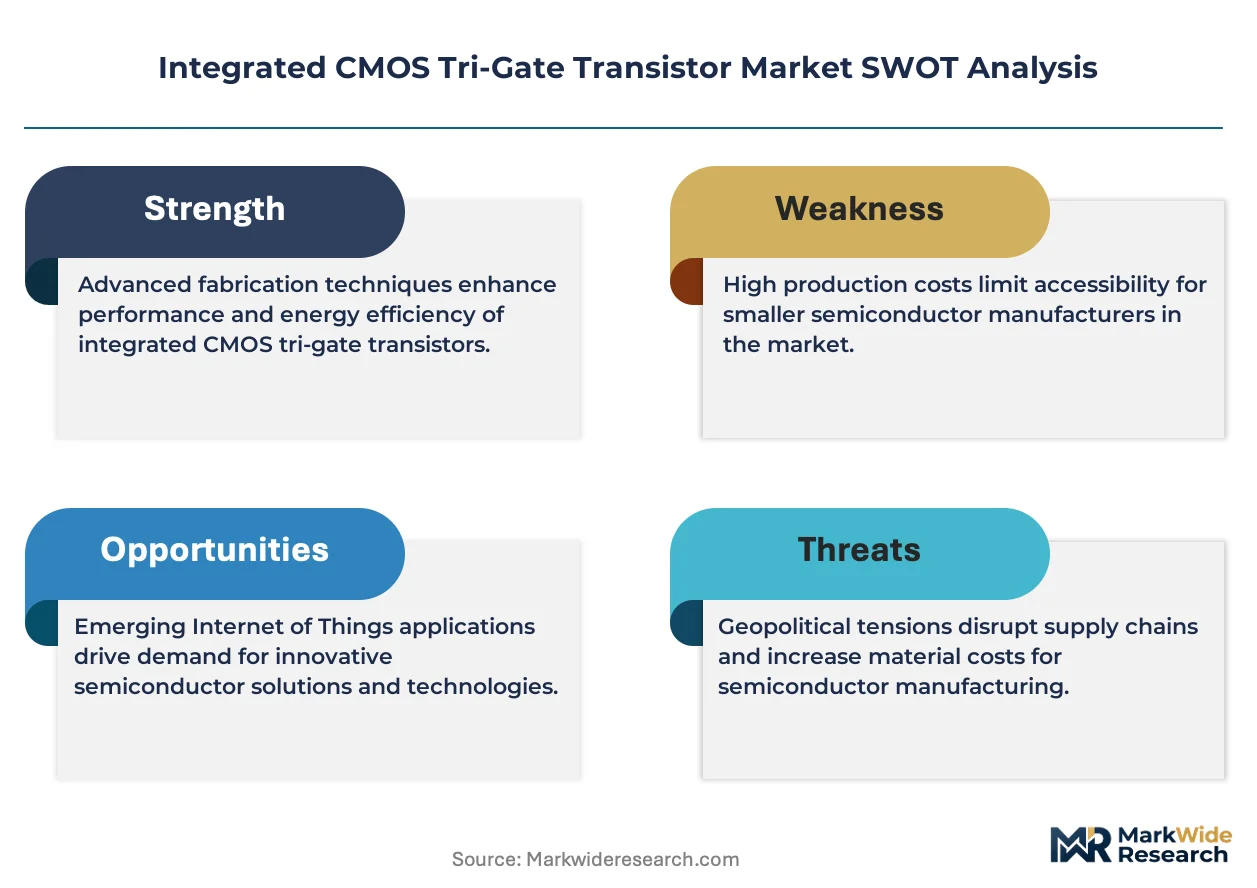
Gate-all-around process readiness is compressing the revenue window for legacy tri-gate nodes, forcing incumbents to defend depreciation cycles against architectural substitution before payback periods complete.
For Market Incumbents: Compound leading-edge capacity reservations through Hsinchu and Tainan expansion to preempt customer migration toward Samsung and Intel GAA roadmaps. Deepen backward integration into EUV tool maintenance infrastructure and fluorinated gas recycling systems to reduce operating cost exposure from EPA emissions frameworks. For New Entrants and Emerging Players: Automotive-grade ISO 26262 certification fast-tracks offer the most penetrable entry vector as NHTSA autonomous vehicle mandates create qualification demand outside incumbent cloud-provider relationships. Target India's PLI scheme wafer incentives to establish packaging and testing presence before foundry construction timelines mature. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among foundry services providers with multi-year hyperscaler prepayment structures, though gate-all-around transition timelines threaten contract renegotiation cycles. Watch for ASML EUV tool delivery acceleration as the inflection signal for capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Gate-All-Around Process Transition | Intel and Samsung tape-outs for GAA architectures compress tri-gate payback windows. |
| EUV Tool Reservation Expansion | ASML equipment allocation wars determine foundry customer commitment security. |
| Automotive Certification Investment | NHTSA ADAS mandates create qualification pathways outside consumer electronics. |
| Fluorinated Gas Abatement Deployment | EPA emissions frameworks elevate operating costs for US-based fabrication. |
| Chiplet Architecture Standardization | Disaggregation into tile-based designs extends tri-gate relevance in interposer applications. |
Research Methodology
Initial hypotheses were tested against primary input from foundry process engineers, fabless semiconductor procurement directors, and cloud hyperscaler silicon engineering teams and refined through secondary validation against SEC 10-K filings, ASML equipment order disclosures, and customs data for fluorinated gas imports. Bottom-up wafer shipment estimates from Taiwan's Hsinchu corridor and top-down cloud capex allocation models were triangulated to constrain forecast variance.
Variance decomposition across technology nodes, product categories, and geographic production clusters structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory convergence. Modeled inputs included EUV tool delivery schedules, sovereign subsidy program disbursement timelines, and gate-all-around customer tape-out acceleration rates.
Underlying assumptions cover sustained cloud AI infrastructure investment and EPA regulatory enforcement continuity, with deviation risk concentrated in export control expansion affecting Chinese equipment access and gate-all-around yield ramp timelines. Recalibration cycles align with material shifts in ASML order book composition and sovereign foundry construction milestone achievements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
Battery Fuel Gauge IC Market
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market
IC (Integrated Circuits)
Digital IC Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Asia Pacific Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market
IC (Integrated Circuits)
Asia Pacific Logic IC Market
IC (Integrated Circuits)
CMOS Power Amplifier Market
IC (Integrated Circuits)
Semiconductor Integrated Circuit Chip Market
IC (Integrated Circuits)
GNSS IC Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
3D IC and 2.5D IC Market
IC (Integrated Circuits)
APAC Analog IC Market