
 United States Analog Integrated Circuits Market | 2026-2036
United States Analog Integrated Circuits Market Size, Share, and Industry Trends Forecast 2026-2036
United States Analog Integrated Circuits Market Insights
Multi-source procurement from captive foundries is decoupling from traditional single-source reliance among defense-tier suppliers. Texas Instruments leverages vertical integration into 300mm analog wafer fabrication to sustain margin control. Analog Devices anchors its position through precision signal-chain specialization in industrial and aerospace segments. ON Semiconductor competes aggressively in automotive power management, where electrification programs require ruggedized operational amplifiers.
United States analog integrated circuits are semiconductor devices that process continuous electrical signals with specifications typically spanning microvolt input offset voltages and bandwidths from DC to several gigahertz, fabricated through precision bipolar, CMOS, or BiCMOS processes for sensor interfacing, power regulation, and radio frequency conditioning. Their primary commercial purpose spans automotive battery management, telecommunications base station signal chains, and industrial motor drive controls. Voltage regulators capture the deepest margin pools as electrification strains power integrity requirements across automotive and telecom applications. Operational amplifiers lead volume consumption in industrial automation, where precision instrumentation demands sub-microvolt offset stability. CMOS technology dominates new design starts for portable and IoT endpoints, while BiCMOS processes retain pricing power in mixed-signal automotive safety systems.
The Department of Commerce Bureau of Industry and Security shapes demand through export control classifications on advanced node equipment, compelling domestic qualification of analog processes previously sourced from offshore foundries. The Environmental Protection Agency and OSHA jointly constrain fabrication chemistry choices, elevating capital costs for new greenfield capacity in Arizona and Texas. The Federal Communications Commission spectrum auctions indirectly stimulate radio frequency analog content in telecommunications infrastructure. Stakeholders must monitor CHIPS Act disbursement timelines against foundry build-out schedules to calibrate capacity commitments.
Market Dynamics
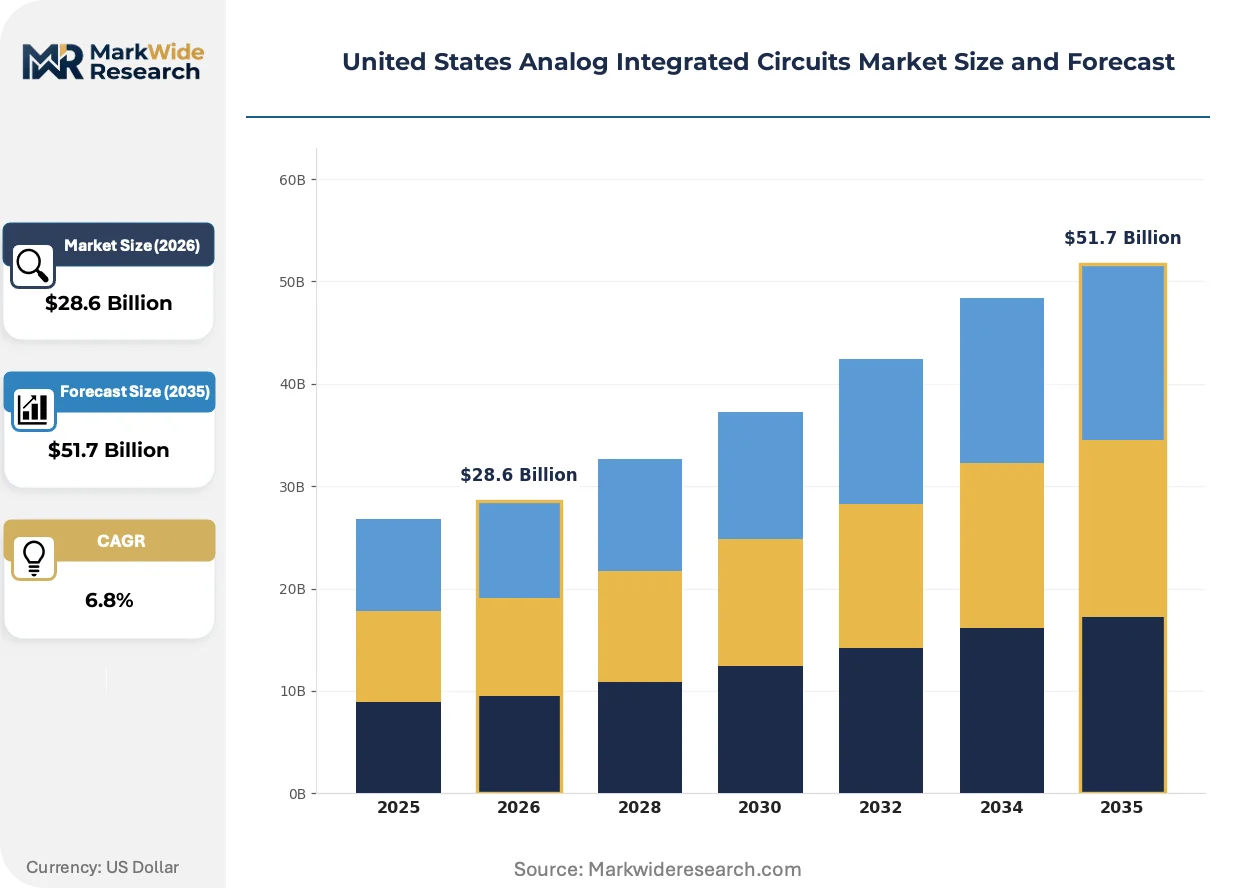
Automotive electrification programs at Ford and General Motors are expanding demand for precision voltage regulators while the CHIPS and Science Act reshapes domestic fabrication capacity. Texas foundry clusters anchored by Samsung and TSMC are concentrating supply-side investment.
Growth Catalysts
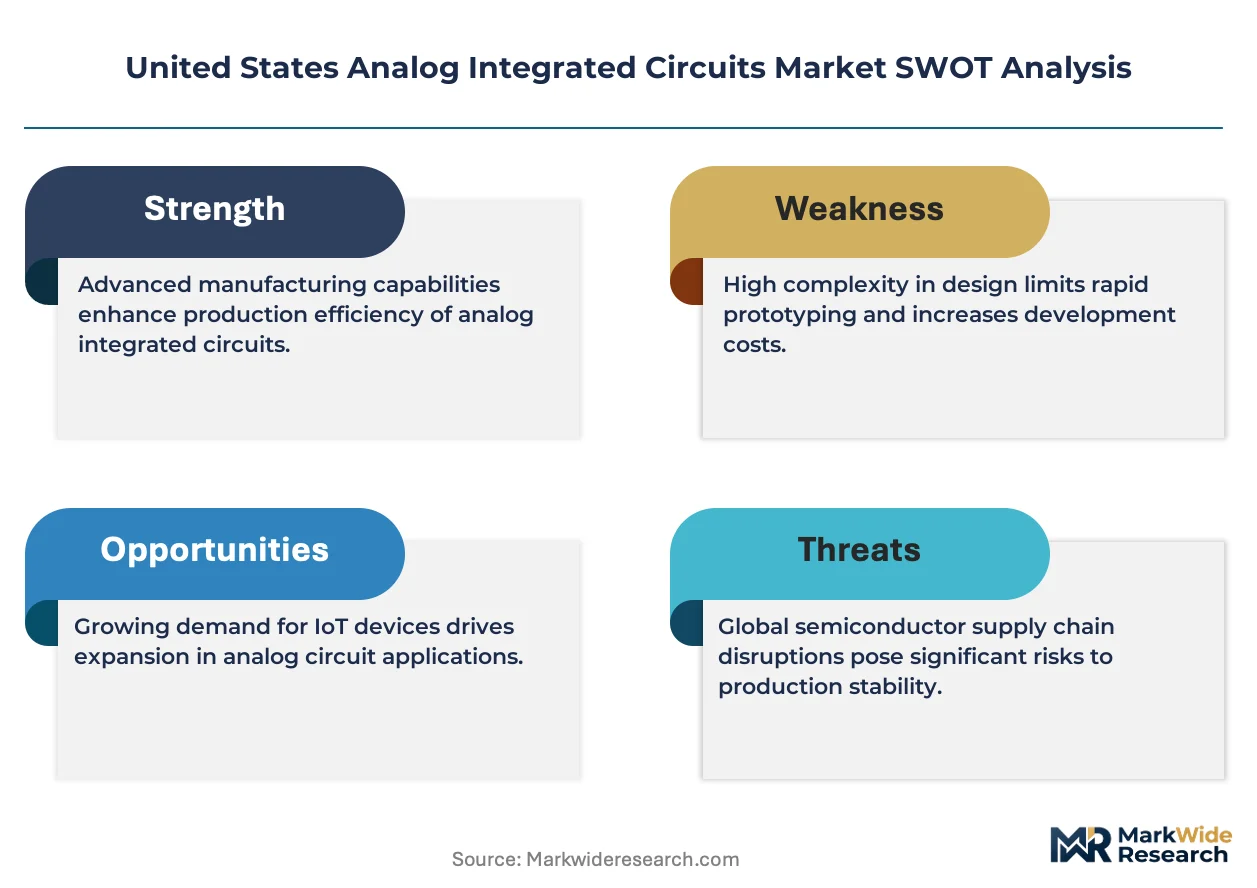
- CHIPS Act disbursements:Federal capital injections are accelerating greenfield fab construction in Arizona and Texas, expanding captive analog wafer supply for defense-tier qualification.
- Automotive battery management:Electrification mandates from NHTSA and California Air Resources Board are multiplying sensor interface and power regulation content per vehicle platform.
- Telecommunications infrastructure:FCC spectrum auctions are stimulating radio frequency analog content in 5G base station deployments across the Midwest and Southeast.
Market Restraints
- Specialized equipment scarcity:Advanced node lithography tools subject to Bureau of Industry and Security export controls are constraining process migration timelines for precision bipolar fabrication.
- Fab chemistry compliance costs:EPA and OSHA joint constraints on etchant and solvent handling are elevating capital intensity for new greenfield capacity in water-stressed Arizona regions.
- Single-source legacy dependence:Defense-tier suppliers remain exposed to offshore foundry concentration for qualified analog processes despite multi-source procurement mandates.
Strategic Opportunities
- Industrial IoT endpoints:CMOS technology migration for portable sensor nodes is opening design-win opportunities in Midwest manufacturing automation corridors.
- BiCMOS automotive safety:Mixed-signal process specialization retains pricing power in advanced driver-assistance systems requiring sub-microvolt offset stability.
- Domestic qualification acceleration:Department of Commerce export control timelines are compressing customer qualification cycles for onshore analog foundry alternatives.
Industry Challenges
- Analog design talent scarcity:Precision circuit design expertise concentrated among veteran engineers is constraining expansion capacity for BiCMOS automotive safety programs.
- Legacy system integration friction:New voltage regulator architectures face extended validation cycles against existing industrial motor drive control installations.
- Multi-source procurement complexity:Defense-tier suppliers must simultaneously qualify captive foundry output while maintaining legacy offshore supply continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Analog Integrated Circuits Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Amplifiers, Voltage Regulators, Comparators, Linear Amplifiers Technology: Bipolar, CMOS, BiCMOS, GaAs Application: Consumer Electronics, Automotive, Telecommunications, Industrial Automation End User: OEMs, Contract Manufacturers, Distributors, Research Institutions |
| Companies Covered | Texas Instruments, Analog Devices, ON Semiconductor, Microchip Technology, Skyworks Solutions, Infineon Technologies, STMicroelectronics, NXP Semiconductors, Silicon Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Analog Integrated Circuits Market Trends and Innovations
Silicon carbide integration and gallium nitride power stages are compressing efficiency benchmarks while machine learning-assisted layout tools reshape analog design productivity. Regulatory pressure on supply chain provenance is accelerating domestic process qualification.
Silicon carbide power integration is automating thermal management reduction in automotive traction inverters. Tier-1 suppliers are adopting 650V and 1200V SiC MOSFET gate drivers at compressed development cycles. This technology is automating the displacement of silicon IGBT modules in Ford and General Motors electrification platforms.
The CHIPS and Science Act's domestic content incentives are mandating foundry investment location decisions. Bureau of Industry and Security export classifications on advanced deposition equipment are compelling process node choices. Precision analog segments in Texas and Arizona are responding with qualified 180nm and 130nm bipolar-CMOS flows.
Defense procurement offices are consolidating supplier lists around qualified domestic foundry output. Multi-source mandates from the Department of Defense are displacing single-source offshore reliance with captive Texas fab capacity. This concentration is most visible in precision voltage regulator programs for aerospace applications.
United States Analog Integrated Circuits Market Segmentation
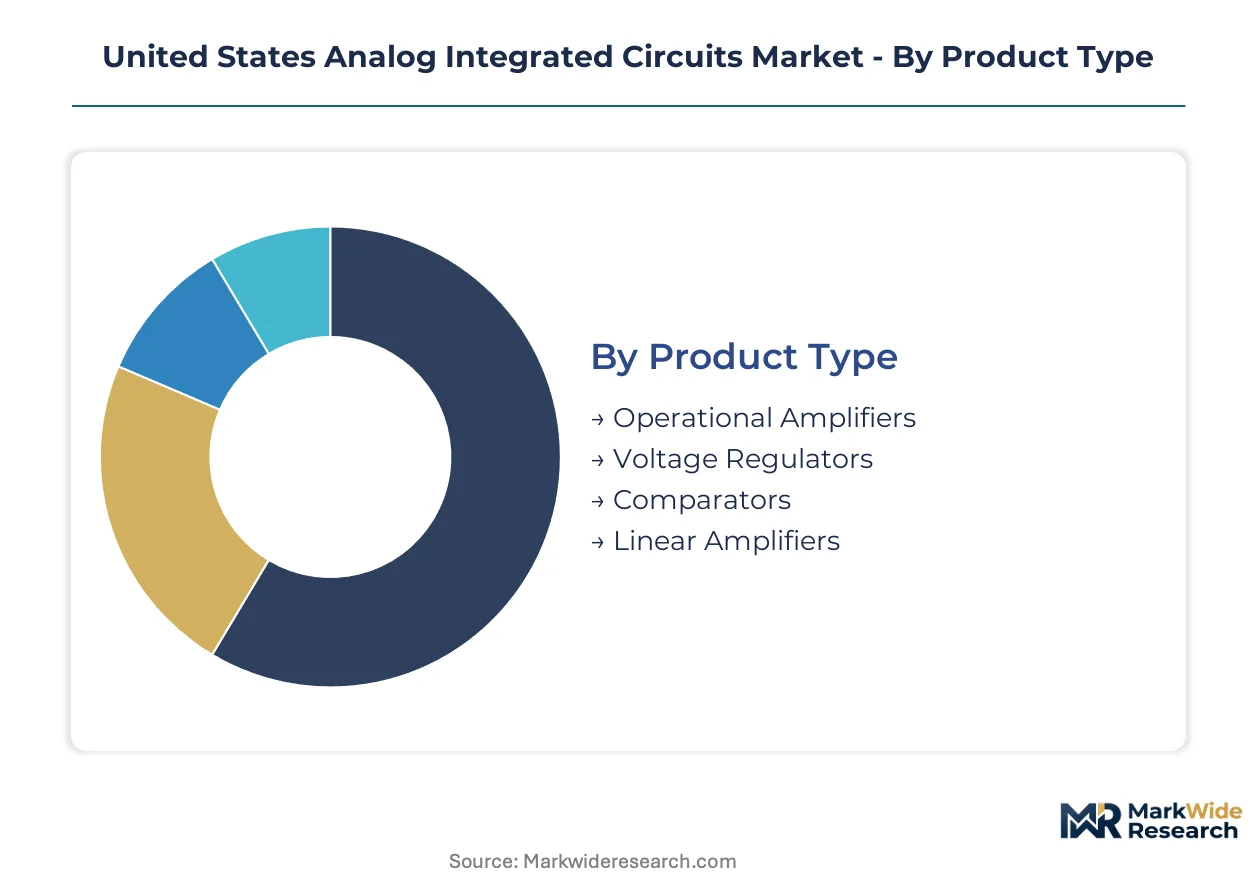
Analog integrated circuits serve heterogeneous performance requirements across power regulation, signal conditioning, and sensor interfacing. Segmentation reveals where process technology investments concentrate and which application verticals command premium pricing. Texas Instruments and Analog Devices allocate fabrication capacity based on these category boundaries.
Product Type:
Voltage regulators demand the heaviest capital commitment due to precision thermal management and automotive qualification protocols.
- Voltage Regulators:These devices maintain stable output voltage across varying load conditions and input fluctuations, fabricated through precision bipolar processes for sub-1% line regulation. Automotive battery management systems at Ford and General Motors consume the deepest volume pools as electrification strains power integrity requirements. EPA and OSHA constraints on fab chemistry elevate capital intensity for automotive-grade qualification.
- Operational Amplifiers:High-gain differential amplifiers with microvolt input offset specifications enable precision instrumentation and sensor signal conditioning. Industrial automation corridors in Michigan and Ohio drive volume consumption where sub-microvolt offset stability commands premium positioning. NHTSA electrification mandates are multiplying sensor interface content per manufacturing platform.
- Comparators:High-speed switching devices for threshold detection applications in power management and timing circuits. FCC spectrum auction timelines are stimulating radio frequency comparator content in 5G infrastructure deployments.
- Linear Amplifiers:Signal amplification components for audio and instrumentation applications requiring low distortion characteristics. Consumer electronics OEMs in California and Texas anchor procurement volume for portable device integration.
Most installed capacity flows through Voltage Regulators. Expansion is steepest in Operational Amplifiers.
Technology:
Process selection determines margin structure and foundry equipment requirements across the technology portfolio.
- BiCMOS:Mixed-signal processes combining bipolar precision with CMOS density enable automotive safety systems and industrial instrumentation. Advanced driver-assistance systems requiring sub-microvolt offset stability retain pricing power in this segment. CHIPS Act disbursements are accelerating domestic BiCMOS qualification at Arizona foundry clusters.
- CMOS:Dominant technology for portable and IoT endpoints leverages digital process scalability for cost-sensitive analog functions. Midwest manufacturing automation corridors are opening design-win opportunities for CMOS-based sensor nodes.
- Bipolar:Legacy precision processes maintain foothold in voltage reference and high-linearity amplification applications. Bureau of Industry and Security export controls on advanced lithography tools are constraining bipolar process migration timelines.
- GaAs:Gallium arsenide processes serve high-frequency radio frequency applications in telecommunications infrastructure. FCC spectrum allocations are stimulating GaAs content in millimeter-wave base station deployments.
BiCMOS captures the deepest margin pools. CMOS is climbing the fastest in new design starts.
Application:
End-use concentration shapes customer qualification cycles and reliability specifications.
- Automotive:Battery management, motor control, and sensor interfacing functions require AEC-Q100 qualification and zero-defect protocols. California Air Resources Board electrification mandates are multiplying analog content per vehicle platform across Detroit-based OEM supply chains.
- Industrial Automation:Precision motor drives, process control, and instrumentation systems demand extended operational temperature ranges. Ohio and Indiana manufacturing corridors anchor procurement concentration for ruggedized operational amplifiers.
- Telecommunications:Base station signal chains and optical networking infrastructure require low-noise amplification and power regulation. FCC spectrum auctions are stimulating analog content in Midwest and Southeast 5G deployments.
- Consumer Electronics:Portable devices and computing peripherals drive volume consumption of cost-optimized CMOS analog functions. Texas and California design centers concentrate procurement for smartphone and wearable integration.
Automotive commands the steepest pricing premiums. Industrial Automation is gaining share fastest in domestic foundry qualification.
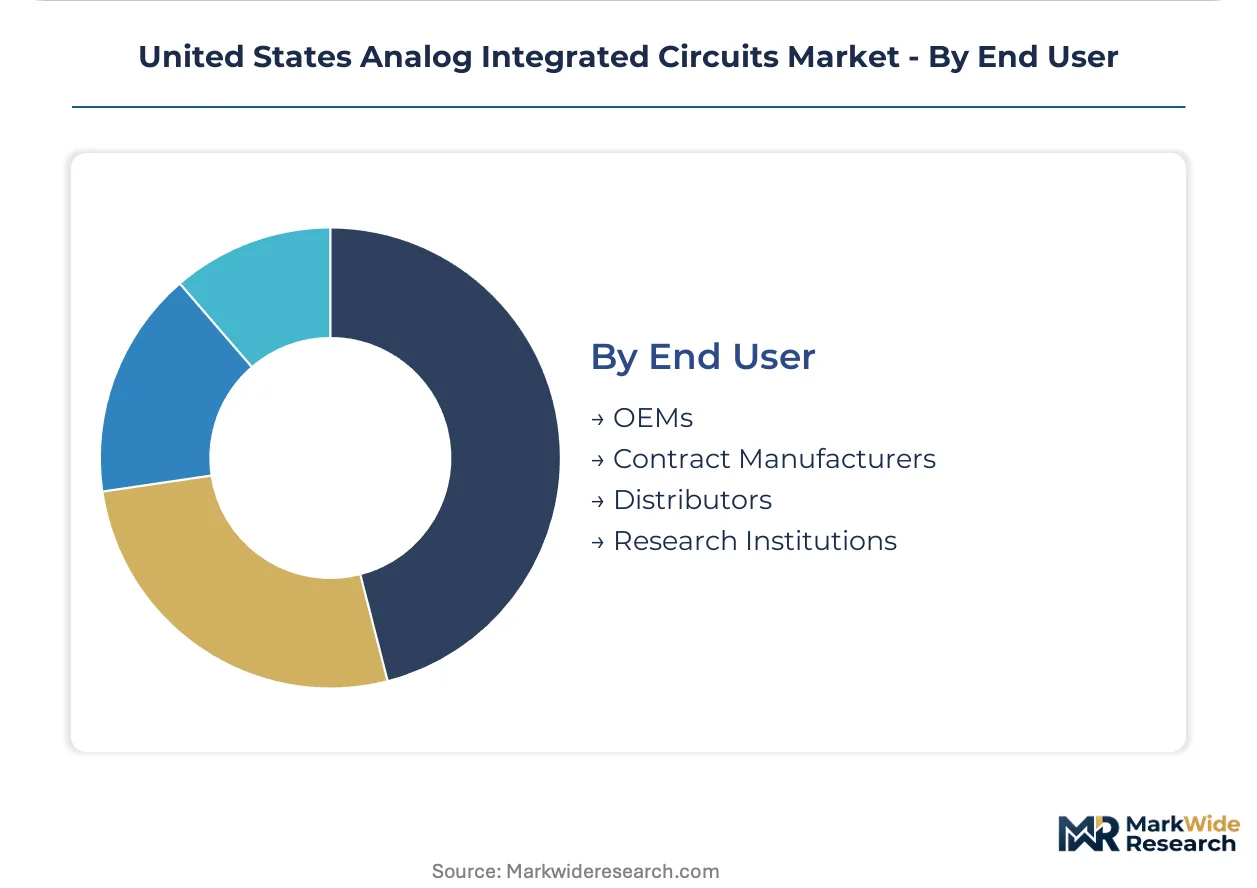
End User:
Procurement authority distribution determines channel strategy and technical support requirements.
- OEMs:Original equipment manufacturers in automotive and industrial verticals direct specification authority for qualified analog components. Ford and General Motors electrification programs are expanding direct procurement of precision voltage regulators.
- Contract Manufacturers:Electronics manufacturing services providers aggregate demand across multiple OEM programs for volume pricing leverage. Mexican border maquiladora operations are concentrating contract manufacturing capacity for US-bound analog consumption.
- Distributors:Authorized and independent channels manage inventory and logistics for fragmented customer bases. Multi-source procurement mandates from defense procurement offices are reshaping distributor qualification requirements.
- Research Institutions:Universities and national laboratories drive early-stage process development and prototype volume. Department of Commerce export control timelines are compressing research institution qualification cycles for domestic foundry alternatives.
OEMs direct the largest procurement volume. Contract Manufacturers are expanding most quickly in nearshored electronics assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns track cost-of-compliance gaps between water-stressed Arizona regions and EPA-constrained chemistry handling. Texas foundry clusters exploit regulatory arbitrage through lower fab chemistry compliance burdens.
Texas
Samsung and TSMC anchor new foundry clusters in Austin and Sherman. CHIPS Act disbursements accelerate greenfield construction. Dallas-Fort Worth concentrates precision voltage regulator qualification for automotive battery management systems.
Arizona
Water scarcity elevates capital intensity for EPA-compliant etchant handling. Intel and emerging domestic foundries expand 180nm bipolar-CMOS flows. Phoenix-Tucson corridor attracts defense-tier supplier qualification programs.
California
Consumer electronics OEMs in Silicon Valley and San Diego drive CMOS analog procurement for portable devices. CARB electrification mandates multiply sensor interface content. Bay Area design centers concentrate RF analog specification authority.
Michigan
Detroit-based OEM supply chains anchor industrial automation demand for operational amplifiers. NHTSA mandates expand precision instrumentation requirements. Ann Arbor-Grand Rapids corridor concentrates ruggedized amplifier procurement.
Ohio
Manufacturing automation corridors drive volume consumption of sub-microvolt offset stability devices. EPA constraints on fab chemistry limit greenfield expansion. Cleveland-Columbus-Dayton triangle concentrates industrial motor drive control installations.
United States Analog Integrated Circuits Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue automotive electrification adjacencies through mixed-signal specialization. The vendor base stratifies across three tiers: vertically integrated incumbents controlling captive wafer supply, fabless specialists outsourcing to domestic foundries, and diversified conglomerates leveraging automotive customer relationships. Dominant competitive moves include backward integration into 300mm analog wafer fabrication and multi-source procurement qualification for defense-tier programs.
Among vertically integrated fabricators, Texas Instruments exemplifies the captive-foundry archetype through in-house production of precision bipolar processes. Analog Devices occupies a position within the signal-chain specialization tier, while ON Semiconductor represents the automotive power management vector. These three anchors illustrate how competitive positioning depends on process technology control and end-market concentration.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| ON Semiconductor |
| Microchip Technology |
| Skyworks Solutions |
| Infineon Technologies |
| STMicroelectronics |
| NXP Semiconductors |
| Silicon Laboratories |
| Others |
Pricing and Supply Chain Analysis
AEC-Q100 automotive qualification tiers bifurcate pricing power between zero-defect premium grades and industrial-standard commercial grades, concentrating supply chain investment toward Texas foundry clusters where EPA compliance costs run lower than Arizona alternatives. This tier divergence channels procurement volume through qualified domestic capacity while pricing compression intensifies for unqualified CMOS commodity flows.
Pricing Analysis
Distributor margin layers absorb 15-25 point spreads between authorized channel pricing and direct OEM procurement of precision voltage regulators. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer CMOS levels reflects certification investment recovery timelines. Pricing pressure stems from captive foundry capacity expansion in Texas compressing spot market premiums for standard-grade operational amplifiers. Defense-tier buyers exhibit lowest price sensitivity due to multi-source qualification mandates, while consumer electronics OEMs drive hardest volume negotiations.
Supply Chain Analysis
Automotive qualification gating restricts qualified wafer supply to Taiwan, South Korea, and domestic Texas foundries with certified bipolar-CMOS flows. Silicon wafers, specialty etchant chemicals, and precision lithography equipment anchor raw material dependencies. Single-source vulnerability concentrates in advanced node deposition tools subject to Bureau of Industry and Security export classifications. Distribution runs through authorized distributors managing defense-tier qualification documentation alongside contract manufacturers nearshoring assembly to Mexican border operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Texas-Arizona regulatory arbitrage on fab chemistry compliance costs creates geographic positioning leverage for capacity investment decisions, with water-stressed Arizona regions carrying 20-30% elevated capital intensity for EPA-constrained etchant handling.
For Market Incumbents: Anticipate margin compression from emerging domestic foundry capacity by accelerating backward integration into 300mm analog wafer fabrication. Prioritize captive supply of precision bipolar processes before CHIPS Act disbursements saturate qualified capacity. Defend pricing power through AEC-Q100 certification depth that new entrants cannot replicate within compressed qualification timelines.
For New Entrants and Emerging Players: Mid-tier industrial automation OEMs in Ohio and Michigan represent underserved buyer archetypes seeking sub-microvolt offset stability without automotive-grade pricing premiums. White-space targets include CMOS-based sensor nodes for Midwest manufacturing corridors and domestic qualification acceleration services for defense-tier suppliers. Go-to-market execution should anchor on foundry partnership models bypassing captive fabrication capital requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where analog design talent scarcity constrains BiCMOS automotive safety program expansion. Long-term viability favors vertically integrated incumbents with captive wafer supply over fabless specialists exposed to foundry pricing cycles. Acquisition target archetypes include precision signal-chain specialists with aerospace qualification depth. Monitor Bureau of Industry and Security export control timeline compression as inflection signal for domestic qualification acceleration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Texas Instruments' 300mm analog wafer fabrication in Texas secures margin control against spot market volatility. |
| Multi-Source Procurement Qualification | Defense-tier suppliers simultaneous qualification of domestic and offshore foundries reduces single-source vulnerability. |
| BiCMOS Process Specialization | Mixed-signal precision for advanced driver-assistance systems retains pricing power in automotive safety segments. |
| Industrial IoT Design-Win Expansion | CMOS technology migration captures Midwest manufacturing automation corridor demand for portable sensor nodes. |
| Domestic Foundry Alternative Acceleration | Department of Commerce export control timelines compress customer qualification cycles for onshore analog capacity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with analog design engineers, foundry operations directors, Tier 1 automotive supplier procurement leads, and defense procurement officers with secondary validation against SEC 10-K filings, Bureau of Industry and Security export classification records, and CHIPS Act disbursement documentation. Bottom-up wafer capacity modeling and top-down OEM demand aggregation provided triangulation anchors.
Segment-weighting approaches distributed value projections across voltage regulator, operational amplifier, and comparator product categories, with technology splits across BiCMOS, CMOS, bipolar, and GaAs process flows. Application dimensions spanned automotive, industrial automation, telecommunications, and consumer electronics end-uses. CAGR derivation integrated foundry build-out schedules against electrification program timelines, with CHIPS Act capital injection trajectories and NHTSA mandate compliance deadlines as key forecast inputs.
Underlying measurement precision varies by segment; automotive battery management and defense-tier voltage regulator categories carry tighter precision than consumer CMOS analog flows due to visible OEM procurement data. Forecasts reflect documented assumptions on foundry yield ramp timelines and qualification cycle durations. A model refresh is warranted upon material change in Bureau of Industry and Security export control classifications or CHIPS Act disbursement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
Global Linear Regulator Power Management IC Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
NFC Reader Ics Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
Taiwan Integrated Circuits Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market
IC (Integrated Circuits)
Semiconductor Integrated Circuit Chip Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
Japan Analog IC Market
IC (Integrated Circuits)
Global Analog Integrated Circuit (IC) Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
CMOS Power Amplifier Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Global Special Purpose Logic IC Market