
 CMOS Power Amplifier Market | 2026-2036
CMOS Power Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
CMOS Power Amplifier Market Analysis
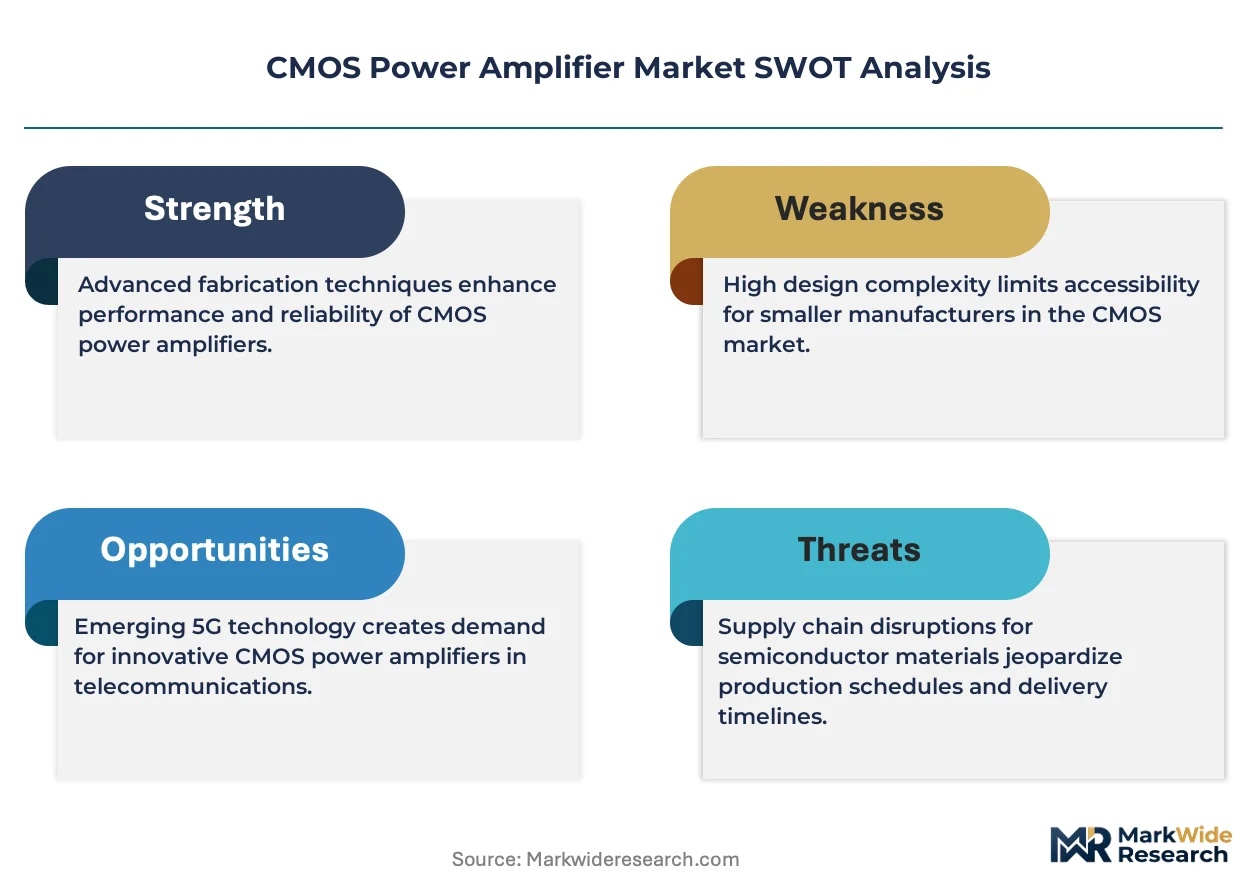
EU Green Deal energy-efficiency mandates is expanding requirements for low-power RF components across European telecommunications infrastructure. Murata Manufacturing leverages its ceramic packaging expertise to dominate high-frequency CMOS amplifier supply for 5G base stations. Infineon Technologies anchors its position through in-house production of RF front-end modules integrating CMOS power stages. Qualcomm Technologies competes by specializing in modem-to-antenna CMOS solutions that reduce handset bill-of-materials complexity.
A CMOS power amplifier is a complementary metal-oxide-semiconductor integrated circuit that amplifies radio-frequency signals using silicon-based transistor arrays operating at supply voltages typically below 5V, fabricated through sub-10nm lithography processes for integration with digital baseband processors. Its primary purpose is boosting transmitted signal power in wireless communication systems while maintaining linearity and minimizing heat dissipation. The 5G application segment leads volume demand as massive MIMO arrays require hundreds of low-cost amplifiers per base station, while the IoT application segment represents the fastest-growing margin pool as ultra-low-power CMOS designs displace discrete gallium arsenide alternatives in sensor networks. Technology competition between pure CMOS and SiGe processes concentrates in sub-6GHz mid-band implementations where cost-integration trade-offs remain unresolved.
The Federal Communications Commission in the United States mandates spectral efficiency standards that directly shape CMOS amplifier linearity specifications for commercial transmitters, while China's Ministry of Industry and Information Technology enforces domestic content requirements that redirect supply chain localization. REACH chemical restrictions in Europe constrain lead-free solder and plating materials used in CMOS amplifier packaging, forcing foundries to qualify alternative metallization stacks. Stakeholders must monitor how Open RAN interface standardization alters procurement patterns for disaggregated RF components versus integrated CMOS front-end modules.
Market Dynamics
Massive MIMO base station deployment is compressing unit economics for CMOS power amplifiers as telecommunications carriers demand higher channel density at lower per-channel cost structures. The transition from discrete gallium arsenide modules to integrated silicon solutions is restructuring supplier relationships across the RF front-end value chain.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:European telecommunications infrastructure procurement now prioritizes sub-5V CMOS designs that reduce thermal dissipation in dense base station arrays.
- China's domestic base station buildouts:MIIT localization requirements redirect supply chain capacity toward captive CMOS foundry services for 5G massive MIMO deployments.
- Sub-10nm lithography maturation:Advanced silicon processes enable digital baseband integration that eliminates discrete interface components between modem and RF stages.
Market Restraints
- Silicon-on-insulator wafer cost volatility:SOI substrate pricing fluctuations compress gross margins for CMOS amplifier specialists without captive wafer supply.
- Gallium nitride substitution threat:GaN-on-SiC devices retain efficiency advantages above 3.5GHz that constrain CMOS addressable market in upper mid-band spectrum.
- REACH chemical compliance friction:ECHA restrictions on lead-free solder metallization force foundries to requalify packaging stacks, extending product development cycles.
Strategic Opportunities
- India PLI scheme localization:Production-linked incentives for telecom equipment manufacturing attract CMOS packaging investments to serve South Asian 5G rollouts.
- Open RAN disaggregation:O-RAN Alliance interface specifications create procurement channels for standalone CMOS amplifiers outside integrated front-end modules.
- Ultra-low-power IoT sensor networks:IEEE 802.11ah and LoRaWAN deployments displace discrete RF components with integrated CMOS transmitters in agricultural and industrial monitoring.
Industry Challenges
- RF-linearization algorithm talent scarcity:Digital pre-distortion and envelope tracking expertise concentrates among legacy baseband semiconductor teams, constraining new entrant capability building.
- FCC Part 27 certification timelines:Commercial transmitter approval processes for new CMOS amplifier variants extend 14-18 months, compressing product refresh windows against process node transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CMOS Power Amplifier Market |
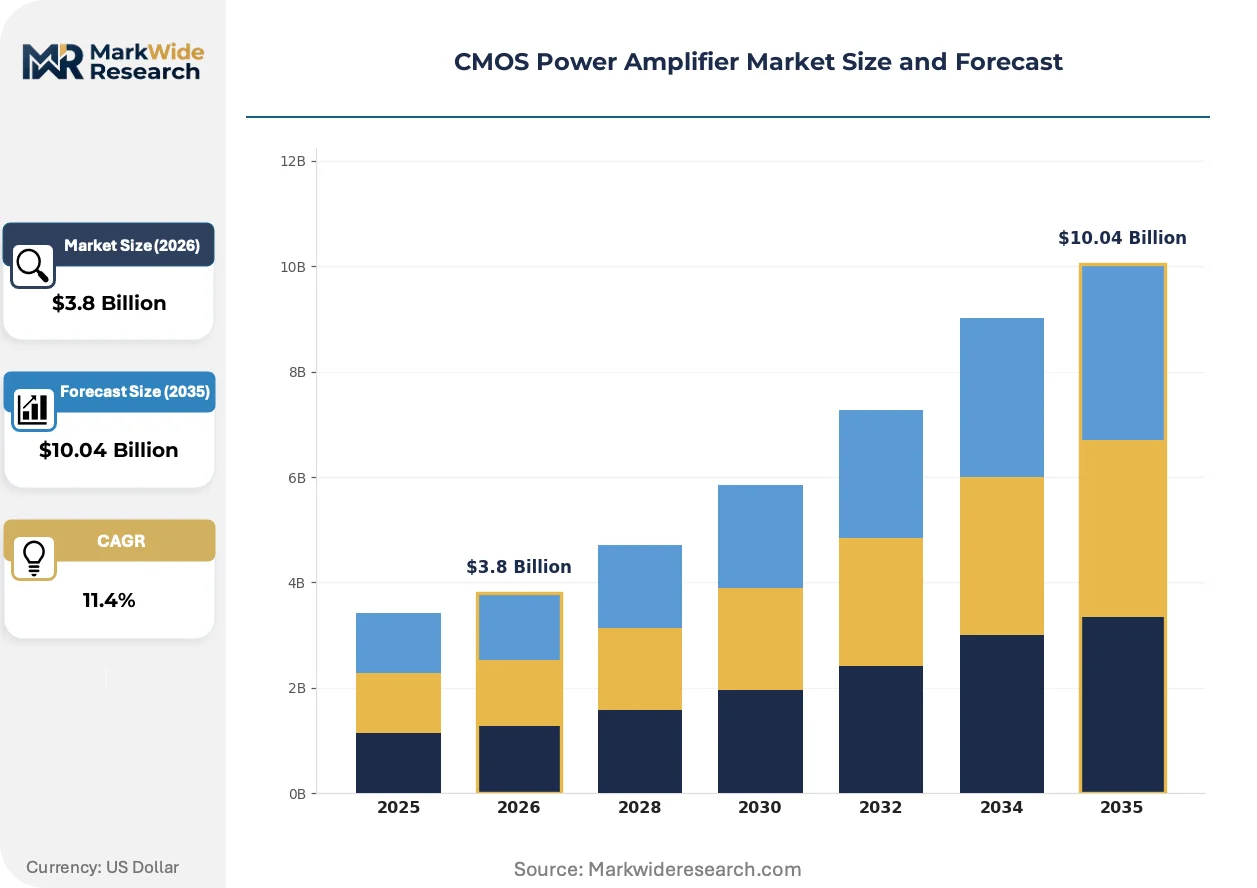
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linearity, Efficiency, Gain, Frequency Range End User: Telecommunications, Consumer Electronics, Automotive, Industrial Technology: CMOS, BiCMOS, GaN, SiGe Application: RFID, 5G, WLAN, IoT |
| Companies Covered | Murata Manufacturing, Infineon Technologies, Broadcom, Toshiba Corporation, Analog Devices, Skyworks Solutions, Texas Instruments, ACCO Semiconductor, Qualcomm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CMOS Power Amplifier Market Emerging Trajectories
Silicon process convergence with digital signal processing is dissolving traditional boundaries between power amplification and linearization functions. This structural shift is enabling new architectural approaches that compress bill-of-materials complexity while tightening regulatory compliance.
Envelope tracking power management is integrating with CMOS amplifier cores to dynamically modulate supply voltage against instantaneous signal amplitude. Base station OEMs are adopting these combined solutions to meet FCC spectral mask requirements without external linearization modules. The technology is integrating analog power stages with digital control loops that previously required separate ASIC implementations.
REACH chemical restrictions are forcing metallization stack redesigns across European-bound CMOS amplifier production. ECHA substance restrictions on hexavalent chromium plating and specific tin-lead alloys compel foundries to qualify alternative barrier layers and solder compositions. Packaging specialists serving EU telecommunications infrastructure face 12-18 month requalification cycles that delay new product introductions.
Carrier procurement is consolidating RF front-end sourcing around modem-to-antenna platform vendors capable of certifying complete transmit chains. Tier-1 telecommunications equipment manufacturers are disintermediating standalone amplifier suppliers in favor of integrated module providers who assume full linearity compliance liability. This concentration is most visible in China's 5G base station tenders where MIIT domestic content requirements favor vertically integrated subsystem suppliers.
CMOS Power Amplifier Market Segmentation
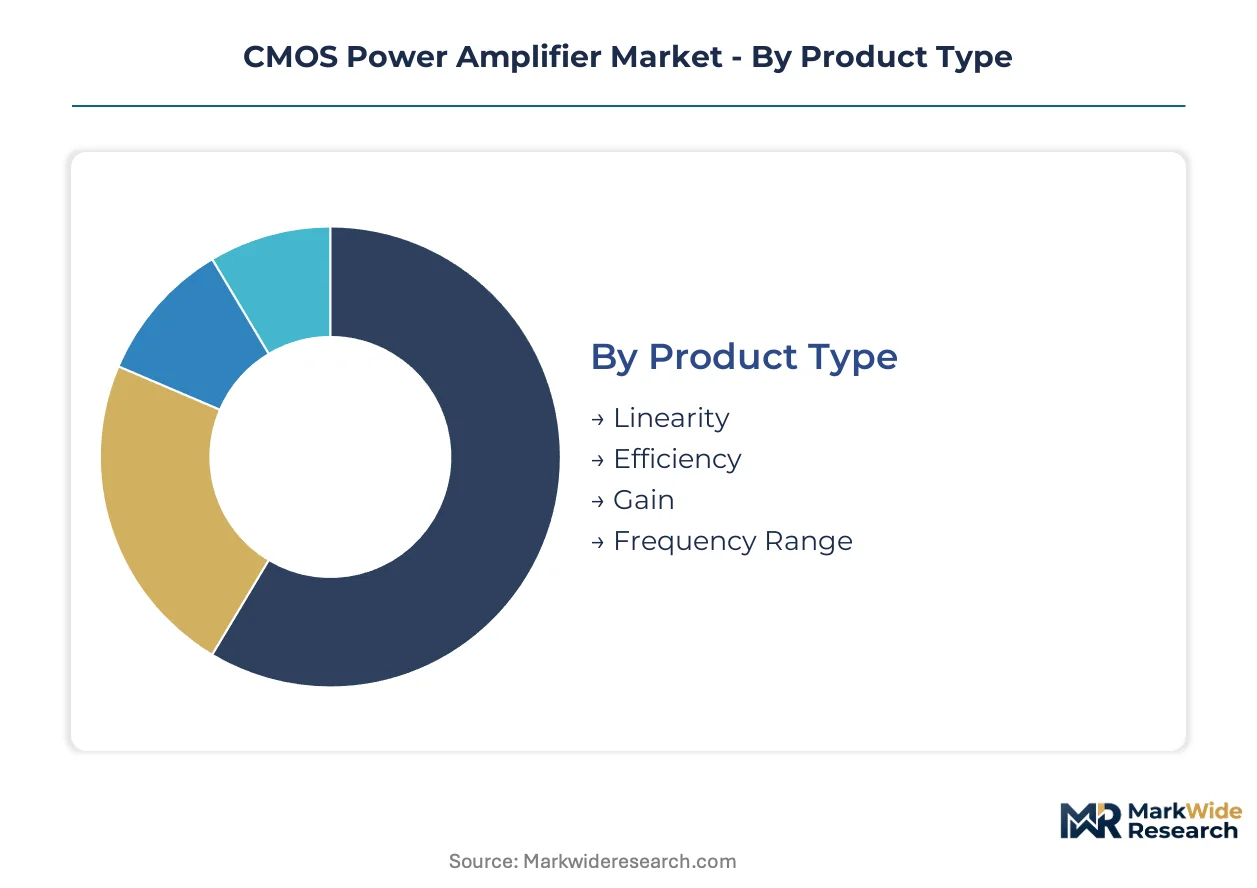
CMOS power amplifier procurement patterns diverge sharply across frequency bands, integration requirements, and regulatory compliance burdens. Understanding these segment boundaries clarifies where silicon-based solutions displace compound semiconductors versus where GaN and GaAs retain structural advantages.
Product Type:
Buyers in this category prioritize either spectral purity for dense constellation schemes or thermal headroom for envelope-tracking implementations.
- Linearity:Error vector magnitude specifications below 3% enable 256-QAM and 1024-QAM modulation in 5G massive MIMO arrays. European base station OEMs under EU Green Deal thermal mandates favor these variants for reduced cooling overhead in urban small-cell clusters.
- Efficiency:Power-added efficiency above 35% at peak output reduces DC power draw in battery-constrained IoT endpoints. Agricultural sensor networks across the American Midwest and Australian wheat belts specify these amplifiers for solar-powered LoRaWAN gateways operating multi-year deployment cycles.
- Gain:Fixed-gain blocks simplify RF chain design for cost-sensitive consumer electronics.
- Frequency Range:Broadband architectures accommodate multi-band carrier aggregation in smartphone front-end modules.
Linearity leads volumes today; efficiency is gaining share fastest.
End User:
Volume concentration and margin structure split cleanly between infrastructure capex cycles and consumer replacement demand.
- Telecommunications:Base station OEMs specify CMOS amplifiers for sub-6GHz massive MIMO where channel counts exceed 64 per antenna array. China's MIIT-directed 5G buildouts concentrate demand among domestic equipment vendors qualifying captive foundry supply.
- Consumer Electronics:Smartphone manufacturers integrate CMOS power stages into modem-to-antenna modules to compress bill-of-materials count. FCC Part 27 certification requirements in the United States and CE marking in Europe impose identical linearity standards regardless of integration level.
- Automotive:V2X communication modules specify automotive-grade CMOS for C-V2X PC5 interface compliance.
- Industrial:Private 5G networks in German manufacturing clusters and Japanese automotive plants deploy ruggedized CMOS amplifiers for deterministic latency.
Telecommunications dominates absolute consumption; automotive is expanding most quickly.
Technology:
Process selection hinges on frequency ceiling, integration density, and foundry access rather than pure performance optimization.
- CMOS:Sub-10nm lithography enables digital baseband co-integration that eliminates discrete interface components between modem and RF stages. Qualcomm and MediaTek smartphone platforms anchor demand for these fully-integrated transmit chains.
- BiCMOS:Combines bipolar linearity with CMOS logic density for mixed-signal radar front-ends in automotive applications.
- GaN:Gallium nitride-on-SiC retains efficiency advantages above 3.5GHz that constrain CMOS addressable market in upper mid-band spectrum.
- SiGe:Silicon-germanium processes compete with CMOS in sub-6GHz implementations where cost-integration trade-offs remain unresolved.
CMOS captures the widest deployment base; GaN is climbing the fastest in revenue per unit.
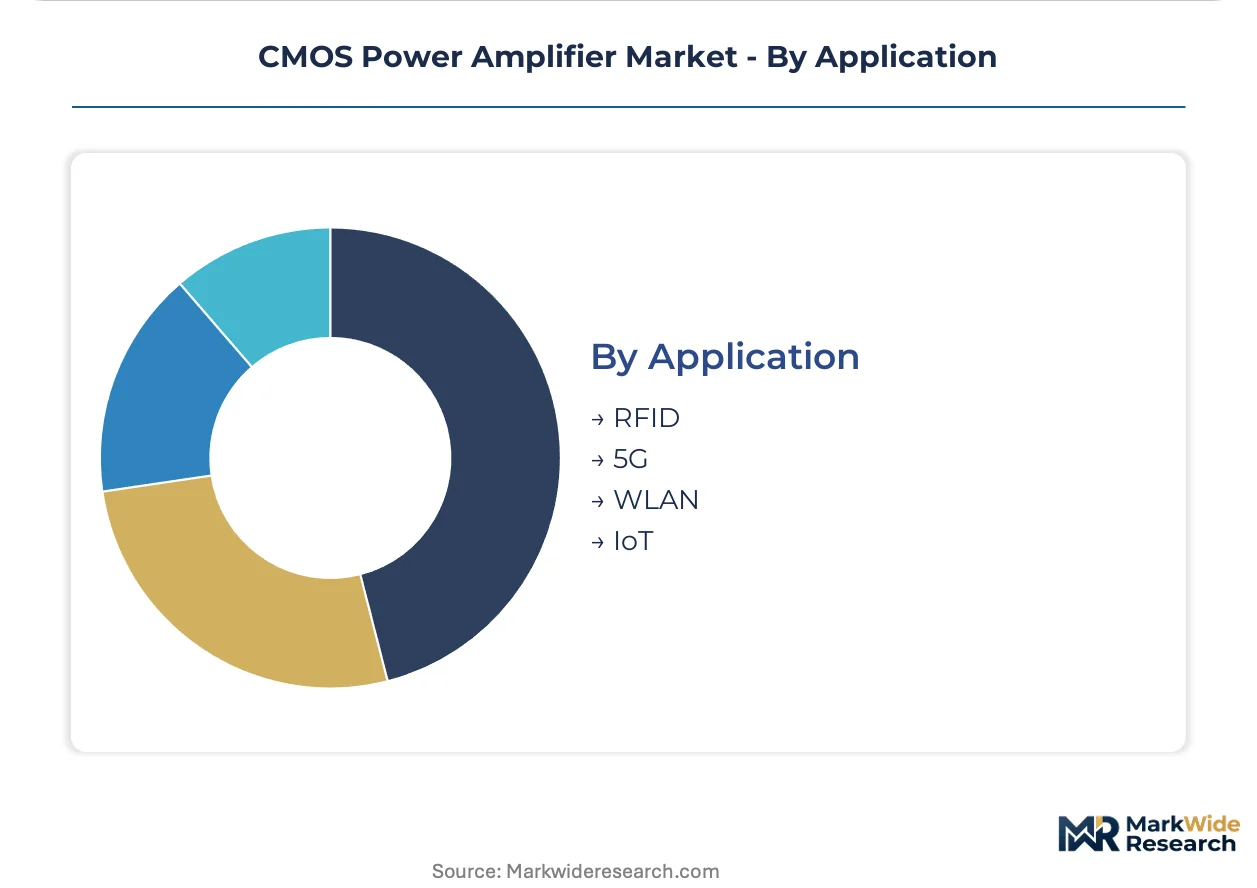
Application:
Spectral allocation and duty cycle requirements determine whether integrated CMOS solutions suffice or discrete compound semiconductors prove necessary.
- 5G:Massive MIMO base stations require hundreds of low-cost amplifiers per installation, with MIIT localization requirements in China redirecting supply chain capacity toward captive foundry services. EU Green Deal energy-efficiency mandates accelerate adoption of sub-5V designs that reduce thermal dissipation in dense arrays.
- IoT:IEEE 802.11ah and LoRaWAN deployments displace discrete RF components with integrated CMOS transmitters in agricultural and industrial monitoring. Ultra-low-power designs operating below 1mW in sleep mode are expanding most quickly.
- RFID:UHF passive tag readers specify CMOS for cost-sensitive inventory tracking in retail and logistics.
- WLAN:Wi-Fi 6E and Wi-Fi 7 access points demand linearity for 4096-QAM in 6GHz spectrum.
5G leads absolute volumes today; IoT is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent clusters in Shenzhen, Munich, and Austin anchor CMOS power amplifier design activity. These concentrations attract fabless semiconductor firms and integrated device manufacturers seeking proximity to telecommunications OEMs. Regional specialization patterns reflect divergent regulatory regimes and infrastructure deployment cycles.
United States
Massive MIMO base station deployment by Verizon and AT&T drives demand for sub-6GHz CMOS amplifiers. FCC Part 27 certification requirements impose 14-18 month approval timelines that compress product refresh windows. Austin and Boston house design centers where envelope tracking and digital pre-distortion expertise concentrates among legacy baseband engineering teams.
China
Domestic 5G buildouts by Huawei and ZTE consume hundreds of amplifiers per massive MIMO installation. MIIT localization requirements redirect supply chain capacity toward captive foundry services. Shenzhen and Beijing host vertically integrated subsystem suppliers qualifying domestic CMOS production for state-directed infrastructure tenders.
Germany
Industrial private 5G networks in automotive plants specify ruggedized CMOS amplifiers for deterministic latency. EU Green Deal energy-efficiency mandates prioritize sub-5V designs reducing thermal dissipation. Munich anchors RF front-end development for automotive V2X modules serving BMW and Volkswagen supply chains.
Japan
Smartphone manufacturers integrate CMOS power stages into compact front-end modules for export markets. METI funding supports sub-10nm lithography maturation enabling baseband-RF integration. Tokyo and Nagoya clusters concentrate packaging expertise for high-frequency ceramic substrates used in 5G millimeter-wave arrays.
South Korea
Modem-to-antenna platform vendors source CMOS transmit chains for flagship handset programs. MFDS radio equipment certification aligns with CE marking requirements for European export compatibility. Seoul Capital Area houses Samsung and LG RF procurement teams consolidating supplier relationships around integrated module providers.
CMOS Power Amplifier Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent cost structures. IDMs with captive foundries exploit wafer supply security while fabless specialists leverage advanced lithography access through TSMC partnerships. Three archetypes dominate: vertically integrated Japanese component houses, European automotive-RF conglomerates, and American modem-platform vendors. Competitive moves concentrate on backward integration into gallium arsenide fabs and strategic partnerships with Open RAN software vendors.
Within the integrated device manufacturer tier, Murata Manufacturing exemplifies ceramic packaging specialists leveraging materials science for high-frequency applications. Infineon Technologies anchors European supply through in-house production of RF front-end modules. Qualcomm Technologies occupies a position as a modem-to-antenna platform vendor reducing handset bill-of-materials complexity for smartphone OEMs.
| Leading Market Players |
|---|
| Murata Manufacturing |
| Infineon Technologies |
| Broadcom |
| Toshiba Corporation |
| Analog Devices |
| Skyworks Solutions |
| Texas Instruments |
| ACCO Semiconductor |
| Qualcomm Technologies |
| Others |
Supply Flow & Price Mechanics
Linearity certification tiers bifurcate CMOS power amplifier procurement between FCC Part 27-compliant premium modules and unlicensed IoT commodity variants, with that divergence manifesting in both unit pricing spreads and foundry allocation priorities across Taiwan and mainland China.
Pricing Analysis
Bundled modem-to-antenna platform sales dominate smartphone procurement, while unbundled standalone amplifiers persist in Open RAN base station disaggregation. Pricing stratifies across premium, standard, and economy tiers based on EVM performance below 3% and REACH-compliant packaging certification. Cost compression in the economy tier intensifies as Chinese foundries expand 28nm RF-CMOS capacity. Smartphone OEMs exhibit highest price sensitivity; automotive V2X module buyers prioritize thermal reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Munich, and Austin anchor hub-and-spoke fulfillment patterns for RF front-end modules. Manufacturing concentrates in Taiwan, South Korea, and China, with sub-10nm lithography feeding from TSMC and Samsung captive lines. Silicon-on-insulator wafers and ceramic packaging substrates constitute critical input dependencies. Single-source vulnerability in EU-bound REACH-compliant metallization stacks threatens European delivery timelines. Distribution runs through vertically integrated subsystem suppliers rather than standalone component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CMOS power amplifier manufacturing arbitrage favors captive foundry investments in India under PLI scheme incentives versus European REACH compliance cost burdens, exploiting a structural regulatory cost differential that redirects packaging capacity toward South Asian 5G rollout demand.
For Market Incumbents: Acquire gallium arsenide fab assets to defend against GaN substitution above 3.5GHz. Qualcomm and MediaTek platform consolidation threatens standalone amplifier suppliers; backward integration into ceramic packaging secures thermal performance differentiation for base station OEMs. MIIT localization requirements in China demand captive foundry partnerships or joint ventures with domestic semiconductor houses. For New Entrants and Emerging Players: Envelope tracking algorithm IP offers a technology-first wedge against legacy baseband engineering concentration. Agricultural LoRaWAN gateways and Indian smart metering deployments represent penetrable white-space segments with lower FCC certification barriers. Partner with Open RAN software vendors for disaggregated RF component qualification bypassing integrated module incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where fabless specialists lack SOI wafer supply security against volatile substrate pricing. Long-term viability favors IDMs with captive packaging capabilities and automotive-grade qualification pathways. Watch for MIIT tender announcements redirecting Chinese domestic content requirements as inflection signals for supply chain localization momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SOI Wafer Supply | Captive silicon-on-insulator sourcing insulates margins against substrate price volatility affecting fabless competitors. |
| REACH-Compliant Packaging Stack Requalification | ECHA metallization compliance unlocks European telecommunications infrastructure procurement under Green Deal mandates. |
| Open RAN Alliance Interface Certification | O-RAN specifications create standalone amplifier procurement channels outside integrated front-end module consolidation. |
| Envelope Tracking Algorithm Acquisition | Digital pre-distortion expertise concentrates among legacy baseband teams; talent scarcity commands premium valuations. |
| India PLI Scheme Manufacturing Localization | Production-linked incentives attract packaging investments serving South Asian 5G deployment cycles. |
Methodological Framework
Direct dialogue with RF front-end procurement managers, baseband semiconductor engineering directors, foundry operations executives, and telecommunications equipment OEM sourcing leads grounded qualitative assessment. Secondary validation drew from FCC equipment authorization databases, MIIT 5G tender disclosures, ECHA substance restriction updates, and SEC semiconductor segment filings. Bottom-up unit demand modeling triangulated against top-down infrastructure capex forecasts.
Bottom-up volume projections aggregated across frequency band, integration level, and end-use application segments over the projection horizon. Analytical frameworks modeled sub-6GHz versus millimeter-wave deployment splits, captive versus fabless supply chain configurations, and EU Green Deal thermal mandate adoption curves. CAGRs derived from linear interpolation between base and terminal year demand points, cross-checked against foundry capacity expansion announcements and carrier spectrum auction timelines.
The model holds under sustained 5G massive MIMO deployment cadence and stable SOI wafer pricing; deviation in GaN-on-SiC cost reduction trajectories or REACH enforcement intensity would shift segment share projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Asia Pacific Logic IC Market
IC (Integrated Circuits)
Motor Driver IC Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Asia Pacific Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Analog Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market