
 Japan Integrated Circuit (IC) Market | 2026-2036
Japan Integrated Circuit (IC) Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Integrated Circuit (IC) Market Insights
Aftermarket service revenue for legacy node ICs is reconfiguring margin pools away from pure wafer sales toward lifecycle support contracts. Renesas Electronics leverages its automotive MCU dominance to sustain long-term supply agreements with domestic OEMs. Sony Semiconductor Solutions Group anchors image sensor production through captive design rules and fab partnerships. ROHM Semiconductor specializes in power management discretes that complement its expanding IC portfolio for EV powertrains.
An integrated circuit is a miniaturized electronic circuit comprising semiconductor devices and passive components fabricated on a single silicon substrate, typically using photolithography processes with feature nodes ranging from mature 40nm to advanced 7nm geometries, serving to process, store, or transmit electrical signals in electronic systems. Digital ICs command the largest revenue share due to their ubiquity in computing and communications infrastructure, while power management ICs represent the fastest-expanding category as electrification multiplies voltage regulation requirements across automotive and industrial applications. Mixed-signal ICs occupy critical interface positions where analog sensor data must convert to digital streams, concentrating margins in high-reliability automotive and medical segments.
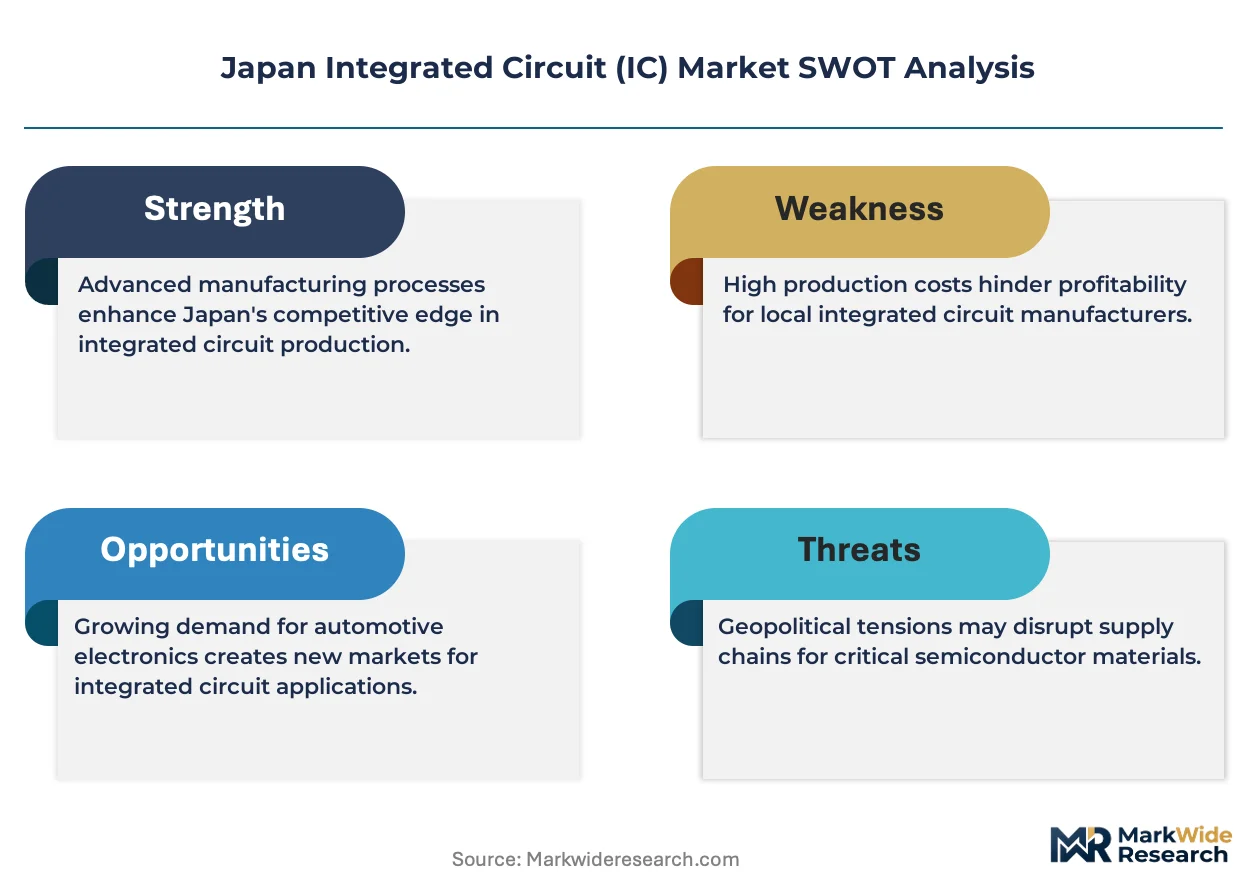
METI's semiconductor strategy and JIS standards frameworks shape domestic capacity investments and export control compliance, while PMDA and METI jointly influence medical device IC certification pathways that gate market access for implantable and diagnostic electronics. The EU AI Act and REACH chemical restrictions on semiconductor materials are forcing Japanese suppliers to reformulate interconnect metals and passivation layers for European-bound shipments. Stakeholders must monitor how METI's next subsidy tranches allocate between legacy node security and advanced logic pursuit.
Market Dynamics
Japanese IC demand pivots around automotive platform electrification as domestic OEMs phase out internal combustion architectures, forcing foundries to rebalance capacity toward power management and mixed-signal geometries while METI subsidy flows redirect toward 7nm domestic production.
Growth Catalysts
- Automotive powertrain electrification:Domestic vehicle manufacturers are consolidating MCU and power management IC procurement around long-term supply agreements, locking in wafer capacity through 2030.
- METI semiconductor revitalization subsidies:Direct capital grants for advanced node fabrication are pulling equipment vendors and materials suppliers into clustered investments in the Tokyo-Yokohama corridor.
- EU AI Act compliance demand:European-bound shipments require reformulated interconnect metals and passivation layers, creating premium qualification revenue for Japanese suppliers with existing JIS-RoHS dual certification.
Market Restraints
- Advanced lithography equipment concentration:Extreme ultraviolet scanner availability constrains domestic 7nm ramp schedules to single-source Dutch equipment cycles.
- Silicon wafer input cost volatility:300mm substrate pricing fluctuates with polysilicon energy intensity, compressing foundry margins on legacy node contracts.
- Fluorinated gas regulatory friction:REACH and F-Gas Regulation restrictions on etching chemistry imports are forcing European-bound production into separate process flows.
Strategic Opportunities
- Kyushu regional fab clustering:Underutilized 200mm capacity in Kumamoto and Miyazaki prefectures offers brownfield expansion for automotive-grade discrete integration.
- Chiplets and 2.5D packaging convergence:Heterogeneous integration of logic dies with HBM stacks is opening new substrate and interposer demand for domestic OSATs.
- Medical device IC certification pathways:PMDA-METI joint review frameworks for implantable electronics are creating first-mover advantage for suppliers with ISO 13485 quality systems.
Industry Challenges
- Process engineer talent scarcity:Advanced node yield optimization requires specialists in computational lithography and plasma etch physics that domestic universities underproduce.
- Legacy-automotive integration complexity:Functional safety certification for ISO 26262 ASIL-D grades demands 18-24 month validation cycles that compress design win windows.
- IP licensing fragmentation:RISC-V and proprietary ARM architecture disputes are complicating microcontroller roadmap decisions for tier-two suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Integrated Circuit (IC) Market |
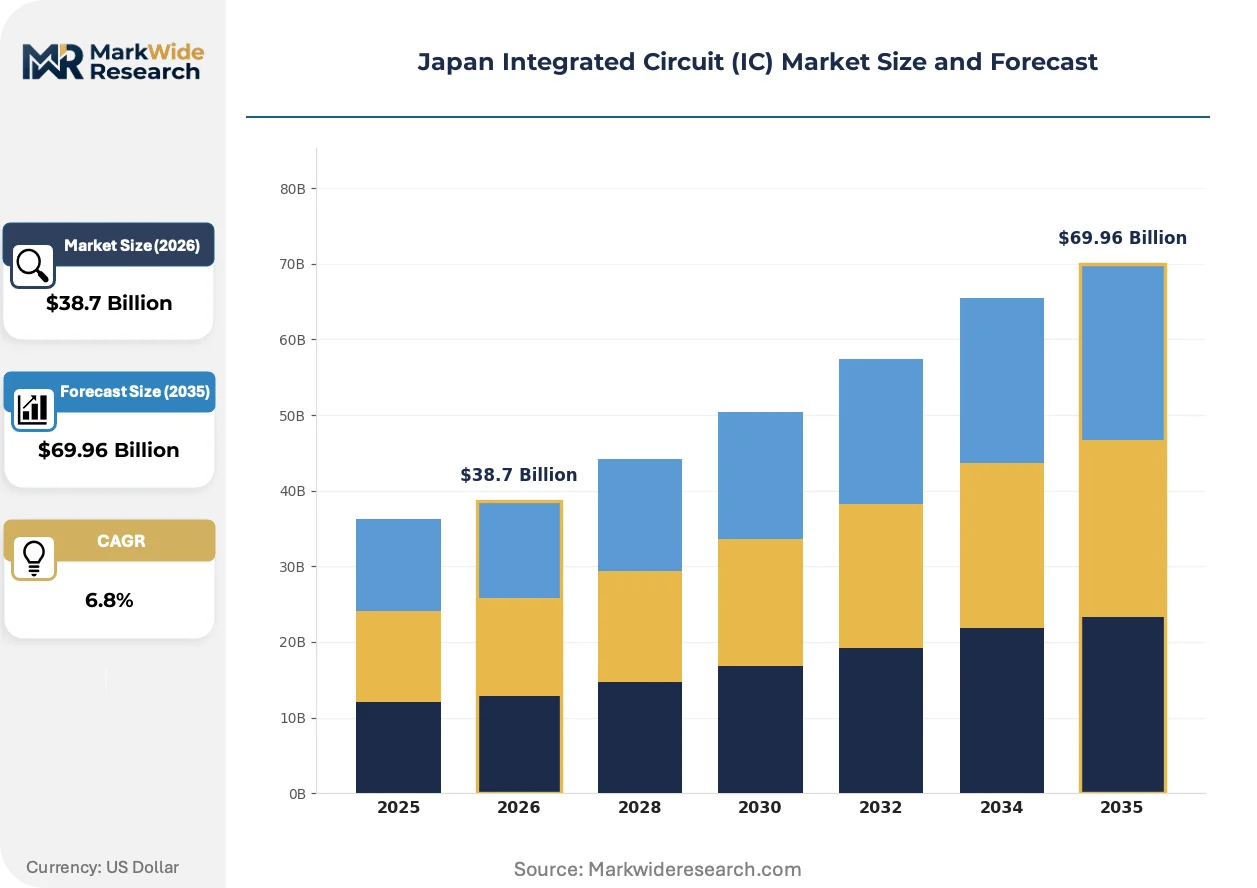
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog ICs, Digital ICs, Mixed-Signal ICs, Power Management ICs End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Technology: CMOS, BiCMOS, BiPolar, SOI Form Factor: Integrated Circuits, System-on-Chip, Memory Chips, Custom ICs |
| Companies Covered | Renesas Electronics Corporation, Sony Semiconductor Solutions Group, ROHM Semiconductor, Kioxia Holdings Corporation, Mitsubishi Electric Corporation, Toshiba Electronic Devices & Storage Corporation, Fujitsu Limited, NXP Semiconductors N.V., Infineon Technologies AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Integrated Circuit (IC) Market Trends and Innovations
Digital twin implementation is compressing fab ramp schedules and yield learning curves, while regulatory chemical reformulation and procurement model restructuring reshape competitive positioning across the value chain.
Virtual fab simulation software is virtualizing process development by allowing photolithography and etch parameter optimization without physical wafer consumption. Automotive foundry customers are demanding virtual qualification data packages before committing to volume production slots. This compression of the traditional silicon learning curve is virtualizing margin protection for IDMs facing aggressive EV platform deadlines.
EU REACH Annex XVII restrictions on PFAS and fluorinated greenhouse gases are forcing reformulation of C4F8 and SF6-based dielectric etch chemistries for European-bound shipments. Japanese materials suppliers with JIS-certified alternative chemistries are capturing qualification premiums while competitors face 12-18 month revalidation timelines. Power management ICs with European distribution exposure are most affected, with several domestic suppliers accelerating plasma etch tool retrofits.
Long-term supply agreements now dominate automotive MCU procurement, displacing spot market purchasing and quarterly price negotiations. Tier-one OEMs are consolidating vendor lists to three qualified suppliers per function, locking in volume commitments against capacity reservation fees. This concentration is most visible in the Kanto region, where Toyota, Honda, and Nissan procurement offices coordinate synchronized qualification schedules with nearby design houses.
Japan Integrated Circuit (IC) Market Segmentation
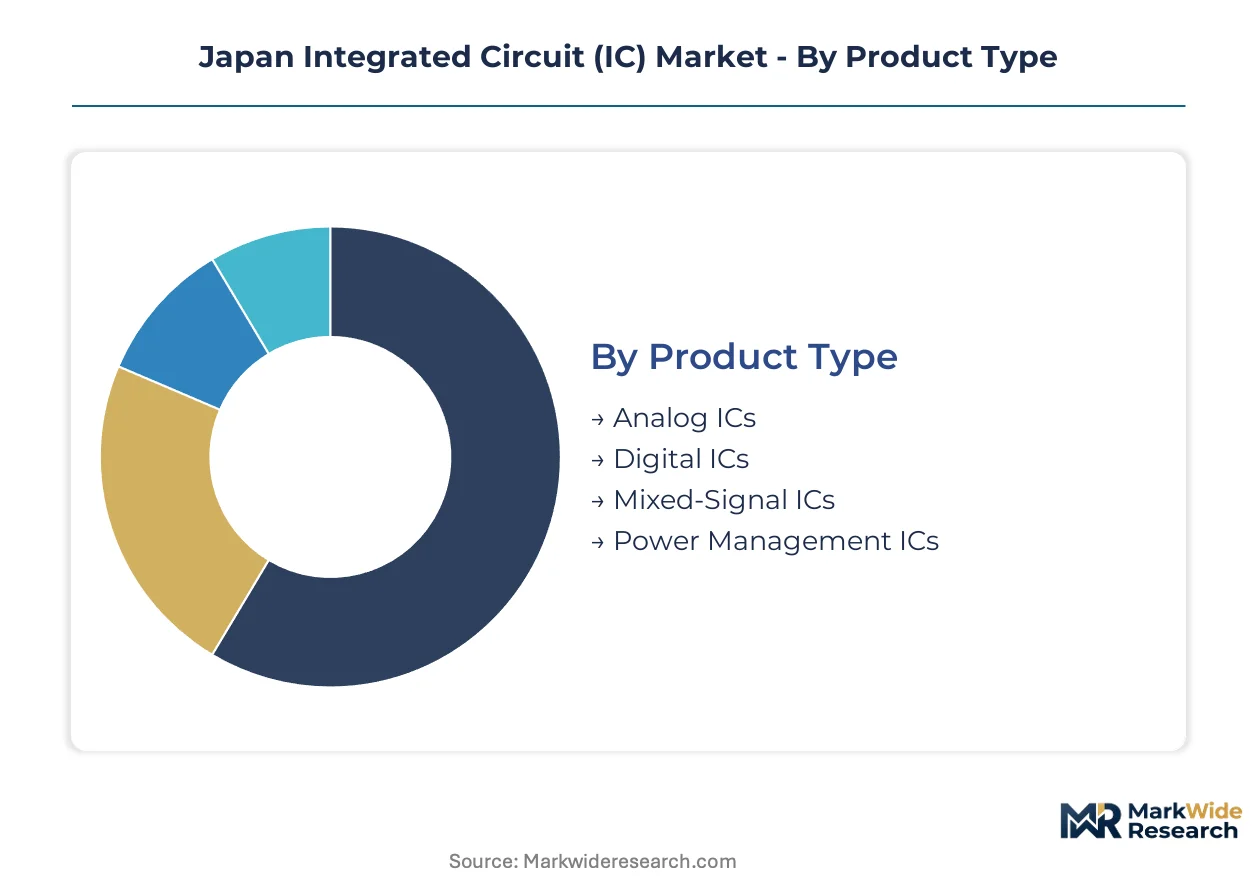
Segmentation reveals how Japanese IC demand fragments across competing technical requirements. Product type and end-user splits expose where domestic fabrication investments concentrate.
Product Type:
Cost tier differentiation separates commodity analog functions from premium digital logic.
- Digital ICs:Logic gates, microprocessors, and memory arrays fabricated at 7-40nm nodes process binary data streams. Kanto region fabs prioritize these for server and AI accelerator demand. Long-term supply agreements with domestic OEMs lock in wafer capacity through decade-end.
- Power Management ICs:Voltage regulators, DC-DC converters, and battery charging circuits manage electrical distribution across systems. Automotive powertrain electrification multiplies unit requirements per vehicle. METI subsidies redirect toward these geometries as EV platforms scale.
- Analog ICs:Operational amplifiers, comparators, and signal conditioning circuits interface with physical sensors.
- Mixed-Signal ICs:Data converters and interface bridges translate between analog and digital domains.
Digital ICs command the established base. The steepest expansion runs through Power Management ICs.
End User:
Application concentration determines which JIS certification tiers suppliers must maintain.
- Automotive:Engine control modules, ADAS processors, and battery management systems require ISO 26262 ASIL-D functional safety grades. Toyota, Honda, and Nissan procurement offices in the Kanto region synchronize qualification schedules with nearby design houses. METI's semiconductor revitalization policies prioritize this segment for domestic capacity reservation.
- Consumer Electronics:Smartphones, wearables, and home appliances drive high-volume, short-lifecycle demand. Image sensor integration for camera modules concentrates in Sony Semiconductor's captive supply chain.
- Telecommunications:Baseband processors and RF front-end modules enable 5G infrastructure deployment.
- Industrial Equipment:Programmable logic controllers and motor drives demand extended temperature range specifications.
Automotive anchors volume commitment structures. Consumer Electronics generates the fastest design cycle turnover.
Technology:
Maturity levels separate legacy process nodes from leading-edge investments.
- CMOS:Complementary metal-oxide-semiconductor logic dominates digital IC fabrication with superior power efficiency. Tokyo-Yokohama corridor foundries concentrate 7nm CMOS capacity for advanced node pursuit.
- BiCMOS:Bipolar-CMOS integration combines high-speed analog with dense digital logic for mixed-signal applications.
- BiPolar:Discrete transistor arrays deliver high-current drive capability for power applications.
- SOI:Silicon-on-insulator substrates reduce parasitic capacitance for RF and radiation-hardened designs.
CMOS underpins the installed fabrication base. SOI claims the fastest qualification pace for specialized defense and space applications.
Form Factor:
Integration depth determines substrate complexity and OSAT partnership requirements.
- System-on-Chip:CPU, GPU, and memory subsystems integrated on single die maximize performance per watt. Automotive ADAS platforms drive heterogeneous integration with HBM stacks.
- Memory Chips:DRAM and NAND flash arrays store program and user data across computing tiers.
- Integrated Circuits:Standard packaged dies serve general-purpose logic and analog functions.
- Custom ICs:Application-specific designs optimize for unique electrical or mechanical constraints.
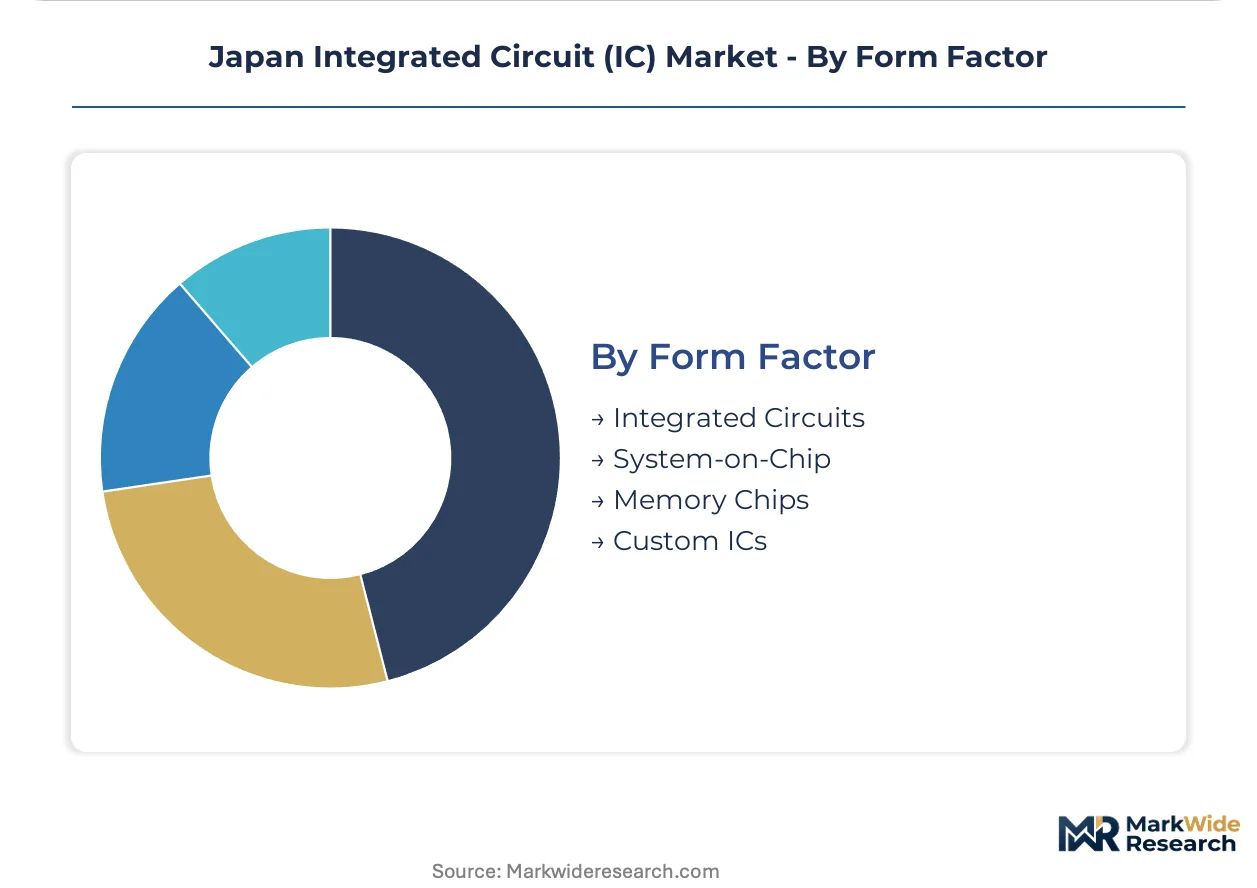
System-on-Chip integration concentrates R&D investment. Custom ICs expand most quickly for medical device certification pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement offices in the Kanto region lock in capacity through decade-end, while consumer electronics buyers in Kansai negotiate shorter-term flexibility. Price elasticity varies sharply across these demand pools.
Kanto
Toyota, Honda, and Nissan electrification programs drive power management IC demand. METI's semiconductor revitalization subsidies concentrate capital grants in the Tokyo-Yokohama corridor. Foundry clusters in Yokohama and Tsukuba rebalance toward 7nm CMOS capacity for AI accelerator production.
Kansai
Osaka-based consumer electronics manufacturers source image sensors and display driver ICs. JIS standards alignment governs quality certification for smartphone-bound shipments. Design houses in Kyoto and semiconductor packaging facilities in Osaka prefecture coordinate short-lifecycle production ramps.
Chubu
Toyota Motor Corporation's Nagoya headquarters anchors automotive MCU procurement. Regional suppliers maintain ISO 26262 ASIL-D certification for functional safety compliance. Industrial equipment manufacturers in Aichi prefecture source mixed-signal ICs for programmable logic controllers.
Kyushu
Underutilized 200mm fab capacity in Kumamoto and Miyazaki prefectures offers brownfield expansion for automotive-grade discrete integration. METI subsidies target legacy node security for domestic supply chain resilience. Power management IC specialists occupy captive fab arrangements with domestic tier-one suppliers.
Tohoku
Silicon wafer manufacturing clusters in Miyagi and Iwate prefectures supply 300mm substrates to Kanto foundries. PMDA-METI joint review frameworks for medical device ICs create certification pathways for implantable electronics. Materials suppliers reformulate interconnect metals for EU REACH compliance on European-bound shipments.
Japan Integrated Circuit (IC) Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Domestic IDMs retain process integration depth across automotive and industrial segments, while foundry-dependent fabless players compete on design velocity. Three archetypes define the field: vertically integrated conglomerates with captive fabs, automotive-specialist MCU suppliers with long-term OEM agreements, and memory-focused diversifiers with materials science advantages. Competitive moves center on capacity reservation fees for automotive procurement and heterogeneous packaging partnerships for AI accelerator demand.
Among domestic conglomerates, Renesas Electronics Corporation and Sony Semiconductor Solutions Group occupy positions at opposite ends of the application spectrum. Renesas exemplifies the automotive-specialist archetype through its MCU dominance and OEM supply agreements. Sony Semiconductor anchors image sensor production with design-rule control and fab partnerships. ROHM Semiconductor sits within the power management tier, specializing in discretes that complement EV powertrain electrification. These three represent how Japanese suppliers segment across automotive, consumer imaging, and electrification vectors without direct overlap.
| Leading Market Players |
|---|
| Renesas Electronics Corporation |
| Sony Semiconductor Solutions Group |
| ROHM Semiconductor |
| Kioxia Holdings Corporation |
| Mitsubishi Electric Corporation |
| Toshiba Electronic Devices & Storage Corporation |
| Fujitsu Limited |
| NXP Semiconductors N.V. |
| Infineon Technologies AG |
| Others |
Pricing and Supply Chain Analysis
EUV scanner single-source dependency from Dutch suppliers compresses domestic 7nm ramp schedules and forces Japanese foundries into capacity reservation fee structures that widen pricing spreads between automotive long-term contracts and consumer spot purchases.
Pricing Analysis
Aftermarket service revenue for legacy node lifecycle support contracts now drives lifetime value capture beyond pure wafer sales. Three-tier pricing structure across premium ASIL-D certified automotive, standard industrial-grade, and economy consumer electronics tiers separates qualification-intensive safety-critical supply from commodity spot markets. Pricing pressure stems from 300mm silicon wafer input cost volatility tied to polysilicon energy intensity, compressing foundry margins on mature node contracts. Automotive OEM procurement offices exhibit lowest price sensitivity due to decade-long supply security mandates, while consumer electronics buyers in Kansai negotiate quarterly flexibility.
Supply Chain Analysis
Export-control restrictions on extreme ultraviolet lithography equipment limit flows from Dutch and Japanese vendors into Chinese fabs, redirecting equipment allocation toward Tokyo-Yokohama corridor capacity builds. Taiwan, South Korea, and the United States anchor geographic supply concentration for advanced logic and memory components. Raw material dependencies center on 300mm silicon wafers from Tohoku prefecture, high-purity fluorinated gases for plasma etch processes, and copper interconnect metals subject to EU REACH reformulation requirements. Single-source vulnerability runs through ASML EUV scanner availability. Distribution runs through direct foundry relationships with tier-one automotive OEMs and OSAT partnerships for heterogeneous packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive platform electrification fragments procurement into power management, mixed-signal, and advanced logic niches that reward specialized capability depth over scale breadth.
For Market Incumbents: Build captive fab capacity moats through METI subsidy capture for 7nm domestic production. Consolidate position by locking tier-one OEMs into capacity reservation agreements extending through decade-end. Deepen backward integration into 300mm silicon wafer supply through Tohoku prefecture partnerships. Counter threat from foundry-dependent fabless competitors by accelerating ISO 26262 ASIL-D certification pipelines. For New Entrants and Emerging Players: Kyushu regional underutilized 200mm fab capacity offers brownfield entry for automotive-grade discrete integration without greenfield capital intensity. Target medical device IC certification pathways where PMDA-METI joint review frameworks create first-mover advantage for ISO 13485 quality system holders. Pursue chiplets and 2.5D packaging convergence as go-to-market angle through OSAT partnerships bypassing front-end fab requirements. For Investors and Strategic Acquirers: The market sits at a subsidy-deployment phase that favors automotive-specialist MCU suppliers with long-term OEM agreements over memory-focused diversifiers. Five-to-ten year viability hinges on domestic advanced node execution against Taiwanese foundry scale. Acquisition target archetype: power management IC specialists with EV powertrain qualification and Kyushu captive fab arrangements. Signal to watch: METI subsidy tranche allocation between legacy node security and advanced logic pursuit.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Toyota, Honda, and Nissan procurement offices lock wafer capacity through 2030 against reservation fees. |
| Capacity Expansion | Tokyo-Yokohama corridor foundries rebalance toward 7nm CMOS for AI accelerator domestic production. |
| Backward Integration | Tohoku silicon wafer manufacturers secure 300mm substrate supply for Kanto foundry clusters. |
| Joint Venture | OSAT partnerships enable heterogeneous HBM integration without front-end fab capital intensity. |
| Green Manufacturing Transition | JIS-certified alternative chemistries capture REACH compliance premiums on European-bound power management ICs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of METI policy filings, JIS standards documentation, and EU regulatory registers. Primary interviews engaged semiconductor process engineers, automotive OEM procurement directors, foundry operations managers, and materials supplier technical leads. Secondary validation drew from customs trade data, SEC semiconductor equipment filings, and PMDA medical device certification databases. Bottom-up wafer demand modeling triangulates against top-down macroeconomic semiconductor consumption indices.
Forecast inputs incorporate automotive electrification platform roadmaps, METI subsidy disbursement schedules, and EU REACH chemical restriction implementation timelines. Segmentation dimensions span product type, end-user application, process technology node, and regional demand cluster across the analysis window. CAGRs derive from installed base replacement cycles, content-per-vehicle expansion rates, and foundry capacity utilization trajectories. Industry-specific inputs include EV powertrain semiconductor intensity curves and AI accelerator deployment forecasts.
Practitioners should monitor EU AI Act compliance deadlines, fluorinated gas regulatory friction, and extreme ultraviolet equipment allocation patterns for early signals of forecast deviation. Forecasts reflect assumptions on subsidy continuity, OEM electrification commitment durability, and alternative chemistry qualification timelines. Material shifts in Dutch lithography equipment export policy or METI funding priority reallocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Digital Potentiometer IC Market
IC (Integrated Circuits)
United States Integrated Circuits Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market
IC (Integrated Circuits)
Asia Pacific Logic IC Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Mixed Signal IC Market
IC (Integrated Circuits)
NFC Reader Ics Market
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
Standard Logic IC Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
3D Integrated Circuit Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market