
 United States Logic Integrated Circuits Market | 2026-2036
United States Logic Integrated Circuits Market Size, Share, and Industry Trends Forecast 2026-2036
United States Logic Integrated Circuits Market Insights
Domestic foundry capacity in the southwestern United States is restructuring as federal incentives draw capital toward advanced node production. Intel Corporation leverages its Arizona and Oregon fabrication complexes to anchor leading-edge logic supply. Texas Instruments sustains broad vertical integration across analog and embedded processing portfolios. Advanced Micro Devices competes aggressively in data center and PC processor segments through fabless design partnerships with TSMC.
Logic integrated circuits are semiconductor devices that perform Boolean operations and digital signal processing, typically fabricated on silicon wafers using photolithography with feature sizes measured in nanometers, and serve as the computational core of electronic systems. Digital ICs dominate volume shipments while mixed-signal ICs capture widening margin pools at the analog-digital boundary. CMOS technology leads manufacturing economics due to favorable power-delay characteristics, though SOI variants gain traction in radiation-hardened and RF applications. Automotive end users now represent the fastest-growing demand channel as electrification and autonomous systems multiply per-vehicle semiconductor content.
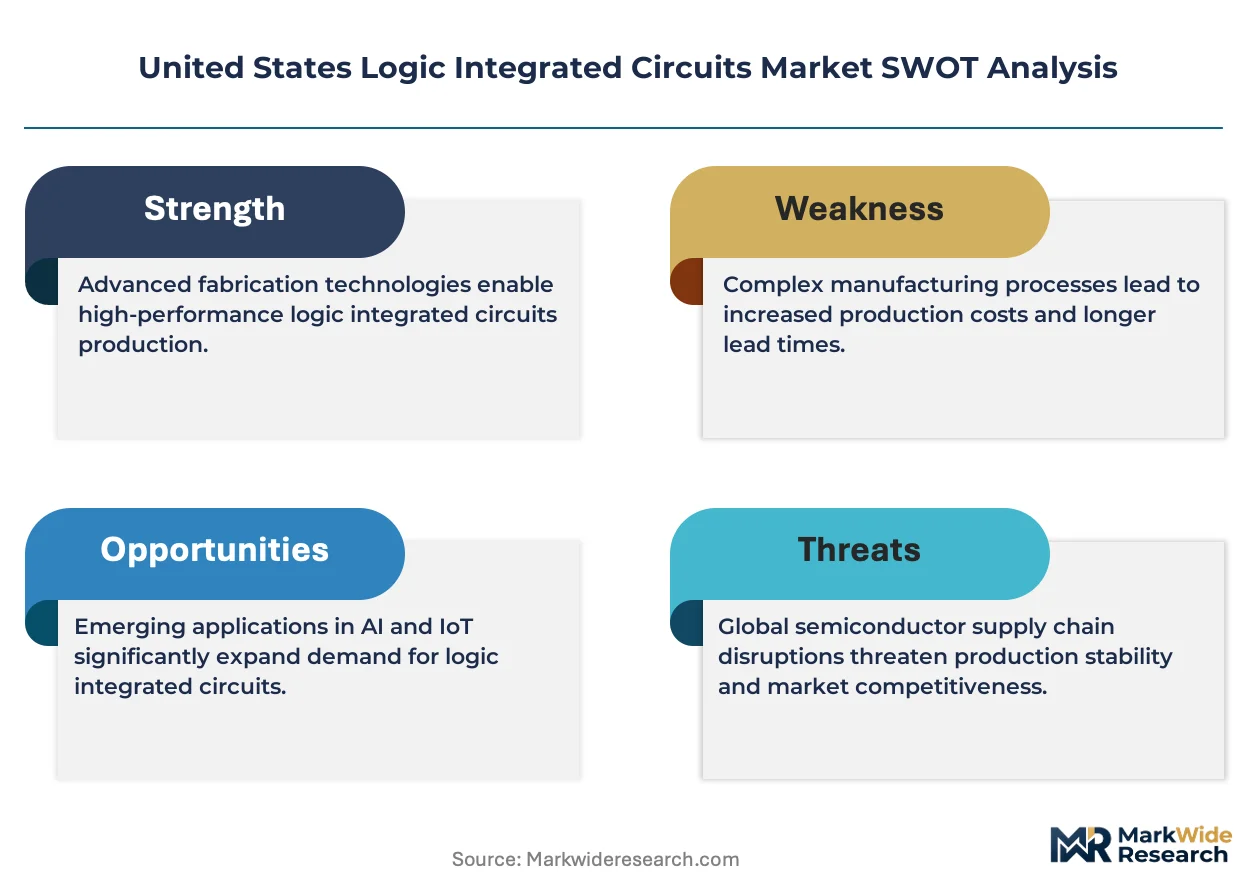
The CHIPS and Science Act shapes capital allocation through NIST-administered grants and Department of Commerce loan authority, while export controls administered by the Bureau of Industry and Security restrict access to advanced manufacturing equipment. EPA hazardous waste rules and OSHA semiconductor industry standards govern fab operations and worker exposure limits. Stakeholders must monitor how Commerce Department entity list updates and emerging state-level clean energy mandates reshape supply chain geography and equipment procurement timelines.
Market Dynamics
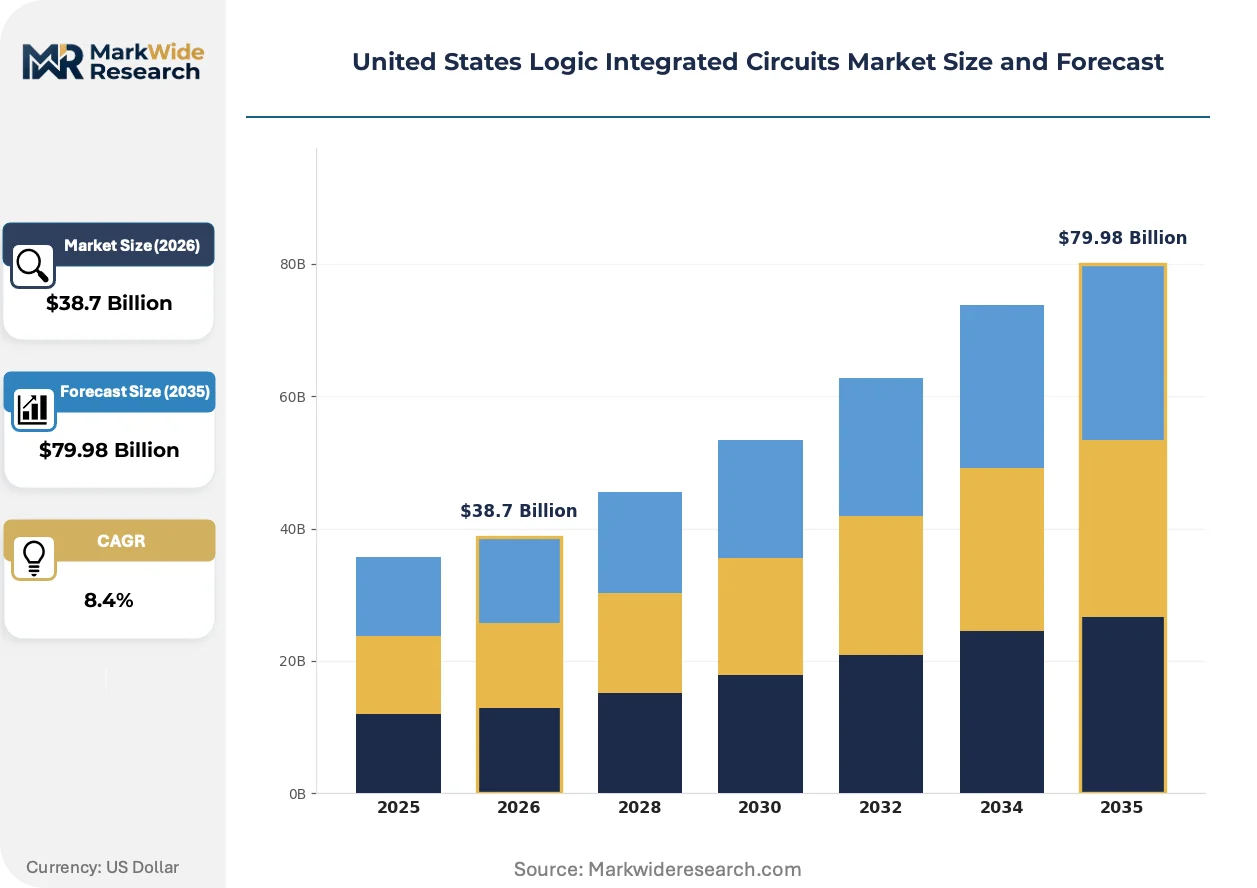
The CHIPS and Science Act is concentrating capital flows toward domestic fabrication facilities, fundamentally restructuring how logic IC capacity aligns with end-use demand across automotive electronics and data center accelerators. Federal loan guarantees and NIST-administered grants are accelerating fab construction timelines in Arizona and Texas.
Growth Catalysts
- CHIPS Act Incentives:Department of Commerce loan authority and manufacturing tax credits are de-risking greenfield fab investments. Capital commitments from equipment suppliers are following federal funding announcements.
- Automotive Electrification:Battery management systems and autonomous driving platforms are multiplying per-vehicle semiconductor content. Tier-1 suppliers are qualifying domestic logic IC sources for supply security.
- Data Center Acceleration:AI training and inference workloads are expanding demand for high-performance logic at advanced nodes. Cloud service providers are securing multi-year allocation agreements with foundry partners.
Market Restraints
- EUV Equipment Concentration:Extreme ultraviolet lithography systems rely on a single Dutch supplier, creating chokepoint vulnerability for sub-7nm production ramps.
- EPA Hazardous Waste Rules:Perfluorinated compound emissions limits are extending environmental permitting timelines for new fab construction. Compliance costs are elevating operational expenditure budgets.
- Technical Talent Scarcity:Process engineering and yield optimization expertise pools are insufficient relative to announced capacity expansion targets. Universities are struggling to scale specialized training programs.
Strategic Opportunities
- Defense Electronics:DOD trusted foundry programs are creating dedicated demand channels for radiation-hardened logic. Security clearance requirements limit foreign competition.
- Chiplets and Advanced Packaging:Heterogeneous integration is enabling performance gains without sole reliance on monolithic die shrinks. OSAT capacity in New York and Arizona is scaling to capture value migration.
- State Clean Energy Mandates:California and New York grid decarbonization requirements are accelerating on-site renewable power installation at fabrication complexes. Excess generation creates potential revenue streams.
Industry Challenges
- Cleanroom Construction Bottlenecks:Specialized contractors capable of semiconductor-grade facility buildout are overcommitted. Project delays are compressing equipment installation windows.
- Export Control Compliance:Bureau of Industry and Security entity list updates are requiring real-time screening of customer relationships. Licensing uncertainty is complicating long-term supply agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Logic Integrated Circuits Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog ICs, Digital ICs, Mixed-Signal ICs, Power Management ICs Technology: CMOS, Bipolar, BiCMOS, SOI End User: Consumer Electronics, Automotive, Telecommunications, Industrial Application: Signal Processing, Data Processing, Communication Systems, Control Systems |
| Companies Covered | Intel Corporation, Texas Instruments, Analog Devices, STMicroelectronics, Renesas Electronics Corporation, Advanced Micro Devices, Broadcom, NXP Semiconductors, Microchip Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Logic Integrated Circuits Market Trends and Innovations
Logic IC manufacturing is undergoing process architecture and supply configuration shifts that are compressing design-to-silicon cycles while expanding domestic production footprints.
Gate-all-around transistor architectures are replacing finFET structures at 3nm and below, delivering superior electrostatic control and power efficiency. Automotive semiconductor buyers are accelerating qualification timelines for these nodes to support next-generation autonomous systems. This transition is rewriting competitive positioning between foundries with early GAA yield maturity versus those trailing in process ramp schedules.
The Department of Commerce is administering CHIPS Act funding awards with domestic content requirements and technology safeguard provisions. Equipment procurement contracts now incorporate Buy American thresholds and supply chain security attestations. Advanced node projects in Arizona and Texas are navigating these conditions while securing complementary state-level incentive packages.
Cloud hyperscalers are consolidating logic IC procurement through direct foundry relationships rather than merchant semiconductor distributors. Vertical integration of chip design and silicon supply is displacing traditional component resale channels. This pattern is most pronounced in California and Washington state data center clusters where capital deployment scale justifies dedicated allocation negotiations.
United States Logic Integrated Circuits Market Segmentation
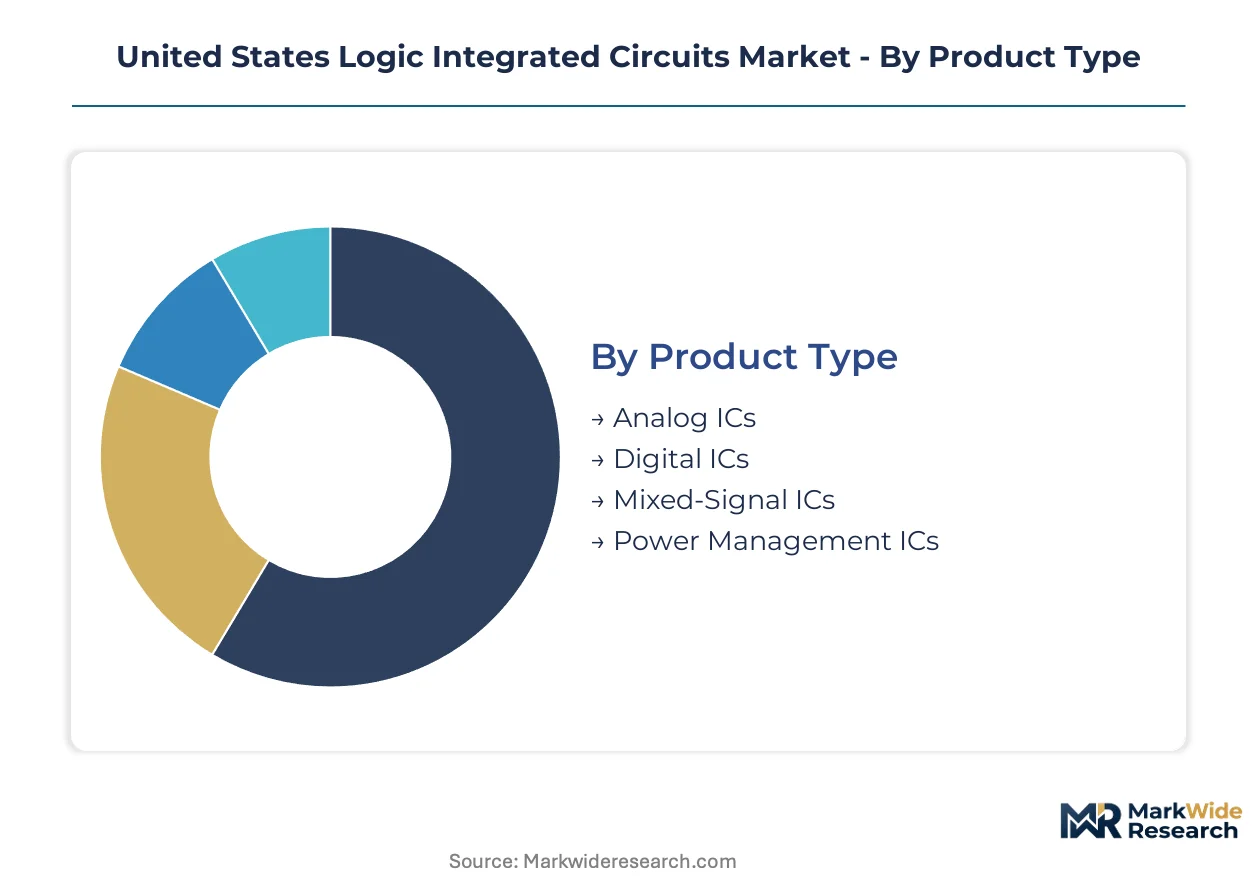
Logic IC segmentation reveals how capital allocation, process complexity, and end-use requirements fragment manufacturing economics across the United States. Distinct technology nodes and application profiles command differentiated pricing power and fab utilization rates.
Product Type:
Capital intensity varies sharply across product categories, with advanced digital devices demanding multi-billion-dollar fab investments while analog and power management ICs utilize older, depreciated capacity.
- Digital ICs:Boolean logic gates, microprocessors, and memory controllers fabricated at nodes below 7nm require EUV lithography and cleanroom investments exceeding ten billion dollars. Arizona and Texas fabs are concentrating capacity here to serve cloud data centers and AI accelerators, though equipment lead times from ASML constrain ramp velocity.
- Mixed-Signal ICs:Devices integrating analog sensing with digital processing capture widening margin pools at the analog-digital boundary. Automotive radar and lidar systems in Michigan and California are driving qualification timelines for these devices.
- Analog ICs:Operational amplifiers, voltage references, and sensor interfaces operate at relaxed geometries with lower mask costs. Texas Instruments maintains broad vertical integration across this portfolio in Texas fabs.
- Power Management ICs:Voltage regulators and battery charging circuits support electrification trends. Electric vehicle platforms are expanding per-vehicle content multiples.
Most installed capacity flows through Analog ICs. Expansion is steepest in Digital ICs.
Technology:
Process architecture selection determines power-delay characteristics and radiation hardness, with CMOS dominating economics while SOI variants address niche reliability requirements.
- CMOS:Complementary metal-oxide-semiconductor technology delivers favorable static power consumption and scaling economics through finFET and gate-all-around architectures. Intel's Arizona and Oregon complexes anchor leading-edge CMOS supply for domestic data center and PC processor demand.
- SOI:Silicon-on-insulator variants eliminate latch-up susceptibility and improve subthreshold swing for radiation-hardened and RF applications. Department of Defense trusted foundry programs in New York and California specify SOI for space and military systems.
- Bipolar:Junction transistor structures excel at high-speed switching and linearity for precision analog. Legacy fabs in the Southwest sustain production for industrial instrumentation.
- BiCMOS:Combined bipolar-CMOS processes merge high-speed analog with dense digital logic. Telecommunications infrastructure in Texas and New Jersey utilizes BiCMOS for mixed-signal baseband processing.
Process maturity concentrates in CMOS. Technology transition is accelerating most quickly in SOI.
End User:
Customer verticals impose divergent qualification standards, with automotive and industrial buyers demanding extended reliability testing that extends design-to-revenue cycles.
- Automotive:Battery management systems, autonomous driving platforms, and domain controllers multiply per-vehicle semiconductor content while requiring AEC-Q100 qualification. Tier-1 suppliers in Michigan and Ohio are qualifying domestic logic IC sources for supply security.
- Consumer Electronics:Smartphones, tablets, and wearable devices prioritize cost minimization and miniaturization. California design houses drive specifications though manufacturing resides offshore.
- Telecommunications:5G baseband processors and network infrastructure demand high-reliability logic at extended temperature ranges. Texas and New Jersey equipment manufacturers specify extended qualification.
- Industrial:Programmable logic controllers, motor drives, and sensor interfaces require decade-long supply continuity. Midwest manufacturing automation is sustaining demand for mature-node devices.
Volume concentration sits with Consumer Electronics. Demand expansion is climbing the fastest in Automotive.
Application:
Functional use cases determine performance thresholds and interface requirements, with signal processing and data processing commanding distinct architectural optimizations.
- Data Processing:Central processing units, graphics processors, and AI accelerators execute computational workloads with memory-intensive architectures. Cloud hyperscalers in Washington and California are consolidating procurement through direct foundry relationships.
- Signal Processing:Analog-to-digital converters, digital filters, and modulation circuits manipulate continuous waveforms. Medical imaging equipment in Massachusetts and Minnesota specifies high-resolution converters.
- Communication Systems:Baseband modems, protocol controllers, and encryption engines manage data transmission. Secure communications programs require domestic fabrication attestation.
- Control Systems:Microcontrollers and programmable logic devices execute real-time deterministic operations. Factory automation in the Midwest and Southeast sustains demand for ruggedized variants.
Deployment scale favors Data Processing. Application growth is gaining share fastest in Signal Processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal CHIPS Act subsidies are redrawing the cost-of-compliance map for advanced logic fabrication, concentrating capital in states with streamlined permitting and workforce pipelines while elevating operational expenditure burdens in jurisdictions with stringent environmental mandates.
California
Data center hyperscalers in Silicon Valley and Sacramento Valley are driving procurement consolidation for AI accelerators and high-performance processors. Cal/OSHA semiconductor industry standards and CARB emissions regulations impose elevated compliance costs on fab operations. San Jose and Santa Clara host design engineering clusters that anchor fabless semiconductor specifications for domestic foundry partners.
Texas
Automotive electrification demand from Dallas-Fort Worth and Houston logistics hubs is expanding qualification programs for power management and mixed-signal devices. The Texas Commission on Environmental Quality administers air quality permits that affect fab construction timelines. Austin and Richardson fabrication complexes are scaling capacity for analog and embedded processing portfolios under state-level tax incentive frameworks.
Arizona
Advanced node production for data center and defense applications is concentrating in Phoenix metropolitan fabrication corridors. EPA Region 9 hazardous waste oversight governs perfluorinated compound emissions from semiconductor manufacturing. Intel Corporation's Chandler and Ocotillo complexes anchor leading-edge CMOS supply with CHIPS Act loan guarantees accelerating equipment installation schedules.
New York
Department of Defense trusted foundry programs are sustaining demand for radiation-hardened logic in Syracuse and Albany corridors. The New York State Department of Environmental Conservation regulates industrial emissions from semiconductor facilities under state clean energy mandates. Saratoga County and Hudson Valley advanced packaging clusters are scaling heterogeneous integration capacity for defense and aerospace supply chains.
United States Logic Integrated Circuits Market Competitive Landscape
Southwestern producers anchor one tier of domestic logic IC supply; fabless specialists concentrated on the coasts hold design and market access advantages. Market structure exhibits vertical segmentation between integrated device manufacturers with captive fabrication and fabless houses dependent on foundry partnerships. Three archetypes dominate: vertically integrated manufacturers with multi-decade fab assets, fabless design houses leveraging external silicon supply, and mixed-signal specialists maintaining selective integration. Capacity expansion and strategic foundry partnerships constitute the dominant competitive moves reshaping supply configuration.
Among integrated device manufacturers, Intel Corporation and Texas Instruments occupy positions that exemplify divergent integration strategies, with the former concentrating on leading-edge digital CMOS and the latter sustaining broad analog and embedded processing portfolios. Advanced Micro Devices represents the fabless archetype, competing through design partnerships rather than captive fabrication. These three companies anchor distinct competitive vectors within the domestic logic IC landscape.
| Leading Market Players |
|---|
| Intel Corporation |
| Texas Instruments |
| Analog Devices |
| STMicroelectronics |
| Renesas Electronics Corporation |
| Advanced Micro Devices |
| Broadcom |
| NXP Semiconductors |
| Microchip Technology |
| Others |
Pricing and Supply Chain Analysis
Silicon wafer spot price indices cascade through foundry cost structures into tiered pricing for logic ICs across automotive and data center end markets. Federal CHIPS Act subsidies compress domestic fab cost bases relative to offshore alternatives, while EUV equipment scarcity at ASML concentrates pricing power among leading-edge producers in Arizona and Texas.
Pricing Analysis
Distributor margins have compressed as cloud hyperscalers consolidate procurement through direct foundry relationships, bypassing traditional component resale channels. Three-tier pricing structure across premium, standard, and economy levels separates radiation-hardened defense-grade devices from automotive-qualified and consumer-grade alternatives. Cost compression in mature-node analog ICs reflects depreciated fab assets in Texas, while advanced-node digital logic maintains pricing resilience due to single-source EUV dependency. Tier-1 automotive suppliers in Michigan exhibit highest price sensitivity due to volume procurement mandates, whereas Department of Defense programs demonstrate lowest sensitivity given security clearance requirements.
Supply Chain Analysis
Reverse-logistics flows for semiconductor equipment refurbishment center on ASML's Veldhoven facilities and Applied Materials' Singapore service hubs, extending productive life of lithography and deposition tools. Taiwan, South Korea, and the United States concentrate advanced logic fabrication, with the supply chain drawing from high-purity silicon ingots, photoresist chemicals, and specialty gases. Single-source vulnerability at EUV lithography creates structural risk for sub-7nm production ramps. Distribution runs through authorized distributors for smaller OEMs and direct allocation agreements for cloud hyperscalers and automotive Tier 1s.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EPA-regulated states with extended permitting timelines and Texas-Arizona corridors with streamlined environmental approvals and state tax incentive packages.
For Market Incumbents: Anchor leading-edge capacity in Arizona and Texas through CHIPS Act loan guarantees while accelerating yield maturation at gate-all-around nodes to defend against TSMC's foundry dominance. Prioritize backward integration into advanced packaging capacity in New York to capture value migration from monolithic die shrinks. Threat substitution from Chinese memory makers and margin pressure in mature-node analog segments demand selective portfolio pruning. For New Entrants and Emerging Players: Fabless design houses offer the most penetrable entry vector through partnerships with Intel Foundry Services or Samsung Austin for domestic silicon supply. Target radiation-hardened logic for DOD trusted foundry programs where security clearance requirements limit foreign competition. Go-to-market angle centers on heterogeneous integration chiplets for automotive domain controllers, bypassing monolithic process node barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with advanced packaging specialists in New York and Arizona scaling heterogeneous integration capacity for defense supply chains. Long-term viability favors firms with demonstrated yield at 3nm and below across the projection horizon. Acquisition target archetype includes SOI-process specialists with DOD trusted foundry accreditation. Signal to watch: Bureau of Industry and Security entity list updates that redirect foundry allocation toward domestic suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Node Yield Maturation | Gate-all-around transistor qualification at Intel's Arizona complexes secures data center allocation agreements. |
| Heterogeneous Integration Scale-Up | Chiplet packaging capacity in New York captures value migration from monolithic die shrinks for defense applications. |
| Trusted Foundry Accreditation | DOD security clearance requirements create dedicated demand channels with limited foreign competition in Syracuse corridors. |
| Direct Hyperscaler Allocation | Cloud procurement consolidation in Washington and California bypasses distributor margins for volume silicon supply. |
| State Incentive Stacking | Texas Commission on Environmental Quality permits combined with CHIPS Act loans compress fab construction timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fab operations executives, Tier-1 automotive procurement directors, cloud hyperscaler silicon supply managers, and Department of Defense trusted foundry program officers with secondary validation against SEC 10-K filings, Department of Commerce CHIPS Act award disclosures, EPA hazardous waste compliance records, and SEMI equipment billings data. Bottom-up wafer shipment estimates and top-down end-use consumption models triangulated market sizing across the analysis window.
Segment-weighting approaches applied differential capacity utilization assumptions by technology node, with CMOS, SOI, bipolar, and BiCMOS process architectures modeled separately alongside product-type splits across digital, mixed-signal, analog, and power management ICs. End-use weighting incorporated automotive electrification content curves, data center AI accelerator deployment trajectories, and defense electronics procurement cycles. CAGRs derived from equipment installation timelines, yield ramp schedules, and qualification protocol durations without year-specific references.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Bureau of Industry and Security export control enforcement, ASML equipment allocation across foundry customers, and EPA perfluorinated compound emissions rule revisions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Application Specific Consumer Analog Integrated Circuit Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
Global Linear Regulator Power Management IC Market
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Ultra Large Scale Ics Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Application Specific Computer Analog IC Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
NFC Reader Ics Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
Motor Driver IC Market
IC (Integrated Circuits)
Lithium Battery Charger Ics Market