
 Logic IC Market | 2026-2036
Logic IC Market Size, Share, and Industry Trends Forecast 2026-2036
Logic IC Market Outlook
Buyer concentration among hyperscale data center operators is recalibrating procurement volumes across the Logic IC supply base. Texas Instruments leverages its captive 300mm fabrication to sustain analog-to-digital logic margins. Samsung Electronics anchors advanced CMOS output through its Pyeongtaek foundry complex. Infineon Technologies specializes in automotive-grade logic families for traction inverter and battery management systems.
Logic ICs are semiconductor devices that perform Boolean algebra and digital signal processing through transistor arrays fabricated at nanometer-scale nodes, with current production targeting 3nm gate lengths for density-critical applications. CMOS technology dominates mainstream production due to its power-efficiency tradeoffs in mobile and edge computing endpoints. FPGA platforms represent the fastest-growing technology segment as telecommunications vendors demand field-reconfigurable infrastructure for 5G baseband processing. Automotive end users concentrate margin pools in AEC-Q100 qualified BiCMOS devices for engine control and ADAS signal paths.
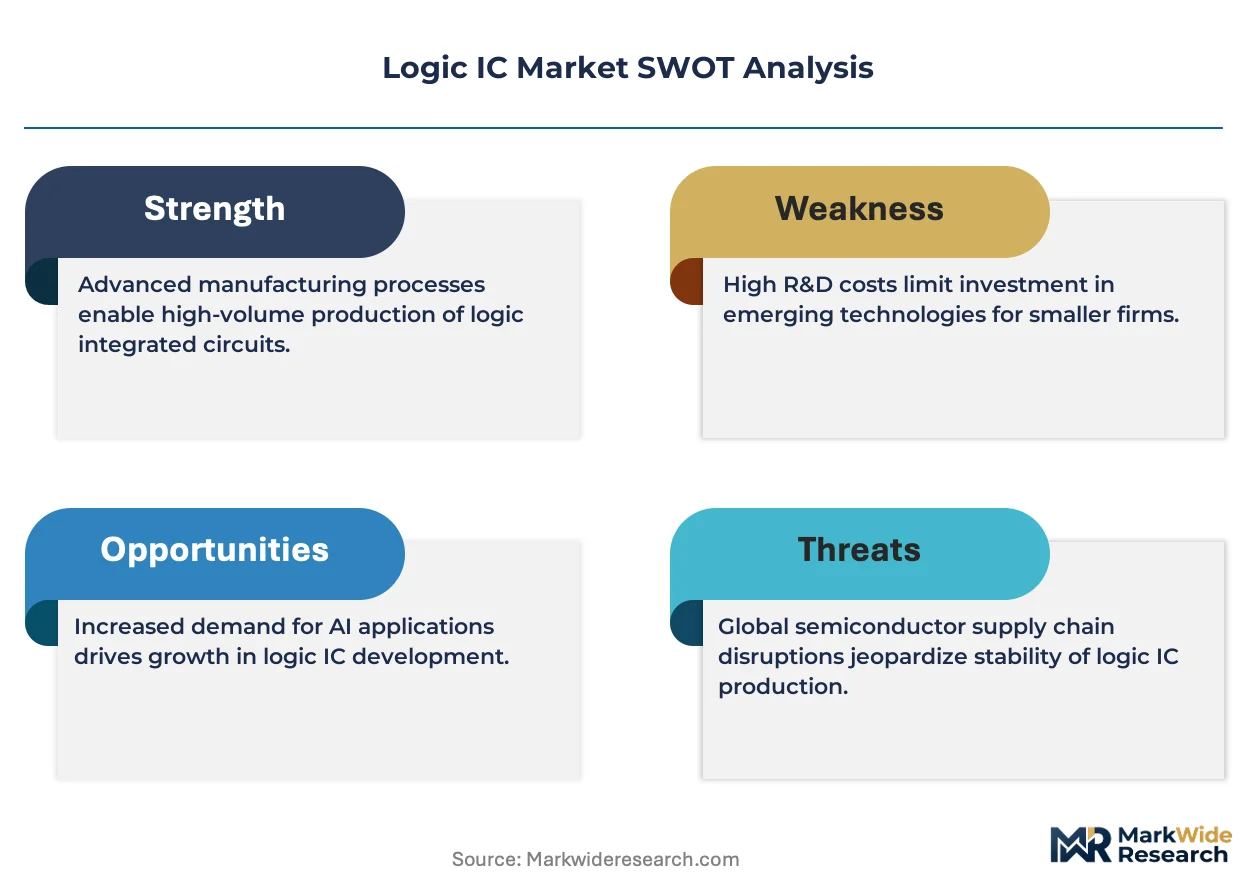
REACH substance restrictions and RoHS hazardous material limits from European regulators constrain lead-frame metallurgy and molding compound chemistries across Logic IC packaging flows. The EU Chips Act and US CHIPS and Science Act are reshaping fab location economics through direct capital subsidies and domestic content thresholds. China's MIIT sets GB standards for logic device electromagnetic compatibility in telecommunications infrastructure. Stakeholders must monitor which regulatory jurisdiction captures the next tranche of leading-edge wafer starts.
Market Dynamics
Hyperscale data center operators are consolidating procurement around 3nm-class logic devices, compressing supplier lead times while Taiwan's Hsinchu cluster absorbs the capacity surge. This buyer concentration is forcing foundries to prioritize wafer starts for cloud infrastructure over legacy automotive and consumer allocations.
Growth Catalysts
- EU Chips Act capital subsidies:Direct fabrication grants are redirecting greenfield investment toward European sovereign capacity, expanding trailing-edge logic supply for industrial automation.
- 5G baseband processing:Telecommunications vendors are scaling FPGA deployments for field-reconfigurable infrastructure, accelerating programmable logic adoption in network equipment.
- Automotive electrification:Traction inverter and battery management systems are consuming AEC-Q100 qualified BiCMOS devices at volumes that justify dedicated automotive logic fab lines.
Market Restraints
- EUV lithography equipment scarcity:ASML's extreme ultraviolet tool output constrains 3nm node expansion, capping leading-edge logic supply regardless of capital availability.
- Wafer-level substrate concentration:ABF substrate production clusters in Taiwan and Japan, creating single-source vulnerability for high-density logic packaging.
- REACH substance restrictions:ECHA constraints on lead-frame metallurgy and molding compounds force reformulation of established packaging chemistries, extending qualification cycles.
Strategic Opportunities
- Edge AI inference endpoints:Low-power logic families for on-device machine learning remain underpenetrated outside mobile handsets, opening industrial and retail deployment channels.
- US CHIPS Act domestic content thresholds:Subsidy-linked sourcing mandates are creating captive demand for logic devices fabricated in Arizona and Texas greenfield sites.
- Chiplets and 2.5D integration:Die disaggregation is converging with advanced packaging to enable cost-effective performance scaling without monolithic reticle limits.
Industry Challenges
- Process engineer scarcity:3nm node characterization requires specialized expertise in atomic-layer deposition and computational lithography that outstrips university pipeline output.
- IP licensing fragmentation:ARM architecture agreements, RISC-V open-source governance, and proprietary ISA portfolios create complex royalty stacking for logic design teams.
- Legacy node equipment obsolescence:Maintenance of 28nm and larger process tools depends on secondary parts markets as original vendors discontinue support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Logic IC Market |
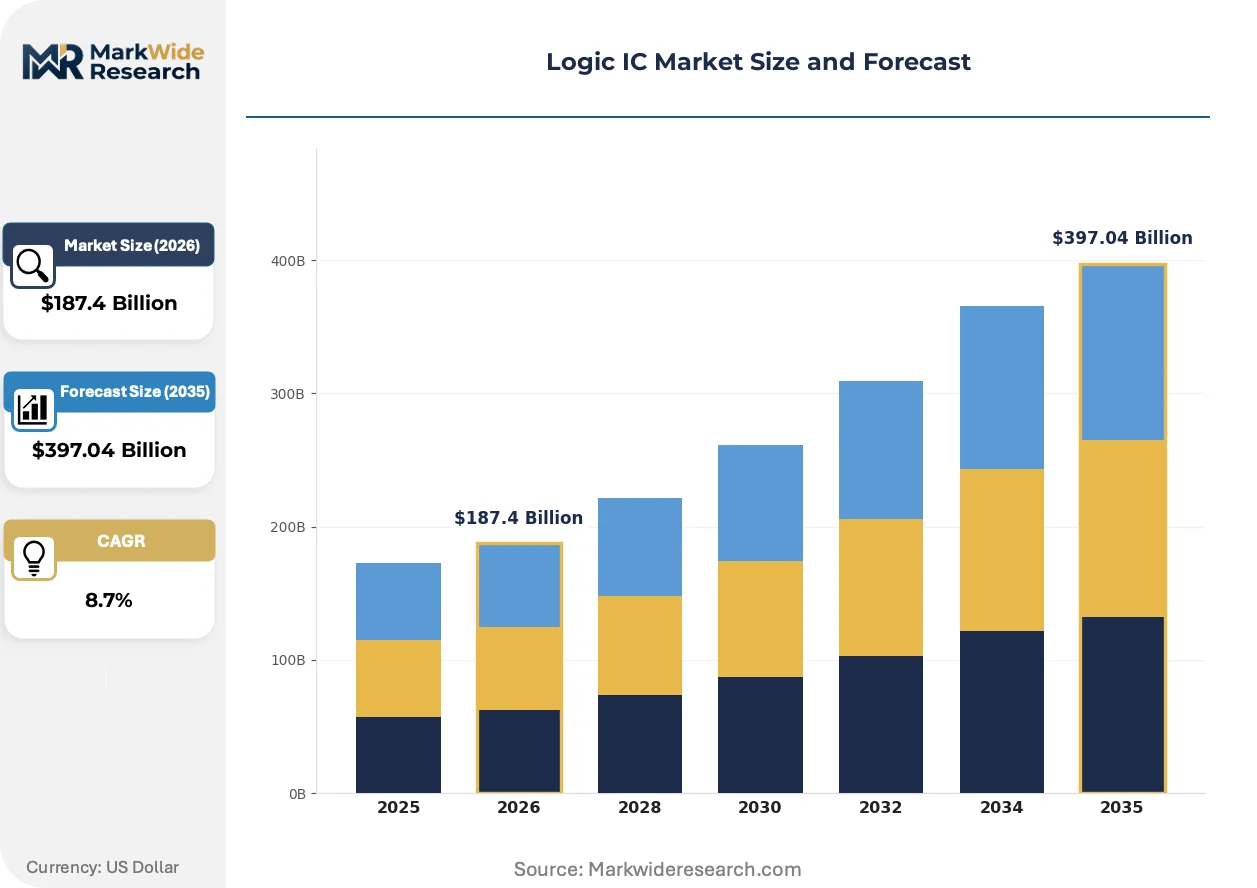
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TTL, CMOS, BiCMOS, Analog End User: Consumer Electronics, Automotive, Telecommunications, Industrial Automation Technology: FPGA, ASIC, Heterogeneous Integration, SiP Application: Signal Processing, Data Communication, Embedded Systems, Control Systems |
| Companies Covered | Analog Devices, Infineon Technologies, Texas Instruments, Samsung Electronics, Renesas Electronics, NXP Semiconductors, ON Semiconductor, Toshiba, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Logic IC Market Strategic Shifts
Logic IC architecture is fragmenting across specialization axes—power efficiency for edge endpoints, raw throughput for data centers, and functional safety for automotive—rather than pursuing universal process scaling. This divergence is spawning distinct design methodologies and foundry service tiers.
Gate-all-around transistor architecture is integrating nanosheet channels to replace finFET structures at 2nm-class nodes. Samsung Electronics and TSMC are accelerating process qualification for 2025-2026 production ramps. This transition is integrating vertical channel control that reduces leakage current by orders of magnitude, compressing power-performance-area tradeoffs for high-density logic.
REACH substance restrictions and RoHS hazardous material limits from European regulators are constraining lead-frame metallurgy and molding compound chemistries across packaging flows. ECHA's candidate list expansion is forcing suppliers to qualify halogen-free and bismaleimide-triazine alternatives. Automotive and industrial logic segments are responding with extended qualification protocols that delay new package introductions by 12-18 months.
Hyperscale operators are consolidating logic procurement through direct foundry relationships, bypassing traditional distribution channels for 3nm-class devices. Cloud infrastructure buyers in the United States and Taiwan are negotiating wafer-start commitments that lock capacity two years forward. This concentration is visible in TSMC's customer mix, where five data center operators now account for the majority of advanced logic wafer demand.
Logic IC Market Segmentation
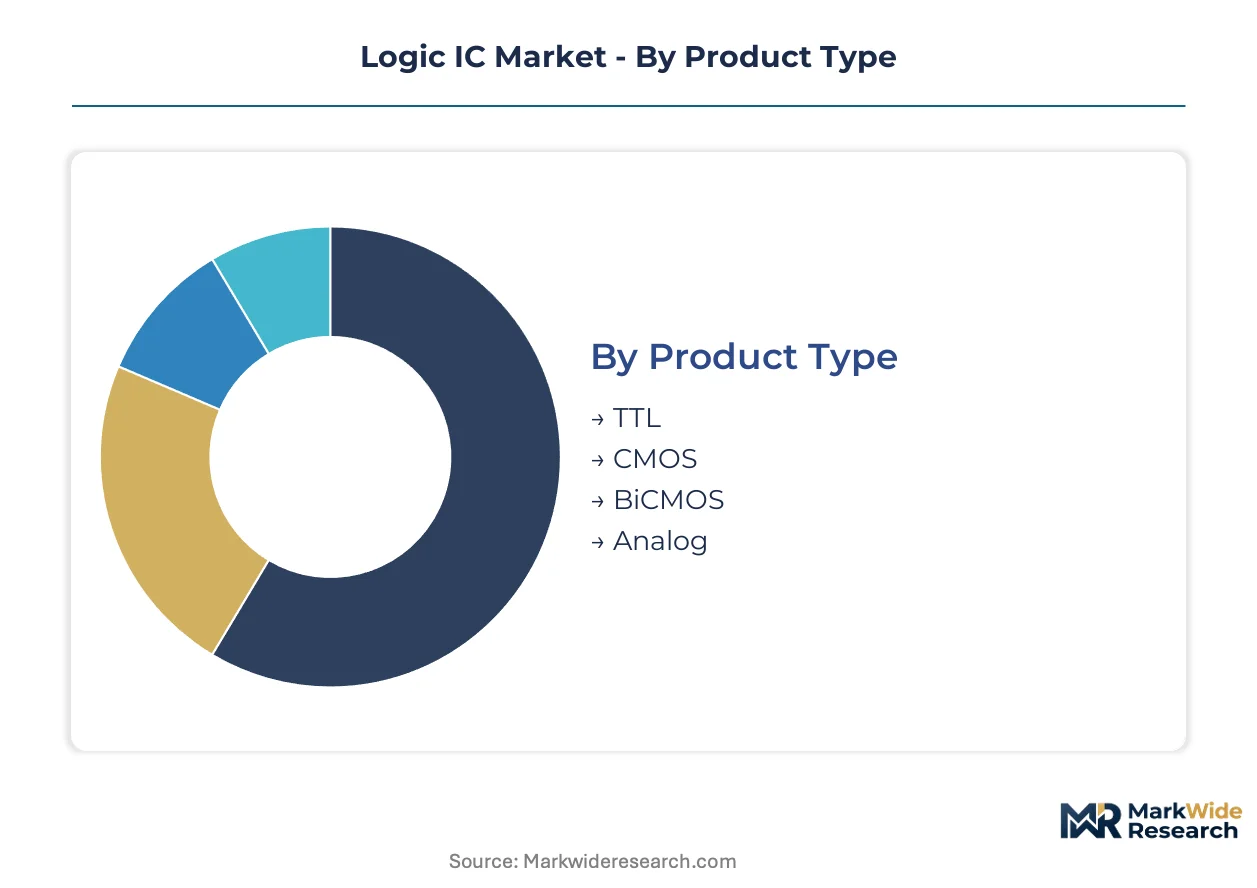
Logic IC segmentation reveals divergent optimization targets across power budgets, reliability thresholds, and reconfigurability requirements. Each axis demands distinct transistor architectures, qualification protocols, and foundry service tiers that reshape supplier economics.
Product Type:
Customization intensity varies sharply across this category, from standardized commodity logic to application-specific mixed-signal variants.
- CMOS:Complementary metal-oxide-semiconductor technology pairs n-type and p-type MOSFETs for minimal static power dissipation. Mobile handset and laptop manufacturers in Taiwan's Hsinchu corridor absorb the majority of 3nm-class CMOS wafer output, driven by battery life specifications that tolerate no leakage current penalty.
- TTL:Transistor-transistor logic employs bipolar junction transistors for high-speed switching in legacy industrial equipment. Demand concentrates in German and Japanese automation retrofits where equipment refresh cycles extend beyond 15 years, constrained by RoHS lead-frame restrictions that force palladium-silver metallurgy substitutions.
- BiCMOS:Bipolar-CMOS integration serves automotive powertrain and ADAS signal paths requiring both analog precision and digital density.
- Analog:Linear logic functions process continuous signals for sensor interfaces and power management controllers.
Most installed capacity flows through CMOS. Expansion is steepest in BiCMOS.
End User:
Volume concentration versus margin capture defines the cost tier structure across this category, with automotive commanding qualification premiums against hyperscale procurement scale.
- Automotive:AEC-Q100 qualified devices withstand temperature cycling from minus 40 to 150 degrees Celsius for 15-year operational lifespans. Battery management and traction inverter deployments in Germany, Japan, and the United States justify dedicated 28nm and 40nm fab lines as electrification accelerates.
- Telecommunications:5G baseband and optical transport infrastructure consume programmable logic at volumes that strain foundry allocation priorities. Field-reconfigurable requirements in South Korean and United States carrier networks favor FPGA platforms over fixed-function ASICs for protocol evolution flexibility.
- Consumer Electronics:Smartphone and wearable OEMs drive leading-edge node adoption through annual release cadences.
- Industrial Automation:Programmable logic controllers and motor drives demand extended temperature range operation.
Telecommunications claims the highest wafer-start growth rate. Automotive captures the widest gross margin spread.
Technology:
Application maturity determines whether customers accept fixed silicon or demand post-fabrication reconfigurability.
- FPGA:Field-programmable gate arrays embed lookup tables and routing matrices that enable hardware reconfiguration without mask respins. Network equipment vendors in the United States and Taiwan deploy FPGA-based baseband processing to accommodate evolving 3GPP releases without board-level redesigns.
- ASIC:Application-specific integrated circuits optimize transistor density and power efficiency for frozen specifications. Hyperscale data center operators commission custom AI accelerators through direct foundry relationships, locking architecture 24 months ahead of tape-out.
- Heterogeneous Integration:Die disaggregation combines logic, memory, and analog functions in 2.5D and 3D stacks.
- SiP:System-in-package modules integrate multiple dies with passive components in molded substrates.
ASIC absorbs the majority of leading-edge capital expenditure. FPGA deployment is expanding most quickly in telecommunications infrastructure.
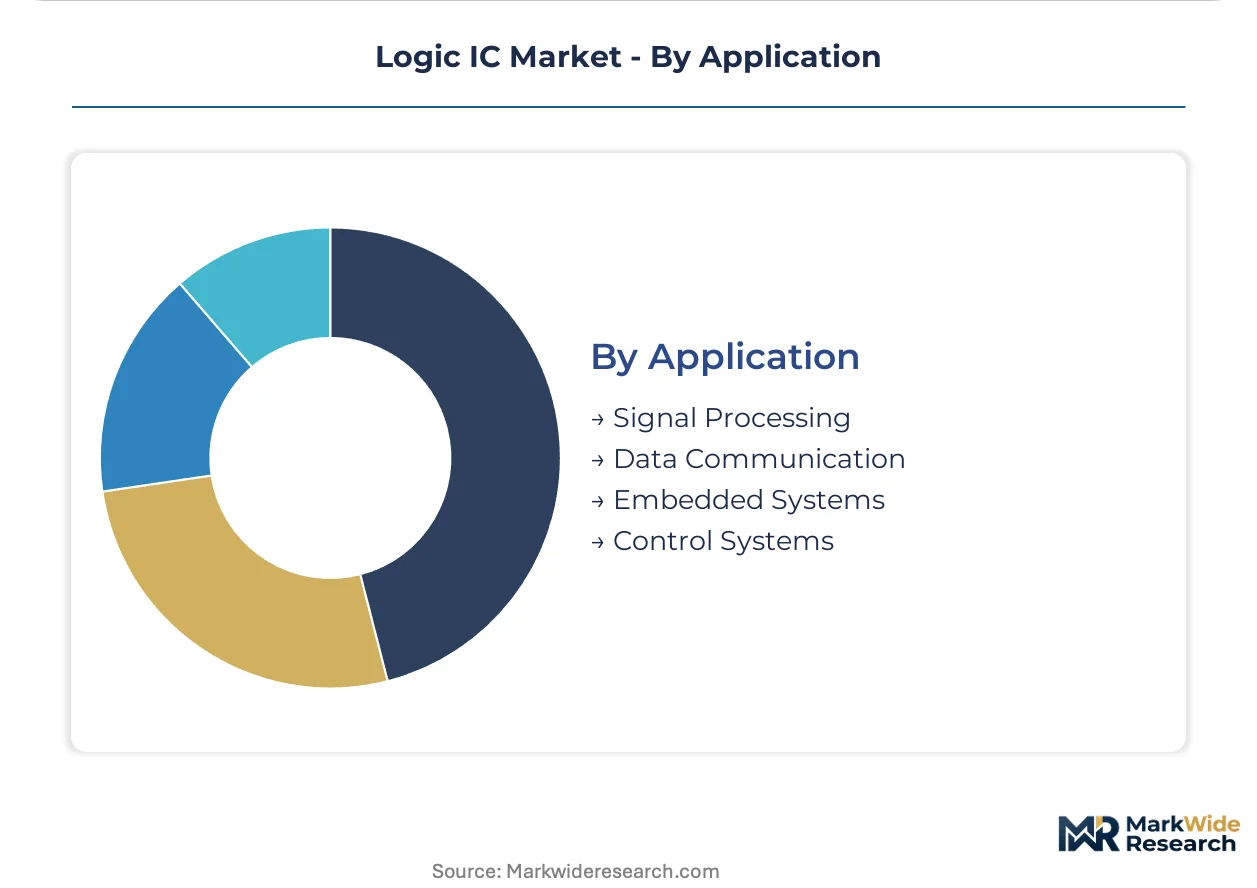
Application:
Signal path complexity and real-time constraints segment this category by processing throughput requirements.
- Data Communication:SerDes and switch fabric logic process terabit-scale traffic through pipelined architectures. Cloud data center operators in Virginia, Oregon, and Taiwan negotiate two-year forward capacity commitments for 112G PAM4 PHY designs.
- Signal Processing:Digital filter and transform engines execute multiply-accumulate operations at deterministic latencies. Radar and software-defined radio systems in defense and automotive applications drive precision requirements.
- Embedded Systems:Microcontroller-class logic integrates processing, memory, and peripherals for deterministic control.
- Control Systems:Industrial PLCs and robotics controllers demand functional safety certification.
Data Communication commands the largest wafer allocation. Signal Processing is gaining share fastest in automotive and defense procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers specializing in atomic-layer deposition and computational lithography concentrate in Taiwan's Hsinchu Science Park, Germany's Saxony cluster, and Arizona's Phoenix metro. This talent distribution anchors leading-edge wafer fabrication capacity.
United States
Hyperscale data center operators in Virginia and Oregon negotiate two-year forward wafer commitments for 3nm-class devices. The CHIPS and Science Act directs capital subsidies toward Arizona and Texas greenfield fabrication sites. Intel's expanding presence in Chandler and Samsung's Austin operations anchor domestic advanced logic capacity expansion.
Taiwan
TSMC's Hsinchu cluster absorbs the majority of global 3nm wafer demand from cloud infrastructure buyers. The National Development Council coordinates semiconductor talent pipelines through university partnerships. Tainan's Southern Taiwan Science Park hosts next-generation gate-all-around process qualification facilities.
South Korea
Samsung Electronics anchors advanced CMOS output through Pyeongtaek foundry complexes serving telecommunications and memory-logic integration. The Ministry of Trade, Industry and Energy backs domestic equipment supply chain localization. Seoul's Pangyo Techno Valley concentrates fabless design houses specializing in AI accelerator architectures.
China
MIIT sets GB standards for logic device electromagnetic compatibility in telecommunications infrastructure. Yangtze Memory Technologies and SMIC operate trailing-edge logic lines for industrial automation and consumer electronics. Shanghai's Zhangjiang Hi-Tech Park hosts domestic EDA tool development initiatives.
Germany
Infineon Technologies specializes in automotive-grade logic families for traction inverter systems from its Dresden and Regensburg facilities. ECHA REACH restrictions constrain lead-frame metallurgy substitutions across packaging flows. Bavaria's semiconductor cluster concentrates power electronics expertise for electrification applications.
Logic IC Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers. The vendor base organizes around captive fabrication ownership, foundry services, and fabless design capabilities. Three archetypes dominate: integrated device manufacturers controlling wafer supply, pure-play foundries allocating capacity across customer portfolios, and fabless specialists outsourcing fabrication while retaining architecture design. Competitive moves center on EUV lithography capacity expansion and strategic partnerships for advanced packaging integration.
Among diversified integrated device manufacturers, Texas Instruments and Samsung Electronics exemplify archetypes combining captive fabrication with broad product portfolios. Infineon Technologies occupies a position within the automotive-specialized tier, representing focused application expertise. These three anchors illustrate how geographic and segment concentration shapes competitive positioning without universal process scaling strategies.
| Leading Market Players |
|---|
| Analog Devices |
| Infineon Technologies |
| Texas Instruments |
| Samsung Electronics |
| Renesas Electronics |
| NXP Semiconductors |
| ON Semiconductor |
| Toshiba |
| STMicroelectronics |
| Others |
Value Chain & Pricing Dynamics
EUV lithography tool depreciation feeds through foundry wafer pricing tiers, compressing margins for trailing-edge logic while concentrating premium capture at 3nm-class nodes serving hyperscale data center operators in Virginia and Taiwan. REACH substance restrictions on lead-frame metallurgy extend qualification cycles, forcing packaging cost absorption across automotive-grade BiCMOS supply chains in Germany and Japan.
Pricing Analysis
Foundry services split between unbundled wafer-only supply and bundled turnkey solutions incorporating design support and advanced packaging. Three-tier pricing structure across premium, standard, and economy levels reflects AEC-Q100 certification grade, volume scale commitments, and geographic delivery cost differentials. Cost compression in trailing-edge nodes is intensifying because legacy equipment obsolescence shrinks maintenance vendor competition. Hyperscale cloud operators exhibit lowest price sensitivity due to two-year forward capacity locks, while industrial automation buyers in Germany and Japan face highest sensitivity from extended equipment refresh cycles.
Supply Chain Analysis
Process engineer scarcity in Taiwan's Hsinchu corridor, Germany's Saxony cluster, and Arizona's Phoenix metro constrains 3nm node expansion regardless of capital availability. Raw material dependencies center on ABF substrate supply from Taiwan and Japan, high-purity silicon wafers from South Korea and Germany, and EUV photoresist chemistries from Japan and Belgium. Single-source vulnerability in ABF substrate production creates chokepoint exposure for high-density logic packaging. Distribution runs through direct foundry relationships for leading-edge devices, with traditional semiconductor distributors handling legacy node and industrial-grade allocations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Logic IC market functions as a regulatory compounder where EU Chips Act capital subsidies and US CHIPS Act domestic content thresholds are redirecting fabrication investment toward sovereign capacity, amplifying demand for trailing-edge logic in industrial automation applications.
For Market Incumbents: Deploy EUV lithography capacity expansion as the primary lever against ASML tool scarcity constraints. Foundries must prioritize wafer starts for cloud infrastructure buyers committing two-year forward volumes, while securing AEC-Q100 certification pipelines for automotive electrification demand. Captive 300mm fabrication ownership insulates margin pools from foundry allocation competition.
For New Entrants and Emerging Players: Fabless design houses specializing in AI accelerator architectures offer the most penetrable partnership channel for edge AI inference endpoints outside mobile handsets. White-space targets include industrial automation PLCs and retail deployment channels for on-device machine learning. Go-to-market positioning should emphasize field-reconfigurable FPGA platforms for 5G baseband processing flexibility.
For Investors and Strategic Acquirers: Consolidation pressure builds where process engineer scarcity outstrips university pipeline output for 3nm node characterization expertise. Long-term viability favors vertically integrated specialists controlling captive wafer supply and advanced packaging integration. The signal to monitor is gate-all-around transistor yield ramp at Samsung Electronics and TSMC qualification facilities, indicating next-generation node competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| EUV Lithography Capacity Expansion | ASML tool allocation determines foundry competitiveness at 3nm-class nodes for cloud infrastructure. |
| Automotive Certification Investment | AEC-Q100 qualification protocols unlock traction inverter and battery management system deployments in Germany. |
| Gate-All-Around Process Qualification | Samsung Electronics and TSMC yield ramps at 2nm-class nodes signal next-generation transistor architecture transition. |
| Advanced Packaging Integration | Chiplets and 2.5D integration enable cost-effective performance scaling without monolithic reticle limits. |
| Edge AI Inference Development | Low-power logic families for industrial and retail machine learning endpoints remain underpenetrated outside mobile. |
Study Parameters
Coverage spans Taiwan, South Korea, Germany, and the United States, with primary inputs from each region combining foundry operations executives, fabless design house CTOs, automotive Tier 1 procurement leads, and telecommunications equipment vendor platform engineers. Secondary validation draws from SEC 10-K filings, MIIT GB standards documentation, ECHA REACH substance restriction updates, and hyperscaler capital expenditure disclosures. Bottom-up wafer demand modeling triangulates against top-down foundry revenue aggregation.
Granularity-level modeling disaggregates CMOS, BiCMOS, TTL, and analog product types; automotive, telecommunications, consumer electronics, and industrial automation end users; FPGA, ASIC, heterogeneous integration, and SiP technologies; and data communication, signal processing, embedded systems, and control systems applications. CAGRs derive from node-specific wafer start projections and foundry pricing trajectory analysis across the projection horizon. Forecast inputs incorporate EUV lithography tool delivery schedules and ABF substrate capacity expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gate-all-around yield ramp schedules, process engineer pipeline output, and regulatory subsidy continuity under EU Chips Act and US CHIPS Act appropriations. Forecasts reflect assumptions regarding ASML equipment delivery commitments and REACH substance restriction implementation timelines. Material deviation in EUV tool availability or ECHA candidate list expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
3D Integrated Circuit Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Isolated Interface Chip Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Analog Integrated Circuit (IC) Market
IC (Integrated Circuits)
Digital Potentiometer IC Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Americas Analog IC Market
IC (Integrated Circuits)
China Integrated Circuit (IC) Market
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
Semiconductor Integrated Circuit Chip Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market