
 8K Display Resolution Market | 2026-2036
8K Display Resolution Market Size, Share, and Industry Trends Forecast 2026-2036
8K Display Resolution Market Analysis
Display engineering talent is rotating toward quantum dot and microLED fabrication, tightening labor availability for legacy LCD lines and reshaping competitive dynamics. Samsung Electronics leverages captive semiconductor capacity to control backlight driver IC supply. Sony Corporation anchors premium professional AV positioning through broadcast camera-to-display integration. BOE Technology Group competes on Gen 10.5 substrate scale for cost-efficient 8K panel output.
8K display resolution denotes a pixel matrix of 7680 horizontal by 4320 vertical lines, delivering sixteen times the density of Full HD and enabling immersive viewing at shorter distances without visible pixel structure. The technology serves commercial broadcast, medical imaging, and simulation applications requiring extreme fidelity. Televisions occupy the dominant revenue position among product types, while MicroLED technology captures the fastest growth trajectory due to modular scalability and luminance advantages. Professional AV applications command premium pricing, whereas residential end users represent volume concentration in East Asian metropolitan markets.
The US FCC governs spectrum allocation affecting 8K terrestrial broadcast trials, while Japan's METI subsidizes next-generation display manufacturing through targeted industrial policy. China's GB standards and MIIT certification requirements shape import compatibility and domestic procurement preferences. Stakeholders must weigh panel technology bets against evolving regional content production standards and subsidy durability.
Market Dynamics
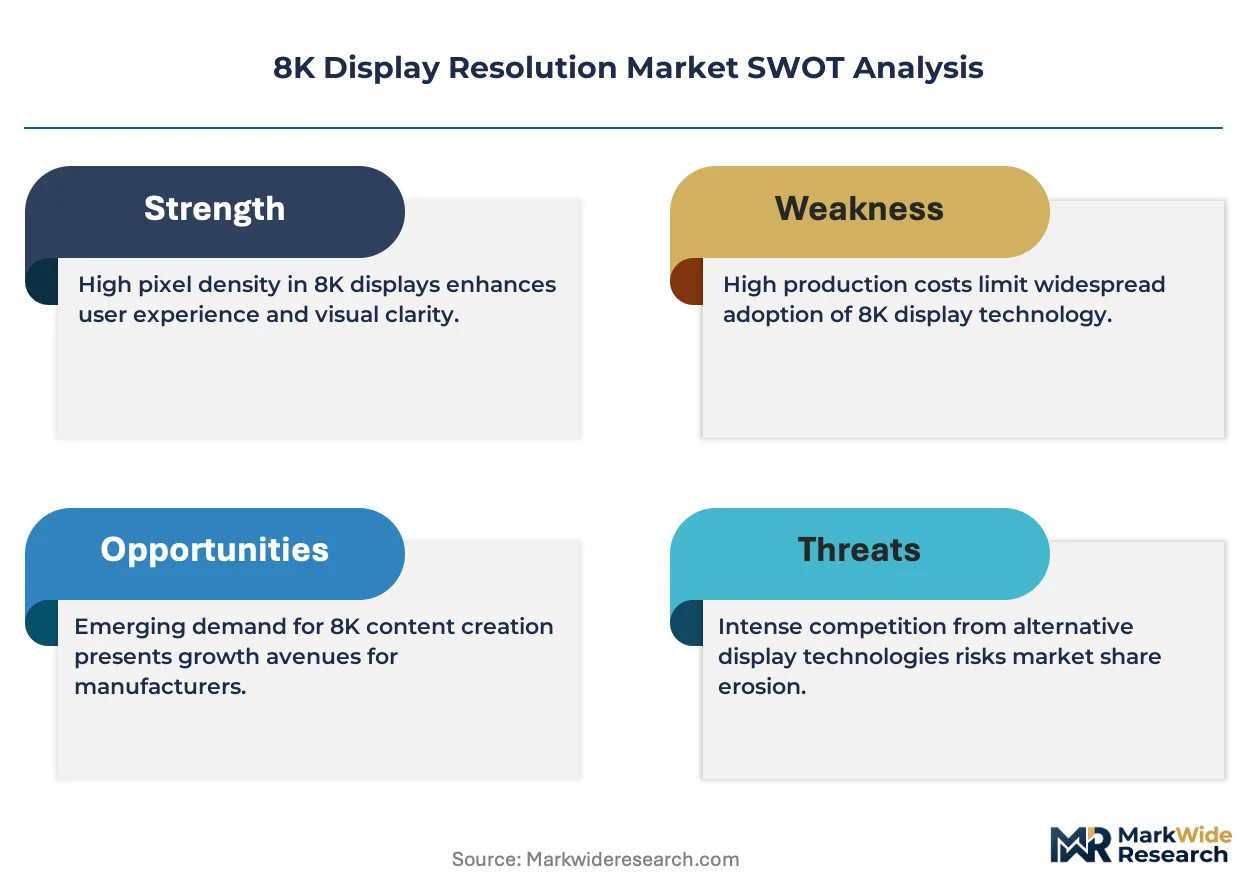
Semiconductor foundry capacity allocation for display driver ICs is constraining 8K panel output, forcing display manufacturers to secure multi-year wafer supply agreements or risk production line idling.
Growth Catalysts
- Japan's METI Subsidy Programs:Targeted industrial policy accelerates domestic Gen 10.5 fab construction and reduces capital burden for next-generation display manufacturing investments.
- Live Sports Broadcasting Infrastructure:Professional AV demand for ultra-high-definition capture is pulling 8K camera-to-display integration into stadiums and production trucks.
- MicroLED Modular Scalability:Tile-based assembly eliminates the yield constraints of monolithic large-area panels, opening commercial signage and simulation applications.
Market Restraints
- Polysilicon Supply Volatility:Input cost swings for TFT backplane materials compress margins on Gen 8.5 and larger substrate production.
- Terrestrial Spectrum Scarcity:The US FCC's allocation framework limits 8K broadcast trials to experimental licenses, constraining content availability for consumer upgrade cycles.
- Quantum Dot Inkjet Deposition:This alternative color conversion technology threatens to cap OLED-based 8K premium pricing before microLED achieves cost parity.
Strategic Opportunities
- Medical Imaging Diagnostic Displays:Radiology and surgical visualization requirements for extreme fidelity create premium-priced niche demand outside consumer cycles.
- China's GB Standard Harmonization:MIIT certification alignment with international interfaces reduces import friction for non-domestic panel vendors.
- Direct-to-Integrator Distribution:Bypassing traditional retail channels for commercial AV projects captures margin and accelerates specification control.
Industry Challenges
- MicroLED Mass Transfer Yield:Chip placement accuracy requirements at sub-10 micron tolerances strain equipment vendor capacity and extend qualification timelines.
- 8K Content Pipeline Integration:Legacy 4K production workflows require complete infrastructure replacement, slowing broadcaster deployment commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 8K Display Resolution Market |
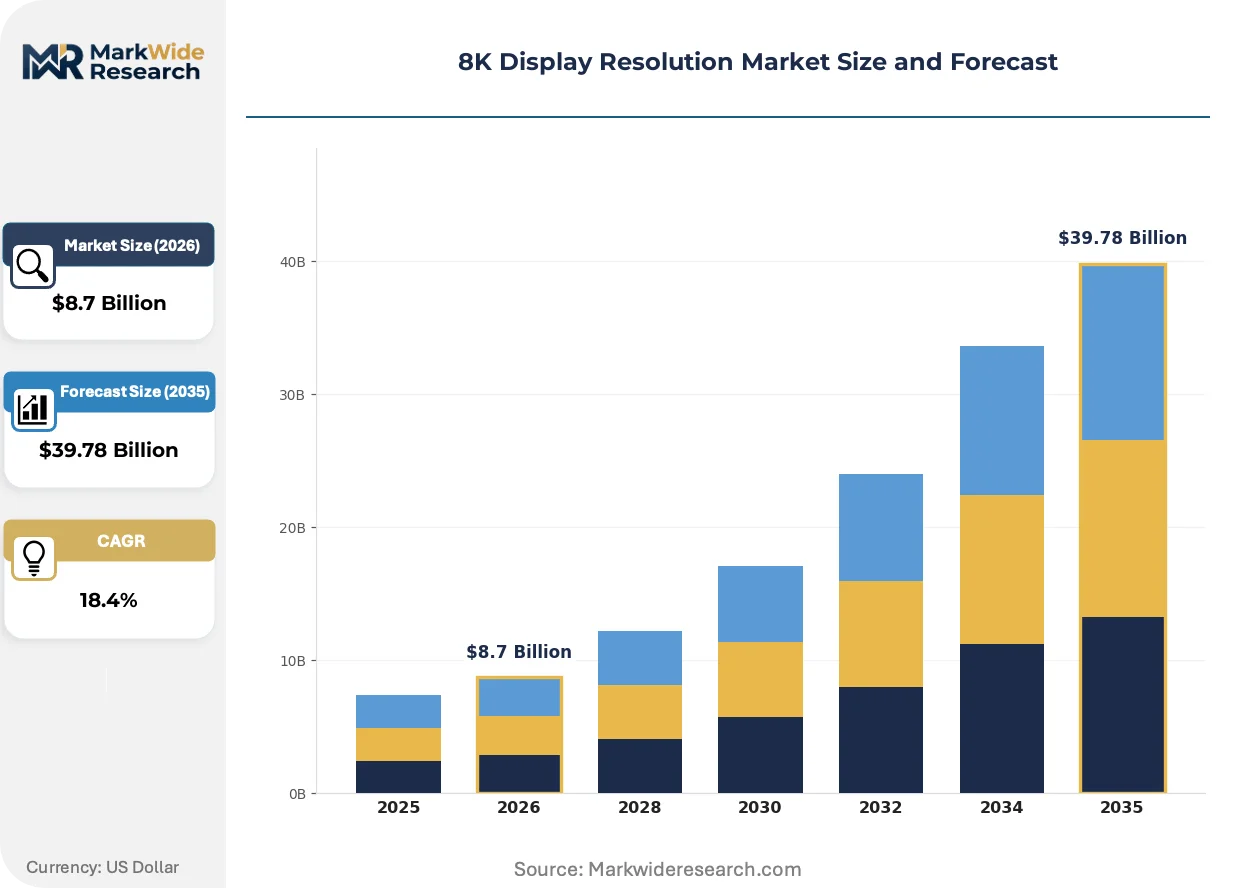
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Televisions, Monitors, Projectors, Laptops Technology: LED, OLED, QLED, MicroLED Application: Entertainment, Gaming, Professional AV, Healthcare End User: Residential, Commercial, Educational, Government |
| Companies Covered | Samsung Electronics, LG Electronics, Sony Corporation, TCL Technology, Sharp Corporation, Panasonic Corporation, Hisense Group, BOE Technology Group, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
8K Display Resolution Market Emerging Trajectories
Display architecture is pivoting from passive backlighting to self-emissive pixel control, compressing the technology stack and redistributing value capture toward semiconductor and transfer equipment vendors.
MicroLED pixel arrays are displacing incumbent LCD and OLED solutions in applications requiring sustained luminance above 1000 nits. Defense simulation contractors and luxury retail signage operators are adopting modular microLED tiles for seamless scaling beyond 100-inch diagonal formats. This displacement is compressing the addressable market for quantum dot-enhanced LCD panels above 75 inches.
China's MIIT is tightening GB standards for advanced display energy efficiency and electromagnetic compatibility, raising compliance costs for import-dependent supply chains. Domestic panel manufacturers gain procurement preference in government and state-owned enterprise tenders. Foreign vendors are responding by localizing final assembly and firmware customization within mainland facilities.
Broadcast equipment procurement is consolidating around camera-to-display ecosystem bundles rather than discrete component sourcing. Japanese regional broadcasters and South Korean telecom operators are favoring single-vendor integration packages that guarantee end-to-end 8K signal integrity. This specification bundling is most visible in East Asian metropolitan markets where NHK and KBS transmission infrastructure investments are concentrated.
8K Display Resolution Market Segmentation
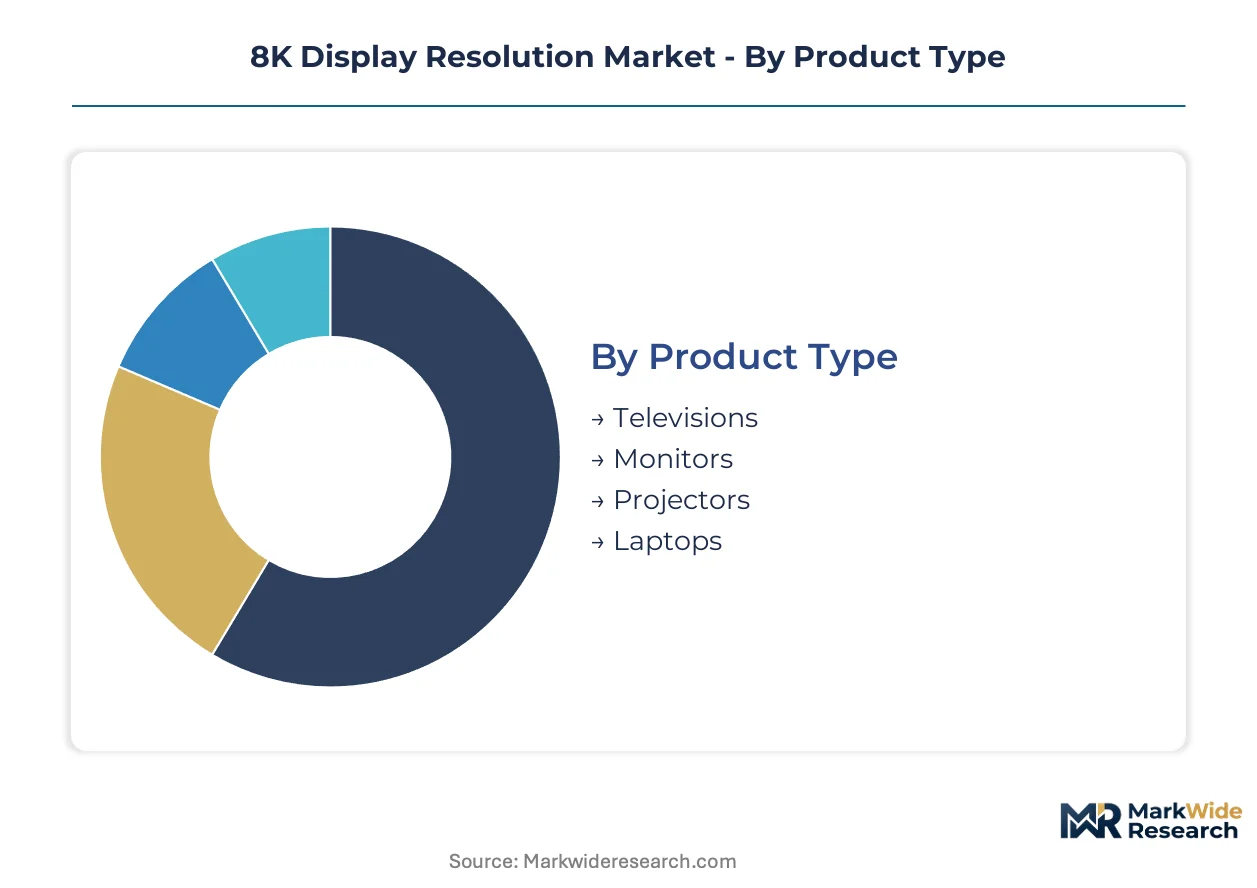
8K display procurement patterns diverge sharply across customer types. Residential buyers prioritize screen size and streaming compatibility, while commercial purchasers emphasize signal integrity and integration warranties. Understanding these channel dynamics enables targeted specification and pricing strategies.
Product Type:
Televisions dominate consumer electronics retail and direct-to-home fulfillment channels. Professional monitors and projectors flow through AV integrators and specialized distributors with installation services bundled.
- Televisions:Panel sizes from 65 to 98 inches anchor living room installations. Japanese metropolitan households upgrading from 4K drive volume concentration, supported by NHK satellite broadcast infrastructure.
- Monitors:Professional reference displays with factory calibration target post-production suites and medical imaging workstations. Healthcare systems in South Korea specify these for radiology PACS integration.
- Projectors:Laser-illuminated cinema installations serve commercial screening rooms and simulation domes. Defense contractors in the United States procure these for training environments.
- Laptops:Compact 8K panels remain niche, limited to creative workstation configurations. Mobile form factor constraints suppress mainstream adoption.
By volume, Televisions leads. By growth pace, Monitors is expanding most quickly in professional verticals.
Technology:
Cost tier stratification separates mass-market penetration from premium positioning. LED-backlit LCD occupies economy and standard tiers, while self-emissive technologies command premium pricing.
- LED:Quantum dot-enhanced LCD panels with miniLED backlighting deliver cost-efficient 8K output at scale. Chinese Gen 10.5 fabs in Hefei and Wuhan concentrate supply.
- OLED:Organic electroluminescent layers enable perfect black levels and wide viewing angles. South Korean manufacturers anchor supply for premium television applications.
- QLED:Samsung's branded quantum dot implementation competes with OLED on color volume and brightness retention. Retail channel placement emphasizes side-by-side comparison fixtures.
- MicroLED:Inorganic gallium nitride emitters eliminate burn-in risk and sustain luminance above 2000 nits. Modular tile architecture enables seamless scaling beyond 150 inches for luxury retail and command center deployments.
By installed base, LED holds the largest footprint. By investment intensity, MicroLED attracts the steepest expansion trajectory in commercial signage.
Application:
Customer type determines specification priority and procurement authority. Consumer applications emphasize content ecosystem compatibility, while institutional buyers require compliance certification and service level agreements.
- Entertainment:Streaming service original production and theatrical exhibition drive demand for reference-grade color accuracy. Japanese broadcasters specify these for 8K satellite transmission compliance.
- Gaming:High-refresh 8K panels target enthusiast PC builds and next-generation console connectivity. South Korean esports venues install these for spectator display walls.
- Professional AV:Live event production, corporate boardrooms, and house of worship installations require signal distribution redundancy. Integrators specify HDBaseT and SDI input compatibility.
- Healthcare:Diagnostic displays for pathology and surgical visualization demand DICOM calibration and anti-microbial surface treatments. United States hospital procurement favors FDA-registered devices.
By revenue concentration, Entertainment leads. By margin structure, Healthcare commands premium pricing outside consumer cycles.
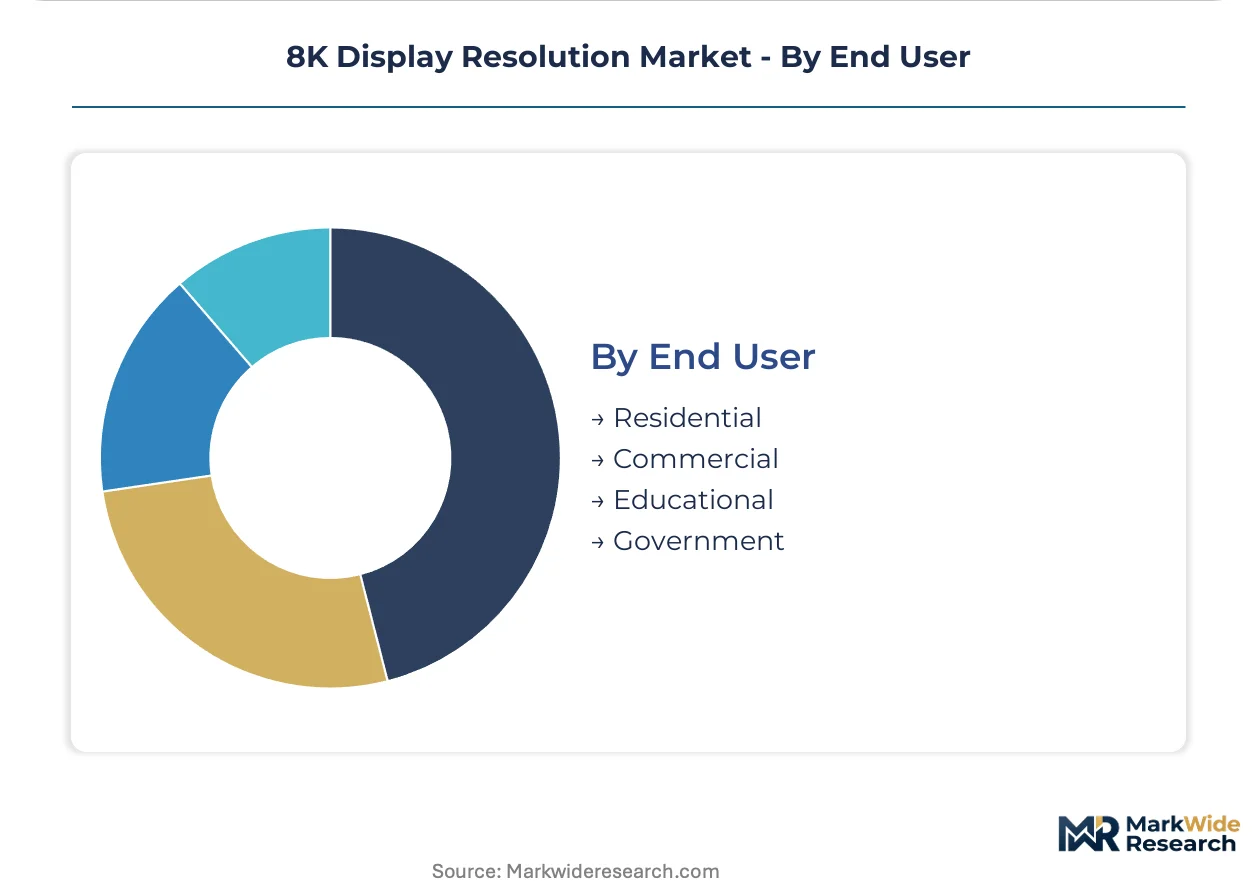
End User:
Volume scale inversely correlates with specification complexity. Residential purchases concentrate in single-unit transactions, while government tenders require multi-year maintenance contracts and domestic content verification.
- Residential:Affluent households in Tokyo, Seoul, and Shanghai metropolitan districts drive upgrade cycles. Retail channel promotions coincide with regional broadcast infrastructure milestones.
- Commercial:Corporate headquarters, hospitality, and retail flagship locations specify 8K for brand differentiation. Property developers in Dubai and Singapore bundle these into luxury residential pre-installations.
- Educational:University media labs and research visualization centers procure reference displays for scientific computing. Grant-funded installations in the United States and Germany favor open-source signal processing compatibility.
- Government:Defense simulation, intelligence analysis, and public safety command centers require secure supply chains and TAA compliance. China's state-owned enterprise tenders favor MIIT-certified domestic manufacturers.
By unit volume, Residential dominates. By contract value, Government captures the highest average transaction size.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese broadcasters command premium pricing for 8K professional equipment while Chinese panel manufacturers drive consumer price compression through substrate scale advantages. This asymmetry shapes procurement patterns across East Asian metropolitan markets and influences technology transfer negotiations.
Japan
NHK's satellite broadcasting infrastructure anchors domestic upgrade cycles in Tokyo and Osaka metropolitan districts. METI subsidizes Gen 10.5 fab construction to reduce capital burden for next-generation display manufacturing. Kanto region broadcast equipment procurement concentrates around camera-to-display integration packages.
China
MIIT certification requirements and GB standards accelerate domestic panel procurement preference in government tenders. Hefei and Wuhan host concentrated Gen 10.5 substrate production for cost-efficient 8K output. Yangtze River Delta manufacturers localize final assembly to satisfy import compatibility rules.
South Korea
Esports venues and telecom operators drive demand for high-refresh 8K display walls in Seoul and Busan. MFDS regulations shape medical imaging display certification for diagnostic applications. Seoul Capital Area panel fabricators compete on OLED premium positioning against Chinese LCD scale.
United States
Defense simulation contractors procure laser-illuminated 8K projectors for training environments. FCC spectrum allocation limits terrestrial 8K broadcast trials to experimental licenses. California and Texas host broadcast technology development clusters focused on professional AV integration.
Germany
University media labs and research visualization centers specify reference displays for scientific computing. REACH and RoHS compliance requirements raise certification costs for import-dependent supply chains. Bavaria and Baden-Württemberg concentrate broadcast equipment engineering talent.
8K Display Resolution Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. South Korean and Japanese manufacturers anchor premium professional AV positioning through integrated camera-to-display ecosystems. Chinese panel producers compete on Gen 10.5 substrate scale and domestic procurement preference. Strategic moves concentrate on multi-year wafer supply agreements for display driver ICs and localization of final assembly within mainland China.
Among diversified electronics conglomerates, Samsung Electronics, Sony Corporation, and BOE Technology Group exemplify the three dominant competitive archetypes. Samsung leverages captive semiconductor capacity to control backlight driver supply chains. Sony anchors broadcast camera-to-display integration for professional applications. BOE competes on substrate scale and MIIT certification alignment for domestic Chinese tenders.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Sony Corporation |
| TCL Technology |
| Sharp Corporation |
| Panasonic Corporation |
| Hisense Group |
| BOE Technology Group |
| Canon Inc. |
| Others |
Supply Flow & Price Mechanics
MIIT certification requirements and GB standards gate both supply qualification and price differentiation simultaneously, forcing foreign vendors to localize final assembly within mainland China while domestic manufacturers capture procurement preference through compliance-aligned production.
Pricing Analysis
Japanese metropolitan markets command premium pricing for professional broadcast equipment while Chinese Gen 10.5 fabs drive consumer panel price compression. Pricing stratifies across premium self-emissive tiers, standard quantum dot-enhanced LCD, and economy direct-lit LED configurations. Cost compression in standard tiers intensifies because BOE and TCL Technology expand substrate scale advantages. Residential buyers in East Asian metropolitan districts exhibit highest price sensitivity, whereas defense contractors and healthcare systems demonstrate lowest sensitivity due to specification rigidity.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes strain inbound logistics for display driver ICs and specialized glass substrates. Manufacturing concentrates in China, South Korea, and Japan, with Hefei and Wuhan hosting concentrated Gen 10.5 production. The supply chain draws from polysilicon feedstock for TFT backplanes, gallium nitride epitaxy for microLED emitters, and semiconductor wafer supply for driver ICs. Single-source vulnerability in display driver foundry capacity poses structural risk. Distribution runs through AV integrators for commercial projects and direct-to-retail for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Broadcast camera-to-display ecosystem bundling signals platform-economics inflection, with NHK and KBS transmission infrastructure investments creating interoperability lock-in that rewards integrated vendors over component specialists.
For Market Incumbents: Fortify multi-year wafer supply agreements for display driver ICs to prevent production line idling, and deepen captive semiconductor capacity for backlight control components. Quantum dot inkjet deposition threatens OLED premium positioning before microLED achieves cost parity. Certification investment in MIIT-aligned GB standards secures access to Chinese state-owned enterprise tenders. For New Entrants and Emerging Players: Post-production suite calibration services represent a service-layer gap where incumbents under-serve independent content creators and regional broadcasters. Medical imaging diagnostic displays offer the most penetrable segment due to DICOM compliance complexity that deters consumer-focused entrants. Direct-to-integrator distribution bypassing traditional retail channels accelerates specification control in commercial AV projects. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microLED mass transfer equipment as sub-10 micron placement tolerances strain vendor capacity. Long-term viability over the analysis window favors equipment suppliers and transfer technology specialists over panel manufacturers facing substrate scale commoditization. Watch microLED yield qualification timelines as the critical inflection indicator for technology substitution pace.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Wafer Supply Agreement | Semiconductor foundry commitments from Samsung Electronics secure driver IC availability against foundry allocation constraints. |
| MIIT Certification Alignment | GB standards compliance from BOE Technology Group unlocks procurement preference in Chinese government tenders. |
| Camera-to-Display Integration Package | End-to-end 8K signal integrity guarantees from Sony Corporation consolidate Japanese broadcaster procurement decisions. |
| Modular MicroLED Tile Architecture | Scalable luminance solutions from specialized vendors displace monolithic panels in luxury retail and command center deployments. |
| Direct-to-Integrator Distribution Channel | Bypass structures capture margin and accelerate specification control in professional AV and healthcare verticals. |
Methodological Framework
Desk research of SEC filings, customs trade records, and MIIT certification databases preceded structured interviews with display panel procurement managers, broadcast technology directors, AV integration specialists, and semiconductor foundry planning officers. Primary fieldwork combined telephone and video interviews with secondary validation against regulatory submissions and industry association technical reports. Bottom-up unit economics triangulated against top-down market sizing across technology and application segments.
Variance decomposition separates volume drivers from price trajectory components across the projection horizon. Segmentation dimensions modeled include product type, display technology, application vertical, end-user category, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for technology substitution and infrastructure deployment timelines. Forecast inputs incorporated NHK broadcast infrastructure milestones, METI subsidy program allocations, and MIIT domestic procurement preference enforcement patterns.
Underlying assumptions cover sustained semiconductor foundry capacity allocation for display drivers, with deviation risk concentrated in polysilicon supply volatility and terrestrial spectrum allocation delays. Forecasts reflect these documented conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Display Mask Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
Touch Screen Film Market
Display Technologies
Capacitive Touch Screen Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Phosphor Screen Market
Display Technologies
Asia-Pacific Industrial Display Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
Europe Microdisplay Market
Display Technologies
3LCD Projector Market
Display Technologies
Touch Screen Display Market
Display Technologies
Resistive Touchscreen Market
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
Privacy Screens Market
Display Technologies
Large Industrial Displays Market
Display Technologies
Global Next Generation Display Market