
 Computer and Peripherals Standard Logic IC Market | 2026-2036
Computer and Peripherals Standard Logic IC Market Size, Share, and Industry Trends Forecast 2026-2036
Computer and Peripherals Standard Logic IC Market Analysis
Software-defined configuration layers is rebalancing how standard logic ICs are monetized beyond discrete component sales. Texas Instruments Inc leverages its broad analog-digital portfolio to anchor long-term supply agreements with peripheral OEMs. NXP Semiconductors NV differentiates through automotive-grade reliability standards that it extends into computing applications. STMicroelectronics NV competes on foundry flexibility, sustaining dual-source strategies for tier-one PC manufacturers.
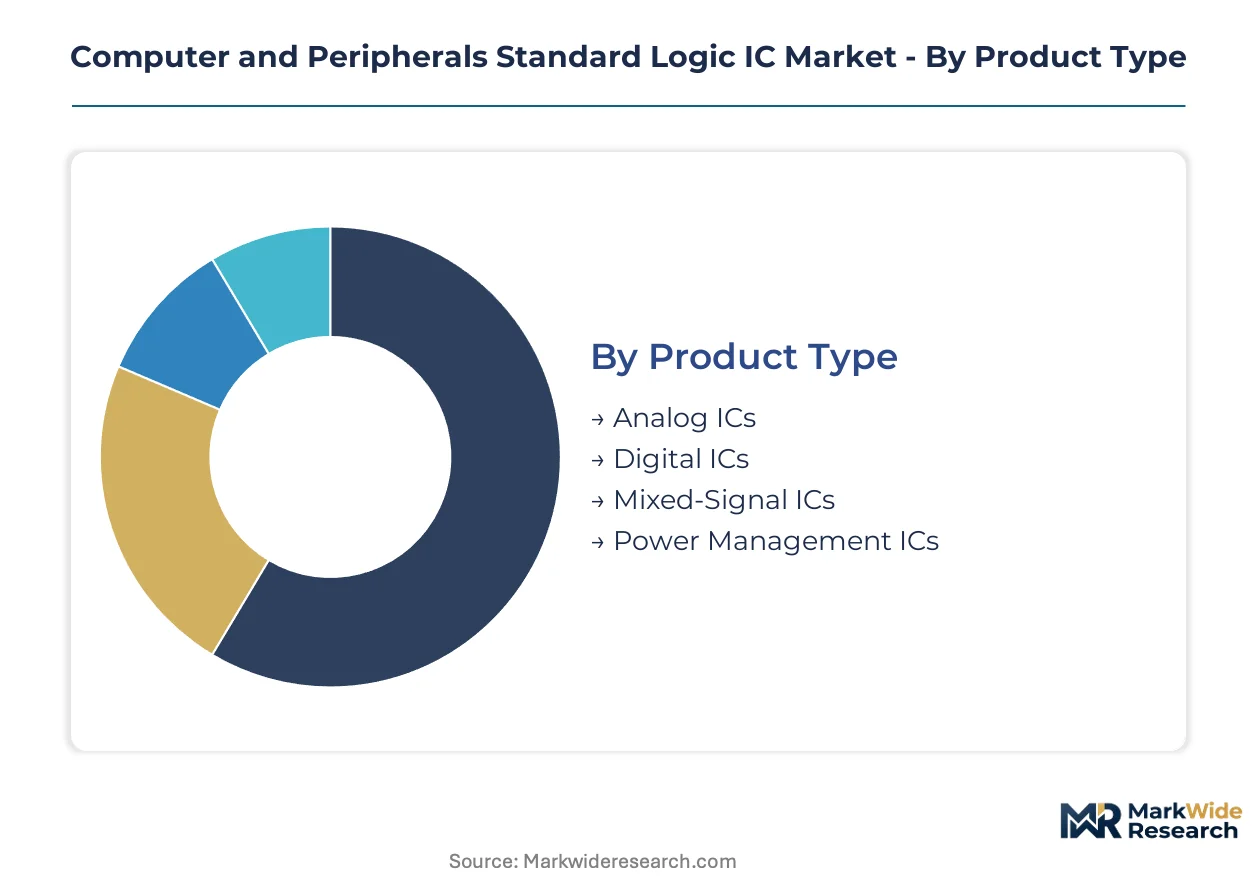
Computer and Peripherals Standard Logic ICs comprise gate arrays, flip-flops, multiplexers, and buffers fabricated on CMOS or BiCMOS processes with operating voltages from 1.2V to 5V, serving as the fundamental switching and timing elements in digital circuit design. These devices translate binary signals across motherboard buses, display controllers, and storage interfaces in commercial computing equipment. Digital ICs occupy the largest volume tier, though mixed-signal variants capture disproportionate margin pools where analog-digital boundaries blur in modern peripheral architectures. Power Management ICs within this category are gaining share as USB-C and Thunderbolt interfaces proliferate across computing devices, while FinFET-based logic remains confined to high-performance segments due to cost structures.
FCC electromagnetic compatibility rules in the United States and CE marking requirements under the EU's Radio Equipment Directive shape product certification pathways for logic ICs deployed in communication peripherals. China's GB standards for electronic product safety, administered by SAMR, dictate local market access conditions for imported standard logic components. Buyers must monitor how dual carbon goals in Beijing and the EU Green Deal's embodied carbon tracking will reshape supplier qualification criteria for semiconductor packaging materials.
Market Dynamics
Embedded systems adoption in industrial automation is compressing design cycles and forcing logic IC suppliers to align roadmaps with real-time control requirements rather than discrete component specifications.
Growth Catalysts
- Industrial automation:Factory floor digitization in Germany and Japan demands high-reliability logic ICs for motion controllers and sensor interfaces.
- REACH and RoHS:European material compliance mandates are accelerating lead-free packaging transitions across peripheral supply chains.
- USB-C proliferation:Universal charging standards are expanding addressable market for power management logic in docking stations and monitors.
Market Restraints
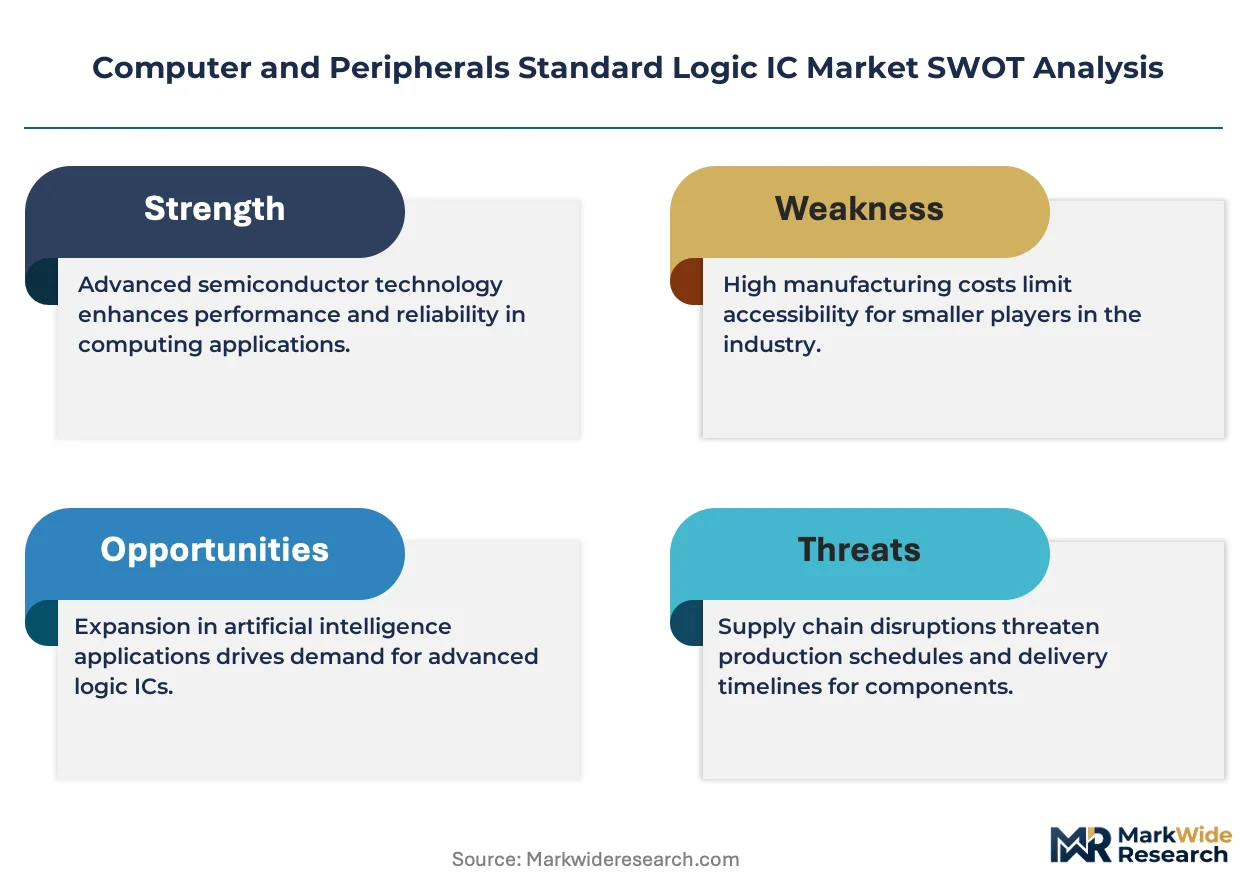
- Silicon wafer cost volatility:300mm substrate pricing fluctuations squeeze margins on mature-node logic IC production.
- Foundry concentration risk:Taiwan-based advanced logic capacity creates single-source vulnerability for FinFET-based segments.
- BiCMOS technical limitation:Higher static power consumption restricts deployment in battery-powered peripherals versus pure CMOS alternatives.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives are attracting PC peripheral assembly operations requiring localized logic IC sourcing.
- Automotive-grade crossover:AEC-Q100 qualified logic families are penetrating industrial computing where reliability premiums command pricing power.
- EU Green Deal:Embodied carbon tracking requirements favor suppliers with verified low-carbon packaging supply chains.
Industry Challenges
- Mixed-signal design expertise gap:Shortage of engineers proficient at analog-digital boundary optimization delays product qualification timelines.
- Dual-source certification complexity:Tier-one PC manufacturers require redundant qualification of logic ICs across foundries, extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer and Peripherals Standard Logic IC Market |
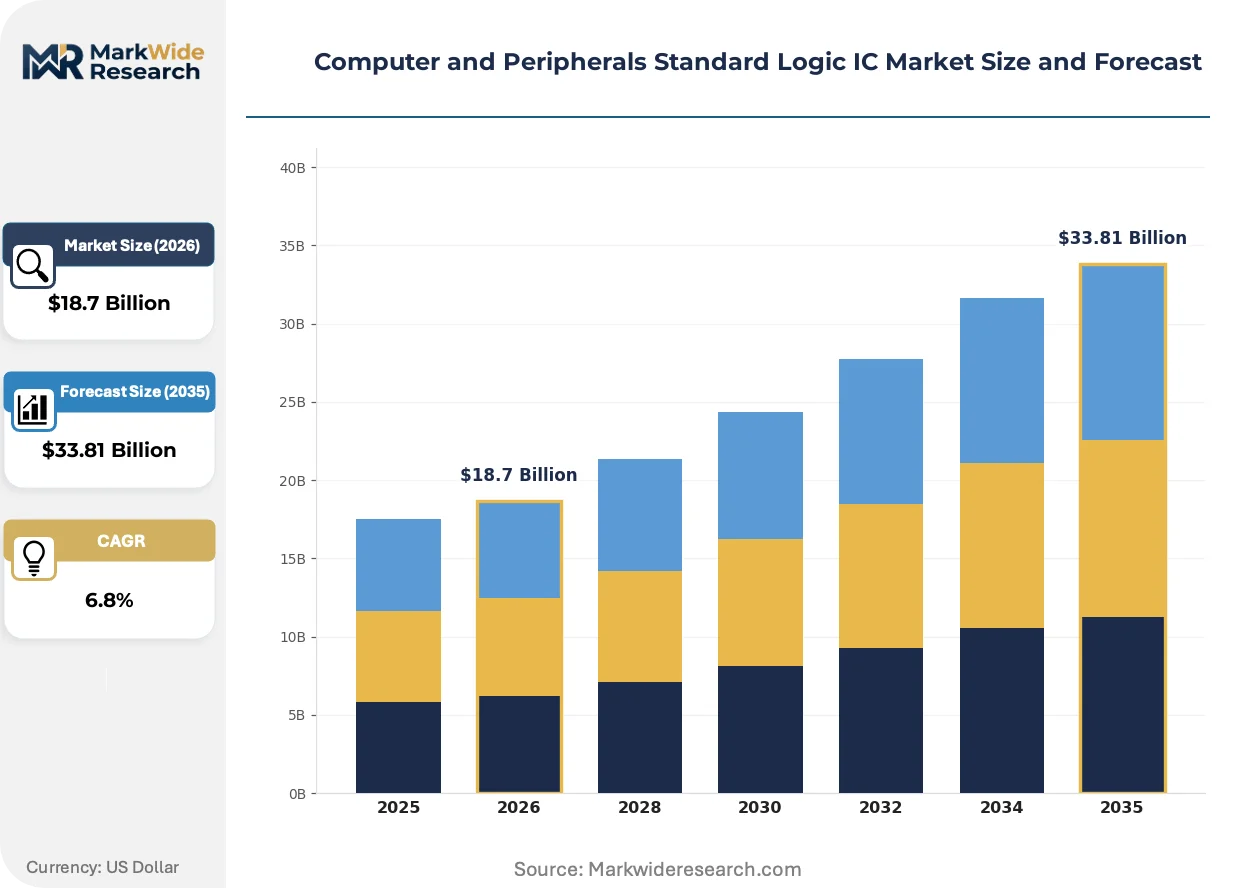
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog ICs, Digital ICs, Mixed-Signal ICs, Power Management ICs End User: PC Manufacturers, Consumer Electronics, Industrial Automation, Telecommunications Application: Embedded Systems, Communication Devices, Computing Devices, Signal Processing Technology: CMOS, BiCMOS, Bipolar, FinFET |
| Companies Covered | Microchip Technology Inc, Toshiba Electronic Devices and Storage Corporation, ROHM Co Ltd, Diodes Incorporated, Texas Instruments Inc, onsemi, NXP Semiconductors NV, STMicroelectronics NV, Skyworks Solutions Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer and Peripherals Standard Logic IC Market Emerging Trajectories
Software-defined configuration layers are redefining how standard logic ICs deliver value, shifting competitive advantage from discrete component performance to programmable integration capabilities.
Programmable logic devices with embedded non-volatile memory are consolidating multiple discrete gate functions into single-package solutions. Industrial controller OEMs in Germany and Japan are adopting these configurable arrays to reduce board space and inventory complexity. This consolidation is compressing demand for commodity discrete logic while expanding margins on integrated programmable alternatives.
China's GB standards for electronic product safety, administered by SAMR, are tightening electromagnetic compatibility testing protocols for logic ICs in communication peripherals. Domestic certification timelines have extended by several months for imported components. PC peripheral manufacturers are responding by pre-qualifying logic families against both GB and FCC standards during initial design phases.
Direct contracting between logic IC suppliers and peripheral OEMs is displacing traditional distribution channels for high-volume programs. Dell and HP procurement teams in Texas and Taiwan are negotiating long-term supply agreements that bypass authorized distributors. This channel compression is most visible in notebook and display controller segments where annual volumes exceed ten million units.
Computer and Peripherals Standard Logic IC Market Segmentation
Standard logic IC procurement decisions hinge on voltage compatibility, thermal envelopes, and certification grade rather than unit cost alone. Each segmentation dimension reveals distinct margin structures and supplier qualification barriers that shape competitive positioning across peripheral ecosystems.
Product Type:
Buyers prioritize power efficiency thresholds and analog-digital integration depth when selecting logic families for motherboard and peripheral designs.
- Digital ICs:Gate arrays, flip-flops, and multiplexers fabricated on 1.2V to 5V CMOS processes handle binary signal translation across motherboard buses and storage controllers. PC manufacturers in Taiwan and China concentrate procurement here for notebook and desktop platforms, driven by USB-C and Thunderbolt interface proliferation requiring high-speed switching.
- Mixed-Signal ICs:Devices straddling analog-digital boundaries integrate ADCs, DACs, and timing circuits for display controllers and sensor hubs. Industrial automation OEMs in Germany and Japan source these for motion control systems where signal fidelity commands reliability premiums.
- Analog ICs:Voltage regulators and reference circuits buffer power rails in peripheral subsystems.
- Power Management ICs:DC-DC converters and load switches optimize thermal budgets in docking stations and monitors.
Digital ICs lead on scale; Power Management ICs lead on momentum.
End User:
Volume concentration and qualification rigor vary sharply across customer categories, with automotive-grade standards increasingly penetrating industrial segments.
- PC Manufacturers:Dell, HP, and Lenovo procurement teams negotiate direct supply agreements for logic families in notebook chipsets and display controllers. Annual volumes exceeding ten million units compress channel margins and favor suppliers with dual-source foundry flexibility.
- Industrial Automation:Factory floor digitization in Germany and Japan demands AEC-Q100 qualified logic for motion controllers and sensor interfaces. Real-time control requirements compress design cycles and force roadmap alignment with embedded system vendors.
- Consumer Electronics:Smartphone and tablet OEMs prioritize compact package sizes for logic integration.
- Telecommunications:Base station and router manufacturers specify extended temperature range logic for outdoor deployments.
PC Manufacturers anchor procurement volume; Industrial Automation commands the steepest expansion trajectory.
Application:
Signal path complexity and latency tolerance determine logic family selection across computing and communication subsystems.
- Embedded Systems:Microcontroller companion logic and programmable gate arrays consolidate discrete functions in industrial controllers. German and Japanese OEMs adopt configurable arrays with embedded non-volatile memory to reduce board space and inventory complexity.
- Communication Devices:Ethernet PHY interfaces and PCIe signal conditioning demand high-speed logic with tight jitter specifications. China's GB standards administered by SAMR extend certification timelines for imported components in this segment.
- Computing Devices:CPU voltage regulators and memory buffer logic serve motherboard and storage subsystems.
- Signal Processing:Audio codecs and video timing circuits require precision mixed-signal integration.
Embedded Systems dominate design-in activity; Communication Devices are gaining share fastest.
Technology:
Process node selection trades static power consumption against switching speed and manufacturing cost in peripheral logic designs.
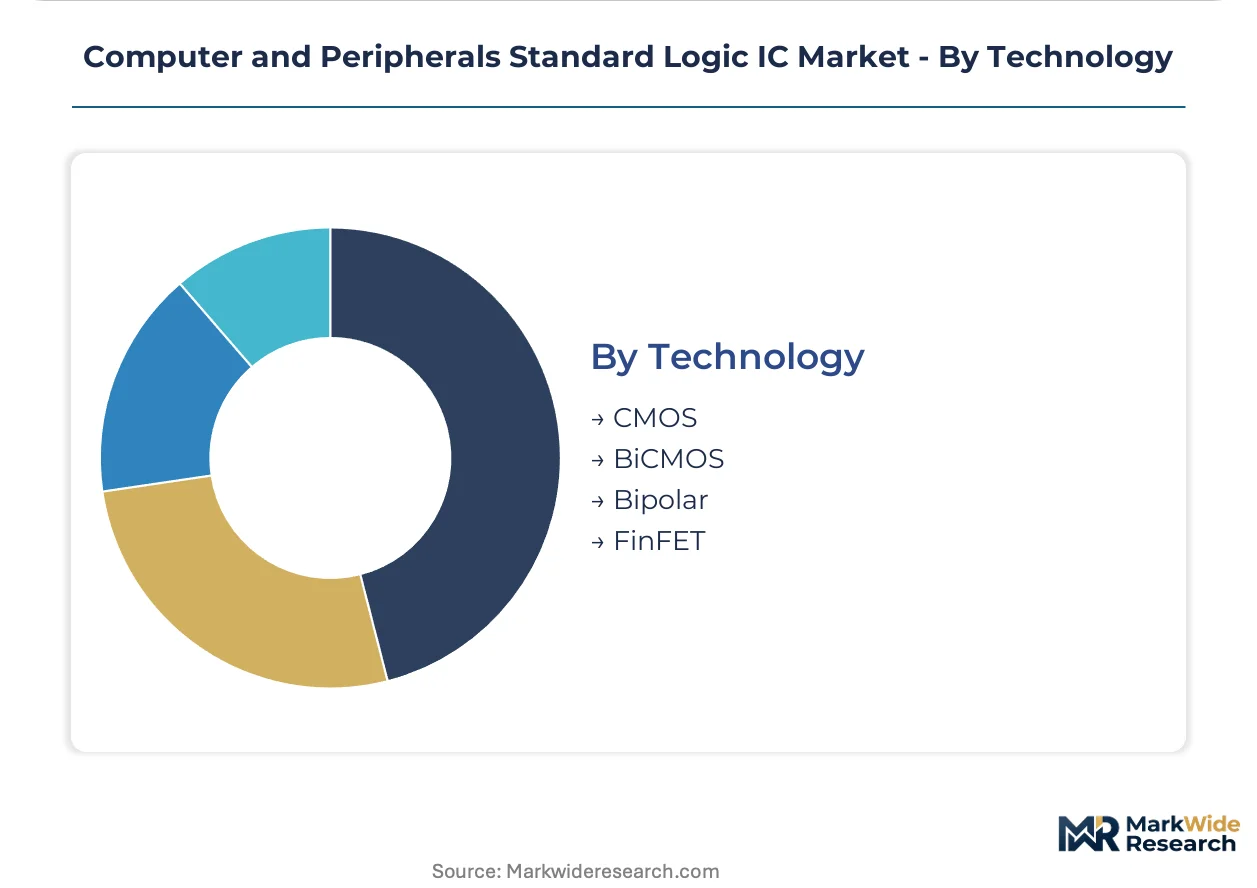
- CMOS:Dominant process for standard logic with operating voltages from 1.2V to 5V, offering optimal static power for battery-powered peripherals. Foundry flexibility at mature nodes sustains dual-source strategies for tier-one PC manufacturers.
- FinFET:Three-dimensional transistor architecture delivers switching performance for high-speed SerDes and memory interfaces. Taiwan-based advanced logic capacity creates single-source vulnerability given cost structures confining deployment to premium segments.
- BiCMOS:Bipolar-CMOS hybrid processes serve precision analog-digital boundaries in mixed-signal applications.
- Bipolar:Legacy process persists in voltage reference and comparator circuits requiring temperature stability.
CMOS leads on scale; FinFET leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's domestic PC manufacturing clusters are expanding faster than Germany's industrial automation base, yet both markets impose divergent compliance burdens on logic IC suppliers. Japan maintains precision manufacturing dominance while India attracts peripheral assembly through production incentives. The United States anchors high-volume procurement through direct OEM contracting.
China
Domestic PC manufacturing clusters in the Yangtze River Delta and Pearl River Delta are expanding capacity for logic IC procurement. SAMR-administered GB standards for electronic product safety extend certification timelines for imported components. Shenzhen and Suzhou industrial parks are consolidating motherboard and display controller production for notebook OEMs.
Germany
Factory floor digitization demands high-reliability logic ICs for motion controllers and sensor interfaces in automotive and industrial crossover applications. REACH and RoHS compliance mandates accelerate lead-free packaging transitions across peripheral supply chains. Bavaria's industrial automation corridor anchors demand from Siemens and Bosch supply ecosystems.
United States
Dell and HP procurement teams negotiate direct supply agreements that bypass traditional distribution channels for high-volume programs. FCC electromagnetic compatibility rules shape product certification pathways for logic ICs in communication peripherals. Texas and California design centers concentrate notebook and display controller specification authority.
Japan
Industrial controller OEMs adopt configurable logic arrays with embedded non-volatile memory to reduce board space and inventory complexity. METI industrial policy supports domestic semiconductor ecosystem resilience. Nagoya and Osaka manufacturing belts concentrate precision automation equipment production requiring AEC-Q100 qualified logic.
India
PLI scheme incentives attract PC peripheral assembly operations requiring localized logic IC sourcing. BIS certification requirements for electronic components create qualification barriers for non-domestic suppliers. Karnataka and Tamil Nadu electronics manufacturing clusters are expanding motherboard and docking station production capacity.
Computer and Peripherals Standard Logic IC Market Vendor Landscape
Top-tier vendors anchor premium-grade logic families, while mid-tier specialists compete on foundry flexibility and regional certification support. The vendor base stratifies across three tiers: integrated analog-digital portfolios, automotive-grade reliability specialists, and programmable logic configurators. Two dominant competitive moves are emerging: direct OEM contracting displaces distribution channels for high-volume programs, and automotive-grade qualification standards penetrate industrial computing segments.
Within the integrated portfolio tier, Texas Instruments Inc and NXP Semiconductors NV occupy positions exemplifying broad analog-digital convergence strategies. STMicroelectronics NV represents the foundry-flexibility archetype, sustaining dual-source qualification capabilities for tier-one PC manufacturers. These three entities anchor distinct competitive vectors without exclusive segment lock-in.
| Leading Market Players |
|---|
| Microchip Technology Inc |
| Toshiba Electronic Devices and Storage Corporation |
| ROHM Co Ltd |
| Diodes Incorporated |
| Texas Instruments Inc |
| onsemi |
| NXP Semiconductors NV |
| STMicroelectronics NV |
| Skyworks Solutions Inc |
| Others |
Supply Flow & Price Mechanics
Silicon wafer spot price indices cascade through mature-node logic IC production, compressing margin pools at commodity tiers while amplifying pricing power for suppliers with automotive-grade certification and dual-source foundry flexibility. This cost transmission mechanism stratifies procurement negotiations across PC manufacturers, industrial automation OEMs, and peripheral assembly operations.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard logic families as domestic foundry expansion intensifies competition at 40nm and above. Contract-based long-term offtake agreements dominate high-volume notebook and display controller programs, with Dell and HP procurement teams extracting volume discounts that bypass distributor markups. Price differentiation hinges on AEC-Q100 certification grade and dual-source qualification status, with automotive-grade logic commanding reliability premiums. Cost compression in commodity digital ICs is intensifying because 300mm substrate pricing volatility squeezes margins on mature-node production. PC manufacturers exhibit highest price sensitivity due to annual volumes exceeding ten million units, while industrial automation OEMs in Germany and Japan prioritize qualification rigor over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from tier-one PC manufacturers mandate redundant qualification of logic ICs across Taiwan, South Korea, and domestic China foundries, extending time-to-revenue but mitigating single-source vulnerability. Raw material dependencies center on 300mm silicon wafers, high-purity chemical precursors for CMOS fabrication, and lead-free packaging substrates compliant with REACH and RoHS mandates. Supply chain risk concentrates in Taiwan-based advanced logic capacity for FinFET segments, where cost structures confine deployment to premium high-speed SerDes applications. Distribution runs through direct OEM contracting displacing traditional authorized channels for programs exceeding ten million annual units, particularly in notebook and display controller segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme production incentives attract peripheral assembly operations requiring localized logic IC sourcing, exploiting a cost differential against China's tightening SAMR certification timelines for imported components.
For Market Incumbents: Hedge against foundry concentration risk by qualifying secondary sources in South Korea and domestic China for mature-node CMOS production. Anchor long-term supply agreements with Dell and HP procurement teams through automotive-grade AEC-Q100 certification investments that penetrate industrial computing segments. Defensive consolidation should target programmable logic configurators with embedded non-volatile memory capabilities to capture margin expansion from discrete function consolidation. For New Entrants and Emerging Players: Industrial automation OEMs in Germany and Japan represent an underserved buyer archetype seeking AEC-Q100 qualified logic for motion controllers with compressed design cycle support. White-space targets include configurable logic arrays for embedded systems and power management ICs for USB-C docking stations. The most penetrable segment is India's expanding motherboard and peripheral assembly clusters under PLI incentives, where BIS certification barriers filter out established competitors. A go-to-market angle anchored in regional certification support and foundry flexibility can displace mid-tier incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where automotive-grade reliability standards penetrate industrial computing, favoring suppliers with verified AEC-Q100 qualification and low-carbon packaging supply chains aligned with EU Green Deal embodied carbon tracking. Long-term viability across the analysis window rests on programmable integration capabilities rather than discrete component scale. Acquisition target archetypes include mid-tier specialists with dual-source foundry relationships and regional certification expertise in China or India. The signal to watch is direct contracting displacement of distribution channels, which accelerates margin compression for distributor-dependent vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade Certification Investment | AEC-Q100 qualification unlocks industrial automation premiums in Germany and Japan. |
| Dual-Source Foundry Qualification | Redundant Taiwan-South Korea capacity mitigates single-source vulnerability for tier-one PC manufacturers. |
| Direct OEM Supply Agreement | Bypassing distributors captures margin from Dell and HP high-volume notebook programs. |
| Lead-Free Packaging Transition | REACH and RoHS compliance secures European market access for peripheral supply chains. |
| Programmable Logic Integration | Embedded non-volatile memory consolidates discrete functions for industrial controller OEMs. |
Methodological Framework
Multiple input streams — primary interviews with logic IC procurement managers at PC manufacturers and industrial automation OEMs, secondary validation through SEC semiconductor filings and SAMR certification databases, and customs trade data on 300mm wafer imports — were reconciled through bottom-up and top-down triangulation. Stakeholder roles engaged included tier-one PC manufacturer procurement directors, industrial controller OEM design engineers, foundry account managers, and distribution channel partners. Secondary sources encompassed FCC electromagnetic compatibility filings, ECHA REACH substance registrations, METI industrial policy disclosures, and IHS Markit semiconductor production data.
Historical shipment patterns were cross-referenced against panel input from procurement executives to construct demand elasticity parameters across the projection horizon. Segmentation dimensions modeled include product type, end user category, application subsystem, and process technology node, with voltage compatibility thresholds and thermal envelopes as industry-specific modifiers. CAGRs were derived from regression analysis of foundry capacity expansion timelines against OEM design-in activity, incorporating USB-C interface proliferation and embedded systems adoption as demand drivers.
Underlying measurement precision varies by segment; digital ICs and PC manufacturer procurement carry tighter precision than emerging mixed-signal variants and India's nascent peripheral assembly base. Forecasts reflect assumptions regarding SAMR certification timeline stability, Taiwan foundry capacity allocation policies, and EU Green Deal carbon tracking implementation. Deviation in silicon wafer pricing volatility or REACH material compliance enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Digital Audio IC Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
3D IC and 2.5D IC Market
IC (Integrated Circuits)
Digital IC Market
IC (Integrated Circuits)
Audio Power Amplifier IC Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Ultra Large Scale Ics Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Touch Controller IC Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market