
 Global Amplifier and Comparator IC Market | 2026-2036
Global Amplifier and Comparator IC Market Size, Share, and Industry Trends Forecast 2026-2036
Global Amplifier and Comparator IC Market Foresight
Analog design engineering talent is bifurcating between legacy bipolar expertise and advanced CMOS specialization, constraining product development cycles across the industry. Texas Instruments leverages its captive fabrication network to sustain gross margin structures that competitors struggle to match. Analog Devices anchors its position through instrumentation amplifier portfolios that dominate precision measurement channels. STMicroelectronics competes aggressively in automotive-qualified operational amplifier segments where AEC-Q100 certification creates supplier stickiness.
Amplifier and comparator ICs are monolithic semiconductor devices that condition, amplify, or threshold-detect analog signals across voltage ranges from microvolts to hundreds of volts, fabricated through processes including CMOS, BiCMOS, and legacy bipolar junction transistor flows with critical parameters such as input offset voltage, slew rate, and common-mode rejection ratio determining suitability for precision sensing, audio processing, and control-loop applications. Operational amplifiers constitute the mature volume base of the market where price competition intensifies, while programmable gain amplifiers capture expanding margin pools in software-defined instrumentation and adaptive RF front ends. CMOS technology leads unit shipments through foundry scalability, though BiCMOS processes retain defensible positions where noise performance and voltage handling must coexist in single devices.
FDA oversight of medical device electronics, EU RoHS substance restrictions, and China's GB standards for telecommunications equipment collectively elevate compliance costs while screening out marginal suppliers unable to sustain certification investments. Japan's METI energy-efficiency guidelines for consumer appliances indirectly shape comparator IC specifications through standby power budgets that demand sub-microamp quiescent currents. Stakeholders must monitor foundry allocation dynamics between analog and digital capacity expansions as that trade-off determines lead-time stability and pricing leverage across amplifier categories.
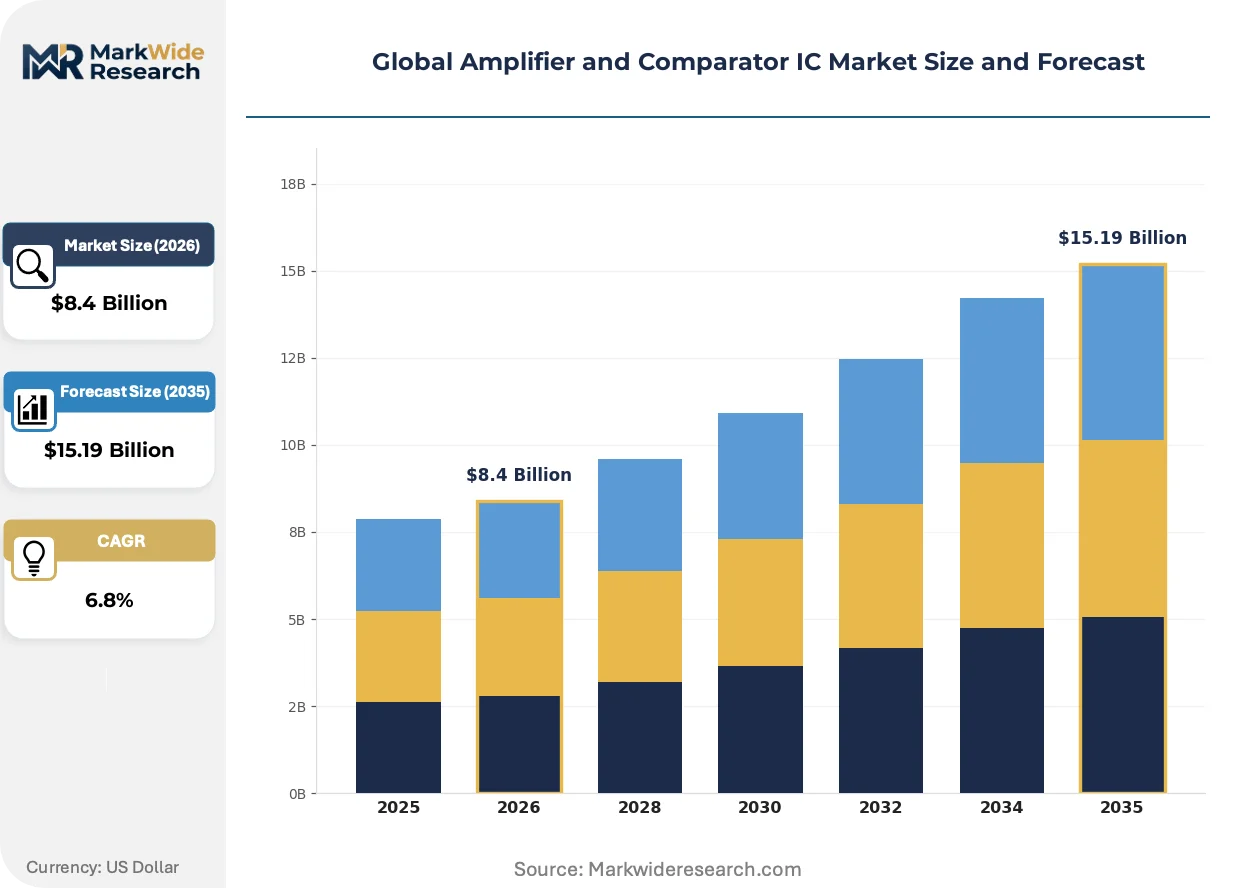
Market Dynamics
Automotive electrification platforms are recalibrating analog content requirements across voltage sensing, battery management, and motor control subsystems, compressing development timelines while expanding specification envelopes for precision amplifiers.
Growth Catalysts
- EV Powertrain Electrification:Battery management systems demand high-precision current-sense amplifiers with sub-microvolt offset specifications. Tier-1 suppliers in Germany, Japan, and China are qualifying AEC-Q100 Grade 0 devices for traction inverter applications.
- RoHS and F-Gas Compliance:Europe's material restrictions are screening out packaging suppliers unable to certify lead-free solder alloys and halogen-free mold compounds, consolidating procurement toward qualified analog foundries.
- Software-Defined Instrumentation:Test equipment manufacturers are integrating programmable gain amplifiers with digital calibration loops, replacing discrete resistor networks in precision measurement channels.
Market Restraints
- Silicon Wafer Cost Volatility:200mm wafer supply for mature analog processes faces allocation pressure from power semiconductor and MEMS demand, elevating die costs for bipolar and BiCMOS flows.
- Foundry Concentration Risk:Analog capacity expansion at TSMC, GlobalFoundries, and domestic Chinese foundries remains skewed toward 300mm digital nodes, constraining 200mm specialty process availability.
- CMOS Noise Floor Limitations:Sub-micron CMOS processes exhibit 1/f noise characteristics that disqualify them from sub-microvolt precision applications, preserving costly BiCMOS and bipolar alternatives.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging and testing are attracting analog assembly investments to Gujarat and Tamil Nadu clusters, creating regional supply alternatives to East Asian concentration.
- Medical Wearable Integration:Continuous glucose monitors and cardiac patch devices require nanopower comparators with sub-500nA quiescent current, opening design-win opportunities outside traditional instrumentation channels.
- GaN and SiC Driver Synergies:Isolated gate drivers with integrated comparators for overcurrent protection are converging with wide-bandgap power switches in EV onboard chargers and solar inverters.
Industry Challenges
- Analog Design Talent Scarcity:Bipolar transistor-level expertise is retiring faster than university programs replenish CMOS-biased graduates, extending product development cycles for precision amplifier families.
- AEC-Q100 Certification Timelines:Automotive qualification protocols demand 1,000-hour high-temperature operating life testing and extended temperature cycling, delaying revenue recognition for new product introductions by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Amplifier and Comparator IC Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Amplifiers, Comparator ICs, Instrumentation Amplifiers, Programmable Gain Amplifiers Technology: CMOS, Bipolar Junction Transistor, BiCMOS, Gallium Arsenide Application: Consumer Electronics, Telecommunications Equipment, Test and Measurement, Aerospace & Defense End User: OEM Electronics Manufacturers, Electronic Design Services, Embedded Systems Developers, IoT Device Producers |
| Companies Covered | Texas Instruments, Analog Devices, STMicroelectronics, Broadcom, Microchip Technology, Infineon Technologies, NXP Semiconductors, Renesas Electronics, ON Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Amplifier and Comparator IC Market Shifts & Advancements
Zero-drift chopper-stabilized architectures are migrating from industrial instrumentation into cost-sensitive consumer and automotive segments, collapsing traditional performance-tier boundaries. This diffusion pattern is compressing margin structures while elevating baseline specifications across price categories.
Chopper-stabilized amplifiers with integrated EMI filtering are displacing discrete auto-zero implementations in weigh-scale and pressure-sensor applications. Industrial automation OEMs in Germany and Japan are adopting these monolithic solutions for PLC analog input modules. The displacement is collapsing the addressable market for standalone precision voltage references and discrete offset-nulling networks.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon use in semiconductor manufacturing cleanrooms and etching processes, elevating compliance costs for analog foundries operating legacy equipment. Packaging suppliers are reformulating mold compounds and die-attach materials to meet halogen-free thresholds. Automotive-qualified amplifier suppliers with European wafer fab exposure face margin compression from material substitution and qualification retesting.
Contract manufacturers in Southeast Asia are consolidating amplifier procurement through consolidated component distributors rather than direct foundry relationships. EMS providers in Vietnam and Malaysia are shifting volume purchasing to authorized distributors with bonded inventory programs, reducing direct OEM engagement with analog semiconductor suppliers. This channel migration is most pronounced in consumer audio and appliance segments where specification standardization enables distributor private-label sourcing.
Global Amplifier and Comparator IC Market Segmentation
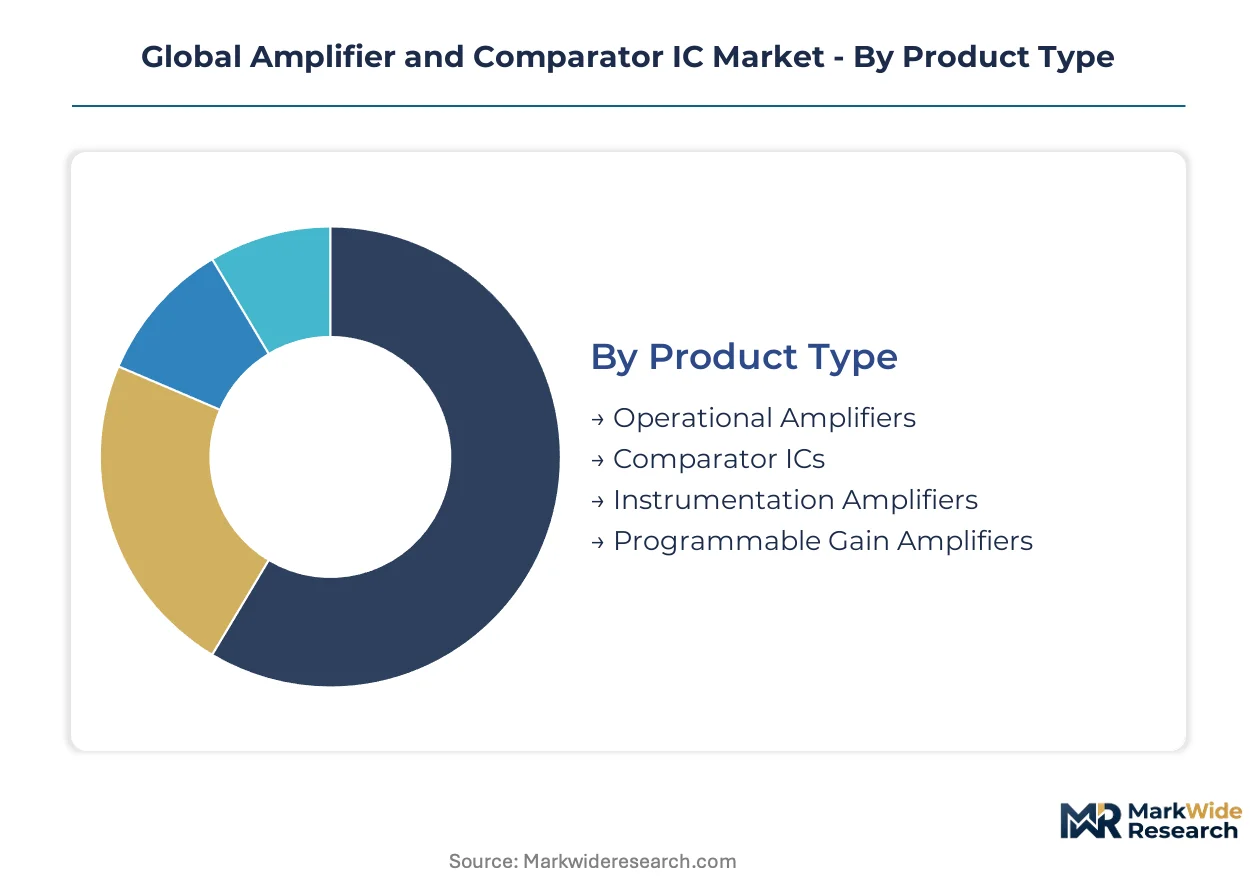
Segmentation in the amplifier and comparator IC market reveals how substitution pressures and process constraints reshape competitive boundaries across product architectures and customer ecosystems. Understanding these fault lines exposes where margin pools concentrate and where commoditization accelerates.
Product Type:
Substitution pressure runs deepest where digital signal processing encroaches on traditional analog conditioning functions, compressing viable territory for discrete amplifier categories.
- Operational Amplifiers:General-purpose voltage amplifiers fabricated through mature CMOS and bipolar flows dominate unit shipments across cost-sensitive consumer audio and appliance controls. China's domestic foundries are scaling 200mm capacity for these devices, pressuring margin structures at the standard-grade tier.
- Comparator ICs:Threshold-detection devices with nanopower quiescent specifications below 500nA are capturing design wins in medical wearables and battery-powered IoT endpoints. FDA oversight of continuous glucose monitors and cardiac patch devices elevates certification barriers for suppliers targeting this segment.
- Instrumentation Amplifiers:Differential-input architectures with high common-mode rejection ratios serve precision measurement channels in industrial automation and medical imaging.
- Programmable Gain Amplifiers:Digitally configurable gain stages with integrated calibration loops displace discrete resistor networks in software-defined test equipment.
Operational amplifiers retain volume leadership; programmable gain amplifiers hold the steepest expansion curve.
Technology:
Cost tier stratification follows process node accessibility, with foundry economics determining which technologies serve premium versus commodity applications.
- CMOS:Sub-micron foundry processes enable the highest integration density and lowest per-unit cost for high-volume consumer and computing applications. TSMC and GlobalFoundries allocate 300mm capacity toward these nodes, though 1/f noise limitations exclude CMOS from sub-microvolt precision sensing.
- Bipolar Junction Transistor:Legacy junction-isolated processes deliver superior transconductance and voltage noise performance for precision instrumentation and professional audio. Retiring design expertise and constrained 200mm wafer supply extend development cycles for new bipolar product families.
- BiCMOS:Combined bipolar-CMOS flows merge analog precision with digital control in automotive battery management and motor control subsystems.
- Gallium Arsenide:III-V compound semiconductor processes serve microwave and millimeter-wave amplifier applications in telecommunications infrastructure.
CMOS commands the broadest application base; BiCMOS claims the most defensible margin structure.
Application:
Customer type concentration varies sharply across end-use sectors, with procurement centralization in automotive and fragmentation in consumer electronics reshaping channel economics.
- Consumer Electronics:Smartphones, tablets, and wearable devices integrate amplifiers for audio playback, haptic feedback, and sensor interfacing. China's GB standards for telecommunications equipment and Japan's METI energy-efficiency guidelines constrain quiescent current budgets and electromagnetic compatibility specifications.
- Telecommunications Equipment:Base stations and optical transport systems demand wideband amplifiers with low distortion characteristics for 5G and fiber-optic signal chains. India's TRAI spectrum allocation policies and China's MIIT infrastructure mandates shape regional procurement volumes.
- Test and Measurement:Oscilloscopes, spectrum analyzers, and semiconductor parametric testers require precision amplifiers with sub-microvolt offset stability.
- Aerospace & Defense:Radiation-hardened and extended-temperature-range devices serve satellite communications and avionics platforms.
Consumer electronics generates the highest unit volumes; test and measurement sustains the most favorable pricing environment.
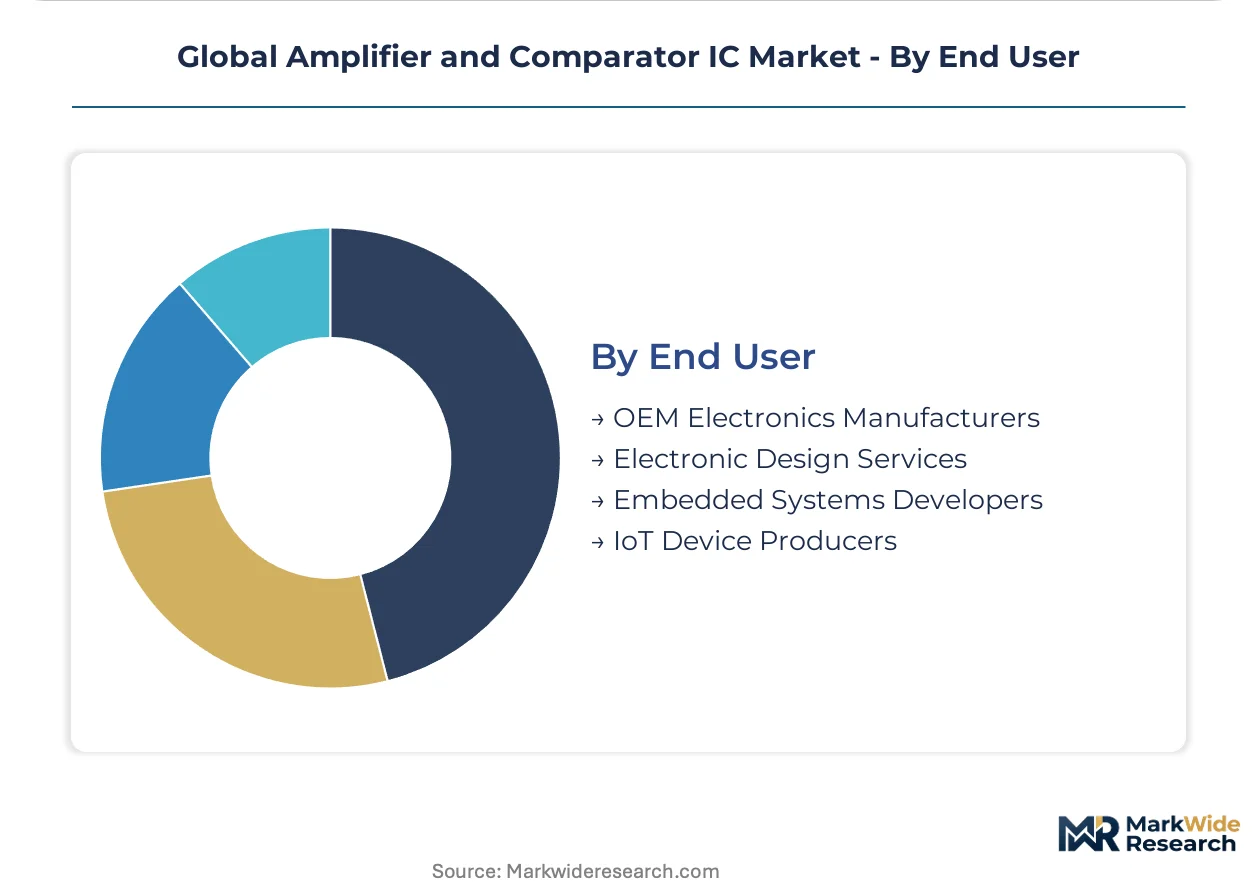
End User:
Geography-driven demand concentration in East Asian manufacturing clusters concentrates procurement leverage among contract manufacturers and consolidated distributors.
- OEM Electronics Manufacturers:Tier-1 automotive suppliers in Germany, Japan, and China qualify AEC-Q100 Grade 0 devices for traction inverters and battery management systems. These manufacturers negotiate direct foundry relationships for high-volume amplifier families, bypassing distributor margins.
- Electronic Design Services:Third-party engineering firms in India and Vietnam specify amplifiers for custom industrial and medical device developments. India's PLI scheme incentives for semiconductor packaging are attracting analog assembly investments to Gujarat and Tamil Nadu clusters.
- Embedded Systems Developers:Industrial automation OEMs in Germany and Japan integrate monolithic solutions for PLC analog input modules.
- IoT Device Producers:Low-power comparator and amplifier integration enables battery-operated sensor nodes and smart home endpoints.
OEM electronics manufacturers anchor procurement volume; IoT device producers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT infrastructure mandates in China are reshaping analog semiconductor procurement patterns across telecommunications and automotive electrification platforms. The report identifies five countries where amplifier and comparator IC demand concentrates through distinct regulatory and industrial configurations.
China
Domestic foundry capacity for analog processes is scaling rapidly in the Yangtze River Delta and Pearl River Delta clusters. GB standards for telecommunications equipment constrain electromagnetic compatibility specifications for consumer-facing amplifier designs. Shanghai and Shenzhen manufacturing hubs are absorbing volume production of operational amplifiers for smartphone and wearable device integration.
Germany
Tier-1 automotive suppliers in Bavaria and Baden-Württemberg qualify AEC-Q100 Grade 0 devices for traction inverter and battery management applications. Europe's F-Gas Regulation elevates compliance costs for analog foundries operating legacy equipment in Dresden and Regensburg wafer fabrication facilities. Stuttgart's automotive electronics corridor concentrates procurement leverage for precision instrumentation amplifiers.
United States
FDA oversight of continuous glucose monitors and cardiac patch devices elevates certification barriers for nanopower comparator suppliers targeting medical wearable segments. EPA and FCC regulations intersect with analog design requirements in industrial automation and telecommunications infrastructure. Texas and Arizona semiconductor clusters sustain captive fabrication networks for high-margin amplifier families.
Japan
METI energy-efficiency guidelines for consumer appliances indirectly shape comparator IC specifications through standby power budgets demanding sub-microamp quiescent currents. Kanto and Kansai industrial corridors retain bipolar transistor-level expertise for precision instrumentation applications. Nagoya's automotive electronics ecosystem qualifies devices for extended temperature range operation.
India
PLI scheme incentives for semiconductor packaging and testing are attracting analog assembly investments to Gujarat and Tamil Nadu clusters. TRAI spectrum allocation policies shape regional procurement volumes for telecommunications infrastructure amplifiers. Bangalore and Hyderabad electronic design services firms specify custom amplifier solutions for industrial and medical device developments.
Global Amplifier and Comparator IC Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the amplifier and comparator IC market. Captive fabrication networks sustain margin structures that fabless competitors struggle to match, while foundry-dependent specialists concentrate on programmable gain and instrumentation amplifier niches. Three archetypes dominate: integrated IDMs with in-house analog processes, fabless designers leveraging foundry partnerships, and automotive-qualified specialists with AEC-Q100 certification depth. Competitive moves center on foundry capacity reservations for 200mm specialty processes and backward integration into packaging materials compliant with RoHS and halogen-free mandates.
Among North American IDMs, Texas Instruments and Analog Devices exemplify divergent strategic positions within the competitive structure. Texas Instruments occupies a scale-driven position anchored by captive fabrication networks spanning multiple geographies. Analog Devices represents specialization in precision measurement channels through instrumentation amplifier portfolio depth. STMicroelectronics, a European-headquartered IDM, sits within the automotive-qualified tier where AEC-Q100 certification creates supplier stickiness in traction inverter and battery management applications.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| STMicroelectronics |
| Broadcom |
| Microchip Technology |
| Infineon Technologies |
| NXP Semiconductors |
| Renesas Electronics |
| ON Semiconductor |
| Others |
Supply & Pricing Matrix
200mm wafer fab utilization rates at specialty analog foundries create asymmetric cost structures that concentrate pricing power among integrated device manufacturers with captive fabrication networks. Scale advantages in bipolar and BiCMOS processes translate directly into price floor elevation for precision amplifier tiers, while CMOS commoditization accelerates margin compression at the standard-grade operational amplifier level.
Pricing Analysis
Geographic price spreads between German automotive-qualified devices and Chinese domestic-grade operational amplifiers exceed three-to-one ratios based on certification tier and thermal performance guarantees. Pricing stratifies across AEC-Q100 Grade 0 premium, industrial-grade standard, and consumer-economy tiers with volume scale and temperature range as primary differentiation drivers. Cost compression in the consumer tier intensifies because Yangtze River Delta foundries are scaling 200mm CMOS capacity for smartphone integration. Tier-1 automotive suppliers in Stuttgart and Nagoya exhibit the lowest price sensitivity due to liability exposure and traceability requirements.
Supply Chain Analysis
Strategic stockpiling of halogen-free mold compounds and lead-free solder alloys dominates inventory strategy as Europe's F-Gas Regulation accelerates material substitution timelines. Geographic supply concentration centers on Taiwan for 300mm CMOS foundry services, Germany for automotive-qualified BiCMOS wafer processing, and China for domestic 200mm bipolar capacity expansion. Raw material dependencies include high-purity silicon wafers, gold wire bonding materials, and ceramic packaging substrates. Single-source vulnerability in 200mm specialty process equipment creates structural risk as tool vendors prioritize 300mm digital node deliveries. Distribution runs through consolidated authorized distributors with bonded inventory programs rather than direct foundry relationships for sub-tier EMS providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bipolar transistor-level design expertise is departing the workforce faster than university programs replenish CMOS-biased graduates, creating a capability-scarcity environment where analog engineering talent arbitrage determines competitive survival. This asset gap favors incumbents with established design teams and punishes entrants lacking legacy process knowledge.
For Market Incumbents: Secure captive 200mm wafer supply agreements with GlobalFoundries and domestic Chinese foundries before allocation shifts toward power semiconductor demand. Deepen backward integration into halogen-free packaging materials to preempt RoHS compliance cost escalation. AEC-Q100 certification depth serves as the priority defensive moat against fabless competitors attempting automotive qualification. For New Entrants and Emerging Players: AEC-Q100 Grade 2 fast-track qualification for industrial automation applications offers lower barrier entry than Grade 0 automotive traction inverter certification. Target India's PLI scheme packaging clusters in Gujarat and Tamil Nadu for assembly cost advantages outside East Asian concentration. Medical wearable comparator segments with FDA 510(k) pathways represent the most penetrable white-space with nanopower quiescent current specifications below 500nA. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated IDMs with in-house bipolar and BiCMOS processes over foundry-dependent fabless designers. Long-term viability over the projection horizon rests on analog design team depth and automotive certification infrastructure rather than digital CMOS scale advantages. Acquisition target archetypes include precision instrumentation amplifier specialists with established industrial automation channels. The signal to watch is 200mm wafer allocation shifts between analog and power semiconductor demand as inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | 200mm specialty process allocation at TSMC and GlobalFoundries secures lead-time stability for precision amplifier families. |
| AEC-Q100 Certification Investment | Automotive qualification depth creates supplier stickiness in traction inverter and battery management applications. |
| Backward Integration into Packaging | In-house halogen-free mold compound production preempts Europe's F-Gas Regulation compliance cost escalation. |
| India PLI Scheme Assembly Expansion | Gujarat and Tamil Nadu packaging clusters reduce East Asian supply concentration risk for automotive-qualified devices. |
| Zero-Drift Architecture Migration | Chopper-stabilized amplifier integration displaces discrete auto-zero implementations in weigh-scale and pressure-sensor applications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC semiconductor filings, MIIT infrastructure mandates, and ECHA REACH substance databases through structured validation protocols. Primary interviews engaged analog design engineering directors, Tier-1 automotive supplier procurement managers, analog foundry capacity planning officers, and medical device regulatory affairs leads. Secondary sources included FDA 510(k) clearance databases, AEC-Q100 qualification registries, and customs trade flow records for amplifier and comparator IC categories. Bottom-up product-level shipment analysis triangulates against top-down semiconductor consumption models.
Segmentation dimensions modeled span product architecture, fabrication technology, application sector, and end-user procurement concentration across the projection horizon. The analytical framework derives CAGRs from foundry capacity expansion schedules, automotive electrification platform ramp rates, and medical wearable device approval trajectories. Industry-specific forecast inputs include 200mm wafer supply allocation ratios between analog and power semiconductor demand, plus AEC-Q100 certification timeline distributions for new product introductions.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification investment levels or analog foundry capacity expansion commitments would require recalibration. Forecasts reflect assumptions regarding bipolar design expertise retirement rates and China domestic foundry yield maturation. Revision becomes warranted when 200mm wafer pricing volatility or F-Gas Regulation enforcement intensity crosses thresholds that alter foundry economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
NFC Reader Ics Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
CMOS Power Amplifier Market
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
Gate Driver IC Market
IC (Integrated Circuits)
NFC Tag Ics Market
IC (Integrated Circuits)
Global Application Specific Automotive Analog IC Market
IC (Integrated Circuits)
GNSS IC Market
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
APAC Analog IC Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market