
 Global Application Specific Consumer Analog Integrated Circuit Market | 2026-2036
Global Application Specific Consumer Analog Integrated Circuit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Application Specific Consumer Analog Integrated Circuit Market Foresight
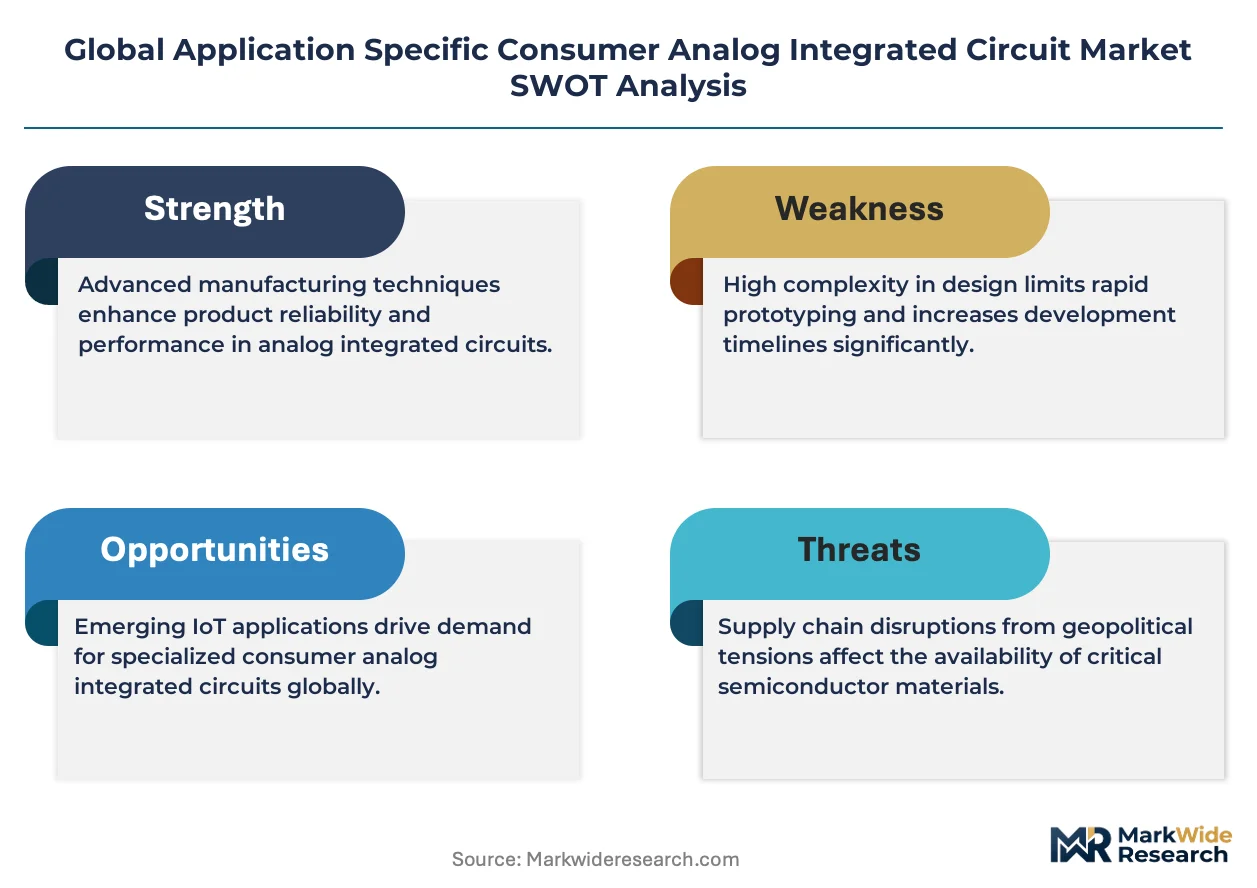
ISO 26262 functional safety certification is reorganizing supplier eligibility for automotive-grade analog IC procurement. Texas Instruments leverages captive fabrication to sustain margin control across voltage regulator portfolios. Infineon Technologies anchors European automotive electronics through specialized power amplifier modules. Skyworks Solutions dominates RF signal conditioning for premium smartphone platforms.
Application specific consumer analog integrated circuits are customized semiconductor devices engineered to process continuous electrical signals within defined voltage ranges, noise floors, and power budgets for targeted consumer equipment. These circuits integrate operational amplifiers, comparators, and voltage regulators fabricated in BiCMOS or GaN processes to achieve precise signal conditioning in space-constrained devices. The technology dimension shows CMOS maintaining cost leadership in high-volume consumer electronics while GaN displaces legacy silicon in fast-charging power stages. Audio processing applications command premium pricing due to low total harmonic distortion requirements, whereas sensor interface segments expand fastest from wearable and smart home adoption.
FCC Part 15 emissions rules in the United States constrain RF analog designs for wireless consumer products, while EU RoHS and REACH directives restrict substance use in European-bound shipments. Japan's METI enforces energy efficiency benchmarks that shape power management IC specifications for export markets. Stakeholders must weigh dual carbon compliance timelines against GaN process migration costs when committing capacity expansion plans.
Market Dynamics
GaN process migration is compressing design cycles for power-stage analog ICs while REACH halogen-free mandates restructure packaging material sourcing across European-bound supply chains.
Growth Catalysts
- Fast-charging power stage proliferation:Smartphone OEMs in South Korea are integrating GaN-based voltage regulators to shrink adapter footprints. This process shift accelerates BiCMOS displacement in premium consumer segments.
- EU REACH substance restrictions:Halogen-free packaging material mandates are forcing foundry qualification programs for epoxy molding compounds. Compliance is unlocking access to high-margin European distribution channels.
- Wearable sensor interface expansion:Health-monitoring device manufacturers are specifying ultra-low-noise analog front-ends. BiCMOS operational amplifiers with sub-microvolt offset specifications are capturing design wins in wrist-worn form factors.
Market Restraints
- GaN wafer cost volatility:Six-inch GaN-on-silicon substrate pricing fluctuates with power electronics demand from electric vehicle inverters. Consumer analog IC margins compress when substrate allocation prioritizes automotive customers.
- East Asian foundry concentration:Mature-node BiCMOS capacity clusters in Taiwan and South Korea. Geographic concentration risk escalates during regional power grid stress or trade policy friction.
- Silicon LDMOS performance ceiling:Legacy silicon power transistors face thermal dissipation limits above 100W fast-charging profiles. Design engineers encounter switching frequency constraints that GaN solves but at qualification cost.
Strategic Opportunities
- India electronics manufacturing expansion:PLI scheme incentives for smartphone assembly are creating demand for localized analog IC sourcing. Audio codec and touch controller suppliers can establish captive testing facilities in Tamil Nadu and Karnataka clusters.
- Audio processing convergence with spatial computing:Mixed-reality headset manufacturers require multi-channel DAC arrays with sub-0.001% THD. This specification tier commands premium positioning unavailable in commodity smartphone audio ICs.
- Japan METI energy efficiency benchmarks:Standby power regulations for consumer electronics are mandating sub-milliwatt quiescent current in voltage regulators. Compliant designs qualify for preferential procurement in export markets.
Industry Challenges
- Analog-mixed-signal design talent scarcity:Experienced BiCMOS layout engineers with noise-optimization expertise command compensation premiums. Foundry design service teams face recruitment competition from automotive sensor IC divisions.
- ISO 26262 certification timeline compression:Consumer-grade analog IC suppliers seeking automotive adjacencies must implement functional safety management systems. Documentation and third-party audit cycles extend product launch schedules by 18-24 months.
- Legacy socket compatibility requirements:Smart home device OEMs demand pin-compatible replacements for end-of-life audio amplifiers. Engineering teams must replicate electrical characteristics without access to original process recipes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Application Specific Consumer Analog Integrated Circuit Market |
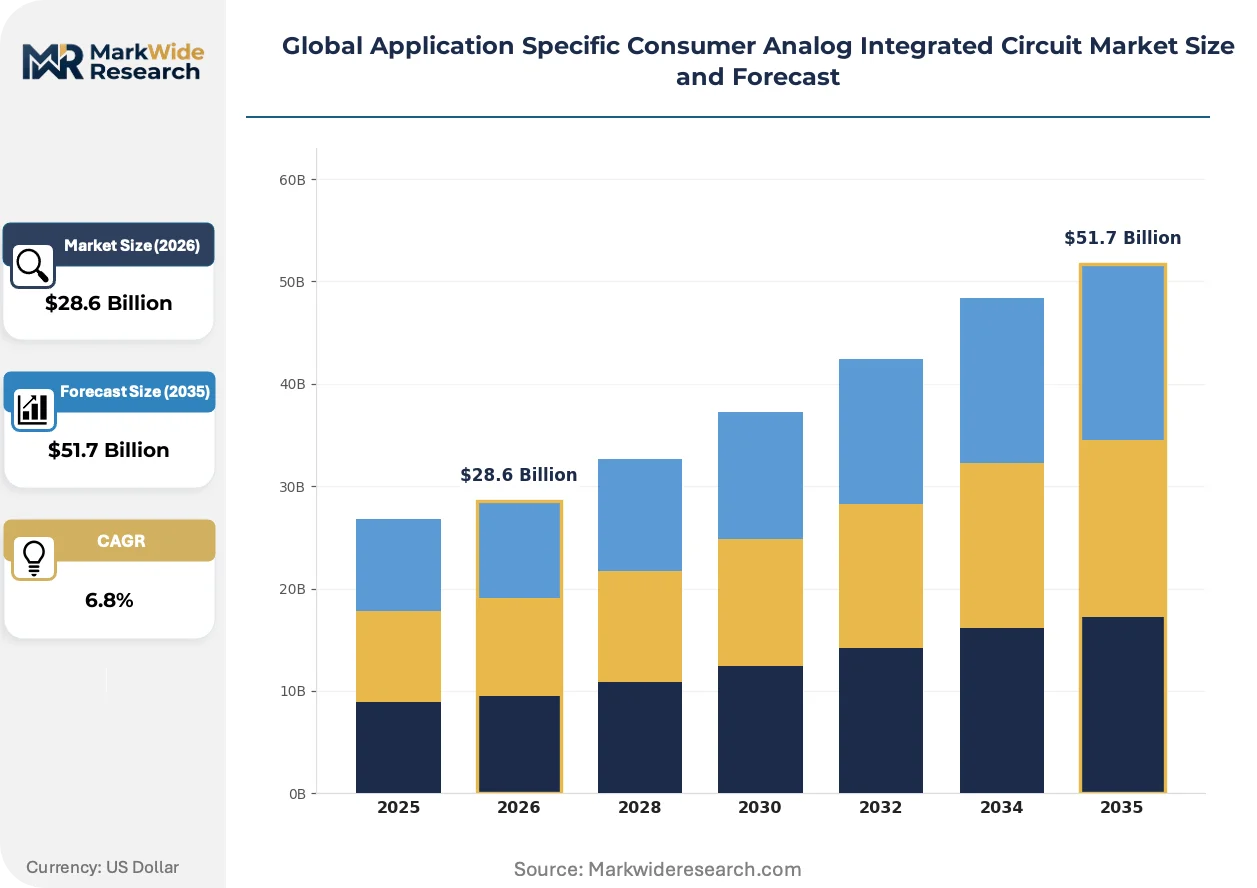
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Amplifiers, Operational Amplifiers, Voltage Regulators, Comparator Circuits End User: Consumer Electronics, Automotive Electronics, Industrial Equipment, Telecommunications Technology: BiCMOS, CMOS, BJT, GaN Application: Audio Processing, Signal Conditioning, Data Acquisition, Sensor Interfaces |
| Companies Covered | Infineon Technologies, Renesas Electronics, Texas Instruments, Microchip Technology, ON Semiconductor, Analog Devices, NXP Semiconductors, Skyworks Solutions, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Application Specific Consumer Analog Integrated Circuit Market Shifts & Advancements
Process node diversification and regulatory substance bans are fragmenting analog IC qualification pathways while procurement models consolidate around direct foundry partnerships for GaN capacity allocation.
GaN-on-silicon power transistors is supplanting silicon superjunction MOSFETs in smartphone fast-charging adapters. Premium tier-1 OEMs in South Korea and China have completed platform transitions to 65W+ GaN-based designs. This substitution is compressing bill-of-material costs while enabling 50% volume reduction in wall-charger enclosures.
EU REACH Annex XVII restrictions on halogenated flame retardants are mandating green molding compound conversion for QFN and BGA packages. Epoxy resin suppliers in Germany and the Netherlands are qualifying phosphorus-based alternatives with equivalent thermal cycling performance. Audio processing ICs bound for European consumer electronics face 2025 compliance deadlines that accelerate packaging line changeovers.
Direct foundry capacity contracting is displacing merchant distributor procurement for GaN analog IC wafers. Smartphone OEMs in Shenzhen and Seoul are negotiating multi-year take-or-pay agreements with Taiwan-based foundries. This channel shift concentrates volume commitment risk with buyers while securing priority queue positioning during capacity tightness.
Global Application Specific Consumer Analog Integrated Circuit Market Segmentation
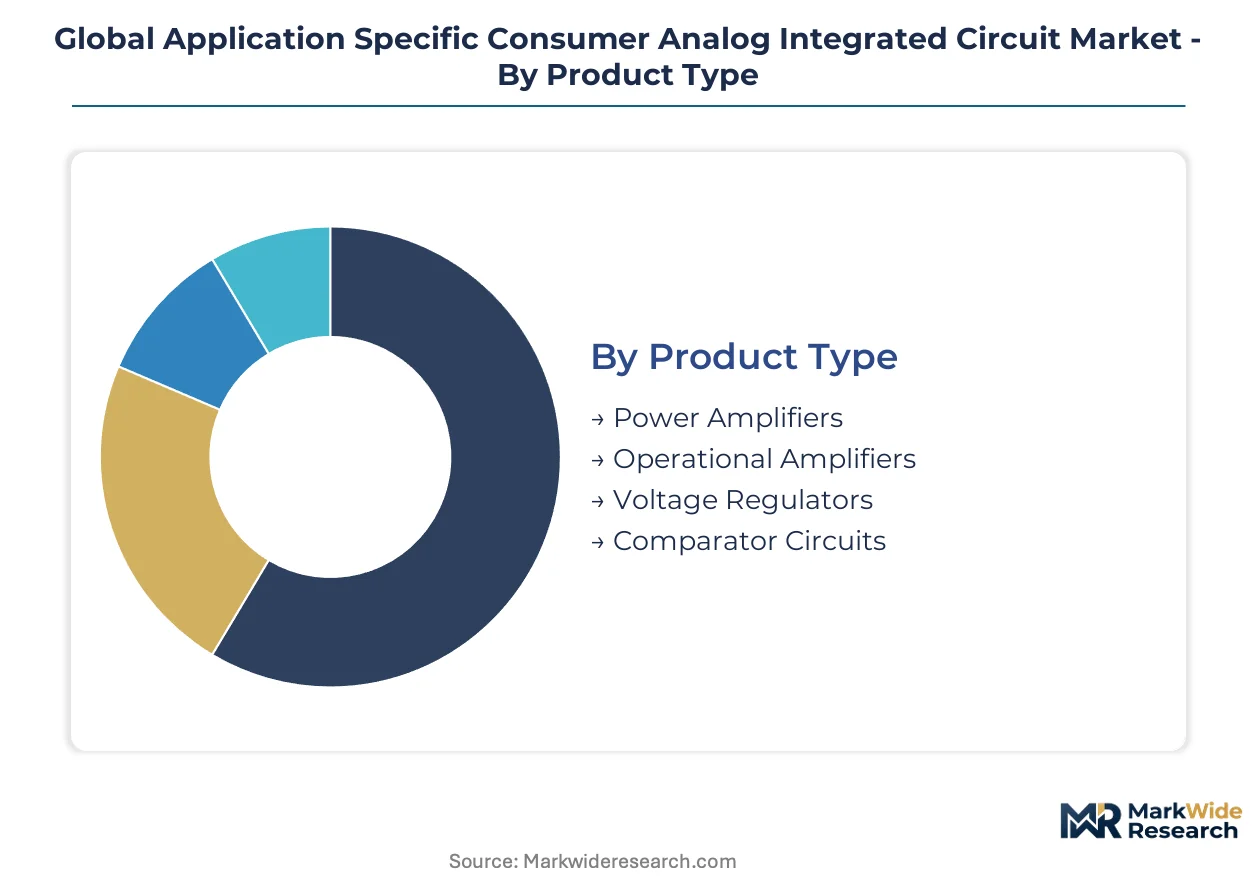
Product architecture, process technology, and end-use requirements fragment the consumer analog IC landscape into distinct procurement channels. Each segment carries unique qualification protocols and margin profiles that shape supplier selection criteria.
Product Type:
Power amplifiers and voltage regulators flow through tier-1 smartphone OEM direct procurement channels, while operational amplifiers and comparators distribute through specialized analog distributors serving mid-volume electronics manufacturers.
- Voltage Regulators:These devices maintain stable output voltage across varying load conditions and input fluctuations. GaN-based variants in South Korean smartphone adapters are displacing silicon LDOs in fast-charging applications. Demand concentrates in Shenzhen and Seoul manufacturing clusters where 65W+ adapter platforms dominate premium tiers.
- Power Amplifiers:Audio amplification stages deliver specified output power with controlled distortion characteristics. RF power amplifiers for smartphone platforms command premium positioning through Skyworks Solutions' direct foundry partnerships. European automotive electronics procurement requires ISO 26262 documentation that consumer-grade suppliers struggle to provide.
- Operational Amplifiers:High-gain differential signal processing blocks with defined input offset and bandwidth specifications.
- Comparator Circuits:High-speed threshold detection elements for sensor interface and power management triggering applications.
By volume, voltage regulators lead procurement schedules. By expansion trajectory, power amplifiers for RF applications are climbing the fastest.
End User:
Cost tier stratification separates high-volume consumer electronics procurement from automotive and industrial segments where certification premiums apply.
- Consumer Electronics:Smartphone, tablet, and wearable OEMs specify analog ICs for audio processing and power management functions. South Korean display manufacturing clusters generate concentrated demand for sensor interface chips. FCC Part 15 emissions compliance shapes RF analog designs for wireless consumer products bound for US distribution.
- Automotive Electronics:Infotainment and ADAS subsystems require AEC-Q100 qualified components with extended temperature ranges. ISO 26262 functional safety certification reorganizes supplier eligibility, extending product launch timelines substantially. European tier-1 suppliers anchor procurement through specialized power amplifier modules.
- Telecommunications:Base station and network infrastructure equipment demands high-linearity signal conditioning components.
- Industrial Equipment:Factory automation and instrumentation applications prioritize precision and long-term supply stability over cost minimization.
Consumer electronics captures the largest shipment volumes. Automotive electronics shows the steepest margin expansion as electrification multiplies analog content per vehicle.
Technology:
Process maturity and capital intensity create divergent supply concentration patterns across fabrication technologies.
- GaN:Gallium nitride-on-silicon power transistors enable high-frequency switching with reduced thermal losses. Taiwan-based foundries negotiate multi-year take-or-pay agreements with Shenzhen and Seoul OEMs for capacity allocation. Substrate cost volatility from electric vehicle inverter demand compresses consumer analog margins during automotive allocation priority.
- BiCMOS:Bipolar-CMOS integration combines analog precision with digital density for mixed-signal applications. Mature-node capacity clusters in Taiwan and South Korea concentrate geographic risk during regional power grid stress. Experienced layout engineers with noise-optimization expertise command compensation premiums that inflate design service costs.
- CMOS:Pure CMOS processes maintain cost leadership in high-volume consumer electronics voltage regulation and switching functions.
- BJT:Bipolar junction transistor processes persist in specialized high-voltage and precision reference applications.
CMOS dominates unit shipments by substantial margin. GaN is gaining share fastest as fast-charging adapter platforms proliferate.
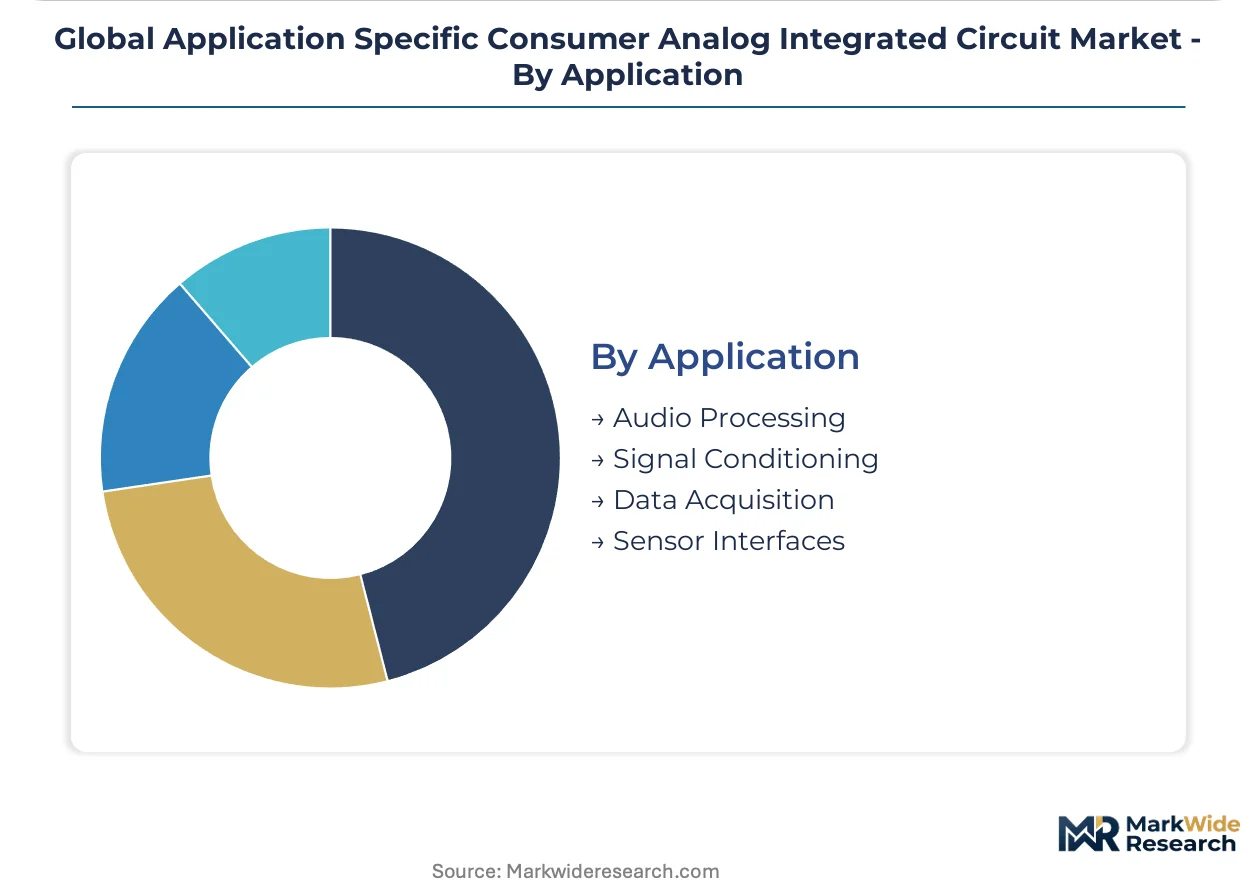
Application:
Functional performance requirements segment procurement between premium audio specifications and high-volume sensor interface growth.
- Audio Processing:Multi-channel DAC and ADC arrays with sub-0.001% total harmonic distortion specifications serve mixed-reality headset manufacturers. This specification tier commands positioning unavailable in commodity smartphone audio ICs. Spatial computing convergence is expanding channel counts and precision requirements beyond traditional stereo configurations.
- Sensor Interfaces:Ultra-low-noise analog front-ends capture physiological and environmental signals in wrist-worn and smart home form factors. BiCMOS operational amplifiers with sub-microvolt offset specifications are capturing design wins as health-monitoring device manufacturers expand specifications. India's PLI scheme incentives for smartphone assembly are creating localized demand for touch controller and motion sensor interface chips.
- Signal Conditioning:Amplification, filtering, and level translation functions prepare signals for digital processing stages.
- Data Acquisition:Precision sampling and conversion subsystems for measurement and control applications.
Sensor interfaces lead volume expansion from wearable and smart home adoption. Audio processing maintains the highest average selling prices through distortion performance differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electronics manufacturing is redrawing procurement geography for consumer analog ICs. South Korea's smartphone OEMs are consolidating GaN-based fast-charging supply chains. Germany's REACH enforcement is restructuring packaging material qualification timelines.
United States
FCC Part 15 emissions compliance is shaping RF analog designs for wireless consumer products. The EPA's energy efficiency guidelines influence standby power specifications in voltage regulators. Austin and Dallas-Fort Worth semiconductor clusters are expanding BiCMOS design service teams for audio processing applications.
South Korea
Samsung and LG Electronics are driving concentrated demand for sensor interface chips in display manufacturing. The MFDS enforces electromagnetic compatibility standards that constrain RF power amplifier designs. Seoul Capital Area foundries are negotiating multi-year GaN capacity agreements with smartphone OEMs.
Germany
ECHA's REACH Annex XVII halogen restrictions are mandating green molding compound conversion for European-bound shipments. The KBA's automotive safety standards create certification premiums for suppliers seeking adjacencies. Bavaria's precision electronics manufacturers are qualifying phosphorus-based epoxy alternatives for QFN packages.
China
MIIT's dual carbon goals are accelerating GaN process migration in fast-charging adapter production. Shenzhen smartphone OEMs are contracting directly with Taiwan-based foundries for capacity allocation. Pearl River Delta manufacturing clusters are displacing silicon LDMOS in 65W+ power stage designs.
Japan
METI's standby power regulations are mandating sub-milliwatt quiescent current in voltage regulators for export markets. JIS standards shape precision specifications for wearable sensor interface chips. Kanto region electronics manufacturers are capturing design wins in mixed-reality headset audio processing.
Global Application Specific Consumer Analog Integrated Circuit Market Competitive Landscape
Player mix skews toward diversified semiconductor conglomerates with captive fabrication assets. Tier-1 suppliers anchor premium smartphone and automotive procurement channels through direct foundry partnerships. Mid-scale specialists occupy sensor interface niches requiring ultra-low-noise BiCMOS expertise. Competitive moves concentrate on GaN capacity reservation agreements and REACH-compliant packaging line conversions.
Among diversified analog IC fabricators, Texas Instruments, Infineon Technologies, and Skyworks Solutions exemplify distinct strategic positioning. Texas Instruments represents the captive fabrication archetype sustaining margin control across voltage regulator portfolios. Infineon Technologies anchors European automotive electronics procurement through specialized power module expertise. Skyworks Solutions occupies the RF signal conditioning tier for premium smartphone platforms.
| Leading Market Players |
|---|
| Infineon Technologies |
| Renesas Electronics |
| Texas Instruments |
| Microchip Technology |
| ON Semiconductor |
| Analog Devices |
| NXP Semiconductors |
| Skyworks Solutions |
| STMicroelectronics |
| Others |
Supply & Pricing Matrix
Multi-year take-or-pay agreements with Taiwan-based foundries lock in GaN wafer access and price visibility for Shenzhen and Seoul smartphone OEMs, insulating premium tier procurement from substrate cost volatility driven by electric vehicle inverter demand.
Pricing Analysis
Cost-plus contracts with gallium nitride substrate indexation dominate GaN analog IC procurement. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels separates AEC-Q100 qualified components from commodity smartphone audio ICs. Pricing pressure stems from six-inch GaN-on-silicon substrate allocation prioritizing automotive power electronics. Consumer electronics OEMs exhibit highest price sensitivity, while mixed-reality headset manufacturers accept premium positioning for sub-0.001% THD audio specifications.
Supply Chain Analysis
Six-inch GaN-on-silicon substrate supply from Taiwan, Japan, and the United States anchors power-stage analog IC production. Epoxy molding compounds draw from German and Dutch suppliers qualifying phosphorus-based alternatives under REACH Annex XVII. Single-source vulnerability concentrates in mature-node BiCMOS foundry capacity across Taiwan and South Korea. Distribution runs through direct foundry partnerships displacing merchant distributor channels for GaN capacity allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN process migration in fast-charging adapters represents an early-cycle expansion story, with South Korean smartphone OEM platform transitions justifying sustained capacity reservation demand across the projection horizon.
For Market Incumbents: Shield margin position through captive GaN fabrication or backward integration into substrate sourcing. Lock in multi-year capacity agreements before Taiwan foundry queues tighten further. Prioritize ISO 26262 certification investment to access automotive electronics procurement channels where Infineon Technologies currently anchors European demand. For New Entrants and Emerging Players: Anchor in India's PLI scheme electronics manufacturing clusters for localized audio codec and touch controller testing facilities. Target sensor interface segments requiring ultra-low-noise BiCMOS expertise where experienced layout engineer scarcity limits incumbent expansion. Pursue direct partnerships with Tamil Nadu and Karnataka smartphone assembly operations as the go-to-market angle. For Investors and Strategic Acquirers: Specialized GaN power-stage design houses with direct foundry relationships represent the most compelling acquisition target archetype. Long-term viability hinges on sustained displacement of silicon LDMOS in 65W+ fast-charging platforms. Monitor Taiwan foundry utilization rates as the inflection indicator for capacity tightness and pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Process Migration Acceleration | Enables 50% volume reduction in wall-charger enclosures for South Korean OEMs. |
| REACH-Compliant Packaging Conversion | Unlocks European distribution access through phosphorus-based epoxy qualification. |
| Direct Foundry Capacity Contracting | Concentrates volume commitment risk with buyers while securing priority queue positioning. |
| ISO 26262 Certification Investment | Extends product launch timelines 18-24 months but opens automotive procurement channels. |
| India PLI Localization | Captures smartphone assembly demand for audio codec and sensor interface chips in Tamil Nadu. |
Research Methodology
A standing panel of analog IC design engineers, foundry procurement managers, smartphone OEM component strategists, and regulatory compliance officers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from SEC semiconductor filings, Taiwan Stock Exchange foundry capacity disclosures, ECHA REACH substance restriction updates, and customs trade data. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates against foundry wafer starts and OEM bill-of-material disclosures.
Consistency checks validated model outputs against external benchmarks including foundry revenue reports and smartphone adapter teardown analyses. The analytical framework segments by product type, process technology, end-use application, and regional manufacturing cluster across the projection horizon. CAGRs derive from regression analysis of historical foundry utilization, OEM platform transition timelines, and regulatory compliance deadline impacts. GaN substrate pricing indices and BiCMOS design service cost inflation feed directly into margin compression modeling.
Decision-makers should treat outputs as directional under assumptions of sustained GaN fast-charging adoption and stable REACH enforcement timelines; material deviation in electric vehicle inverter demand or halogen-free packaging conversion rates would warrant model refresh. Practitioners should keep alternative scenarios live as Taiwan foundry capacity allocation priorities and India PLI scheme incentive structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Standard Logic IC Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Rugged IC Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
Application Specific Analog IC Market
IC (Integrated Circuits)
Europe Integrated Circuits Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
Global Application Specific Automotive Analog IC Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
CMOS Power Amplifier Market
IC (Integrated Circuits)
Asia Pacific Integrated Circuit (IC) Market