

Embedded Universal Integrated Circuit Card (eUICC) Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Universal Integrated Circuit Card (eUICC) Market Insights
Platform licensing revenue is tilting from hardware-centric SIM distribution toward recurring profile-management services. Thales sustains technology leadership through advanced remote SIM provisioning architectures. Giesecke+Devrient dominates physical secure element manufacturing with deep ties to European telecommunications operators. Qualcomm extends its position by integrating eUICC functionality directly into cellular modem chipsets for streamlined device onboarding.
An embedded universal integrated circuit card is a solderable, non-removable secure element that stores multiple operator profiles and enables over-the-air provisioning through M2M or consumer remote SIM specifications, typically manufactured on certified Common Criteria EAL4+ semiconductor processes. Its primary purpose is to eliminate physical SIM swaps while enabling seamless carrier switching across IoT, automotive, and consumer devices. Memory eUICC segments anchor volume in low-complexity IoT metering applications where cost sensitivity dominates procurement decisions. Connected vehicles represent the fastest-growing application as automotive OEMs mandate embedded connectivity for telematics, emergency calling, and software-defined vehicle updates.
The European Telecommunications Standards Institute sets functional requirements for M2M and consumer eUICC architectures, while the GSM Association governs interoperability certification through its SAS-UP accreditation scheme for remote SIM provisioning servers. In the United States, the FCC's equipment authorization rules intersect with carrier-specific network access requirements, creating layered compliance obligations for device manufacturers. China's MIIT enforces domestic encryption standards that influence secure element designs for products entering that market. Stakeholders must monitor whether fragmented national cybersecurity certifications fragment the interoperability that eUICC technology was designed to achieve.
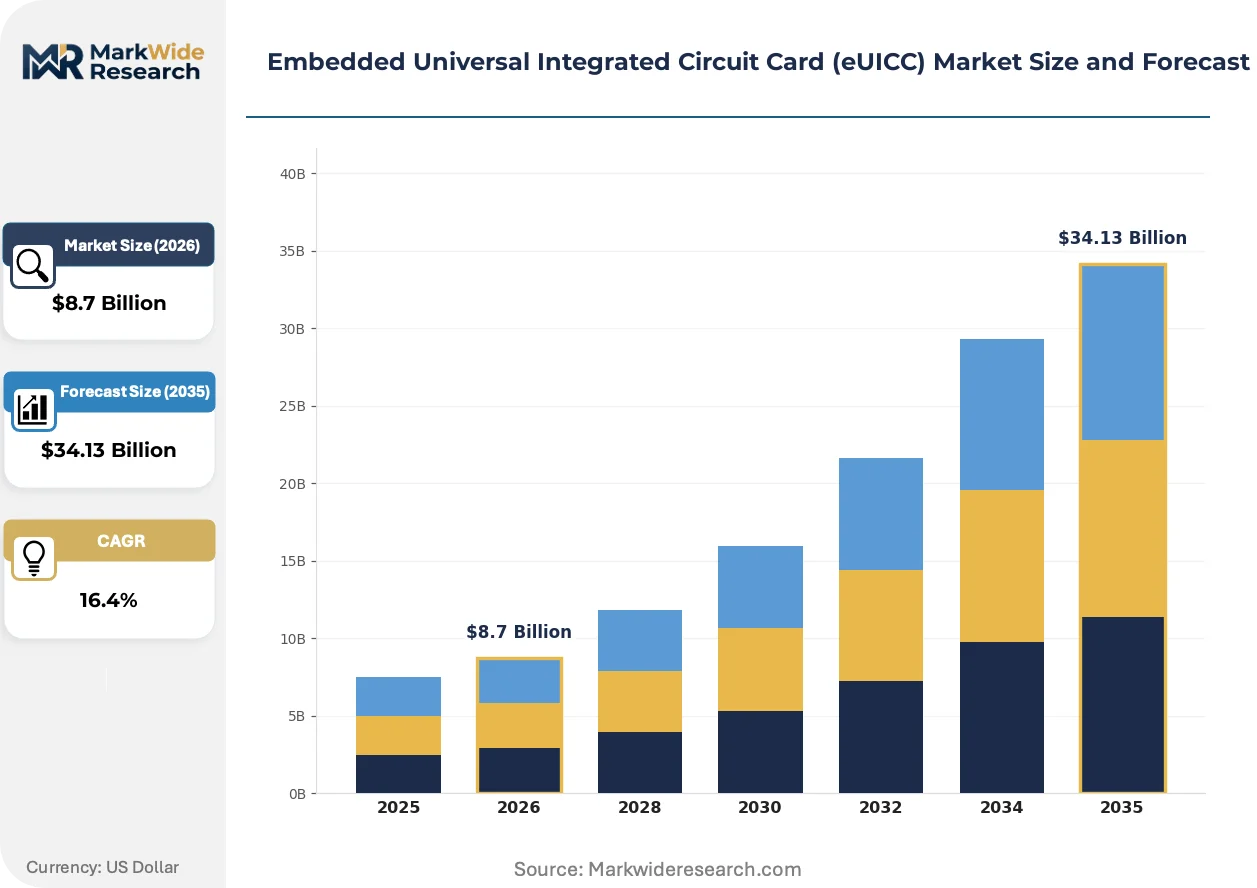
Market Dynamics
The eUICC market is being fundamentally restructured by automotive OEMs mandating embedded connectivity architectures for software-defined vehicle fleets, compressing traditional SIM supply chains into semiconductor-integrated secure elements.
Growth Catalysts
- EU Cybersecurity Act:The regulation mandates Common Criteria EAL4+ certification for secure elements, accelerating carrier adoption of standardized eUICC architectures across connected vehicle and industrial IoT deployments.
- Automotive telematics:OEMs in Germany, the United States, and China are embedding eUICC functionality directly into vehicle gateway modules to enable over-the-air firmware updates and emergency calling mandates.
- Remote SIM provisioning:The GSMA's SAS-UP accreditation scheme for subscription management servers is collapsing technical barriers to multi-profile switching across M2M and consumer devices.
Market Restraints
- Semiconductor foundry concentration:Secure element fabrication depends on a limited number of certified Common Criteria facilities in Germany and South Korea, creating supply vulnerability during capacity constraints.
- MIIT encryption standards:China's domestic cryptographic requirements force design variants for products entering that market, fragmenting hardware economies of scale.
- Legacy MFF2 form factor substitution:Removable machine-to-machine form factors persist in cost-sensitive IoT metering applications where solderable eUICC premiums face procurement resistance.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for semiconductor assembly and testing are attracting eUICC packaging investments to serve domestic telecommunications and automotive demand.
- Integrated SIM (iSIM):The convergence of secure element functionality with cellular baseband processors eliminates discrete component costs and opens subscription management to low-complexity consumer electronics.
- Software-defined vehicles:Automotive OEMs in Germany and the United States are specifying eUICC as mandatory for connected car platforms, creating embedded connectivity pull through 2035.
Industry Challenges
- Common Criteria EAL4+ certification timelines:Security evaluation processes for new semiconductor designs extend 12-18 months, delaying product launches and freezing architecture decisions early in development cycles.
- Interoperability testing complexity:Fragmented national cybersecurity certifications across EU member states, the United States, and China multiply compliance engineering overhead for global device manufacturers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Universal Integrated Circuit Card (eUICC) Market Trends and Innovations
Remote SIM provisioning specifications are collapsing traditional carrier-device relationships, while semiconductor integration and regulatory fragmentation are reshaping competitive boundaries across secure element supply chains.
Integrated SIM architectures are collapsing the distinction between cellular modem and secure element functions. Qualcomm and Mediatek are embedding tamper-resistant enclaves directly into 5G baseband silicon, enabling automotive OEMs and smartphone manufacturers to eliminate discrete eUICC components entirely. This integration is collapsing hardware bill-of-materials differentiation and shifting value capture toward subscription management platform operators.
ETSI's consumer eUICC architecture specifications are tightening interoperability requirements across European telecommunications markets. The standards body is mandating standardized profile formats and remote provisioning interfaces, forcing subscription management providers to compete on service reliability rather than proprietary lock-in. German automotive OEMs and French mobile network operators are most affected, accelerating migration from M2M-specific implementations toward unified consumer-grade architectures.
Carrier procurement of eUICC-enabled devices is compressing traditional distribution channels. Mobile network operators in the United States and China are specifying embedded connectivity requirements in original equipment manufacturer supply agreements, bypassing traditional SIM card distributors and negotiating directly with semiconductor vendors. This disintermediation is most visible in connected vehicle supply chains, where BMW, Mercedes-Benz, and Ford are sourcing eUICC functionality through tier-one electronics suppliers rather than telecommunications intermediaries.
Embedded Universal Integrated Circuit Card (eUICC) Market Segmentation
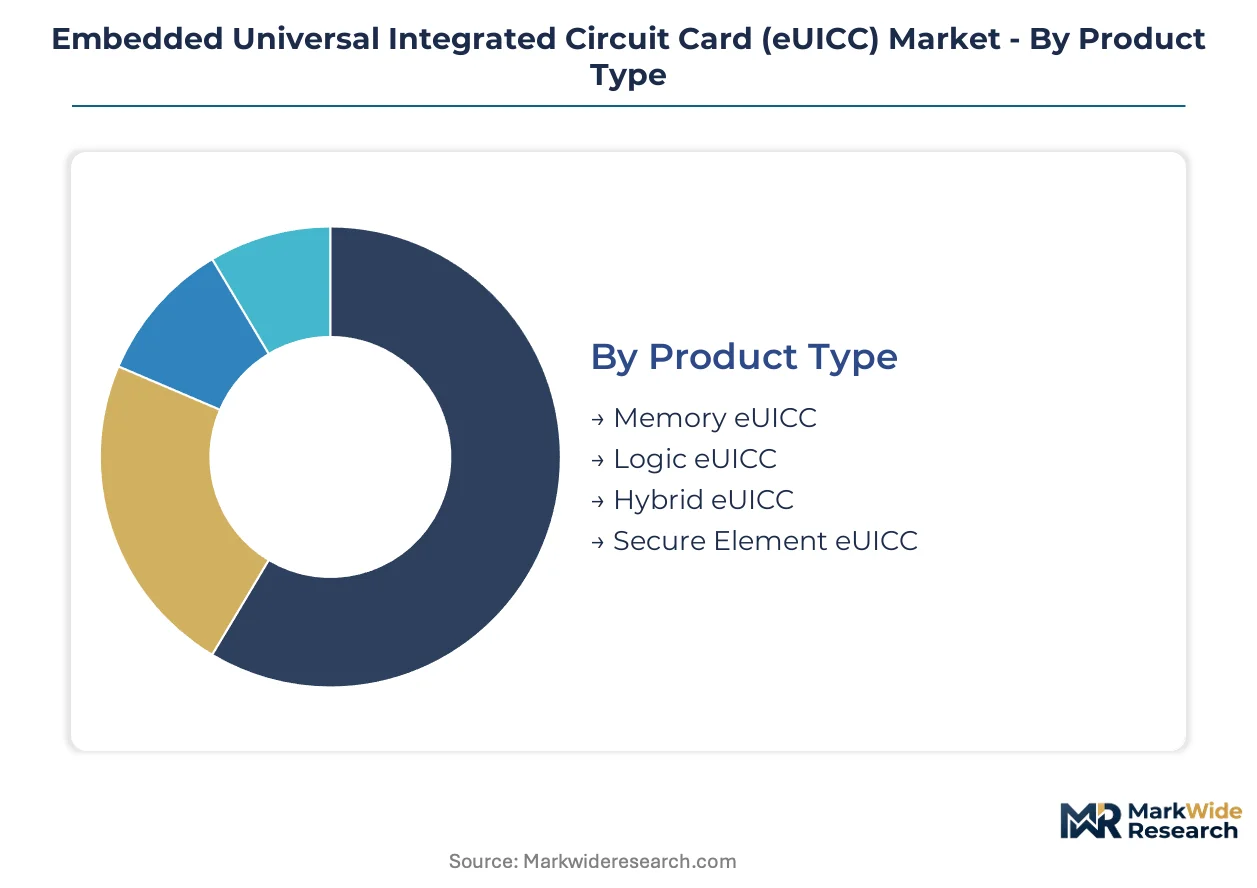
eUICC procurement cycles vary dramatically across segments, with automotive platforms demanding 7-10 year supply commitments while consumer electronics refresh annually. Understanding these velocity differentials shapes inventory strategy and certification roadmaps for secure element vendors.
Product Type:
Automotive qualification cycles stretch 18-24 months, compressing to 6-9 months for consumer-grade variants. Memory eUICC and Logic eUICC command the longest design-in timelines due to telematics integration requirements.
- Memory eUICC:Stores limited operator profiles with minimal processing capability, optimized for cost-constrained IoT endpoints. German automotive OEMs specify this variant for basic telematics in entry vehicle segments where firmware update frequency remains low. ETSI M2M specifications govern its remote provisioning protocols.
- Logic eUICC:Incorporates dedicated cryptographic processors enabling secure authentication and key management. Connected vehicle platforms in the United States deploy this architecture for over-the-air software updates requiring hardware-backed integrity verification. Common Criteria EAL4+ certification is mandatory for automotive procurement.
- Hybrid eUICC:Combines memory density with programmable logic for mid-tier industrial applications. Manufacturing companies in China favor this balance for smart factory deployments.
- Secure Element eUICC:Highest-assurance variant with tamper-resistant silicon and side-channel attack countermeasures. Financial services and government applications specify this grade.
Memory eUICC dominates installed base. Logic eUICC is where expansion concentrates.
Technology:
Cost structures stratify sharply between subscription management platforms and physical secure element implementations. OTA Provisioning and Remote SIM Provisioning capture disproportionate platform licensing value.
- OTA Provisioning:Enables encrypted profile delivery over cellular networks without physical device interaction. Telecommunications operators in Germany leverage this for industrial IoT fleet management where field technician visits are cost-prohibitive. GSMA SAS-UP accreditation governs server infrastructure.
- Remote SIM Provisioning:GSMA-standardized architecture separating subscription management from device manufacturing. Automotive OEMs in the United States mandate this for software-defined vehicle programs requiring carrier-agnostic connectivity. Profile interoperability across MNOs is the critical procurement criterion.
- Profile Management:Lifecycle services enabling activation, suspension, and deletion of operator credentials. Utility providers rely on this for smart metering estate transitions between network operators.
- Embedded SIM Architecture:Physical integration specifications defining electrical interfaces and form factors. Device manufacturers in China optimize designs around MIIT encryption requirements.
Remote SIM Provisioning anchors platform revenue. OTA Provisioning is climbing the fastest as industrial IoT scales.
Application:
Volume concentration diverges between high-unit consumer markets and high-value automotive platforms. Smart Metering and Connected Vehicles sit at opposite ends of the margin spectrum.
- Connected Vehicles:Embedded connectivity mandatory for emergency calling regulations and autonomous data pipelines. OEMs in Germany and the United States source eUICC through tier-one electronics suppliers rather than telecommunications intermediaries. NHTSA and EU eCall mandates are structural demand drivers.
- Smart Metering:Cost-optimized deployments for utility infrastructure where device lifecycles exceed 15 years. European utilities specify Memory eUICC variants with minimal profile switching capability. Regulatory pressure for remote meter reading accelerates replacement cycles.
- Consumer Electronics:Smartphones and tablets driving highest unit volumes with shortest replacement cycles. Qualcomm integration into cellular basebands is collapsing discrete component demand.
- Industrial Automation:Manufacturing equipment requiring reliable connectivity across global facility footprints. Predictive maintenance applications favor Logic eUICC architectures.
- Wearable Devices:Space-constrained designs where iSIM integration is displacing discrete secure elements. Health monitoring applications in the United States specify FDA-aligned security requirements.
Consumer Electronics dominates unit shipments. Connected Vehicles is gaining share fastest on per-device value.
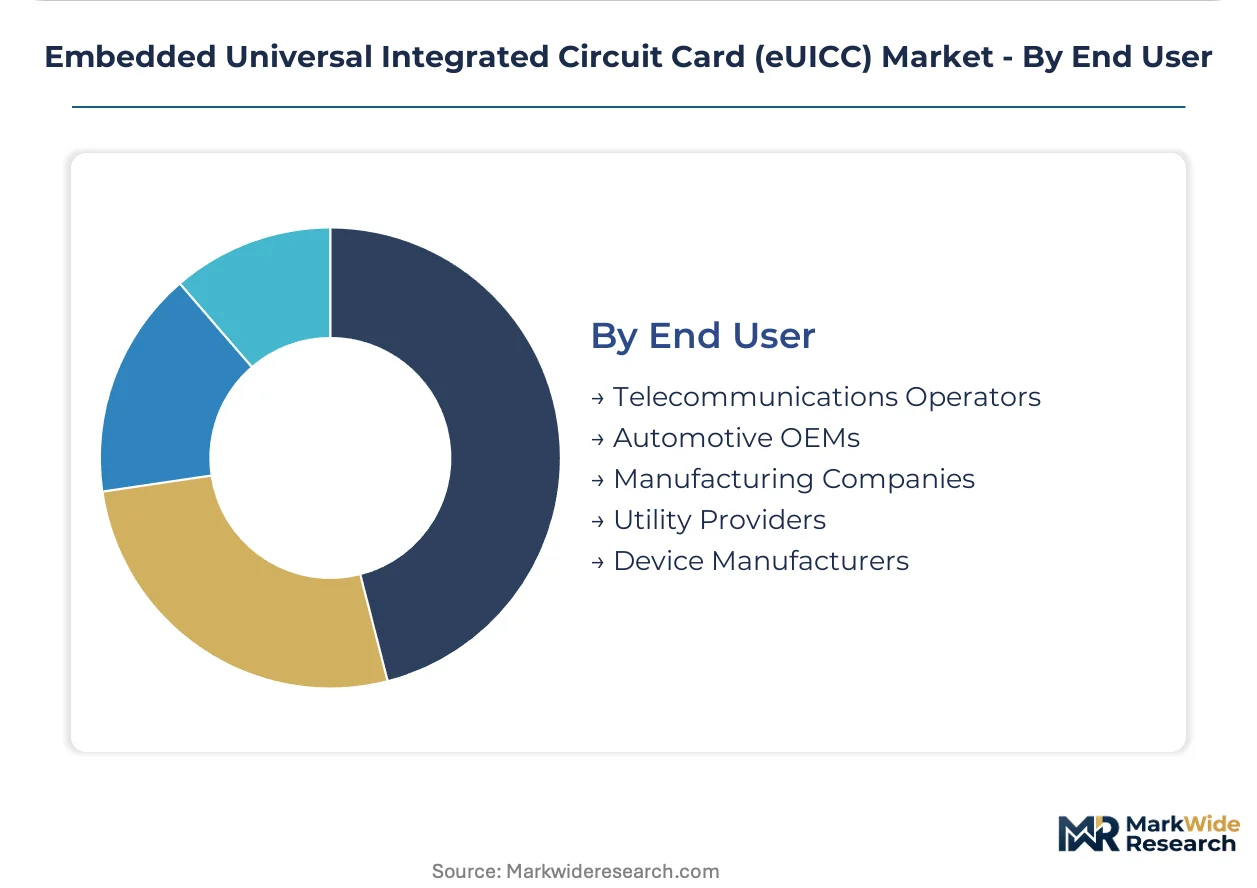
End User:
Procurement authority is shifting from telecommunications intermediaries toward device manufacturers and automotive OEMs. Automotive OEMs and Device Manufacturers now control specification standards.
- Automotive OEMs:Direct semiconductor negotiations bypassing traditional SIM distribution. Mercedes-Benz, BMW, and Ford specify eUICC requirements in tier-one supplier contracts. Software-defined vehicle architectures mandate embedded connectivity.
- Device Manufacturers:Apple, Samsung, and Xiaomi integrating eUICC into product design cycles. Baseband processor integration is collapsing discrete secure element procurement for premium tiers.
- Telecommunications Operators:AT&T, Verizon, and Deutsche Telekom operating subscription management platforms. Revenue is tilting from hardware distribution toward recurring profile services.
- Utility Providers:Centrica, E.ON, and State Grid deploying smart metering at national scale. Procurement favors lowest total cost of ownership over technical sophistication.
- Manufacturing Companies:Siemens, Bosch, and Foxconn specifying industrial IoT connectivity. Predictive maintenance and asset tracking drive specification requirements.
Telecommunications Operators dominate legacy revenue. Automotive OEMs is where specification authority concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, the United States, and China consume eUICC technology through fundamentally different procurement lenses: automotive OEMs in Germany prioritize Common Criteria certification depth, US carriers emphasize subscription management platform control, and Chinese manufacturers optimize around domestic encryption mandates.
United States
FCC equipment authorization rules intersect with carrier-specific network access requirements, creating layered compliance obligations for device manufacturers. NHTSA mandates embedded connectivity for emergency calling regulations, accelerating automotive eUICC specification. Detroit-based OEMs source secure elements through tier-one electronics suppliers rather than traditional telecommunications intermediaries.
Germany
KBA vehicle type approval processes enforce rigorous security evaluation timelines for connected car platforms. The EU Cybersecurity Act mandates Common Criteria EAL4+ certification for secure elements deployed across industrial IoT and automotive applications. Stuttgart and Munich anchor automotive OEM procurement concentration, with Mercedes-Benz and BMW specifying eUICC requirements directly in supplier contracts.
China
MIIT enforces domestic encryption standards that influence secure element designs for products entering the domestic market. The country's dual carbon goals accelerate smart metering deployment at national scale. Shenzhen and Shanghai manufacturing clusters optimize eUICC production for both domestic consumption and export markets, though cryptographic variants fragment hardware economies of scale.
South Korea
MFDS-aligned security requirements shape medical device connectivity specifications where eUICC enables remote patient monitoring. Samsung Electronics and Hyundai Motor Group drive demand through consumer electronics and automotive platforms respectively. Seoul Capital Area semiconductor foundries provide certified Common Criteria fabrication capacity serving regional secure element demand.
India
TRAI regulations on embedded SIM provisioning are harmonizing with GSMA standards to accelerate carrier adoption. The PLI scheme for semiconductor assembly and testing attracts eUICC packaging investments to serve domestic telecommunications and emerging automotive demand. Karnataka and Telangana electronics manufacturing clusters host expanding secure element testing and integration facilities.
Embedded Universal Integrated Circuit Card (eUICC) Market Competitive Landscape
Capability concentration sits with semiconductor specialists possessing certified Common Criteria fabrication access; scale advantage sits with platform operators commanding subscription management infrastructure. The market structures around three tiers: secure element foundries with EAL4+ certification, subscription management platform providers with GSMA SAS-UP accreditation, and integrated modem vendors collapsing discrete component functions. Dominant competitive moves include strategic partnerships between automotive OEMs and semiconductor vendors, plus geographic expansion of certified fabrication capacity to reduce supply concentration risk.
Within the secure element tier, Giesecke+Devrient and Thales occupy positions defined by deep European telecommunications operator relationships and advanced remote SIM provisioning architectures. Qualcomm exemplifies the integration vector, embedding tamper-resistant enclaves directly into cellular baseband silicon to eliminate discrete eUICC procurement for premium-tier device manufacturers.
| Leading Market Players |
|---|
| Giesecke+Devrient |
| Thales |
| STMicroelectronics |
| Infineon Technologies |
| IDEMIA |
| NXP Semiconductors |
| Qualcomm |
| Kigen |
| Deutsche Telekom |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor carries secure element wafers and packaged eUICC components, with freight cost volatility amplifying procurement premiums for automotive OEMs while compressing margins on high-volume IoT contracts. This logistics tension reinforces pricing stratification between Common Criteria-certified automotive tiers and cost-optimized consumer variants.
Pricing Analysis
Long-term offtake agreements dominate automotive procurement, with Mercedes-Benz and BMW locking 7-10 year supply commitments for EAL4+-certified Logic eUICC variants. Price differentiation rests on certification grade and volume scale, with spot-market Memory eUICC facing downward pressure from Chinese packaging competition. Automotive OEMs exhibit lowest price sensitivity due to regulatory mandates, while European utilities drive hardest bargaining on smart metering tenders.
Supply Chain Analysis
Contract manufacturing concentrates at STMicroelectronics and Infineon foundries in Germany, Samsung's Seoul-area facilities, and SMIC-certified lines serving China's domestic market. Silicon wafer supply draws from TSMC's specialty nodes, while OSAT capacity in Malaysia and Vietnam handles backend packaging. Single-source vulnerability clusters at Common Criteria-certified semiconductor fabs, with distribution running through tier-one electronics suppliers rather than traditional SIM distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The eUICC market sits at a platform-economics inflection where GSMA SAS-UP interoperability standards are collapsing proprietary subscription management moats and redistributing value toward integrated modem vendors.
For Market Incumbents: Build switching-cost moats through embedded subscription management platform integration. Thales and Giesecke+Devrient should deepen GSMA SAS-UP accreditation breadth to defend against Qualcomm's iSIM displacement threat. Secure Common Criteria EAL4+ certification pipeline capacity in India to offset German foundry concentration risk. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-supported semiconductor packaging segment where TRAI-GSMA harmonization is accelerating carrier adoption. Target industrial IoT fleet management platforms in Germany where remote SIM provisioning complexity creates service-layer entry points. Lead with OTA provisioning specialization rather than secure element fabrication. For Investors and Strategic Acquirers: Carve-out targets emerge from telecommunications operators spinning off subscription management infrastructure as standalone platform businesses. Long-term viability favors integrated iSIM architectures over discrete component vendors. Watch for NHTSA emergency calling mandate expansion as inflection signal for automotive eUICC specification authority.| Strategic Initiative | Industry Significance |
|---|---|
| GSMA SAS-UP Platform Accreditation | Enables Thales to capture recurring profile-management revenue from Deutsche Telekom. |
| India PLI Semiconductor Packaging Investment | Positions Giesecke+Devrient to serve TRAI-aligned domestic telecommunications demand. |
| iSIM Baseband Integration | Allows Qualcomm to eliminate discrete eUICC procurement for Samsung smartphone tiers. |
| Automotive Tier-One Direct Sourcing | Bypasses traditional SIM distribution channels for BMW connected vehicle programs. |
| Common Criteria EAL4+ Certification Expansion | Accelerates Infineon access to KBA-mandated German automotive secure element procurement. |
Research Methodology
A spread of perspectives from semiconductor procurement directors at automotive OEMs, GSMA accreditation auditors, telecommunications operator platform engineers, and secure element foundry operations managers converged on the working assumptions. Primary interview insights were cross-validated against ETSI specification documents, GSMA SAS-UP accreditation registries, FCC equipment authorization filings, and MIIT encryption standard notices. Bottom-up unit demand modeling from connected vehicle production pipelines and smart metering deployment schedules was reconciled with top-down secure element wafer supply estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeled by product type (Memory, Logic, Hybrid, Secure Element), application (Connected Vehicles, Smart Metering, Consumer Electronics, Industrial Automation), and end user procurement authority (Automotive OEMs, Device Manufacturers, Telecommunications Operators). CAGRs were derived from installed base turnover rates and replacement cycle compression in automotive platforms. Forecast inputs incorporated NHTSA emergency calling mandate timelines and EU Cybersecurity Act certification rollout pace.
Sensitivities concentrate around Common Criteria EAL4+ evaluation timeline delays, MIIT encryption standard fragmentation effects on hardware economies of scale, and iSIM integration pace in premium smartphone tiers. Forecasts reflect these structural assumptions without incorporating speculative regulatory acceleration. Quarterly review of automotive OEM eUICC specification releases and GSMA SAS-UP accreditation expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.