
 Standard Logic IC Market | 2026-2036
Standard Logic IC Market Size, Share, and Industry Trends Forecast 2026-2036
Standard Logic IC Market Analytics
Automotive OEMs is unwinding the traditional dominance of consumer electronics buyers in standard logic IC procurement. Texas Instruments leverages its broad catalog of automotive-qualified logic families to sustain design-win momentum across powertrain and body electronics. STMicroelectronics anchors its position through integrated manufacturing in European and Asian fabs, competing on delivery reliability for industrial automation customers. NXP Semiconductors differentiates by specializing in AEC-Q100 certified buffers and translators that occupy critical signal-path roles in EV architectures.
Standard Logic ICs are combinational and sequential digital circuits fabricated on silicon wafers using CMOS or BiCMOS processes, with operating voltages typically spanning 1.65V to 5.5V and propagation delays measured in nanoseconds; they perform Boolean operations, data storage, and signal routing in electronic systems. Logic gates and flip-flops dominate unit shipments due to their ubiquity in board-level designs, while decoders and multiplexers command margin premiums in telecommunications base stations where channel density requirements intensify. CMOS technology leads volume production for its power efficiency, though BiCMOS variants gain traction in automotive signal conditioning where mixed-signal performance matters.
EPA automotive emissions standards and NHTSA functional safety mandates in the United States compel logic IC suppliers to validate parts across wider temperature ranges and longer operational lifetimes. ECHA REACH restrictions on lead and halogenated substances reshape material choices for packaging and substrate finishes, raising compliance costs for non-European suppliers. ISO 26262 functional safety frameworks extend into industrial automation, forcing semiconductor vendors to document failure modes and diagnostic coverage. Stakeholders must monitor how China's dual carbon goals and GB standards for electronic components reshape domestic sourcing rules and import substitution timelines.
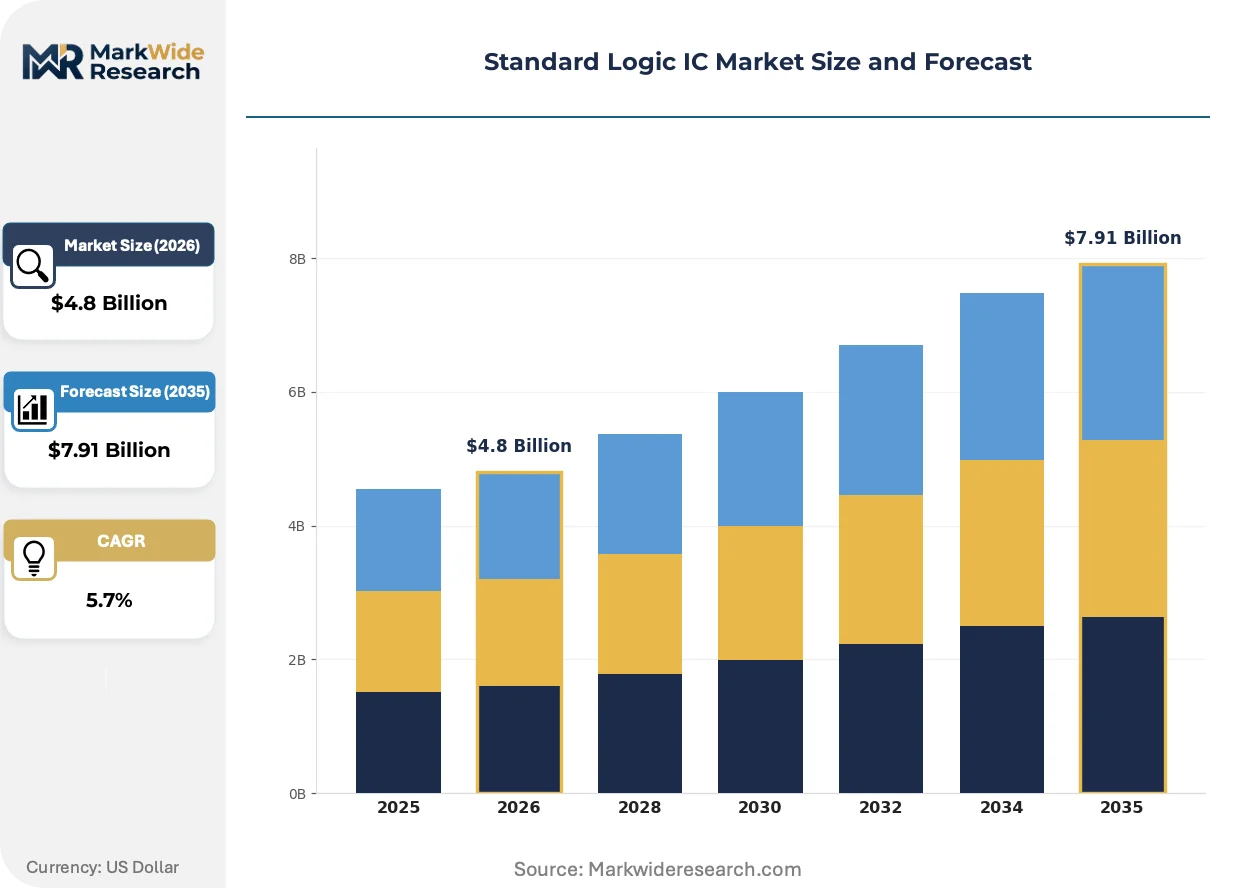
Market Dynamics
Automotive electrification is compressing design cycles and forcing logic IC suppliers to requalify portfolios for AEC-Q100 Grade 0 temperature ranges, shifting procurement power toward tier-1 powertrain integrators who now specify signal-conditioning buffers at the board-architecture stage.
Growth Catalysts
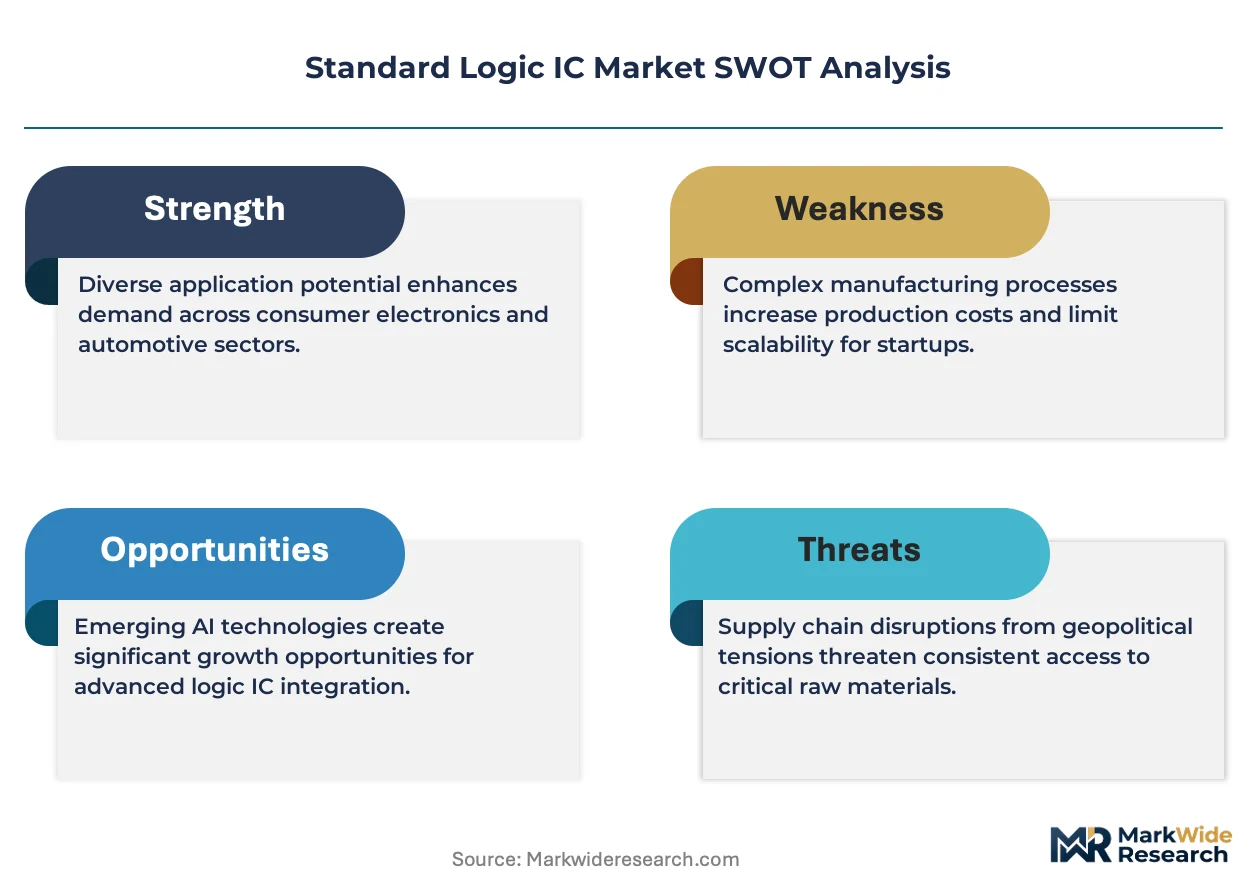
- EPA automotive emissions standards:Powertrain control modules require expanded logic IC content for real-time sensor processing, pulling CMOS buffers into engine management units across US vehicle platforms.
- China's dual carbon goals:Domestic EV producers are building captive inventories of standard logic devices to insulate against import volatility, concentrating demand in Shenzhen and Shanghai manufacturing clusters.
- BiCMOS process advancement:Mixed-signal performance requirements in automotive signal conditioning are accelerating foundry investment in BiCMOS capacity for voltage translation and level-shifting applications.
Market Restraints
- Substrate material concentration:Lead-free packaging transitions mandated by ECHA REACH restrictions have concentrated qualified laminate suppliers in Taiwan and South Korea, creating input cost volatility for European foundries.
- Legacy node capacity scarcity:Standard logic ICs rely on 180nm-350nm mature processes where foundry investment has stagnated, constraining volume elasticity during demand spikes from industrial automation customers.
- Functional safety documentation burden:ISO 26262 compliance requires extensive failure-mode analysis that extends qualification timelines, particularly for sequential logic devices in safety-critical EV architectures.
Strategic Opportunities
- India's PLI scheme for electronics:Component manufacturing incentives are attracting logic IC packaging investments to Gujarat and Tamil Nadu, creating a new supply node for industrial automation exporters.
- Telecommunications base station densification:Channel density requirements in 5G infrastructure are creating margin premiums for high-speed multiplexers and decoders in European and Japanese equipment markets.
- EU Green Deal material mandates:Halogen-free substrate requirements are accelerating development of novel molding compounds that command price premiums in medical and aerospace qualification tiers.
Industry Challenges
- Mixed-signal design talent scarcity:BiCMOS process expertise has atrophied at engineering schools, forcing semiconductor vendors to retrain digital-focused teams for analog-intensive automotive signal-path roles.
- Multi-standard certification stacking:Simultaneous AEC-Q100, ISO 26262, and IEC 61508 validations for industrial-automation crossover parts are compressing engineering bandwidth and extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Standard Logic IC Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Logic Gates, Flip-Flops, Decoders, Multiplexers Technology: CMOS, BiCMOS, TTL, ECL End User: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Application: Data Processing, Signal Conditioning, Control Systems, Communication |
| Companies Covered | Texas Instruments, STMicroelectronics, Renesas Electronics, NXP Semiconductors, ON Semiconductor, Broadcom, Analog Devices, Toshiba Electronic Devices & Storage Corporation, Diodes Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Standard Logic IC Market Evolving Landscape
Silicon integration architectures are converging with packaging miniaturization to redefine power-performance tradeoffs, while regulatory material bans and procurement centralization reshape how logic ICs reach end-equipment manufacturers.
Advanced fan-out wafer-level packaging is miniaturizing standard logic die footprints while preserving thermal dissipation for automotive under-hood placement. Tier-1 powertrain suppliers in Germany and Japan are adopting these formats for transmission control modules. The technology is compressing board-area requirements and enabling multi-die integration of buffers with voltage regulators.
REACH Annex XVII restrictions on lead and halogenated flame retardants are forcing substrate material substitutions across European-bound production. Foundries in Malaysia and the Philippines are qualifying novel epoxy molding compounds to maintain CE marking eligibility. Automotive-qualified parts face the steepest reformulation costs due to thermal cycling reliability requirements.
Consolidated procurement desks at Chinese smartphone OEMs and EV producers are displacing fragmented distributor relationships with direct foundry contracts and volume-commitment frameworks. Authorized distributors in the Asia-Pacific region are responding by adding value-in-design services and buffer inventory financing. The shift is most visible in Shenzhen, where domestic brands now specify logic families at the reference-design stage.
Standard Logic IC Market Segmentation
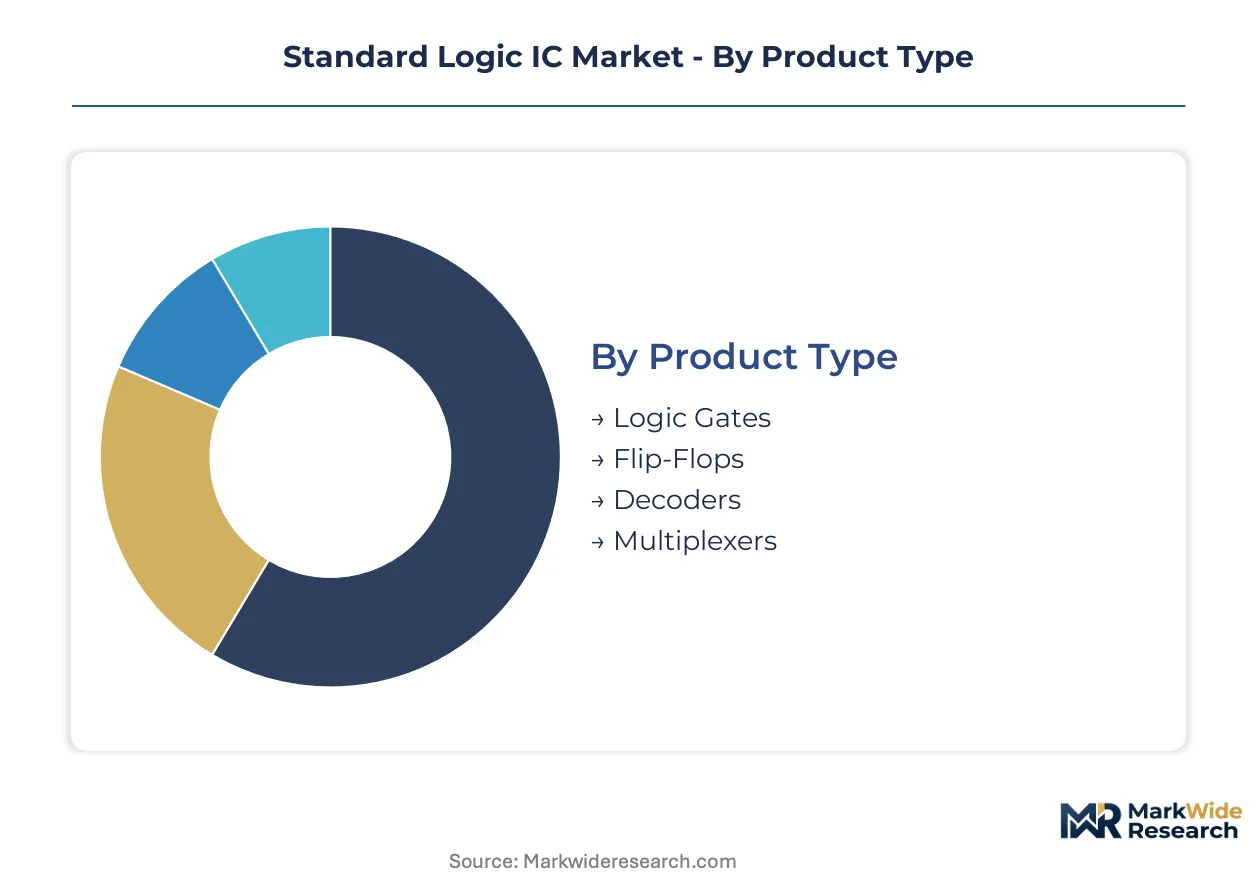
Segmentation in standard logic ICs reveals how regulatory frameworks and performance requirements fragment procurement patterns across end-equipment categories. Understanding these divisions exposes where margin premiums concentrate and where volume commoditization pressures dominate supplier economics.
Product Type:
ECHA REACH substance restrictions and AEC-Q100 thermal cycling specifications are bifurcating qualification requirements between commodity logic families and automotive-grade variants.
- Logic Gates:AND, OR, NAND, and NOR gates perform Boolean operations in digital circuit designs. Consumer electronics OEMs in Shenzhen and Shanghai absorb the majority of unit volume for smartphones and tablets, though automotive powertrain modules are pulling CMOS variants into Grade 0 temperature specifications.
- Flip-Flops:Sequential storage elements capture and hold digital states across clock cycles. Industrial automation controllers in Germany and Japan specify D-type and JK flip-flops for deterministic timing in safety-certified PLCs, with ISO 26262 documentation extending qualification timelines.
- Decoders:Address translation and data routing functions in telecommunications infrastructure.
- Multiplexers:Channel selection devices commanding margin premiums in 5G base station deployments.
Logic Gates handles the majority of throughput; Multiplexers is the fastest mover on share.
Technology:
Cost tier differentiation separates power-efficient mainstream production from premium mixed-signal variants serving automotive signal-path requirements.
- CMOS:Complementary metal-oxide-semiconductor fabrication dominates volume production through sub-micron feature geometries and negligible static power draw. Foundries in Taiwan and South Korea concentrate 180nm-350nm mature node capacity for consumer and industrial applications, though legacy investment stagnation constrains elasticity during demand spikes.
- BiCMOS:Bipolar-CMOS integration combines high-speed bipolar transistors with CMOS density for analog-digital interfaces. Voltage translation and level-shifting applications in EV architectures are accelerating foundry investment, with NXP and STMicroelectronics competing on AEC-Q100 certified buffers for transmission control modules.
- TTL:Transistor-transistor logic legacy families maintained for backward compatibility in industrial equipment.
- ECL:Emitter-coupled logic for ultra-high-speed telecommunications switching where power dissipation is secondary.
CMOS carries the volume base; BiCMOS is climbing the fastest as automotive electrification intensifies.
End User:
Customer type concentration is displacing fragmented procurement relationships with direct foundry contracts and volume-commitment frameworks.
- Consumer Electronics:Smartphones, tablets, wearables, and personal computing equipment. Domestic Chinese OEMs are building captive inventories to insulate against import volatility, consolidating procurement desks in Shenzhen manufacturing clusters and specifying logic families at reference-design stages.
- Automotive:Powertrain control, body electronics, and infotainment systems. EPA emissions standards and NHTSA functional safety mandates compel validation across wider temperature ranges, shifting procurement power toward tier-1 integrators who specify signal-conditioning buffers at board-architecture stages.
- Industrial Automation:PLCs, robotics, and process control equipment requiring IEC 61508 certification.
- Telecommunications:Base stations, routers, and network infrastructure demanding channel density.
Consumer Electronics anchors absolute volume; Automotive is gaining share fastest as electrification compresses design cycles.
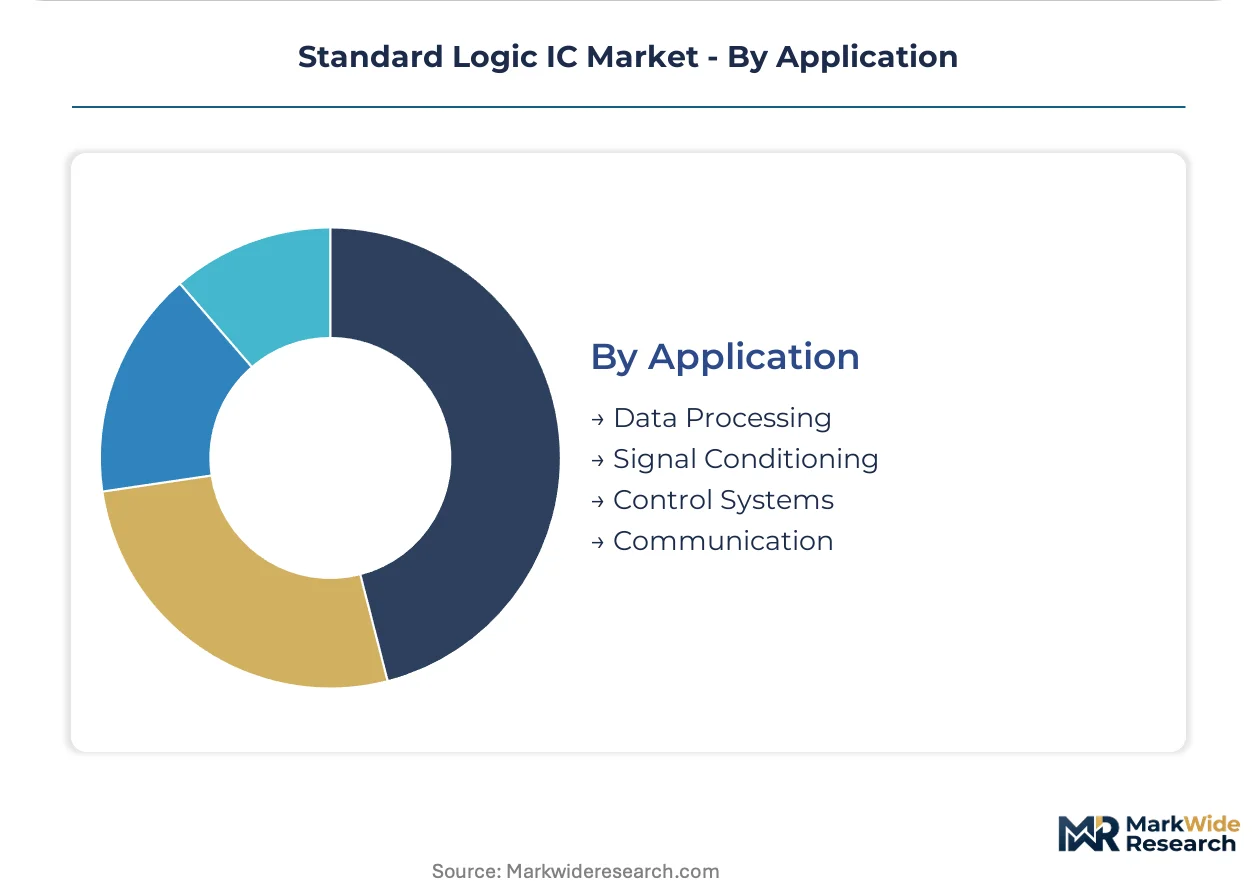
Application:
Supply concentration in mature process nodes directly shapes which functional applications face capacity constraints during demand surges.
- Data Processing:Arithmetic operations, register files, and computational logic in digital systems. Cloud infrastructure expansion in Virginia and Frankfurt data centers is pulling CMOS gates into server motherboard designs, though margin compression limits supplier enthusiasm relative to automotive opportunities.
- Signal Conditioning:Voltage translation, level shifting, and noise filtering at interface boundaries. Mixed-signal performance requirements in EV battery management systems are accelerating BiCMOS adoption, with Texas Instruments leveraging automotive-qualified families for design-win momentum.
- Control Systems:Feedback loops and state machines in industrial and automotive equipment.
- Communication:Protocol interfacing and data serialization in networked equipment.
Data Processing commands the widest deployment footprint; Signal Conditioning shows the steepest expansion trajectory as vehicle electrification intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electrification and consumer electronics procurement desks are concentrating demand in manufacturing clusters across five countries. Tier-1 powertrain integrators and domestic smartphone OEMs now specify logic families at the board-architecture stage, shifting supply relationships toward direct foundry contracts.
United States
EPA automotive emissions standards and NHTSA functional safety mandates are pulling CMOS buffers into engine management units across Detroit and Austin vehicle platforms. Virginia and Frankfurt data centers are expanding cloud infrastructure that absorbs logic gates for server motherboard designs. Tier-1 automotive suppliers in Michigan specify signal-conditioning buffers during early board-architecture stages.
China
Domestic EV producers and smartphone OEMs are building captive inventories to insulate against import volatility under the country's dual carbon goals. GB standards for electronic components are reshaping domestic sourcing rules across Shenzhen and Shanghai manufacturing clusters. Consolidated procurement desks now specify logic families at the reference-design stage.
Germany
ECHA REACH restrictions on lead and halogenated substances are forcing substrate material substitutions for CE marking eligibility. Industrial automation controllers in Bavaria and Baden-Württemberg specify D-type flip-flops for safety-certified PLCs under ISO 26262 documentation requirements. Tier-1 powertrain suppliers are adopting fan-out wafer-level packaging for transmission control modules.
Japan
METI industrial policy is reinforcing domestic semiconductor supply chains for automotive and telecommunications equipment. Kansai and Chubu manufacturing belts are qualifying AEC-Q100 certified buffers for EV battery management systems. Base station densification for 5G infrastructure is creating margin premiums for high-speed multiplexers in Tokyo and Osaka equipment markets.
South Korea
Lead-free packaging transitions have concentrated qualified laminate suppliers in Seoul and Gyeonggi manufacturing corridors, creating input cost volatility for European foundries. Foundries are maintaining 180nm-350nm mature node capacity for consumer and industrial logic IC production. BiCMOS process investment is accelerating for voltage translation applications in automotive signal conditioning.
Standard Logic IC Market Competitive Landscape
Player mix skews toward integrated device manufacturers with captive fabrication and broad catalog coverage. Market structure exhibits moderate consolidation around semiconductor conglomerates with automotive qualification expertise. Three archetypes dominate: diversified analog-logic hybrids, automotive-specialized fabricators, and industrial-focused suppliers with safety certification depth. Competitive moves center on AEC-Q100 portfolio requalification and strategic partnerships with tier-1 powertrain integrators.
Among diversified analog-logic hybrids, Texas Instruments and ON Semiconductor exemplify the scale-driven archetype with broad automotive-qualified families. STMicroelectronics anchors the European integrated manufacturing position through multi-site fabrication in France and Italy. NXP Semiconductors occupies the automotive-specialized tier with AEC-Q100 certified signal-path components. These three represent distinct competitive vectors: catalog breadth, geographic manufacturing diversification, and functional safety certification depth.
| Leading Market Players |
|---|
| Texas Instruments |
| STMicroelectronics |
| Renesas Electronics |
| NXP Semiconductors |
| ON Semiconductor |
| Broadcom |
| Analog Devices |
| Toshiba Electronic Devices & Storage Corporation |
| Diodes Incorporated |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements with volume-commitment frameworks lock in both foundry capacity access and price visibility for tier-1 automotive integrators sourcing AEC-Q100 certified buffers from Taiwan and South Korea. These contracts insulate procurement desks at German and Japanese powertrain suppliers against spot-market volatility in 180nm-350nm mature node capacity.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate procurement relationships for standard logic ICs, linking final unit prices to raw material input movements. Three-tier pricing structure across automotive-grade, industrial-certified, and consumer-economy levels reflects AEC-Q100 qualification costs and ISO 26262 documentation burdens. Pricing pressure stems from legacy node capacity scarcity as foundry investment stagnation constrains volume elasticity during demand spikes. Consumer electronics OEMs in Shenzhen exhibit highest price sensitivity, while automotive tier-1s accept premiums for guaranteed supply continuity.
Supply Chain Analysis
Strategic stockpiling preferences among Chinese EV producers and smartphone OEMs are displacing just-in-time norms as dual carbon goals and import volatility fears concentrate inventory holdings in Shenzhen and Shanghai. Supply concentrates in Taiwan, South Korea, and Malaysia, with qualified laminate suppliers for lead-free packaging drawing from concentrated epoxy molding compound sources. Single-source vulnerability in mature process node equipment creates structural risk for volume expansion. Distribution runs through authorized distributors adding value-in-design services, though direct foundry contracts are displacing fragmented channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BiCMOS process expertise scarcity at engineering schools and atrophied analog design capabilities are constraining supplier response to automotive signal-path requirements, creating competitive advantage for vendors with retraining infrastructure and mixed-signal talent pipelines.
For Market Incumbents: Consolidate AEC-Q100 portfolio requalification momentum by locking in multi-year supply agreements with tier-1 powertrain integrators in Germany and Japan. Deepen backward integration into substrate material supply as ECHA REACH restrictions concentrate qualified laminate sources in Taiwan and South Korea, threatening margin stability for non-integrated competitors.
For New Entrants and Emerging Players: Lead with India's PLI scheme for electronics manufacturing incentives as a white-space entry point, targeting packaging investments in Gujarat and Tamil Nadu for industrial automation export markets. Penetrate telecommunications base station densification opportunities in Europe and Japan where channel density requirements for 5G infrastructure create margin premiums for high-speed multiplexers. Pursue value-in-design distributor partnerships rather than direct foundry competition.
For Investors and Strategic Acquirers: Automotive-specialized fabricators with AEC-Q100 certified buffers and established tier-1 relationships represent the priority acquisition archetype for exposure to EV electrification tailwinds. Long-term viability hinges on sustained BiCMOS capacity investment and functional safety certification depth. Watch for inflection when China's GB standards for electronic components accelerate import substitution timelines beyond current captive inventory building.
| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Portfolio Requalification | Texas Instruments and NXP leverage automotive certification to secure design wins in Detroit powertrain platforms. |
| BiCMOS Foundry Capacity Expansion | Mixed-signal process investment addresses voltage translation demand in EV battery management systems. |
| Lead-Free Packaging Transition | Malaysian and Philippine foundries qualify novel epoxy compounds to maintain ECHA REACH compliance. |
| Direct Foundry Contracting | Shenzhen smartphone OEMs displace distributor relationships with volume-commitment frameworks. |
| Fan-Out Wafer-Level Packaging Adoption | German tier-1 suppliers compress board area for transmission control module miniaturization. |
Research Methodology
Desk research of SEC semiconductor filings, ECHA substance restriction databases, and vehicle production data preceded structured interviews with tier-1 automotive procurement managers, foundry operations directors, and industrial automation OEM engineers. Primary fieldwork combined with secondary validation across customs records, AEC-Q100 qualification registries, and foundry capacity announcements. Bottom-up segment sizing and top-down market reconciliation ensured cross-verification of volume and value estimates.
Variance-decomposition across product type, technology node, end-user vertical, and application function shaped the analytical framework over the projection horizon. Modeled dimensions included logic gate families versus sequential elements, CMOS versus BiCMOS process splits, and automotive versus consumer electronics demand concentrations. CAGRs derived from historical shipment trajectories and foundry capacity expansion announcements, with automotive electrification intensity and telecommunications infrastructure capex cycles as primary forecast inputs.
Forecasts assume regulatory continuity in EPA automotive emissions standards and ECHA REACH substance restrictions; material policy shifts would require re-modeling of qualification timelines and material substitution costs. Revision becomes warranted when China's GB standards implementation crosses thresholds that accelerate domestic sourcing mandates beyond current captive inventory strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Application Specific Analog IC Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Energy Metering IC Chip Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
Digital Audio IC Market
IC (Integrated Circuits)
Global Application Specific Automotive Analog IC Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
Lithium Battery Charger Ics Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market
IC (Integrated Circuits)
Touch Controller IC Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Rugged IC Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market