
 Discrete Capacitors Market | 2026-2036
Discrete Capacitors Market Size, Share, and Industry Trends Forecast 2026-2036
Discrete Capacitors Market Intelligence
REACH compliance is repositioning the cost-of-entry calculus for European-bound capacitor shipments, forcing reformulation of electrolyte chemistries and expanded documentation. Murata Manufacturing leverages its ceramic powder vertical integration to sustain margin pools amid rising raw material volatility. Samsung Electro-Mechanics anchors high-volume supply to Korean smartphone OEMs, while TDK Corporation dominates automotive-grade film capacitor certification through its power electronics specialization.
Discrete capacitors store electrical energy in a dielectric medium between conductive plates, with capacitance values spanning picofarads to thousands of microfarads depending on dielectric material and plate geometry. These passive components filter noise, stabilize voltage rails, and manage energy transients across switching circuits in power converters, RF front-ends, and motor drives. Ceramic capacitors lead volume shipment due to MLCC miniaturization for 5G handsets and automotive ECUs, while film capacitors capture premium positioning in EV inverter DC-link applications where temperature cycling endurance matters. Tantalum capacitors occupy niche medical and aerospace slots despite supply concentration risks, whereas aluminum electrolytic variants retain cost-driven industrial equipment sockets.
EU REACH and RoHS frameworks restrict hazardous substances in dielectric formulations and mandate supply chain transparency, compelling reformulation of electrolytic capacitor chemistries. China's GB standards and MIIT energy efficiency directives enforce minimum performance thresholds for power conversion components, filtering subscale domestic producers. Japan's METI circular economy guidelines pressure OEMs toward design-for-recovery in consumer electronics assemblies. Stakeholders must monitor evolving automotive functional safety certifications and raw material provenance requirements as qualification timelines extend.
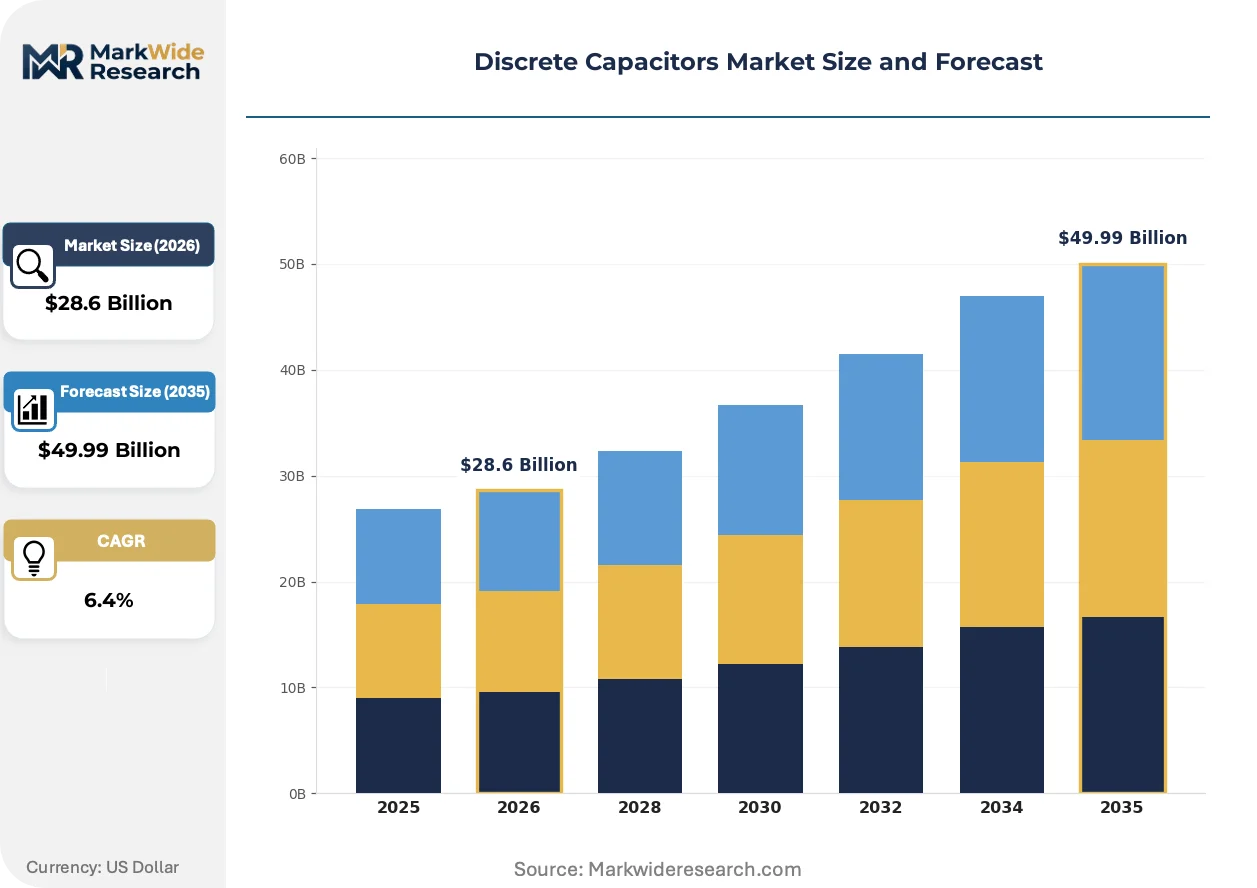
Market Dynamics
Powertrain electrification is compressing capacitor qualification timelines while fragmenting dielectric material sourcing across ceramic, film, and aluminum electrolytic chemistries. Automotive functional safety mandates from ISO 26262 now gate supplier entry before volume commitments materialize.
Growth Catalysts
- EV Inverter DC-Link Expansion:Film capacitor demand is accelerating in traction inverter modules as OEMs prioritize temperature cycling endurance over unit cost in high-voltage architectures.
- China MIIT Efficiency Mandates:Minimum performance thresholds for power conversion components are filtering subscale domestic producers and concentrating procurement among qualified tier-one suppliers.
- 5G Base Station Deployment:MLCC miniaturization requirements for massive MIMO arrays are pulling high-capacitance ceramic formulations into telecom infrastructure at scale.
Market Restraints
- Palladium and Nickel Volatility:Precious metal electrode costs in multilayer ceramic capacitors are compressing margin pools for non-integrated fabricators without captive powder supply.
- Tantalum Ore Concentration:Central African mining concentration creates single-source dependency risks for aerospace and medical-grade tantalum capacitor supply chains.
- REACH Documentation Burden:ECHA substance-of-very-high-concern declarations are extending European-bound shipment lead times by forcing electrolyte chemistry reformulation and expanded supply chain transparency.
Strategic Opportunities
- India PLI Scheme Alignment:Electronics manufacturing incentive structures are attracting capacitor module assembly investments to serve domestic smartphone and automotive OEM demand.
- Solid-State Battery Interface Development:Next-generation energy storage architectures require specialized DC-link capacitors with enhanced ripple current handling and reduced equivalent series resistance.
- Direct OEM Contracting Models:Bypassing traditional distribution channels through vendor-managed inventory programs is capturing margin previously absorbed by tier-two electronics distributors.
Industry Challenges
- Automotive Functional Safety Certification:ISO 26262 ASIL-D qualification timelines extending 18-24 months are delaying revenue recognition for new supplier entrants.
- Dielectric Powder Synthesis Expertise Gap:Scarce ceramic formulation chemists and thin-film deposition engineers are constraining R&D throughput for next-generation high-voltage formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Discrete Capacitors Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic, Aluminum Electrolytic, Tantalum, Film Application: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Equipment End User: Manufacturers, OEMs, Repair Services, Electronics Assemblers Technology: Surface Mount, Through-Hole, Power Film, Flexible Film |
| Companies Covered | Murata Manufacturing Co., Ltd., Samsung Electro-Mechanics, TDK Corporation, KEMET Corporation, Vishay Intertechnology, Kyocera Corporation, Taiyo Yuden Co., Ltd., Panasonic Corporation, AVX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Discrete Capacitors Market Strategic Shifts & Innovations
Material science breakthroughs and procurement model compression are simultaneously reshaping capacitor performance benchmarks and supplier-commercial relationships. Three developments merit particular attention.
Nanocomposite dielectric formulations incorporating barium titanate derivatives are consolidating high-voltage ceramic capacitor architectures. EV power electronics teams at Korean and German OEMs are adopting these chemistries for 800V traction inverters. The technology is consolidating what previously required parallel capacitor banks into single-package solutions, reducing board space and assembly cost.
EU F-Gas Regulation phase-down schedules are restricting fluorinated greenhouse gases in capacitor manufacturing processes. Industrial equipment producers are reformulating impregnation chemistries for film capacitors to maintain dielectric strength without prohibited substances. German and Italian motor drive manufacturers face the steepest compliance curves given their reliance on legacy oil-impregnated designs.
Consolidated procurement through tier-one electronics manufacturing services is displacing fragmented distributor relationships. Foxconn and Jabil are negotiating direct volume commitments with Murata and TDK, extracting price concessions in exchange for demand visibility. This concentration is most visible in Taiwanese and Vietnamese contract manufacturing corridors serving North American smartphone OEMs.
Discrete Capacitors Market Segmentation
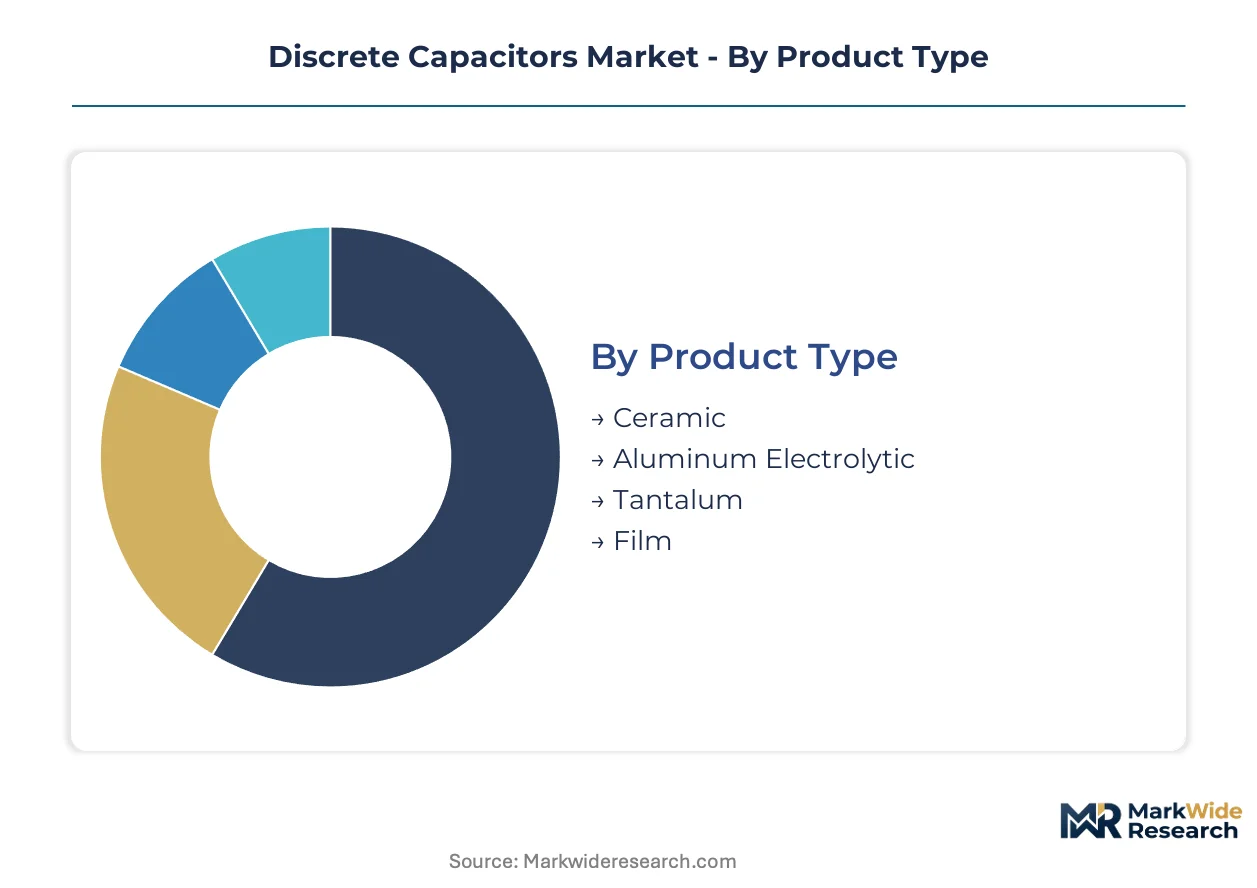
Discrete capacitor segmentation reveals how dielectric material choices and mounting technologies concentrate margin pools across divergent supply chain configurations. Understanding these splits exposes where procurement leverage accumulates and where technical moats protect pricing power.
Product Type:
Supply concentration in ceramic powder synthesis and electrode metallization creates divergent margin structures across dielectric families, with captive material control separating profitable tiers from commodity exposure.
- Ceramic:Multilayer ceramic chip capacitors dominate volume through barium titanate formulations miniaturized for 5G handsets and automotive ECUs. Demand concentrates in East Asian manufacturing clusters serving Korean smartphone OEMs and Japanese automotive tier-ones, with palladium electrode costs compressing margins for non-integrated fabricators.
- Film:Polypropylene and polyester dielectric layers deliver temperature cycling endurance for EV inverter DC-link applications where unit cost matters less than reliability under thermal stress. Procurement is tightening around German and Korean powertrain suppliers qualifying 800V architectures.
- Aluminum Electrolytic:Etched aluminum foil and liquid electrolyte chemistries retain industrial equipment sockets where cost-driven filtering dominates specification.
- Tantalum:Manganese dioxide and polymer cathode variants occupy medical and aerospace niches despite Central African ore concentration risks.
Today's leader: Ceramic. Tomorrow's challenger: Film.
Application:
End-use qualification timelines fragment the competitive landscape, with automotive functional safety mandates gating supplier entry before volume commitments materialize.
- Automotive Electronics:Traction inverters, onboard chargers, and DC-DC converters demand AEC-Q200 qualification and ISO 26262 ASIL-D certification. Korean and German OEMs are compressing supplier lists to tier-ones with proven high-voltage track records.
- Consumer Electronics:Smartphones, laptops, and wearables drive MLCC miniaturization toward 008004 case sizes. Foxconn and Jabil are consolidating procurement through direct volume commitments with Japanese and Korean capacitor majors.
- Telecommunications:Massive MIMO base stations pull high-capacitance ceramic formulations into telecom infrastructure at scale.
- Industrial Equipment:Motor drives and power supplies retain aluminum electrolytic dominance where cost thresholds override performance premiums.
Automotive commands the steepest expansion trajectory. Consumer electronics maintains volume leadership.
End User:
Procurement model compression is displacing fragmented distributor relationships, with vendor-managed inventory programs capturing margin previously absorbed by intermediaries.
- OEMs:Direct contracting with Murata, TDK, and Samsung Electro-Mechanics extracts price concessions in exchange for demand visibility. Taiwanese and Vietnamese contract manufacturing corridors serving North American smartphone OEMs exhibit the most pronounced concentration.
- Manufacturers:Captive production for internal consumption shapes procurement in vertically integrated electronics conglomerates.
- Electronics Assemblers:EMS providers face margin pressure as tier-one OEMs bypass traditional channels.
- Repair Services:Aftermarket replacement demand fragments across unauthorized distributors and component brokers.
OEM direct contracting dominates value capture. Repair services remain structurally fragmented.
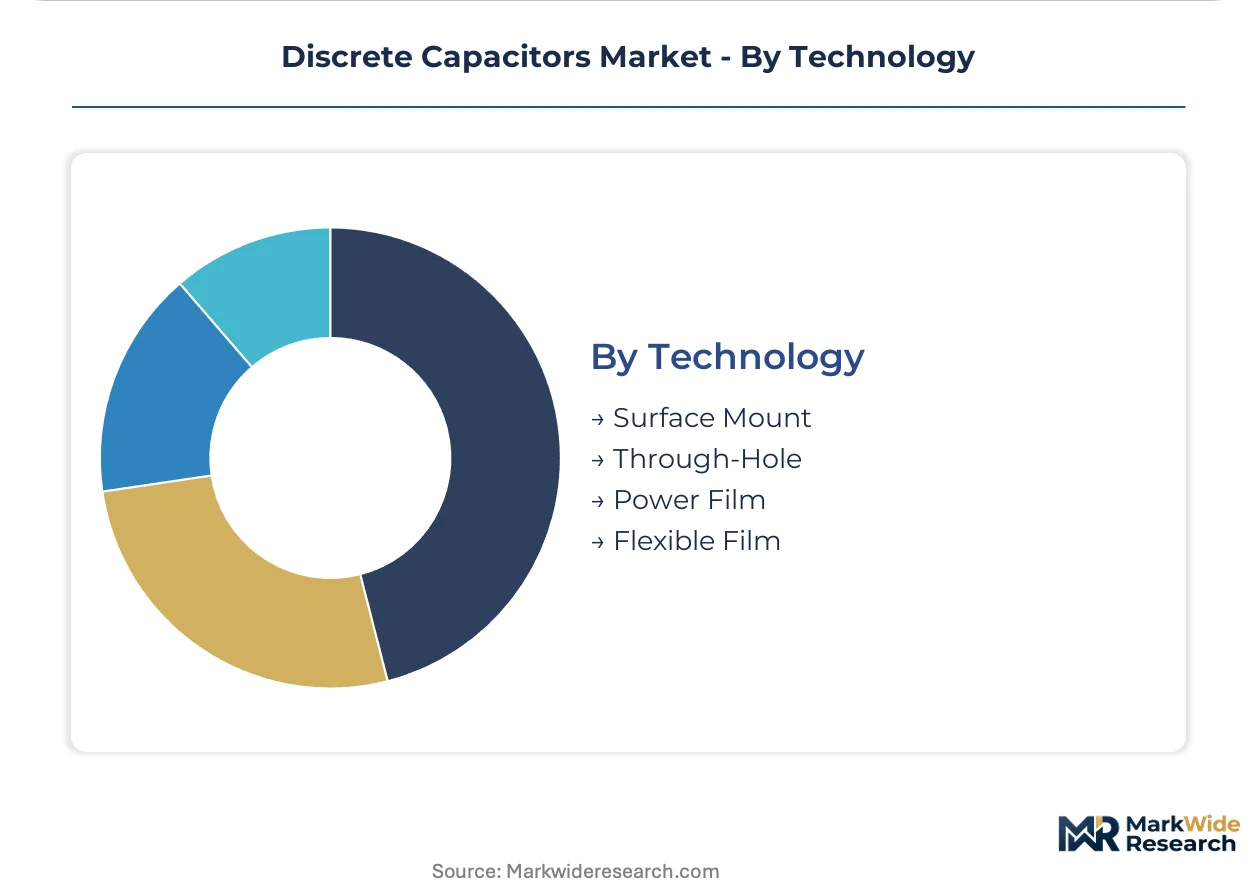
Technology:
Mounting technology selection tracks board density requirements and thermal management constraints, with surface mount architectures consolidating volume as through-hole retention narrows to high-voltage industrial applications.
- Surface Mount:MLCC and chip tantalum formats enable automated assembly at miniaturized pitch densities. 5G handset and automotive ECU demand is accelerating adoption of 0201 and smaller case sizes.
- Power Film:Segmented metallization patterns and self-healing dielectric properties address EV inverter ripple current handling requirements.
- Through-Hole:Radial and axial leaded formats retain industrial and legacy equipment sockets where manual rework capability outweighs density optimization.
- Flexible Film:Polymer substrate integration enables conformal mounting in wearable and medical device form factors.
Surface mount holds volume dominance. Power film is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Materials scientists and thin-film deposition engineers concentrate in East Asian manufacturing corridors, anchoring global capacitor production networks. Their expertise clusters around ceramic powder synthesis facilities and semiconductor packaging hubs. This talent distribution shapes regional competitive advantages.
China
MIIT efficiency mandates filter subscale domestic producers while concentrating procurement among qualified tier-one suppliers. GB standards enforce minimum performance thresholds for power conversion components. The Yangtze River Delta manufacturing belt hosts capacitor module assembly serving domestic EV and smartphone OEMs.
Japan
METI circular economy guidelines pressure OEMs toward design-for-recovery in consumer electronics assemblies. JIS standards govern dielectric material specifications and qualification protocols. The Kansai region's materials science belt sustains ceramic powder vertical integration and high-voltage formulation R&D.
South Korea
Korean smartphone OEMs compress supplier lists to tier-ones with proven high-voltage track records. MFDS oversees medical-grade component standards affecting tantalum capacitor specifications. The Seoul Capital Area semiconductor packaging corridor anchors high-volume MLCC supply chains.
Germany
ECHA substance-of-very-high-concern declarations extend European-bound shipment lead times through electrolyte chemistry reformulation. EU F-Gas Regulation phase-down schedules restrict fluorinated greenhouse gases in manufacturing processes. Bavaria's automotive tier-one cluster drives AEC-Q200 and ISO 26262 ASIL-D qualification demand.
United States
FAA and NHTSA safety frameworks influence aerospace and automotive capacitor certification requirements. EPA oversight intersects with REACH-aligned documentation for European export compliance. The Pacific Northwest electronics corridor concentrates RF front-end and 5G infrastructure component demand.
Discrete Capacitors Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. The vendor base separates into three archetypes: integrated material-captive fabricators controlling ceramic powder supply, scale-driven assemblers serving high-volume consumer electronics, and certification-heavy specialists targeting automotive functional safety sockets. Dominant competitive moves include backward integration into dielectric raw materials and direct OEM contracting that bypasses traditional distribution channels.
Within the integrated material-captive tier, Murata Manufacturing Co., Ltd. exemplifies vertical control over ceramic powder synthesis. Samsung Electro-Mechanics and TDK Corporation occupy positions bridging scale-driven consumer electronics supply and automotive-grade certification requirements. These three anchors represent divergent strategic postures: captive raw material security, high-volume manufacturing leverage, and power electronics specialization respectively.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| Samsung Electro-Mechanics |
| TDK Corporation |
| KEMET Corporation |
| Vishay Intertechnology |
| Kyocera Corporation |
| Taiyo Yuden Co., Ltd. |
| Panasonic Corporation |
| AVX Corporation |
| Others |
Cost & Logistics Intelligence
Ceramic formulation chemists and thin-film deposition engineers concentrate in Japan's Kansai region and South Korea's Seoul Capital Area, anchoring labor-cost differentials that stretch pricing-tier spreads between captive-material fabricators and commodity assemblers. These technical workforce clusters enable premium pricing for high-voltage formulations while cost-driven industrial segments face margin compression from non-integrated competitors.
Pricing Analysis
Component-plus-certification bundling separates automotive-grade AEC-Q200 qualified supply from unbundled industrial commodity transactions. Three-tier pricing structure across automotive-certified, industrial-standard, and economy-grade levels tracks ISO 26262 ASIL-D investment recovery and palladium electrode cost pass-through. Cost compression in consumer electronics MLCC tiers is intensifying because Foxconn and Jabil extract volume concessions through direct contracting. Smartphone OEMs exhibit highest price sensitivity; German automotive tier-ones prioritize reliability premiums over unit cost.
Supply Chain Analysis
Returns and end-of-life recovery flows remain underdeveloped for ceramic and film capacitor streams despite Japan's METI circular economy guidelines pressuring design-for-recovery protocols. Manufacturing concentrates in Japan, South Korea, and China, with the Yangtze River Delta hosting module assembly for domestic EV demand. Raw material flows draw from Central African tantalum ore deposits, Japanese barium titanate powder synthesis, and Korean palladium electrode supply. Single-source vulnerability in tantalum ore concentration threatens aerospace and medical-grade supply security. Distribution runs through consolidated EMS direct procurement and fragmented industrial distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The discrete capacitors market represents a late-cycle quality story as EV powertrain electrification shifts procurement criteria from cost-per-unit toward temperature cycling endurance and functional safety certification. This specification premium rewards suppliers with proven high-voltage track records and captive material control.
For Market Incumbents: Extend automotive certification coverage into 800V traction inverter architectures before Korean and German OEMs finalize supplier lists. Deepen backward integration into barium titanate powder synthesis to offset palladium electrode volatility. Lock in vendor-managed inventory programs with Foxconn and Jabil to defend channel position against distributor disintermediation. For New Entrants and Emerging Players: Solid-state battery interface capacitor development offers a technology-first wedge into next-generation energy storage architectures. Target India's PLI scheme corridor for module assembly investments serving domestic smartphone and automotive OEM demand. Pursue direct OEM contracting models that bypass tier-two electronics distributors and capture margin previously absorbed by intermediaries. For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated fabricators without captive ceramic powder supply, though these assets carry palladium cost exposure. Five-to-ten year viability hinges on automotive functional safety certification density and high-voltage formulation R&D throughput. Monitor ISO 26262 ASIL-D qualification timeline compression as an inflection indicator for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Synthesis | Murata Manufacturing sustains margin pools through captive barium titanate supply control. |
| Automotive Functional Safety Certification Investment | TDK Corporation captures EV inverter DC-link demand via ISO 26262 ASIL-D qualification leadership. |
| Direct OEM Contracting Model Expansion | Samsung Electro-Mechanics extracts price concessions from Korean smartphone OEMs through demand visibility exchange. |
| India PLI Scheme Manufacturing Footprint | Module assembly investments serve domestic automotive and consumer electronics procurement localization. |
| Nanocomposite Dielectric Formulation Development | German and Korean OEMs consolidate parallel capacitor banks into single-package 800V solutions. |
Research Approach
Bottom-up automotive and consumer electronics demand modeling reconciled against top-down ceramic powder production and capacitor shipment tracking forms the analytical core. Primary interviews with capacitor procurement managers at German and Korean automotive tier-ones, MLCC sourcing leads at Taiwanese EMS providers, and ceramic formulation R&D directors at Japanese materials suppliers combined with secondary validation from MIIT efficiency directive filings, ECHA REACH substance declarations, and AEC-Q200 qualification databases.
Input-output matrices map dielectric material flows through electrode metallization, thin-film deposition, and final packaging stages across the projection horizon. Segmentation dimensions include dielectric family, mounting technology, end-use application, and regional manufacturing cluster. CAGRs derive from installed base growth in EV traction inverters, 5G massive MIMO deployment, and smartphone unit volume trajectories, cross-referenced against capacitor content-per-unit assumptions and supplier capacity expansion announcements.
The model holds under stable palladium and nickel price regimes; deviation in precious metal electrode cost volatility or Central African tantalum supply disruption would shift margin pool distribution between integrated and non-integrated fabricators. Practitioners should monitor ECHA substance-of-very-high-concern declaration timelines and MIIT energy efficiency threshold adjustments for early signals of qualification burden expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Americas MPU Market
Electronic Components
North America USB Retimer Market
Electronic Components
Chip Shield Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
North America Touch Screen Controllers Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
North America MLCC Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
Cordless Phone Battery Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
GPIO Expanders Market
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
Video Surveillance Chip Market
Electronic Components
Microcontroller Socket Market
Electronic Components
Stretchable Conductors in Electronics Market
Electronic Components
Handheld Devices Battery Market