
 Fuel Pump Driver Module Market | 2026-2036
Fuel Pump Driver Module Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Pump Driver Module Market Analytics
East Asian semiconductor foundry capacity is broadening substrate availability for fuel pump driver module manufacturers. Bosch leverages in-house ASIC design to sustain module integration across European OEM platforms. Denso anchors production scale through captive supply of power management components in Japan. Continental competes on smart control firmware that extends diagnostic capability into hybrid drivetrain architectures.
A fuel pump driver module is an electromechanical control unit that regulates voltage delivery to in-tank or inline fuel pumps, typically operating between 12V and 48V systems with pulse width modulation frequencies up to 20 kHz to maintain precise fuel rail pressure across varying engine loads. Its primary purpose is to optimize pump speed, reduce electrical noise, and extend component life while meeting evaporative emissions standards. Electronic modules with pulse width modulation technology dominate OEM fitment due to superior efficiency and emissions compliance, while relay-based systems occupy the price-sensitive aftermarket tier. Smart control segments are gaining fastest as automakers integrate fuel delivery with engine management CAN networks.
NHTSA fuel system integrity standards and EPA evaporative emissions regulations in the United States shape product validation requirements and testing protocols for module durability and electromagnetic compatibility. The EU Green Deal and REACH substance restrictions in Europe constrain material selection for housings and potting compounds, pushing suppliers toward halogen-free thermoplastics. Stakeholders must monitor how OEM electrification roadmaps alter fuel system architecture decisions across hybrid and range-extended vehicle programs.
Market Dynamics
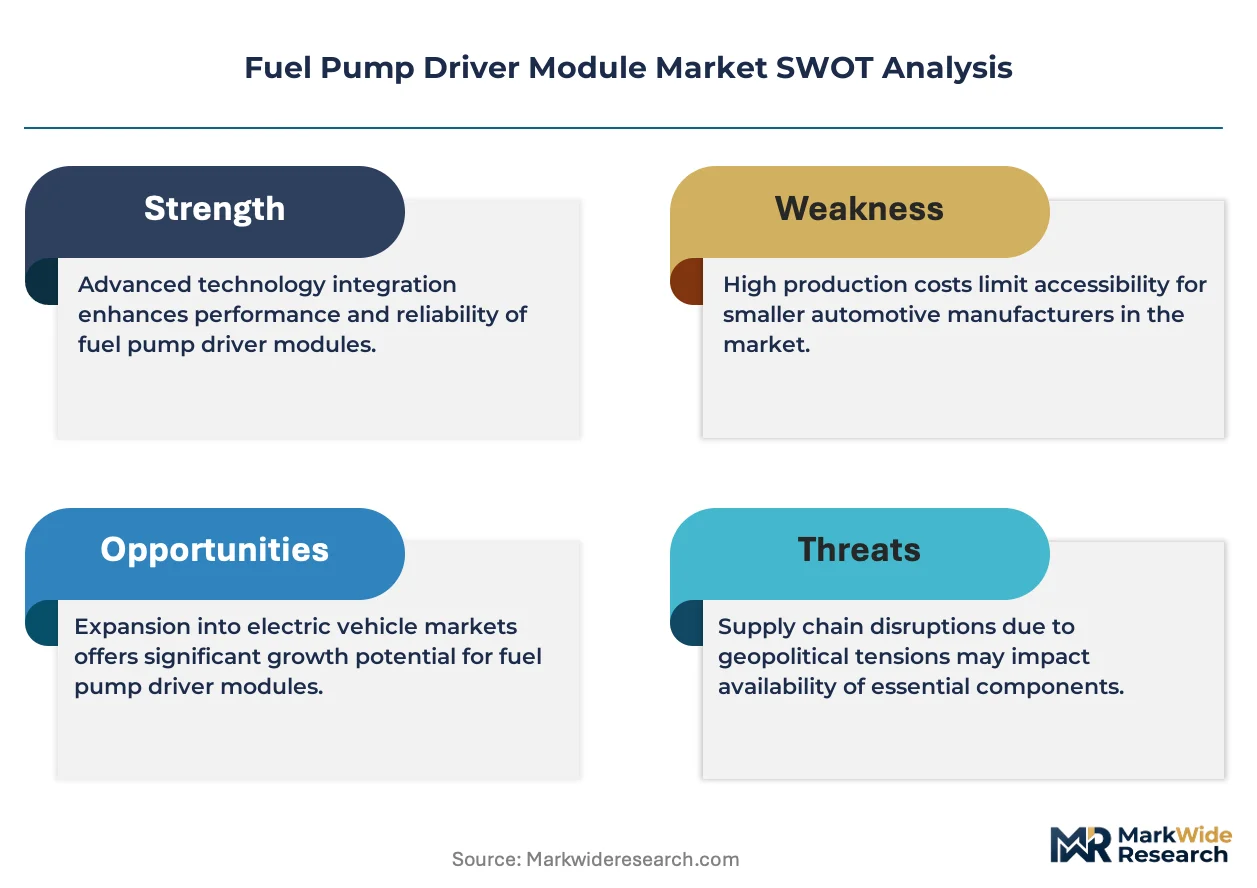
Passenger vehicle electrification programs are compressing the addressable market for conventional fuel pump driver modules while simultaneously elevating technical requirements for hybrid architectures. This structural tension between declining pure-ICE volumes and rising hybrid complexity defines supplier strategy.
Growth Catalysts
- EU Green Deal compliance:German OEM electrification mandates are accelerating 48V mild-hybrid deployments that require advanced pulse width modulation control for dual-fuel architectures.
- East Asian semiconductor substrate expansion:Foundry capacity additions in Taiwan and South Korea are improving component availability for module manufacturers serving tier-one automotive suppliers.
- China MIIT fuel efficiency standards:Domestic OEM procurement is concentrating on electronic modules with smart diagnostic capability to meet tightening corporate average fuel consumption targets.
Market Restraints
- Silicon carbide substrate cost volatility:Power semiconductor wafer pricing fluctuations are compressing gross margins for module suppliers dependent on external foundry relationships.
- Supply concentration in East Asian packaging:Leadframe and substrate assembly capacity clustering in Malaysia and Vietnam creates geographic risk exposure for European and North American module vendors.
- REACH substance restrictions:ECHA limitations on halogenated flame retardants are forcing housing material reformulations that extend qualification timelines by 12-18 months.
Strategic Opportunities
- India BIS automotive electronics localization:PLI scheme incentives for domestic manufacturing are opening captive supply opportunities for module assembly serving Maruti Suzuki and Tata Motors platforms.
- Range-extended electric vehicle architectures:Series-hybrid programs from BMW and Mazda are creating demand for high-voltage fuel pump control systems with integrated thermal management.
- CAN network integration convergence:Smart control firmware combining fuel delivery with engine management diagnostics is enabling subscription-based predictive maintenance revenue streams.
Industry Challenges
- Embedded systems firmware talent scarcity:Shortage of automotive-qualified software engineers with functional safety expertise is extending development cycles for ISO 26262-compliant modules.
- Electromagnetic compatibility certification complexity:NHTSA and EPA combined validation requirements for fuel system integrity and evaporative emissions are creating multi-jurisdiction testing bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Pump Driver Module Market |
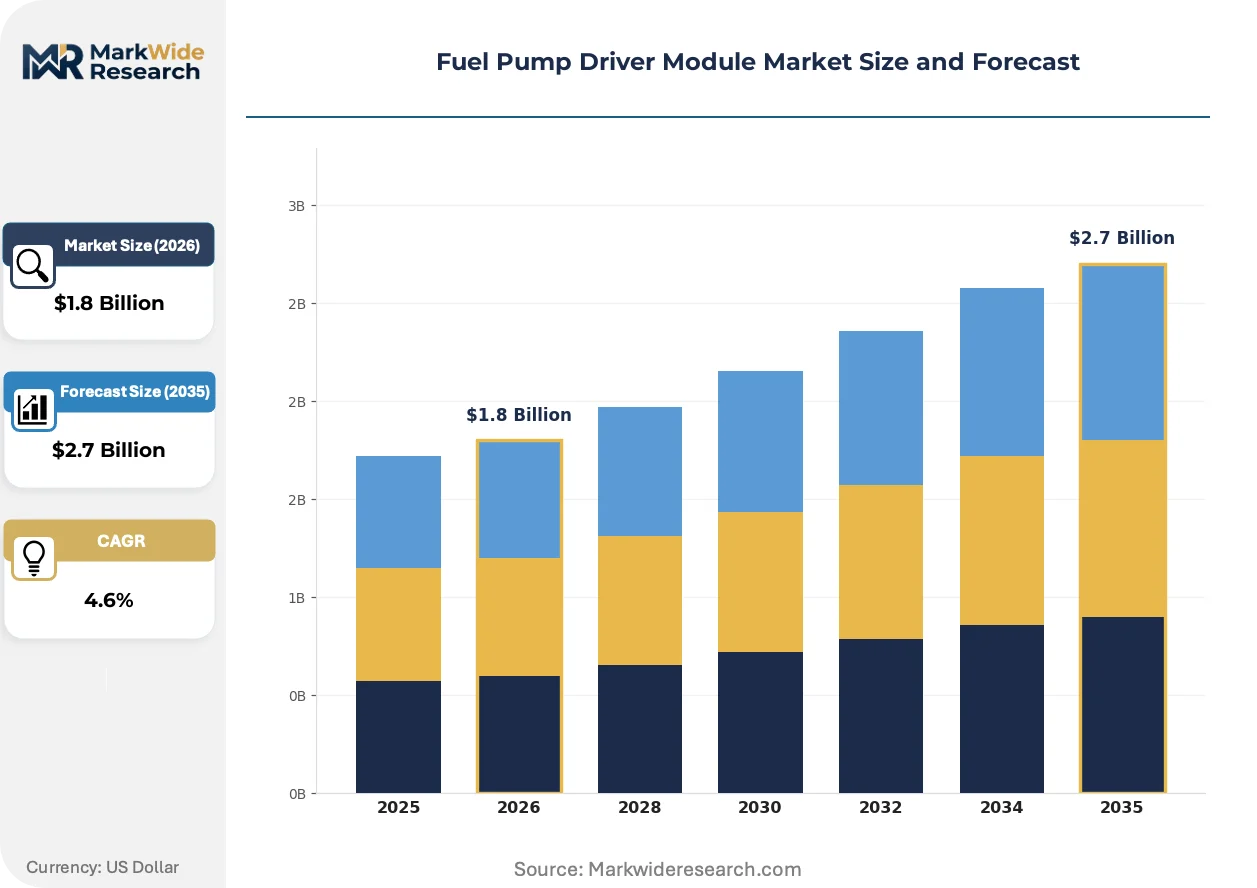
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electronic, Hybrid, Integrated Technology: Pulse Width Modulation, Constant Voltage, Relay-Based, Smart Control Application: Automotive, Aerospace, Marine, Industrial End User: OEMs, Aftermarket Providers, Distributors, Repair Shops |
| Companies Covered | Denso, Bosch, Continental, Aptiv (Delphi Technologies), Hitachi Astemo, TI Fluid Systems, Marelli, Aisan Industry, Magna, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Pump Driver Module Market Evolving Landscape
Electrification roadmaps are fragmenting fuel system architectures across parallel development tracks for full hybrid, plug-in hybrid, and range-extended platforms. Module suppliers must engineer for voltage scalability and network interoperability simultaneously.
Gallium nitride power semiconductors are consolidating switching efficiency advantages in next-generation driver modules. Tier-one suppliers are adopting these wide-bandgap devices for 48V systems to reduce switching losses and thermal management overhead. This transition is consolidating procurement around foundry partners with GaN epitaxy capability.
EPA evaporative emissions enforcement is tightening validation protocols for fuel system integrity across hybrid operating modes. Module firmware must now demonstrate leak detection capability during extended electric-only operation periods. California Air Resources Board zero-emission vehicle credits are pressuring OEMs to minimize fuel system vapor generation during hot-soak conditions.
Fleet procurement contracts are unbundling fuel pump driver modules from traditional engine management system bundles. Commercial vehicle operators in North America are sourcing replacement modules through direct distribution channels rather than OEM captive parts networks. This channel shift is most pronounced in Class 4-7 medium-duty truck segments where aftermarket service independence carries operational value.
Fuel Pump Driver Module Market Segmentation
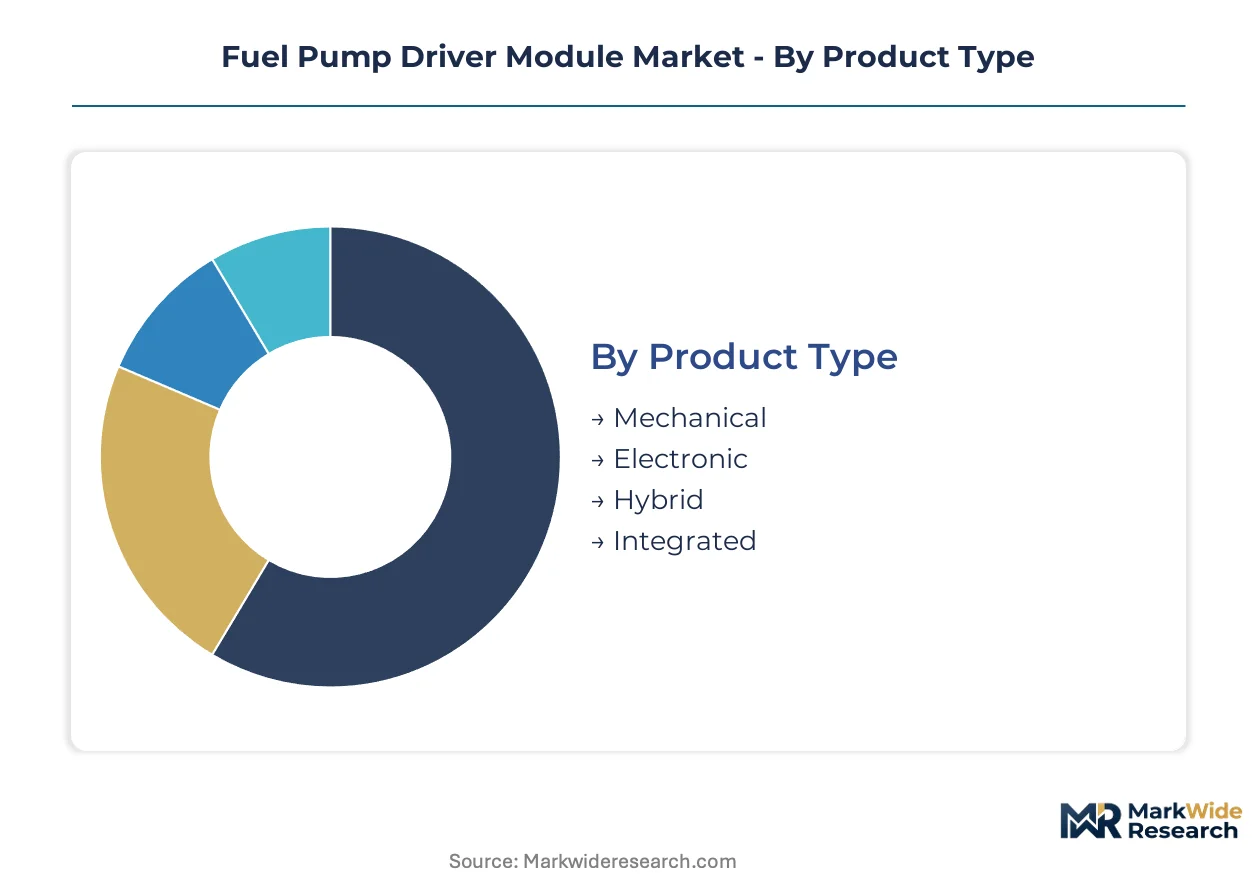
Fuel pump driver module segmentation reflects competing pressures from electrification mandates, semiconductor availability, and channel restructuring. Suppliers engineer across voltage classes and control architectures to capture hybrid platform procurement while defending aftermarket positions.
Product Type:
Voltage regulation architecture and integration depth separate these categories across OEM specification tiers.
- Electronic:Pulse width modulation circuitry enables precise fuel rail pressure control across 12V to 48V hybrid systems. Procurement from German OEMs for mild-hybrid architectures is tightening qualification standards for electromagnetic compatibility under EU Green Deal timelines.
- Integrated:Combines driver electronics with power management and diagnostic firmware in single housings. Denso and Bosch are anchoring production scale through in-house ASIC design for these modules serving Japanese and European OEM platforms respectively.
- Mechanical:Relay-actuated voltage delivery for cost-sensitive replacement demand in aging vehicle fleets.
- Hybrid:Dual-mode modules switching between electronic and mechanical control based on operating conditions.
Mature deployment sits with Mechanical units in aftermarket channels. Newer deployment is concentrated in Integrated modules for 48V hybrid architectures.
Technology:
Control methodology determines efficiency, emissions compliance capability, and firmware complexity requirements.
- Smart Control:CAN network-integrated modules with predictive diagnostics and thermal management algorithms. BMW and Mazda range-extended programs are sourcing these systems for high-voltage fuel pump coordination with battery thermal loops.
- Pulse Width Modulation:Dominant OEM fitment technology operating at frequencies up to 20 kHz for precise pump speed modulation. China's MIIT fuel efficiency standards are concentrating domestic OEM procurement on these modules with diagnostic feedback capability.
- Constant Voltage:Fixed-output regulation for basic fuel delivery without load-adaptive optimization.
- Relay-Based:Binary on/off switching for price-sensitive aftermarket replacement demand.
Constant Voltage modules anchor legacy fleet maintenance. Smart Control systems are climbing the fastest as OEMs integrate fuel delivery with engine management networks.
Application:
Operating environment severity and duty cycle intensity shape module specification requirements.
- Automotive:Dominant volume segment spanning passenger vehicles, light trucks, and commercial fleets. NHTSA fuel system integrity standards and EPA evaporative emissions regulations govern validation protocols for durability across hybrid operating modes.
- Industrial:Stationary power generation and material handling equipment requiring extended thermal tolerance. These applications prioritize relay-based and constant voltage architectures for cost efficiency in non-emissions-critical deployments.
- Aerospace:Aviation fuel systems with extreme reliability requirements and specialized certification protocols.
- Marine:Corrosion-resistant housings for saltwater operating environments with vibration isolation specifications.
Automotive applications concentrate electronic and smart control deployment. Marine and Aerospace segments retain mechanical and relay-based systems for redundancy requirements.
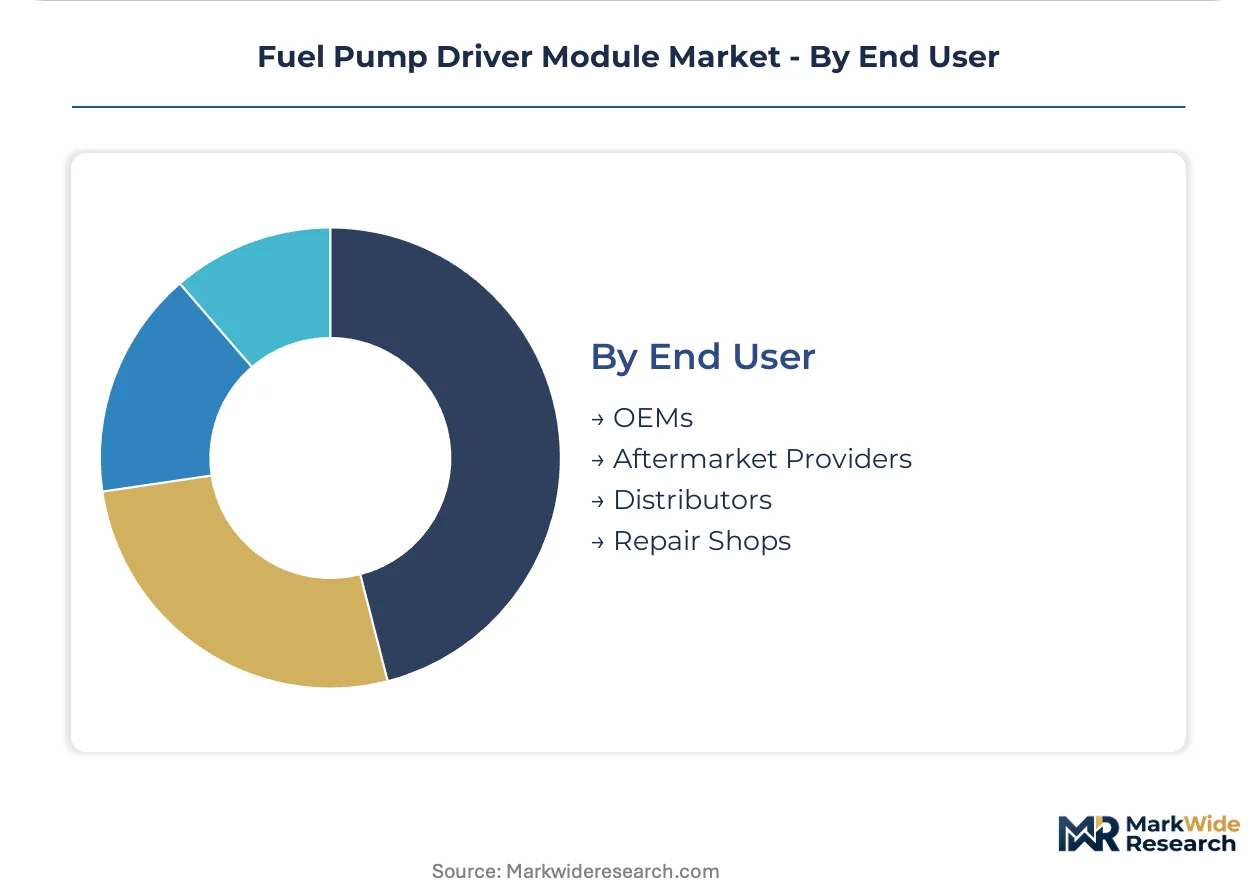
End User:
Channel structure and procurement authority determine pricing power and technical specification influence.
- OEMs:Direct platform integration with multi-year supply agreements and joint firmware development. ECHA REACH substance restrictions are forcing housing material reformulations that extend qualification timelines by 12-18 months for these customers.
- Aftermarket Providers:Independent distributors and private-label suppliers serving price-sensitive replacement demand. Fleet procurement contracts in North America are unbundling modules from engine management bundles in Class 4-7 medium-duty truck segments.
- Distributors:Inventory-holding intermediaries balancing OEM captive parts networks against independent service channels.
- Repair Shops:Installation-focused buyers prioritizing part availability and diagnostic compatibility over specification optimization.
OEM relationships concentrate smart control and integrated module development. Aftermarket channels represent the steepest expansion trajectory for electronic modules as fleet operators seek service independence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon carbide substrate availability from East Asian foundries anchors procurement geography for module manufacturers. German OEM electrification mandates and Chinese MIIT efficiency standards concentrate demand-side specification authority in these markets.
United States
NHTSA fuel system integrity standards and EPA evaporative emissions regulations govern validation protocols for module durability across hybrid operating modes. Fleet procurement contracts in Class 4-7 medium-duty truck segments are unbundling modules from traditional engine management bundles. Detroit's automotive supplier corridor hosts module assembly operations serving domestic OEM platforms.
Germany
EU Green Deal compliance deadlines are accelerating 48V mild-hybrid deployments requiring advanced pulse width modulation control for dual-fuel architectures. ECHA REACH substance restrictions constrain housing material selection, extending qualification timelines by 12-18 months. Stuttgart's automotive engineering cluster concentrates firmware development for smart control integration.
China
MIIT corporate average fuel consumption targets are concentrating domestic OEM procurement on electronic modules with diagnostic feedback capability. Dual carbon goals are pressuring suppliers toward halogen-free thermoplastics in housing formulations. Shanghai's Yangtze River Delta manufacturing belt anchors module assembly scale for domestic and export demand.
Japan
METI automotive electrification roadmaps are elevating technical requirements for hybrid fuel system architectures. JIS standards govern electromagnetic compatibility certification for module suppliers serving domestic OEMs. Nagoya's Chubu industrial corridor hosts captive power management component production for integrated module manufacturing.
India
PLI scheme incentives for domestic automotive electronics manufacturing are opening captive supply opportunities for module assembly. BIS automotive standards are tightening localization requirements for OEM procurement contracts. Tamil Nadu's Sriperumbudur supplier park is attracting module assembly investments serving Maruti Suzuki and Tata Motors platforms.
Fuel Pump Driver Module Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart control firmware specialization. The vendor base clusters around three strategic archetypes: diversified automotive electronics conglomerates with in-house semiconductor design, tier-one system integrators leveraging external foundry relationships, and captive suppliers serving single OEM platforms. Consolidation pressure is intensifying as electrification roadmaps fragment fuel system architectures. Dominant competitive moves include backward integration into power management components and strategic partnerships for gallium nitride epitaxy access.
Among diversified automotive electronics conglomerates, Denso and Bosch exemplify scale-driven positioning through captive supply chain control. Continental occupies a position within the tier-one system integrator archetype, competing on firmware differentiation for hybrid drivetrain applications. These three companies represent the prevailing competitive structure: Japanese and German-origin producers anchor premium-tier procurement through in-house ASIC design, while broader tier-one suppliers compete on smart control integration for network-convergent architectures.
| Leading Market Players |
|---|
| Denso |
| Bosch |
| Continental |
| Aptiv (Delphi Technologies) |
| Hitachi Astemo |
| TI Fluid Systems |
| Marelli |
| Aisan Industry |
| Magna |
| Others |
Value Network & Pricing Analysis
EU Green Deal compliance deadlines gate qualified supply for fuel pump driver modules, restricting premium-tier pricing access to vendors with REACH-certified halogen-free housing formulations and extended electromagnetic compatibility validation. This environmental mandate compresses margins for non-compliant suppliers while elevating pricing power for incumbents with pre-qualified material streams.
Pricing Analysis
Warranty and diagnostic service bundling separates premium integrated modules from unbundled electronic units sold through aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from OEM procurement teams. Cost compression in the relay-based aftermarket tier is intensifying because fleet operators are unbundling modules from engine management bundles. Aftermarket providers serving Class 4-7 medium-duty trucks exhibit highest price sensitivity, while German OEMs purchasing 48V mild-hybrid architectures demonstrate lowest sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
Single-source vulnerability sits with East Asian semiconductor foundry capacity, particularly Taiwan and South Korea wafer fabrication for power management components. Module assembly draws from Malaysia and Vietnam leadframe packaging clusters, with raw material dependencies spanning silicon carbide substrates, halogen-free thermoplastics, and gallium nitride epitaxy wafers. Tariff exposure on Chinese-sourced power semiconductors creates geographic risk for European and North American module vendors. Distribution runs through tier-one system integrators holding captive OEM supply agreements, with aftermarket channels bypassing traditional engine management bundle structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH substance restrictions create a barrier-to-entry moat for housing material suppliers with pre-qualified halogen-free formulations.
For Market Incumbents: Anchor production scale through backward integration into power management components and captive ASIC design capability. Denso and Bosch exemplify this defensive posture through in-house semiconductor development. Threat substitution from gallium nitride power semiconductors demands firmware talent investment for ISO 26262-compliant smart control modules. Capacity addition in India's Sriperumbudur supplier park offers geographic diversification against East Asian packaging concentration. For New Entrants and Emerging Players: Launch via direct distribution partnerships with North American fleet operators unbundling modules from engine management bundles in Class 4-7 medium-duty truck segments. White-space concentration sits with smart control firmware specialization for range-extended electric vehicle architectures from BMW and Mazda. The most penetrable segment is predictive maintenance subscription services enabled by CAN network-integrated diagnostic capability. Go-to-market angle should emphasize thermal management algorithm differentiation for high-voltage fuel pump coordination with battery thermal loops. For Investors and Strategic Acquirers: BMW and Mazda range-extended program procurement announcements are the leading indicator that high-voltage fuel pump control systems will command premium valuations over conventional 12V modules. Long-term viability favors suppliers with GaN epitaxy partnerships and functional safety certification depth. Acquisition target archetype: tier-two module vendors with smart control firmware assets but lacking foundry relationships. Signal to monitor: EPA evaporative emissions enforcement tightening validation protocols for leak detection capability during extended electric-only operation.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Epitaxy Partnership Formation | Secures switching efficiency advantages for 48V mild-hybrid architectures from German OEMs. |
| REACH-Certified Housing Material Qualification | Unlocks EU Green Deal procurement timelines with 12-18 month lead time over non-compliant competitors. |
| Smart Control Firmware Development | Enables CAN network integration for predictive maintenance revenue streams with fleet operators. |
| India PLI Scheme Manufacturing Localization | Captures Maruti Suzuki and Tata Motors platform procurement under BIS automotive standards. |
| ASIC Design Capability Acquisition | Replicates Denso and Bosch captive supply chain control for integrated module margin defense. |
Research Methodology
SEC 10-K filings from tier-one automotive electronics suppliers, EPA evaporative emissions enforcement databases, and MIIT corporate average fuel consumption compliance records formed the secondary backbone for market sizing and regulatory trajectory assessment. Primary interviews with OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors serving Class 4-7 fleets, and semiconductor foundry account managers validated demand assumptions and technology transition timelines. Bottom-up and top-down triangulation reconciled module shipment volumes against vehicle production data and content-per-vehicle estimates.
Bottom-up modeling aggregated segment-level demand across voltage classes, control architectures, and end-user channels, while top-down validation cross-referenced against automotive electronics procurement spend patterns. Segmentation dimensions included propulsion architecture, integration depth, network connectivity tier, and regional regulatory cluster. CAGRs were derived from regression analysis of historical penetration rates and electrification roadmap commitments. Forecast inputs incorporated silicon carbide substrate pricing volatility indices and OEM hybrid platform launch schedules.
Silicon carbide wafer cost fluctuations, REACH substance restriction enforcement timelines, and NHTSA fuel system integrity standard revisions are the dominant revision risks that could alter module demand trajectories. Forecasts reflect assumptions about electrification program continuity and foundry capacity expansion schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
North America MLCC Market
Electronic Components
Braking Resistors Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Switch Diode Market
Electronic Components
Digital Audio Processor Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Blockchain in Electronic Component Market
Electronic Components
Structural Electronics Market
Electronic Components
Fuse Bases Market
Electronic Components
Motherboard Battery Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Stretchable and Conformal Electronics Market
Electronic Components
Digital Pulse Mixer Market
Electronic Components
2D Electronics Market