
 Aluminum Cable Market | 2026-2036
Aluminum Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Cable Market Analysis
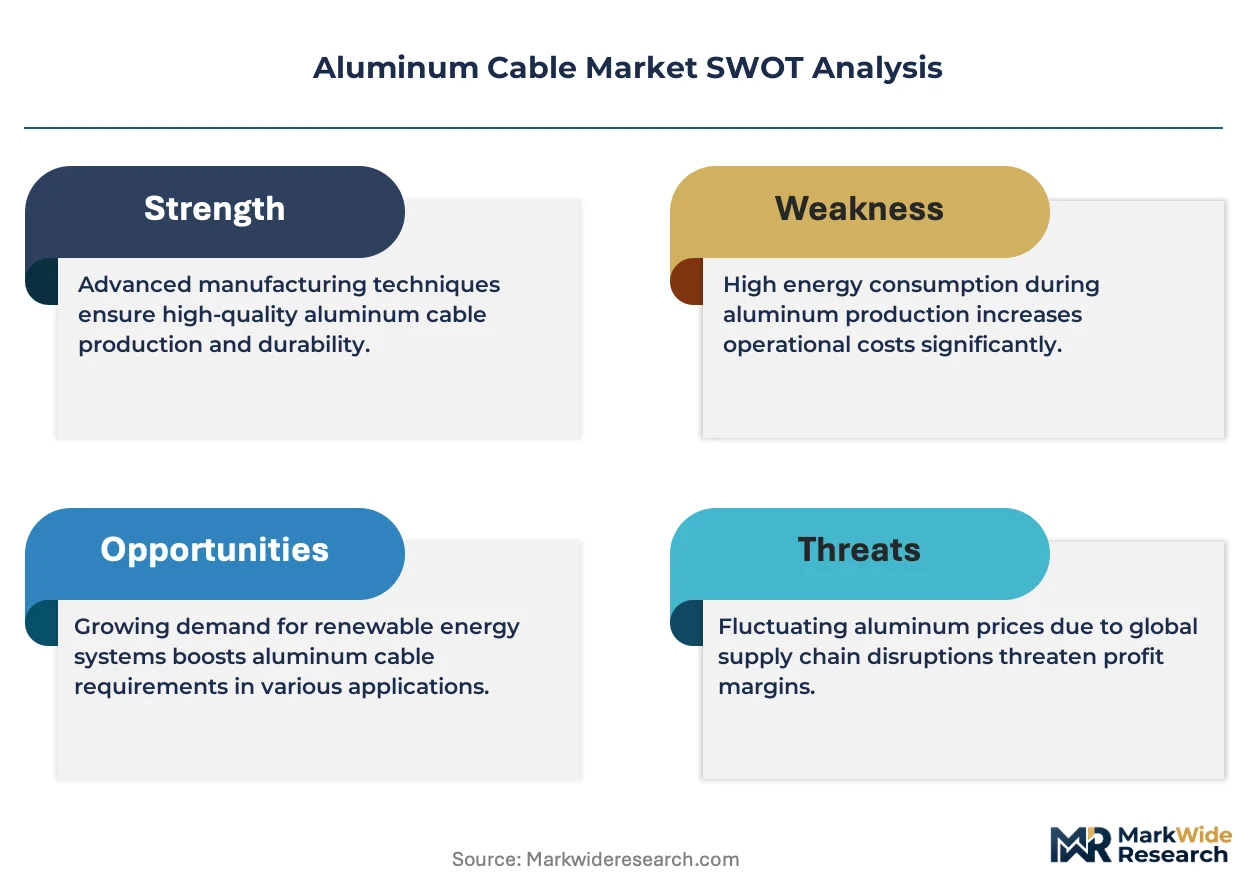
Project finance for transmission infrastructure is fragmenting the competitive landscape, allowing regional specialists to bid against integrated multinationals. Prysmian Group leverages its manufacturing scale across Europe and the Americas to anchor long-term utility contracts. KEI Industries competes on cost-optimized stranded conductor production for India's distribution networks. Southwire Company controls domestic channel access through extensive distributor relationships in North American construction markets.
Aluminum cable consists of electrically conductive aluminum cores, often alloyed with magnesium or silicon to improve tensile strength, manufactured through continuous casting and rolling processes for overhead and underground installations. Its primary purpose is to transmit electrical power across distances where lower density and cost relative to copper justify larger conductor sizes. Stranded conductors dominate volume in power transmission applications where flexibility and mechanical durability matter most. Medium voltage sizing captures expanding margin pools as utilities modernize aging distribution feeders. The construction application segment sustains steady pull from commercial building electrification mandates in multiple jurisdictions.
The US National Electrical Code and EPA efficiency standards shape product specifications and installation practices for aluminum cable in building and utility environments. China's GB standards and MIIT energy directives govern alloy composition and conductor ratings for domestic infrastructure procurement. India's CEA technical standards and state utility bidding rules determine qualification thresholds for cable suppliers participating in transmission tenders. Stakeholders must monitor how carbon-border adjustments and localized content requirements alter sourcing economics for aluminum smelters and downstream cable manufacturers.
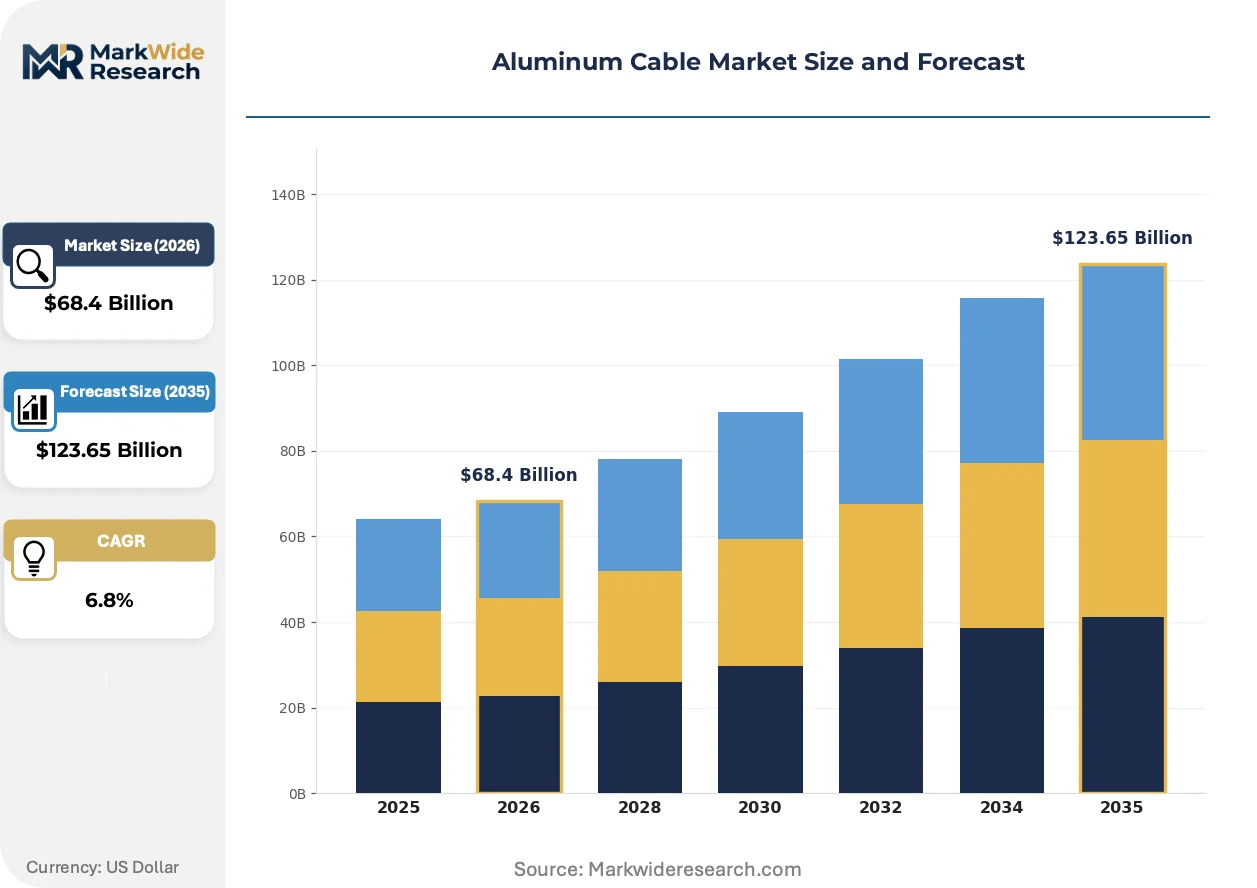
Market Dynamics
China's dual carbon goals and stricter energy-efficiency mandates in building codes are accelerating material substitution from copper to aluminum across power transmission and distribution infrastructure worldwide.
Growth Catalysts
- India's rural electrification programs:State utilities favor aluminum conductors for cost-optimized distribution networks serving remote populations. Distribution losses drive procurement of larger-gauge stranded aluminum.
- MIIT energy directives:China's alloy composition standards mandate higher conductivity grades for domestic infrastructure procurement. Domestic cable manufacturers retool continuous casting lines to meet GB standard upgrades.
- Overhead transmission expansion:Southeast Asian utilities deploy aluminum conductor steel-reinforced (ACSR) cables to reduce tower loading and foundation costs across archipelago geography.
Market Restraints
- Alumina price volatility:Smelter energy costs and bauxite export restrictions from Guinea concentrate input cost risk. Cable producers lack hedging instruments for long-dated utility contracts.
- Copper substitution resilience:Premium building segments and data center power distribution retain copper for fire safety and termination reliability. Aluminum faces technical barriers in low-voltage residential wiring.
- REACH compliance burden:European cable importers face extended substance testing timelines for alloy additives. Certification costs disproportionately impact mid-volume suppliers.
Strategic Opportunities
- Medium-voltage grid modernization:Aging distribution feeders in the US Northeast and Midwest require XLPE-insulated aluminum replacements. Utilities prioritize lifecycle cost over first-cost procurement.
- Offshore wind interconnection:Subsea aluminum power cables reduce jacket weight and installation vessel requirements. Developers in the North Sea and Baltic markets specify alloy-core designs.
- Carbon-border adjustment positioning:EU CBAM implementation creates first-mover advantage for smelters with verified low-carbon production. Cable assemblers can secure green aluminum premiums.
Industry Challenges
- Termination technician shortage:Proper aluminum-to-copper connection requires torque-specified lugs and antioxidant compounds. Electrical contractor training lags installation volume growth.
- Fire-resistance certification timelines:IEC 60331 and BS 6387 testing protocols extend product launch cycles by 8-14 months. Development costs strain R&D budgets at regional manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Cable Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductor, Alloy, Stranded, Solid Application: Power Transmission, Telecommunication, Construction, Railways End User: Utilities, Industrial, Commercial, Residential Size: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage |
| Companies Covered | LS Cable & System, Furukawa Electric, Prysmian Group, KEI Industries, Jiangsu Hengtong Cable, Nexans, Southwire Company, NKT Cables, Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Cable Market Emerging Trajectories
Active material science advances and procurement model evolution are compressing product lifecycles while expanding addressable applications for aluminum conductor systems across voltage classes.
Aluminum-magnesium-silicon alloy conductor (AAAC) technology is hybridizing overhead line performance by combining tensile strength equivalent to ACSR with reduced electrical resistance. European transmission system operators in Germany and Spain accelerate deployment for reconductoring projects. The technology is hybridizing procurement specifications by enabling higher temperature ratings without tower replacement.
EPA efficiency standards under the Inflation Reduction Act now prescribe minimum conductivity thresholds for federally funded grid infrastructure. Domestic cable manufacturers must certify alloy purity and resistivity to qualify for loan guarantee programs. Medium-voltage distribution segments in Texas and California utilities show fastest compliance adoption.
Utility procurement departments now unbundle cable supply from installation services, creating direct manufacturer-to-utility contracting channels. Traditional electrical distributor margins compress as state-owned grids in India and Vietnam establish approved vendor lists. The shift concentrates most visibly in India's state electricity boards, which now negotiate aluminum conductor contracts through centralized tender platforms.
Aluminum Cable Market Segmentation
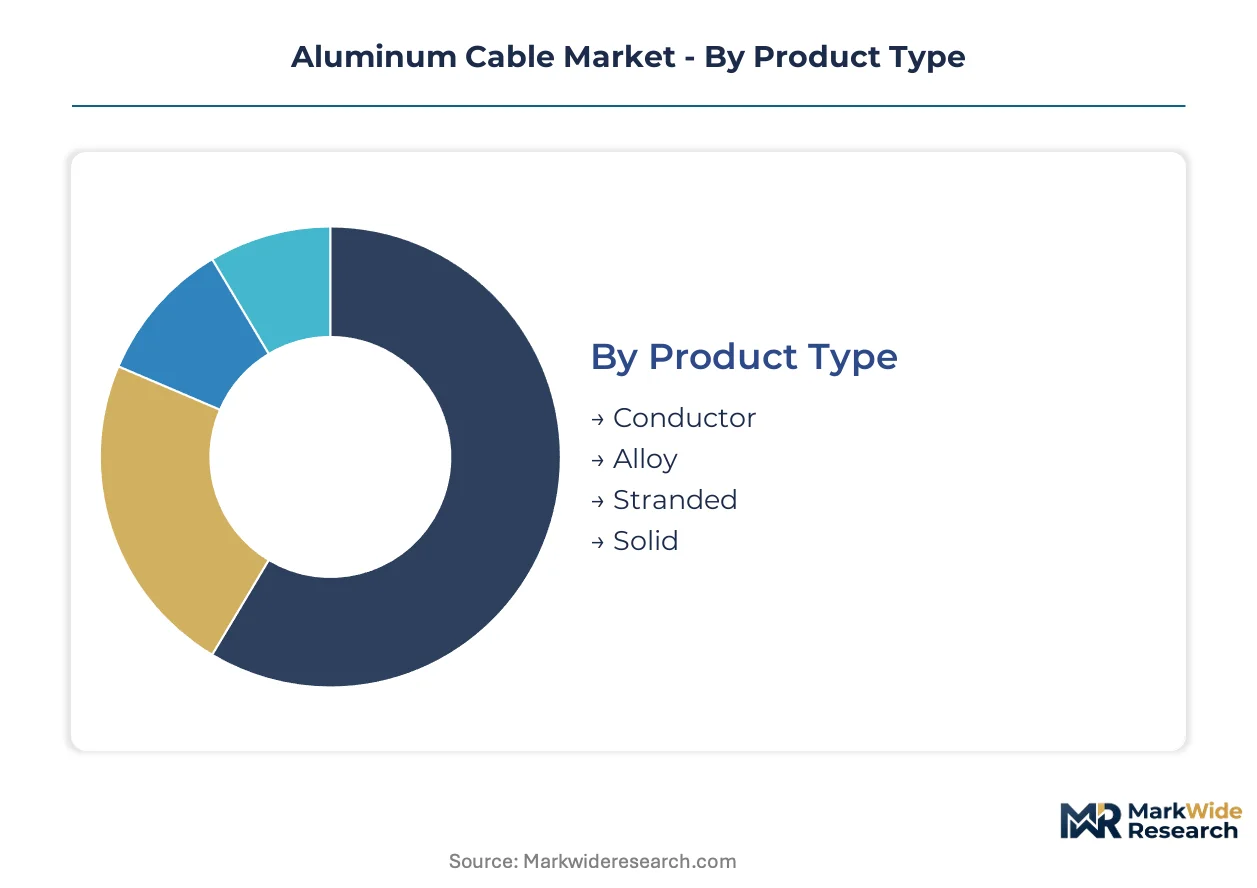
Aluminum cable procurement patterns diverge sharply across voltage classes and installation environments. Product specifications, alloy compositions, and conductor geometries must align with distinct mechanical loads, thermal cycling requirements, and regulatory compliance thresholds.
Product Type:
Cost tier differentiation separates commodity conductors from engineered alloy formulations with premium mechanical properties.
- Conductor:Unalloyed electrical-grade aluminum delivers baseline conductivity for overhead transmission lines. India's state electricity boards specify conductor purity grades through CEA technical standards for rural electrification tenders.
- Alloy:Aluminum-magnesium-silicon formulations achieve tensile strength parity with steel-reinforced designs at reduced weight. German transmission operators deploy AAAC alloys for reconductoring projects without tower replacement.
- Stranded:Multi-wire constructions provide flexibility for medium-voltage distribution feeders and submarine installations.
- Solid:Single-core designs serve building wire applications where termination simplicity outweighs mechanical durability requirements.
Conductor holds installed capacity. Alloy is rotating up the share rankings.
Application:
End-use environments dictate insulation systems, armor requirements, and fire-resistance certification tiers.
- Power Transmission:Overhead lines and underground corridors move bulk electricity across regional grids. Southeast Asian utilities favor ACSR cables to reduce foundation costs across archipelago terrain.
- Telecommunication:Fiber-optic composite ground wires integrate communications with electrical shielding functions. European TSOs specify optical fiber counts for smart grid monitoring.
- Construction:Building wire segments face divergent code requirements between commercial and residential occupancies.
- Railways:Catenary systems and traction power feeders demand fatigue-resistant alloys for vibration-intensive installations.
Power Transmission anchors volume procurement. Telecommunication is climbing the fastest as grid digitalization accelerates.
End User:
Customer type determines contract structures, payment terms, and technical qualification thresholds.
- Utilities:State-owned grids and investor-owned operators procure through centralized tender platforms with multi-year delivery schedules. India's state electricity boards negotiate aluminum conductor contracts through approved vendor lists.
- Industrial:Manufacturing facilities specify medium-voltage feeders with lifecycle cost priorities over first-cost procurement.
- Commercial:Building developers face electrification mandates in California and New York jurisdictions.
- Residential:Single-family construction retains copper preference for branch circuit wiring due to termination reliability concerns.
Utilities dominate contract value. Industrial is gaining share fastest as manufacturing reshoring intensifies.
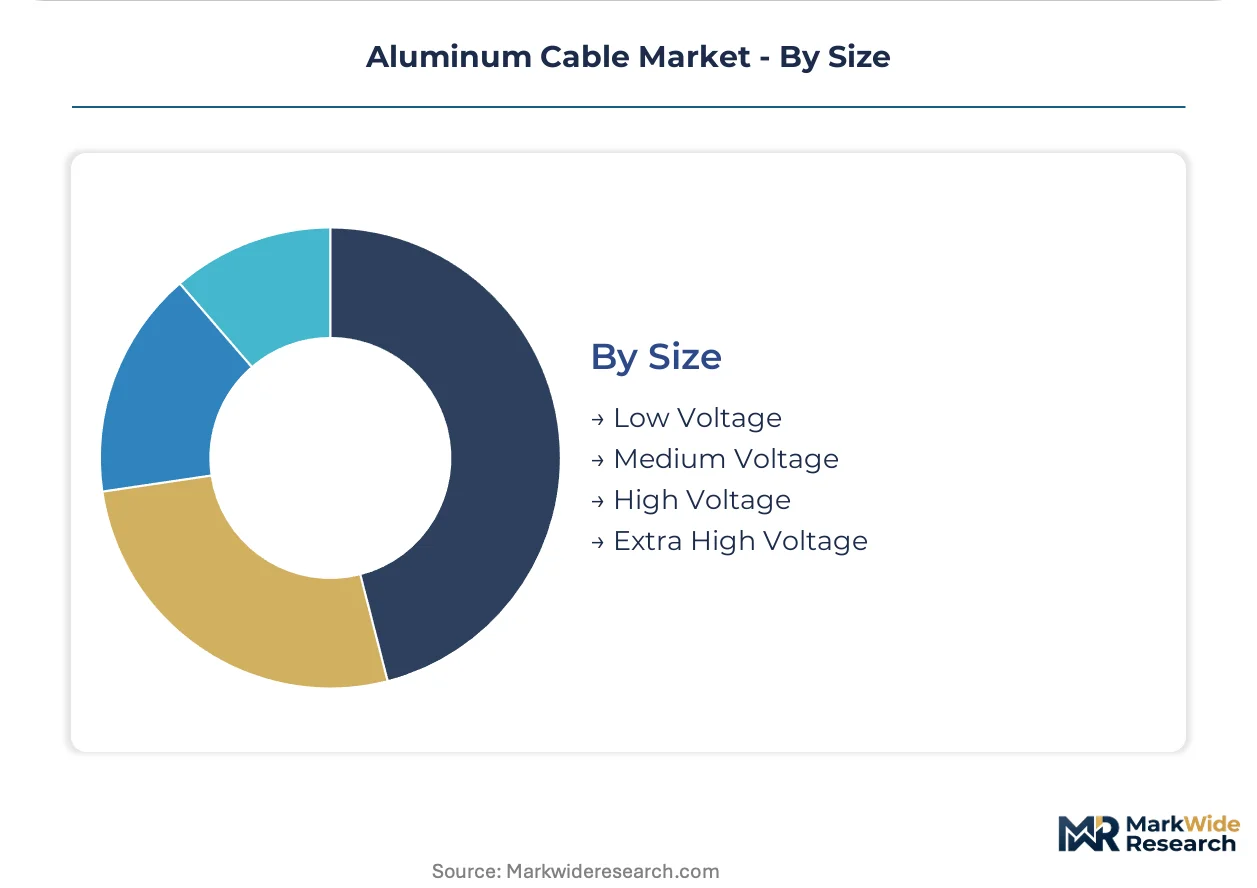
Size:
Voltage classification aligns with insulation thickness, shielding requirements, and installation methodology.
- Low Voltage:Building wire and service entrance cables operate below 1kV with PVC or XLPE insulation. Fire-resistance certification timelines extend product launch cycles for European importers facing REACH compliance.
- Medium Voltage:Distribution feeders between 1kV and 35kV require extruded insulation systems and metallic shielding. US Northeast utilities prioritize XLPE-insulated aluminum replacements for aging infrastructure.
- High Voltage:Subtransmission corridors between 35kV and 230kV deploy cross-linked polyethylene or oil-filled paper insulation.
- Extra High Voltage:Bulk power transfer above 230kV employs oil-impregnated paper or gas-insulated lines with specialized jointing systems.
Medium Voltage commands margin expansion. Extra High Voltage is expanding most quickly with offshore wind interconnection projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-owned utilities and private grid operators concentrate procurement authority across distinct national regulatory environments. Each geography imposes alloy specifications, tender platforms, and carbon-accounting rules that reshape supplier qualification thresholds.
China
MIIT energy directives mandate higher conductivity grades for domestic infrastructure procurement. Dual carbon goals accelerate material substitution from copper to aluminum across power transmission networks. Jiangsu Hengtong Cable anchors manufacturing capacity in the Yangtze River Delta for continuous casting line retooling.
India
State electricity boards favor aluminum conductors for cost-optimized rural electrification programs. CEA technical standards determine qualification thresholds for cable suppliers participating in transmission tenders. KEI Industries concentrates stranded conductor production in Maharashtra for distribution network deployment.
United States
Northeast and Midwest utilities prioritize XLPE-insulated aluminum replacements for aging distribution feeders. EPA efficiency standards under the Inflation Reduction Act prescribe minimum conductivity thresholds for federally funded grid infrastructure. Southwire Company controls domestic channel access through extensive distributor relationships across southeastern construction markets.
Germany
Transmission system operators accelerate AAAC alloy deployment for reconductoring projects without tower replacement. ECHA REACH compliance burdens European cable importers with extended substance testing timelines for alloy additives. Prysmian Group leverages manufacturing scale across central European facilities to anchor long-term utility contracts.
Vietnam
State-owned grids deploy aluminum conductor steel-reinforced cables to reduce tower loading across archipelago geography. Centralized tender platforms unbundle cable supply from installation services for direct manufacturer contracting. Regional specialists bid against integrated multinationals for expanding transmission infrastructure project finance.
Aluminum Cable Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base stratifies between scale-driven manufacturers with multi-continent production footprints and regional fabricators optimized for cost-sensitive tender markets. Three archetypes dominate: integrated multinationals with utility-direct relationships, mid-volume specialists with alloy formulation expertise, and construction-channel distributors with installation service bundling. Competitive moves concentrate on geographic expansion through approved vendor list qualification and backward integration into aluminum smelter partnerships for carbon-border positioning.
Within the integrated multinational tier, Prysmian Group and Nexans occupy positions defined by manufacturing scale across European and North American anchor markets. KEI Industries exemplifies the regional specialist archetype with cost-optimized production concentrated for India's state electricity board procurement. Southwire Company sits within the channel-control segment where distributor relationships dominate North American construction market access.
| Leading Market Players |
|---|
| LS Cable & System |
| Furukawa Electric |
| Prysmian Group |
| KEI Industries |
| Jiangsu Hengtong Cable |
| Nexans |
| Southwire Company |
| NKT Cables |
| Sumitomo Electric Industries |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing cluster anchors continuous casting capacity that feeds directly into utility-scale procurement tenders across Southeast Asia. Smelter energy costs and alloy grade specifications concentrate pricing power among integrated producers with captive aluminum supply.
Pricing Analysis
Certification level (IEC/GB/CE-grade) creates the primary spread between commodity conductor and premium alloy cable tiers. Three-tier pricing structure across premium, standard, and economy levels reflects alloy purity grades, volume scale, and bundled installation services. Cost compression in standard-grade stranded conductor is intensifying because state electricity boards unbundle supply from installation contracts. Distribution utilities in India exhibit highest price sensitivity, while offshore wind developers in the North Sea prioritize lifecycle cost over first-cost procurement.
Supply Chain Analysis
Export controls on high-purity aluminum smelting technology limit capacity expansion outside established production corridors. China, India, and Germany concentrate primary aluminum refining and continuous casting line deployment. Downstream cable assembly draws from alumina, magnesium-silicon alloy additives, and XLPE insulation compounds. Single-source vulnerability in Guinea bauxite exports threatens input cost stability. Distribution runs through state-owned grid tender platforms in India and Vietnam, direct manufacturer contracting in Germany, and electrical distributor networks in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-border adjustment implementation and dual carbon regulatory mandates are disrupting procurement economics, compressing margins for carbon-intensive producers while rewarding verified low-carbon supply chains.
For Market Incumbents: Insulate long-term utility contracts through backward integration into smelter partnerships with verified low-carbon production. Prysmian Group and Nexans should anchor manufacturing scale across European facilities to meet EU CBAM qualification thresholds. Capacity expansion in India and Vietnam defends position against regional specialists bidding on unbundled tender platforms.
For New Entrants and Emerging Players: Mid-market commercial building electrification in California and New York represents the most penetrable entry point for AAAC alloy cable specialists. Offshore wind interconnection projects in the Baltic Sea offer white-space demand for subsea aluminum power cable with reduced jacket weight specifications. Direct utility contracting through approved vendor list qualification bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors alloy formulation specialists with IEC 60331 fire-resistance certification and carbon-border-ready supply chains. Long-term viability hinges on smelter partnerships with hydro-powered or renewable-integrated production. The signal to watch is state utility tender rule changes mandating lifecycle cost evaluation over first-cost procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Smelter Partnership Formation | Secures low-carbon aluminum supply for EU CBAM compliance and green premium capture. |
| Fire-Resistance Certification Investment | IEC 60331 qualification unlocks medium-voltage grid modernization contracts in US Northeast utilities. |
| Approved Vendor List Qualification | Direct access to India's state electricity board centralized tender platforms bypasses distributor margins. |
| Continuous Casting Line Retooling | GB standard upgrades for higher conductivity grades meet MIIT energy directive procurement mandates. |
| Subsea Cable Engineering Capability | Offshore wind interconnection specifications in North Sea and Baltic markets demand alloy-core designs. |
Methodological Framework
Desk research of customs trade databases, CEA technical standards filings, and utility tender documentation preceded structured interviews with transmission planning officers, cable procurement managers at state electricity boards, continuous casting line engineers, and EPC contractors specializing in grid infrastructure. Secondary validation drew from MIIT energy directive publications, EPA efficiency standard rulemakings, and IEC certification registries. Bottom-up volume estimates from country-level utility procurement pipelines were triangulated against top-down aluminum consumption forecasts from smelter association data.
Assumptions held fixed include current alloy composition standards, existing carbon-border adjustment implementation timelines, and state utility procurement centralization trends. Variables tested across the analysis window encompass alumina price volatility scenarios, copper-aluminum substitution elasticity in building wire segments, and REACH compliance burden escalation for European importers. Segmentation dimensions modeled include voltage class, conductor geometry, application environment, and end-user procurement channel. CAGRs were derived from utility capital expenditure pipelines and infrastructure investment commitments documented in regulatory filings.
Practitioners should monitor Guinea bauxite export policy shifts, EU CBAM verification protocol changes, and state utility tender rule modifications for early signals requiring forecast reassessment. Material shifts in smelter energy cost structures or alloy additive regulatory restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Patch Cable Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
United States Cable Accessories Market
Cables
Mexico Wires and Cables Market
Cables
Downhole Cables Market
Cables
North America Copper Wire and Cable Market
Cables
Wire and Cable Label Market
Cables
Cable Accessories Market
Cables
Anti-Static Space Wires Market
Cables
High Voltage Cable Termination Market
Cables
Audio and Video Cables Market
Cables
Hybrid Cables Market
Cables
Japan Cables Market
Cables
Asia Pacific MV and HV Underground Cables and Accessories Market
Cables
LASER Light Cables Market
Cables
Class 1E Electric Cables Market