
 North America Touch Screen Controllers Market | 2026-2036
North America Touch Screen Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Touch Screen Controllers Market Analytics
Distributor consolidation across North American electronics channels is tilting procurement power toward fewer authorized distributors serving Tier 1 automotive and industrial accounts. Texas Instruments Incorporated leverages its Dallas-based fabrication and analog design heritage to sustain controller supply agreements with Detroit-area automotive suppliers. Infineon Technologies anchors its North American position through a dedicated automotive microcontroller division operating from San Jose and Livonia facilities. NXP Semiconductors competes by extending its touch controller portfolio into pressure-sensitive and haptic-enabled variants for premium vehicle interiors.
Touch screen controllers are mixed-signal integrated circuits that convert analog capacitive or resistive panel inputs into digital coordinate data for host processors, typically operating with signal-to-noise ratios exceeding 60 dB and scan frequencies between 60 Hz and 120 Hz to eliminate display synchronization artifacts. Their primary purpose is enabling human-machine interface functionality in displays where mechanical buttons prove impractical or durability-limited. Capacitive controllers dominate revenue contribution owing to multi-touch gesture requirements in smartphones and automotive center stacks, while haptic feedback technology captures the fastest expansion as OEMs seek tactile confirmation without mechanical actuators. Embedded installation configurations retain the largest volume share as system designers integrate controllers directly into display module substrates to reduce bill-of-materials complexity.
The U.S. Federal Communications Commission enforces Part 15 unintentional radiator limits that constrain controller electromagnetic emissions, while the U.S. National Highway Traffic Safety Administration references FMVSS distraction guidelines affecting automotive touch interface response latency requirements. Canada's ISED radio equipment certification and Mexico's national standards body electrical safety markings create a three-jurisdiction compliance burden for suppliers distributing across the United States-Mexico-Canada Agreement trade zone. Stakeholders must monitor evolving automotive functional safety standards and cross-border harmonization negotiations to preempt certification delays and qualification cost escalations.
Market Dynamics
Automotive OEMs in the United States and Canada are consolidating touch controller procurement around fewer qualified suppliers capable of meeting simultaneous FCC electromagnetic compatibility and NHTSA distraction-mitigation requirements, compressing vendor qualification timelines and elevating technical barriers to entry.
Growth Catalysts
- Capacitive multi-touch mandates:Tier 1 automotive suppliers across Michigan and Ontario are specifying controllers supporting ten-point touch for center-stack infotainment, eliminating resistive alternatives from new vehicle programs.
- FMVSS 111 rear-visibility compliance:Backup camera integration with touch-activated parking assist interfaces is expanding controller deployments in light trucks and SUVs assembled in Texas and Tennessee.
- Haptic feedback convergence:Pressure-sensitive and localized vibration response technologies are penetrating premium vehicle interiors as mechanical button elimination accelerates design refresh cycles.
Market Restraints
- Indium tin oxide supply concentration:Transparent conductor substrates for capacitive panels face price volatility tied to Chinese rare earth processing capacity, squeezing controller module margins.
- FCC Part 15 certification backlog:Unintentional radiator testing queues at accredited laboratories are extending product launch timelines by four to six months for new entrants.
- Voice and gesture substitution:Amazon Alexa Auto and Google Assistant integrations in Ford, GM, and Stellantis vehicles are reducing touch dependency for climate and media control functions.
Strategic Opportunities
- Mexico automotive manufacturing expansion:Controller suppliers qualifying under USMCA rules of origin can capture assembly plant demand in Aguascalientes and Guanajuato without tariff exposure.
- Industrial HMI retrofit cycles:Food processing and pharmaceutical packaging equipment in Wisconsin and Illinois is replacing membrane switches with sealed capacitive panels for washdown compliance.
- ISED 5G coexistence certification:Controllers demonstrating immunity to sub-6 GHz interference gain preferred vendor status for Canadian telecom infrastructure and smart city deployments.
Industry Challenges
- Mixed-signal IC design talent scarcity:Analog front-end and noise-cancellation algorithm expertise concentrates in Silicon Valley and Austin, forcing competitors to relocate engineering functions or accept compensation inflation.
- Functional safety ISO 26262 qualification:ASIL-B and ASIL-C certification for automotive touch controllers demands eighteen-month validation cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Touch Screen Controllers Market |
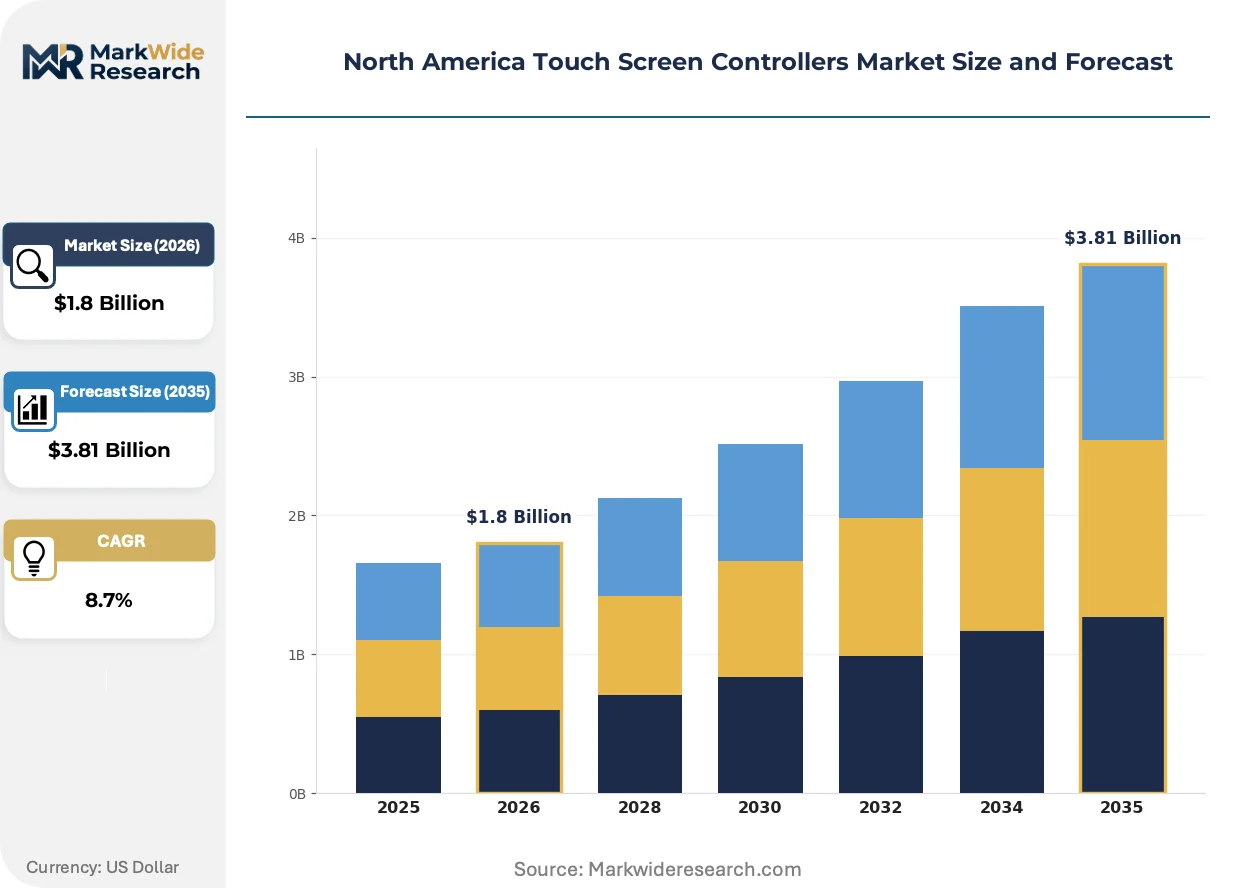
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Resistive, Infrared, Optical End User: Consumer Electronics, Automotive, Industrial Automation, Healthcare Technology: Multi-Touch, Single-Touch, Pressure-Sensitive, Haptic Feedback Installation: Built-In, Add-On, Embedded, Standalone |
| Companies Covered | Texas Instruments Incorporated, Infineon Technologies, Analog Devices Inc, NXP Semiconductors, Microchip Technology Incorporated, Silicon Laboratories, Broadcom Inc, Integrated Device Technology Inc, Semtech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Touch Screen Controllers Market Evolving Landscape
Controller architectures are converging around system-on-chip integration that embeds haptic drivers and machine-learning gesture recognition, collapsing discrete component counts while demanding new competencies in firmware and acoustics engineering.
Ultrasonic touch sensing is virtualizing physical button functions by detecting finger proximity and pressure through solid surfaces without etched electrode patterns. Automotive interior designers at Detroit-area studios are specifying these modules for curved dashboard substrates that resist traditional capacitive deposition. The technology is virtualizing supply chain requirements by eliminating separate haptic actuator assemblies and simplifying module sourcing.
The FCC's 2023 update to Part 15 Class B emission limits for digital devices is forcing controller firmware revisions to suppress harmonic interference in the 2.4 GHz band. Module suppliers serving aftermarket automotive channels are absorbing redesign costs to maintain market access, while OEM-direct vendors accelerated pre-compliance testing to avoid production holds. Michigan-based Tier 1s are responding by consolidating validation programs with laboratories holding dual FCC-ISED accreditation.
Buyer concentration among Detroit's automotive purchasing consortiums is compressing supplier negotiation leverage and standardizing controller specifications across competing OEM platforms. Distributor inventories in the Southwest and Midwest are thinning as direct vendor-managed inventory agreements replace traditional stocking arrangements. This consolidation is most visible in Texas semiconductor manufacturing clusters where controller die production is migrating to captive foundry relationships.
North America Touch Screen Controllers Market Segmentation
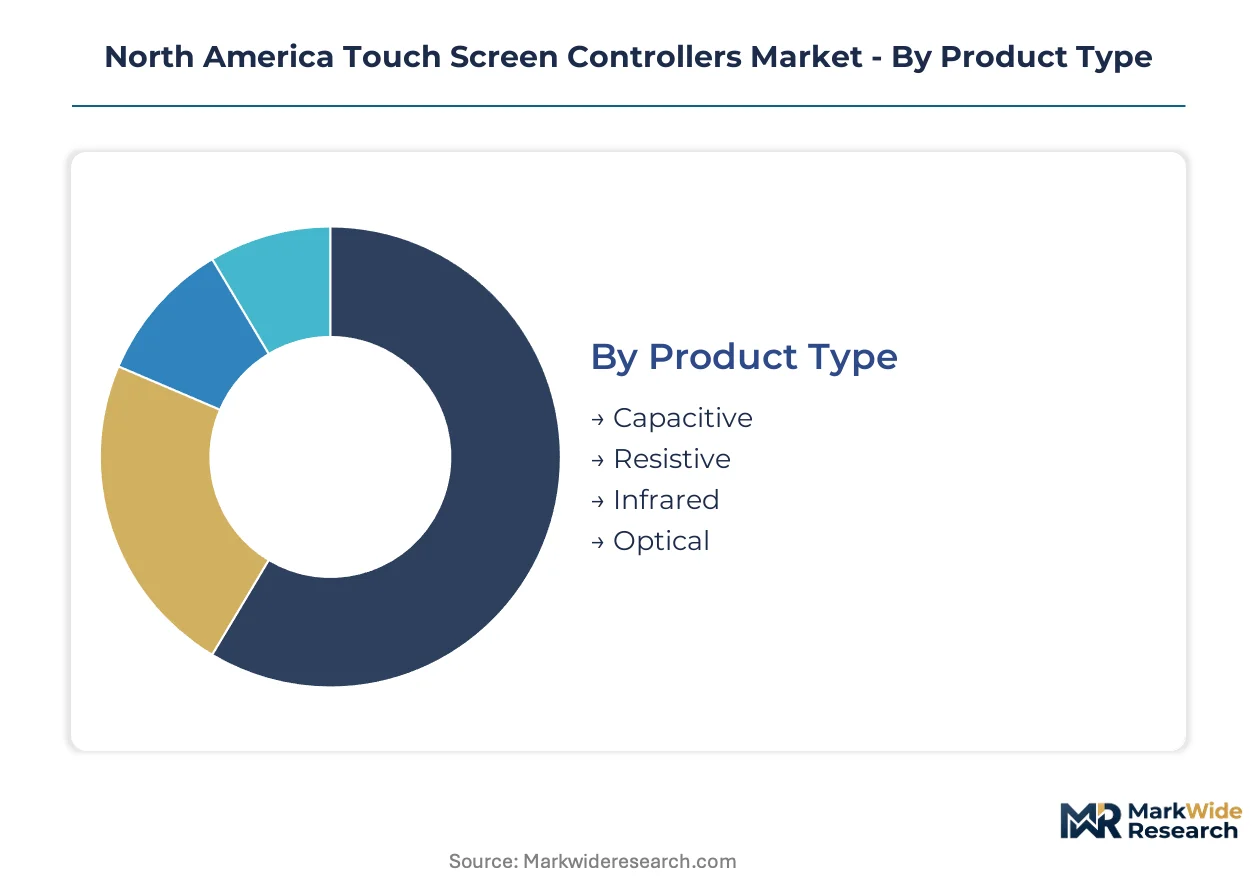
Touch screen controller segmentation in North America reflects divergent technical requirements across automotive safety systems, consumer electronics portability demands, and industrial environmental resilience. Procurement patterns vary sharply by end-use sector, with FCC certification timelines and NHTSA functional safety mandates creating distinct qualification barriers.
Product Type:
Controller architectures span the full use-case spectrum from high-sensitivity multi-touch surfaces to cost-optimized single-point interfaces.
- Capacitive:These controllers detect touch through electrical field disruption, enabling ten-point gesture recognition with sub-millimeter accuracy. Michigan-based Tier 1 automotive suppliers specify capacitive modules for center-stack infotainment, driven by FMVSS 111 rear-visibility integration requirements that demand rapid touch response times.
- Resistive:Pressure-activated layers complete electrical circuits upon mechanical deformation, tolerating stylus and glove inputs. Food processing equipment manufacturers in Wisconsin deploy resistive panels for HMI retrofit cycles where washdown compliance and cost containment outweigh gesture complexity needs.
- Infrared:LED emitter-detector arrays create optical touch grids without surface coatings. Kiosks and outdoor digital signage in Texas and Arizona favor infrared for vandal resistance and extreme temperature operation.
- Optical:Camera-based imaging tracks finger position through frustrated total internal reflection principles. Medical imaging workstations in Boston and Toronto research clusters adopt optical controllers for large-format diagnostic displays requiring sterile surface compatibility.
The dominant share belongs to Capacitive, while Haptic Feedback convergence in premium automotive interiors is closing the gap fastest.
End User:
Customer archetypes range from high-volume consumer electronics OEMs to safety-critical automotive suppliers with eighteen-month validation cycles.
- Consumer Electronics:Smartphone, tablet, and wearable manufacturers in California design hubs specify ultra-low-power controllers with sub-100 microamp sleep currents. California's consumer electronics procurement concentrates around San Jose and Irvine design centers, where FCC Part 15 pre-certification testing accelerates product launch timelines.
- Automotive:Detroit-area OEMs and Ontario assembly plants demand ASIL-B qualified controllers with fault-tolerant architectures. Tier 1 suppliers in Livonia and Warren face compressed vendor qualification timelines as purchasing consortiums consolidate around fewer qualified sources capable of simultaneous electromagnetic compatibility and functional safety certification.
- Industrial Automation:Programmable logic controller interfaces and robotic teach pendants require sealed panels with IP65 ingress protection. Pharmaceutical packaging lines in Illinois and Ohio specify capacitive replacements for membrane switches to meet FDA washdown compliance.
- Healthcare:Medical device manufacturers prioritize antimicrobial surface coatings and IEC 60601-1-2 electromagnetic immunity. Diagnostic equipment OEMs in Minnesota and Massachusetts integrate touch controllers into imaging systems where response latency affects clinical workflow efficiency.
Automotive commands the largest revenue concentration, with Industrial Automation expanding most quickly through food safety and pharmaceutical packaging retrofit demand.
Technology:
Interface sophistication tiers separate commodity single-touch applications from premium haptic-enabled experiences.
- Multi-Touch:Controllers process simultaneous contact points for pinch-zoom and rotation gestures. Texas semiconductor clusters manufacture multi-touch die for Detroit automotive programs where center-stack complexity rivals smartphone interfaces.
- Single-Touch:Simplified architectures detect one contact point, minimizing die area and power consumption. Point-of-sale terminals and industrial pushbutton replacements across the Midwest specify single-touch for cost-constrained retrofit applications.
- Pressure-Sensitive:Force-sensing resistor networks quantify applied pressure alongside positional coordinates. NXP Semiconductors extends its portfolio into pressure-sensitive variants for premium vehicle interiors where mechanical button elimination accelerates design refresh cycles.
- Haptic Feedback:Piezoelectric or linear resonant actuators provide tactile confirmation without mechanical travel. Ultrasonic touch sensing modules specified by Detroit-area studios for curved dashboard substrates represent the steepest expansion trajectory as designers virtualize physical button functions.
Multi-Touch retains volume leadership, while Pressure-Sensitive variants gain share fastest through automotive premium interior differentiation.
Installation:
Physical integration approaches trade off design flexibility against bill-of-materials simplification.
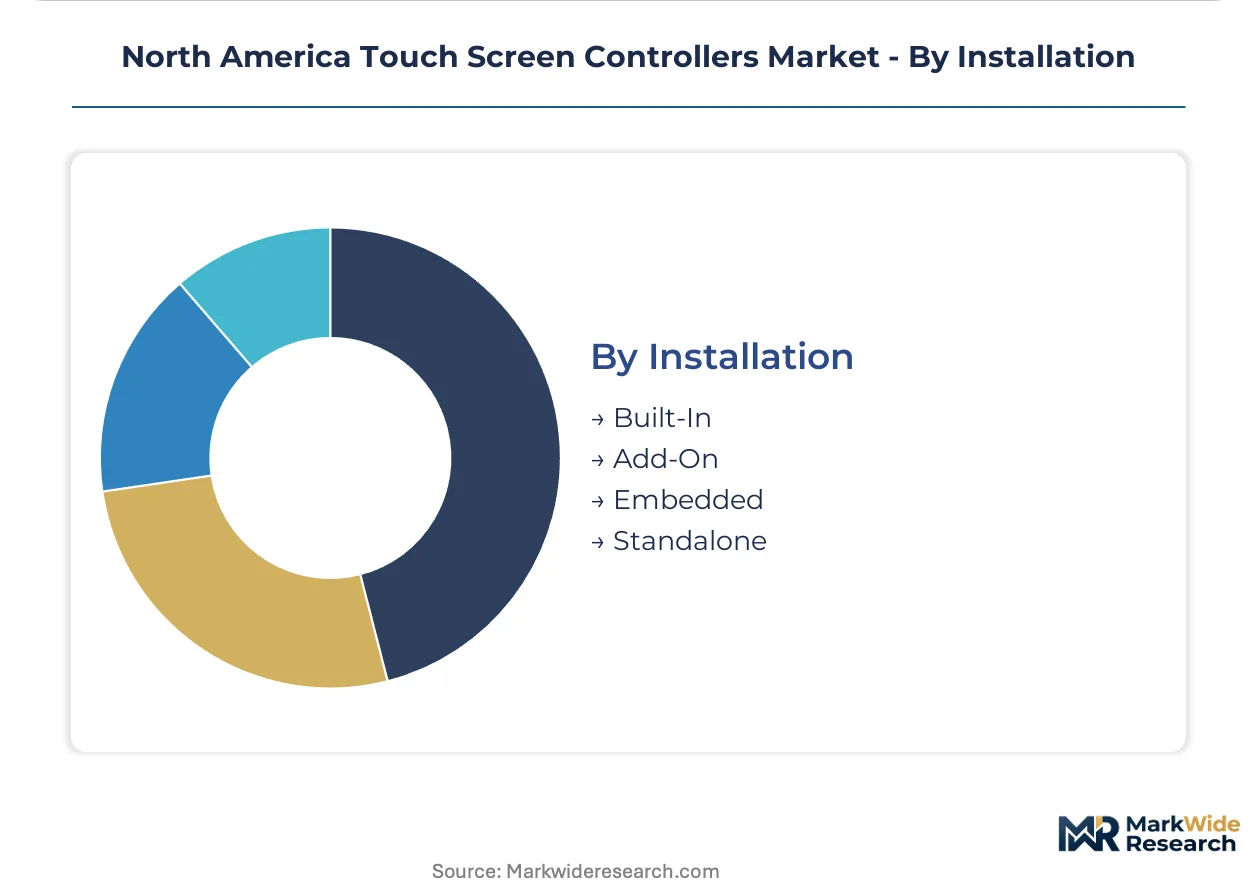
- Built-In:Controllers ship pre-integrated within display module assemblies. Texas Instruments leverages Dallas-based fabrication to supply built-in configurations for Detroit-area automotive suppliers seeking reduced supply chain complexity.
- Add-On:Retrofit controllers attach to existing displays through flex cable or board-to-board connectors. Aftermarket automotive channels in the Southwest absorb FCC Part 15 redesign costs to maintain market access amid 2023 emission limit updates.
- Embedded:Die-level integration places touch sensing directly on display driver substrates. System designers in California and Texas integrate embedded controllers to reduce component counts and electromagnetic interference vulnerability.
- Standalone:Discrete controller modules connect via I2C or SPI to host processors. Industrial HMI retrofits in Wisconsin and Illinois favor standalone modules for field upgradeability without full display replacement.
Embedded configurations dominate procurement volume, while Add-On installations climb fastest through aftermarket automotive and industrial upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-35 corridor freight rail network and cross-border pipeline infrastructure anchor North American electronics manufacturing, enabling just-in-time controller deliveries between Texas semiconductor foundries and Michigan automotive assembly plants.
United States
Michigan's automotive corridor generates concentrated demand for ASIL-B qualified controllers as Detroit-area OEMs consolidate purchasing around fewer electromagnetic compatibility-certified suppliers. The FCC enforces Part 15 unintentional radiator limits that constrain controller emissions in the 2.4 GHz band. Dallas-based fabrication facilities supply built-in controller configurations directly to Tier 1 suppliers in Warren and Livonia, compressing traditional distribution channels.
Canada
Ontario assembly plants in Windsor and Oakville specify controllers meeting simultaneous ISED radio equipment certification and USMCA rules of origin requirements. Health Canada references electromagnetic immunity standards for medical device integration. Toronto-area diagnostic equipment manufacturers prioritize antimicrobial surface coatings and IEC 60601-1-2 compliance for imaging system interfaces.
Mexico
Aguascalientes and Guanajuato automotive assembly expansion creates controller demand for center-stack infotainment without tariff exposure under USMCA provisions. The national standards body electrical safety markings create compliance coordination with FCC and ISED requirements. Northern border states concentrate maquiladora electronics assembly serving California consumer electronics design hubs.
North America Touch Screen Controllers Market Competitive Landscape
On the supply side, the industry is consolidating around mixed-signal semiconductor specialists capable of simultaneous functional safety and electromagnetic compatibility certification. Tier 1 automotive purchasing consortiums compress vendor qualification timelines from twenty-four to eighteen months. Two strategic archetypes dominate: integrated device manufacturers with captive fabrication and fabless designers outsourcing to foundry partners. Competitive moves center on ASIL-C certification acceleration and direct OEM vendor-managed inventory agreements replacing distributor stocking arrangements.
Among Dallas-based integrated manufacturers, Texas Instruments Incorporated anchors the captive fabrication archetype through analog design heritage and direct automotive supply agreements. Infineon Technologies and NXP Semiconductors represent the European-headquartered specialists competing via dedicated automotive microcontroller divisions and pressure-sensitive portfolio extensions. These three exemplify the qualification-intensive positioning required for Detroit-area purchasing consolidation.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Infineon Technologies |
| Analog Devices Inc |
| NXP Semiconductors |
| Microchip Technology Incorporated |
| Silicon Laboratories |
| Broadcom Inc |
| Integrated Device Technology Inc |
| Semtech Corporation |
| Others |
Value Network & Pricing Analysis
The I-35 corridor freight rail network connects Texas semiconductor foundries with Michigan automotive assembly plants, and its freight cost dynamics amplify pricing power for captive-fabrication suppliers while forcing fabless competitors into premium positioning to absorb logistics and tariff exposure.
Pricing Analysis
Three-tier pricing structure across automotive-grade ASIL-certified, industrial-standard, and economy aftermarket levels governs controller procurement. Price differentiation hinges on ISO 26262 certification tier and volume commitment scale, with ASIL-C qualified modules commanding substantial premiums over uncertified alternatives. Pricing pressure stems from indium tin oxide substrate volatility squeezing module margins. Aftermarket automotive channels exhibit highest price sensitivity, while Detroit OEM purchasing consortiums prioritize qualification reliability over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for transparent conductor substrates. Controller die fabrication concentrates in Taiwan, South Korea, and the United States, with raw material dependencies spanning silicon wafers, rare earth oxides, and specialty analog front-end components. Single-source vulnerability in Chinese indium processing feeds from concentrated mining capacity. Distribution runs through authorized distributors serving Tier 1 automotive accounts, with direct vendor-managed inventory agreements displacing traditional stocking arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Voice and gesture interfaces from Amazon Alexa Auto and Google Assistant represent a substitution threat that touch controller incumbents must neutralize through haptic differentiation and safety-critical integration depth.
For Market Incumbents: Build certification moats by accelerating ASIL-C qualification timelines and securing dual FCC-ISED laboratory accreditation to compress competitor vendor approval windows. Deepen backward integration into analog front-end design talent pools in Austin and Silicon Valley to offset compensation inflation. Defend against ultrasonic touch sensing substitutes by embedding haptic drivers directly into system-on-chip architectures. For New Entrants and Emerging Players: Pursue industrial HMI retrofit opportunities in Wisconsin food processing and Illinois pharmaceutical packaging where washdown compliance requirements displace membrane switches with sealed capacitive panels. Target Mexico automotive assembly expansion in Aguascalientes and Guanajuato under USMCA rules of origin provisions. Establish go-to-market partnerships with regional distributors holding existing Tier 2 industrial relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from European semiconductor parents seeking to divest North American automotive microcontroller divisions lacking scale against Texas Instruments and NXP. Long-term viability rests on ASIL certification capability and captive fabrication access rather than pure design licensing. Monitor FCC Part 15 certification backlog duration as an inflection indicator for new entrant competitive pressure.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-C Certification Acceleration | Shortens eighteen-month validation cycles to capture Detroit purchasing consortium consolidation. |
| Dual FCC-ISED Laboratory Accreditation | Eliminates cross-border testing redundancy for USMCA zone supplier qualification. |
| Haptic Driver System-on-Chip Integration | Collapses discrete component counts while creating ultrasonic touch substitution defense. |
| Vendor-Managed Inventory Agreements | Replaces distributor stocking arrangements with direct Tier 1 automotive supply control. |
| Mexico Manufacturing Footprint Expansion | Captures Aguascalientes and Guanajuato assembly demand without tariff exposure. |
Research Methodology
The analysis maps capacitive, resistive, infrared, and optical controller architectures, each validated through procurement directors at Tier 1 automotive suppliers, analog design leads at semiconductor firms, and industrial equipment OEMs. Primary interviews with FCC certification laboratory managers, distributor inventory planners, and automotive platform engineers combined with secondary validation against SEC semiconductor filings, FCC equipment authorization databases, and vehicle production registries. Bottom-up die shipment estimates and top-down automotive content-per-vehicle calculations provided triangulation anchors.
Assumptions held fixed include USMCA trade zone integrity, FCC Part 15 emission limit stability, and ISO 26262 functional safety standard continuity, while variables included automotive electrification penetration rates and voice interface substitution velocity. Segmentation modeling spanned product type, end-user sector, technology tier, and installation configuration across the projection horizon. CAGRs derived from polynomial trend fitting against historical semiconductor shipment data and automotive platform lifecycle timing, with specific inputs including Michigan automotive purchasing consortium qualification timelines and Texas semiconductor foundry utilization rates.
Sensitivities concentrate around indium supply disruption, FCC certification queue lengthening, and voice interface adoption acceleration in Ford, GM, and Stellantis vehicles. Forecasts reflect these documented assumptions with acknowledged revision triggers from regulatory harmonization negotiations or rare earth processing capacity shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Cordless Phone Battery Market
Electronic Components
Electronic Shelf Label Market
Electronic Components
Electric Capacitor Market
Electronic Components
Digital Class-D Amplifier Market
Electronic Components
Blockchain in Electronic Component Market
Electronic Components
AC Adapter Market
Electronic Components
Audio Capacitor Market
Electronic Components
Tower Mounted Amplifier Market
Electronic Components
China Data Converter Market
Electronic Components
Chip Shield Market
Electronic Components
Audio Amplifier Market
Electronic Components
Europe Water Cooled Capacitors Market
Electronic Components
Wearable Technology Component Market
Electronic Components
Laser Direct Structuring (LDS) Antenna Market
Electronic Components
Radiation Hardened Electronics Market
Electronic Components
North America Safety Relay and Timers Market