
 US Frequency Control and Timing Devices Market | 2026-2036
US Frequency Control and Timing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
US Frequency Control and Timing Devices Market Insights
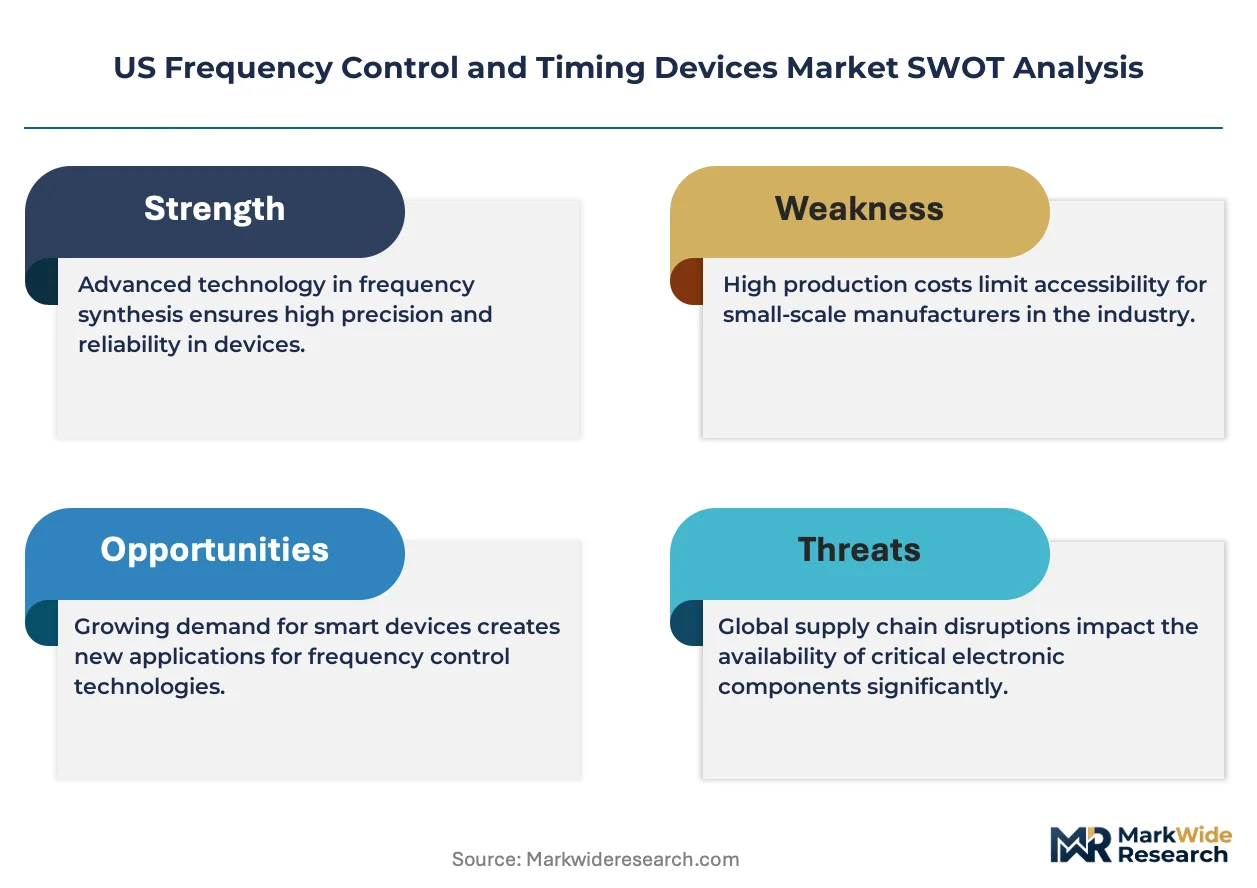
Precision timing IP licensing is rewriting margin distribution across the value chain as semiconductor firms seek recurring revenue streams. SiTime Corporation leverages MEMS programmable architecture to displace legacy quartz in 5G infrastructure slots. Texas Instruments Incorporated anchors broad portfolio breadth across temperature-compensated and oven-controlled oscillator lines. Microchip Technology Inc. specializes in integrated clock generation for aerospace and defense programs with stringent phase noise requirements.
Frequency control and timing devices govern signal synchronization through quartz crystal resonators, MEMS silicon resonators, or surface acoustic wave elements stabilized against thermal drift via compensation circuits or ovenized enclosures, with phase noise and Allan deviation serving as critical performance parameters. Oscillators and timing modules command the deepest margin pools as system designers prioritize integrated solutions over discrete crystal sourcing. TCXO and OCXO technologies retain dominance in satellite navigation and military communications where holdover stability requirements exclude MEMS alternatives, though MEMS is displacing conventional quartz in consumer wireless and automotive edge nodes.
FAA certification standards for avionics timing, NHTSA reliability mandates for automotive sensor fusion, and FCC spectrum coordination rules for 5G mmWave deployment collectively elevate product qualification barriers and extend design-in cycles. The Department of Commerce export controls on advanced frequency sources to certain foreign entities further constrain supplier flexibility and reinforce domestic manufacturing investments. Stakeholders must monitor CHIPS Act disbursement timelines and foundry capacity commitments to calibrate capital allocation between legacy quartz expansion and MEMS process development.
Market Dynamics
CHIPS Act capital disbursements are concentrating oscillator and resonator fabrication capacity in Texas and Arizona foundry clusters, pulling suppliers away from legacy offshore quartz supply chains and into domestic semiconductor ecosystems.
Growth Catalysts
- Defense Electronics Procurement:Pentagon programs for satellite navigation and secure communications mandate OCXO and TCXO precision timing components, creating sustained demand pull through classified procurement channels.
- FCC 5G mmWave Spectrum Coordination:Base station density requirements for millimeter-wave deployment multiply timing device counts per cell site, expanding oscillator volume in telecommunications infrastructure.
- MEMS Process Maturation:Silicon resonator manufacturing yields now match quartz economics at automotive temperature ranges, opening sensor fusion and edge computing sockets previously closed to programmable timing.
Market Restraints
- Quartz Raw Material Concentration:High-purity lascas quartz feedstock concentrates in limited Appalachian and Brazilian mining operations, exposing crystal resonator supply to geographic disruption risk.
- OCXO Thermal Budget Constraints:Oven-controlled oscillator power consumption exceeds satellite and portable defense system energy envelopes, freezing MEMS alternatives out of holdover stability applications.
- Department of Commerce Export Controls:Advanced frequency source licensing to restricted foreign entities constrains revenue diversification for domestic precision timing manufacturers.
Strategic Opportunities
- Autonomous Vehicle Sensor Fusion:Lidar and radar synchronization requirements in Detroit and California automotive development centers create qualified socket opportunities for AEC-Q200 certified timing modules.
- CHIPS Act Incentives:Domestic packaging facility construction in Arizona draws oscillator suppliers into captive foundry partnerships with preferential capacity allocation.
- Space-Qualified MEMS:NASA and Space Force radiation-hardening programs are qualifying silicon resonators for low-earth orbit constellations, opening a premium tier previously quartz-exclusive.
Industry Challenges
- FAA Certification Timeline Compression:DO-254 and DO-178C avionics software and hardware qualification cycles extend 18-24 months, delaying revenue recognition for new timing product introductions.
- Hybrid Quartz-MEMS Integration Complexity:System architects struggle to partition holdover stability requirements between legacy oven-controlled oscillators and emerging silicon resonators in unified clock trees.
- Phase Noise Specialist Scarcity:RF engineering talent with Allan deviation and jitter measurement expertise concentrates in defense contractors, constraining commercial product development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Frequency Control and Timing Devices Market |
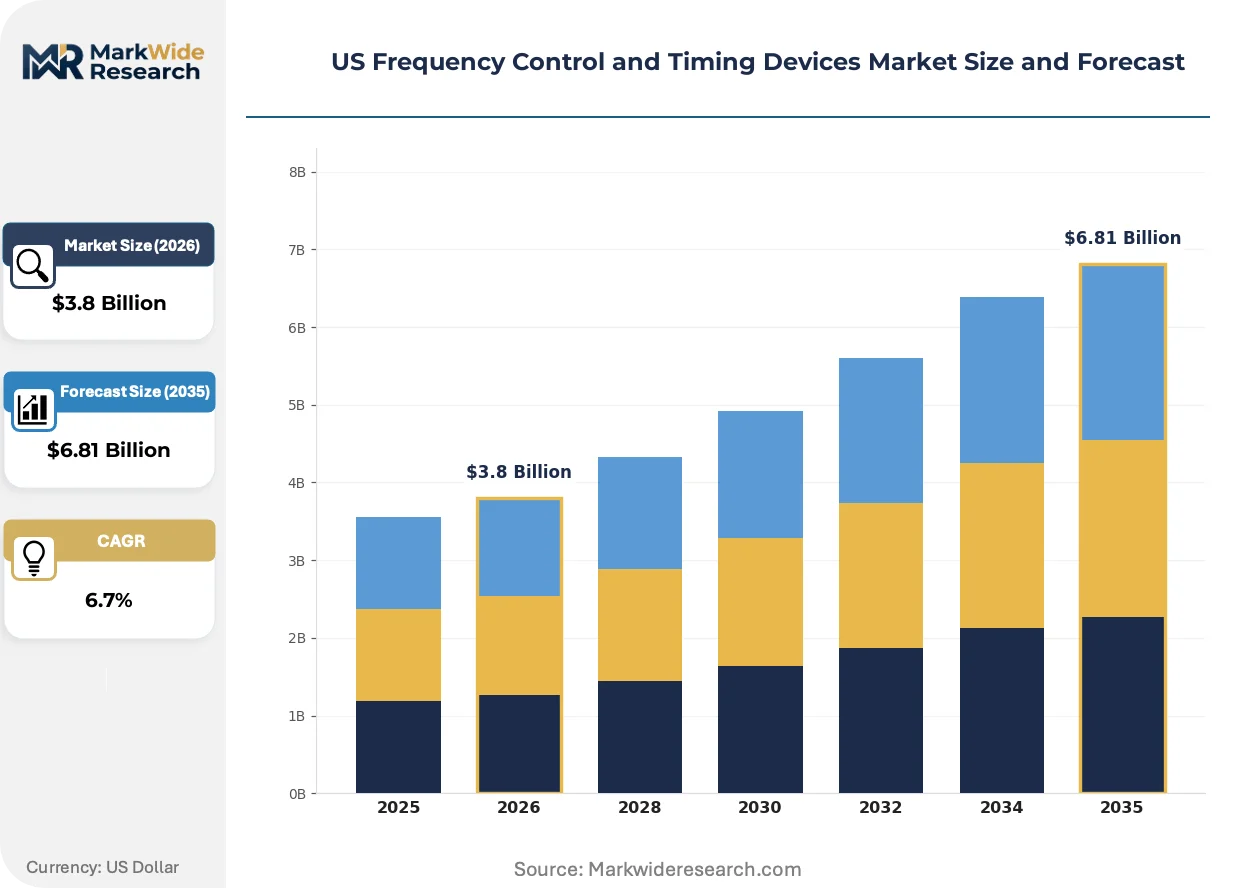
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quartz Crystals, Oscillators, Timing Modules, Frequency Synthesizers End User: Telecommunications, Consumer Electronics, Aerospace, Industrial Automation Technology: MEMS, SAW, TCXO, OCXO Application: Wireless Communication, Automotive, Medical Devices, Embedded Systems |
| Companies Covered | Microchip Technology Inc., SiTime Corporation, Texas Instruments Incorporated, Abracon, Murata Manufacturing Co. Ltd, Kyocera Corporation, TXC Corporation, Rakon Limited, Seiko Epson Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Frequency Control and Timing Devices Market Trends and Innovations
Programmable MEMS architectures are collapsing the traditional quartz customization cycle, enabling software-defined frequency configuration that eliminates oscillator SKU proliferation and accelerates design-in velocity.
MEMS temperature-compensated oscillators with in-situ programmable drive strength and frequency pull are rendering obsolete the quartz TCXO trim-and-test model that required crystal blank lapping for each target frequency. 5G infrastructure OEMs in Texas and California are adopting these devices at volume, compressing oscillator qualification from months to weeks and eliminating overseas crystal fab dependencies.
FAA Advisory Circular 20-152B and updated DO-160G environmental testing standards are tightening phase noise and g-sensitivity requirements for commercial avionics timing. These mandates force oscillator suppliers to dual-source quartz and MEMS qualification paths, extending development budgets while creating barrier-to-entry moats against unqualified competitors in the satellite navigation and terrain avoidance system markets.
Prime contractors for defense and aerospace programs are consolidating vendor lists around qualified domestic timing sources, displacing the historical distributor-led procurement model. This concentration shifts pricing power to oscillator manufacturers with in-house foundry relationships and TS16949/AS9100 certifications, particularly visible in Colorado and Florida defense corridor procurement offices where sole-source justifications now favor captive supply chains over spot-market crystal purchasing.
US Frequency Control and Timing Devices Market Segmentation
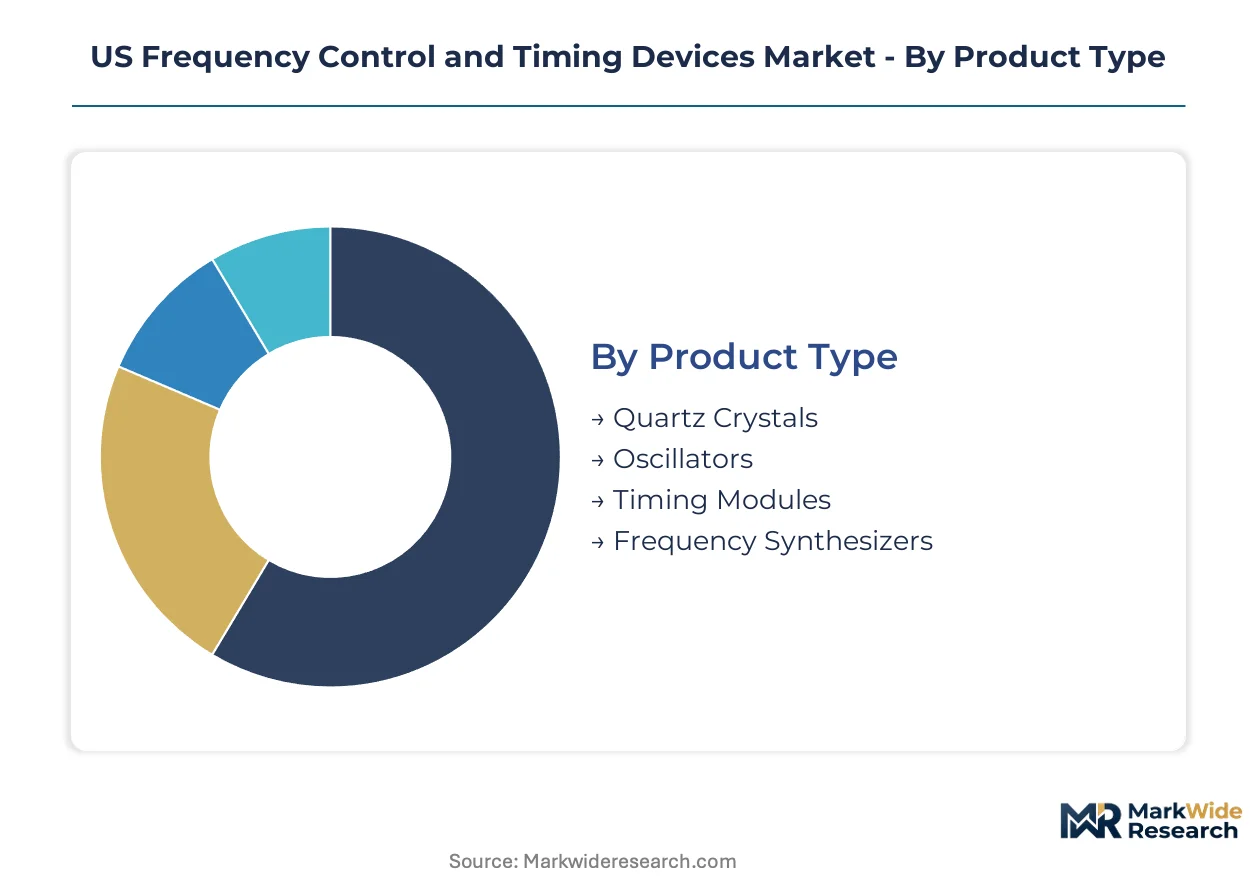
Frequency control and timing devices fragment across multiple technical dimensions, each imposing distinct qualification barriers, margin structures, and aftermarket service requirements. Procurement patterns vary sharply between defense programs demanding traceable OCXO lineages and consumer electronics sourcing MEMS oscillators through distributor channels.
Product Type:
After-sales service intensity escalates dramatically from passive crystal blanks through oven-controlled oscillators, with thermal management failures in OCXOs requiring field calibration support that quartz resonators never demand.
- Oscillators:Active timing circuits integrating resonators with driver amplifiers and compensation electronics. Texas and Arizona foundry clusters concentrate procurement for 5G infrastructure and defense applications where phase noise specifications exclude passive alternatives. CHIPS Act incentives are pulling oscillator assembly into domestic packaging facilities.
- Timing Modules:Multi-output clock generators with integrated PLLs and jitter attenuation. Automotive sensor fusion programs in Detroit and California development centers specify AEC-Q200 qualified modules with in-system configurability. MEMS-based architectures are collapsing traditional quartz customization cycles.
- Quartz Crystals:Passive resonator blanks requiring external oscillator circuits. Appalachian and Brazilian lascas feedstock concentration exposes supply chains to geographic disruption.
- Frequency Synthesizers:Programmable multi-frequency sources for software-defined radios and test equipment. Pentagon secure communications programs mandate domestic fabrication with export-controlled PLL IP.
By volume, Quartz Crystals leads. By growth pace, Timing Modules is expanding most quickly.
End User:
Cost tier stratification separates defense procurement with sole-source qualification requirements from consumer electronics spot purchasing through distribution.
- Telecommunications:Base station and optical transport infrastructure demanding sub-100 femtosecond jitter performance. FCC 5G mmWave spectrum coordination rules multiply timing device counts per cell site across Texas and California deployment corridors. Volume concentration in infrastructure OEMs compresses pricing through multi-year supply agreements.
- Aerospace:Satellite navigation and avionics systems requiring FAA DO-254 and DO-178C certification. Colorado and Florida defense corridors consolidate vendor lists around qualified domestic sources with AS9100 traceability.
- Consumer Electronics:Smartphones and wearables driving MEMS oscillator adoption through programmable frequency agility.
- Industrial Automation:Precision motion control and robotics synchronization in Midwest manufacturing hubs.
Telecommunications commands the deepest revenue pool. Aerospace shows the steepest margin expansion trajectory.
Technology:
Technology maturity curves separate field-proven quartz compensation methods from emerging silicon resonator architectures still penetrating radiation-hardened applications.
- TCXO:Temperature-compensated oscillators using analog or digital correction circuits to stabilize frequency drift. Satellite navigation systems in Pentagon procurement channels specify TCXOs for holdover stability where MEMS alternatives fail thermal envelope constraints.
- MEMS:Silicon resonators manufactured on standard CMOS foundry processes. Automotive edge computing sockets in Detroit development centers adopt programmable MEMS for sensor fusion timing.
- OCXO:Oven-controlled oscillators maintaining resonators at constant temperature through heated enclosures. Power consumption exceeds portable defense system budgets.
- SAW:Surface acoustic wave devices for high-frequency filtering and timing in wireless handsets.
TCXO retains installed base dominance. MEMS is gaining share fastest in new design-ins.
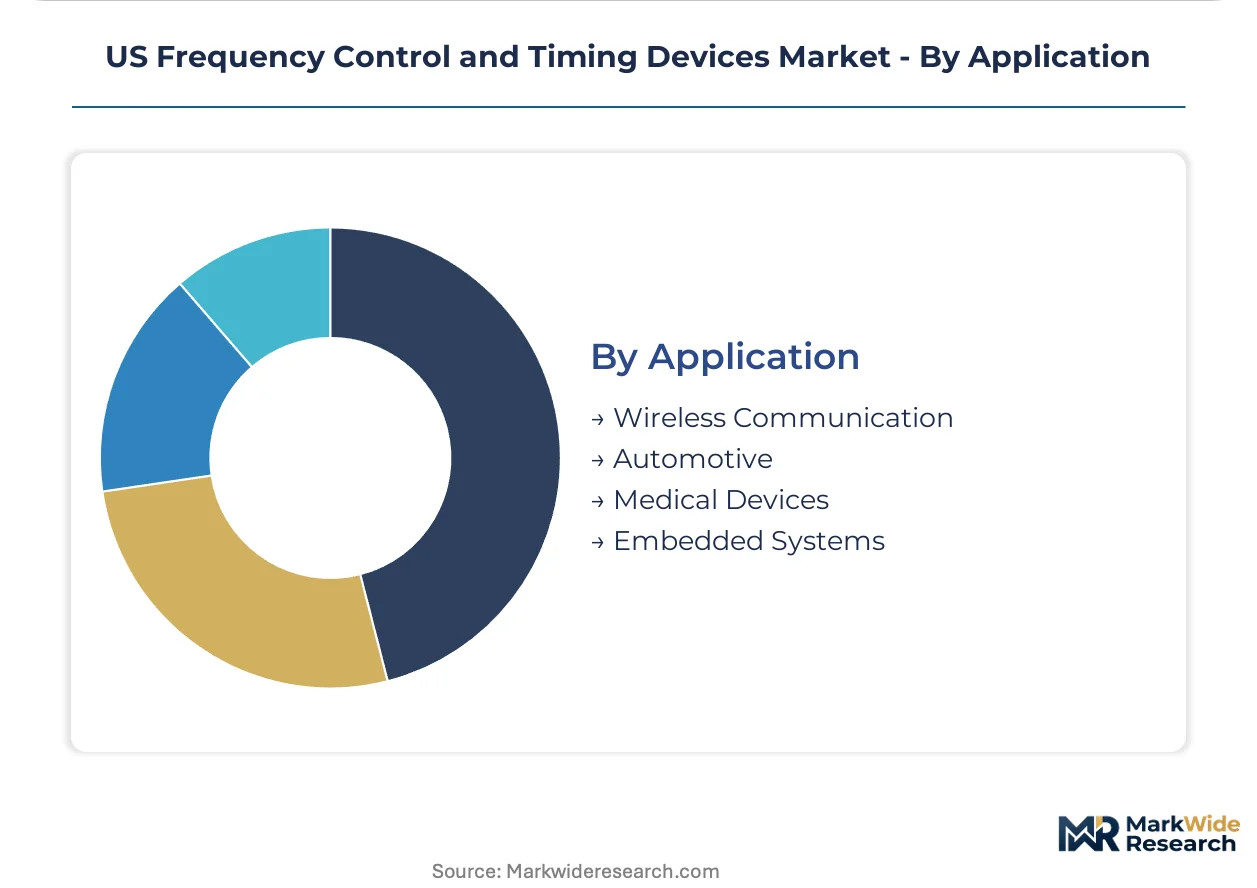
Application:
Application-driven qualification timelines stretch from weeks for consumer wireless to years for FAA-certified avionics, fragmenting supplier competitive dynamics.
- Wireless Communication:5G macro cells, small cells, and mmWave backhaul demanding tight phase noise specifications. FCC spectrum coordination enforcement elevates product qualification barriers for base station timing.
- Automotive:Lidar and radar synchronization for autonomous vehicle sensor fusion. NHTSA reliability mandates extend AEC-Q200 testing cycles.
- Embedded Systems:Industrial IoT and edge computing nodes driving volume through programmable timing adoption.
- Medical Devices:Imaging and diagnostic equipment requiring low-phase-noise references for signal processing accuracy.
Wireless Communication leads by unit volume. Automotive shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense contractors in Colorado and Florida exhibit the lowest price elasticity, absorbing premium OCXO costs for holdover stability, while consumer electronics distributors in California operate on thin margins where MEMS displacement of quartz drives aggressive cost-down cycles.
Texas
CHIPS Act foundry construction in Austin and Dallas draws oscillator suppliers into captive packaging partnerships with preferential capacity allocation. NHTSA automotive reliability mandates push Detroit-tier suppliers to qualify AEC-Q200 timing modules in Texas development centers. The Austin-San Antonio corridor concentrates MEMS process engineering talent for programmable timing architectures.
Arizona
TSMC and Intel packaging facility investments in Phoenix create regional demand pull for precision timing components in advanced node semiconductor manufacturing. Department of Commerce export controls on frequency sources reinforce domestic fabrication commitments from suppliers seeking Pentagon procurement channels. The Phoenix-Tucson corridor hosts emerging oscillator assembly operations serving defense and aerospace programs.
California
5G infrastructure OEMs in San Jose and San Diego adopt software-configurable MEMS oscillators, compressing qualification cycles from months to weeks. FCC mmWave spectrum coordination rules multiply timing device counts per base station across Los Angeles and Bay Area deployment corridors. Consumer electronics distribution through Southern California channels operates on volume-driven spot purchasing with minimal sole-source qualification.
Colorado
Satellite navigation and secure communications programs in Colorado Springs and Denver mandate OCXO precision timing with traceable defense procurement lineages. FAA DO-254 and DO-178C certification requirements for avionics timing extend design-in cycles 18-24 months. The Colorado Springs defense corridor consolidates vendor lists around qualified domestic sources with AS9100 traceability, displacing distributor-led procurement.
Florida
Space Force and NASA radiation-hardening programs in Cape Canaveral and Orlando qualify silicon resonators for low-earth orbit constellations. Pentagon classified procurement channels for satellite timing components create sustained demand pull through sole-source justification processes. The Space Coast corridor favors oscillator manufacturers with in-house foundry relationships and domestic fabrication certifications.
US Frequency Control and Timing Devices Market Competitive Landscape
Programmable-architecture specialists and legacy quartz incumbents split the market between MEMS displacement momentum and entrenched holdover stability requirements. The vendor base concentrates around three strategic archetypes: fabless MEMS designers leveraging CMOS foundry partnerships, integrated device manufacturers with captive crystal fabrication, and precision timing specialists serving defense-aerospace qualification channels. Capacity expansion into CHIPS Act-subsidized packaging facilities and technology licensing for programmable frequency IP dominate competitive moves.
Within the programmable-architecture tier, SiTime Corporation and Microchip Technology Inc. exemplify the fabless MEMS model displacing quartz in consumer and automotive sockets. Texas Instruments Incorporated anchors the integrated manufacturer archetype with broad portfolio breadth across temperature-compensated and oven-controlled oscillator lines. These three companies occupy positions spanning the technology maturity curve from emerging silicon resonators to field-proven quartz compensation methods.
| Leading Market Players |
|---|
| Microchip Technology Inc. |
| SiTime Corporation |
| Texas Instruments Incorporated |
| Abracon |
| Murata Manufacturing Co. Ltd |
| Kyocera Corporation |
| TXC Corporation |
| Rakon Limited |
| Seiko Epson Corporation |
| Others |
Pricing and Supply Chain Analysis
CHIPS Act disbursement timelines function as a regulatory chokepoint that compresses pricing tier spreads between legacy quartz oscillators and emerging MEMS alternatives while simultaneously reshaping domestic supply chain geography toward Arizona and Texas foundry clusters.
Pricing Analysis
After-sales service revenue from OCXO field calibration and thermal management support drives lifetime value for precision timing manufacturers. Three-tier pricing structure across defense-qualified, automotive-certified, and consumer-grade levels separates Pentagon procurement channels from spot-market distributor purchasing. Cost compression in consumer wireless sockets intensifies as programmable MEMS architectures eliminate quartz customization premiums. Defense contractors in Colorado Springs exhibit the lowest price sensitivity, while California consumer electronics distributors operate on thinnest margins.
Supply Chain Analysis
Extended payment terms from packaging facility operators in Arizona and Texas are restructuring supplier cash flow dynamics across oscillator assembly tiers. High-purity lascas quartz feedstock draws from Appalachian and Brazilian mining operations, while CMOS foundry capacity rests on Taiwan and South Korea wafer fabrication. Single-source vulnerability concentrates in Department of Commerce export-controlled PLL IP for frequency synthesizers. Distribution runs through prime contractor vendor lists in defense corridors and volume distributor channels in consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from defense procurement cyclicality as Pentagon satellite navigation and secure communications programs accelerate oscillator demand through classified channels.
For Market Incumbents: Pre-empt MEMS displacement in automotive sensor fusion by qualifying AEC-Q200 timing modules in Detroit development centers before programmable silicon resonators capture lidar synchronization sockets. Lock in captive foundry partnerships with TSMC Arizona and Intel Phoenix packaging facilities to secure preferential capacity allocation against emerging fabless competitors.
For New Entrants and Emerging Players: Establish a beachhead in space-qualified MEMS timing for Space Force low-earth orbit constellations, where NASA radiation-hardening programs are opening premium tiers previously exclusive to quartz. Target Florida Space Coast procurement offices with domestic fabrication certifications and AS9100 traceability as the most penetrable defense corridor.
For Investors and Strategic Acquirers: Fabless MEMS designers with CMOS foundry partnerships and programmable frequency IP portfolios represent the highest-conviction acquisition archetype for the 5-10 year window. Monitor CHIPS Act capacity commitment announcements as the inflection signal for capital allocation timing between legacy quartz expansion and silicon resonator process development.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Foundry Partnership | Captive packaging capacity with TSMC Arizona secures Pentagon procurement channel access. |
| Programmable MEMS Qualification | Software-defined frequency configuration collapses quartz customization cycles for 5G infrastructure. |
| Defense-Aerospace Certification Investment | AS9100 and DO-254 compliance creates sole-source justification moats in Colorado Springs. |
| Radiation-Hardening Development | NASA qualification opens space timing sockets previously exclusive to oven-controlled oscillators. |
| Automotive AEC-Q200 Certification | Sensor fusion timing modules qualify for Detroit autonomous vehicle development programs. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with defense procurement officers, automotive platform engineers, RF timing specialists, and CMOS foundry operations managers; and secondary validation through SEC 10-K filings, Department of Commerce export control notices, FCC spectrum coordination dockets, and Pentagon budget justification documents. Bottom-up oscillator shipment estimates triangulated against top-down CHIPS Act capital disbursement tracking.
Forecast inputs span product type, technology maturity, end-user qualification tier, and application-driven design-in velocity across the projection horizon. CAGRs derive from segment-level volume build-ups calibrated to foundry capacity expansion timelines and defense procurement cycle phasing. Phase noise specification tightening in FAA Advisory Circular 20-152B and NHTSA reliability mandate enforcement serve as demand-side modeling anchors.
Sensitivities concentrate around CHIPS Act disbursement delays, export control expansion to additional frequency source categories, and MEMS radiation-hardening qualification setbacks. Forecasts reflect assumptions on defense budget continuity and automotive sensor fusion adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Wearable Technology Component Market
Electronic Components
Docking Station Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
Global Circuit Protection Market
Electronic Components
Intel Motherboards Market
Electronic Components
Loudspeaker Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
TWS and Noise-Cancelling Headphone with MEMS Chip Market
Electronic Components
Power Resistor Market
Electronic Components
Robotic Flat Cable Market
Electronic Components
Breadboards Market
Electronic Components
Resonators Market
Electronic Components
Flexible Heater Market
Electronic Components
Camera Battery Charger Market
Electronic Components
Capacitive Stylus Pen Market
Electronic Components
SAW Filters Market