
 Plastics in Consumer Electronics Market | 2026-2036
Plastics in Consumer Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Plastics in Consumer Electronics Market Intelligence
UL 94 flammability certification is redrawing supplier eligibility for plastics destined for consumer electronics housings and internal components. SABIC leverages its broad resin portfolio to sustain qualification across multiple OEM tiers. Covestro AG differentiates through specialty polycarbonate grades engineered for thin-wall smartphone designs. LG Chem Ltd. anchors its position with integrated caprolactam-to-nylon supply chains serving Korean electronics brands.
Plastics in consumer electronics encompass thermoplastic and thermoset polymers formulated for dimensional stability, electromagnetic shielding compatibility, and injection-molded precision in devices typically operating between minus forty and eighty-five degrees Celsius. These materials primarily enable lightweight structural enclosures, thermal management, and electrical insulation in portable and stationary electronic hardware. Polycarbonate and ABS blends dominate casing applications where optical clarity and impact resistance command premium positioning, while nylon compounds capture connector segments demanding fatigue endurance and miniaturization tolerance. Polypropylene variants occupy cost-sensitive internal component niches where dimensional precision requirements moderate relative to housing grades.
The EPA oversees flame-retardant chemical assessments under TSCA while the EU REACH regulation restricts halogenated compounds in electronics plastics, jointly elevating demand for phosphorus-based and mineral-filled alternatives. China's GB standards and the EU RoHS Directive converge on limiting heavy metal content, compelling reformulation across multinational material portfolios. Stakeholders must monitor evolving extended producer responsibility frameworks and substance restriction timelines to preempt compliance-driven supply disruptions.
Market Dynamics
EU RoHS Directive substance restrictions and REACH flame-retardant limitations are forcing polycarbonate and ABS reformulation across OEM portfolios, compressing supplier qualification timelines while elevating phosphorus-based alternatives.
Growth Catalysts
- Recycled polymer mandates:Smartphone OEMs are expanding post-consumer recycled content requirements in housing specifications, pulling rPET and rABS volumes into electronics-grade streams.
- REACH Annex XVII expansion:ECHA restrictions on halogenated flame retardants are redirecting formulation R&D toward phosphorus-nitrogen synergists and mineral fillers.
- Shenzhen manufacturing cluster density:Concentrated molding capacity around Pearl River Delta electronics assemblers reduces logistics friction for just-in-time resin delivery.
Market Restraints
- Caprolactam price volatility:Nylon 6 feedstock costs fluctuate with benzene derivative markets, compressing margin stability for connector-grade compounds.
- East Asian supply concentration:Over half of specialty polycarbonate pellet capacity sits within 500 kilometers of Shanghai, creating geographic risk exposure.
- Thin-wall molding limits:Sub-millimeter smartphone casing tolerances restrict material candidates to ultra-high-flow polycarbonate grades, narrowing supplier pools.
Strategic Opportunities
- India PLI scheme electronics manufacturing:Production-linked incentives for mobile device assembly are pulling molding investment toward Noida and Chennai corridors.
- Bio-based nylon 56:Pentamethylenediamine-derived alternatives to petrochemical polyamides offer carbon intensity reduction for premium laptop chassis segments.
- Direct OEM resin procurement:Bypassing distributor tiers through volume commitments and technical service integration captures margin and specification control.
Industry Challenges
- UL 94 V-0 requalification timelines:Reformulated halogen-free compounds require 12-18 month certification cycles, freezing supplier switches during product development windows.
- Electromagnetic compatibility integration:Conductive filler loading for EMI shielding degrades mechanical properties, demanding iterative alloy optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastics in Consumer Electronics Market |
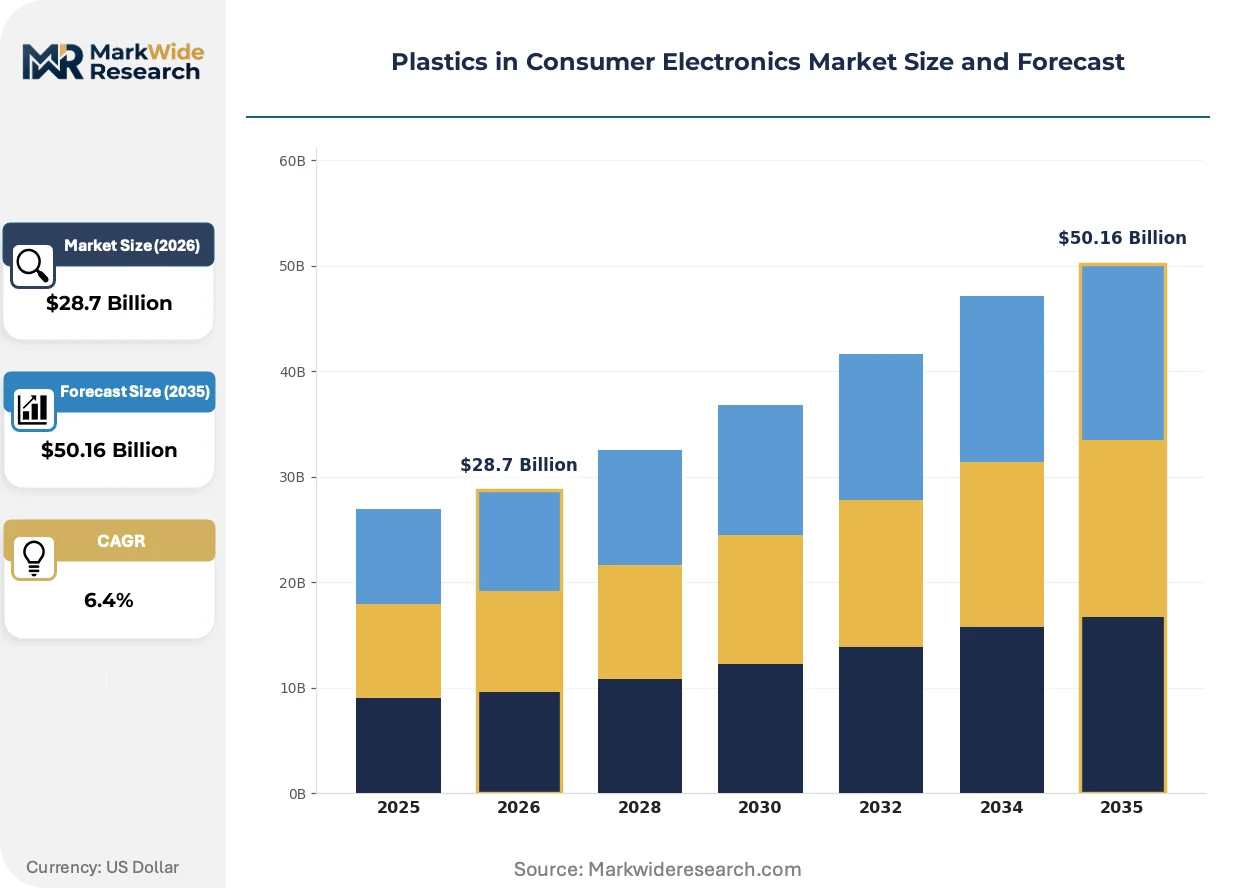
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Tablets, Wearable Devices Application: Casing, Internal Components, Connectors, Housing Material: Polycarbonate, ABS, Nylon, Polypropylene End User: Consumers, Retailers, OEMs, Distributors |
| Companies Covered | SABIC, Mitsubishi Chemical Group Corporation, Celanese Corporation, Dow Inc., Trinseo PLC, Covestro AG, LG Chem Ltd., LyondellBasell Industries N.V., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastics in Consumer Electronics Market Strategic Shifts & Innovations
Material substitution and regulatory chemistry constraints are compressing traditional polymer hierarchies while opening formulation white space for bio-derived and recycled feedstocks.
Mass-balanced polycarbonate is decomposing the virgin-petroleum supply chain for transparent electronics housings. Laptop and monitor OEMs are qualifying ISCC PLUS-certified grades at scale. The technology is decomposing historical price premiums for sustainable alternatives, forcing conventional producers to accelerate circular content integration.
EU REACH restrictions on medium-chain chlorinated paraffins are eliminating legacy flame-retardant synergists from power-cable and adapter housing compounds. Compounders are reformulating with aluminum phosphinate and melamine polyphosphate systems. Korean electronics brands face compressed compliance deadlines relative to multinational peers, accelerating local technical service investment.
Smartphone OEMs are consolidating resin specifications across model tiers to capture volume pricing and reduce qualification overhead. Procurement teams are shifting from grade-by-grade sourcing to platform-level master agreements with compounders. This consolidation is most visible among Shenzhen-based contract manufacturers serving multiple brand labels simultaneously.
Plastics in Consumer Electronics Market Segmentation
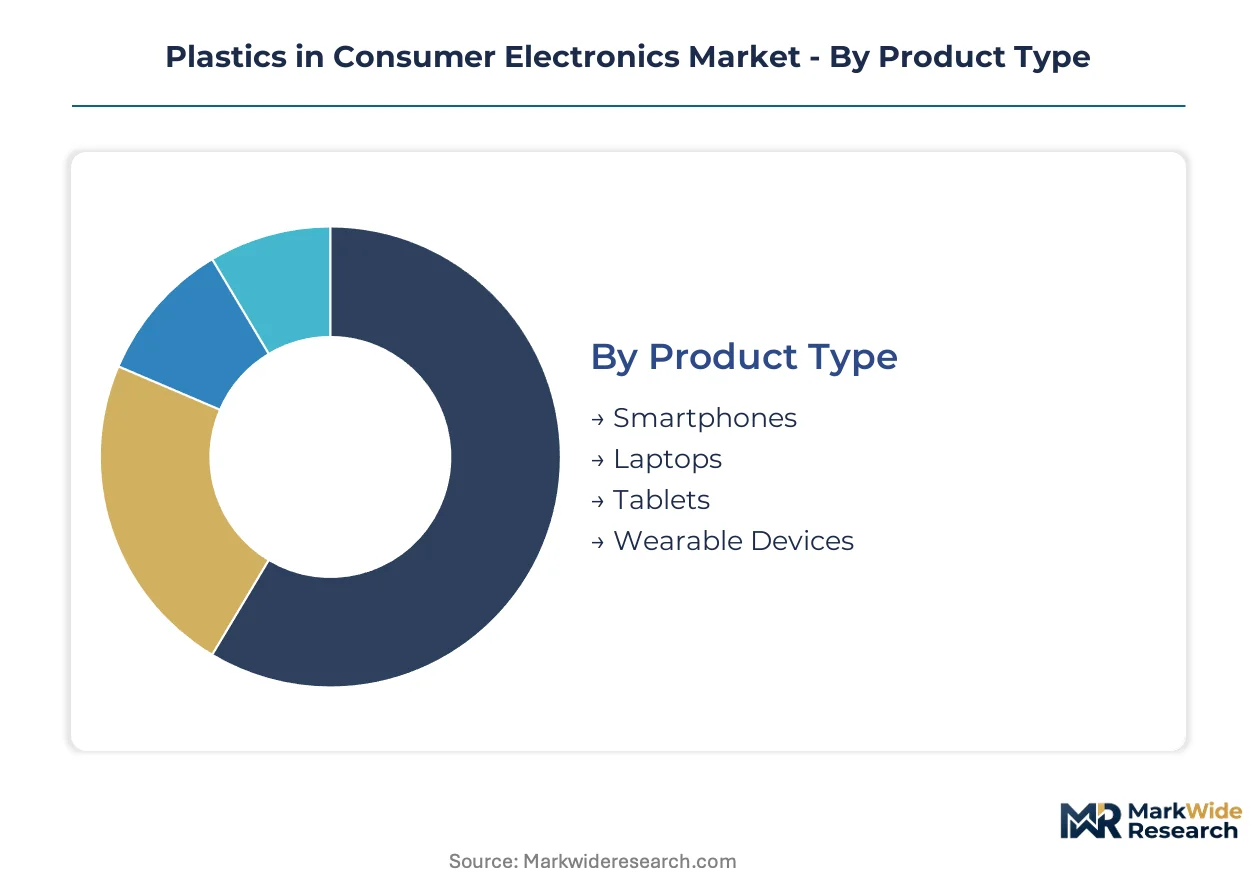
Segmentation in plastics for consumer electronics traces how resin specifications cascade through distinct procurement channels. OEM direct sourcing, contract manufacturer consignment, and distributor spot purchasing each filter material grades differently, creating tiered qualification barriers that reshape competitive access.
Product Type:
Smartphone and laptop OEMs source housing-grade polycarbonate through direct resin partnerships, while tablet and wearable assemblers rely more heavily on compounder distribution networks for smaller volume batches.
- Smartphones:Ultra-thin polycarbonate and glass-filled nylon formulations dominate flagship chassis production. Shenzhen-based contract manufacturers concentrate molding capacity for premium housing grades, driven by sub-millimeter tolerance requirements and UL 94 V-0 certification mandates.
- Laptops:High-flow ABS blends and recycled-content polycarbonates capture clamshell enclosures and display bezels. Korean electronics brands anchor demand through integrated supply chains serving Seoul-Incheon manufacturing corridors, constrained by EPEAT registration and carbon footprint disclosure requirements.
- Tablets:Cost-optimized PC/ABS alloys serve education and enterprise segments through distributor channels.
- Wearable Devices:Miniaturized nylon 12 and bio-based TPE grades address fitness band and smartwatch housings.
Smartphones dominate installed base. Wearable devices are where expansion concentrates.
Application:
Cost tier stratification separates housing applications commanding resin premiums from internal components competing on cycle-time efficiency.
- Casing:Optical-grade polycarbonate and metallic-effect ABS blends enable aesthetic differentiation in retail-facing surfaces. EU REACH substance restrictions on halogenated flame retardants are redirecting formulation toward phosphorus-based systems in external housing grades.
- Internal Components:Reinforced polypropylene and mineral-filled nylons address structural brackets and shielding frames. Chinese GB standards compliance drives local compounder qualification for power supply enclosures serving domestic OEMs.
- Connectors:High-heat nylon 46 and LCP alternatives serve board-to-board interfaces demanding reflow solder compatibility.
- Housing:Recycled-content ABS and mass-balanced polycarbonates satisfy emerging post-consumer mandates from multinational brands.
Casing commands margin premiums. Internal components scale through volume concentration.
Material:
Supply concentration around East Asian petrochemical complexes shapes regional availability and qualification timelines for each resin family.
- Polycarbonate:Bisphenol-A derived aromatic polycarbonates deliver optical clarity and impact resistance for transparent electronics housings. Mass-balanced and chemically recycled grades are gaining ISCC PLUS certification traction among laptop OEMs seeking Scope 3 reductions.
- ABS:Acrylonitrile-butadiene-styrene terpolymers balance processability and surface aesthetics for cost-sensitive enclosures. Caprolactam price volatility transmits through styrene monomer markets, compressing margin stability for compounders serving connector-grade specifications.
- Nylon:Polyamide 6 and 66 compounds dominate fatigue-critical connector and hinge applications.
- Polypropylene:Homopolymer and copolymer grades occupy internal structural components where dimensional precision requirements moderate.
Polycarbonate leads value contribution. Nylon climbs the fastest on miniaturization demands.
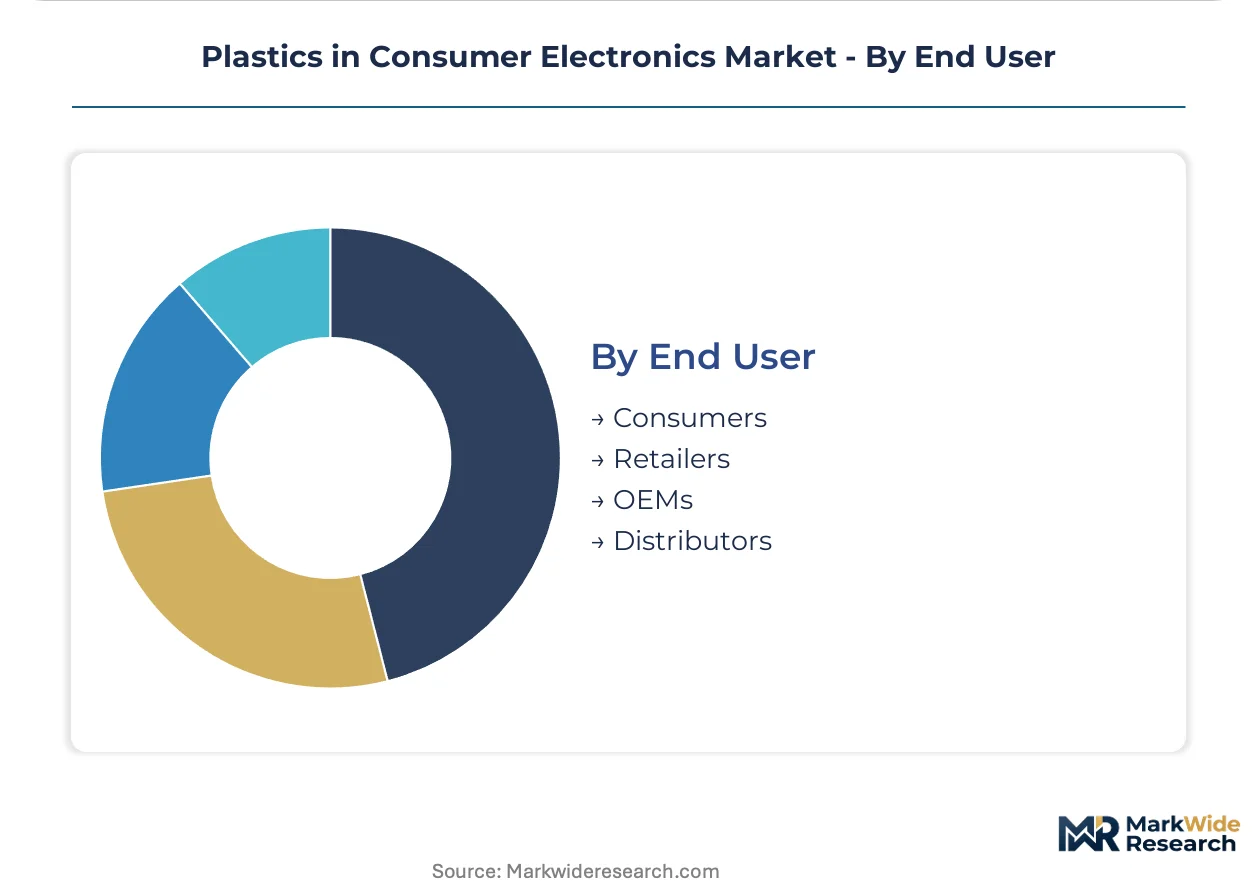
End User:
Procurement authority concentration varies sharply across the value chain, with OEMs increasingly bypassing distributor tiers for strategic resin categories.
- Consumers:Indirect demand manifests through brand sustainability preferences and repairability expectations that cascade into OEM material specifications. ESG disclosure requirements are elevating recycled content thresholds in premium device segments.
- Retailers:Private-label electronics and warranty service networks influence secondary material demand for replacement housings and repair parts. Amazon and European electronics retailers are imposing packaging and product-level recycled content standards on supplier bases.
- OEMs:Apple, Samsung, and Dell direct material qualification and volume contracting for strategic resin grades.
- Distributors:Avnet, Arrow, and regional compounders serve spot demand and smaller assembler volumes.
OEMs dominate specification authority. Retailers are where sustainability pressure concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smartphone OEM procurement teams concentrate purchasing authority in four East Asian manufacturing clusters. Contract manufacturers in these corridors dictate resin qualification timelines and volume commitments. Each geography presents distinct regulatory exposure and supply chain configuration.
China
Shenzhen-based contract manufacturers drive housing-grade polycarbonate demand for flagship smartphone assembly. GB standards compliance and MIIT substance restrictions compel local compounder qualification for power supply enclosures. The Pearl River Delta corridor concentrates over half of specialty polycarbonate pellet capacity within 500 kilometers of Shanghai.
South Korea
Seoul-Incheon manufacturing corridors anchor demand for high-flow ABS blends and recycled-content polycarbonates in laptop clamshell production. MFDS and REACH-aligned domestic regulations enforce EPEAT registration and carbon footprint disclosure requirements. LG Chem Ltd. maintains integrated caprolactam-to-nylon supply chains serving Samsung Electronics and domestic electronics brands.
United States
EPA TSCA flame-retardant assessments and state-level extended producer responsibility frameworks elevate demand for phosphorus-based alternatives in adapter housings. California and Texas host molding operations serving North American distribution channels. The EPA oversees chemical safety evaluations while California's SB 54 imposes recycled content mandates on electronics packaging.
Germany
EMA and ECHA regulatory stringency drives reformulation toward halogen-free flame retardants in connector-grade compounds. The KBA and federal environmental agencies coordinate with EU REACH Annex XVII expansion timelines. Bavaria and North Rhine-Westphalia host compounder technical centers serving Central European OEM specification development.
Japan
METI circular economy roadmaps and JIS standards compliance shape resin qualification for precision connector applications. Kanto and Kansai manufacturing belts concentrate molding capacity for camera module and semiconductor packaging components. Domestic OEMs prioritize miniaturization tolerance in board-to-board interface materials.
Plastics in Consumer Electronics Market Key Industry Players
Player mix skews toward diversified petrochemical conglomerates with integrated resin-to-compound capabilities. Market structure concentrates around five to seven suppliers capable of UL 94 V-0 certification across multiple polymer families. Strategic archetypes include integrated petrochemical majors, specialty compounders with technical service differentiation, and regional distributors serving spot demand. Competitive moves center on backward integration into recycled feedstock streams and geographic expansion toward India PLI scheme corridors.
Within the integrated petrochemical tier, SABIC, Covestro AG, and LG Chem Ltd. occupy positions defined by broad resin portfolios and regional manufacturing footprints. SABIC leverages qualification breadth across OEM tiers. Covestro AG exemplifies specialty polycarbonate differentiation. LG Chem Ltd. anchors Korean electronics brand supply chains through captive caprolactam integration. These three represent distinct competitive vectors: certification breadth, material specialization, and vertical supply chain control.
| Leading Market Players |
|---|
| SABIC |
| Mitsubishi Chemical Group Corporation |
| Celanese Corporation |
| Dow Inc. |
| Trinseo PLC |
| Covestro AG |
| LG Chem Ltd. |
| LyondellBasell Industries N.V. |
| BASF SE |
| Others |
Cost & Logistics Intelligence
UL 94 V-0 certification gates both supplier qualification and price stratification across electronics-grade polycarbonate and ABS tiers, compressing margins for uncertified compounders while concentrating premium pricing power among qualified resin portfolios. OEM procurement teams leverage this dual function to extract volume concessions during platform-level master agreement negotiations.
Pricing Analysis
Cost-plus contracts with benzene derivative indexation dominate nylon 6 and caprolactam-linked formulations, transmitting feedstock volatility directly into connector-grade compound pricing. Price differentiation rests on UL 94 certification tier and volume scale, with smartphone OEM direct procurement commanding steepest discounts. Pricing pressure stems from recycled-content mandates forcing reformulation investment without immediate pass-through mechanisms. Contract manufacturers in Shenzhen corridors exhibit highest price sensitivity; Korean electronics brands show lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Just-in-time resin delivery preferences among Shenzhen contract manufacturers clash with strategic stockpile tendencies of Korean electronics brands facing REACH compliance deadlines. Supply concentrates in China, South Korea, and Germany, with specialty polycarbonate pellet capacity clustered within 500 kilometers of Shanghai. The chain draws from bisphenol-A, styrene monomer, and caprolactam feedstocks. Single-source vulnerability runs through East Asian petrochemical complexes. Distribution runs through compounder technical centers serving direct OEM partnerships and regional distributor tiers for spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among smartphone and laptop OEMs consolidating resin specifications across model tiers, fragmenting pricing leverage for compounders without platform-level master agreements.
For Market Incumbents: Consolidate backward integration into chemically recycled and mass-balanced feedstock streams to preempt ISCC PLUS certification requirements from Apple and Dell procurement teams. Expand technical service capacity in India PLI scheme corridors before molding investment saturates Noida and Chennai. Defend margin position by locking Korean electronics brands into long-term caprolactam supply contracts ahead of bio-based nylon 56 scale-up. For New Entrants and Emerging Players: Lead with halogen-free flame-retardant compound qualification for power-cable and adapter housing segments where UL 94 V-0 requalification timelines have frozen incumbent supplier switches. Target wearable device miniaturization grades—nylon 12 and bio-based TPE—where specification consolidation lags smartphones. Pursue direct OEM resin procurement bypassing Avnet and Arrow distribution tiers through volume commitments bundled with electromagnetic compatibility integration services. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chemically recycled polycarbonate capacity buildouts, favoring asset-light compounders with ISCC PLUS certification over integrated petrochemical majors with legacy virgin-resin infrastructure. Acquisition targets should display qualification breadth across multiple OEM tiers and captive positions in India PLI scheme corridors. Watch for ECHA REACH Annex XVII expansion timelines as the signal indicating reformulation R&D spend inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstocks | ISCC PLUS certification secures qualification for laptop OEM Scope 3 reduction mandates. |
| Technical Center Expansion in India | Noida and Chennai corridors capture PLI scheme electronics manufacturing pull. |
| Halogen-Free Flame-Retardant Qualification | REACH Annex XVII compliance opens power-cable housing substitution windows. |
| Platform-Level Master Agreements | Consolidated resin specifications capture volume pricing from Shenzhen contract manufacturers. |
| Caprolactam-to-Nylon Supply Chain Control | Captive integration anchors Korean electronics brand relationships against bio-based alternatives. |
Research Approach
Initial hypotheses were tested against primary input from resin procurement directors at smartphone OEMs, compounder technical service leads, and contract manufacturing sourcing managers, then refined through secondary validation against SEC 10-K filings, customs and trade data from East Asian petrochemical corridors, and ECHA REACH substance restriction databases. Bottom-up volume modeling across polycarbonate, ABS, nylon, and polypropylene grades triangulated with top-down OEM bill-of-materials analysis.
Variance decomposition across the projection horizon isolates feedstock price fluctuation, regulatory timeline uncertainty, and OEM specification consolidation velocity as primary forecast drivers. Segmentation dimensions include device category, application tier, material family, and procurement channel authority. CAGRs derive from elasticity-adjusted demand curves incorporating recycled-content mandate penetration and miniaturization tolerance requirements in connector-grade specifications.
Forecasts assume regulatory continuity in EU REACH Annex XVII and EPA TSCA flame-retardant assessment regimes; material policy shifts would require re-modeling. Revision becomes warranted when smartphone OEM recycled-content thresholds or ECHA substance restriction timelines cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Ceramic Capacitors Market
Electronic Components
Data Acquisition Card Market
Electronic Components
Americas MPU Market
Electronic Components
China Data Converter Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Audio Amplifier Market
Electronic Components
PTC Resettable Device Market
Electronic Components
Flex-Rigid PCB Market
Electronic Components
Lowpass Filters Market
Electronic Components
Microspeaker Market
Electronic Components
Coaxial Coupler Market
Electronic Components
Global Microfluidic Components Market
Electronic Components
Digital Isolator Market
Electronic Components
Capacitor Kits Market
Electronic Components
Hydrogen Thyratron Market
Electronic Components
Motherboard Market