
 Global Tantalum Capacitors Market | 2026-2036
Global Tantalum Capacitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tantalum Capacitors Market Intelligence
The split between premium-grade solid tantalum and commodity polymer variants is realigning procurement priorities across the supply chain. Panasonic Corporation leverages vertical integration in raw material sourcing to sustain pricing power in high-reliability segments. KEMET Corporation anchors its position through specialized wet tantalum lines for aerospace and defense applications. Murata Manufacturing competes aggressively in surface-mount chip capacitor formats for consumer electronics volume.
Tantalum capacitors store electrical energy using a tantalum pentoxide dielectric layer formed through electrochemical anodization, typically achieving capacitance values from microfarads to several millifarads with voltage ratings up to 50V in compact surface-mount packages. Solid tantalum dominates military and medical applications where failure tolerance approaches zero, while polymer tantalum captures share in telecommunications infrastructure seeking lower equivalent series resistance. Niobium oxide variants occupy a narrowing niche as drop-in alternatives where tantalum supply constraints elevate substitution economics.
RoHS and REACH in Europe restrict hazardous substances and mandate supply chain transparency for conflict minerals, compelling manufacturers to document smelter and refiner origins. Japan's METI promotes domestic capacitor resilience through critical component stockpiling directives, while China's GB standards enforce localized testing protocols for imported passive components. Stakeholders must monitor evolving conflict-mineral disclosure rules and polymer dielectric reliability data as these forces reshape supplier qualification timelines and inventory strategies.
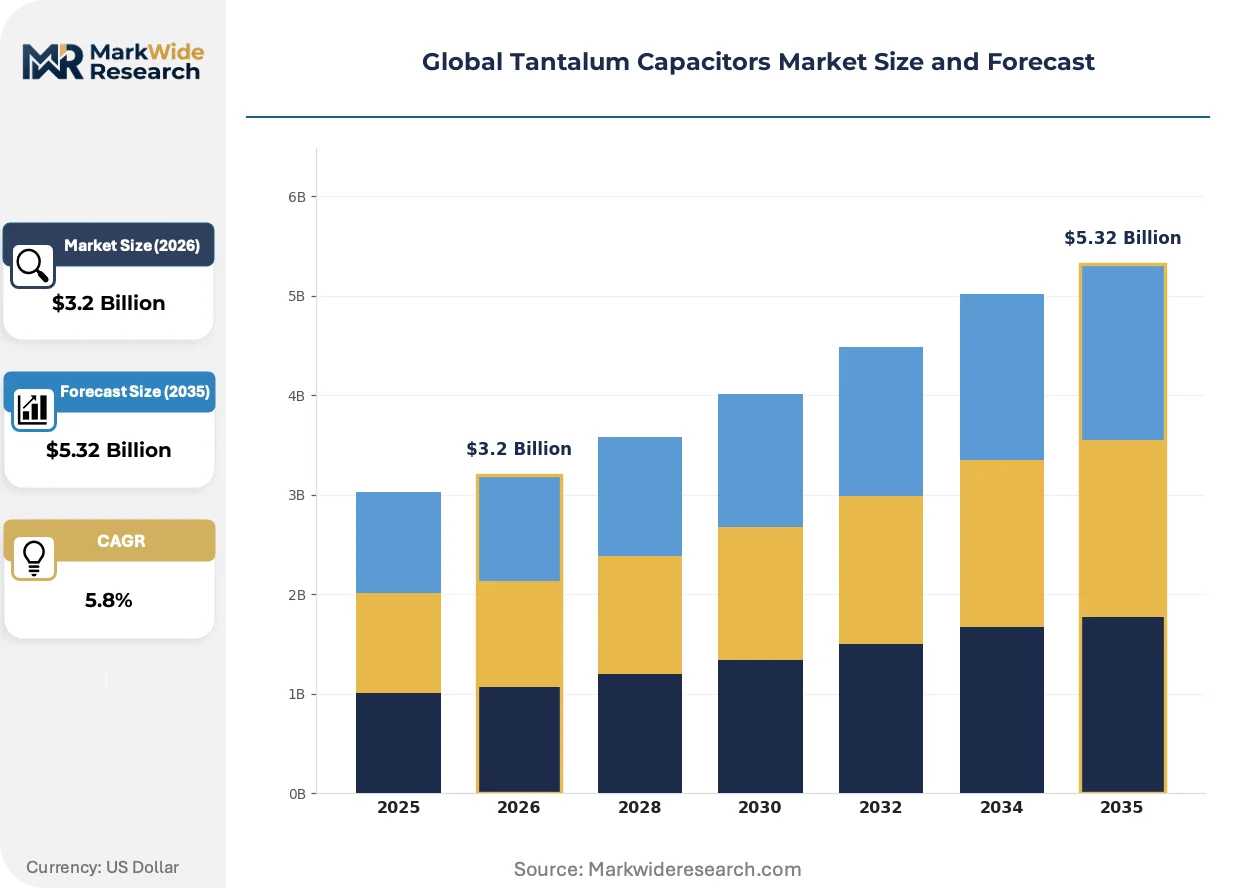
Market Dynamics
Conflict-mineral traceability mandates under EU RoHS and REACH are restructuring supplier qualification timelines, while aerospace reliability specifications tighten dielectric performance thresholds across the value chain.
Growth Catalysts
- Aerospace Reliability Mandates:Stricter failure-tolerance specifications for avionics and satellite systems are elevating demand for solid tantalum dielectrics with demonstrated mean-time-between-failures performance.
- METI Localization Directives:Japan's Ministry of Economy, Trade and Industry stockpiling programs for critical passive components are accelerating domestic surface-mount manufacturing capacity expansion in Osaka and Kyoto industrial clusters.
- Polymer Dielectric Adoption:Telecommunications infrastructure operators are specifying conductive polymer tantalum for base station power supplies to achieve lower equivalent series resistance without volumetric penalties.
Market Restraints
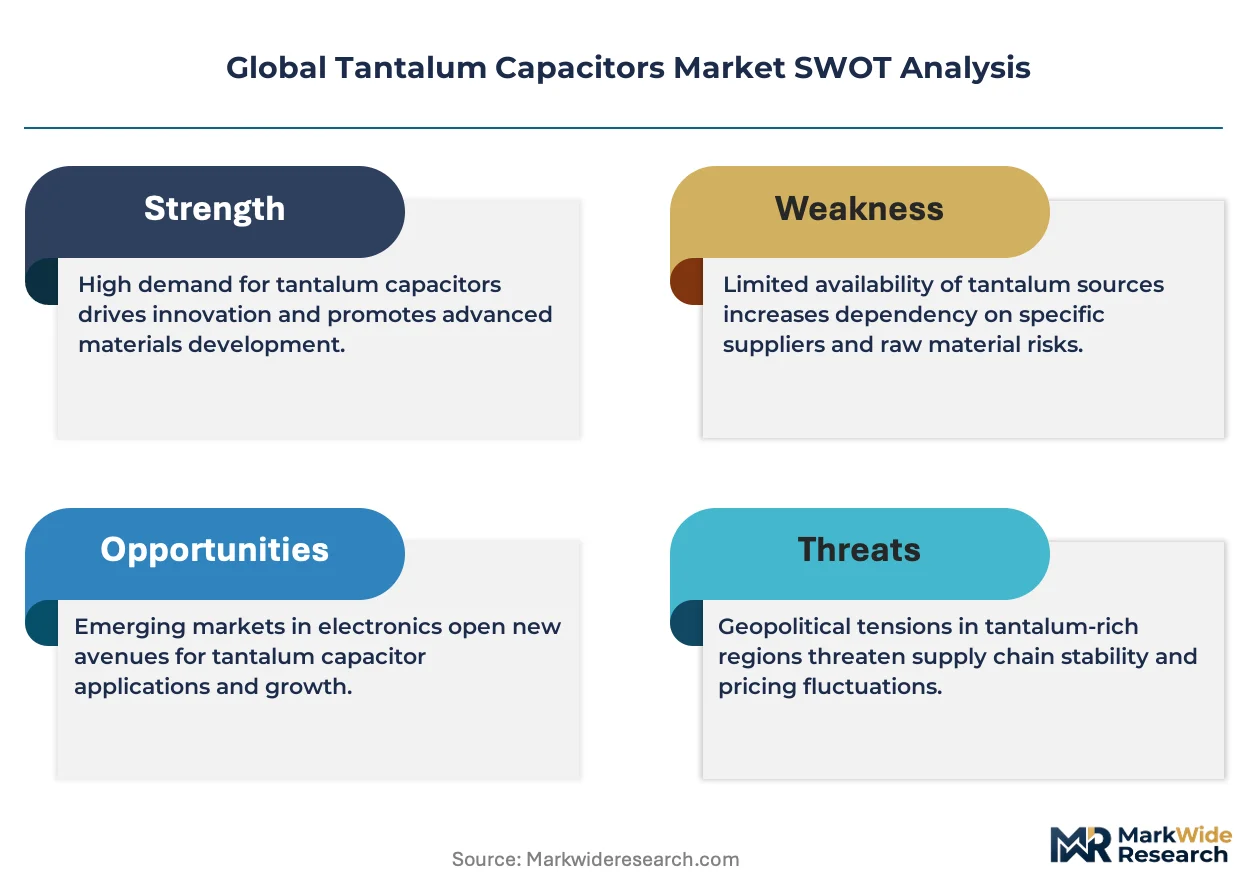
- Tantalum Ore Concentration:Primary tantalum concentrate supply concentrates in Central African mining jurisdictions, exposing processors to geopolitical disruption and smelter audit complexity under OECD conflict-mineral guidelines.
- Niobium Oxide Substitution Economics:Niobium oxide capacitors present technically viable drop-in alternatives where tantalum pentoxide supply constraints elevate relative material costs for standard-grade applications.
- Electrochemical Anodization Throughput Limits:Dielectric formation processes require extended voltage-soak cycles that constrain batch processing velocity and capital efficiency at scale.
Strategic Opportunities
- Medical Implant Miniaturization:Pacemaker and neurostimulator manufacturers are specifying sub-millimeter tantalum chip formats where biocompatibility and hermetic sealing requirements exclude aluminum electrolytic alternatives.
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and passive component production are attracting tantalum capacitor assembly investments to serve domestic telecom and automotive demand.
- REACH Supply Chain Transparency:EU smelter and refiner disclosure requirements create competitive advantage for vertically integrated manufacturers with documented conflict-free sourcing from certified Australian and Brazilian mines.
Industry Challenges
- Electrochemical Process Engineering Talent:Specialized expertise in anodization voltage profiling and electrolyte chemistry formulation remains concentrated among aging technical workforces in Japan and Germany.
- Aerospace Qualification Timelines:MIL-PRF-55365 certification cycles extend 18-24 months for new tantalum chip derivatives, compressing product development returns against shorter consumer electronics design windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tantalum Capacitors Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.32 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Tantalum, Polymer Tantalum, Niobium Oxide, Wet Tantalum Technology: Surface Mount, Through Hole, Hybrid Mounting, Chip Capacitors Application: Consumer Electronics, Aerospace Systems, Defense Equipment, Telecommunications End User: Electronic Manufacturers, Component Distributors, Contract Manufacturers, Research Laboratories |
| Companies Covered | Panasonic Corporation, Murata Manufacturing, KEMET Corporation, Rohm Semiconductor, TDK Corporation, KYOCERA AVX Components Corporation, Samsung Electro-Mechanics, Sunlord Electronics, Vishay Intertechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tantalum Capacitors Market Strategic Shifts & Innovations
Dielectric material science and procurement digitization are converging to reshape how capacitor specifications propagate through electronics manufacturing ecosystems.
Conductive polymer tantalum is absorbing market share in telecommunications power conversion applications where equivalent series resistance below 10 milliohms enables higher switching frequencies. Base station original equipment manufacturers in South Korea and Finland are qualifying these formats for 5G macro cell deployments. This absorption is compressing traditional manganese dioxide solid tantalum volumes in infrastructure segments while preserving premium positioning in military and medical verticals.
REACH Article 33 disclosure obligations are forcing component distributors to maintain blockchain-traceable smelter documentation across every tantalum-bearing stock-keeping unit. European electronics manufacturing service providers now reject supplier shipments lacking ECHA-compliant conflict-mineral reports. Medical device manufacturers in Germany and Switzerland face the steepest compliance velocity requirements as notified body audits integrate supply chain transparency into MDR technical documentation.
Consolidated component distributors are unbundling after-sales technical support from unit pricing, shifting toward subscription-based field application engineering for high-reliability tantalum selection. This model displaces traditional spot-buy procurement for aerospace and defense contractors in the United States and Israel. The transition is most visible in satellite prime contractor supply chains where mission-critical derating analysis now carries separate service fees rather than embedded margin.
Global Tantalum Capacitors Market Segmentation
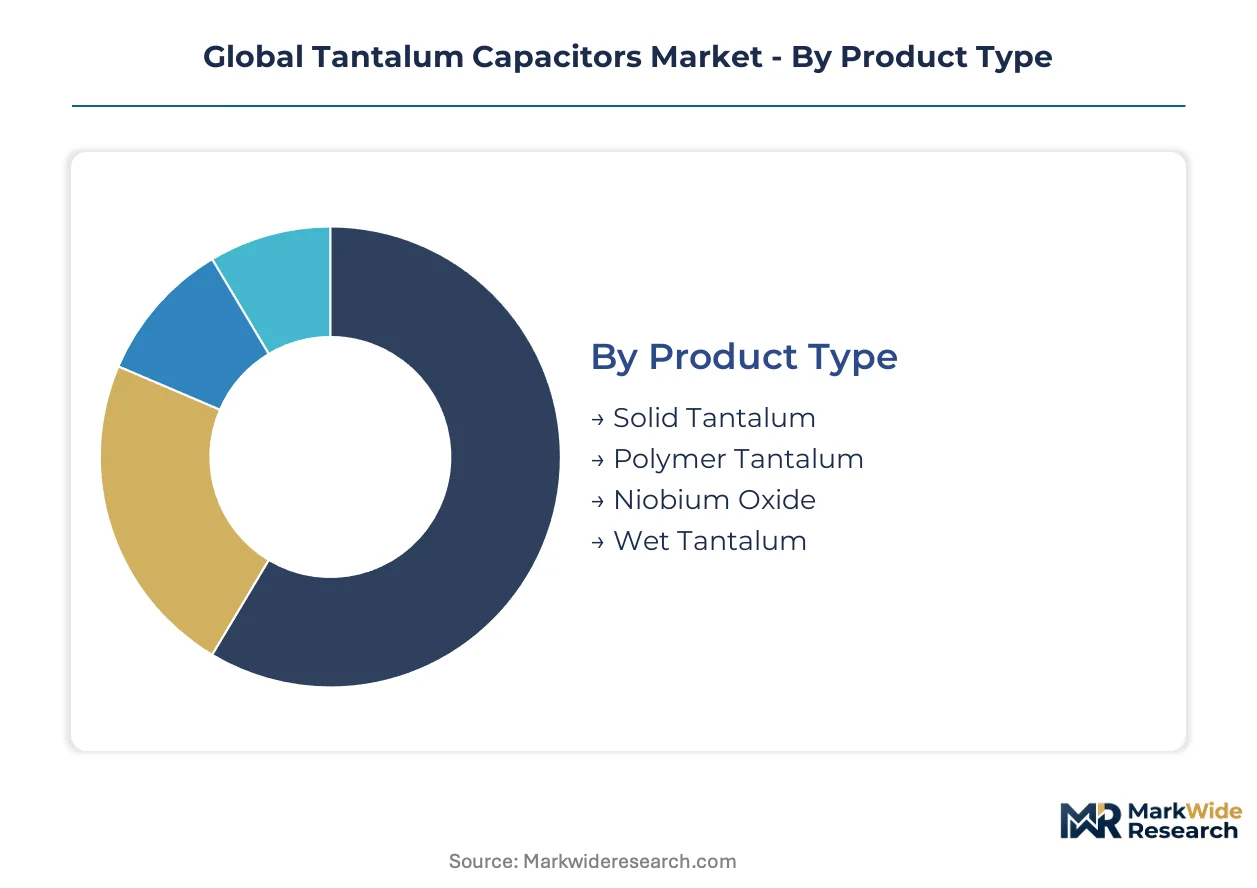
Tantalum capacitor procurement decisions hinge on dielectric reliability requirements, mounting density constraints, and conflict-mineral traceability obligations. Each segmentation dimension captures distinct buyer priorities across defense, medical, and telecommunications verticals.
Product Type:
Dielectric chemistry determines failure tolerance thresholds and equivalent series resistance performance across end-use specifications.
- Solid Tantalum:Manganese dioxide cathode construction achieves volumetric efficiency in hermetically sealed packages. Aerospace avionics manufacturers in the United States and Israel specify MIL-PRF-55365 qualified chips for satellite power distribution where mean-time-between-failures requirements approach zero.
- Polymer Tantalum:Conductive polymer cathode replaces manganese dioxide to reduce equivalent series resistance below 10 milliohms. South Korean 5G base station OEMs are qualifying these formats for macro cell power supplies where switching frequency demands exceed solid tantalum capabilities.
- Niobium Oxide:Drop-in alternative using niobium pentoxide dielectric where tantalum concentrate supply constraints elevate substitution economics for standard-grade consumer applications.
- Wet Tantalum:Liquid electrolyte construction delivers highest capacitance-voltage product in axial leaded formats; defense contractors specify these for missile guidance systems requiring extended temperature operation.
Volume sits with solid tantalum; growth tilts toward polymer tantalum.
Technology:
Mounting methodology constrains board real estate utilization and automated assembly throughput in contract manufacturing environments.
- Surface Mount:Rectangular chip formats with nickel-barrier terminations enable high-speed pick-and-place assembly. Osaka and Kyoto manufacturing clusters in Japan concentrate automated surface-mount capacitor output for consumer electronics and automotive modules.
- Through Hole:Radial and axial leaded construction persists in military and industrial power supplies where mechanical strain relief exceeds surface-mount solder joint reliability.
- Hybrid Mounting:Mixed-format assemblies combining surface-mount density with through-hole mechanical robustness in aerospace power conditioning units.
- Chip Capacitors:Sub-millimeter case sizes address pacemaker and neurostimulator miniaturization where biocompatibility requirements exclude aluminum electrolytic alternatives.
Assembly velocity favors surface mount; reliability premiums sustain through-hole in defense applications.
Application:
End-use reliability specifications stratify procurement qualification timelines and supplier approval hierarchies.
- Consumer Electronics:Smartphones and laptops drive volume demand for compact case sizes with standard reliability grades; supply chain transparency requirements under EU REACH complicate distributor stocking strategies.
- Aerospace Systems:Avionics and satellite subsystems mandate extended temperature cycling and vibration tolerance; stricter EU RoHS reliability mandates are expanding adoption of solid tantalum dielectrics in European satellite prime contractor supply chains.
- Defense Equipment:MIL-PRF qualification cycles extend 18-24 months for new chip derivatives, compressing development returns against shorter design windows in adjacent segments.
- Telecommunications:Base station power conversion specifications are specifying conductive polymer formats for 5G infrastructure deployments in Finland and South Korea.
Consumer electronics dominates unit volume; telecommunications infrastructure is climbing the fastest on polymer dielectric conversion.
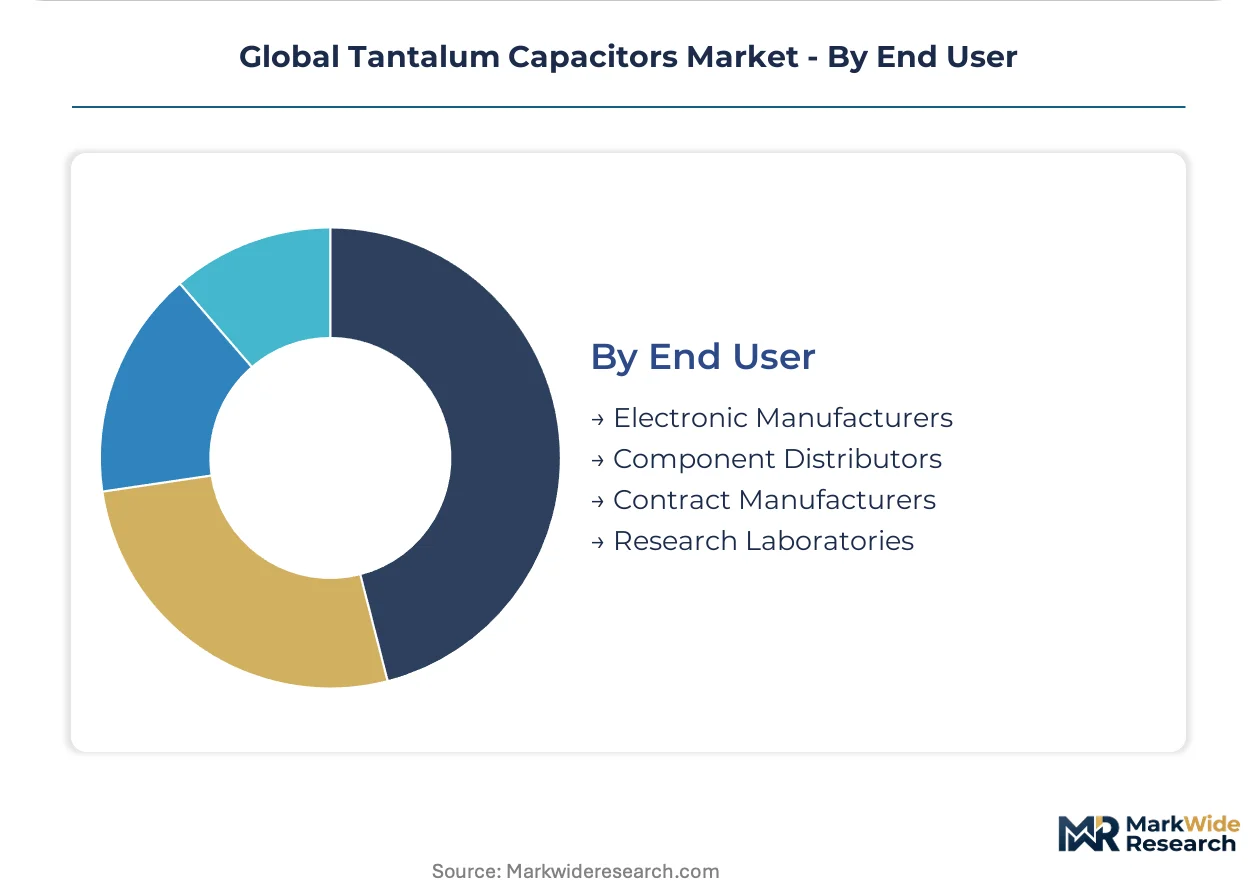
End User:
Procurement channel structure determines technical support intensity and inventory liability allocation across the value chain.
- Electronic Manufacturers:OEMs with captive component engineering teams specify dielectric formulations directly; medical device manufacturers in Germany face steepest REACH Article 33 compliance velocity as notified body audits integrate supply chain transparency.
- Component Distributors:Consolidated distributors are unbundling after-sales field application engineering from unit pricing, shifting toward subscription-based derating analysis for aerospace contractors.
- Contract Manufacturers:Electronics manufacturing service providers in Europe now reject shipments lacking ECHA-compliant conflict-mineral reports across every tantalum-bearing stock-keeping unit.
- Research Laboratories:Prototyping volumes with non-standard specifications and extended qualification support requirements.
Direct procurement concentrates with electronic manufacturers; distributor service model transformation is gaining share fastest in aerospace channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka and Kyoto anchor the densest concentration of surface-mount tantalum capacitor manufacturing worldwide, with METI-backed stockpiling programs accelerating capacity expansion across Japan's Kansai industrial corridor.
Japan
Aerospace reliability mandates from the Japan Aerospace Exploration Agency drive solid tantalum procurement for satellite systems. METI's critical component localization directives channel subsidies toward Osaka-Kyoto manufacturing clusters. Surface-mount output from these hubs supplies domestic automotive and consumer electronics OEMs.
United States
MIL-PRF-55365 qualified capacitors power missile guidance and satellite power distribution for defense primes. FAA airworthiness directives tighten failure-tolerance specifications for commercial avionics. Manufacturing concentrates in Southwest industrial corridors serving aerospace contractors in California and Texas.
Germany
REACH Article 33 disclosure obligations force medical device manufacturers to document conflict-free smelter origins for implantable neurostimulators. ECHA compliance velocity requirements integrate supply chain transparency into MDR technical documentation. Production clusters in Bavaria serve Siemens Healthineers and other notified body-regulated OEMs.
South Korea
5G base station OEMs specify conductive polymer tantalum for macro cell power supplies requiring sub-10 milliohm equivalent series resistance. MFDS medical device regulations parallel EU MDR traceability standards. Busan-Ulsan manufacturing zones export telecommunications-grade capacitors to Finnish and Indian network equipment providers.
India
PLI scheme incentives attract tantalum capacitor assembly investments for domestic telecom infrastructure and automotive electronics. BIS localized testing protocols enforce GB-standard-equivalent validation for imported passive components. Karnataka and Tamil Nadu electronics manufacturing zones concentrate contract assembly capacity for Samsung and Apple supply chains.
Global Tantalum Capacitors Market Key Industry Players
Premium-margin players sit above commodity-margin players across dielectric reliability certification tiers, with aerospace-qualified solid tantalum commanding pricing multiples over standard-grade polymer variants. The vendor base organizes around three strategic archetypes: vertically integrated materials-to-components specialists, defense-focused qualification-heavy incumbents, and high-volume surface-mount scale operators. Consolidation pressures intensify as REACH compliance costs favor documented conflict-free sourcing networks. Capacity expansion and backward integration into tantalum concentrate offtake agreements represent the dominant competitive moves.
Among Japanese fabricators, Panasonic Corporation and Murata Manufacturing occupy positions spanning premium and volume tiers, while KEMET Corporation anchors the defense-aerospace specialist archetype. These three exemplify divergent strategic postures: Panasonic leverages captive raw material sourcing, Murata competes on surface-mount format velocity, and KEMET concentrates qualification-intensive wet tantalum lines for extended-temperature applications.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Murata Manufacturing |
| KEMET Corporation |
| Rohm Semiconductor |
| TDK Corporation |
| KYOCERA AVX Components Corporation |
| Samsung Electro-Mechanics |
| Sunlord Electronics |
| Vishay Intertechnology |
| Others |
Cost & Logistics Intelligence
MIL-PRF-55365 certification requirements from aerospace primes are compressing procurement timelines and forcing suppliers to absorb qualification costs upfront, which concentrates pricing power among Japanese and US fabricators with captive anodization capacity and documented conflict-free tantalum concentrate offtake.
Pricing Analysis
Mean-time-between-failures performance in satellite power distribution anchors value-based pricing for aerospace-grade solid tantalum. Three-tier pricing structure across premium, standard, and economy levels separates MIL-qualified chips from telecommunications polymer variants and consumer-grade manganese dioxide formats. Price differentiation hinges on certification grade and vertical integration depth. Cost compression in standard-grade polymer segments is intensifying because South Korean base station OEMs are consolidating supplier panels. Medical implant manufacturers exhibit lowest price sensitivity due to biocompatibility mandates that exclude aluminum electrolytic substitutes.
Supply Chain Analysis
Freight cost volatility from Central African mining jurisdictions to East Asian processing hubs is amplifying inventory carrying costs for distributors holding ECHA-compliant conflict-mineral documentation. Tantalum concentrate supply concentrates in the Democratic Republic of Congo and Rwanda, with refining capacity concentrated in China and Germany. Raw material dependencies include tantalum pentoxide powder, manganese dioxide cathode material, and conductive polymer formulations. Single-source vulnerability runs through Central African smelter concentration under OECD conflict-mineral guidelines. Distribution runs through consolidated component distributors unbundling field application engineering from unit pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into certified Australian and Brazilian tantalum concentrate offtake has become the decisive competitive lever as REACH disclosure obligations eliminate spot-market sourcing flexibility for European medical device manufacturers.
For Market Incumbents: Deepen captive control over electrochemical anodization capacity in Osaka-Kyoto clusters to defend margin position against niobium oxide substitution in consumer electronics. Lock in 18-24 month MIL-PRF qualification pipelines with US and Israeli defense primes before polymer dielectric reliability data matures. METI stockpiling directives offer subsidy capture opportunities for surface-mount capacity expansion. For New Entrants and Emerging Players: Enter via India PLI scheme assembly incentives for telecommunications-grade polymer tantalum serving domestic 5G infrastructure and automotive electronics demand. Target Karnataka and Tamil Nadu electronics manufacturing zones where BIS testing protocols create localization requirements. Qualify conductive polymer formats for base station power supplies where equivalent series resistance specifications exclude solid tantalum incumbents. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with documented conflict-free smelter networks and aerospace certification backlogs. Long-term viability rests on consolidation of electrochemical process engineering talent concentrated in aging Japanese and German workforces. Watch for polymer dielectric field failure rates in 5G macro cell deployments as inflection indicator for solid tantalum demand resilience.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Tantalum Concentrate | ECHA-compliant smelter documentation secures European medical device qualification pipelines against supply disruption. |
| MIL-PRF-55365 Certification Investment | 18-24 month qualification cycles with US defense primes create pricing power in satellite power distribution. |
| Conductive Polymer Dielectric Scale-Up | Sub-10 milliohm equivalent series resistance captures South Korean 5G base station procurement specifications. |
| Osaka-Kyoto Surface-Mount Capacity Expansion | METI stockpiling subsidies accelerate automated assembly output for automotive and consumer electronics OEMs. |
| Blockchain-Traceable Smelter Documentation | REACH Article 33 compliance enables distributor retention of European electronics manufacturing service provider contracts. |
Research Approach
SEC 10-K filings, ECHA conflict-mineral disclosure databases, and METI critical component stockpiling reports formed the secondary backbone, cross-referenced with primary interviews across capacitor procurement managers at aerospace primes, electrochemical process engineers at Japanese fabricators, and medical device supply chain directors at German notified body-regulated OEMs. Bottom-up and top-down triangulation validated segment-level assumptions against customs data for tantalum concentrate trade flows.
Bottom-up modeling of dielectric chemistry segments, mounting technology formats, and end-use reliability tiers across the projection horizon generated volume and value outputs. CAGRs derived from segment growth rate differentials weighted by aerospace qualification backlog visibility and telecommunications infrastructure deployment schedules. Industry-specific forecast inputs included MIL-PRF certification pipeline durations and polymer dielectric field reliability data from 5G base station deployments.
Revisions become necessary when Central African mining jurisdiction stability deteriorates, OECD conflict-mineral audit protocols expand scope, or polymer dielectric mean-time-between-failures data in high-temperature applications materializes below solid tantalum benchmarks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Graphics Add-In Board (AIB) Market
Electronic Components
Passive Attenuator Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
Loudspeaker Market
Electronic Components
Europe Radiation-Hardened Electronics Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Amplifier Market
Electronic Components
Timing Relay Market
Electronic Components
TWS and Noise-Cancelling Headphone with MEMS Chip Market
Electronic Components
RAID Controller Card Market
Electronic Components
VPX SBC Market
Electronic Components
Stretchable Conductors in Electronics Market
Electronic Components
Digital Audio Processor Market
Electronic Components
Fixed Capacitor Market
Electronic Components
Metal Composite Power Inductor Market