
 Aluminum Electrolytic Capacitor Market | 2026-2036
Aluminum Electrolytic Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Electrolytic Capacitor Market Analysis
Capital-intensity divergence between in-house foil-etching capabilities and outsourced electrode production is bifurcating competitive tiers. Panasonic Corporation leverages captive aluminum foil operations to sustain margin control across high-voltage industrial grades. Nippon Chemi-Con Corporation anchors its position through specialized etching technology for automotive-grade snap-in capacitors. Samwha Capacitor Group competes on scale economics in radial formats for consumer power supplies.
An aluminum electrolytic capacitor stores energy through an electrochemical oxide layer formed on etched aluminum foil, using a liquid or gel electrolyte as the cathode; typical operating voltages span 6.3V to 450V with capacitance values reaching hundreds of thousands of microfarads. The device primarily smooths rectified current, filters noise, and buffers energy in power conversion circuits across industrial and consumer hardware. Snap-in and SMD formats dominate volume in automotive electronics and compact power supplies respectively, where board-space constraints and vibration resistance define selection criteria. The 1000µF-10000µF capacitance band captures substantial value in industrial motor drives and EV onboard chargers, while above-10000µF units concentrate in grid-scale inverter applications with extended thermal cycling requirements.
Japan's METI enforces JIS standards for capacitor endurance and flame resistance in industrial equipment, while China's GB standards and MIIT directives govern electrolyte composition and RoHS alignment for domestic and export-bound production. The EU's REACH regulation and F-Gas framework constrain fluorinated solvent use in electrolyte formulations, pushing suppliers toward non-VOC alternatives. Stakeholders must monitor evolving thermal-rating requirements from automotive OEMs and assess electrolyte chemistry transitions before capacity commitments lock in incompatible process lines.
Market Dynamics
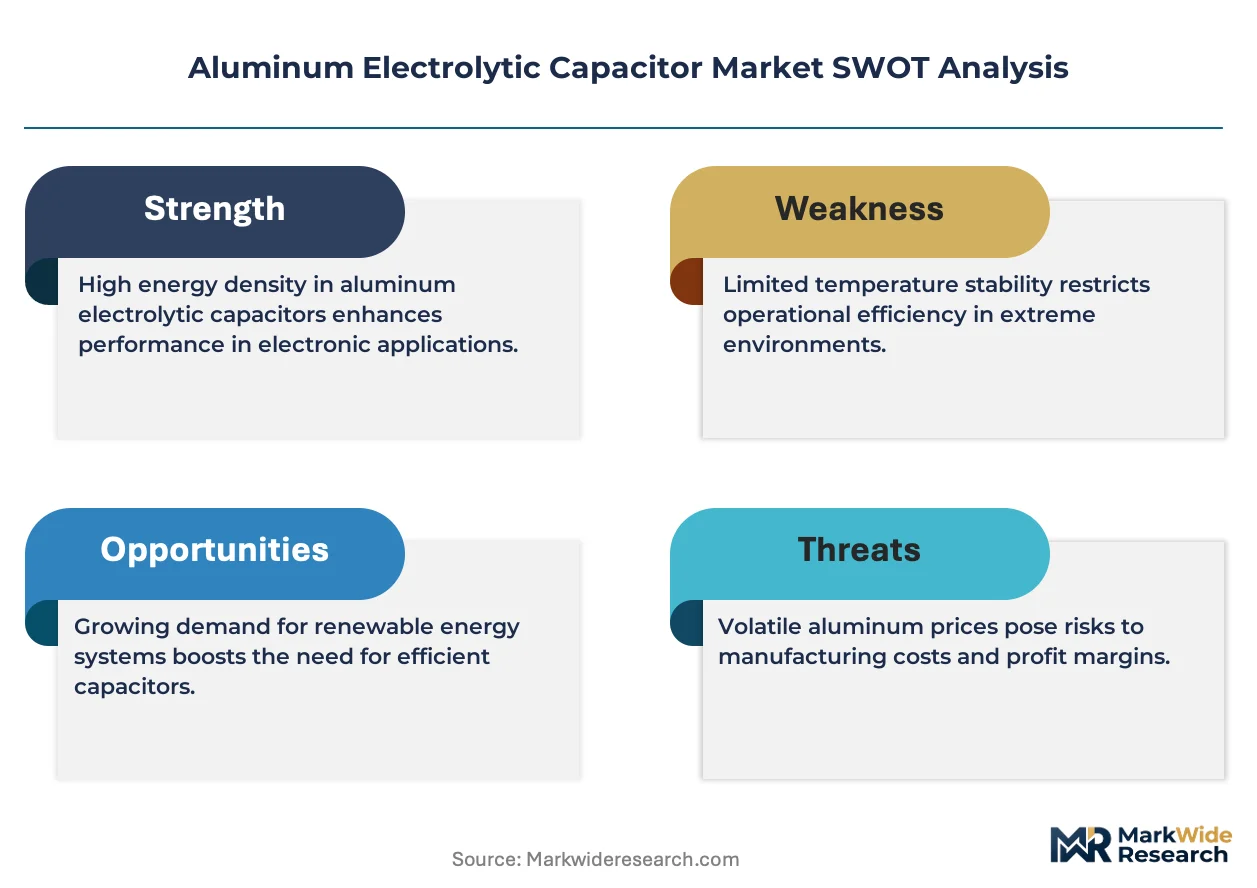
Electrolyte chemistry transitions driven by the EU's F-Gas Regulation and China's dual carbon goals are forcing capacitor manufacturers to rebuild formulation lines while maintaining ripple-current performance. This regulatory compression is reshaping competitive advantage toward suppliers with captive R&D in non-fluorinated solvent systems.
Growth Catalysts
- EV powertrain electrification:Onboard chargers and DC-DC converters in battery electric vehicles demand high-ripple-current snap-in capacitors with extended thermal cycling endurance.
- MIIT electrolyte directives:China's domestic content requirements for GB-standard compliance are accelerating local production capacity for export-bound and domestic automotive supply chains.
- Etched foil process innovation:Advanced tunnel-etching techniques for high-purity aluminum are expanding surface-area ratios without compromising mechanical integrity in vibration-prone automotive mounts.
Market Restraints
- Aluminum foil supply concentration:High-purity anode foil production concentrates among Japanese and Chinese metallurgical suppliers, creating input bottlenecks during capacity expansions.
- REACH compliance costs:ECHA substance-of-very-high-concern listings for legacy electrolyte additives are forcing expensive formulation requalification cycles for EU-bound shipments.
- Solid polymer substitution:Conductive polymer aluminum capacitors are capturing board-space in compact consumer power supplies below 100V operating thresholds.
Strategic Opportunities
- Grid-scale energy storage:Above-10000µF units for utility inverter applications remain undersupplied relative to solar and wind installation growth trajectories.
- India industrial automation:BIS certification alignment with IEC standards is opening import substitution potential for motor drive and UPS manufacturers in Gujarat and Tamil Nadu manufacturing corridors.
- Non-VOC electrolyte platforms:ECHA's solvent volatility restrictions are creating first-mover advantage for suppliers with qualified water-based and ionic liquid formulations.
Industry Challenges
- Electrochemical engineer scarcity:Specialized expertise in oxide formation kinetics and electrolyte ionic conductivity is concentrating among retiring cohorts in Japanese and German technical centers.
- AEC-Q200 certification timelines:Automotive-grade qualification cycles for snap-in formats extend 18-24 months, locking capacity commitments before demand visibility clarifies.
- Legacy equipment integration:New etching and forming lines must interface with existing winding and sealing infrastructure without disrupting high-volume radial production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Electrolytic Capacitor Market |
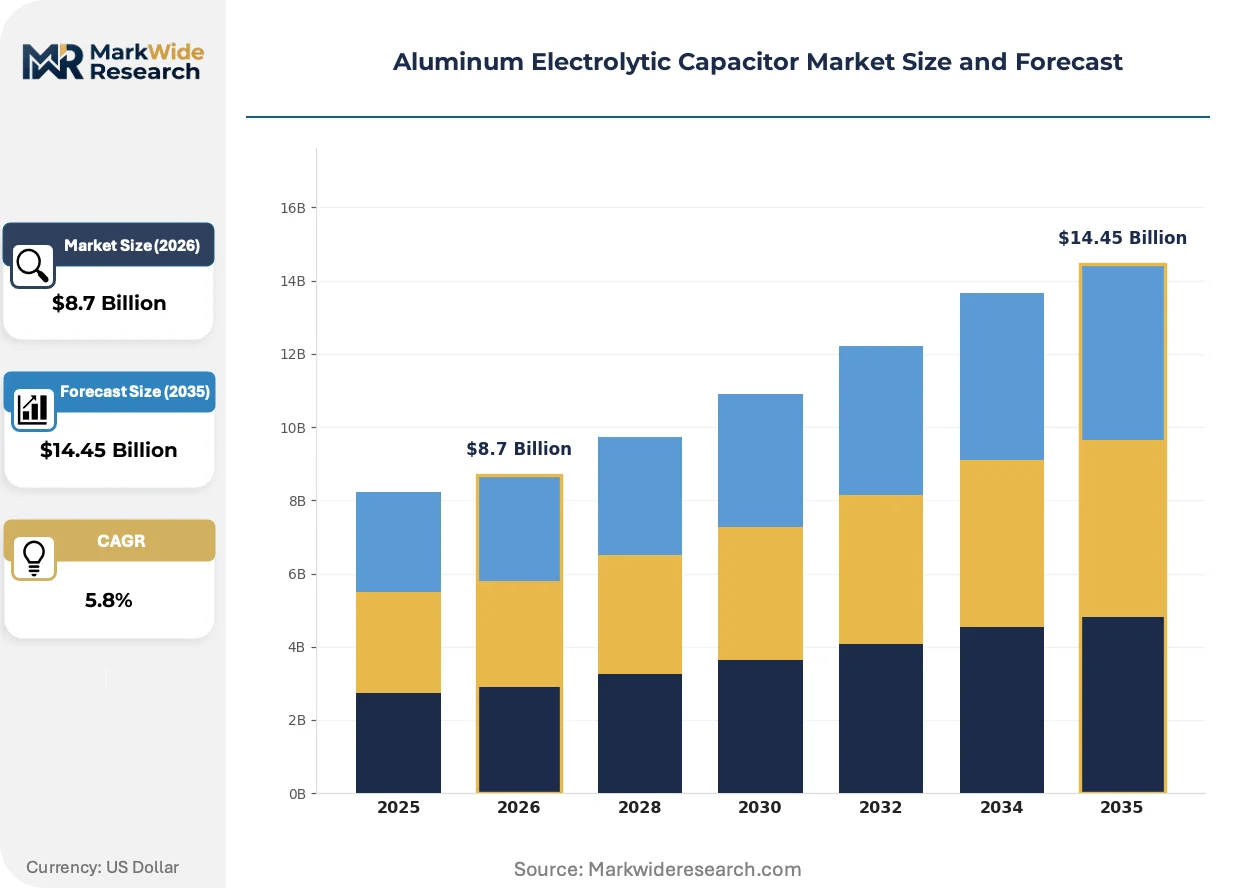
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial, Axial, SMD, Snap-in Application: Consumer Electronics, Automotive Electronics, Power Supplies, Industrial Equipment Capacitance Range: 10µF-100µF, 100µF-1000µF, 1000µF-10000µF, Above 10000µF Temperature Rating: -40°C to 85°C, -40°C to 105°C, -55°C to 125°C, Others |
| Companies Covered | Panasonic Corporation, Nippon Chemi-Con Corporation, Nichicon Corporation, Rubycon Corporation, Vishay Intertechnology Inc., KEMET Corporation, Samwha Capacitor Group, Lelon Electronics Corp., Nantong Jianghai Capacitor Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Electrolytic Capacitor Market Emerging Trajectories
Hybrid electrolyte systems and surface-mount form factors are compressing traditional boundaries between aluminum electrolytic and solid polymer technologies. Manufacturers are racing to deliver vibration-resistant, high-density solutions before automotive electrification timelines harden.
Hybrid polymer-aluminum capacitors combine liquid electrolyte ionic conductivity with conductive polymer cathode layers, delivering lower equivalent series resistance than conventional wet aluminum designs. Tier-1 automotive suppliers in Germany and Japan are qualifying these components for 48V mild-hybrid systems at accelerated schedules. The technology is miniaturizing footprint requirements for onboard chargers while maintaining the surge-current handling that pure polymer capacitors sacrifice.
REACH Annex XVII restrictions on perfluorinated compounds are compelling electrolyte suppliers to eliminate fluorinated solvents from high-voltage industrial grades. ECHA's 2023 update to substance restriction entries triggered reformulation programs across European capacitor manufacturers and their Asian component suppliers. Industrial motor drive producers in Italy and France are now specifying non-fluorinated electrolyte certificates in procurement tenders, forcing supply chain transparency down to raw material sourcing.
Consolidated component sourcing is compressing distributor tiers as automotive OEMs direct-specify capacitor grades rather than delegating to EMS provider discretion. Tier-1 power module manufacturers in South Korea and Japan are establishing approved vendor lists with locked formulation specifications, bypassing traditional broadline distribution for high-reliability segments. This pattern is most pronounced in EV powertrain contracts where traceability requirements from mine to module override cost-minimization priorities.
Aluminum Electrolytic Capacitor Market Segmentation
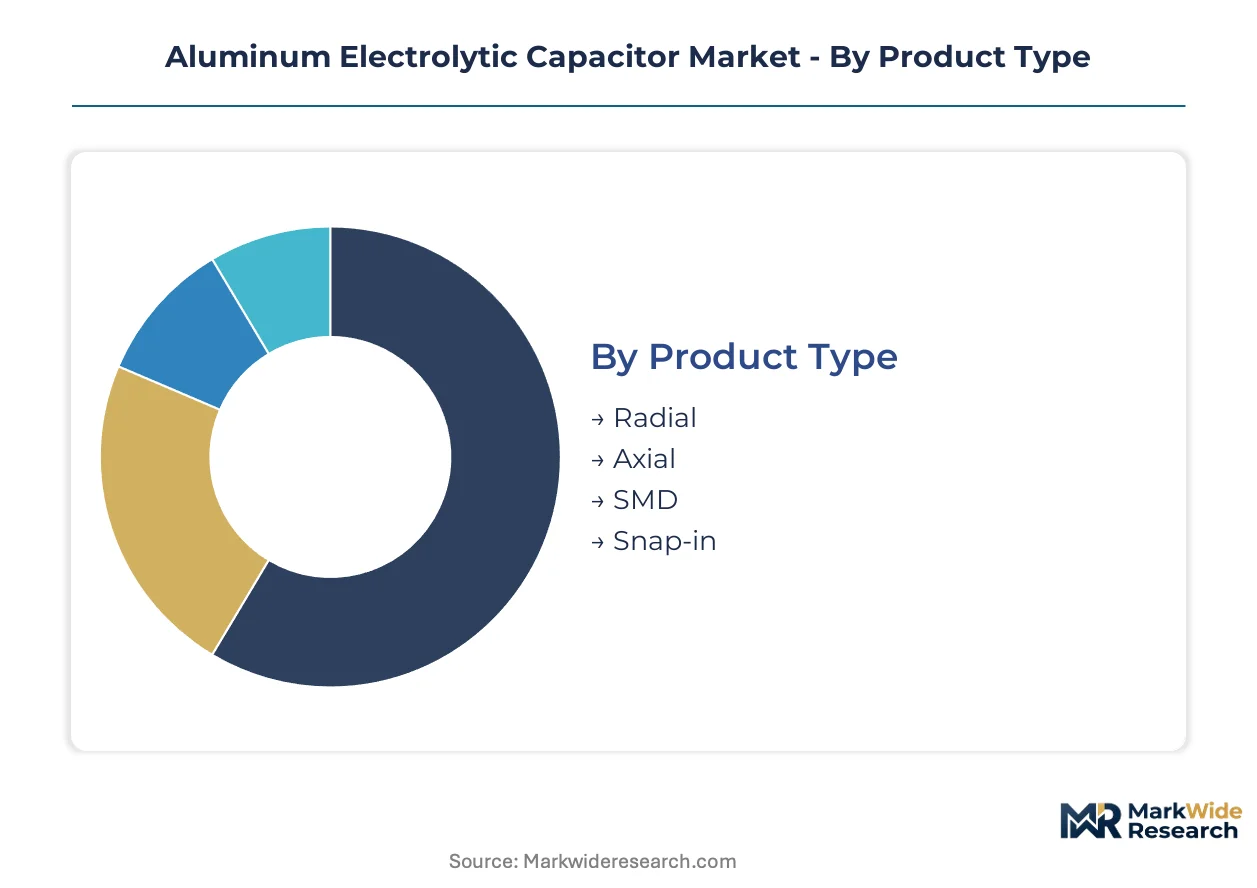
Capacitor manufacturers configure production lines around specific form factors and thermal envelopes. Segment selection determines electrolyte chemistry, foil etching depth, and sealing technology investments.
Product Type:
Radial and axial formats dominate domestic appliance supply chains in China and Japan, while SMD and snap-in variants anchor export-led automotive programs in Germany and South Korea.
- Radial:Leads in consumer power supply boards with through-hole mounting and cylindrical aluminum cans. Demand concentrates in Shenzhen and Dongguan manufacturing clusters serving white-goods OEMs, constrained by solid polymer substitution below 100V thresholds.
- Snap-in:Features plastic base with solder pins for PCB retention in high-vibration environments. German and Japanese automotive Tier-1s specify these for onboard chargers and DC-DC converters, with AEC-Q200 qualification cycles extending 18-24 months.
- Axial:Horizontal lead configuration suits legacy industrial equipment and replacement markets. Russian and Eastern European maintenance channels sustain residual demand.
- SMD:Surface-mount aluminum cans with conductive polymer hybrids capture notebook adapter and compact LED driver designs. South Korean EMS providers drive specifications for reduced board height.
Radial holds the largest share; momentum sits with snap-in formats as EV powertrain electrification accelerates.
Application:
Cost tier separation distinguishes high-reliability automotive grades from commodity consumer electronics, with industrial equipment occupying a mid-tier certification band.
- Automotive Electronics:Snap-in and hybrid polymer capacitors buffer energy in 48V mild-hybrid and full-electric powertrains. Japanese and German OEMs mandate traceability from mine to module, compressing distributor tiers.
- Power Supplies:Radial and SMD formats smooth rectified AC in adapter and server PSU designs. Taiwanese and South Korean ODMs specify 105°C-rated units for extended thermal margins.
- Consumer Electronics:Entry-level radial capacitors face conductive polymer displacement in sub-100V smartphone charger applications. Chinese domestic brands drive volume with aggressive cost positioning.
- Industrial Equipment:High-voltage snap-in and large-can designs filter motor drive inverters and UPS systems. Italian and French industrial OEMs now require non-fluorinated electrolyte certificates per ECHA restrictions.
Power supplies generate the highest unit volumes; automotive electronics deliver the steepest expansion trajectory as electrification timelines harden.
Capacitance Range:
Volume scale concentrates in mid-range bands where winding automation achieves maximum throughput, while specialty above-10000µF units command premium positioning.
- 1000µF-10000µF:Dominates industrial motor drives and EV onboard chargers with optimized surface-area-to-volume ratios. Japanese etched-foil suppliers prioritize tunnel-etching R&D for this band.
- Above 10000µF:Screw-terminal and large-can designs buffer grid-scale solar and wind inverters. Supply remains undersupplied relative to utility installation growth in Spain and Australia.
- 100µF-1000µF:Standard radial formats for consumer power supplies and lighting ballasts. Chinese manufacturers compete on scale economics with automated winding lines.
- 10µF-100µF:Compact SMD and sub-miniature radial units for signal coupling and timing circuits. Solid polymer capacitors capture share in high-frequency switching applications.
The 1000µF-10000µF band holds the largest share; above-10000µF units are climbing the fastest as renewable energy storage deployment accelerates.
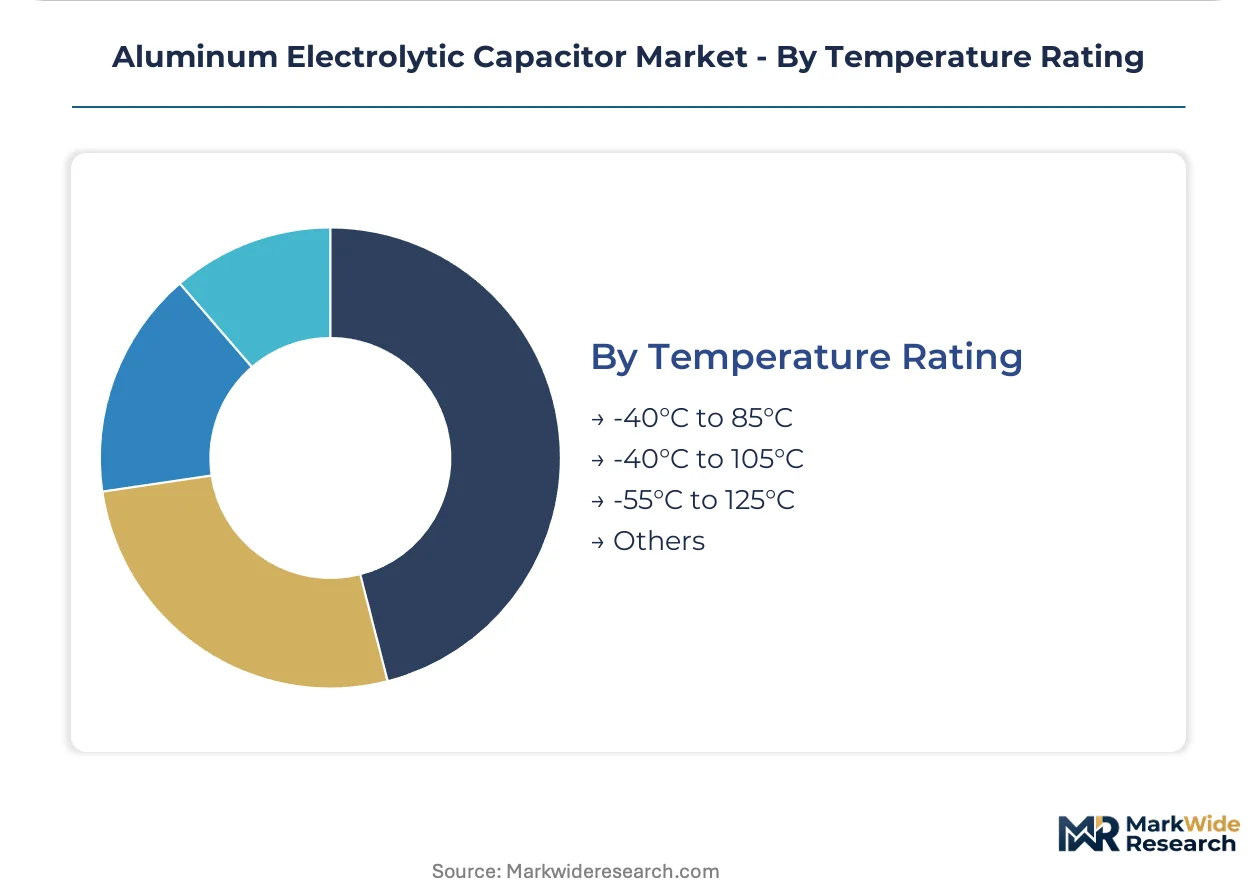
Temperature Rating:
Customer type stratification separates automotive OEMs demanding 125°C endurance from consumer brands accepting 85°C lifecycles.
- -40°C to 105°C:Industrial and commercial sweet spot balancing electrolyte stability against cost. German and Japanese manufacturers dominate with proprietary ethylene glycol formulations.
- -55°C to 125°C:Automotive-grade specification for under-hood and powertrain mounting. Extended qualification timelines and AEC-Q200 certification create supply scarcity.
- -40°C to 85°C:Entry-level consumer electronics standard with 2000-hour rated life. Chinese producers leverage cost advantages in white-goods and lighting markets.
- Others:Specialty cryogenic and high-temperature ratings for aerospace and downhole drilling. Limited supplier base with captive etching capabilities.
The -40°C to 105°C rating holds the largest share; -55°C to 125°C specifications are gaining share fastest as automotive thermal requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Chinese coastal manufacturing clusters exhibit acute price sensitivity in radial formats for consumer power supplies, while German automotive Tier-1s prioritize thermal endurance and traceability over unit cost in snap-in specifications for EV powertrains.
China
Domestic EV production and renewable energy inverter deployment drive demand for high-ripple-current snap-in and large-can capacitors. MIIT directives on GB-standard electrolyte composition and dual carbon goals accelerate local capacity expansion for automotive-grade supply chains. Manufacturing concentrates in Shenzhen and Dongguan clusters for consumer electronics, with Nantong and Suzhou emerging for industrial-grade etched-foil processing.
Japan
Advanced automotive electronics and industrial motor drive applications sustain premium-tier demand for high-voltage snap-in formats. METI enforces JIS standards for endurance and flame resistance, extending qualification timelines for export-bound automotive shipments. Kansai and Nagoya industrial corridors host captive foil-etching operations serving domestic and overseas Tier-1 power module manufacturers.
Germany
48V mild-hybrid and full-electric powertrain programs from domestic OEMs specify AEC-Q200 certified snap-in capacitors with extended thermal cycling margins. ECHA REACH restrictions and F-Gas Regulation compliance constrain electrolyte formulation sourcing, favoring suppliers with qualified non-fluorinated solvent systems. Baden-Württemberg and Bavaria anchor automotive electronics procurement clusters with direct OEM specification authority.
South Korea
Battery electric vehicle onboard chargers and DC-DC converters from domestic automotive groups drive snap-in and hybrid polymer format qualification. MFDS alignment with international chemical substance regulations shapes electrolyte import protocols for high-reliability segments. Seoul Capital Area and Busan-Ulsan manufacturing belts concentrate EMS providers with locked vendor lists for powertrain capacitor sourcing.
United States
Data center power supply and grid-scale solar inverter installations sustain demand for above-10000µF screw-terminal units and 105°C-rated industrial formats. EPA and OSHA chemical handling standards intersect with state-level clean energy procurement mandates in California and Texas. Southeast manufacturing corridors in Georgia and Tennessee attract capacitor distributor consolidation serving industrial automation and EV battery plant buildouts.
Aluminum Electrolytic Capacitor Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with Japanese and South Korean manufacturers anchoring premium automotive and industrial tiers while Chinese producers dominate scale-driven consumer electronics supply. The vendor base stratifies into three tiers: integrated foil-etching specialists with captive metallurgical operations, mid-scale format-focused producers serving EMS consolidation, and regional commodity suppliers competing on radial volume. Dominant competitive moves include backward integration into high-purity aluminum foil supply and strategic partnerships with automotive Tier-1s for locked formulation specifications.
Among Japanese manufacturers, Panasonic Corporation and Nippon Chemi-Con Corporation exemplify the integrated-technology archetype with metallurgical and etching capabilities sustaining margin control in high-voltage industrial grades. Samwha Capacitor Group represents the scale-driven Korean tier competing on radial format economics for consumer power supply boards.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Nippon Chemi-Con Corporation |
| Nichicon Corporation |
| Rubycon Corporation |
| Vishay Intertechnology Inc. |
| KEMET Corporation |
| Samwha Capacitor Group |
| Lelon Electronics Corp. |
| Nantong Jianghai Capacitor Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for high-purity etched aluminum foil lock in supply access and price visibility for Japanese and Korean capacitor manufacturers, insulating them from spot-market volatility in raw material inputs while committing capacity years ahead of demand crystallization.
Pricing Analysis
After-sales service contracts and technical support agreements drive lifetime value in industrial-grade capacitor sales. Three-tier pricing structure across automotive-certified, industrial-standard, and consumer-economy levels separates AEC-Q200 qualified snap-in units from radial formats for white-goods. Cost compression in consumer radial tiers is intensifying because Chinese manufacturers automate winding lines at scale. White-goods OEMs in Shenzhen exhibit acute price sensitivity; German automotive Tier-1s prioritize thermal endurance over unit cost.
Supply Chain Analysis
Japan and China anchor high-purity aluminum foil production and etched anode manufacturing, with South Korea specializing in hybrid polymer format assembly. Supply chains draw from bauxite refining in Australia, smelting operations in China, and precision etching in Japanese metallurgical facilities. Single-source vulnerability concentrates in tunnel-etching equipment suppliers serving foil processors. Distribution runs through locked vendor lists at automotive Tier-1s and broadline electronics distributors for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward automotive OEMs that direct-specify capacitor grades rather than delegate to EMS providers, compressing distributor tiers and locking formulation specifications before demand visibility clarifies.
For Market Incumbents: Consolidate backward integration into high-purity aluminum foil supply to defend margin control against Chinese scale competitors. Deepen captive etching capabilities for automotive-grade snap-in formats before AEC-Q200 qualification timelines harden capacity commitments. Lock formulation specifications with German and Korean Tier-1s through multi-year supply agreements.
For New Entrants and Emerging Players: Differentiate on non-VOC electrolyte platforms qualified for ECHA REACH compliance, capturing first-mover advantage as European industrial OEMs mandate fluorinated-solvent-free certificates. Target grid-scale inverter applications in Spain and Australia where above-10000µF units remain undersupplied relative to renewable installation growth. Pursue qualification partnerships with utility-scale solar EPCs rather than competing on radial volume.
For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors suppliers with captive R&D in non-fluorinated solvent systems and locked automotive certifications. Long-term viability over a five-to-ten-year window rests on etching technology depth and electrolyte chemistry transitions rather than scale economics alone. Acquisition target archetype: mid-cap specialists with AEC-Q200 qualified snap-in lines and backward integration into foil processing. Signal to watch: MIIT electrolyte directive enforcement accelerating Chinese domestic content requirements for export-bound automotive supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foil Etching | Captive metallurgical operations insulate Panasonic and Nippon Chemi-Con from input bottlenecks during capacity expansions. |
| Non-VOC Electrolyte Platform Development | ECHA solvent volatility restrictions create first-mover advantage for suppliers with qualified water-based formulations. |
| AEC-Q200 Certification Investment | Extended automotive qualification cycles lock out unqualified competitors from 48V mild-hybrid and EV powertrain contracts. |
| Locked Vendor List Partnerships | Tier-1 power module manufacturers in South Korea and Japan bypass distributors for traceability-compliant capacitor sourcing. |
| Grid-Scale Inverter Supply Agreement | Utility-scale solar and wind installations in Spain and Australia drive undersupplied demand for above-10000µF screw-terminal units. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and MIIT directive documentation. Primary interviews engaged capacitor plant managers, procurement leads at automotive Tier-1s, distribution channel partners, and technical R&D directors specializing in oxide formation kinetics. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segmentation dimensions modeled include form factor configuration, application end-use, capacitance band, and temperature rating tier across regional production clusters. CAGRs were derived from growth driver elasticity analysis and capacity expansion timelines. Forecast inputs incorporated etched-foil surface-area yield improvements and electrolyte chemistry transition schedules without specific year anchoring.
Material uncertainties — regulatory enforcement timing on fluorinated solvent restrictions, automotive OEM thermal-rating requirement evolution, and aluminum foil smelting capacity expansion decisions — sit outside the modeled envelope. Forecasts reflect assumptions on qualification cycle durations and substitution elasticity between wet aluminum and solid polymer formats. Recalibration cycles align with material shifts in ECHA restriction updates and MIIT directive implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
PTC Resettable Device Market
Electronic Components
North America Miniature Ball Bearing Market
Electronic Components
Wireless Charging Stand Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
Stretchable and Conformal Electronics Market
Electronic Components
Coaxial Coupler Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
USB Charger Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
Microcontroller Socket Market
Electronic Components
Conductive Polymer Capacitor Market
Electronic Components
Speaker Cone Material Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
Distribution Components Market
Electronic Components
Flex-Rigid PCB Market
Electronic Components
Americas MPU Market