
 Video Surveillance Chip Market | 2026-2036
Video Surveillance Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Video Surveillance Chip Market Insights
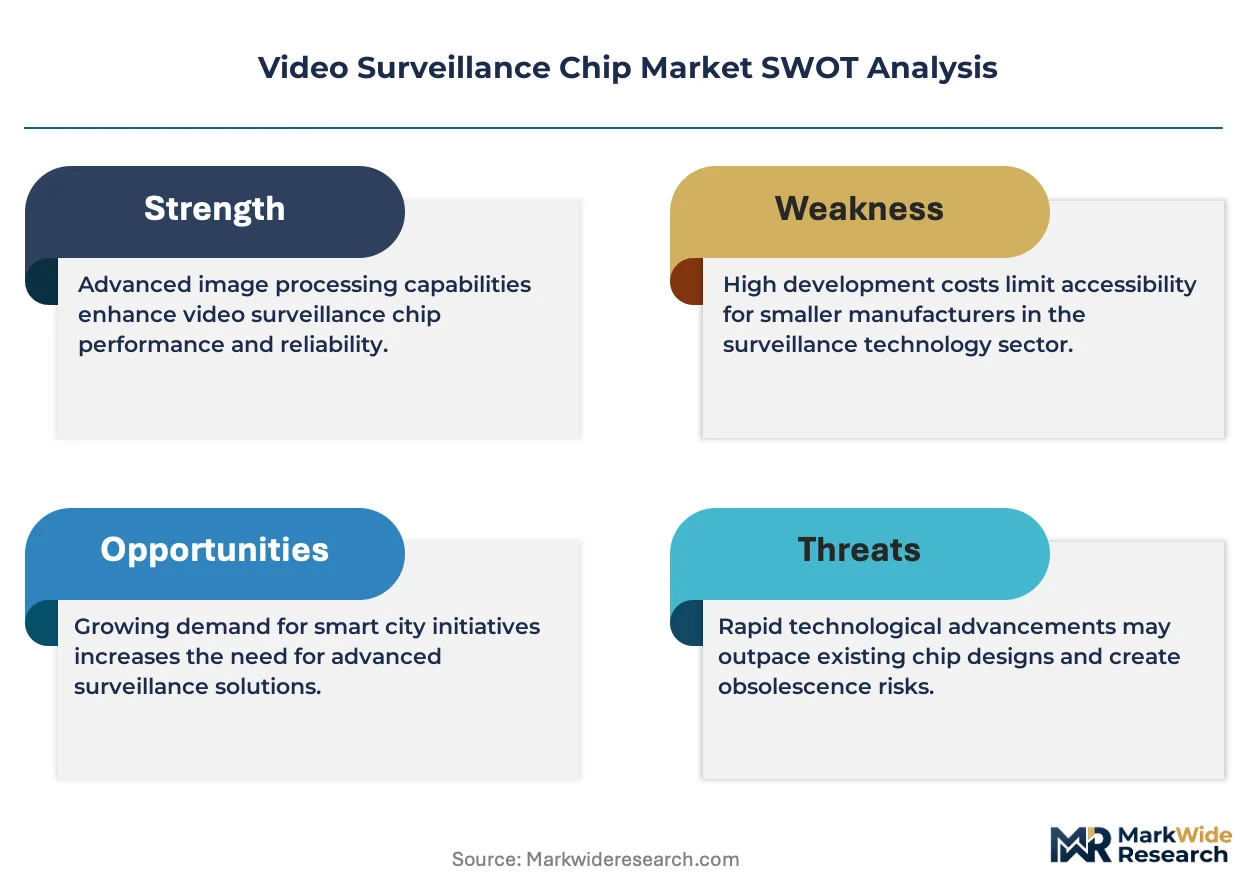
Critical infrastructure protection is broadening the addressable base for surveillance semiconductor suppliers beyond traditional security budgets. Hangzhou Hikvision Digital Technology Co., Ltd. leverages captive chip design to control cost structures across its camera portfolio. Dahua Technology Co., Ltd. sustains R&D intensity in AI-optimized silicon for facial recognition pipelines. Axis Communications AB differentiates through open-platform chip architectures that accommodate third-party analytics at the edge.
Video surveillance chips are integrated circuits purpose-built for image signal processing, video encoding, and neural network inference within camera systems and network video recorders, typically fabricated on nodes between 28nm and 7nm depending on AI workload density. Their commercial purpose centers on enabling real-time threat detection while minimizing bandwidth consumption through edge-side computation. CMOS sensor interface chips dominate unit volumes due to universal adoption across IP camera platforms, while FPGA-based acceleration modules command premium positioning in military and aviation applications where reconfigurable logic outperforms fixed-function DSPs. The transportation security application segment exhibits the steepest growth trajectory as railway operators and port authorities mandate AI-enhanced perimeter monitoring.
FCC equipment authorization requirements constrain RF-enabled surveillance devices in the US market, while EU AI Act provisions classify biometric identification systems as high-risk and impose conformity assessment obligations. China's SAMR enforces cybersecurity review for video products deployed in government facilities, creating a bifurcated compliance landscape. Stakeholders must monitor whether export control expansions on advanced node manufacturing equipment will constrain supply of AI-capable surveillance silicon to specific national markets.
Market Dynamics
Edge AI inference requirements are compressing silicon procurement cycles as municipal governments and critical infrastructure operators mandate on-camera neural processing for real-time threat detection, bypassing cloud latency constraints entirely.
Growth Catalysts
- Smart City Infrastructure Mandates:China's GB standards for intelligent video analytics compel municipal procurement of AI-capable silicon across transportation hubs and public safety networks. Shenzhen-based system integrators source directly from domestic foundries to meet deployment timelines.
- Transportation Security Modernization:Railway operators and port authorities across Asia and North America require AI-enhanced perimeter monitoring, expanding addressable silicon volumes beyond traditional security budgets. Edge-side computation minimizes bandwidth consumption across distributed networks.
- Critical Infrastructure Protection:Government facilities in multiple geographies now classify video analytics as essential cybersecurity infrastructure, triggering dedicated funding streams for semiconductor upgrades. SAMR cybersecurity review requirements accelerate replacement cycles in China.
Market Restraints
- Advanced Node Supply Concentration:AI-capable surveillance silicon fabrication depends on equipment subject to export control expansions, constraining foundry capacity for neural network inference chips below 14nm.
- Regulatory Fragmentation:FCC equipment authorization requirements for RF-enabled devices operate in parallel with EU AI Act high-risk classification for biometric systems, forcing dual compliance architectures that extend certification timelines.
- CMOS Sensor Interface Commoditization:Universal adoption across IP camera platforms compresses margins on high-volume interface chips, limiting R&D recovery for suppliers without captive downstream integration.
Strategic Opportunities
- Aviation and Military FPGA Modules:Reconfigurable logic outperforms fixed-function DSPs in applications requiring post-deployment algorithm updates, commanding premium positioning unavailable to standard silicon suppliers.
- India Smart City Mission:Underpenetrated municipal surveillance infrastructure creates procurement windows for edge AI chips as BIS standards align with international video encoding protocols.
- Open-Platform Architecture Convergence:Third-party analytics accommodation at the edge enables software-defined camera ecosystems, displacing vertically integrated hardware-software bundles.
Industry Challenges
- Neural Network Optimization Talent Scarcity:Chip designers capable of mapping facial recognition pipelines to 7nm silicon command compensation premiums that strain mid-tier vendor R&D budgets.
- Legacy Analog Infrastructure Integration:Hybrid deployments requiring backward compatibility with coaxial cable networks complicate firmware architectures and extend qualification cycles for new silicon generations.
- Cross-Border Data Flow Restrictions:GDPR biometric processing limitations and China's data localization mandates force region-specific silicon feature sets, fragmenting product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Surveillance Chip Market |
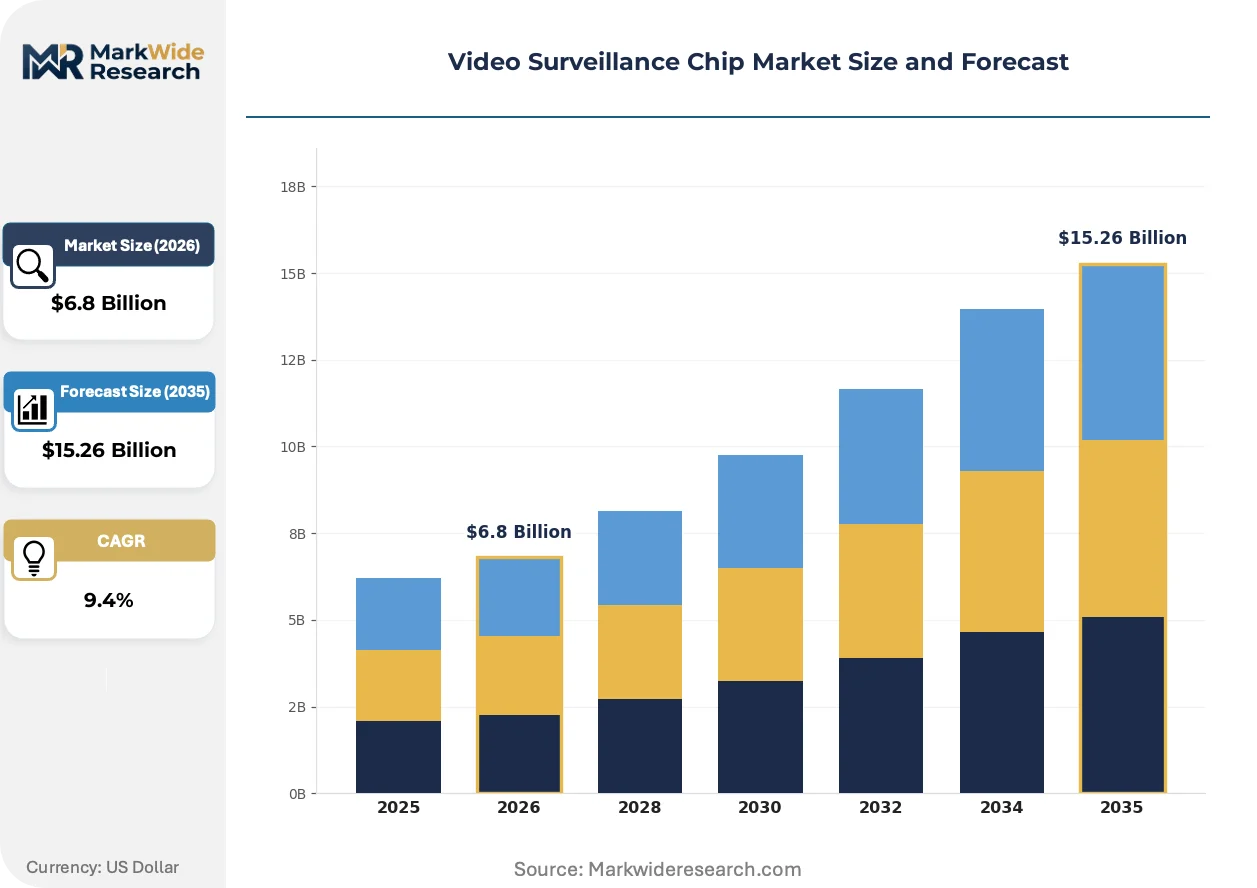
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Chips, Digital Chips, IP Chips, Hybrid Chips Technology: CMOS, CCD, DSP, FPGA Application: Home Security, Industrial Monitoring, Retail Surveillance, Transportation Security End User: Government, Commercial, Residential, Educational |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Axis Communications AB, Honeywell International Inc., Motorola Solutions, Inc., Bosch Security Systems GmbH, Hanwha Vision Co., Ltd., Teledyne FLIR LLC, i-PRO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Surveillance Chip Market Trends and Innovations
Silicon architectures are bifurcating between commodity image signal processors and premium neural inference engines, with procurement specifications increasingly written around AI workload density rather than resolution or frame rate metrics.
Neural processing units with dedicated tensor cores are consolidating video encoding and real-time inference onto single-die solutions. Railway operators in Japan and port authorities in Singapore specify these integrated architectures for perimeter monitoring systems. The consolidation eliminates discrete FPGA coprocessors from mainstream municipal deployments, compressing bill-of-materials complexity for system integrators.
EU AI Act provisions classify biometric identification systems as high-risk and impose conformity assessment obligations on camera manufacturers. Industrial consequence includes mandatory third-party auditing of training data provenance and algorithmic bias testing. European critical infrastructure operators now require chip-level audit trails, with German railway procurement specifications explicitly referencing CE marking extensions for AI-enabled surveillance.
Municipal procurement departments are consolidating vendor relationships around silicon suppliers offering decade-long supply guarantees. China's Greater Bay Area integrators negotiate direct foundry partnerships, while North American operators favor distributors with bonded inventory programs. The shift is most visible in transportation security verticals, where port authorities in California and British Columbia now specify supply chain resilience as a weighted evaluation criterion alongside technical performance.
Video Surveillance Chip Market Segmentation
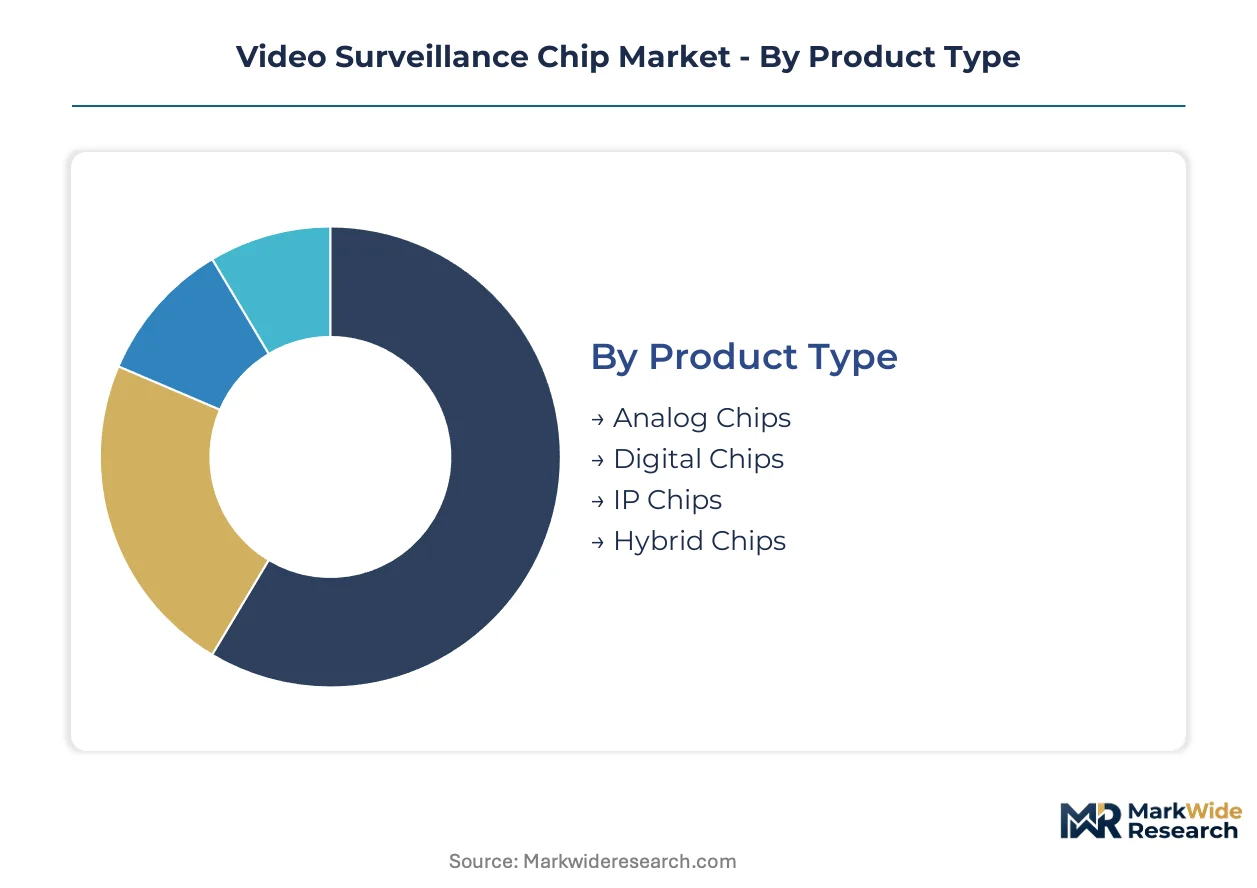
Procurement specifications for video surveillance silicon diverge sharply across deployment contexts, with edge AI requirements, legacy infrastructure constraints, and regulatory compliance each dictating distinct technical priorities. Understanding these segment boundaries enables suppliers to align foundry roadmaps with actual demand concentration rather than assumed volume distribution.
Product Type:
Customization intensity spans from commodity analog replacement chips to fully programmable AI inference engines, with procurement cycles compressing for neural-capable categories.
- IP Chips:Purpose-built for network camera architectures with integrated H.265/H.266 encoding and ONVIF protocol support. Railway operators in Japan and port authorities in Singapore specify these for perimeter monitoring systems where edge-side inference eliminates cloud latency.
- Digital Chips:Fixed-function signal processors for DVR and NVR platforms, dominating volume in municipal retrofits where legacy coaxial infrastructure persists. China's Greater Bay Area integrators source these from domestic foundries for cost-sensitive public safety deployments.
- Analog Chips:Image signal processors for CVBS and HD-TVI camera platforms, sustaining demand in emerging market price-sensitive segments.
- Hybrid Chips:Dual-path architectures supporting both analog and IP output, extending equipment lifecycles in phased upgrade scenarios.
Leading the category by volume: Digital Chips. Expanding most quickly: IP Chips.
Technology:
Node geometry and reconfigurability define margin tiers, with sub-14nm neural engines commanding premiums against mature-node commodity interfaces.
- CMOS:Sensor interface chips fabricated on 28nm-40nm nodes, achieving universal adoption across IP camera platforms. FCC equipment authorization requirements constrain RF-enabled variants in the US market, while China's SAMR mandates cybersecurity review for government facility deployments.
- FPGA:Reconfigurable logic arrays enabling post-deployment algorithm updates in military and aviation applications. German railway procurement specifications reference CE marking extensions for AI-enabled surveillance, favoring these modules where certification flexibility outweighs unit cost.
- DSP:Dedicated video encoding processors with fixed-function pipelines, standard in mid-tier municipal contracts.
- CCD:Legacy image sensor technology, persisting in specialized low-light and scientific imaging niches.
Highest volume concentration: CMOS. Steepest expansion trajectory: FPGA.
Application:
Threat detection latency requirements stratify silicon specifications, with real-time perimeter monitoring demanding neural inference unavailable in general-purpose security deployments.
- Transportation Security:AI-enhanced perimeter monitoring for railway operators and port authorities across Asia and North America. EU AI Act high-risk classification for biometric systems imposes conformity assessment obligations, forcing dual compliance architectures alongside FCC requirements.
- Retail Surveillance:Loss prevention and occupancy analytics with moderate inference requirements. Edge-side computation minimizes bandwidth consumption across distributed store networks.
- Industrial Monitoring:Process safety and hazard detection in manufacturing environments, prioritizing thermal tolerance and long supply guarantees.
- Home Security:Consumer-grade devices with cloud-dependent processing, constrained by cost ceilings below enterprise silicon.
Dominant volume segment: Retail Surveillance. Gaining share fastest: Transportation Security.
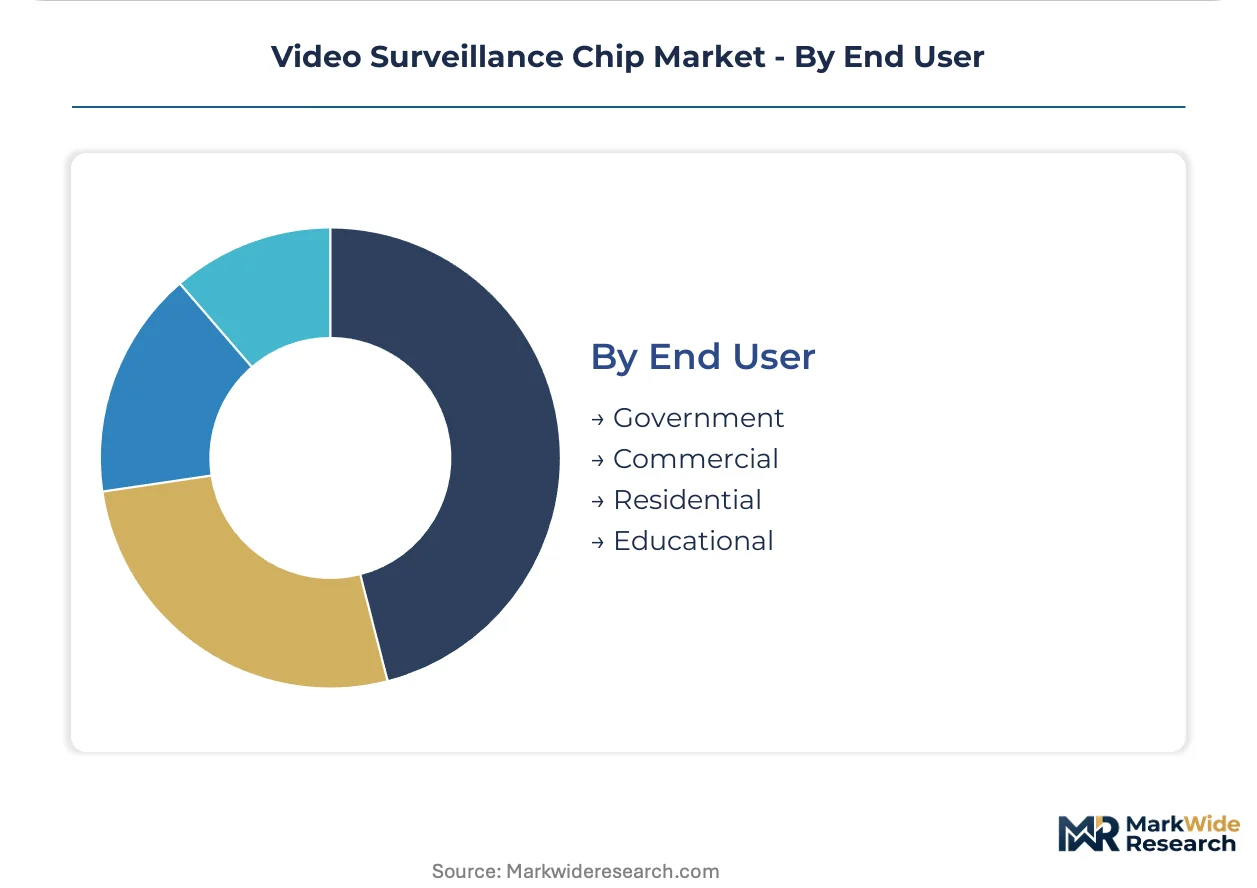
End User:
Budget authority and compliance exposure determine procurement sophistication, with government mandates accelerating replacement cycles against commercial cost optimization.
- Government:Critical infrastructure protection mandates trigger dedicated funding streams for semiconductor upgrades. China's SAMR cybersecurity review accelerates replacement cycles, while India's Smart City Mission creates procurement windows as BIS standards align with international protocols.
- Commercial:Enterprise security budgets prioritize open-platform architectures accommodating third-party analytics at the edge.
- Residential:Price-sensitive demand concentrated in DIY installation channels with minimal customization requirements.
- Educational:Campus safety mandates with moderate AI requirements, typically procured through municipal consortium arrangements.
Largest procurement volume: Commercial. Fastest policy-driven expansion: Government.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Greater Bay Area special economic zone concentrates video surveillance chip procurement through Shenzhen-based system integrators sourcing directly from domestic foundries. Municipal smart city mandates across Asia and North America accelerate deployment timelines. Regulatory fragmentation between export control regimes and data localization requirements shapes regional supply strategies.
United States
Transportation security modernization drives AI-enhanced perimeter monitoring procurement for railway operators and port authorities. FCC equipment authorization requirements constrain RF-enabled surveillance devices, extending certification timelines for edge AI silicon. California port authorities specify supply chain resilience as a weighted evaluation criterion alongside technical performance.
China
GB standards for intelligent video analytics compel municipal procurement of AI-capable silicon across transportation hubs and public safety networks. SAMR enforces cybersecurity review for video products deployed in government facilities, accelerating replacement cycles. Shenzhen-based system integrators negotiate direct foundry partnerships to meet deployment timelines in the Greater Bay Area.
Germany
Railway procurement specifications explicitly reference CE marking extensions for AI-enabled surveillance under EU AI Act provisions. German critical infrastructure operators now require chip-level audit trails for biometric identification systems classified as high-risk. Industrial demand concentrates in Bavaria and Baden-Württemberg, where manufacturing facilities mandate thermal-tolerant silicon for process safety monitoring.
Japan
Railway operators specify neural processing units with dedicated tensor cores for perimeter monitoring systems, eliminating discrete FPGA coprocessors from mainstream deployments. METI industrial policy supports edge AI semiconductor development for critical infrastructure applications. Nagoya and Osaka industrial clusters drive demand for long-supply-guarantee silicon in manufacturing hazard detection.
India
Underpenetrated municipal surveillance infrastructure creates procurement windows for edge AI chips as BIS standards align with international video encoding protocols. The Smart City Mission triggers dedicated funding streams for semiconductor upgrades across transportation security verticals. Demand concentrates in Maharashtra and Karnataka, where system integrators bridge legacy analog infrastructure with IP camera architectures.
Video Surveillance Chip Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive silicon design capabilities determining margin capture in municipal procurement. The vendor base organizes around three archetypes: vertically integrated security equipment manufacturers with in-house chip design, open-platform specialists licensing third-party silicon, and pure-play semiconductor suppliers serving multiple OEMs. Dominant competitive moves include backward integration into foundry partnerships and geographic expansion through distributor bonding programs.
Within the vertically integrated tier, Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. exemplify Chinese manufacturers controlling cost structures through captive chip design. Axis Communications AB occupies a distinct position among open-platform specialists, accommodating third-party analytics at the edge through architecture licensing rather than silicon fabrication. These three anchors represent divergent strategic postures: foundry-direct integration, R&D-intensive AI optimization, and software-defined hardware ecosystems.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Axis Communications AB |
| Honeywell International Inc. |
| Motorola Solutions, Inc. |
| Bosch Security Systems GmbH |
| Hanwha Vision Co., Ltd. |
| Teledyne FLIR LLC |
| i-PRO |
| Others |
Pricing and Supply Chain Analysis
Neural inference engine premium tiers versus commodity image signal processors generate divergent margin structures across the video surveillance chip landscape, with sub-14nm AI silicon commanding foundry-direct pricing while mature-node CMOS interfaces trade on volume scale. Shenzhen-based system integrators negotiate captive supply agreements with domestic foundries for GB-standard compliance, whereas North American operators absorb distributor markups for bonded inventory programs that guarantee decade-long availability.
Pricing Analysis
Short lead-time premiums apply to neural-capable silicon below 14nm as municipal procurement cycles compress around edge AI mandates. Three-tier pricing structure across premium, standard, and economy levels separates FPGA-based military modules from mid-tier DSP municipal contracts and analog replacement chips for emerging markets. Cost compression in commodity CMOS interfaces intensifies because universal IP camera adoption erodes R&D recovery rates. Government transportation security verticals exhibit lowest price sensitivity due to critical infrastructure classification, while residential DIY channels face absolute cost ceilings.
Supply Chain Analysis
China's domestic-content mandates under GB standards and SAMR cybersecurity review protocols reshape sourcing toward Shenzhen-based foundry partnerships for government facility deployments. Fabrication capacity concentrates in Taiwan, South Korea, and China, with advanced node equipment subject to export control expansions constraining neural inference chip supply. Raw material dependencies span silicon wafers, photoresist chemicals, and specialized packaging substrates. Single-source vulnerability around extreme ultraviolet lithography systems threatens sub-7nm roadmap execution. Distribution runs through bonded inventory programs for North American critical infrastructure operators and direct foundry relationships for Greater Bay Area integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced node fabrication equipment restrictions prop pricing power for incumbent neural inference suppliers as municipal edge AI mandates outstrip foundry capacity expansion.
For Market Incumbents: Extend supply guarantee programs to capture decade-long municipal procurement cycles as California and British Columbia port authorities weight resilience alongside technical performance. Deepen backward integration into photoresist and advanced packaging supply to offset single-source lithography vulnerability. Defend against open-platform architecture displacement by embedding proprietary tensor core optimizations that complicate third-party analytics migration. For New Entrants and Emerging Players: Begin with India's Smart City Mission procurement windows where BIS standard alignment creates certification pathways without entrenched incumbent relationships. Target railway perimeter monitoring specifications in underpenetrated Asian markets where neural processing unit consolidation eliminates discrete FPGA incumbents. Pursue aviation and military FPGA module niches where reconfigurable logic premiums persist against fixed-function DSP commoditization. For Investors and Strategic Acquirers: Re-rating potential sits with captive-chip-design security equipment manufacturers given SAMR cybersecurity review acceleration and GB standard procurement compulsion. Long-term viability centers on vertically integrated players controlling foundry access across the 5-10 year policy horizon. Monitor EU AI Act CE marking extension adoption as inflection signal for biometric identification system compliance investment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Consolidation | Direct Shenzhen foundry access secures GB standard compliance timelines for municipal smart city deployments. |
| Open-Platform Architecture Licensing | Third-party analytics accommodation displaces vertically integrated hardware-software bundles in commercial security. |
| Neural Network Optimization Talent Acquisition | 7nm facial recognition pipeline designers command premiums that strain mid-tier vendor R&D budgets. |
| Aviation FPGA Module Premium Positioning | Reconfigurable logic outperforms fixed-function DSPs where post-deployment algorithm updates prove essential. |
| India Smart City Mission Geographic Expansion | BIS standard alignment with H.265/H.266 protocols creates procurement windows for edge AI chip suppliers. |
Research Methodology
Independent corroboration across semiconductor foundry executives, municipal procurement officers, system integration specialists, and railway safety engineers underwrites the qualitative findings. Primary interviews with Shenzhen-based integrators and North American critical infrastructure operators combined with secondary validation from SEC semiconductor filings, SAMR cybersecurity review documentation, EU AI Act conformity assessment guidelines, and Japan METI industrial policy disclosures. Bottom-up bill-of-materials analysis and top-down municipal budget allocation triangulation anchor volume estimates.
Comparable-period anchoring to historical smart city infrastructure deployment timelines and transportation security modernization cycles shapes the projection horizon. Segmentation modeling spans product type, node geometry, application vertical, and end-user budget authority dimensions. CAGRs derive from foundry capacity expansion schedules cross-referenced against municipal procurement pipeline data. Neural network inference workload density specifications and CMOS sensor interface commoditization trajectories inform technology transition assumptions.
Underlying measurement precision varies by segment; transportation security and government end-use categories carry tighter precision than residential DIY channels given budget transparency. Forecasts reflect assumptions around export control regime stability, foundry equipment access, and regulatory compliance timeline execution. Extreme ultraviolet lithography system availability and photoresist chemical supply continuity represent specific revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
USB Wall Charger Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Fixed Capacitor Market
Electronic Components
Gas Discharge Tube Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
Impulse Relays Market
Electronic Components
Data Acquisition Card Market
Electronic Components
Data Bus Market
Electronic Components
Display Port Adapters Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
Crystal Oscillators Market
Electronic Components
Amplifier Market
Electronic Components
PTC Resettable Device Market
Electronic Components
AC Adapter Market
Electronic Components
Braking Resistors Market
Electronic Components
Surface Mountable Laser Direct Structuring Antenna (LDS) Market