
 Chip Shield Market | 2026-2036
Chip Shield Market Size, Share, and Industry Trends Forecast 2026-2036
Chip Shield Market Insights
System-on-chip disaggregation is fragmenting traditional monolithic shielding architectures into modular, chiplet-specific protection schemes. NXP Semiconductors leverages its automotive-grade portfolio to anchor demand from ADAS and powertrain domains. Texas Instruments sustains R&D intensity across precision analog shields for industrial automation. Infineon Technologies dominates silicon carbide-adjacent thermal shielding for traction inverters.
Chip shields are engineered enclosures or coatings—typically fabricated from nickel-iron alloys, conductive polymers, or metallized ceramics—that attenuate electromagnetic interference and dissipate thermal loads across semiconductor packages. Their primary purpose is preserving signal integrity in high-frequency, high-density electronic assemblies where crosstalk and thermal runaway threaten reliability. Passive shielding occupies the largest installed base due to mature stamped-metal manufacturing and broad cross-industry compatibility, while hybrid shielding represents the fastest-expanding category as designers combine absorptive polymers with reflective metal layers to address multi-physics challenges in 5G mmWave and automotive radar modules. RF shielding commands premium margins where aerospace and defense contractors specify custom form factors with traceable material certifications.
The EPA oversees electromagnetic emissions compliance under FCC Part 15 rules that constrain unintentional radiators in consumer and industrial equipment. REACH and RoHS restrict hazardous substances in shielding substrates and surface finishes, compelling suppliers to reformulate plating chemistries and validate alternative alloys. ECHA's evolving SVHC candidate list intensifies material disclosure obligations across European supply chains. Stakeholders must monitor how dual-use export controls and evolving automotive functional safety standards reshape qualification timelines for next-generation shielding platforms.
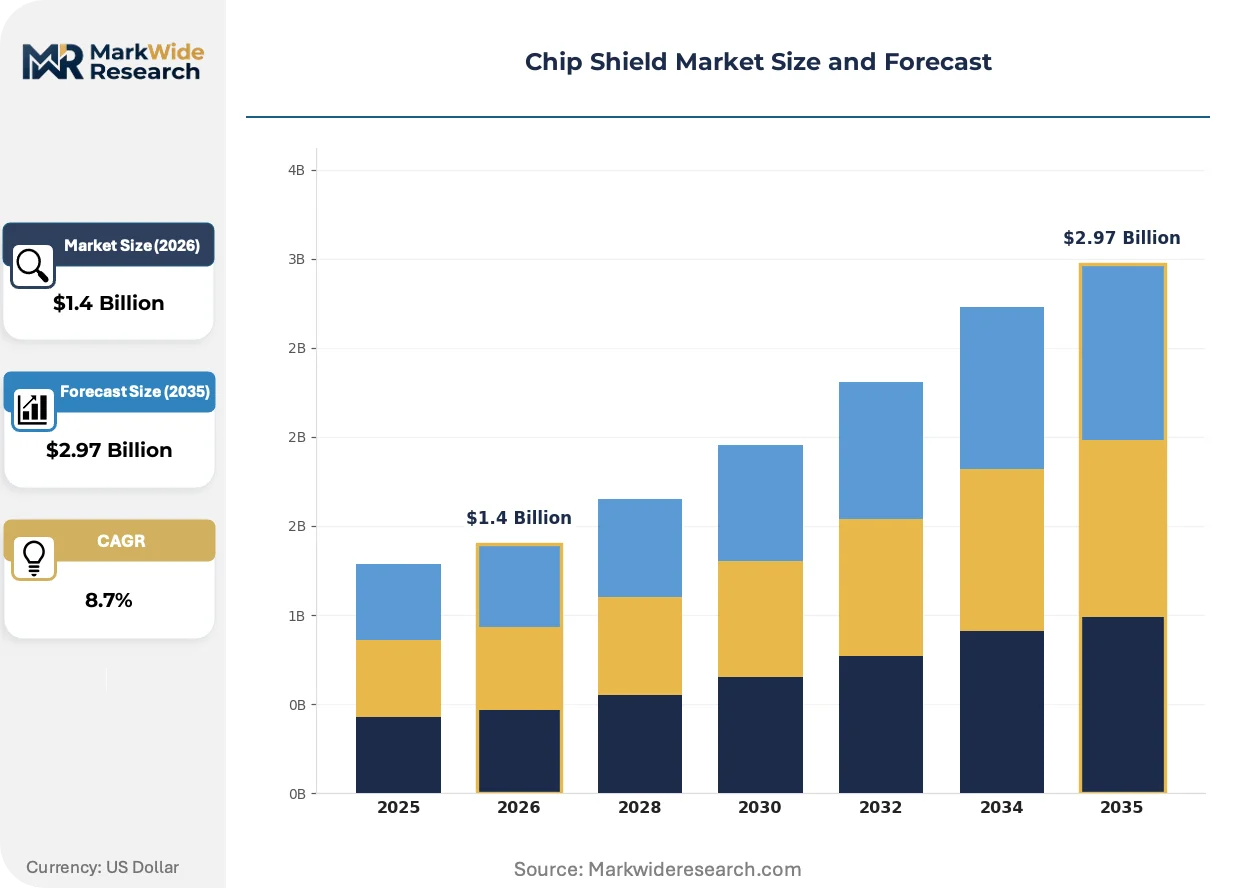
Market Dynamics
System-on-chip disaggregation is fragmenting monolithic shielding architectures into chiplet-specific modular schemes, forcing suppliers to retool for heterogeneous integration across automotive, aerospace, and telecommunications verticals.
Growth Catalysts
- Automotive Electrification:ECU multiplication in battery-electric platforms is expanding shielding requirements across powertrain and ADAS domains. OEM procurement volumes are scaling with 800V architecture rollouts.
- EU F-Gas Regulation:Phase-down of hydrofluorocarbons is compelling thermal shield manufacturers to validate alternative dielectric formulations for high-voltage inverter applications.
- 5G mmWave Deployment:Base station densification and CPE proliferation are accelerating demand for hybrid absorptive-reflective shields that manage multi-physics interference at sub-6 GHz and mmWave bands.
Market Restraints
- Nickel-Iron Alloy Volatility:Permalloy and MuMetal feedstock costs fluctuate with nickel futures, compressing margins for stamped-metal shield producers serving consumer electronics.
- East Asian Supply Concentration:Metallized ceramic substrate fabrication concentrates in Taiwanese and South Korean foundries, exposing buyers to single-source risk during geopolitical disruptions.
- RoHS Material Restrictions:REACH SVHC candidate list expansion is disqualifying legacy hexavalent chromium platings, forcing expensive qualification cycles for replacement chemistries.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging are attracting shielding suppliers to set up captive production for domestic smartphone and automotive module assembly.
- Chiplets in AI Accelerators:Disaggregated GPU and TPU architectures are creating demand for micro-scale shields that protect individual compute tiles in multi-die packages.
- EU Green Deal Procurement:Public sector buying mandates for circular-economy-compliant components are opening preferential channels for shielding suppliers with verified recycled-content alloys.
Industry Challenges
- Multi-Physics Simulation Talent:Electromagnetic-thermal-mechanical co-design expertise remains scarce, delaying optimized shield geometries for heterogeneous integration.
- Automotive Functional Safety Certification:ISO 26262 ASIL-D qualification timelines for shielding in safety-critical ECUs extend 18-24 months, gating revenue recognition.
- Legacy ECU Integration:Backward compatibility requirements for 12V architectures in hybrid vehicle programs complicate shielding designs for mixed-voltage environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chip Shield Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Shielding, Active Shielding, Hybrid Shielding, RF Shielding End User: Automotive, Consumer Electronics, Medical Devices, Aerospace Material: Metal, Plastic, Composite, Ceramic Application: Signal Integrity, Electromagnetic Compatibility, Thermal Management, Environmental Protection |
| Companies Covered | 3M Company, NXP Semiconductors, Texas Instruments, Infineon Technologies, Guardair, EXAIR, Topring, Rockford Systems, Milton Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chip Shield Market Trends and Innovations
Computational electromagnetic modeling is compressing design iteration cycles, while material science advances enable thinner, multifunctional shields that address thermal and interference challenges simultaneously.
Digital twin platforms are virtualizing shield performance validation before physical prototyping. Automotive tier-one suppliers now simulate full vehicle electromagnetic compatibility in silico, reducing hardware build cycles from months to weeks. This virtualization is collapsing traditional sequential design workflows into parallel optimization loops.
ECHA's evolving SVHC candidate list is forcing material disclosure granularity down to smelter-level provenance. Shielding suppliers must now document alloy composition through three tiers of sub-suppliers, with non-compliance triggering automatic disqualification from European automotive and medical device procurement. German OEMs are responding by mandating blockchain-traceable material passports for all metallic components.
Consolidated procurement desks at major electronics manufacturing services firms are compressing supplier panels and demanding system-level shielding responsibility. Foxconn and Jabil are shifting from discrete component sourcing to module-level contracts that bundle shielding with thermal management and structural enclosures. This concentration is most visible in North American and European aerospace programs, where prime contractors now hold single-source agreements for integrated electromagnetic protection systems.
Chip Shield Market Segmentation
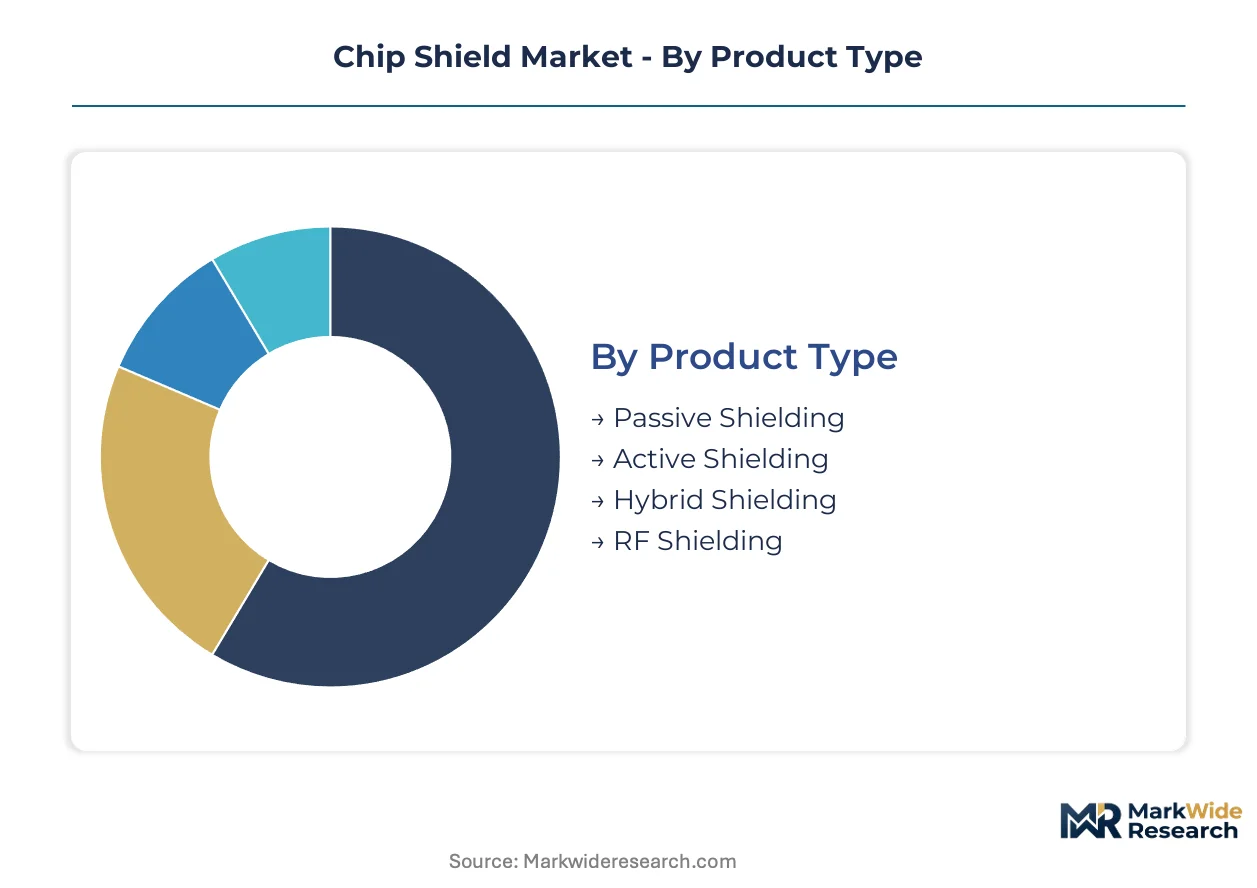
Chip shield segmentation reveals divergent procurement rhythms across product architectures, with stamped-metal solutions cycling through multi-year automotive qualification pipelines while hybrid formulations turn over on smartphone release cadences. Understanding these temporal patterns exposes where inventory risk concentrates and where design-win opportunities emerge fastest.
Product Type:
Passive shielding carries the longest design-in cycles, often locked for vehicle platform lifespans exceeding seven years, while hybrid configurations refresh annually alongside 5G modem generations.
- Passive Shielding:Fabricated from nickel-iron alloys through mature stamping processes, these enclosures deliver cost-effective electromagnetic attenuation across broad frequency ranges. Automotive ECU procurement in Germany anchors volume demand, though RoHS-compliant surface finish conversions are extending qualification timelines. Passive shielding dominates installed base. Hybrid shielding is where expansion concentrates.
- Hybrid Shielding:Combines absorptive polymer substrates with reflective metallized layers to address simultaneous thermal and interference challenges in dense packaging. 5G mmWave base station deployment in South Korea and Japan drives specification intensity, with base station OEMs mandating sub-millimeter thickness tolerances. Hybrid shielding gains share fastest as multi-physics requirements proliferate.
- Active Shielding:Integrates sensor-feedback circuitry for real-time electromagnetic environment adaptation in safety-critical systems.
- RF Shielding:Custom-formulated for aerospace and defense contractors requiring traceable material certifications and lot-specific test data.
Cost stratification separates commodity stamped products from premium custom RF architectures.
End User:
Automotive programs demand eighteen-month ISO 26262 qualification cycles, while consumer electronics procurement compresses to quarterly vendor rotations.
- Automotive:Battery-electric vehicle platforms multiply ECU counts per vehicle, with 800V traction inverters requiring thermal-electromagnetic co-designed shields. German OEM procurement desks consolidate supplier panels around module-level responsibility. Automotive commands premium pricing tiers. Consumer electronics drives volume velocity.
- Consumer Electronics:Smartphone and wearable manufacturers specify ultra-thin shields below 0.3mm for space-constrained designs. Foxconn and Pegatron procurement in Taiwan and China rotate suppliers on product refresh cycles. Consumer electronics turns inventory fastest. Medical devices carries margin concentration.
- Medical Devices:FDA and EMA biocompatibility requirements extend material validation timelines for implantable and diagnostic equipment.
- Aerospace:Prime contractors specify custom form factors with full material provenance documentation for satellite and avionics applications.
Application-specific certification requirements fragment procurement patterns across verticals.
Material:
Metal substrates concentrate in high-volume automotive stamping, while ceramic formulations serve niche thermal management in wide-bandgap semiconductor packaging.
- Metal:Nickel-iron alloys and copper-beryllium variants provide conductive pathways for electromagnetic dissipation with established supply chains. MuMetal feedstock volatility compresses margins for consumer electronics producers. Metal holds volume leadership. Composite materials climb fastest.
- Composite:Carbon-fiber-reinforced polymers with metallized coatings deliver strength-to-weight optimization for aerospace and portable electronics. Japanese material suppliers anchor formulation expertise. Composite expands most quickly in 5G infrastructure.
- Plastic:Conductive polymer compounds enable cost-sensitive applications with moderate shielding effectiveness requirements.
- Ceramic:Aluminum nitride and beryllium oxide substrates manage extreme thermal loads in silicon carbide power modules.
Material selection trades off thermal conductivity against electromagnetic attenuation performance.
Application:
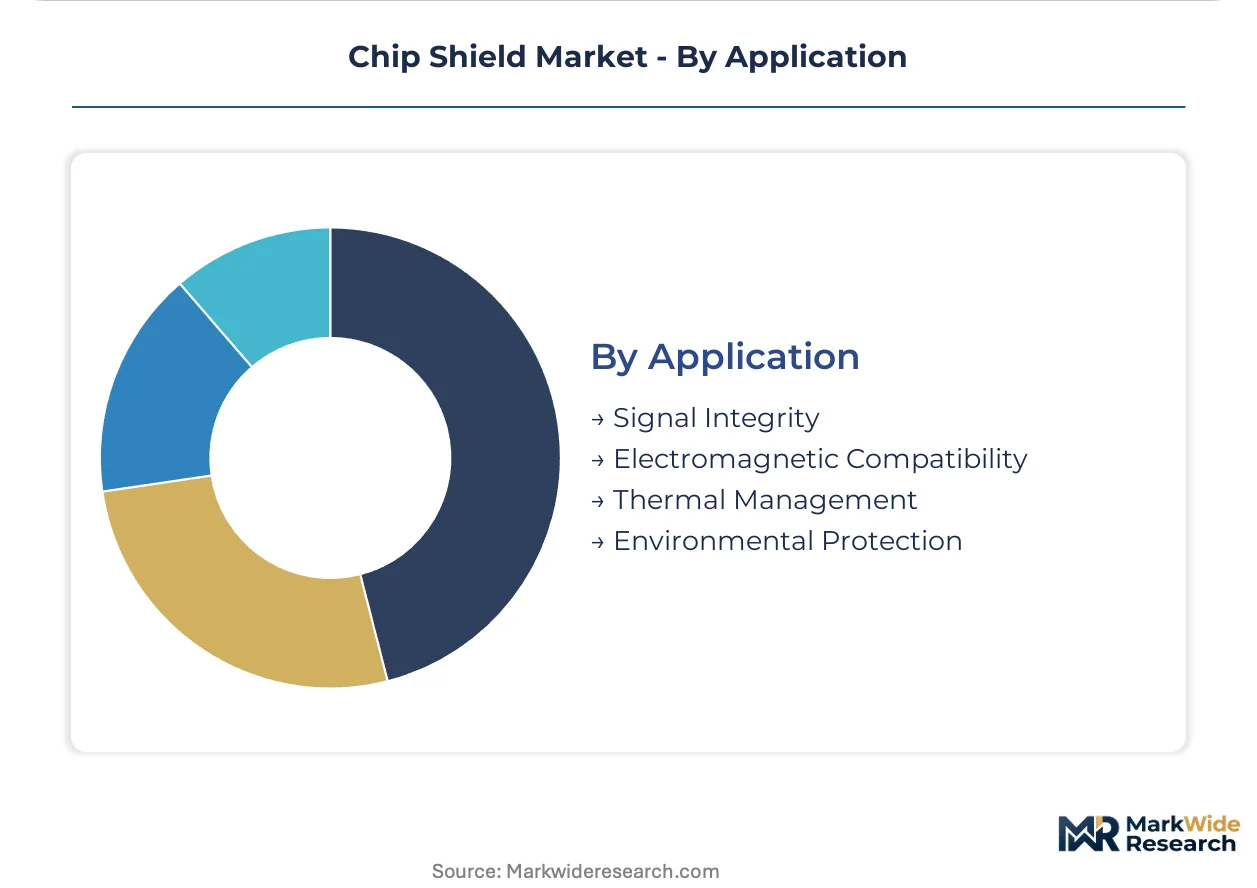
Signal integrity applications command specification intensity in high-speed digital interfaces, while environmental protection serves commodity moisture and particulate sealing.
- Signal Integrity:Preserves data transmission fidelity in DDR5 memory and PCIe 5.0 interconnects through controlled impedance environments. Hyperscale data center buildouts in Virginia and Frankfurt drive demand for rack-level shielding integration. Signal integrity leads specification complexity. Thermal management shows steepest expansion trajectory.
- Thermal Management:Dissipates heat flux from AI accelerators and automotive inverters through conductive spreader and phase-change materials. NVIDIA and Tesla procurement teams co-develop shielding-thermal hybrid solutions. Thermal management is where R&D investment concentrates.
- Electromagnetic Compatibility:Ensures regulatory compliance with FCC Part 15 and CE marking emission limits across consumer and industrial equipment.
- Environmental Protection:Seals against moisture ingress and particulate contamination in outdoor and automotive underhood installations.
Multi-function shields addressing signal, thermal, and environmental challenges simultaneously capture specification momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal Germany as the dominant net importer of precision chip shielding components, while South Korea and Taiwan maintain surplus positions in metallized ceramic substrates. Trade flows concentrate among automotive OEMs sourcing from Asian packaging hubs for European assembly operations.
United States
Hyperscale data center construction in Virginia and Arizona drives rack-level shielding procurement for AI accelerator clusters. The FCC enforces Part 15 emission limits on consumer electronics, compelling shielding validation for 5G CPE devices. Austin and Phoenix anchor semiconductor packaging corridors where Texas Instruments and NXP maintain captive shielding specifications.
Germany
Automotive ECU multiplication across BMW and Volkswagen battery-electric platforms expands shielding volumes for 800V traction inverters. The EU F-Gas Regulation phases down hydrofluorocarbon dielectrics, forcing thermal shield reformulation. Stuttgart and Munich host tier-one supplier engineering centers where ISO 26262 ASIL-D qualification cycles extend eighteen to twenty-four months.
China
Domestic smartphone assembly for Xiaomi and OPPO rotates shielding suppliers on quarterly product refresh cadences. MIIT enforces GB standards for electromagnetic compatibility in telecommunications infrastructure. Shenzhen and Dongguan concentrate Foxconn and Pegatron module assembly operations demanding sub-millimeter thickness tolerances.
South Korea
5G mmWave base station deployment by Samsung Networks accelerates hybrid shield adoption for sub-6 GHz and mmWave coexistence. The MFDS regulates medical device electromagnetic safety, extending material validation timelines for diagnostic equipment. Suwon and Pyeongtaek host semiconductor packaging clusters where thermal-electromagnetic co-design expertise commands premium procurement terms.
Japan
Automotive radar module production for Toyota and Honda ADAS platforms specifies custom form factors with traceable material certifications. METI promotes domestic semiconductor packaging reshoring through subsidy programs. Kyoto and Nagoya anchor precision metal stamping operations serving aerospace and defense contractors with lot-specific test data requirements.
Chip Shield Market Competitive Landscape
On the supply side, the industry is consolidating around module-level responsibility contracts that bundle shielding with thermal management and structural enclosures. Tier-one automotive suppliers and electronics manufacturing services firms compress supplier panels, favoring partners with multi-physics simulation capabilities and three-tier material provenance documentation. Two strategic archetypes dominate: integrated semiconductor manufacturers with captive shielding specifications, and specialized electromagnetic protection fabricators serving aerospace and medical verticals. Competitive moves center on geographic expansion into India under PLI scheme incentives and technology licensing for chiplet-specific modular shield architectures.
Among integrated semiconductor manufacturers, NXP Semiconductors, Texas Instruments, and Infineon Technologies exemplify the captive-specification archetype. These firms anchor demand through internal R&D intensity and direct procurement control across automotive and industrial automation domains. Specialized fabricators occupy positions in custom RF shielding where traceable material certifications and ASIL-D qualification capabilities determine supplier selection. The competitive terrain rewards backward integration into metallized ceramic substrate production and upstream control over nickel-iron alloy feedstock sourcing.
| Leading Market Players |
|---|
| 3M Company |
| NXP Semiconductors |
| Texas Instruments |
| Infineon Technologies |
| Guardair |
| EXAIR |
| Topring |
| Rockford Systems |
| Milton Industries |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's metallized ceramic substrate cluster feeds global shielding demand through Foxconn and Pegatron assembly lines, translating capacity tightness into pricing leverage for hybrid shield configurations. German automotive OEMs absorb premium markups for ASIL-D qualified components while consumer electronics procurement drives cost compression in stamped-metal tiers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with ISO 26262 certification grade and volume scale as primary differentiation drivers. Cost compression in consumer electronics stamped-metal tiers is intensifying because nickel-iron alloy feedstock volatility compresses fabricator margins. Medical device and aerospace buyers show least price sensitivity due to traceable material certification requirements.
Supply Chain Analysis
Dual-use export controls on advanced metallization equipment limit substrate fabrication technology flows to non-allied packaging hubs. Taiwan, South Korea, and Japan concentrate metallized ceramic supply, drawing from nickel-iron alloy feedstocks, conductive polymer resins, and precision stamping tooling. Single-source vulnerability in Taiwanese foundry capacity feeds downstream disruption risk. Distribution runs through consolidated EMS procurement desks bundling shielding with thermal management modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chiplet disaggregation is shifting competitive dynamics toward modular shielding platforms interoperable across heterogeneous integration supply chains, rewarding suppliers with chiplet-specific architecture expertise.
For Market Incumbents: Entrench module-level responsibility contracts with automotive tier-one suppliers by adding captive metallized ceramic substrate production in Germany or South Korea. Deepen backward integration into nickel-iron alloy sourcing to defend against feedstock volatility eroding stamped-metal margins. Prioritize ASIL-D certification pipeline investment to extend eighteen-month qualification moats against emerging competitors.
For New Entrants and Emerging Players: India's PLI scheme subsidized semiconductor packaging corridors offer white-space access for domestic smartphone and automotive module assembly shielding supply. Target hybrid shield configurations for 5G mmWave base station OEMs in South Korea and Japan as the most penetrable premium segment. Pursue technology licensing partnerships with established Japanese material suppliers to shortcut formulation expertise gaps.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized electromagnetic protection divisions lacking chiplet-specific R&D investment. Long-term viability hinges on exposure to automotive electrification and AI accelerator buildouts rather than consumer electronics cyclicality. Monitor ECHA SVHC candidate list expansion velocity as an inflection indicator for material disclosure compliance cost escalations favoring integrated suppliers with blockchain-traceable provenance systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallized Ceramic Substrates | Captive supply of Taiwan-dependent substrates reduces single-source risk for automotive OEM qualification pipelines. |
| ASIL-D Certification Investment | Eighteen-month ISO 26262 qualification cycles create defensive moats against lower-tier competitors in safety-critical ECU supply. |
| India PLI Scheme Manufacturing Footprint | Domestic production for Xiaomi and OPPO module assembly captures smartphone refresh cycle volume velocity. |
| Chiplet-Specific Modular Shield Architecture Licensing | Technology transfer agreements with Japanese material suppliers accelerate entry into AI accelerator heterogeneous integration supply chains. |
| Blockchain-Traceable Material Passport Implementation | Three-tier smelter-level provenance documentation satisfies German OEM mandates for European Green Deal procurement eligibility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade databases, ECHA regulatory submissions, and semiconductor packaging equipment utilization reports. Primary interviews engaged electromagnetic protection R&D directors, automotive tier-one supplier procurement managers, EMS contract manufacturing leads, and metallized ceramic substrate fabrication engineers. Bottom-up demand modeling triangulates against top-down supply capacity assessments across the analysis window.
Forecast inputs span passive, hybrid, active, and RF shielding product architectures alongside automotive, consumer electronics, medical device, and aerospace end-use verticals. Modeled dimensions include material substrate type, application function, and regional regulatory cluster. CAGRs derive from segment-level volume trajectories calibrated against OEM platform rollout schedules and base station deployment pipelines without year-specific anchoring.
Practitioners should monitor REACH SVHC candidate list expansion, nickel futures volatility, and dual-use export control tightening for early signals of forecast deviation. Material shifts in automotive functional safety standard revisions or chiplet packaging technology adoption curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
TWS and Noise-Cancelling Headphone with MEMS Chip Market
Electronic Components
Stretchable Conductors in Electronics Market
Electronic Components
Global Circuit Protection Market
Electronic Components
North America Miniature Ball Bearing Market
Electronic Components
Dual Relay Board Market
Electronic Components
Digital Isolator Market
Electronic Components
Speaker Cone Material Market
Electronic Components
Capacitor Aluminum Polymer Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
Coaxial Attenuators Market
Electronic Components
Fixed Capacitor Market
Electronic Components
Surface Mountable Laser Direct Structuring Antenna (LDS) Market
Electronic Components
Microcontroller Socket Market
Electronic Components
Switch Diode Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
PTC Resettable Device Market