
 North America USB Retimer Market | 2026-2036
North America USB Retimer Market Size, Share, and Industry Trends Forecast 2026-2036
North America USB Retimer Market Insights
High-speed signal conditioning is tilting toward USB4 and Thunderbolt 4 architectures as data rates exceed 20 Gbps across enterprise and consumer platforms. Texas Instruments leverages its analog semiconductor heritage to anchor design wins in industrial automation gateways. Astera Labs specializes in cloud-optimized retimer silicon for hyperscale data center backplanes. Broadcom extends its portfolio through PCIe-USB convergence chips that compete for socket space in enterprise servers.
A USB retimer is a mixed-signal integrated circuit that recovers clock and data from degraded high-speed serial streams, typically operating at 10–40 Gbps to restore signal integrity across printed circuit board traces and cable assemblies. The device employs continuous time linear equalization and decision feedback equalization to compensate for insertion loss and inter-symbol interference in multi-gigabit channels. Standalone retimers occupy the premium margin pool in test equipment and aerospace systems where modular upgrade paths matter. Integrated retimers dominate consumer electronics volumes as laptop and docking station OEMs prioritize board space over flexibility. Thunderbolt 4 represents the fastest-growing technology segment, driven by docking station and external GPU enclosures requiring 40 Gbps symmetric throughput.
FCC equipment authorization requirements govern electromagnetic compatibility for USB retimers sold into US consumer and commercial channels, while NHTSA functional safety standards shape automotive electronics qualification timelines. The EPA's emerging e-waste directives are pressuring OEMs to design for longer service intervals, indirectly favoring retimer architectures that extend cable and connector lifecycles. Stakeholders must monitor how USB-IF specification updates and state-level procurement standards for government data centers reshape supplier qualification criteria.
Market Dynamics
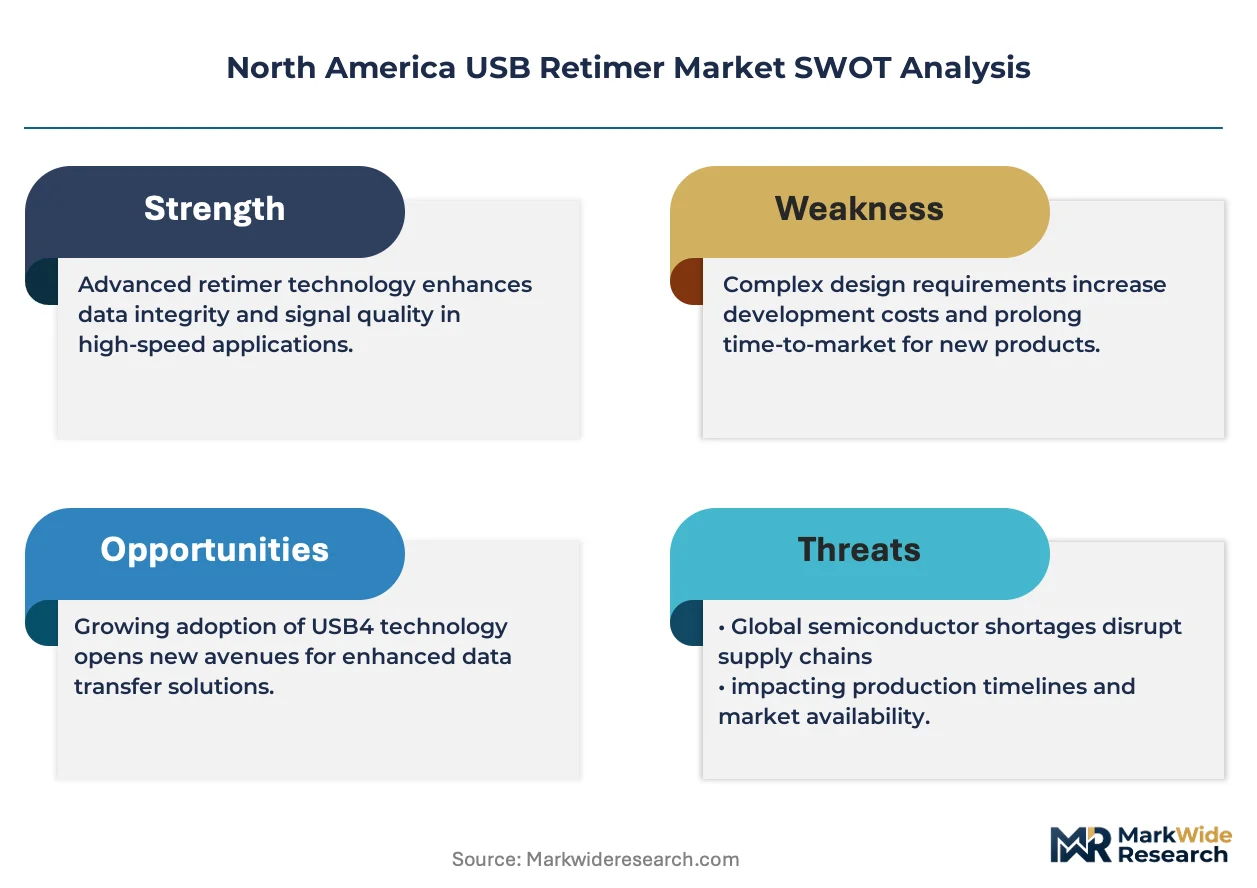
Data center operators across the United States are driving retimer demand as server backplanes push beyond 20 Gbps signal rates, forcing signal integrity architectures to migrate from redrivers to retimers for PCIe-USB convergence applications.
Growth Catalysts
- USB4 specification mandates:The USB-IF's 40 Gbps symmetric throughput requirements in enterprise docking stations create mandatory retimer insertion for signal conditioning compliance.
- Hyperscale buildouts:Cloud infrastructure expansion in California's Silicon Valley corridor concentrates procurement volumes for backplane-optimized retimer silicon.
- Thunderbolt 4 ecosystem:External GPU enclosures and high-resolution display chains require retimer-enabled cable assemblies for 40 Gbps sustained transmission.
Market Restraints
- Advanced process node dependency:Retimer silicon fabrication concentrates at 7nm and 5nm foundry capacity, creating allocation bottlenecks for mixed-signal designs.
- FCC equipment authorization friction:Electromagnetic compatibility testing timelines for high-speed digital devices extend qualification cycles by four to six months.
- Integrated PHY substitution:System-on-chip vendors are embedding retimer functionality directly into USB4 host controllers, compressing standalone socket opportunities.
Strategic Opportunities
- Automotive USB-C proliferation:NHTSA functional safety standards for in-vehicle infotainment create qualification pathways for AEC-Q100 retimer variants.
- Industrial automation gateways:Factory floor equipment migrating to USB4 for machine vision requires extended-temperature retimer solutions.
- EPA e-waste directives:Extended cable lifecycle requirements favor retimer architectures that reduce connector replacement frequency in enterprise deployments.
Industry Challenges
- SerDes architecture specialization:Mixed-signal design talent capable of 40 Gbps clock-data recovery circuits remains concentrated among analog semiconductor veterans.
- Multi-protocol verification complexity:Retimers must simultaneously validate USB4, Thunderbolt 4, and DisplayPort 2.1 interoperability, extending test matrix timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America USB Retimer Market |
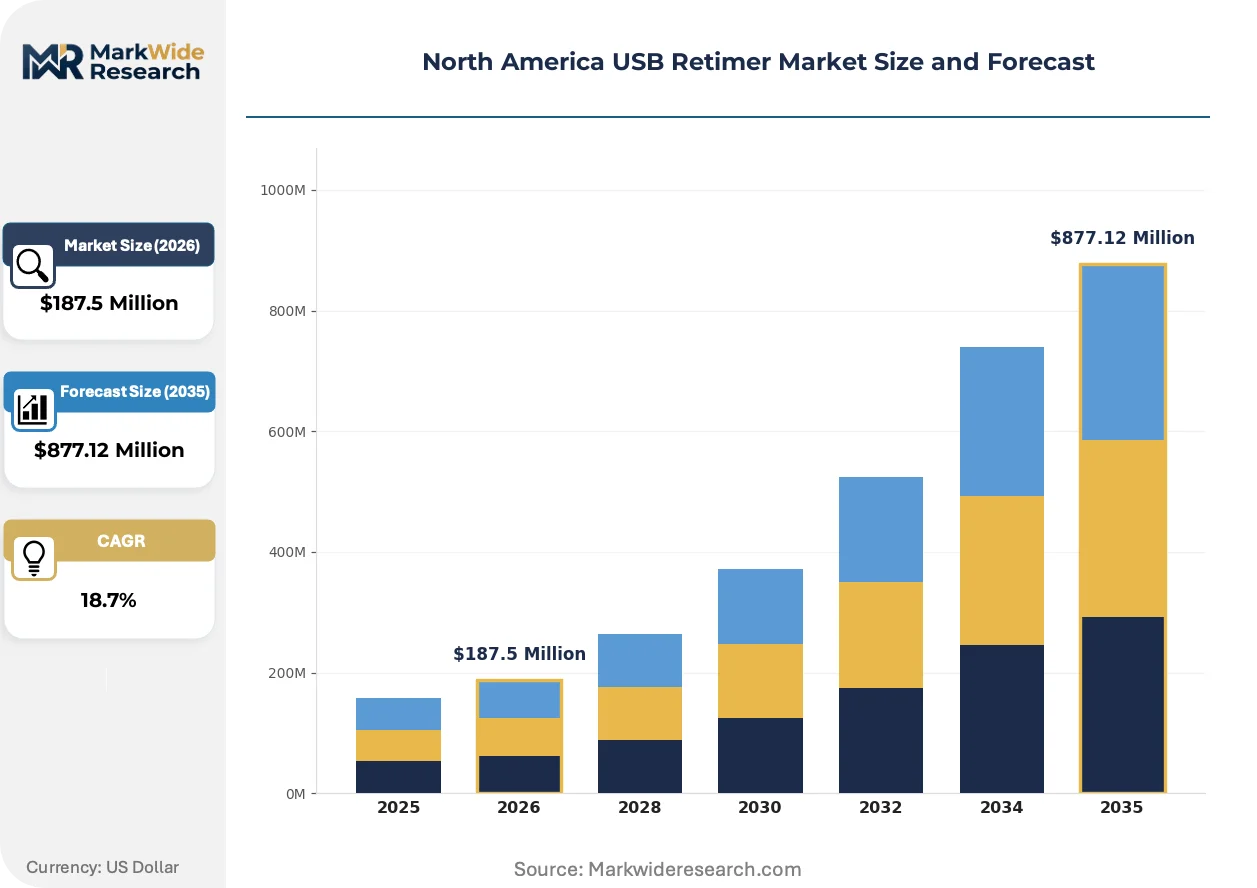
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $877.12 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Retimers, Integrated Retimers, Active Retimers, Passive Retimers Technology: USB 3.1, USB 3.2, USB4, Thunderbolt 3, Thunderbolt 4 Application: Consumer Electronics, Data Communication, Industrial Automation, Automotive Electronics, Aerospace Systems End User: Original Equipment Manufacturers, Aftermarket Vendors, System Integrators, Data Centers, Telecom Providers |
| Companies Covered | Astera Labs, Texas Instruments, Broadcom, Intel, Marvell, Parade Technologies, Analogix, Diodes Incorporated, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America USB Retimer Market Trends and Innovations
Signal conditioning architectures are fragmenting across discrete retimer, integrated PHY, and protocol-agnostic redriver approaches as data rates bifurcate between consumer cost optimization and enterprise performance requirements.
Active cable retimer integration is hybridizing copper assembly economics by embedding signal conditioning chips directly within connector overmolds rather than host PCB placement. Laptop OEMs in the United States are adopting this for premium ultrabook SKUs where board space constraints dominate. The shift is compressing traditional discrete retimer socket counts in consumer volumes while creating captive semiconductor opportunities for cable assemblers.
FCC equipment authorization rules for unintentional radiators are tightening electromagnetic compatibility thresholds for USB retimers operating above 6 GHz fundamental frequencies. Manufacturers must now submit expanded test reports for harmonic emissions in commercial channel deployments. Data center equipment vendors are responding by front-loading pre-compliance scanning into design validation cycles.
Hyperscale procurement patterns are consolidating retimer sourcing around qualified vendor lists with multi-year supply agreements. Cloud operators in Texas and Virginia are displacing spot-market purchasing with direct foundry allocation commitments. This concentration is visible most acutely in enterprise server backplane applications where socket standardization reduces qualification overhead.
North America USB Retimer Market Segmentation
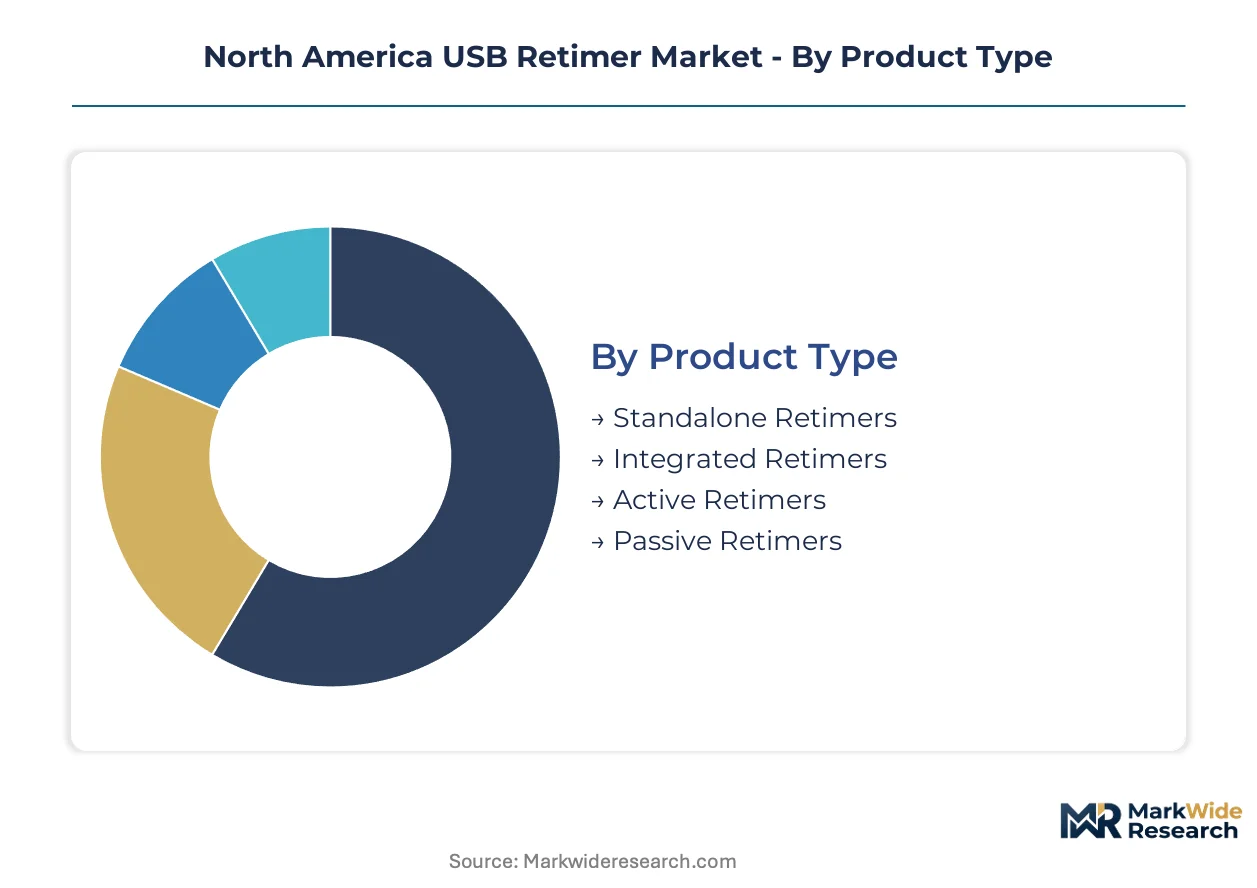
USB retimer segmentation reflects divergent margin structures across discrete versus integrated architectures, with after-sales service intensity varying sharply between modular standalone designs and embedded consumer solutions. Procurement patterns in North America cluster around application-specific qualification requirements that reshape supplier economics across each tier.
Product Type:
After-sales service intensity peaks with standalone retimers requiring field-replaceable modules and extended calibration cycles, while integrated variants minimize service touchpoints through permanent PCB mounting.
- Standalone Retimers:Modular mixed-signal devices packaged in QFN or BGA form factors enabling socketed replacement in test equipment and aerospace backplanes. Procurement concentrates in California's defense corridor and Texas instrumentation clusters where FCC Part 15 compliance documentation demands traceable calibration histories.
- Integrated Retimers:Die-level IP blocks embedded within USB4 host controllers and docking station SoCs, eliminating discrete component procurement entirely. Demand localizes to Taiwan ODM supply chains serving US laptop OEMs, with validation cycles compressed through USB-IF certification pre-approval.
- Active Retimers:Signal-conditioning silicon with integrated power management for cable-embedded applications. Automotive USB-C adoption in Michigan and Ohio drives qualification volumes for AEC-Q100 temperature grades.
- Passive Retimers:Lower-complexity redriver alternatives lacking clock-data recovery circuits. Cost-sensitive consumer peripheral assemblers in Mexico's Baja California corridor specify these for sub-10 Gbps legacy applications.
Standalone retimers hold the largest share; momentum sits with integrated retimers.
Technology:
Cost tier stratification separates legacy USB implementations from premium Thunderbolt architectures, with foundry node requirements driving 3-4x die cost differentials between generations.
- USB4:40 Gbps symmetric retimer silicon fabricated at 7nm and 5nm nodes with mandatory USB-IF certification. Hyperscale data center buildouts in Virginia's Loudoun County and Texas's Hays County anchor procurement volumes for backplane-optimized variants.
- Thunderbolt 4:Intel-certified 40 Gbps retimers with DisplayPort 2.1 tunneling and PCIe 3.0 x4 support. External GPU enclosure manufacturers in Seattle and Portland drive docking station socket demand.
- USB 3.2:20 Gbps retimer architectures serving cost-optimized enterprise peripherals. Volume procurement localizes to contract manufacturers in Guadalajara supplying US commercial channel distributors.
- Thunderbolt 3:Legacy 40 Gbps implementations displaced by USB4 convergence but retained in installed base upgrade cycles. Professional audio/video integrators in Los Angeles and New York maintain spare inventory for field replacement.
- USB 3.1:10 Gbps retimer solutions approaching end-of-life in new designs. Industrial automation OEMs in Illinois and Wisconsin specify these for extended-temperature gateway applications with 10-year supply guarantees.
USB4 holds the largest share; Thunderbolt 4 is gaining share fastest.
Application:
Customer type fragmentation separates high-volume consumer electronics procurement from low-volume, high-margin aerospace qualification pathways with radically different sales cycle economics.
- Consumer Electronics:Laptop, docking station, and smartphone retimer demand dominated by USB4 integration. California-based OEMs specify active cable architectures to compress board space in ultrabook designs.
- Data Communication:Server backplane and storage array retimer deployment driven by PCIe-USB convergence at 25 Gbps and above. Cloud operators in Washington's Quincy and Oregon's Boardman concentrate hyperscale procurement.
- Industrial Automation:Factory floor USB4 migration for machine vision and sensor aggregation. Extended-temperature retimers qualified to -40°C anchor design wins in Michigan automotive tooling and Ohio steel processing.
- Automotive Electronics:In-cabin infotainment and ADAS data backbone retimers subject to NHTSA functional safety documentation. Detroit Three qualification programs specify AEC-Q100 Grade 2 variants for central gateway modules.
- Aerospace Systems:DO-254 traceable retimers for avionics data buses with mandatory obsolescence management. Boeing and Lockheed Martin supplier lists in Washington and Texas concentrate modular standalone procurement.
Consumer electronics holds the largest share; data communication is expanding most quickly.
End User:
Supply concentration varies sharply between captive OEM integration teams and fragmented aftermarket distribution, with data center direct procurement representing an intermediate consolidation tier.
- Original Equipment Manufacturers:Laptop, smartphone, and automotive Tier 1 suppliers with in-house signal integrity teams. USB-IF membership and early specification access differentiate procurement capabilities.
- Data Centers:Hyperscale and enterprise colocation operators sourcing backplane retimers through qualified vendor lists. Multi-year foundry allocation agreements displace spot market purchasing for PCIe-USB convergence silicon.
- System Integrators:Industrial and medical equipment assemblers specifying retimers for custom backplane designs. Regional integrators in Massachusetts and North Carolina maintain relationships with analog semiconductor distributors.
- Telecom Providers:5G fronthaul and edge compute infrastructure deployers. Verizon and AT&T procurement specifications emphasize FCC Part 27 emissions compliance for outdoor cabinet installations.
- Aftermarket Vendors:Repair depots and spare parts distributors serving legacy equipment installed base. Obsolescence management services and counterfeit avoidance protocols dominate supplier selection.
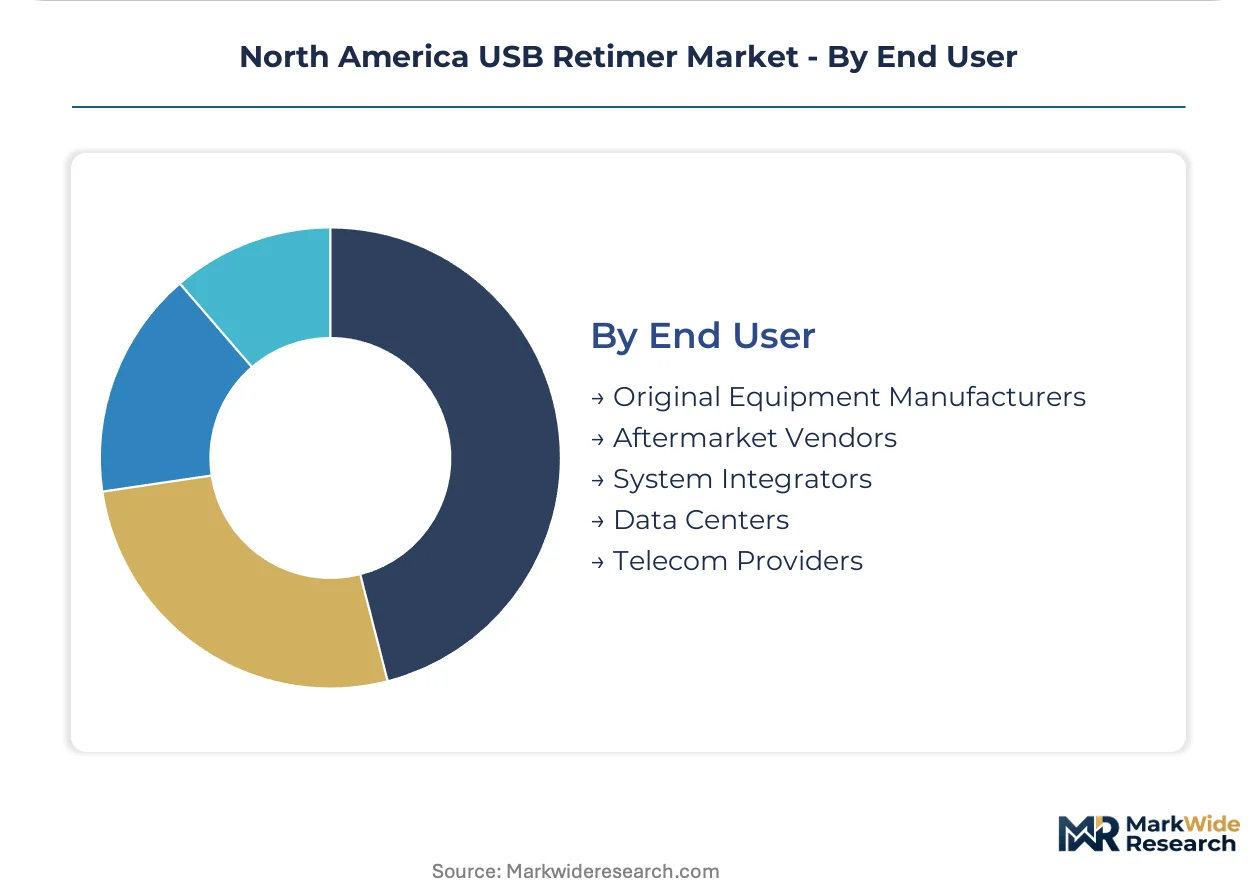
OEMs hold the largest share; data centers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center operators and automotive Tier 1 suppliers concentrate procurement volumes across distinct North American corridors, with regulatory compliance requirements varying by sub-regional industrial specialization.
United States
Cloud infrastructure buildouts in Virginia's Loudoun County and Texas's Hays County anchor retimer demand for PCIe-USB convergence at 40 Gbps. FCC equipment authorization rules for unintentional radiators govern electromagnetic compatibility testing timelines. California's Silicon Valley corridor hosts design win competitions among analog semiconductor vendors serving docking station OEMs.
Canada
Enterprise server backplane deployments in Ontario's Greater Toronto Area drive qualification volumes for extended-temperature retimer variants. Health Canada's equipment authorization framework aligns with FCC Part 15 thresholds for cross-border commercial channel access. British Columbia's Vancouver tech corridor concentrates procurement for external GPU enclosure assemblers.
Mexico
Contract manufacturing clusters in Guadalajara and Tijuana handle cost-optimized USB 3.2 retimer integration for US consumer peripheral distributors. The country's federal telecommunications regulator oversees equipment type approval for imported high-speed digital devices. Baja California's assembly corridors specialize in passive redriver alternatives for sub-10 Gbps legacy applications.
Pacific Northwest
External GPU enclosure manufacturers in Seattle and Portland drive Thunderbolt 4 retimer socket demand for 40 Gbps symmetric throughput. Washington State's clean energy mandates shape data center construction timelines affecting backplane procurement cycles. Oregon's Boardman hyperscale facilities concentrate direct foundry allocation agreements for cloud-optimized silicon.
Midwest Automotive Belt
Detroit Three qualification programs in Michigan and Ohio specify AEC-Q100 Grade 2 retimer variants for central gateway modules. NHTSA functional safety documentation requirements extend automotive electronics validation cycles. Indiana and Illinois industrial automation OEMs specify extended-temperature USB4 solutions for machine vision deployments.
North America USB Retimer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement hierarchies. The vendor base stratifies between analog semiconductor incumbents with mixed-signal heritage and cloud-optimized fabless specialists. Three archetypes dominate: legacy diversified analog suppliers, hyperscale-focused retimer pure-plays, and integrated PHY vendors embedding functionality into host controllers. Competitive moves concentrate on strategic partnerships for foundry allocation security and portfolio diversification into automotive qualification pathways.
Within the cloud-optimized tier, Astera Labs and Marvell exemplify fabless specialists targeting hyperscale backplane applications with protocol-specific architectures. Texas Instruments represents the diversified analog incumbent archetype, leveraging decades of mixed-signal integration expertise across industrial and automotive qualification tiers. These three anchors illustrate the competitive tension between modular standalone solutions and integrated approaches compressing discrete socket opportunities.
| Leading Market Players |
|---|
| Astera Labs |
| Texas Instruments |
| Broadcom |
| Intel |
| Marvell |
| Parade Technologies |
| Analogix |
| Diodes Incorporated |
| Microchip Technology |
| Others |
Pricing and Supply Chain Analysis
The Los Angeles-Long Beach freight corridor's volatile container rates cascade through North American retimer procurement, amplifying cost-plus contract indexation for 7nm and 5nm wafer supply while compressing margins on USB4 silicon bound for Guadalajara assembly lines. Texas and Virginia data center operators leverage multi-year foundry allocations to insulate effective pricing from spot-market DRAM and advanced packaging swings, whereas Mexican contract manufacturers absorb tariff-adjusted component costs into passive redriver quotations for legacy peripheral channels.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate hyperscale procurement, with USB4 retimer pricing stratifying across AEC-Q100 automotive certification tiers, USB-IF compliance validation levels, and foundry node geometries. Pricing pressure stems from integrated PHY substitution in laptop host controllers, compressing standalone socket premiums. Consumer electronics OEMs exhibit highest price sensitivity, prioritizing die-size reduction over signal integrity margins; aerospace and test equipment buyers accept 3-4x markups for modular field-replaceability and traceable calibration documentation.
Supply Chain Analysis
Export-control restrictions on extreme ultraviolet lithography equipment constrain 5nm retimer fabrication to Taiwan and South Korea, with South Korean memory-integrated foundries and US-based analog specialists handling legacy node alternatives. Raw material dependencies center on silicon wafers, gold wirebond supplies, and epoxy mold compounds for QFN packaging. Single-source vulnerability concentrates at TSMC's leading-edge capacity for 40 Gbps USB4 designs. Distribution runs through qualified vendor lists for hyperscale direct procurement, while spot-market distributors serve industrial automation and aftermarket repair channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as PCIe-USB convergence bifurcates procurement between hyperscale backplane optimization and cost-constrained consumer integration, creating distinct competitive arenas with divergent qualification barriers and margin structures.
For Market Incumbents: Entrench foundry allocation security through multi-year wafer agreements with Samsung and TSMC, locking in 7nm capacity ahead of USB4 volume ramps. Defend against integrated PHY substitution by deepening AEC-Q100 automotive certification pipelines in Michigan and Ohio, where NHTSA documentation requirements create sticky qualification relationships. Prioritize backward integration into advanced packaging capabilities to capture margin otherwise ceded to OSAT providers.
For New Entrants and Emerging Players: Establish a beachhead in industrial automation gateways, where extended-temperature USB4 requirements in Illinois and Wisconsin lack incumbent saturation. Target aftermarket aerospace obsolescence management services for Boeing and Lockheed Martin supplier lists, where DO-254 traceability commands premium pricing. Pursue fabless specialization in active cable retimer silicon, embedding signal conditioning into connector overmolds to bypass crowded host PCB socket competition.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified analog conglomerates with undermonetized retimer IP blocks, particularly those holding PCIe-USB convergence patents without hyperscale go-to-market infrastructure. Long-term viability hinges on protocol-agnostic SerDes architectures spanning USB4, Thunderbolt 4, and emerging optical interconnect standards. Monitor Intel's Thunderbolt certification policy shifts as the critical inflection signal; loosened royalty structures would compress pure-play retimer valuations while expanding TAM for integrated alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Allocation Agreement | TSMC 5nm capacity commitments secure supply for Virginia hyperscale backplane deployments. |
| AEC-Q100 Certification Pathway | Grade 2 qualification opens Detroit Three central gateway module procurement to retimer vendors. |
| Active Cable Integration | Embedding silicon in connector overmolds addresses California ultrabook board space constraints. |
| Multi-Protocol SerDes Development | Unified USB4-Thunderbolt 4-DisplayPort 2.1 architectures reduce test matrix timelines for OEMs. |
| Obsolescence Management Service | DO-254 traceable inventory programs capture Boeing and Lockheed Martin aftermarket replacement cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center infrastructure architects, automotive Tier 1 signal integrity engineers, analog semiconductor product managers, and FCC equipment authorization consultants. Secondary validation drew from USB-IF certification databases, SEC 10-K filings of listed semiconductor vendors, hyperscaler capex disclosure reports, and NHTSA functional safety guidance documents. Bottom-up segment sizing triangulated against top-down wafer demand forecasts from foundry utilization reports.
Calibration against historical USB retimer shipment data and foundry revenue disclosures anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, technology generation, application vertical, and end-user procurement tier, with additional stratification by foundry node geometry and certification grade. CAGRs derived from fitted growth curves applied to wafer allocation forecasts and hyperscale server unit projections. Industry-specific inputs incorporated PCIe-USB convergence adoption curves and Thunderbolt 4 docking station attach rates.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or cloud infrastructure buildout pacing would shift the trajectory. Forecasts reflect assumptions on USB-IF specification stability, foundry capacity expansion timelines, and FCC electromagnetic compatibility threshold evolution. Material shifts in export-control restrictions on advanced lithography equipment or Intel's Thunderbolt licensing posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
High Temperature Capacitor Market
Electronic Components
Amplifier Market
Electronic Components
Passive Attenuator Market
Electronic Components
Audio Power Amplifier Market
Electronic Components
Motherboard Battery Market
Electronic Components
Asia Pacific Safety Relays and Timers Market
Electronic Components
Pneumatic Components Market
Electronic Components
China Crystal Oscillator Market
Electronic Components
RAID Controller Card Market
Electronic Components
Fixed Capacitor Market
Electronic Components
Microcontroller Socket Market
Electronic Components
Battery Holders Market
Electronic Components
Industrial Relays Market
Electronic Components
Braking Resistors Market
Electronic Components
Global Smartphone Cover Glass Market
Electronic Components
Fuel Pump Driver Module Market