
 HVDC Converters Market | 2026-2036
HVDC Converters Market Size, Share, and Industry Trends Forecast 2026-2036
HVDC Converters Market Analysis
Utility procurement consolidation around mega-project developers is recalibrating supplier qualification criteria across the HVDC converter supply base. Siemens Energy leverages its manufacturing scale to anchor long-term service contracts for offshore converter platforms. Hitachi Energy competes through technology leadership in modular multilevel converter architectures for subsea applications. Mitsubishi Electric specializes in high-voltage thyristor-based line commutated systems for bulk power transmission corridors in Asia.
High-voltage direct current converters transform alternating current to direct current and back, enabling efficient power transmission across distances exceeding 600 kilometers with losses below 3% per 1,000 km. Modular multilevel converter technology dominates new project awards due to its black-start capability and compact footprint for offshore installations. Voltage source converter configurations represent the fastest-expanding technology segment as grid operators prioritize reactive power control and multi-terminal network flexibility. Line commutated converter systems retain cost advantages for ultra-high-capacity point-to-point links where bidirectional flow timing is predictable.
Grid interconnection applications face evolving compliance requirements under EU TEN-E regulation, China's GB/T standards for ultra-high voltage DC, and FERC Order 2023 interconnection reforms in the United States. CE marking under the EU Machinery Directive and IEC 62501 testing protocols shape product certification timelines and market access for converter station suppliers. Stakeholders must monitor how national renewable integration targets redefine converter redundancy specifications and dynamic performance benchmarks before committing to platform designs.
Market Dynamics
Modular multilevel converter technology is compressing project timelines for offshore wind integration, while procurement consolidation around mega-project developers forces suppliers to restructure qualification frameworks and long-term service architectures.
Growth Catalysts
- Offshore wind procurement:Developers in the North Sea and Baltic regions are expanding voltage source converter station orders to connect distant wind farms to onshore grids. This pulls demand for black-start capable platforms.
- FERC Order 2023:Interconnection reforms in the United States mandate faster grid access studies and standardized cost allocation, accelerating converter deployment timelines for renewable projects.
- Subsea interconnectors:National grid operators across Germany, Norway, and the United Kingdom are awarding contracts for multi-terminal HVDC links that require advanced reactive power control capabilities.
Market Restraints
- Semiconductor supply concentration:Insulated-gate bipolar transistor modules depend on fabrication capacity concentrated in East Asian foundries, exposing project schedules to geopolitical disruption.
- Specialized vessel scarcity:Heavy-lift installation ships for offshore converter platforms face booking backlogs exceeding 24 months, compressing construction windows.
- Labor cost escalation:Skilled commissioning engineers for high-voltage direct current systems command premium rates in Denmark and Germany, inflating total installed cost structures.
Strategic Opportunities
- Brazil-Argentina interconnection:Planned bi-national transmission corridors present untapped demand for line-commutated converter systems suited to predictable bulk power flows.
- Green hydrogen offtake:Electrolyzer manufacturers in Australia and Saudi Arabia require dedicated HVDC supply for gigawatt-scale renewable-powered hydrogen facilities.
- IEC 62501 harmonization:Convergence around standardized testing protocols for voltage source converters reduces certification duplication, opening access for new equipment suppliers.
Industry Challenges
- Control system integration:Grid operators demand seamless coordination between converter stations and legacy supervisory control systems, forcing complex software customization.
- Subsea cable repair protocols:Fault location and jointing procedures for damaged interconnectors require specialized vessel mobilization, extending outage durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVDC Converters Market |
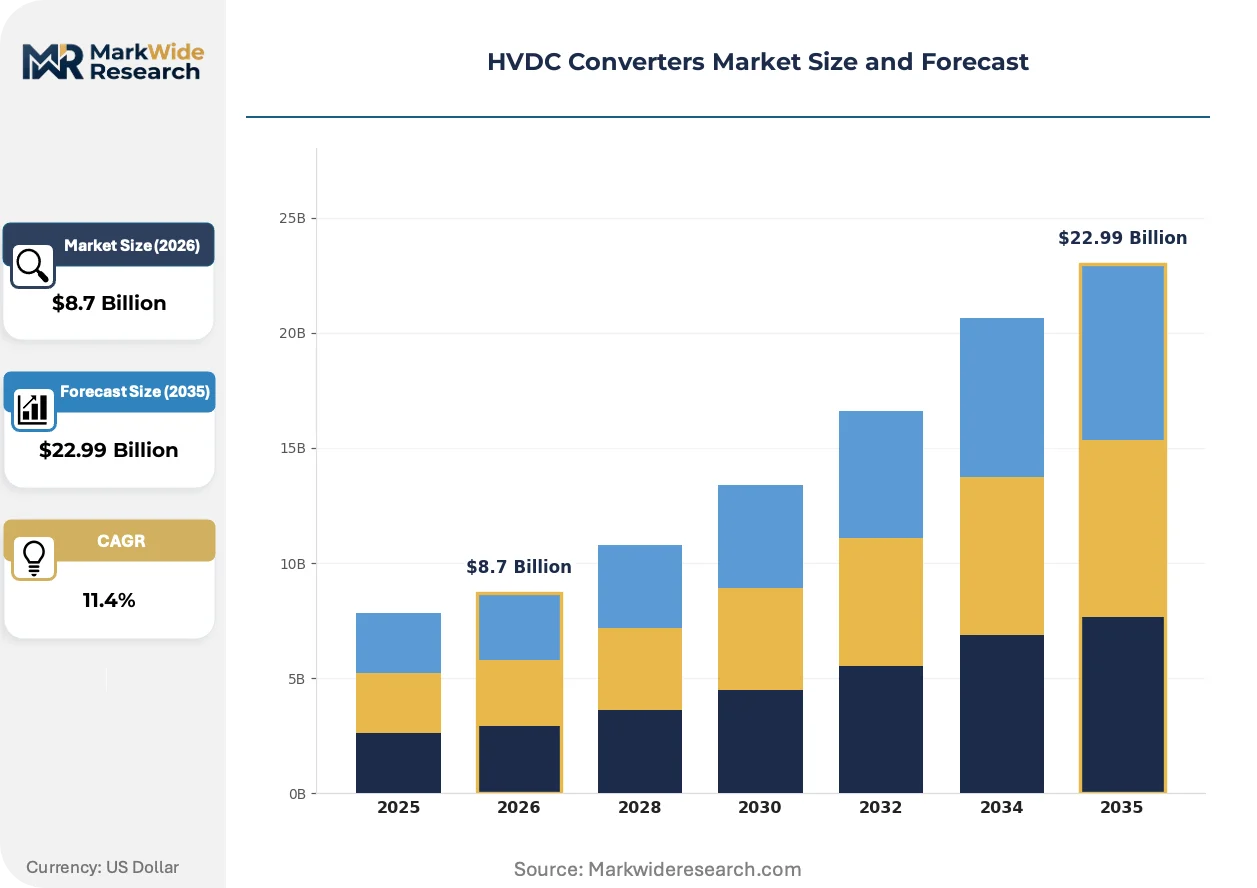
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopole, Bipole, Back-to-Back, VSC Technology: Line Commutated Converter, Voltage Source Converter, Modular Multilevel Converter, Hybrid Converter End User: Utilities, Renewable Energy, Industrial, Transportation Application: Grid Interconnection, Offshore Wind Farms, Power Transmission, Voltage Regulation |
| Companies Covered | Hitachi Energy, Siemens Energy, GE Vernova, Mitsubishi Electric, NR Electric, Toshiba Energy Systems & Solutions, NARI Technology Development, Shanghai Electric Group, Prysmian Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVDC Converters Market Emerging Trajectories
Silicon carbide power semiconductors are penetrating converter designs, while regulatory pressure for faster renewable interconnection compresses supplier qualification cycles and reshapes competitive positioning.
Silicon carbide metal-oxide-semiconductor field-effect transistors replace traditional silicon insulated-gate bipolar transistors in medium-voltage converter modules. Offshore wind developers in the North Sea are piloting these platforms for reduced switching losses and compact platform footprints. This semiconductor transition is expanding into subsea interconnector applications where space constraints and efficiency targets dominate procurement criteria.
The EU TEN-E regulation mandates cost-benefit analysis methodologies for cross-border energy infrastructure, including HVDC interconnectors. Project developers must now demonstrate contribution to EU decarbonization targets before receiving priority corridor status and permitting acceleration. Subsea cable manufacturers and converter station suppliers in Germany and Denmark are restructuring proposal templates to satisfy these new evidentiary requirements.
Long-term service contracts are unbundling from initial equipment procurement, with grid operators separately tendering 15-25 year maintenance and spare parts agreements. This disaggregation pressures original equipment manufacturers to establish regional service hubs and local spare parts inventories. The United Kingdom and Netherlands show the fastest adoption of this bifurcated procurement model, forcing suppliers to restructure revenue recognition and field engineering deployment.
HVDC Converters Market Segmentation
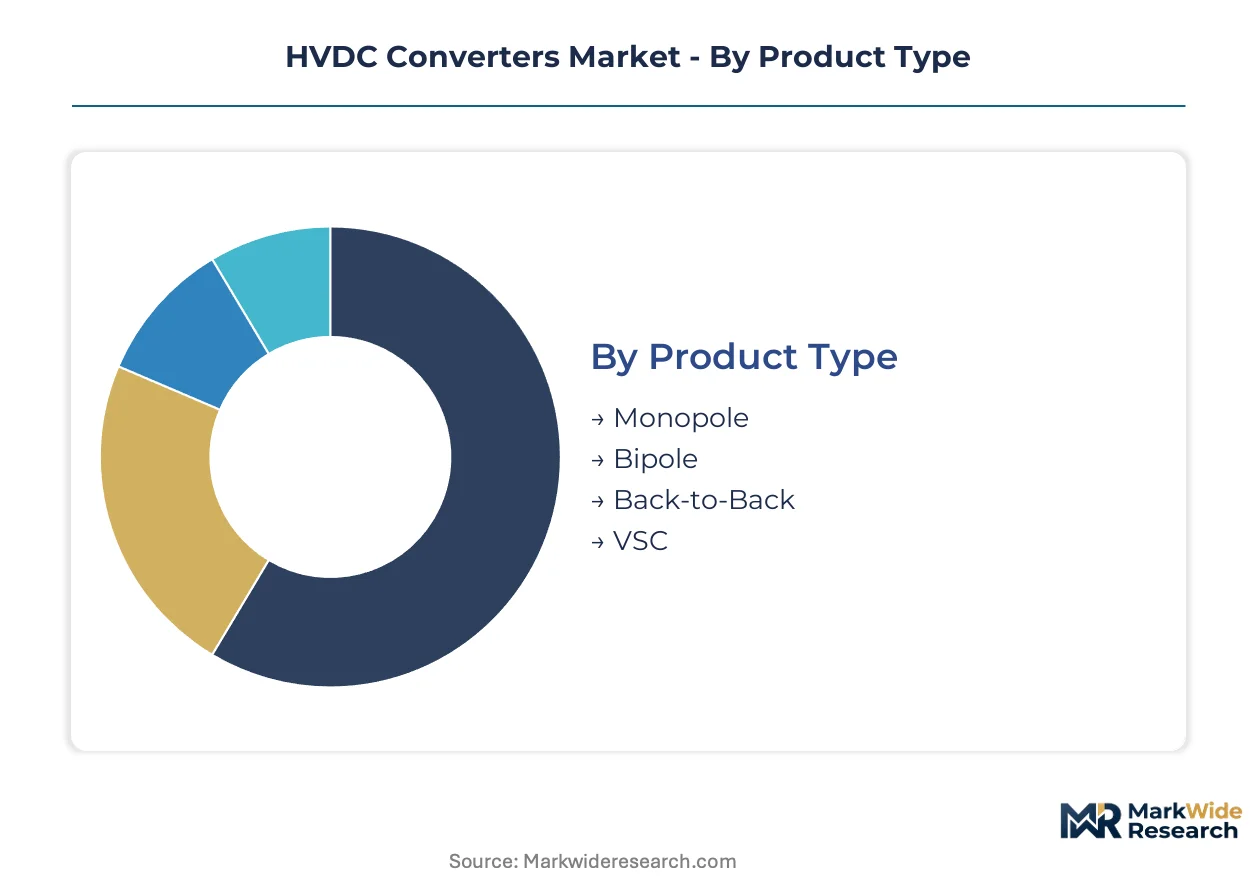
HVDC converter procurement patterns diverge sharply across technical configurations and deployment contexts. Technology selection determines semiconductor requirements, platform footprint, and grid code compliance obligations.
Product Type:
Voltage source and modular multilevel architectures are displacing conventional arrangements in new project awards.
- VSC:Voltage source converter platforms employ insulated-gate bipolar transistor modules to enable bidirectional power flow and black-start capability. Offshore wind developers in Germany and the United Kingdom specify these configurations for North Sea converter stations where reactive power control is mandatory.
- Bipole:Bipole arrangements use two conductors with a ground return, delivering redundancy for subsea interconnectors. Grid operators across Norway and the United Kingdom favor this topology for multi-terminal links where outage minimization drives procurement.
- Monopole:Single-conductor systems with earth or metallic return suit shorter transmission distances and lower capital budgets.
- Back-to-Back:Asynchronous interconnection stations link grids with different frequencies without DC transmission lines.
Mature deployment sits with Bipole configurations for established intercontinental links. Newer deployment is concentrated in VSC platforms for offshore wind integration.
Technology:
Semiconductor switching characteristics and control system architectures define competitive positioning across converter classes.
- Modular Multilevel Converter:Cascaded submodules with distributed capacitors eliminate bulky filters and enable compact offshore platforms. Developers in the Baltic Sea region specify these systems for space-constrained converter stations where reduced switching losses justify premium procurement.
- Voltage Source Converter:Self-commutated topologies using pulse-width modulation provide independent reactive power control and multi-terminal flexibility. Grid codes in Germany and China mandate these capabilities for renewable interconnection projects.
- Line Commutated Converter:Thyristor-based systems retain cost advantages for ultra-high-capacity point-to-point corridors with predictable power flow directionality.
- Hybrid Converter:Combined line-commutated and voltage-source architectures balance efficiency with control flexibility for specific corridor applications.
Established installed base centers on Line Commutated Converter systems across Asian bulk transmission corridors. Steepest expansion trajectory belongs to Modular Multilevel Converter technology for offshore and subsea applications.
End User:
Customer procurement sophistication varies across institutional mandates and technical staffing depth.
- Utilities:National transmission system operators dominate HVDC procurement through centralized tendering for interconnector and grid reinforcement projects. TenneT in the Netherlands and National Grid in the United Kingdom maintain qualified supplier lists with stringent technical pre-qualification.
- Renewable Energy:Offshore wind farm developers contract converter stations as part of transmission system packages, bundling platform engineering with cable installation.
- Industrial:Mining and aluminum smelting operations in remote locations procure dedicated HVDC supply for bulk power access.
- Transportation:Rail electrification and urban transit authorities evaluate DC traction power systems with converter station components.
Volume concentration aligns with Utility procurement for cross-border infrastructure. Fastest-growing demand originates from Renewable Energy developers integrating distant generation.
Application:
Deployment context determines environmental protection ratings, platform architecture, and maintenance access protocols.
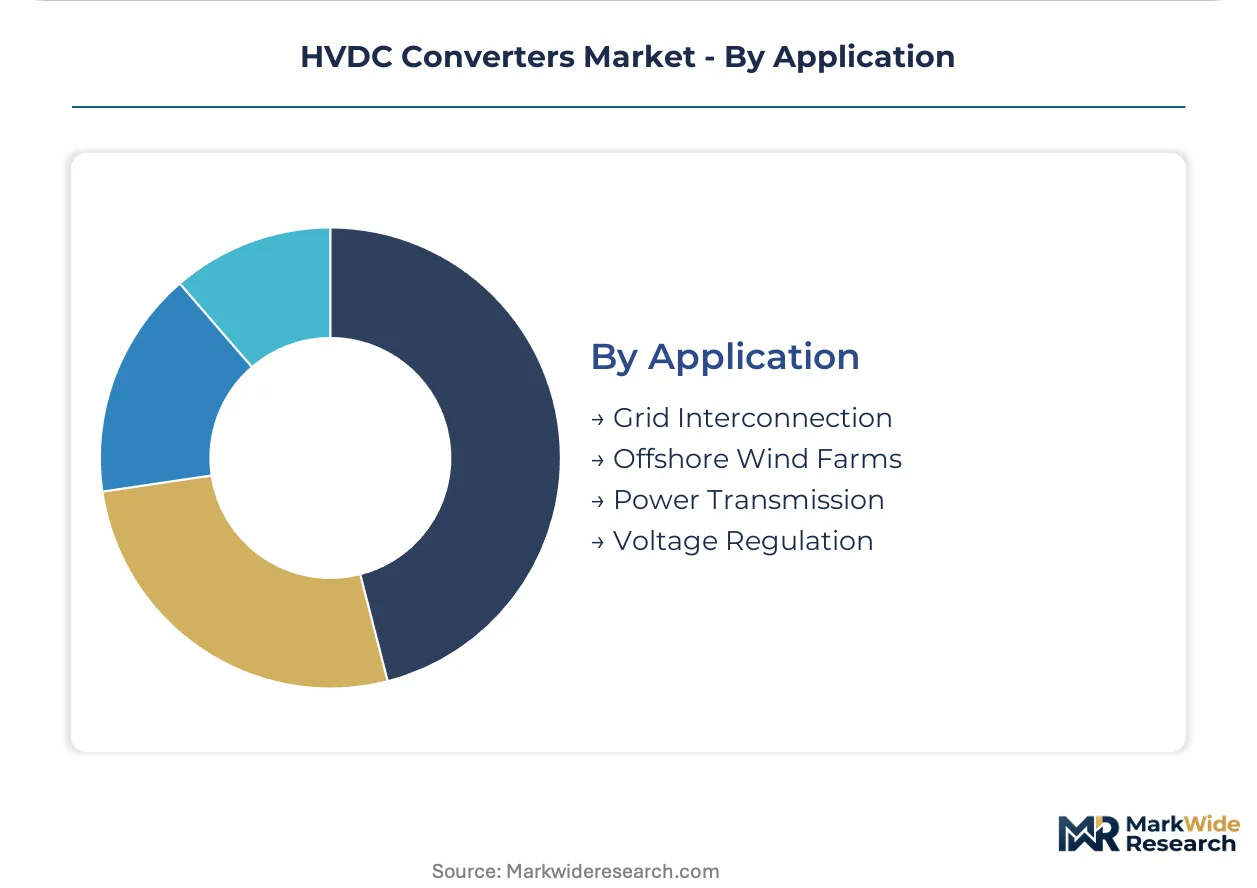
- Offshore Wind Farms:Platform-mounted converter stations require marine-grade enclosures and helicopter-accessible layouts for maintenance. Developers in the North Sea specify these for wind farm clusters beyond 100 kilometers from shore.
- Grid Interconnection:Asynchronous links between national grids demand harmonic filtering and fault ride-through compliance under EU TEN-E regulation and FERC Order 2023.
- Power Transmission:Overland ultra-high-voltage corridors connect remote generation to load centers with minimal right-of-way requirements.
- Voltage Regulation:Dynamic reactive power compensation applications stabilize grid voltage during renewable generation variability.
Installed capacity concentrates in Grid Interconnection for established European and Asian corridors. Deployment momentum is strongest in Offshore Wind Farms as lease rounds accelerate in the North Sea and Baltic regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore wind procurement clusters in the North Sea and Baltic regions concentrate converter station demand, while Asian bulk transmission corridors sustain line-commutated converter deployment. National grid codes and renewable integration mandates reshape regional technology preferences.
Germany
TenneT and 50Hertz expand voltage source converter orders for North Sea offshore wind clusters. The country's national energy regulator enforces fault ride-through requirements under the Grid Expansion Acceleration Act. Converter platform fabrication concentrates in northern ports around Cuxhaven and Wilhelmshaven.
China
State Grid Corporation commissions ultra-high-voltage DC corridors linking western generation to eastern load centers. GB/T standards for ultra-high voltage DC mandate specific converter performance benchmarks. Manufacturing clusters in Xi'an and Shanghai supply thyristor-based systems for domestic and export markets.
United Kingdom
National Grid procures multi-terminal interconnectors linking Scotland's offshore wind to English demand centers. Ofgem's RIIO-2 framework governs cost recovery for converter infrastructure investments. Installation and maintenance operations cluster around Grimsby and Great Yarmouth ports.
Norway
Statnett advances subsea links to Germany and the United Kingdom requiring advanced reactive power control. The Norwegian Water Resources and Energy Directorate oversees grid code compliance for cross-border capacity. Converter engineering capabilities concentrate in Oslo and Trondheim.
United States
Offshore wind developers in Massachusetts and New York evaluate voltage source configurations for Atlantic Coast projects. FERC Order 2023 compresses interconnection study timelines for converter-linked renewable capacity. Equipment sourcing and engineering services cluster in Houston and Boston.
HVDC Converters Market Vendor Landscape
European producers anchor the premium technology tier; East Asian specialists hold scale advantages in thyristor-based systems. The supply base concentrates around integrated energy conglomerates with captive semiconductor sourcing and platform engineering capabilities. Three archetypes dominate: full-system integrators with offshore installation assets, modular technology specialists, and regional champions serving protected domestic markets. Competitive moves center on long-term service contract unbundling and regional spare parts hub establishment.
Within the integrated systems tier, Hitachi Energy and Siemens Energy exemplify full-capability providers spanning converter design through offshore platform delivery. NR Electric represents the specialist archetype focused on control system architectures and grid code compliance engineering. Mitsubishi Electric occupies a position in the thyristor-based segment serving predictable bulk power corridors. These anchors illustrate how geographic origin and historical technology focus stratify competitive positioning across project types.
| Leading Market Players |
|---|
| Hitachi Energy |
| Siemens Energy |
| GE Vernova |
| Mitsubishi Electric |
| NR Electric |
| Toshiba Energy Systems & Solutions |
| NARI Technology Development |
| Shanghai Electric Group |
| Prysmian Group |
| Others |
Supply Flow & Price Mechanics
Utility procurement consolidation around mega-project developers in Germany, the United Kingdom, and China concentrates buying power and compresses converter station pricing into long-term framework agreements with embedded service clauses. This buyer concentration shifts supplier revenue toward 15-25 year maintenance contracts and penalizes standalone equipment vendors lacking regional spare parts infrastructure.
Pricing Analysis
High-volume transmission system operators capture margin through multi-station framework agreements, while specialized offshore wind developers absorb premium pricing for black-start capable modular multilevel converter platforms. Price differentiation separates IEC 62501-certified systems with full grid code compliance from legacy line-commutated configurations lacking reactive power control. Pricing pressure stems from semiconductor supply volatility and specialized vessel scarcity extending project timelines. Industrial mining offtakers in remote locations show highest price sensitivity, while North Sea offshore developers prioritize technical performance over unit cost.
Supply Chain Analysis
Insulated-gate bipolar transistor module supply rests on fabrication capacity concentrated in Japan, South Korea, and Taiwan, with silicon carbide metal-oxide-semiconductor field-effect transistor sourcing expanding from these same production clusters. Critical inputs span high-purity silicon wafers, ceramic substrate materials, and specialized converter control system firmware. Single-source vulnerability in heavy-lift vessel availability for offshore platform installation creates scheduling chokepoints. Distribution runs through integrated energy conglomerates with captive semiconductor sourcing and platform engineering capabilities, bypassing independent component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HVDC converter market sits in a technology-transition phase where silicon carbide power semiconductors displace traditional silicon insulated-gate bipolar transistors across medium-voltage applications. This substitution reshapes supplier qualification criteria and platform design architectures.
For Market Incumbents: Deepen backward integration into silicon carbide semiconductor sourcing to secure supply continuity against East Asian foundry concentration risk. Expand regional service hub footprints in the United Kingdom and Netherlands where bifurcated procurement unbundles equipment from long-term maintenance contracts. Prioritize certification investment under evolving EU TEN-E and FERC Order 2023 grid code requirements to defend qualified supplier list positions. For New Entrants and Emerging Players: Capture white-space opportunity in Brazil-Argentina interconnection corridors where line-commutated converter demand for predictable bulk power flows remains underserved by established European suppliers. Target green hydrogen offtakers in Australia and Saudi Arabia requiring dedicated gigawatt-scale HVDC supply for electrolyzer facilities. Pursue IEC 62501 harmonization compliance as a go-to-market accelerant reducing certification barriers for voltage source converter platforms. For Investors and Strategic Acquirers: The window for entry favors control system architecture specialists with grid code compliance engineering capabilities and modular multilevel converter technology portfolios. Long-term viability hinges on exposure to offshore wind integration and subsea interconnector deployment trajectories rather than legacy thyristor-based bulk transmission. Watch silicon carbide semiconductor cost curves and heavy-lift vessel fleet expansion as inflection indicators for project timeline compression and margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Semiconductor Integration | Reduces switching losses and platform footprint for North Sea offshore installations. |
| Regional Service Hub Establishment | Captures unbundled 15-25 year maintenance contracts under UK and Netherlands procurement models. |
| IEC 62501 Certification Investment | Accelerates market access for voltage source converter suppliers across European priority corridors. |
| Heavy-Lift Vessel Partnership | Secures installation windows exceeding 24-month booking backlogs for offshore converter platforms. |
| Multi-Terminal Control System Development | Enables reactive power coordination for Germany-Norway-UK subsea interconnector networks. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with utility planning officers, offshore wind project developers, EPC contractors, and grid operators across Germany, the United Kingdom, China, and the United States. Secondary sources included FERC interconnection dockets, EU TEN-E priority corridor designations, State Grid Corporation procurement disclosures, and IEC standardization committee documentation. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates across technology and application segments.
Granularity-level modeling operated at converter station technology configuration, deployment context, and end-user procurement archetype dimensions throughout the projection horizon. Voltage source converter, modular multilevel converter, line-commutated converter, and hybrid system deployments were tracked separately with distinct semiconductor input assumptions and grid code compliance timelines. CAGRs derived from project award momentum, regulatory mandate acceleration, and technology substitution curves. Forecast inputs incorporated offshore wind lease round schedules, subsea cable manufacturing capacity, and national renewable integration target trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply chain reconfiguration, heavy-lift vessel fleet expansion, and evolving grid code harmonization across EU, Chinese, and US regulatory frameworks. Forecasts reflect documented assumptions about project development timelines and technology adoption rates. A small set of triggers warrants ongoing watch: silicon carbide cost parity thresholds, specialized vessel delivery schedules, and priority corridor permitting acceleration under EU TEN-E regulation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Europe Shunt Reactors Market
Power Systems
Power Integrated Modules Market
Power Systems
Thyristor Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Three Phase Micro Inverters Market
Power Systems
Micro-Inverter Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Electrical and Automation System Market
Power Systems
Series Reactor Market
Power Systems
Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
AC DC Power Adapter Market
Power Systems
Module-Level Power Electronics (MLPE) Market
Power Systems
Thermoelectric Coolers Market
Power Systems
Traction Inverter Market
Power Systems
Flyback Transformer Market