
 Women Digital Health Solutions Market | 2026-2036
Women Digital Health Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Women Digital Health Solutions Market Analytics
Healthcare provider channels is pivoting toward integrated maternal and mental wellness platforms as reimbursement models evolve. Maven Clinic leverages employer-sponsored benefit networks to sustain enterprise contract growth. Flo Health anchors consumer acquisition through AI-driven cycle tracking, while Elvie differentiates via proprietary hardware-software bundles for pelvic health.
Women digital health solutions encompass software, connected devices, and remote service platforms engineered to monitor, diagnose, or manage conditions specific to female physiology, including hormonal cycles, pregnancy, and menopause-related symptoms. Cloud computing infrastructure enables real-time biometric synchronization across wearable devices and telehealth platforms, while AI algorithms process longitudinal health data to generate personalized intervention protocols. Mobile apps capture the largest addressable user base among product types, though telehealth platforms command superior per-subscriber economics through provider billing integration. Maternal health applications outpace fitness tracking in clinical validation intensity, creating concentrated margin pools for FDA-cleared prenatal monitoring tools.
FDA Software as a Medical Device guidance and HIPAA privacy mandates shape product development timelines and data architecture requirements for US market entrants. The EU AI Act and MDR frameworks impose additional conformity obligations for algorithmic diagnostic tools sold in European member states. Stakeholders must monitor regulatory divergence between FDA's risk-based device classification and emerging EU algorithmic accountability standards when prioritizing geographic expansion sequencing.
Market Dynamics
The Women Digital Health Solutions Market pivots on employer-sponsored benefit expansion, with enterprise purchasers now demanding integrated maternal-mental wellness platforms that bundle telehealth access, wearable monitoring, and care navigation into single contracts.
Growth Catalysts
- FDA Software as a Medical Device framework:The FDA's risk-based classification pathway accelerates market entry for algorithmic diagnostic tools, compressing premarket review timelines for prenatal monitoring applications.
- Cloud-edge computing convergence:Real-time biometric synchronization across wearable devices and telehealth platforms enables continuous glucose monitoring and fetal heart rate tracking without hospital tethering.
- Metropolitan health innovation clusters:Boston and San Francisco concentrate venture deployment and clinical trial infrastructure, anchoring talent pipelines and provider network density for digital health startups.
Market Restraints
- HIPAA compliance architecture costs:Data infrastructure investments to meet privacy mandates consume 15-25% of early-stage capital, diverting resources from product development.
- Silicon sensor supply concentration:Photoplethysmography and accelerometer components rely on East Asian foundry capacity, exposing hardware-software bundles to geopolitical supply shocks.
- Clinical validation intensity:FDA 510(k) clearance for prenatal monitoring tools requires multi-site prospective studies, extending time-to-revenue by 18-36 months versus general wellness applications.
Strategic Opportunities
- Menopause management white space:Hormonal transition symptom tracking and telemedicine access remain underdeveloped relative to maternal health, creating first-mover advantage for thermoregulatory and sleep monitoring tools.
- EU AI Act algorithmic accountability:Conformity obligations for high-risk medical AI create competitive moat for firms investing in explainability documentation and human-in-the-loop protocols.
- Retail pharmacy channel integration:CVS and Walgreens health service expansions offer distribution partnerships that bypass traditional provider sales cycles for direct-to-consumer fertility and cycle tracking products.
Industry Challenges
- Interoperability with electronic health records:HL7 FHIR integration consumes engineering resources and delays hospital system procurement decisions.
- Reimbursement code fragmentation:CPT code coverage gaps for remote patient monitoring in obstetrics force hybrid payment models that complicate revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women Digital Health Solutions Market |
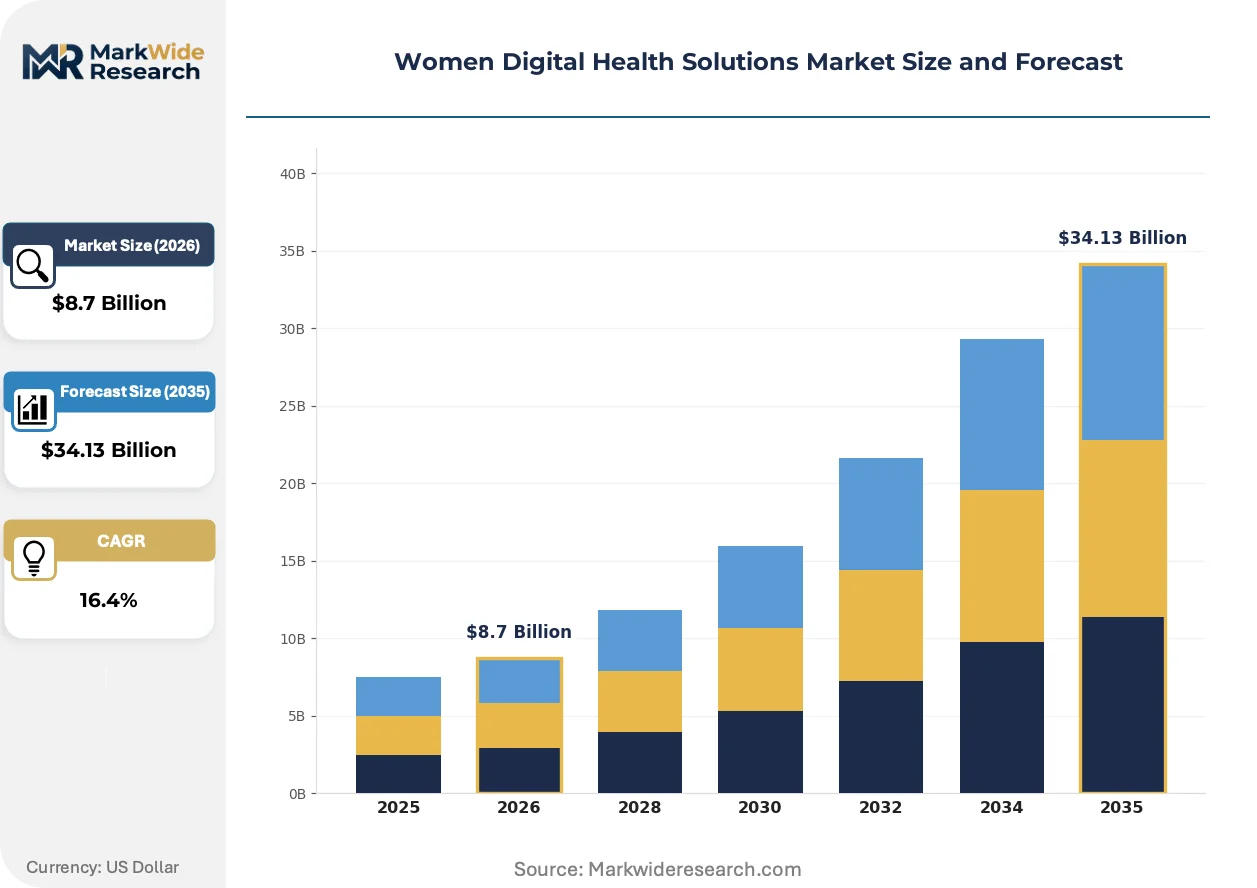
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Apps, Telehealth Platforms, Health Monitoring Software Application: Fitness Tracking, Maternal Health, Mental Wellness, Chronic Disease Management End User: Healthcare Providers, Women Entrepreneurs, Fitness Coaches, Individual Users Technology: AI Algorithms, Cloud Computing, Telecommunication, Data Analytics |
| Companies Covered | Maven Clinic, Elvie, Flo Health, Thirty Madison, MobileODT, Natural Cycles, Clue by Biowink, NURX, Ovia Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women Digital Health Solutions Market Evolving Landscape
Artificial intelligence is reshaping product architecture across the Women Digital Health Solutions Market, with machine learning models now embedded in cycle prediction, risk stratification, and personalized intervention delivery. This shift compresses development cycles while raising regulatory scrutiny.
Continuous glucose monitoring sensors paired with predictive algorithms are expanding into gestational diabetes management, enabling real-time insulin dosing recommendations. Maternal-fetal medicine specialists in academic medical centers are adopting these systems at accelerating pace. The technology is expanding into employer-sponsored wellness programs as a differentiated benefit offering for high-risk pregnancy populations.
The EU AI Act's risk classification system for medical algorithms imposes conformity assessment obligations on fertility prediction and diagnostic support tools sold in European member states. Manufacturers must maintain technical documentation, human oversight protocols, and post-market monitoring systems. Fertility tracking applications with diagnostic claims face the most stringent compliance burdens, prompting some firms to narrow functional scope.
Enterprise benefit managers now mandate platform consolidation, pressuring point-solution vendors to integrate maternal health, mental wellness, and care navigation into unified contracts. This procurement pattern favors vendors with multi-condition capabilities. The shift is most visible among technology sector employers in the United States, where talent competition drives benefit differentiation.
Women Digital Health Solutions Market Segmentation
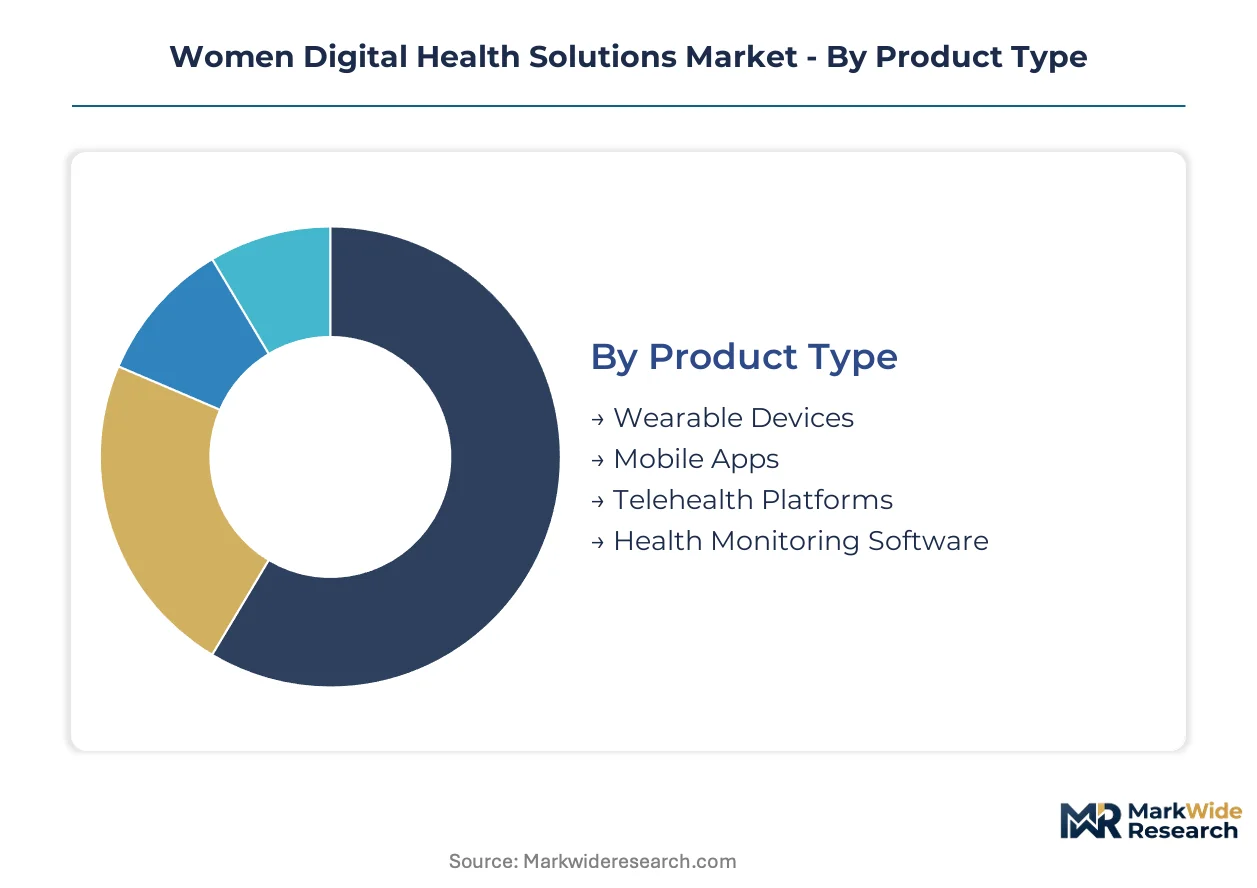
Women digital health solutions fragment across four distinct taxonomies that shape regulatory pathways, customer acquisition costs, and margin architecture. Product type determines FDA Software as a Medical Device classification burden. Application focus dictates clinical validation intensity and reimbursement eligibility. End user orientation separates enterprise sales cycles from direct-to-consumer velocity. Technology stack choices influence cloud infrastructure spend and algorithmic auditability requirements.
Product Type:
FDA Software as a Medical Device framework imposes tiered compliance obligations: wearable devices with diagnostic claims require 510(k) clearance, while general wellness mobile apps fall outside premarket review. Telehealth platforms face state-level telemedicine licensing rather than device classification. Health monitoring software occupies the most contested regulatory territory, with algorithmic diagnostic features triggering SaMD scrutiny.
- Wearable Devices:Photoplethysmography sensors and accelerometer arrays embedded in wrist-worn or skin-patch form factors capture continuous biometric streams. Demand concentrates in employer-sponsored wellness programs across the United States, where gestational diabetes monitoring and fertility tracking justify hardware subsidies. FDA 510(k) clearance timelines extend commercialization by 18-36 months versus general wellness applications.
- Mobile Apps:Smartphone-native applications leverage onboard cameras, microphones, and accelerometers for symptom logging and behavioral nudges. Consumer acquisition in metropolitan health innovation clusters like Boston and San Francisco outpaces national averages, driven by tech-sector employer benefit integration. HIPAA-compliant cloud architecture consumes 15-25% of early-stage capital.
- Telehealth Platforms:Real-time video consultation infrastructure with embedded scheduling, prescribing, and care navigation modules. Provider billing integration commands superior per-subscriber economics versus consumer-paid alternatives. State-by-state telemedicine licensing creates geographic expansion friction.
- Health Monitoring Software:Cloud-based dashboards synthesizing data from multiple input streams for risk stratification and intervention triggering. Algorithmic diagnostic claims trigger FDA SaMD classification, requiring prospective clinical validation. EU AI Act conformity obligations add documentation burden for European market entry.
Mobile apps sit at the top of the volume ranking, with telehealth platforms climbing the fastest.
Application:
Application focus determines reimbursement code availability and clinical trial design complexity. Maternal health commands the most intensive FDA validation requirements. Mental wellness applications face distinct CPT code fragmentation challenges. Fitness tracking occupies the lightest regulatory burden but the most crowded competitive field. Chronic disease management intersects with existing remote patient monitoring reimbursement frameworks.
- Maternal Health:Prenatal monitoring, fetal heart rate tracking, gestational diabetes management, and postpartum depression screening tools. Academic medical centers in the United States adopt continuous glucose monitoring systems at accelerating pace. Multi-site prospective studies extend time-to-revenue versus general wellness categories.
- Mental Wellness:Cognitive behavioral therapy delivery, mood tracking, and care navigation for perinatal depression and anxiety. Employer benefit managers now mandate platform consolidation with maternal health modules. Reimbursement code gaps force hybrid payment models complicating revenue recognition.
- Fitness Tracking:Activity quantification, sleep scoring, and nutrition logging with female-specific physiological adaptations. Consumer subscription fatigue limits pricing power. Retail pharmacy channel partnerships at CVS and Walgreens offer distribution bypassing traditional provider sales cycles.
- Chronic Disease Management:Longitudinal monitoring for endometriosis, polycystic ovary syndrome, and menopause-related cardiovascular risk. HL7 FHIR integration with electronic health records consumes engineering resources and delays hospital procurement decisions. Menopause management remains underdeveloped relative to maternal health, creating first-mover positioning for thermoregulatory monitoring tools.
Maternal health captures the steepest expansion trajectory, with chronic disease management gaining share fastest.
End User:
Customer type separates enterprise sales cycles with 12-18 month procurement timelines from direct-to-consumer acquisition with immediate activation but higher churn. Healthcare providers demand interoperability certification. Individual users drive volume but fragment across dozens of point solutions. Fitness coaches represent an emerging channel for algorithmic training personalization.
- Healthcare Providers:Hospital systems, obstetric clinics, and maternal-fetal medicine specialists procuring enterprise licenses. Procurement requires HL7 FHIR integration and HIPAA Business Associate Agreements. Cloud-edge computing convergence enables real-time biometric synchronization without hospital tethering.
- Individual Users:Direct-to-consumer subscribers purchasing monthly or annual app memberships. Acquisition costs rise as iOS privacy changes limit ad targeting. AI-driven cycle prediction and personalized intervention protocols anchor retention.
- Women Entrepreneurs:Small business owners accessing specialized health benefits through professional associations and chambers of commerce. This segment remains nascent with limited dedicated product development.
- Fitness Coaches:Personal trainers and wellness advisors prescribing digital tools as client engagement extensions. Integration with existing coaching platforms determines adoption velocity.
Individual users dominate volume, with healthcare providers expanding most quickly.
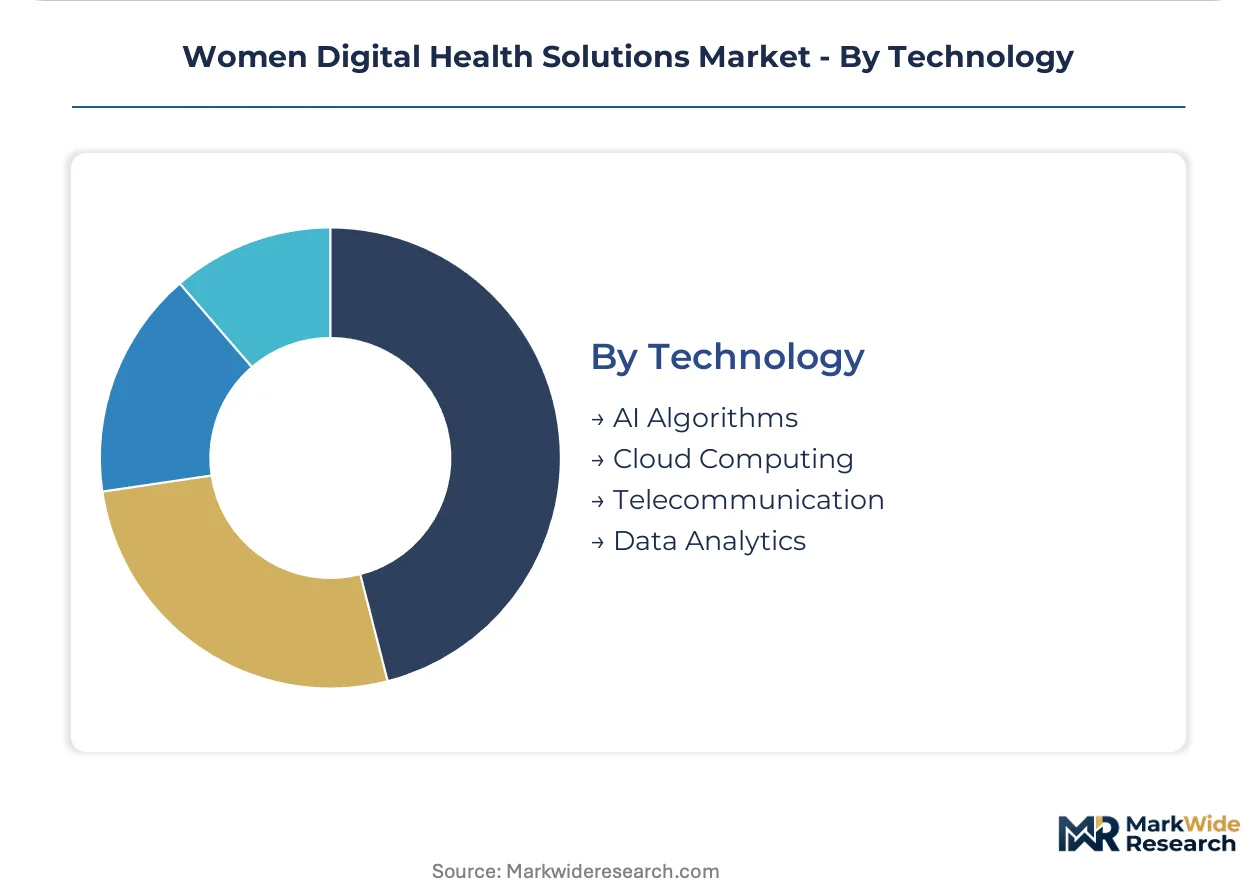
Technology:
Technology stack choices influence regulatory auditability, infrastructure spend, and competitive differentiation durability. AI algorithms face escalating scrutiny under FDA SaMD guidance and EU AI Act risk classification. Cloud computing enables scale but concentrates vendor risk. Data analytics capabilities separate commodity tracking from clinically actionable insight.
- AI Algorithms:Machine learning models for cycle prediction, risk stratification, and personalized intervention delivery. FDA risk-based classification pathway accelerates market entry for prenatal monitoring applications. EU AI Act imposes conformity assessment obligations requiring technical documentation and human-in-the-loop protocols.
- Cloud Computing:Scalable infrastructure for biometric data ingestion, processing, and synchronization across device ecosystems. HIPAA compliance architecture costs divert resources from product development. Multi-region deployment adds complexity for European data residency requirements.
- Telecommunication:Real-time video, audio, and messaging infrastructure for synchronous care delivery. State-level telemedicine licensing creates geographic fragmentation. 5G latency improvements enable remote ultrasound interpretation.
- Data Analytics:Longitudinal health record synthesis and population-level insight generation for employer and payer reporting. Interoperability with electronic health records delays hospital system procurement decisions. Explainability documentation creates competitive moat under emerging algorithmic accountability standards.
Cloud computing anchors current infrastructure spend, with AI algorithms demanding the fastest-growing engineering investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping geographic expansion sequencing as firms weigh FDA Software as a Medical Device compliance costs against EU AI Act conformity burdens. Venture deployment concentrates where reimbursement codes align with enterprise benefit procurement patterns.
United States
Employer-sponsored benefit expansion drives enterprise contract velocity for maternal-mental wellness platforms. FDA risk-based classification accelerates premarket review for algorithmic diagnostic tools relative to European pathways. Metropolitan health innovation clusters in Boston and San Francisco anchor clinical trial infrastructure and provider network density.
United Kingdom
NHS Long Term Plan commitments to digital-first primary care create procurement opportunities for telehealth platforms. MHRA recognition of FDA-cleared devices streamlines market entry for US-origin prenatal monitoring tools. London's health tech corridor concentrates venture capital and regulatory consulting expertise.
Germany
DiGA fast-track reimbursement pathway for digital health applications reduces time-to-revenue for menstrual and fertility tracking tools. BfArM evaluation criteria favor clinical validation intensity comparable to FDA 510(k) standards. Berlin and Munich health tech ecosystems attract cross-border engineering talent.
Sweden
Nordic welfare state procurement models prioritize evidence-based menopause management and hormonal health applications. Medical Products Agency alignment with MDR and EU AI Act risk classifications imposes documentation burdens on fertility prediction algorithms. Stockholm's life sciences cluster supports regulatory science capabilities.
Israel
Defense-derived AI expertise migrates toward femtech applications in predictive diagnostics and computer vision. Ministry of Health digital health sandbox exemptions compress validation timelines for early-stage ventures. Tel Aviv's startup density enables rapid prototyping partnerships with academic medical centers.
Women Digital Health Solutions Market Competitive Landscape
Strategic partnership formation dominates the current landscape as point-solution vendors integrate maternal health, mental wellness, and care navigation modules into unified enterprise contracts. The vendor base separates into three archetypes: employer benefit platform consolidators, hardware-software bundle specialists, and AI-native cycle tracking applications. Consolidation pressure favors multi-condition capabilities over single-use tools. M&A activity and portfolio diversification represent the primary competitive vectors as procurement patterns shift toward platform consolidation.
Within the employer benefit platform tier, Maven Clinic and Ovia Health occupy positions as archetypal enterprise contract anchors. Flo Health exemplifies the AI-native consumer acquisition model, while Elvie represents hardware-software bundle differentiation in pelvic health applications. These three firms collectively illustrate the strategic segmentation between enterprise sales cycles, direct-to-consumer velocity, and proprietary device ecosystems that defines current competitive positioning.
| Leading Market Players |
|---|
| Maven Clinic |
| Elvie |
| Flo Health |
| Thirty Madison |
| MobileODT |
| Natural Cycles |
| Clue by Biowink |
| NURX |
| Ovia Health |
| Others |
Value Network & Pricing Analysis
Captive cloud infrastructure investments by enterprise platform vendors anchor supply positions while compressing pricing power for hardware-dependent entrants. This integration pattern concentrates margin capture among firms controlling end-to-end maternal-mental wellness bundles, forcing point-solution competitors toward aggressive subscription discounting.
Pricing Analysis
Direct-to-employer contract structures bypass traditional distributor margins, compressing channel economics to 8-12% administrative fees versus 25-35% retail markups. Pricing stratifies across FDA-cleared diagnostic tiers, enterprise wellness bundles, and direct-to-consumer freemium tiers, with certification intensity commanding 40-60% premiums. Cost compression in consumer subscription tiers intensifies as iOS privacy changes elevate customer acquisition expenses. Individual users exhibit highest price sensitivity, while enterprise benefit managers prioritize platform consolidation over per-seat cost.
Supply Chain Analysis
Engineering talent scarcity in Boston and San Francisco metropolitan clusters constrains hardware-software bundle development velocity. Photoplethysmography sensor fabrication concentrates in Taiwan and South Korea, while cloud computing infrastructure draws from US and Irish data center regions. Single-source vulnerability in silicon foundry capacity exposes gestational diabetes monitoring hardware to geopolitical disruption. Distribution runs through employer-sponsored benefit networks and retail pharmacy partnerships rather than traditional medical device channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
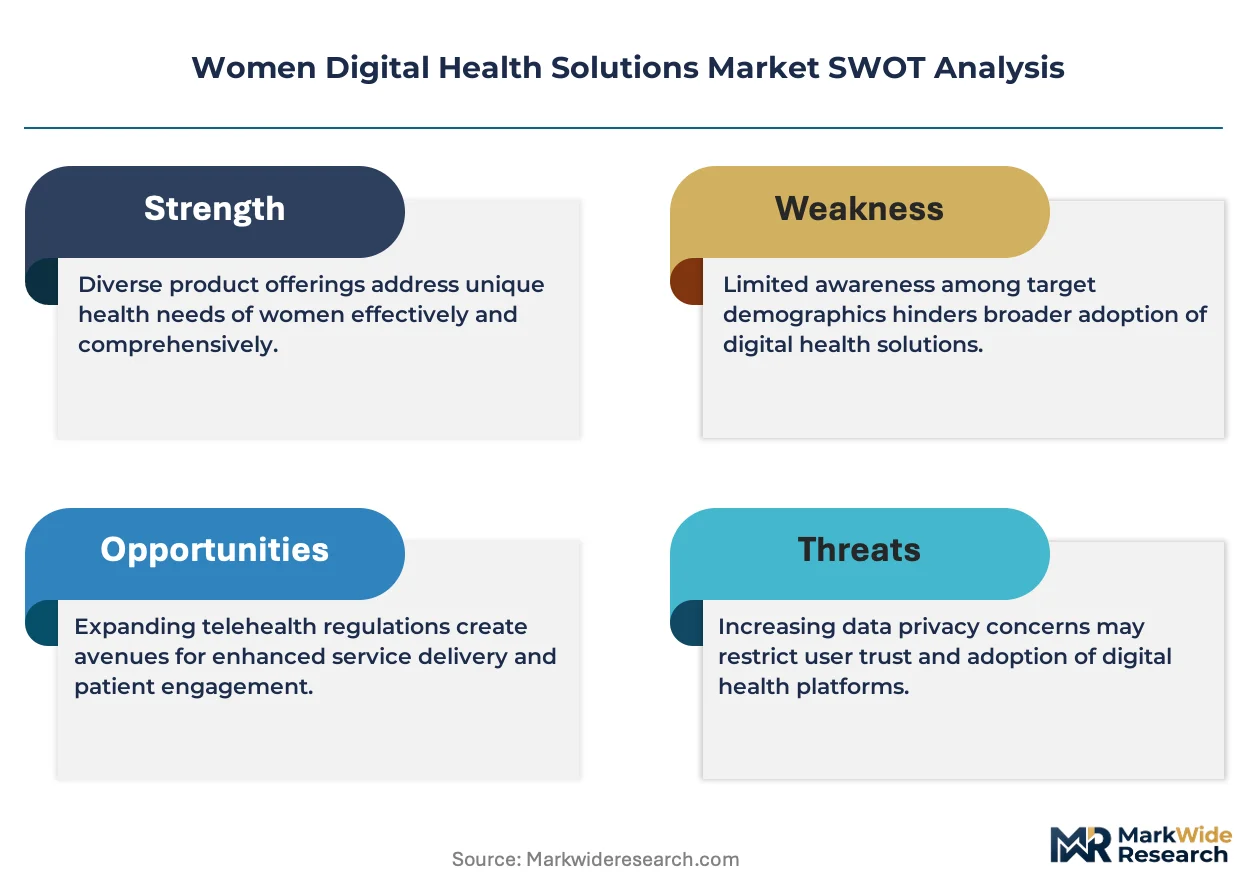
This market functions as a regulatory compounder where FDA Software as a Medical Device framework expansion and EU AI Act risk classification together accelerate demand for compliant platform architectures.
For Market Incumbents: Extend maternal health module integration into mental wellness and care navigation to preempt employer procurement consolidation. Acquire FDA 510(k) clearance for algorithmic diagnostic features before EU AI Act conformity obligations harden competitive moats. Vertical integration into photoplethysmography sensor design mitigates Taiwan foundry concentration risk. For New Entrants and Emerging Players: Employer benefit managers at mid-market technology firms represent an underserved buyer archetype seeking menopause management modules absent from current enterprise contracts. Target thermoregulatory monitoring and sleep tracking applications where clinical validation intensity remains lower than maternal health. Pursue retail pharmacy distribution partnerships at CVS and Walgreens to bypass 12-18 month hospital procurement cycles. For Investors and Strategic Acquirers: Roll-up economics work for AI-native cycle tracking applications because employer benefit managers now mandate platform consolidation that subordinates point solutions to bundled contracts. Five-to-ten year viability hinges on multi-condition capability breadth rather than single-use dominance. Monitor FDA SaMD enforcement patterns as inflection indicator for algorithmic diagnostic tool valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates premarket review timelines for prenatal monitoring applications versus general wellness categories. |
| EU AI Act Conformity Assessment | Creates competitive moat for fertility prediction tools with explainability documentation and human-in-the-loop protocols. |
| Hospital System Partnership | Enables HL7 FHIR integration that satisfies procurement requirements for academic medical center adoption. |
| Software Companion Development | Pairs continuous glucose monitoring sensors with predictive algorithms for gestational diabetes management. |
| Reimbursement Strategy | Navigates CPT code fragmentation for remote patient monitoring in obstetrics through hybrid payment models. |
Research Methodology
Direct dialogue with digital health product managers, FDA regulatory consultants, employer benefit directors, and maternal-fetal medicine specialists grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital GPO contracts, and EU MDR conformity assessment records. Bottom-up and top-down triangulation reconciled enterprise contract velocity with consumer subscription activation rates.
Bottom-up modeling segmented revenue across product type, application focus, end user orientation, and technology stack dimensions. Analytical frameworks incorporated cloud infrastructure spend ratios, clinical validation intensity differentials, and geographic regulatory divergence patterns across the projection horizon. CAGRs derived from employer benefit adoption curves, telehealth platform billing integration rates, and hardware-software bundle penetration assumptions.
Underlying measurement precision varies by segment; telehealth platforms with provider billing integration carry tighter precision than direct-to-consumer fitness tracking applications. Forecasts reflect assumptions about FDA SaMD enforcement consistency, EU AI Act implementation timelines, and employer-sponsored benefit expansion velocity. Material deviation in reimbursement code coverage or silicon sensor supply continuity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Virtual Reality (VR) in Healthcare Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Medical Virtual Reality Operating Systems Market
Digital Health Solutions
Telepsychiatry Software Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Cardiovascular Digital Solutions Market
Digital Health Solutions
Connected Health and Wellness Solutions Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
Advanced Clinical Decision Support Platforms Market
Digital Health Solutions
Global Microservices in Healthcare Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Digital Patient Engagement Solutions Market