

Conversational AI in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Conversational AI in Healthcare Market Insights
Transformer-based natural language processing is shifting from rule-based chatbot architectures toward large language model foundations across healthcare interfaces. Microsoft leverages its Azure cloud infrastructure to anchor clinical documentation workflows in enterprise hospital networks. NVIDIA sustains competitive positioning through specialized healthcare AI chipsets that power real-time inference for voice-based diagnostic assistants. Google Health differentiates by integrating conversational interfaces directly with electronic health record systems, reducing clinician administrative burden.
Conversational AI in healthcare denotes software systems employing natural language understanding, speech recognition, and dialogue management to enable human-computer interaction through text or voice channels, typically processing patient queries with sub-second latency and maintaining context across multi-turn exchanges for clinical or administrative purposes. Chatbot deployments currently dominate patient engagement applications, though voice-based systems represent the fastest-expanding segment as ambient clinical documentation gains traction among physicians seeking hands-free data capture. Cloud-based deployment models capture the largest margin pools by reducing infrastructure overhead for telemedicine providers, while hybrid architectures grow fastest among hospitals balancing data sovereignty with computational scalability.
FDA oversight of AI-enabled medical devices and HIPAA privacy requirements collectively shape product development roadmaps, mandating algorithmic transparency and audit trails that extend engineering cycles but create compliance barriers for entrants. The EU AI Act's risk classification framework for health applications is forcing multinational vendors to maintain parallel regulatory documentation across jurisdictions. Stakeholders must monitor evolving liability standards for autonomous clinical recommendations as courts define accountability boundaries between AI developers and healthcare delivery organizations.
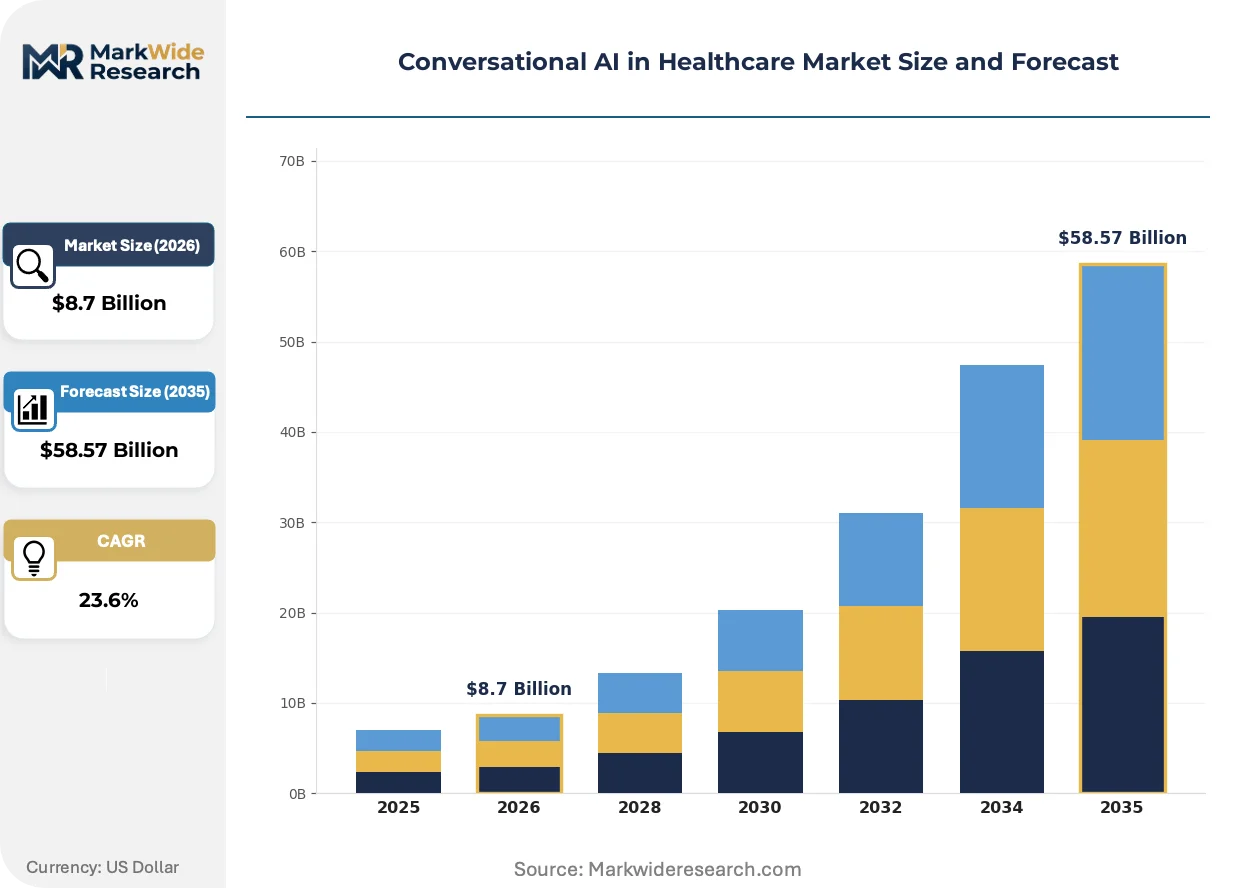
Market Dynamics
Transformer-based architectures are compressing development cycles for clinical natural language processing, forcing incumbent vendors to re-platform legacy rule-based systems or cede enterprise hospital contracts to cloud-native competitors.
Growth Catalysts
- FDA guidance on AI-enabled medical devices:The agency's predetermined change control plans accelerate clinical documentation software approvals, reducing time-to-market for algorithmic triage tools in US health systems.
- Cloud infrastructure maturation:Hyperscale providers now offer healthcare-specific compliance certifications, enabling telemedicine platforms to deploy conversational interfaces without building captive data centers.
- Physician administrative burden:Clinicians spend excessive hours on EHR data entry, creating pull demand for ambient voice documentation that captures encounters without keyboard interaction.
Market Restraints
- Algorithmic audit requirements:HIPAA mandates comprehensive logging of AI-patient interactions, extending engineering sprints and inflating compliance costs for conversational system developers.
- Data sovereignty fragmentation:The EU AI Act's risk classification for health applications forces vendors to maintain parallel technical documentation, duplicating quality management systems across jurisdictions.
- Speech recognition accuracy thresholds:Clinical terminology error rates above 5% trigger liability concerns, limiting deployment in high-stakes diagnostic contexts despite ambient documentation demand.
Strategic Opportunities
- Home health integration:Post-acute care providers in Germany lack conversational patient monitoring, creating white space for German-language chronic disease management chatbots.
- Multimodal convergence:Pairing large language models with computer vision enables symptom-checking through patient-submitted images, expanding use cases beyond text and voice.
- Japan's regulatory pathway:PMDA's Software as a Medical Device framework offers expedited review for AI diagnostic aids, attracting foreign vendors to Tokyo's digital health corridor.
Industry Challenges
- Clinical informatics talent scarcity:Engineers fluent in both transformer architectures and medical ontologies command premium compensation, constraining vendor hiring velocity.
- EHR interoperability friction:Health systems run fragmented electronic record environments, forcing conversational AI vendors to build and maintain dozens of proprietary integration connectors.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conversational AI in Healthcare Market Trends and Innovations
Foundation models trained on clinical corpora are redefining accuracy benchmarks for medical dialogue systems, compressing the performance gap between specialized healthcare NLP and general-purpose large language models.
Large language model inference is overtaking retrieval-augmented generation for patient-facing symptom checkers, with US health systems piloting direct-to-consumer diagnostic chatbots that bypass traditional decision-tree logic. Academic medical centers in Boston and San Francisco are deploying these systems for after-hours triage, compressing emergency department utilization for low-acuity presentations. The structural consequence is overtaking rule-based clinical decision support, as static protocol engines cannot match the conversational flexibility patients now expect.
The EU AI Act's high-risk system classification for medical AI is mandating conformity assessments before market entry, forcing conversational health application developers to establish notified body relationships and technical file documentation. German and French regulators are interpreting the Act's health domain provisions most stringently, creating a two-speed compliance environment across member states. Vendors are responding by segregating EU product roadmaps from US releases, accepting feature divergence to satisfy Brussels' ex-ante oversight requirements.
Health system procurement committees are consolidating vendor relationships around integrated platform providers rather than point solutions for patient engagement. Hospital networks in Texas and Florida are bundling conversational AI with existing EHR contracts, displacing standalone chatbot vendors that lack enterprise workflow integration. This concentration is most visible among nonprofit health systems with centralized IT governance, where single-vendor strategies reduce interoperability testing burdens and streamline security review cycles.
Conversational AI in Healthcare Market Segmentation
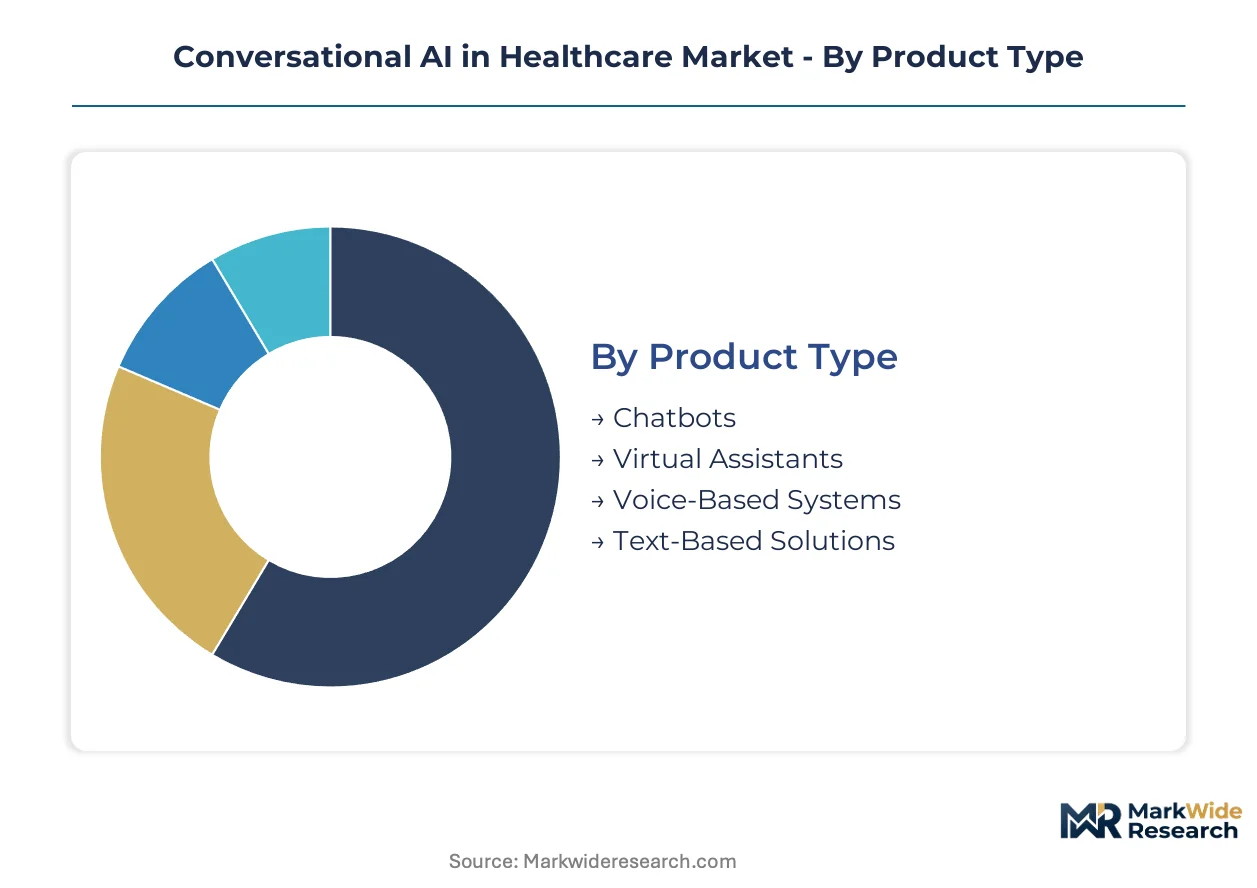
Segmentation reveals how conversational AI architectures map to distinct risk tolerances and workflow integration depths across healthcare delivery organizations. Product configurations range from standalone patient-facing interfaces to deeply embedded clinical documentation systems that require EHR synchronization.
Product Type:
Integration depth separates standalone patient engagement tools from systems requiring real-time clinical data exchange and provider workflow embedding.
- Chatbots:Rule-based and large language model-powered text interfaces handle symptom triage, medication reminders, and administrative queries through web and mobile portals. Hospitals in Texas and Florida deploy these for after-hours patient navigation, reducing emergency department volume for low-acuity presentations. Volume placements concentrate in Chatbots; the faster expansion belongs to Voice-Based Systems.
- Virtual Assistants:AI agents with persistent memory and multi-turn dialogue capabilities manage complex patient journeys including chronic disease monitoring and care coordination across specialties. These systems demand deeper EHR integration than simple chatbots, creating procurement friction for standalone vendors lacking enterprise workflow partnerships.
- Voice-Based Systems:Ambient clinical documentation tools capture physician-patient encounters through always-on microphones, transcribing and structuring notes directly into electronic health records without keyboard interaction. Academic medical centers in Boston pilot these for specialty clinics where hands-free data entry accelerates encounter throughput.
- Text-Based Solutions:SMS and secure messaging platforms deliver asynchronous patient communication for appointment confirmations, lab result delivery, and post-discharge follow-up. Telemedicine providers favor these for their minimal infrastructure requirements and broad patient device compatibility.
Procurement committees favor embedded architectures over standalone deployments as health systems consolidate vendor relationships around integrated platforms.
Application:
Administrative automation commands larger deployment volumes while clinical applications capture premium pricing through regulatory compliance requirements.
- Patient Engagement:Conversational interfaces handle appointment scheduling, medication adherence prompts, and wellness coaching through omnichannel delivery. These applications face lower FDA scrutiny than diagnostic tools, accelerating deployment timelines for risk-averse hospital legal departments.
- Clinical Documentation:Voice and text systems structure encounter notes, capture diagnostic reasoning, and suggest coding classifications for reimbursement optimization. The EU AI Act's high-risk system classification triggers conformity assessments for these applications, forcing parallel technical documentation across jurisdictions.
- Appointment Scheduling:Intelligent routing systems match patient symptoms and preferences with appropriate provider availability, reducing no-show rates through automated reminders. Ambulatory centers in Germany deploy German-language variants to address chronic disease management gaps in post-acute care.
- Remote Monitoring:Conversational agents collect patient-reported outcomes, triage alerts from connected devices, and escalate concerning patterns to clinical teams. These systems integrate with home health platforms to extend care continuity beyond facility walls.
Revenue concentration sits with Clinical Documentation; Patient Engagement gains share fastest as health systems prioritize automated access infrastructure.
End User:
IT governance maturity determines whether organizations adopt point solutions or demand enterprise-grade integration with existing electronic record environments.
- Hospitals:Large health systems with centralized procurement evaluate conversational AI through interoperability testing, security review cycles, and existing EHR contract bundling. Nonprofit networks with unified IT governance displace standalone vendors in favor of platform providers.
- Ambulatory Centers:Outpatient clinics prioritize rapid deployment and minimal infrastructure overhead, favoring cloud-based solutions with pre-built specialty templates. These settings lack dedicated informatics staff, driving demand for managed service delivery models.
- Telemedicine Providers:Virtual-first care organizations require conversational interfaces that scale across state lines while maintaining HIPAA compliance and state licensure verification. Hyperscale cloud certifications enable these deployments without captive data center construction.
- Diagnostic Laboratories:Testing facilities deploy conversational systems for result delivery, pre-test preparation instructions, and patient billing inquiries. These applications face lower clinical liability exposure than diagnostic recommendation engines.
Contract value peaks with Hospitals; Ambulatory Centers represent the most price-sensitive procurement segment.
Deployment:
Data sovereignty requirements and computational latency tolerances shape infrastructure architecture decisions across regulated healthcare environments.
- On-Premise:Captive server installations within hospital data centers satisfy strict data residency mandates and minimize external network dependency for critical clinical workflows. These deployments carry higher capital expenditure and dedicated operations staffing requirements.
- Cloud-Based:Hyperscale provider infrastructure delivers elastic compute for variable patient query volumes while offering healthcare-specific compliance certifications including HIPAA business associate agreements. Margin pools concentrate here through reduced infrastructure overhead and consumption-based pricing.
- Hybrid Models:Split architectures process sensitive patient data on-premise while leveraging cloud inference for non-clinical natural language tasks. Hospitals balancing data sovereignty with computational scalability favor this fastest-expanding configuration.
- Managed Services:Third-party operators handle infrastructure provisioning, model updates, and regulatory compliance monitoring on behalf of resource-constrained healthcare organizations. These arrangements appeal to ambulatory centers lacking dedicated AI engineering capabilities.
Cloud-Based deployments dominate current margin capture; Hybrid Models climb fastest as jurisdictional data fragmentation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for digital health in Singapore and Dubai are concentrating venture deployment and regulatory sandbox programs for conversational AI validation.
United States
Academic medical centers in Boston and San Francisco pilot ambient voice documentation for specialty clinics. FDA's predetermined change control plans accelerate clinical software approvals. Texas and Florida hospital networks bundle conversational AI with existing EHR contracts.
Germany
Post-acute care providers lack German-language chronic disease management chatbots, creating white space for patient monitoring solutions. The EU AI Act's high-risk system classification triggers conformity assessments for clinical documentation applications. Berlin and Munich health networks interpret Brussels' oversight requirements most stringently.
Japan
Aging demographics drive demand for home health conversational agents that extend care continuity beyond facility walls. PMDA's Software as a Medical Device framework offers expedited review for AI diagnostic aids. Tokyo's digital health corridor attracts foreign vendors seeking regulatory pathway efficiency.
United Kingdom
NHS trusts evaluate conversational AI through interoperability testing and existing enterprise workflow partnerships. MHRA guidance on AI-enabled medical devices shapes product development roadmaps for clinical documentation vendors. London health networks prioritize automated patient engagement infrastructure for administrative burden reduction.
India
Telemedicine platforms deploy conversational interfaces across state lines while maintaining compliance with digital health regulations. The country's national pharmaceutical regulator evaluates AI-enabled diagnostic tools through accelerated approval pathways. Bangalore and Hyderabad clusters concentrate engineering talent for healthcare NLP development.
Conversational AI in Healthcare Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers anchoring enterprise hospital contracts while niche vendors serve ambulatory point solutions. The vendor base concentrates around integrated platform providers capable of EHR synchronization and regulatory compliance documentation. Three archetypes dominate: cloud infrastructure anchors, specialized healthcare AI chipmakers, and clinical workflow integrators. Competitive moves center on strategic partnerships with health systems and portfolio diversification into multimodal diagnostic capabilities.
Within the cloud infrastructure tier, Microsoft and Google exemplify platform-scale positioning through enterprise workflow anchoring. NVIDIA occupies a specialized position as a healthcare AI chipset provider powering real-time inference systems. These three represent distinct competitive vectors: workflow integration depth, computational hardware specialization, and ambient documentation deployment scale.
| Leading Market Players |
|---|
| Google Health |
| IBM |
| Microsoft |
| Oracle |
| NVIDIA |
| IQVIA |
| GE HealthCare |
| Medtronic |
| Happiest Minds Technologies |
| Others |
Pricing and Supply Chain Analysis
Foundation model inference is compressing software development costs while concentrating computational supply around hyperscale cloud providers, simultaneously reducing marginal deployment expenses and tightening vendor dependency on NVIDIA GPU clusters and Microsoft Azure infrastructure. This technological shift restructures pricing power toward infrastructure owners and away from standalone application developers.
Pricing Analysis
Volume placements concentrate in standardized chatbot subscriptions while premium margins accrue to voice-based clinical documentation systems with FDA 510(k) clearance. Price differentiation hinges on HIPAA compliance certification tier and EHR integration depth, with cloud-native vendors commanding 40-60% premiums over on-premise alternatives. Cost compression in patient engagement tiers is intensifying because hyperscale providers bundle conversational modules with existing enterprise contracts. Ambulatory centers exhibit highest price sensitivity; academic medical centers with centralized IT governance show lowest sensitivity due to workflow integration requirements.
Supply Chain Analysis
Direct-to-health-system channels handle enterprise hospital demand, while managed service providers serve resource-constrained ambulatory clinics. Computational supply concentrates in United States, Taiwan, and Ireland where hyperscale data centers cluster. Raw material dependencies span NVIDIA H100 chipsets, specialized medical ontologies, and clinical corpus training data. Single-source vulnerability runs through NVIDIA's dominance in healthcare AI accelerators. Distribution runs through EHR-integrated platform partnerships rather than standalone software marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transformer architectures are displacing rule-based clinical NLP systems, creating a technology-transition window where vendor positioning crystallizes around inference infrastructure and regulatory documentation capabilities.
For Market Incumbents: Anchor enterprise hospital relationships through deeper EHR synchronization and FDA predetermined change control plan documentation to defend against cloud-native competitors. Pursue backward integration into specialized healthcare GPU provisioning to reduce NVIDIA dependency and capture infrastructure margin. Prioritize EU AI Act conformity assessment investment to maintain multinational deployment rights against regulatory fragmentation. For New Entrants and Emerging Players: Begin with German-language chronic disease management chatbots for post-acute care providers, the most penetrable white space in European home health. Target Japan's PMDA Software as a Medical Device pathway for expedited AI diagnostic aid approval. Pursue channel partnerships with telemedicine platforms lacking in-house NLP engineering as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by hyperscale cloud providers seeking healthcare vertical integration, with IPO viability restricted to platform-scale vendors with $100M+ recurring revenue. Acquisition target archetype: clinical workflow integrators with live EHR connections at 50+ hospital systems. Watch FDA guidance expansion into autonomous diagnostic recommendations as the signal for liability regime clarity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Predetermined Change Control Plan Submission | Accelerates clinical documentation software approval timelines for US health system deployment. |
| EU AI Act Conformity Assessment | Enables market access across German and French health networks under Brussels oversight. |
| Hospital System EHR Integration Partnership | Locks out standalone chatbot vendors through bundled procurement committee decisions. |
| Ambient Voice Documentation Product Launch | Captures physician administrative burden reduction demand in Boston academic medical centers. |
| Healthcare GPU Supply Agreement | Secures NVIDIA H100 allocation for real-time clinical inference against capacity constraints. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, hospital EHR contract announcements, and hyperscale healthcare cloud capex anchored the trend analysis, supplemented by interviews with hospital chief medical information officers, health system procurement directors, clinical NLP engineering leads, and FDA regulatory affairs specialists. Secondary validation drew from FDA device classification databases, CMS Medicare reimbursement filings, hospital GPO contract repositories, and hyperscale provider healthcare compliance disclosures. Bottom-up deployment counts triangulated against top-down market sizing from infrastructure spending patterns.
Input-output matrices mapped conversational AI adoption across deployment model, end-user IT governance maturity, integration complexity tier, and regional regulatory cluster dimensions over the projection horizon. CAGRs derived from segment-level deployment velocity curves weighted by average contract value. Industry-specific forecast inputs included FDA guidance publication timelines and EU AI Act implementation phase transitions.
Underlying measurement precision varies by segment; cloud-based deployments carry tighter precision than hybrid architectures due to hyperscale disclosure transparency. Forecasts reflect assumptions regarding regulatory pathway stability and EHR vendor partnership durability. Periodic stress-testing of base assumptions is recommended given evolving liability standards for autonomous clinical recommendations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.