
 Wearable Artificial Kidney Market | 2026-2036
Wearable Artificial Kidney Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Artificial Kidney Market Analysis
ISO 14155 clinical investigation standards are rotating the competitive field by requiring rigorous wearable device trials before market authorization. Quanta Dialysis Technologies Ltd. leverages its portable system architecture to compete in hospital-to-home transitions. Vivance (AWAK Technologies) anchors its position through sorbent-based regeneration technology that reduces dialysate volume requirements. Nextkidney specializes in miniaturized filtration modules designed for patient mobility during daily activities.
A wearable artificial kidney constitutes a portable or body-worn system that performs renal replacement therapy through integrated blood purification circuits, typically operating with ultrafiltration rates of 10-30 mL/min and sorbent-based dialysate regeneration to achieve continuous or intermittent toxin clearance outside clinical settings. The technology serves end-stage renal disease patients requiring alternatives to stationary hemodialysis machines. Portable dialysis devices dominate current revenue as the most mature product format, while bioartificial kidney platforms represent the fastest-growing segment due to their potential for biological kidney function restoration. Home care settings capture expanding margin pools as reimbursement frameworks shift toward value-based models that reward reduced clinic utilization.
The FDA breakthrough device program and EMA's innovation task force create parallel regulatory pathways that shape trial design and market access timelines for wearable renal systems. ISO 13485 quality management requirements and the EU Medical Device Regulation enforce biocompatibility and electrical safety standards that filter out undercapitalized entrants. Stakeholders must monitor evolving CMS reimbursement codes for home dialysis modalities and anticipate how sorbent cartridge replacement economics will influence patient adherence and lifetime value calculations.
Market Dynamics
ISO 14155 clinical investigation standards are reshaping competitive entry by mandating rigorous wearable device trials before market authorization, filtering out undercapitalized developers and elevating compliance costs across the sector.
Growth Catalysts
- FDA Breakthrough Device Designation:The FDA's accelerated pathway compresses commercialization timelines for qualifying renal systems, rewarding developers with prioritized review and enhanced payer engagement.
- Home Care Migration:End-stage renal disease patients are shifting from clinic-based hemodialysis toward ambulatory settings, creating pull-through demand for portable filtration platforms.
- Sorbent Regeneration Technology:Advanced dialysate recycling methods reduce fluid volume requirements by orders of magnitude, enabling true wearable form factors previously impossible with conventional cartridge systems.
Market Restraints
- Biocompatibility Certification Burden:ISO 10993 testing requirements for blood-contacting materials extend development cycles and consume substantial R&D budgets before first-in-human trials.
- Single-Source Component Risk:Specialized membrane filtration modules concentrate among German and Japanese suppliers, exposing assemblers to geopolitical supply interruptions.
- Transplant Substitution Threat:Living donor kidney exchange programs and improved immunosuppression protocols compete directly for the same patient pool in wealthy healthcare systems.
Strategic Opportunities
- Indian Subcontinent Expansion:India's CDSCO fast-track pathway for orphan devices and rising diabetic nephropathy incidence create first-mover potential for sorbent-based systems adapted to tropical climates.
- Peritoneal Dialysis Convergence:Hybrid platforms combining wearable hemofiltration with automated peritoneal cycling open dual-modality reimbursement streams and expand addressable patient segments.
- EU MDR Article 54 Consultation:The European Medicines Agency's early engagement mechanism for innovative devices provides regulatory certainty and accelerates CE marking for breakthrough renal technologies.
Industry Challenges
- Biomedical Engineering Talent Scarcity:The intersection of nephrology, membrane science, and wearable electronics requires specialists rarely produced by traditional academic pipelines.
- Clinical Site Activation Delays:ISO 14155-compliant investigation sites with wearable device expertise concentrate in fewer than twelve academic medical centers globally, creating enrollment bottlenecks.
- Legacy Hemodialysis Infrastructure Lock-In:Existing clinic capital investments and trained nursing workforces resist displacement by home-based modalities despite superior patient outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Artificial Kidney Market |
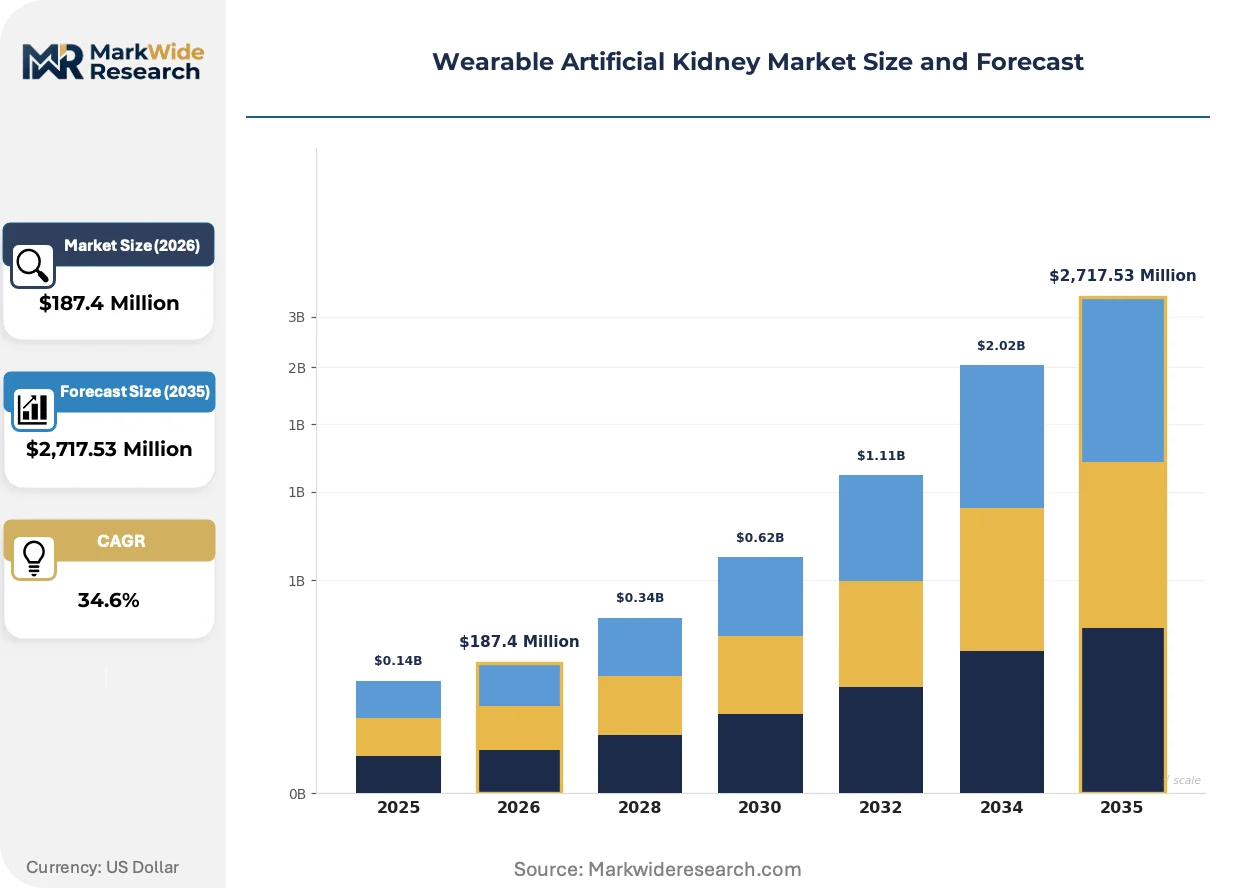
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,717.53 Million |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Dialysis Device, Continuous Renal Replacement Therapy, Wearable Hemodialysis Device, Bioartificial Kidney Technology: Filtration Technology, Ultrafiltration, Peritoneal Dialysis, Electrodialysis End User: Home Care, Hospitals, Clinics, Research Institutions Delivery Mode: Continuous, Intermittent, Scheduled, Automated |
| Companies Covered | KidneyX, Victor Gura, M.D., Vivance (AWAK Technologies), Quanta Dialysis Technologies Ltd., WearOptimo, Nextkidney, Blood Purification Technologies Inc., Triomed AB, NephriaBio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Artificial Kidney Market Emerging Trajectories
Sorbent-based dialysate regeneration is bifurcating product architectures across the wearable renal space, separating continuous-flow systems from intermittent-batch designs and forcing developers to commit to irreversible technical roadmaps.
Miniaturized filtration membranes incorporating silicon nanopore arrays achieve ultrafiltration rates of 20-30 mL/min within palm-sized footprints. Home care providers are piloting these systems for nocturnal therapy, displacing daytime clinic visits. The technology is bifurcating competitive positioning between portability-maximizing startups and incumbent dialysis chains defending installed base economics through hybrid offerings.
The EU Medical Device Regulation's Article 117 requirement for notified body involvement in clinical evaluation reports extends review timelines for wearable renal devices. Manufacturers are responding by front-loading quality management system investments and pursuing MDR certification before US FDA submission. Class III implantable subsegments face the steepest compliance cost escalation, diverting development resources from software-enabled features toward biological safety documentation.
Patient self-management preferences are compressing traditional care delivery hierarchies, with end-stage renal disease cohorts demanding direct-to-consumer device access and telemedicine oversight. Durable medical equipment distributors are losing channel control to specialty renal pharmacies and hospital-at-home programs. This behavioral shift concentrates in the United States and Germany, where reimbursement codes already accommodate remote patient monitoring for home dialysis modalities.
Wearable Artificial Kidney Market Segmentation
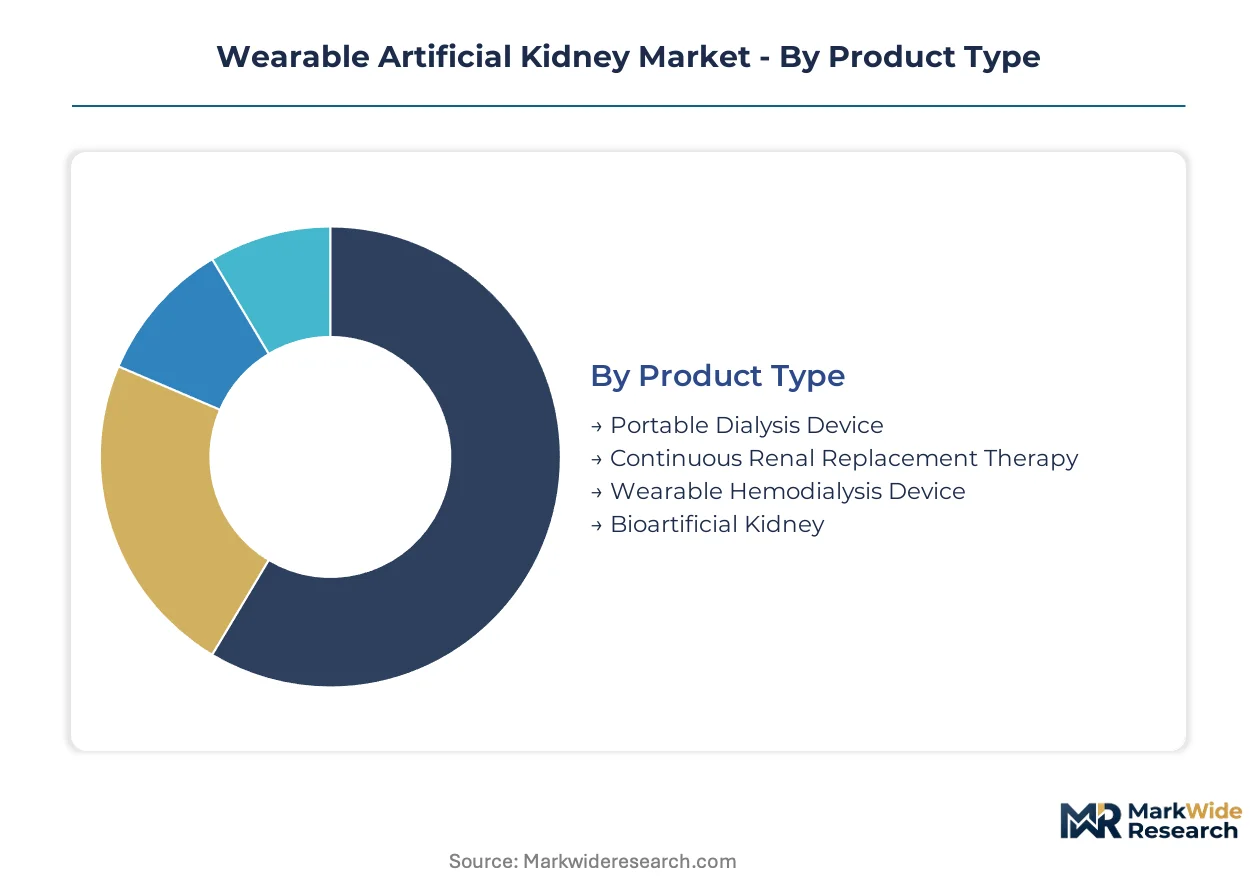
Wearable renal systems fragment across four structural dimensions that determine reimbursement eligibility, regulatory pathway, and patient selection criteria. Product architecture and delivery mode choices lock developers into irreversible technical roadmaps with distinct capital intensity profiles.
Product Type:
Transplant substitution pressure concentrates heaviest on portable formats that merely replicate conventional hemodialysis, while bioartificial platforms face lighter substitution risk due to their biological function restoration promise.
- Portable Dialysis Device:Compact systems integrate blood pumps, dialyzers, and sorbent cartridges into transportable enclosures weighing under 5 kg. Demand clusters in United States home care settings where CMS reimbursement codes for remote patient monitoring reduce clinic dependency. Supply chain exposure to German and Japanese membrane suppliers constrains margin expansion.
- Bioartificial Kidney:Hybrid devices combine silicon nanopore filtration with living renal tubule cells to replicate biological clearance and endocrine functions. Research institutions in California and Massachusetts drive early adoption for patients awaiting transplant. Regulatory complexity under FDA combination product rules extends development timelines beyond pure mechanical alternatives.
- Continuous Renal Replacement Therapy:Hospital-deployed systems target acute kidney injury in ICU settings with 24-hour gentle ultrafiltration.
- Wearable Hemodialysis Device:Belt-worn or vest-integrated platforms enable ambulatory toxin clearance during daily activities.
Portable dialysis devices retain volume leadership; bioartificial kidney platforms hold the steepest expansion curve.
Technology:
Cost tier stratification separates sorbent-based regeneration systems commanding premium pricing from conventional filtration methods facing commodity pressure.
- Filtration Technology:Membrane-based separation using hollow-fiber or flat-sheet configurations achieves molecular weight cutoffs of 10-50 kDa for uremic toxin removal. German industrial clusters around membrane manufacturing concentrate supply, exposing assemblers to single-source risk. ISO 10993 biocompatibility testing requirements for blood-contacting surfaces elevate R&D budgets before first-in-human trials.
- Ultrafiltration:Pressure-driven plasma water removal at 10-30 mL/min rates enables precise volume management without osmotic agents. Home care providers in Germany pilot nocturnal ultrafiltration protocols that displace daytime clinic visits. Patient self-management preferences accelerate direct-to-consumer channel development.
- Peritoneal Dialysis:Catheter-based intraperitoneal fluid exchange leverages the peritoneal membrane as natural filter.
- Electrodialysis:Electric field-driven ion transport reduces dialysate volume requirements through selective toxin migration.
Filtration technology anchors current revenue concentration; ultrafiltration methods are gaining share fastest in ambulatory settings.
End User:
Application concentration determines margin structure, with institutional purchasers demanding volume discounts while home care patients prioritize portability premiums.
- Home Care:Patient-directed therapy outside clinical facilities requires intuitive interfaces, remote monitoring connectivity, and simplified consumable replacement. United States reimbursement frameworks under CMS transitional care management codes reward reduced hospital readmission rates. Specialty renal pharmacies displace traditional durable medical equipment distributors in channel control.
- Hospitals:Acute care settings demand 24/7 technical support, crash cart compatibility, and integration with electronic health record systems. Academic medical centers in Boston, Cleveland, and Pittsburgh concentrate ISO 14155-compliant investigation sites, creating enrollment bottlenecks for pivotal trials.
- Clinics:Outpatient dialysis centers seek hybrid platforms that bridge in-center and home modalities.
- Research Institutions:Universities and contract research organizations drive early-stage validation for breakthrough device designation pathways.
Home care captures expanding margin pools; hospitals maintain the steepest procurement volume trajectory.
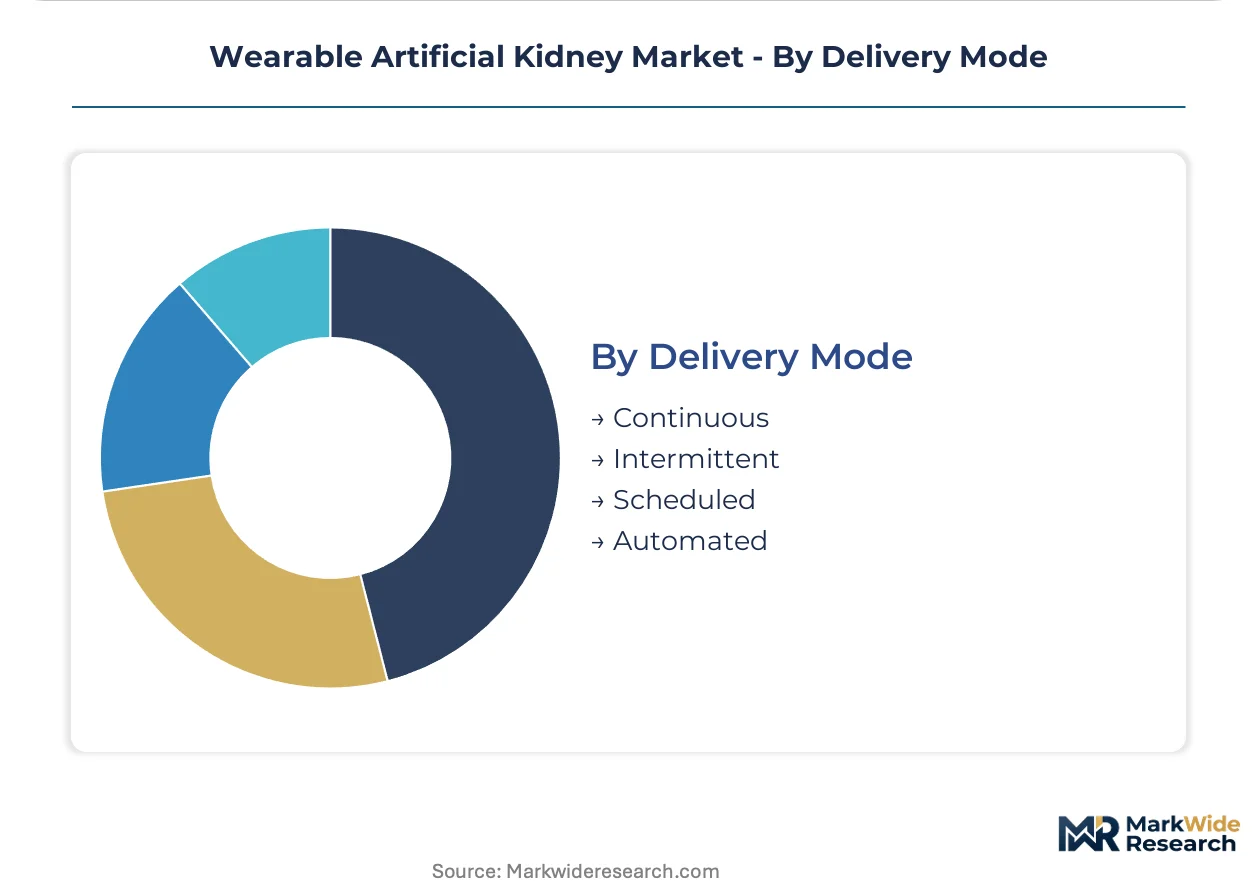
Delivery Mode:
Maturity gradients separate continuous-flow architectures with established reimbursement from automated formats requiring new clinical evidence generation.
- Continuous:Uninterrupted 24-hour toxin clearance mimics native kidney function and reduces peak solute concentrations. Nocturnal therapy protocols in United States home care settings demonstrate superior cardiovascular outcomes versus thrice-weekly clinic hemodialysis. Sorbent cartridge replacement economics influence patient adherence and lifetime value calculations.
- Intermittent:Scheduled treatment sessions align with patient activity patterns and caregiver availability. European Union MDR Article 54 consultation mechanisms provide regulatory certainty for intermittent platforms before US FDA submission.
- Scheduled:Fixed-time delivery windows accommodate employment and travel constraints.
- Automated:Algorithm-driven dose adjustment responds to real-time biomarker feedback.
Continuous delivery retains clinical preference leadership; automated modes are climbing the fastest as artificial intelligence integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home care settings concentrate buyer archetypes in the United States, where CMS reimbursement codes reward reduced clinic utilization. European academic medical centers anchor clinical trial infrastructure under EMA oversight. Asian markets present fast-track regulatory pathways for orphan devices.
United States
Chronic kidney disease prevalence and established reimbursement infrastructure drive patient migration toward ambulatory dialysis modalities. The FDA breakthrough device designation pathway compresses commercialization timelines for qualifying renal systems. Boston, Cleveland, and Pittsburgh concentrate ISO 14155-compliant investigation sites, creating enrollment bottlenecks for pivotal trials.
Germany
Industrial clusters around membrane manufacturing concentrate supply for hollow-fiber filtration modules. The EU Medical Device Regulation enforces biocompatibility and electrical safety standards through notified body involvement in clinical evaluation reports. Academic medical centers in Munich and Heidelberg pilot nocturnal ultrafiltration protocols that displace daytime clinic visits.
Japan
Aging demographics and diabetic nephropathy incidence expand the addressable patient pool for portable renal replacement systems. PMDA regulatory frameworks align with international standards while maintaining distinct quality management requirements. Tokyo and Osaka metropolitan areas host specialized nephrology research institutions driving early adoption of bioartificial platforms.
India
Rising diabetic nephropathy incidence and limited transplant infrastructure create demand for sorbent-based wearable systems adapted to tropical climates. CDSCO fast-track pathways for orphan devices accelerate market access timelines for breakthrough renal technologies. Hyderabad and Bangalore medical device clusters attract developers seeking cost-efficient manufacturing and clinical validation partnerships.
United Kingdom
NHS England's shift toward value-based care models rewards home dialysis modalities that reduce hospital readmission rates. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR standards while introducing distinct UKCA marking requirements. London and Cambridge research institutions anchor early-stage validation for silicon nanopore filtration technologies.
Wearable Artificial Kidney Market Vendor Landscape
Player mix skews toward venture-backed medical device developers with specialized nephrology expertise rather than diversified healthcare conglomerates. The competitive field rotates around ISO 14155 compliance capabilities and sorbent regeneration intellectual property. Two strategic archetypes dominate: portable system architects optimizing hospital-to-home transitions, and bioartificial platform developers pursuing biological function restoration. Dominant competitive moves include strategic partnerships with academic medical centers for trial site access, and technology licensing agreements securing membrane supply from German and Japanese suppliers.
Within the portable system tier, Quanta Dialysis Technologies Ltd. and Vivance (AWAK Technologies) occupy positions defined by their sorbent-based regeneration approaches. Nextkidney represents the miniaturization-focused archetype targeting patient mobility during daily activities. Blood Purification Technologies Inc. anchors the North American development cluster. These developers exemplify the technical roadmap bifurcation between continuous-flow and intermittent-batch architectures.
| Leading Market Players |
|---|
| KidneyX |
| Victor Gura, M.D. |
| Vivance (AWAK Technologies) |
| Quanta Dialysis Technologies Ltd. |
| WearOptimo |
| Nextkidney |
| Blood Purification Technologies Inc. |
| Triomed AB |
| NephriaBio |
| Others |
Supply Flow & Price Mechanics
Membrane manufacturing scale economies in Germany and Japan establish price floors for filtration modules, concentrating supply-side leverage among hollow-fiber producers while forcing assemblers to absorb biocompatibility certification costs that resist volume-driven reduction.
Pricing Analysis
Cost-plus contracts with sorbent cartridge suppliers incorporate medical-grade resin indexation, insulating developers from petrochemical volatility. Three-tier pricing structure across premium bioartificial platforms, standard portable systems, and economy intermittent devices reflects FDA breakthrough designation premiums versus CE-marked alternatives. Pricing pressure stems from CMS reimbursement code negotiations that cap home dialysis device margins. Hospital procurement committees exhibit lowest price sensitivity due to bundled payment structures, while direct-to-consumer channels face acute sensitivity to out-of-pocket sorbent replacement economics.
Supply Chain Analysis
Germany and Japan anchor hollow-fiber membrane production, while the United States concentrates sorbent regeneration chemistry development. Blood-contacting polymers draw from specialized medical-grade resin suppliers in Belgium and Switzerland. Single-source vulnerability concentrates in silicon nanopore array foundries, where MEMS fabrication capacity books 18-24 months forward. Distribution runs through specialty renal pharmacies displacing traditional durable medical equipment channels, particularly in United States home care markets where remote patient monitoring integration determines formulary placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as transplant waiting list expansion and living donor program stagnation renew urgency for renal replacement alternatives, creating demand pull-through independent of macro healthcare spending cycles.
For Market Incumbents: Compound technical roadmaps around sorbent regeneration intellectual property to extend FDA breakthrough designation exclusivity windows. Defend installed base economics by embedding remote patient monitoring software that raises switching costs for home care providers facing CMS value-based reimbursement thresholds. Vertical integration into German membrane supply chains mitigates geopolitical interruption risk.
For New Entrants and Emerging Players: Telemedicine oversight gaps in United States specialty renal pharmacies represent under-served service infrastructure where automated dosing algorithms can displace incumbent technical support models. Target Indian CDSCO fast-track pathways for tropical-adapted sorbent systems before established players localize manufacturing. Pursue hospital-at-home program partnerships as direct channel access bypassing GPO contract lock-in.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bioartificial kidney platforms with combination product regulatory pathways that extend competitive moats beyond mechanical filtration commoditization. Five-to-ten year viability hinges on clinical evidence generation for cardiovascular outcome superiority versus conventional hemodialysis. Watch FDA breakthrough device designation grants to AWAK Technologies and Quanta Dialysis Technologies as inflection signals for reimbursement code expansion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Prioritized review compresses commercialization timelines for qualifying sorbent-based systems. |
| EU MDR Article 54 Consultation | Early EMA engagement accelerates CE marking for innovative renal replacement technologies. |
| Academic Medical Center Partnership | ISO 14155-compliant trial site access in Boston and Cleveland unlocks enrollment bottlenecks. |
| Software Companion Development | Remote patient monitoring integration satisfies CMS transitional care management reimbursement requirements. |
| Reimbursement Strategy | Home dialysis modality code expansion determines patient lifetime value calculations for device economics. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) and breakthrough device filings, EMA innovation task force submissions, CMS Medicare reimbursement databases, and ISO 14155 clinical investigation registries. Primary interviews engaged biomedical engineering directors at wearable renal developers, nephrology department chairs at academic medical centers, GPO contracts managers for dialysis equipment, and specialty renal pharmacy procurement leads. Bottom-up patient population modeling triangulates against top-down healthcare expenditure tracking across home care and hospital segments.
Segmentation dimensions modeled span product architecture, dialysate regeneration technology, end-user setting, and delivery mode continuity across the projection horizon. CAGRs derive from installed base penetration curves for home dialysis modalities, sorbent cartridge replacement frequency assumptions, and reimbursement code expansion scenarios. Industry-specific forecast inputs incorporate transplant waiting list dynamics and diabetic nephropathy incidence trajectories.
Material uncertainties — regulatory pathway delays, biocompatibility certification failures, and sorbent supply interruptions — sit outside the modeled envelope. Forecasts reflect assumptions about ISO 13485 quality management compliance timelines and MDR notified body capacity constraints. Recalibration cycles align with material shifts in FDA breakthrough device designation velocity and CMS value-based care model expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Clot Management Devices Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Medical Fiber Optics Market
Medical Devices
Global Enteral Feeding Tubes Market
Medical Devices
Cervical Implants Market
Medical Devices
Global Medical Loupes Market
Medical Devices
Pneumatic Nebulizers Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
Contact Cast Systems Market
Medical Devices
Glass Syringe Market
Medical Devices
BFS Syringes Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Endoscope Procedure Kits Market