
 Global Real World Evidence Solutions Market | 2026-2036
Global Real World Evidence Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Real World Evidence Solutions Market Foresight
The real world evidence solutions market is restructuring around a sharp divergence between premium analytics platforms with proprietary data networks and commodity software vendors reselling standardized datasets. IQVIA Inc. leverages its integrated clinical-commercial data ecosystem to anchor high-margin evidence generation services for top-tier pharmaceutical clients. Flatiron Health specializes in oncology-specific real-world data curation, while Oracle Corporation competes through cloud infrastructure scale that underpins enterprise-wide deployment of evidence platforms across multiple therapeutic areas.
Real world evidence solutions encompass technologies and services that collect, integrate, and analyze patient health data derived from routine clinical practice, electronic health records, claims databases, and wearable devices to generate clinically meaningful insights outside traditional randomized controlled trials. These systems employ FHIR-based interoperability standards, natural language processing for unstructured clinical notes, and distributed analytics frameworks to protect patient privacy while enabling multi-source data fusion. Evidence generation solutions currently lead solution type segmentation by revenue contribution, reflecting pharmaceutical sponsor demand for regulatory-grade observational studies; patient analytics represents the fastest-expanding category as biotech firms seek biomarker discovery and treatment pathway optimization. Cloud-based deployment models dominate new implementations, though hybrid architectures persist among European clients navigating GDPR-compliant data residency requirements.
The FDA's Real-World Evidence program and EMA's DARWIN EU initiative establish divergent but converging frameworks for observational study acceptance, directly shaping product development roadmaps and market access strategies for solution vendors. ISO 14155 and ICH E6(R2) guidelines impose methodological rigor that filters out underqualified analytics providers and elevates vendors with established biostatistical credentials. Stakeholders must monitor evolving health data privacy legislation across Germany, France, and Japan, as fragmented compliance requirements threaten the cross-border data liquidity upon which scalable evidence networks depend.
Market Dynamics
Pharmaceutical sponsors now demand regulatory-grade observational studies at trial-comparable speeds, compressing evidence generation timelines from years to months and forcing platform vendors to automate biostatistical workflows.
Growth Catalysts
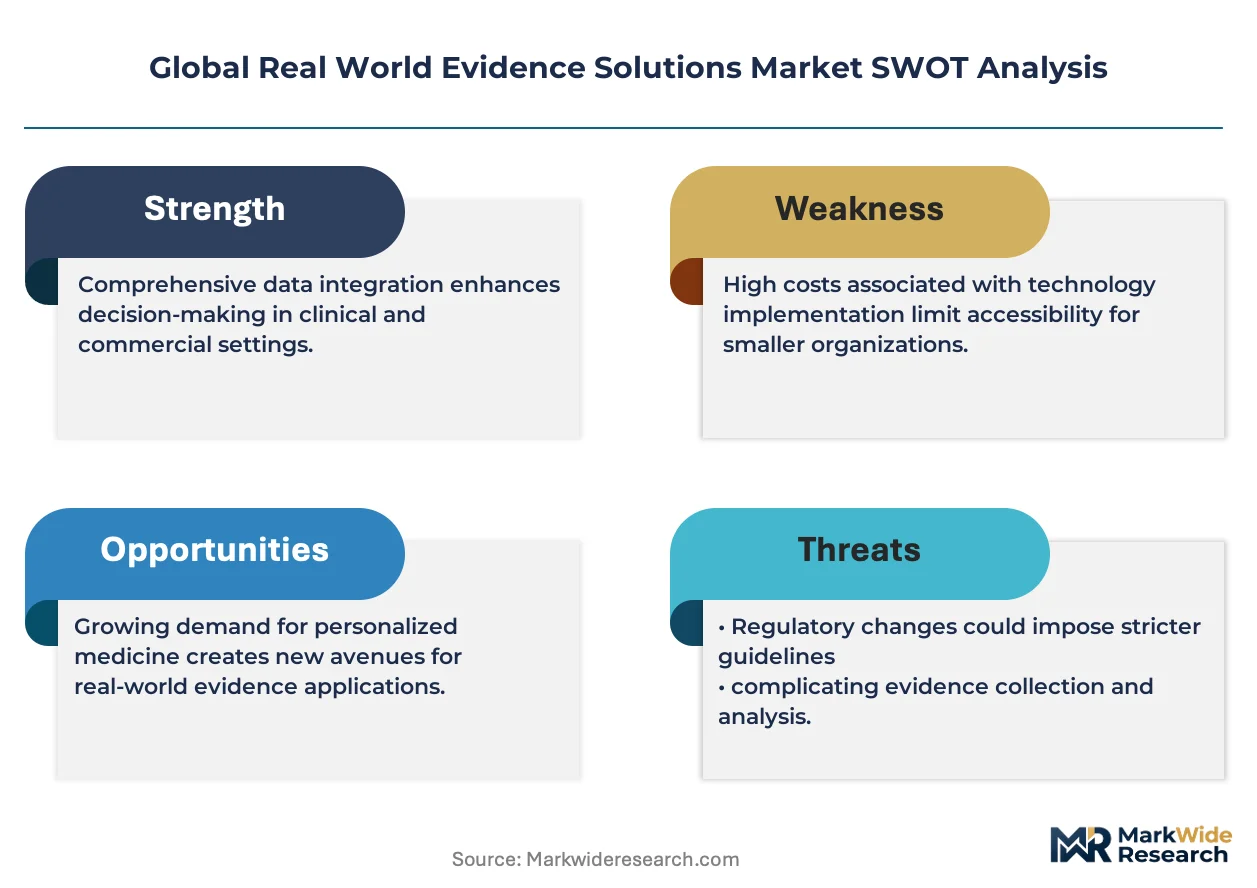
- FDA Real-World Evidence Program:The FDA's structured framework for RWE submissions in drug approvals accelerates pharmaceutical investment in compliant data infrastructure.
- Oncology biomarker discovery:Biotech firms deploy patient analytics to identify treatment-responsive subpopulations outside controlled trial settings.
- FHIR interoperability standards:Fast Healthcare Interoperability Resources enable seamless EHR-to-platform data pipelines, reducing integration costs for health systems.
Market Restraints
- GDPR data residency requirements:European mandates for local data storage fragment cross-border evidence networks and inflate infrastructure costs.
- Natural language processing limitations:Unstructured clinical notes in multiple languages degrade extraction accuracy for multinational studies.
- Specialized biostatistician scarcity:Shortage of professionals trained in both observational epidemiology and regulatory submission standards constrains service expansion.
Strategic Opportunities
- Japan's PMDA RWE guidance:Japan's pharmaceutical regulator actively solicits real-world data for post-market surveillance, creating entry points for compliant platform providers.
- Wearable device convergence:Integration of continuous glucose monitors and cardiac sensors with EHR platforms enables novel efficacy endpoints in diabetes and cardiovascular studies.
- Payer-provider data integration:United States integrated delivery networks seek unified analytics spanning claims, clinical, and pharmacy data for value-based contracting.
Industry Challenges
- Legacy EHR system integration:Proprietary data formats in older hospital information systems require costly custom mapping for evidence platform connectivity.
- ISO 14155 methodological compliance:Adherence to international clinical investigation standards demands extensive protocol documentation that slows study initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Real World Evidence Solutions Market |
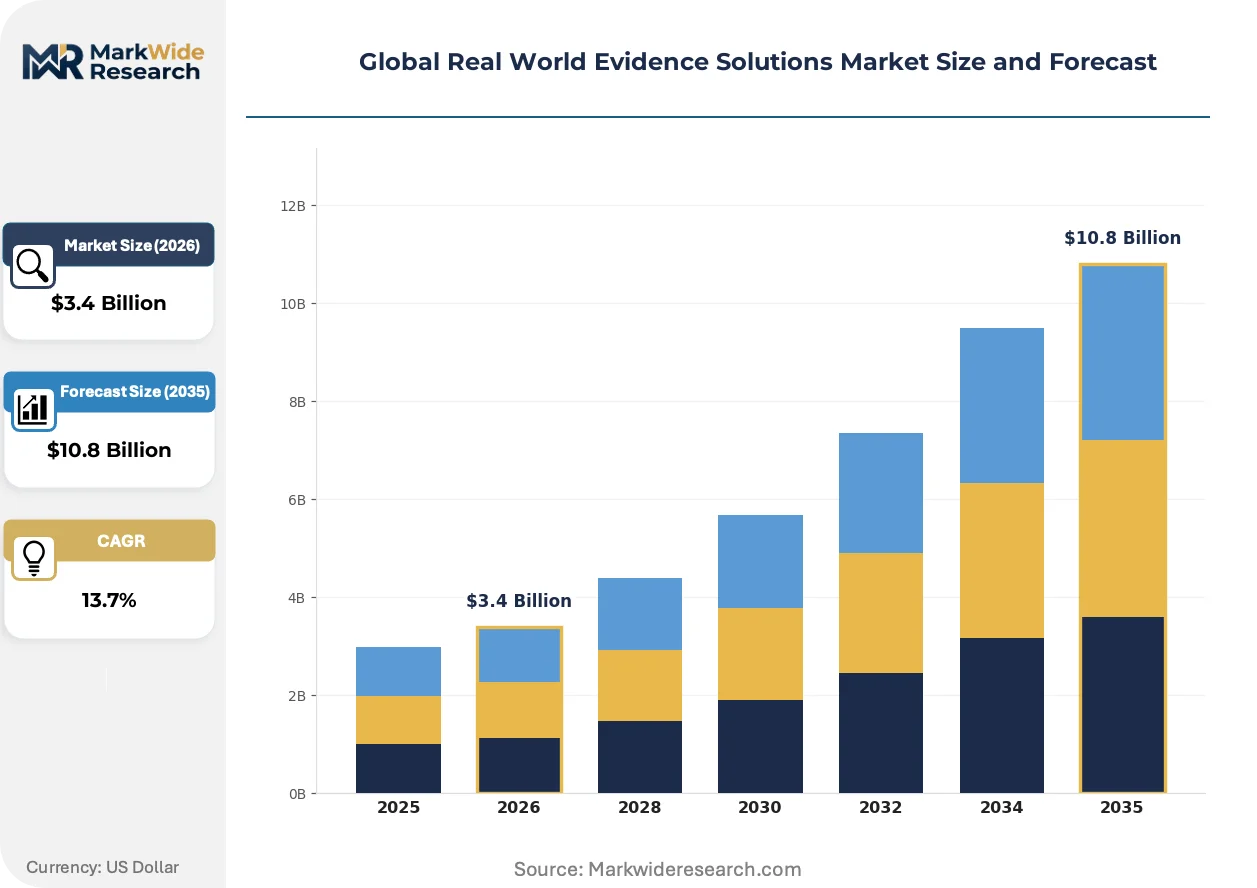
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $10.8 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Integration, Evidence Generation, Patient Analytics, Safety Surveillance, Market Access Application Area: Pharmacovigilance, Health Economics, Clinical Development, Regulatory Compliance, Drug Safety End User: Pharmaceutical Companies, Biotech Firms, Research Organizations, Regulatory Authorities, Payers Deployment Model: Cloud-Based, On-Premise, Hybrid Solutions, SaaS Platforms, Managed Services |
| Companies Covered | IQVIA Inc., IBM Corporation, Optum Inc., ICON plc, Oracle Corporation, Syneos Health, Parexel International Corporation, Flatiron Health, Merative, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Real World Evidence Solutions Market Shifts & Advancements
Distributed analytics architectures and federated learning protocols are restructuring how sensitive health data moves across organizational boundaries, reducing reliance on centralized data lakes while preserving analytical utility.
Federated learning is decentralizing evidence generation by enabling model training across siloed hospital databases without raw data transfer. Pharmaceutical sponsors in immuno-oncology now demand federated deployments to access academic medical center populations. This architecture is compressing patient recruitment timelines while satisfying institutional review board constraints on data export.
The EMA's DARWIN EU initiative establishes a coordinated network of real-world data sources across member states for regulatory decision-making. Pharmaceutical sponsors must now design studies compatible with this distributed infrastructure from protocol inception. Oncology and rare disease applications face the steepest adaptation curves given data sparsity in smaller member states.
Biotech procurement teams now unbundle evidence generation from full-service contracts, selecting specialized analytics vendors for specific study phases. This disintermediation fragments incumbent relationships and elevates vendors with modular, API-accessible platforms. The United States exhibits the most pronounced unbundling as sponsor finance teams scrutinize per-study economics.
Global Real World Evidence Solutions Market Segmentation
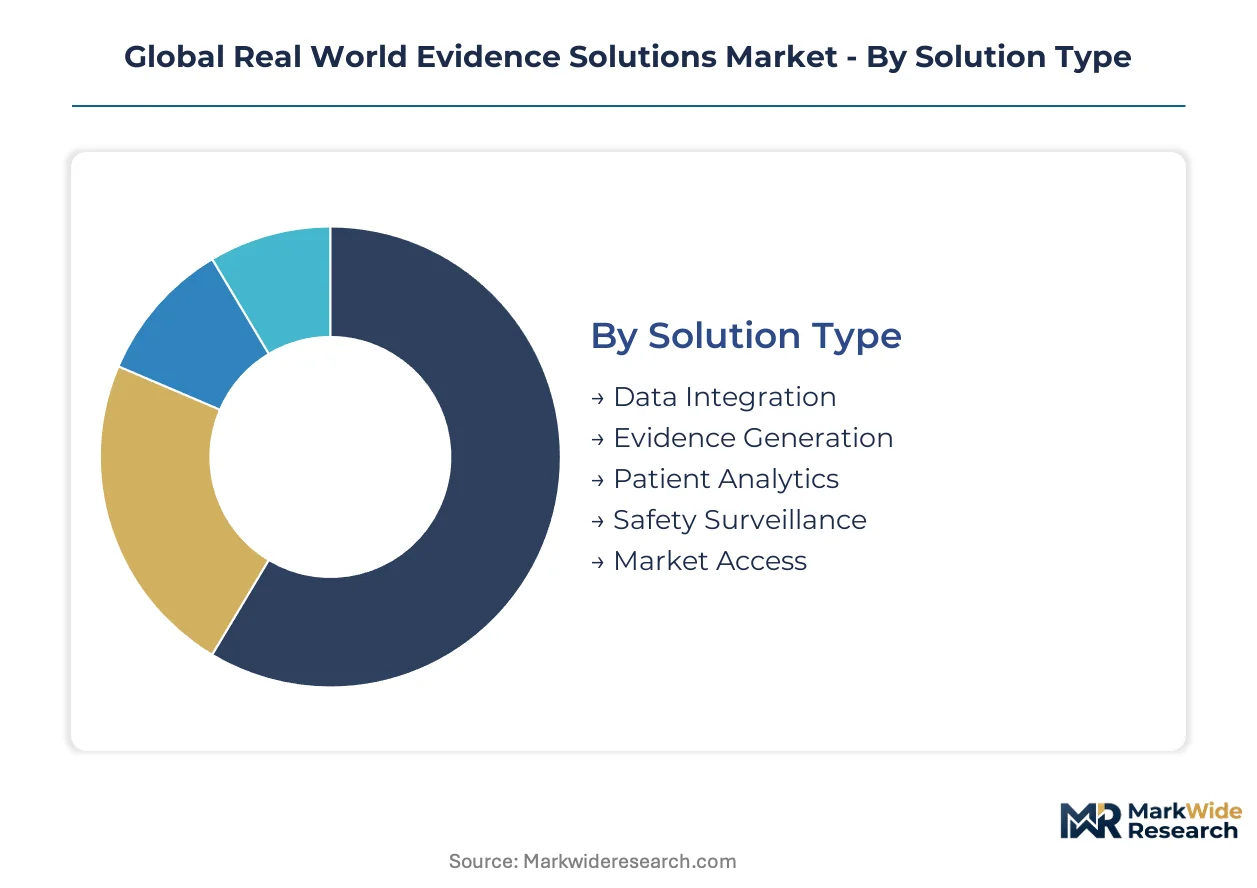
Segmentation in real world evidence solutions reveals how vendor capabilities align with pharmaceutical sponsor workflows. Procurement teams now unbundle evidence generation across specialized platforms rather than purchasing monolithic suites.
Solution Type:
Customization intensity varies sharply across this category, with bespoke protocol design commanding premium pricing against standardized safety surveillance modules.
- Evidence Generation:Regulatory-grade observational study platforms integrate biostatistical automation with protocol templates aligned to FDA and EMA submission standards. Pharmaceutical sponsors in the United States deploy these systems to compress study timelines from years to months. Demand concentrates among top-20 sponsors seeking label expansion indications.
- Patient Analytics:Biomarker discovery platforms fuse EHR-derived phenotyping with genomic data to identify treatment-responsive subpopulations outside controlled trials. Biotech firms leverage these tools for adaptive trial design and companion diagnostic development. Expansion is steepest in oncology and rare disease applications.
- Data Integration:FHIR-based interoperability engines normalize heterogeneous EHR, claims, and wearable data streams into analysis-ready formats.
- Safety Surveillance:Signal detection platforms monitor adverse event patterns across distributed health system networks.
- Market Access:Value demonstration tools synthesize real-world cost-effectiveness data for payer negotiations.
Most installed capacity flows through Evidence Generation. Expansion is steepest in Patient Analytics.
Application Area:
Cost tier stratification separates enterprise-wide pharmacovigilance deployments from targeted health economics modules.
- Pharmacovigilance:Continuous safety monitoring systems aggregate spontaneous reports, EHR signals, and claims data to detect adverse drug reactions. Regulatory mandates from the FDA and EMA drive mandatory adoption across marketed product portfolios. Large pharmaceutical sponsors maintain dedicated surveillance infrastructure.
- Clinical Development:External control arm generation and synthetic cohort construction accelerate trial design while reducing placebo arm enrollment. Oncology developers deploy these capabilities to access historical comparator data from academic medical centers. Demand is climbing fastest in immuno-oncology and gene therapy programs.
- Health Economics:Budget impact and cost-effectiveness modeling tools support market access submissions.
- Regulatory Compliance:Audit-ready documentation systems maintain chain-of-custody for observational data.
- Drug Safety:Risk management and minimization strategy platforms track mandated pharmacovigilance activities.
Volume concentrates in Pharmacovigilance. Margin expansion is strongest in Clinical Development.
End User:
Customer type determines deployment scale, with pharmaceutical companies purchasing enterprise licenses versus research organizations selecting per-study contracts.
- Pharmaceutical Companies:Integrated evidence platforms spanning the clinical-commercial lifecycle anchor vendor relationships. Top-tier sponsors demand federated learning architectures to access academic medical center data without raw data export. United States-based manufacturers lead procurement of modular, API-accessible systems.
- Biotech Firms:Asset-specific evidence generation contracts prioritize speed and regulatory agility over comprehensive functionality. Emerging biotechs in Cambridge and South San Francisco clusters favor cloud-native platforms with rapid study startup capabilities. This segment is gaining share fastest among venture-backed oncology developers.
- Research Organizations:Academic medical centers and contract research organizations deploy evidence tools for investigator-initiated studies.
- Regulatory Authorities:FDA and EMA internal surveillance systems require specialized data access and methodological transparency.
- Payers:United States integrated delivery networks seek unified analytics spanning claims, clinical, and pharmacy data for value-based contracting.
Revenue concentration sits with Pharmaceutical Companies. Biotech Firms are expanding procurement most quickly.
Deployment Model:
Maturity gradients separate established on-premise installations at European sites from cloud-native implementations among United States biotechs.
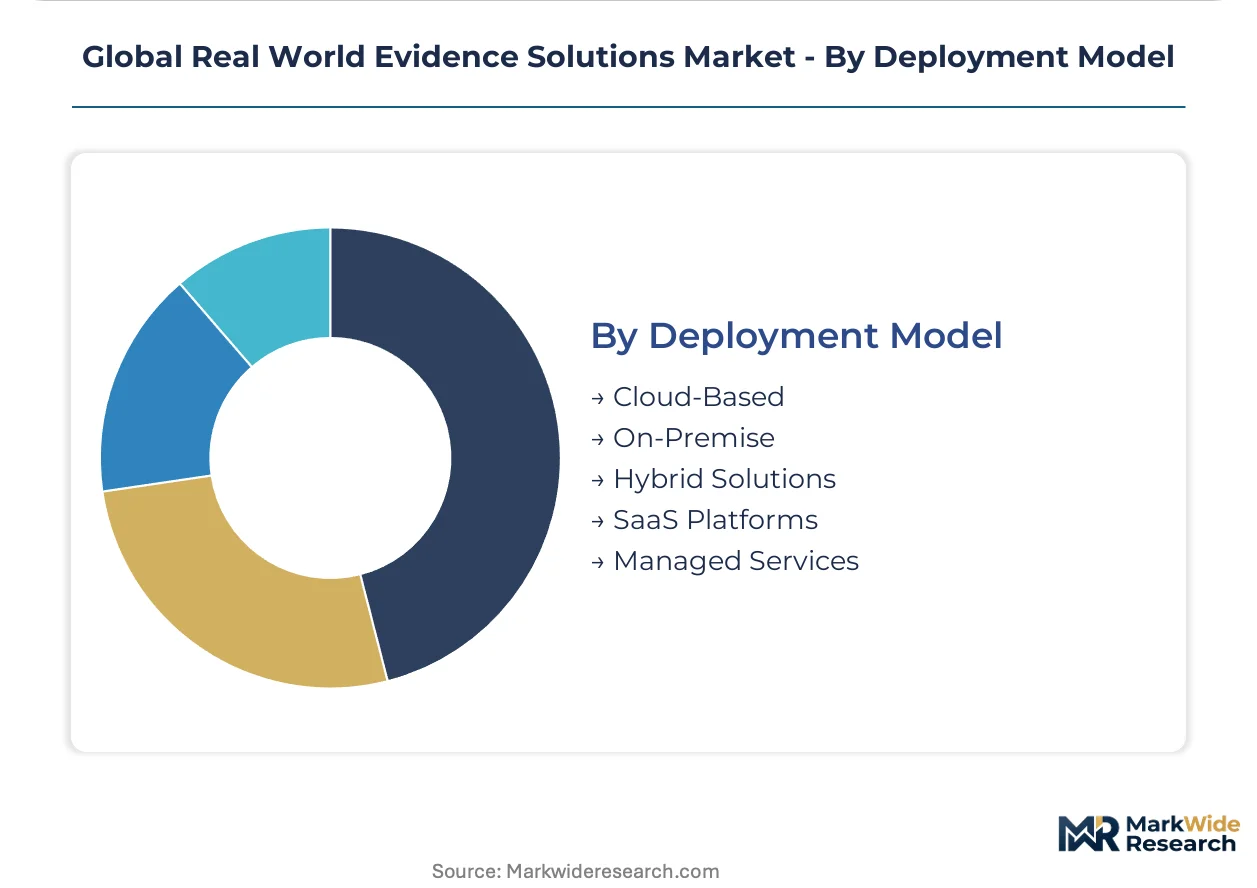
- Cloud-Based:Scalable infrastructure enables rapid study provisioning and elastic compute for large-scale federated analyses. United States health systems and biotech sponsors dominate adoption, driven by speed-to-deployment priorities. GDPR-compliant European implementations require regional data residency configurations.
- Hybrid Solutions:Sensitive patient data remains on-premise while analytics workloads execute in cloud environments. German and French healthcare institutions favor this architecture to satisfy national data protection requirements. This model is expanding most quickly among multinational pharmaceutical sponsors navigating fragmented privacy regimes.
- On-Premise:Legacy installations persist at security-conscious government research institutions.
- SaaS Platforms:Subscription-based evidence tools target mid-market biotechs with standardized study templates.
- Managed Services:Full-service evidence generation bundles platform access with biostatistical staffing.
Installed base tilts toward Cloud-Based deployments. Hybrid Solutions are climbing the fastest as European privacy requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized biostatisticians and health informatics professionals concentrate in the United States, Germany, and Japan, anchoring regional evidence generation capabilities. These talent clusters shape platform development priorities and regulatory submission standards across jurisdictions.
United States
Integrated payer-provider datasets and mature health informatics infrastructure create favorable conditions for advanced analytics deployment. The FDA's 21st Century Cures Act framework accelerates compliant platform investment. Cambridge and South San Francisco biotech clusters drive rapid study startup demand for cloud-native evidence tools.
Germany
Academic medical centers in Berlin and Heidelberg generate substantial observational research demand for federated learning architectures. GDPR data residency requirements favor hybrid cloud deployments with on-premise sensitive data storage. The country's national pharmaceutical regulator enforces ISO 14155 methodological rigor that elevates vendors with established biostatistical credentials.
United Kingdom
The NHS Digital infrastructure provides unified EHR access that reduces evidence platform integration costs. EMA's DARWIN EU initiative participation requires study designs compatible with distributed cross-border data networks. London's health economics consulting cluster specializes in value demonstration tools for payer negotiations.
Japan
PMDA's active solicitation of real-world data for post-market surveillance creates entry points for compliant platform providers. METI's digital health initiatives accelerate FHIR-based interoperability adoption across hospital networks. Tokyo and Osaka pharmaceutical R&D centers drive demand for regulatory-grade observational studies at trial-comparable speeds.
France
ANSM and CNIL oversight creates dual compliance requirements for evidence platform deployments. The country's national health data system supports multi-source data fusion for safety surveillance applications. Paris-based health technology assessment bodies demand standardized cost-effectiveness modules for market access submissions.
Global Real World Evidence Solutions Market Competitive Landscape
Top-tier vendors anchor integrated clinical-commercial data ecosystems, while specialized analytics boutiques occupy niche therapeutic verticals. The market structure reflects consolidation around full-service evidence generation capabilities alongside fragmentation in modular point solutions. Three strategic archetypes dominate: data-integrated platform vendors, oncology-focused specialists, and cloud infrastructure providers. M&A activity targets federated learning capabilities and regional data network access, while strategic partnerships address fragmented EHR interoperability standards.
Within the data-integrated platform tier, IQVIA Inc. and Oracle Corporation exemplify scale-driven positioning through comprehensive evidence generation service bundles. Flatiron Health occupies a specialized position representing oncology-specific real-world data curation archetypes. These three entities collectively illustrate how vendor capabilities align with pharmaceutical sponsor preferences for either enterprise-wide deployment or targeted therapeutic applications.
| Leading Market Players |
|---|
| IQVIA Inc. |
| IBM Corporation |
| Optum Inc. |
| ICON plc |
| Oracle Corporation |
| Syneos Health |
| Parexel International Corporation |
| Flatiron Health |
| Merative |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up evidence generation specialists have consolidated fragmented biostatistical boutiques across the United States and Europe, concentrating pricing power among vendors with integrated FDA submission capabilities while compressing margins for commodity data resellers lacking proprietary network access.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across the real world evidence solutions landscape. Full-service evidence generation contracts incorporating protocol design, biostatistical execution, and regulatory submission support command substantial premiums over modular SaaS platforms offering standardized analytics tools. Price differentiation hinges on ISO 14155 certification tier and the depth of proprietary data network integration. Cost compression in the mid-market SaaS tier is intensifying as venture-backed biotechs scrutinize per-study economics. Pharmaceutical sponsors with enterprise-wide deployments exhibit the lowest price sensitivity, while emerging biotech firms in Cambridge and South San Francisco clusters drive aggressive vendor negotiation.
Supply Chain Analysis
Regional distribution centers for health data aggregation concentrate in the United States, Germany, and the United Kingdom, with academic medical centers serving as primary collection nodes before normalization into analysis-ready formats. Raw data streams draw from EHR systems, claims databases, and wearable device feeds, with FHIR interoperability standards reducing friction in cross-platform transmission. Single-source vulnerability persists around specialized natural language processing engines for multilingual clinical note extraction. Distribution runs through hybrid cloud architectures that satisfy GDPR data residency mandates in European deployments while enabling elastic compute for United States-based pharmaceutical sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where each FDA Real-World Evidence program expansion and EMA DARWIN EU network extension directly expands addressable demand for compliant platform infrastructure.
For Market Incumbents: Lock in federated learning capabilities through exclusive data network partnerships with academic medical centers in Germany and Japan, insulating against cloud-native entrants lacking institutional review board relationships. Prioritize backward integration into proprietary EHR data streams rather than licensing standardized claims datasets where price erosion runs through commoditized resellers. For New Entrants and Emerging Players: Enter via Japan's PMDA RWE guidance compliance gap, where local platform providers remain underdeveloped relative to regulatory solicitation of post-market surveillance data. Target wearable device convergence applications in diabetes and cardiovascular monitoring, deploying API-first architectures that pharmaceutical sponsors can embed within existing evidence workflows without displacement costs. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market biostatistical service firms lacking cloud infrastructure scale but possessing established ISO 14155 protocol libraries and FDA submission track records. The five-to-ten-year viability window favors platforms with demonstrated EMA DARWIN EU technical compatibility. Watch for PMDA guidance expansion beyond post-market surveillance into pre-approval contexts as the signal indicating accelerated Japanese market development.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Deployment | Enables pharmaceutical sponsors to access academic medical center populations without raw data export restrictions. |
| FHIR Interoperability Investment | Reduces EHR integration costs for health systems and accelerates evidence platform deployment timelines. |
| Oncology Data Network Expansion | Captures biomarker discovery demand from immuno-oncology developers seeking treatment-responsive subpopulations. |
| GDPR-Compliant Hybrid Architecture | Opens European pharmaceutical sponsor procurement currently blocked by data residency requirements. |
| Wearable Device Integration | Creates novel efficacy endpoints for diabetes and cardiovascular studies using continuous sensor feeds. |
Research Methodology
Multiple input streams — executive interviews, regulatory filing analysis, and health system procurement database review — were reconciled to construct market estimates for the real world evidence solutions landscape. Primary fieldwork captured perspectives from pharmaceutical evidence generation executives, regulatory affairs leads at biotech firms, hospital informatics officers, payer formulary directors, and biostatistical service providers. Secondary validation drew from FDA Real-World Evidence program documentation, EMA DARWIN EU technical specifications, ClinicalTrials.gov observational study registrations, and ISO 14155 guideline updates. Bottom-up platform deployment counts across identified vendor installations were triangulated against top-down pharmaceutical R&D spending allocations to evidence generation activities.
Data-stream reconciliation across primary and secondary sources informed the analytical framework applied across the projection horizon. Segmentation modeling incorporated solution type, application area, end-user category, and deployment architecture, with regional regulatory cluster treated as an orthogonal dimension. CAGRs were derived from fitted growth curves anchored to documented platform adoption timelines and pharmaceutical sponsor budget allocation surveys. Forecast inputs included FDA submission volume trends for RWE-supported indications and EMA distributed network technical readiness assessments.
The model holds under stable regulatory acceptance trajectories for observational studies; deviation in FDA or EMA guidance stringency would shift pharmaceutical sponsor investment priorities and platform procurement timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
AI Health and Fitness Products Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Global Patient Portal Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Amblyopia Treatment Softwares Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
US Digital Therapeutics Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
VR in Healthcare Market
Digital Health Solutions
Global Preventive Healthcare Technologies and Services Market
Digital Health Solutions
North America Digital Health Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Digital Therapeutics and Wellness Market