
 Healthcare Mobile Application Market | 2026-2036
Healthcare Mobile Application Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Mobile Application Market Intelligence
App store distribution channels is narrowing as platform gatekeepers tighten health claims policies and enforce medical device classification thresholds. Apple Inc. leverages its HealthKit ecosystem to anchor wearable-to-app data pipelines across iOS devices. Samsung Electronics Co., Ltd. competes through Galaxy Watch integration with hospital EHR systems in select markets. Teladoc Health, Inc. sustains enterprise channel control by embedding its software directly into payer and employer benefit portals.
Healthcare mobile applications are software programs running on smartphones and tablets that collect, transmit, or analyze physiological data through embedded sensors, Bluetooth peripherals, or manual user inputs, with primary commercial purpose of enabling remote care delivery, chronic condition self-management, or clinical decision support outside traditional facilities. Telehealth functionality now leads product development investment as synchronous video encounters integrate with asynchronous messaging and prescription workflows. AI-enabled technology segments attract concentrated R&D spending as natural language processing automates symptom triage and clinical documentation, though wearable integration segments show faster user adoption curves among younger demographics tracking fitness and sleep metrics.
FDA digital health pre-certification frameworks and HIPAA security rule enforcement determine market access timelines and liability exposure for developers targeting US healthcare providers. GDPR data portability requirements in Europe impose additional engineering constraints on cross-border patient data architectures. Stakeholders must monitor evolving FDA enforcement discretion boundaries between wellness applications and regulated medical device software.
Market Dynamics
Hospital systems now embed remote patient monitoring into standard care protocols, forcing developers to architect for FDA pre-certification pathways and HIPAA interoperability mandates before commercial release.
Growth Catalysts
- Medicare Reimbursement Expansion:Remote therapeutic monitoring codes in the United States create direct revenue streams for providers deploying chronic disease management platforms.
- Wearable Sensor Miniaturization:Continuous glucose monitors and pulse oximeters transmit clinical-grade data through Bluetooth Low Energy protocols to smartphones.
- AI Triage Automation:Natural language processing engines reduce clinical documentation burden by converting patient-reported symptoms into structured encounter records.
Market Restraints
- Platform Gatekeeper Policies:Apple App Store and Google Play enforce medical device classification thresholds that disqualify wellness apps making diagnostic claims.
- Cross-Border Data Architecture Costs:GDPR portability requirements in Europe impose engineering constraints that fragment product development roadmaps.
- Clinical Validation Burden:FDA enforcement discretion boundaries between wellness applications and regulated software create liability exposure for developers.
Strategic Opportunities
- Geriatric Home Care Integration:Japan's aging population drives demand for fall detection and medication adherence apps linked to municipal health networks.
- Mental Health Platform Convergence:Cognitive behavioral therapy modules merge with asynchronous messaging and prescription management workflows.
- Employer Benefit Channel Embedding:Enterprise software vendors integrate telehealth functionality directly into HR benefit portals bypassing consumer app stores.
Industry Challenges
- Interoperability Engineering Talent Scarcity:Health Level Seven Fast Healthcare Interoperability Resources implementation requires specialized developers commanding premium compensation.
- Legacy EHR Integration Complexity:Hospital information systems built on proprietary architectures resist API connectivity without costly middleware development.
- Clinical Evidence Generation Timelines:Randomized controlled trials for FDA 510(k) clearance extend product launch windows by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Mobile Application Market |
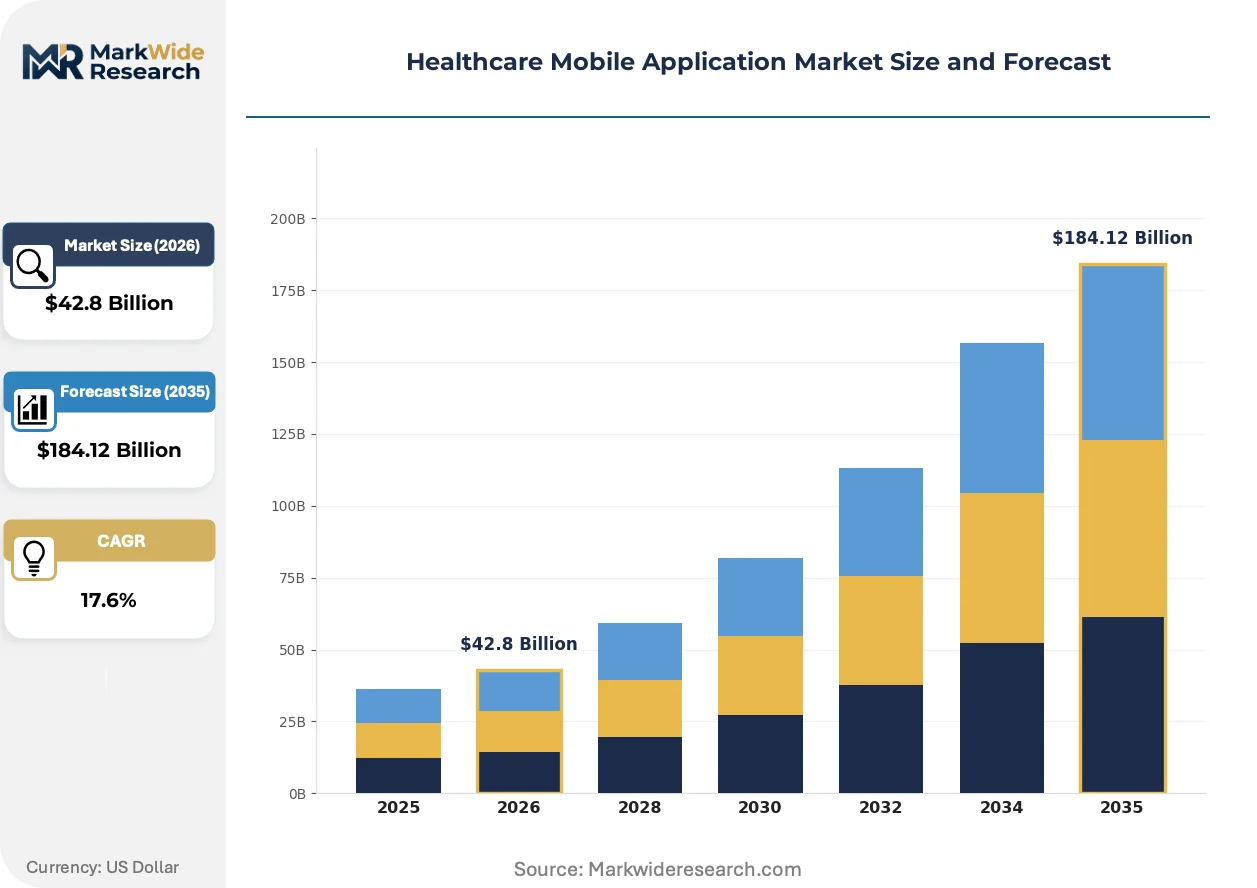
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $184.12 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Tracking, Medication Management, Telehealth, Patient Education End User: Healthcare Professionals, Patients, Caregivers, Wellness Coaches Technology: Cloud-based, On-premises, Wearable Integration, AI-enabled Feature: Data Analytics, User Interface, Security Protocols, Communication Tools |
| Companies Covered | Apple Inc., Fitbit LLC, Samsung Electronics Co., Ltd., Teladoc Health, Inc., MyFitnessPal, Inc., Omada Health, Inc., Philips Healthcare, Epocrates, Inc., Wolters Kluwer N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Mobile Application Market Strategic Shifts & Innovations
Software architectures are pivoting from standalone wellness tracking toward clinical-grade data pipelines that feed directly into provider workflows and payer reimbursement systems.
Edge AI inference on smartphones is rendering obsolete cloud-dependent symptom analysis that introduced latency and privacy risks. Hospital systems in Germany and the United States deploy on-device machine learning models that process physiological signals without transmitting raw data. This architecture compresses infrastructure costs while satisfying data residency requirements.
EU AI Act risk classification rules restructure product development priorities for symptom triage algorithms deployed in member states. High-risk AI systems face conformity assessment obligations that extend time-to-market. Developers targeting European hospital systems now segregate AI functionality to isolate regulated components.
Patient acquisition through employer benefit portals displaces direct-to-consumer marketing that saturated wellness app categories. Large self-insured employers in the United States negotiate exclusive telehealth embeds that lock out competing platforms. This channel consolidation concentrates user bases among enterprise-focused vendors.
Healthcare Mobile Application Market Segmentation
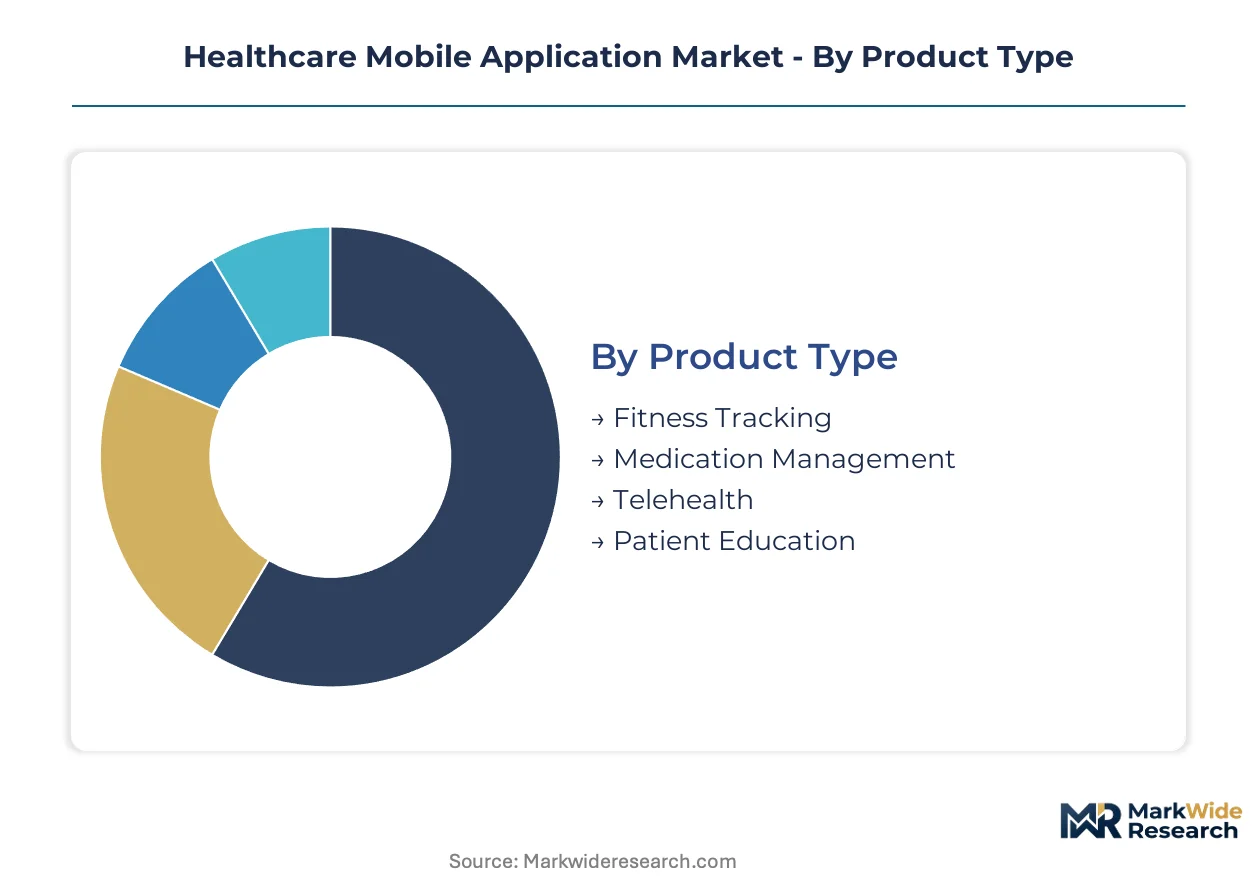
Healthcare mobile applications serve distinct clinical workflows and user capabilities, with each segment demanding specialized regulatory compliance and integration architecture. Product positioning hinges on matching technical sophistication to reimbursement eligibility and end-user digital literacy.
Product Type:
Telehealth platforms anchor provider revenue streams while fitness tracking saturates consumer channels with limited clinical validation.
- Telehealth:Synchronous video encounters integrate with asynchronous messaging and e-prescribing workflows. Hospital systems in the United States deploy these platforms to capture Medicare remote therapeutic monitoring reimbursements, though FDA medical device classification thresholds constrain diagnostic feature expansion.
- Medication Management:Dose scheduling algorithms synchronize with pharmacy fulfillment APIs and caregiver notification systems. Japan's municipal health networks drive adoption for geriatric polypharmacy reduction, where fall detection integration creates bundled home care value propositions.
- Fitness Tracking:Accelerometer and GPS-based activity logging dominates consumer downloads with minimal clinical oversight.
- Patient Education:Structured content modules support chronic condition self-management without diagnostic claims.
Established volume favors Telehealth; emerging adoption favors Medication Management.
End User:
Reimbursement pathways diverge sharply between enterprise-deployed professional tools and direct-to-consumer wellness subscriptions.
- Healthcare Professionals:Clinical decision support and documentation automation reduce administrative burden. EHR integration requirements in Germany and the United States force HL7 FHIR compliance investments that smaller developers cannot sustain.
- Patients:Chronic disease self-monitoring generates the steepest expansion trajectory as continuous glucose monitors and pulse oximeters achieve Bluetooth Low Energy standardization. FDA pre-certification pathways determine whether physiological data feeds directly into provider workflows.
- Caregivers:Proxy access features enable medication adherence oversight for dependent populations.
- Wellness Coaches:Lifestyle guidance platforms operate outside regulated medical device boundaries with limited payer reimbursement.
Enterprise procurement concentrates among Healthcare Professionals; consumer activation concentrates among Patients.
Technology:
Infrastructure deployment models reflect data residency mandates and latency sensitivity for real-time clinical alerts.
- AI-enabled:On-device machine learning inference processes symptom triage without cloud transmission. EU AI Act high-risk system classifications impose conformity assessment obligations that extend European time-to-market for hospital-deployed algorithms.
- Wearable Integration:Continuous physiological monitoring via Bluetooth peripherals anchors remote patient monitoring protocols. Samsung Galaxy Watch and Apple HealthKit ecosystems compete for hospital EHR connectivity in select markets.
- Cloud-based:Centralized data architectures support multi-device synchronization and analytics scale.
- On-premises:Air-gapped deployments satisfy national security requirements for military and government health systems.
AI-enabled architectures command R&D investment; Wearable Integration commands user acquisition spend.
Feature:
Functional module prioritization follows liability exposure gradients and interoperability engineering constraints.
- Security Protocols:HIPAA encryption standards and GDPR data portability requirements impose engineering constraints that fragment product roadmaps. Developers targeting European hospital systems must architect cross-border patient data architectures that satisfy divergent national implementations.
- Data Analytics:Population health dashboards aggregate de-identified cohorts for payers and self-insured employers. Large United States employers negotiate exclusive telehealth embeds that lock competing platforms out of benefit portals.
- User Interface:Accessibility standards and geriatric usability drive design investment for aging demographics.
- Communication Tools:Asynchronous messaging and video APIs integrate with existing clinical workflow platforms.
Compliance spending concentrates on Security Protocols; competitive differentiation concentrates on Data Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors regional demand through Medicare reimbursement codes that monetize remote therapeutic monitoring, while transatlantic data cable infrastructure enables real-time clinical data exchange with European hospital networks.
United States
FDA pre-certification pathways and HIPAA interoperability mandates shape product development timelines for developers targeting hospital systems. Medicare remote therapeutic monitoring codes create direct revenue streams for chronic disease management platforms. Boston and San Francisco metropolitan areas concentrate venture funding for AI-enabled triage automation startups.
Germany
EU AI Act high-risk system classifications impose conformity assessment obligations on symptom triage algorithms deployed in hospital settings. GDPR data portability requirements fragment engineering roadmaps for cross-border patient data architectures. Berlin and Munich health tech clusters drive HL7 FHIR compliance investments for EHR integration.
Japan
METI aging population initiatives accelerate demand for fall detection and medication adherence applications linked to municipal health networks. PMDA digital health guidance determines medical device classification thresholds for diagnostic feature expansion. Tokyo and Osaka metropolitan areas concentrate geriatric home care platform development.
United Kingdom
NHS England remote monitoring procurement frameworks prioritize interoperability with legacy hospital information systems. MHRA software as medical device regulations constrain wellness-to-diagnostic feature migration. London health tech corridor attracts enterprise telehealth vendors embedding into employer benefit portals.
South Korea
MFDS digital health approval pathways enable Samsung Galaxy Watch integration with hospital EHR systems in domestic markets. National health insurance reimbursement for wearable-based chronic disease monitoring accelerates provider adoption. Seoul Digital Healthcare Cluster concentrates Bluetooth Low Energy peripheral standardization R&D.
Healthcare Mobile Application Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying sensor modules and API connectivity. The vendor base clusters around three strategic archetypes: wearable ecosystem owners anchoring hardware-to-app data pipelines, enterprise telehealth vendors embedding through payer channels, and clinical decision support specialists targeting EHR integration. Consolidation pressure intensifies as hospital procurement teams demand end-to-end interoperability certifications. Dominant competitive moves include strategic partnerships with legacy EHR vendors and geographic licensing of FDA-cleared algorithms.
Among wearable ecosystem owners, Apple Inc. and Samsung Electronics Co., Ltd. occupy positions defining platform standards for physiological data transmission. Teladoc Health, Inc. exemplifies the enterprise embed archetype, sitting within payer and employer benefit portal distribution channels that bypass consumer app store gatekeepers. These three companies represent the primary competitive vectors shaping market access and user acquisition economics.
| Leading Market Players |
|---|
| Apple Inc. |
| Fitbit LLC |
| Samsung Electronics Co., Ltd. |
| Teladoc Health, Inc. |
| MyFitnessPal, Inc. |
| Omada Health, Inc. |
| Philips Healthcare |
| Epocrates, Inc. |
| Wolters Kluwer N.V. |
| Others |
Cost & Logistics Intelligence
FDA pre-certification bottlenecks compress margins for developers awaiting 510(k) clearance while simultaneously concentrating supply chain leverage among contract manufacturers with established quality management systems. This regulatory chokepoint widens pricing spreads between clinical-grade platforms and wellness applications, forcing architectural decisions that lock vendors into specific manufacturing partnerships before revenue generation begins.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement, with hospital systems negotiating site-wide licenses that embed per-seat SaaS pricing for clinical decision support modules. Certification-grade differentiation separates FDA-cleared diagnostic features from wellness-tracking subscriptions, with the former commanding 3-4x subscription multiples. Pricing pressure stems from Medicare reimbursement rate compression for remote therapeutic monitoring codes, squeezing vendor margins as providers pass cost accountability upstream. Self-insured employers exhibit lowest price sensitivity due to captive risk pools, while individual wellness subscribers face highest churn from subscription fatigue.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn, Jabil, and Flex holding capacity for Bluetooth Low Energy peripheral assembly in China, Vietnam, and Mexico. Raw material dependencies center on Taiwan-sourced semiconductor foundry capacity for edge AI inference chips, South Korean display panels for wearable integration, and Japanese precision sensors for continuous glucose monitoring. Single-source vulnerability concentrates in TSMC's advanced node allocation for on-device machine learning processors. Distribution runs through hospital GPO contracts, employer benefit portal embeds, and consumer app stores with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HL7 FHIR implementation expertise has become the constraining asset, with fewer than two hundred developers globally capable of architecting EHR-compliant data pipelines. This scarcity elevates acquisition premiums for interoperability specialists and forces strategic choices about build-versus-buy for connectivity infrastructure.
For Market Incumbents: Pre-empt channel consolidation by embedding directly into payer and employer benefit portals before competing platforms lock out distribution access. Acquire HL7 FHIR engineering teams to defend against emerging entrants offering modular interoperability solutions. FDA pre-certification pipeline depth serves as the priority defensive moat against wellness-app upstarts seeking diagnostic feature expansion. For New Entrants and Emerging Players: Pursue geriatric home care integration in Japan's municipal health networks, where METI aging-population initiatives create procurement windows for fall detection and medication adherence bundling. Target mental health platform convergence as the most penetrable white space, merging cognitive behavioral therapy modules with asynchronous prescription workflows. Lead with employer channel embeds rather than consumer app store distribution to bypass platform gatekeeper policies. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors enterprise-focused vendors with established reimbursement pathways over direct-to-consumer wellness platforms. Long-term viability hinges on FDA-cleared algorithm portfolios that sustain provider workflow integration across the care continuum. Watch for CMS remote therapeutic monitoring code expansion as the primary inflection signal for revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Accelerates 510(k) clearance timelines for diagnostic feature modules targeting hospital systems. |
| HL7 FHIR Integration Partnership | Unlocks EHR connectivity with Epic and Cerner deployments across United States health networks. |
| Employer Benefit Portal Embed | Bypasses Apple App Store gatekeeper policies through direct payer channel distribution agreements. |
| EU AI Act Conformity Assessment | Enables high-risk symptom triage deployment in German and French hospital procurement frameworks. |
| Bluetooth Low Energy Peripheral Standardization | Secures Samsung Galaxy Watch and Apple HealthKit ecosystem compatibility for remote monitoring protocols. |
Research Approach
A standing panel of hospital CIOs, biomedical engineers, GPO contracts managers, and digital health product directors provided ongoing calibration against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR conformity assessment registries. Primary interviews with interoperability specialists and payer benefit administrators combined with bottom-up and top-down triangulation across app store analytics and venture funding disclosures.
Scenario-bracketing framed demand projections across the analysis window, modeling telehealth deployment models, patient versus professional end-user segmentation, AI-enabled versus wearable-integrated technology tiers, and regional regulatory cluster variations. CAGRs derived from fitted growth curves anchored to Medicare reimbursement code utilization trajectories and continuous glucose monitor Bluetooth standardization adoption curves.
Sensitivities concentrate around FDA enforcement discretion boundary shifts between wellness and medical device classification, EU AI Act implementation timelines for high-risk algorithm deployments, and Medicare remote therapeutic monitoring reimbursement rate adjustments. Cross-checking against hospital capital expenditure surveys and digital health venture funding databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Patient Case Management Software Market
Digital Health Solutions
US Digital Health Market
Digital Health Solutions
Telepsychiatry Software Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
Mixed Reality in Healthcare Market
Digital Health Solutions
Advanced Clinical Decision Support Platforms Market
Digital Health Solutions
Global Behavioral/Mental Health Software Market
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Artificial Intelligence in Precision Medicine Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Smart Cards in Healthcare Market
Digital Health Solutions
Digital Therapeutics and Wellness Market
Digital Health Solutions
Behavioral Mental Health Care Software Market