
 Middle East and Africa Wireless Healthcare Market | 2026-2036
Middle East and Africa Wireless Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Wireless Healthcare Market Foresight
Subscription-based remote monitoring services is hardening into the core revenue model for wireless healthcare vendors across the Middle East and Africa. Cisco Systems Inc. anchors its regional presence through healthcare-specific network infrastructure that supports real-time patient data transmission in hospital environments. Koninklijke Philips NV leverages its connected care portfolio to sustain installed-base relationships with major health systems in the Gulf states. Qualcomm Technologies Inc. specializes in low-power cellular modem chipsets that enable wearable medical devices to operate reliably across varied network conditions in sub-Saharan Africa.
Wireless healthcare encompasses medical-grade data transmission systems that use radio frequency protocols—typically Bluetooth Low Energy at 2.4 GHz, Wi-Fi 6 at 5 GHz, or licensed cellular bands—to move patient physiological data from point-of-collection sensors to clinical decision platforms without physical tethering. Its primary commercial purpose is to collapse the latency between symptom manifestation and clinical intervention for dispersed or mobility-limited populations. Remote monitoring solutions currently capture the deepest margin pools in this market because recurring device provisioning and data interpretation fees outstrip one-time hardware sales. Telehealth solutions represent the fastest-expanding segment as governments in Saudi Arabia and Egypt build out virtual consultation infrastructure to address physician density gaps.
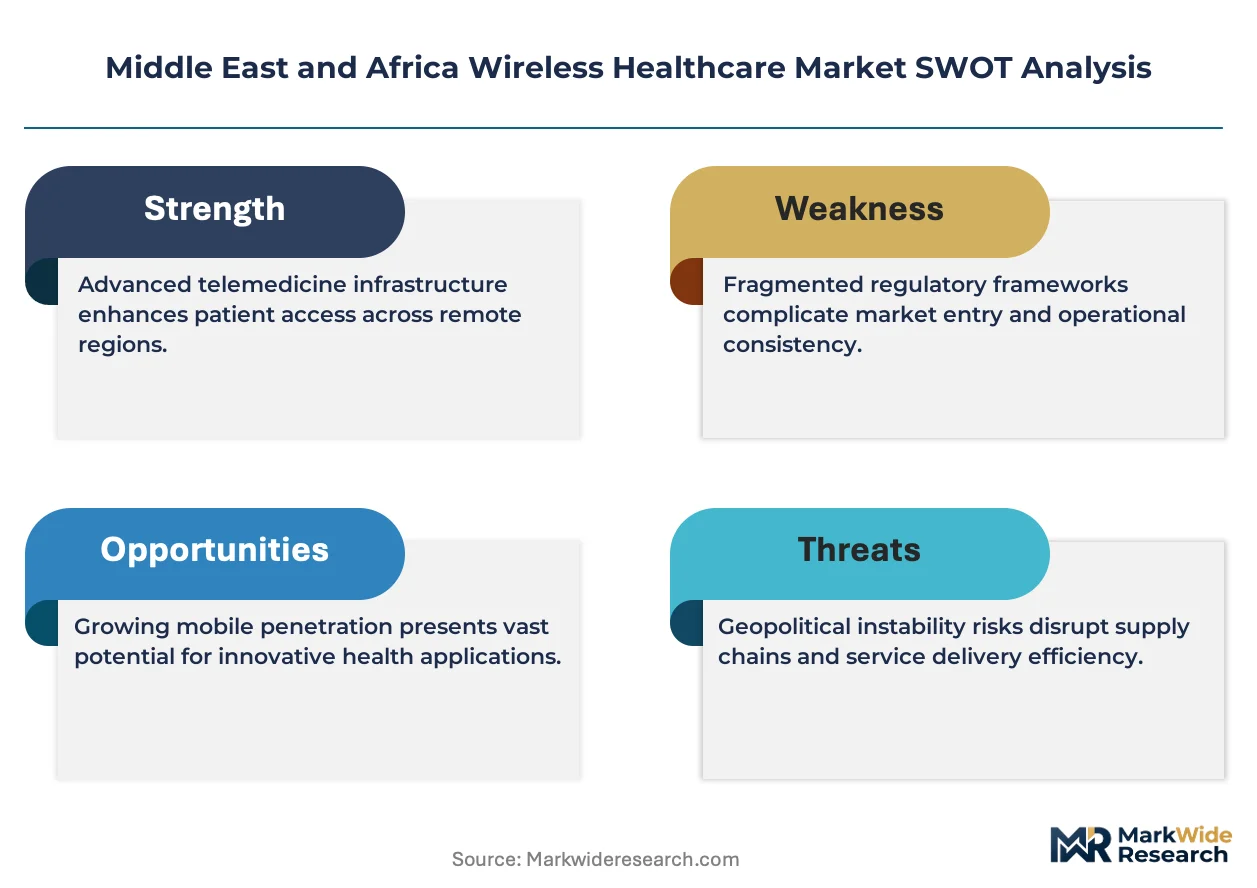
SFDA in Saudi Arabia and the UAE's Ministry of Health and Prevention now mandate encryption standards and data residency requirements for connected medical devices, which shapes vendor product roadmaps and localization investments. South Africa's Health Products Regulatory Authority applies IEC 62304 software lifecycle standards to wireless health applications, creating a compliance threshold that filters smaller developers from hospital procurement channels. Stakeholders must monitor how divergent national cybersecurity frameworks across the Gulf Cooperation Council reshape interoperability requirements for cross-border telehealth platforms.
Market Dynamics
Subscription-based remote monitoring services are hardening into the core revenue model across the Middle East and Africa, collapsing the latency between symptom manifestation and clinical intervention for dispersed populations.
Growth Catalysts
- SFDA Cybersecurity Mandates:Saudi Arabia's new connected medical device guidelines are accelerating compliance investments and procurement of hardened wireless infrastructure by hospital systems.
- Bluetooth Low Energy 5.3:Extended range and lower power consumption are enabling reliable patient data transmission across sub-Saharan Africa's varied network conditions.
- Smart Hospital Procurement:Dubai Health Authority's initiatives are creating concentrated demand for enterprise-grade wireless networks in tertiary care facilities.
Market Restraints
- Cellular Modem Cost Volatility:Semiconductor supply concentration in East Asian foundries creates input cost pressure for wearable device manufacturers serving price-sensitive African markets.
- Data Residency Requirements:UAE and Saudi regulations mandating local data storage increase cloud infrastructure costs for telehealth platform operators.
- Legacy Hospital Infrastructure:South Africa's public health facilities lack compatible network backbone for seamless integration of advanced wireless monitoring systems.
Strategic Opportunities
- Egypt's Virtual Consultation Buildout:Government infrastructure investments to address physician density gaps create first-mover advantage for integrated telehealth platform providers.
- Wi-Fi 6 and 5G Convergence:Hybrid connectivity architectures are enabling seamless handoff between hospital networks and cellular for continuous patient monitoring.
- Homecare Channel Expansion:South African private nursing agencies are adopting direct-to-provider procurement models for connected patient monitoring systems.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Gulf states face acute shortages of technicians qualified to maintain and troubleshoot connected care device fleets.
- IEC 62304 Certification Timelines:South Africa's software lifecycle standards create extended approval delays that filter smaller developers from hospital procurement channels.
- Cross-Border Interoperability Friction:Divergent national cybersecurity frameworks across Gulf Cooperation Council members reshape technical requirements for regional telehealth platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Wireless Healthcare Market |
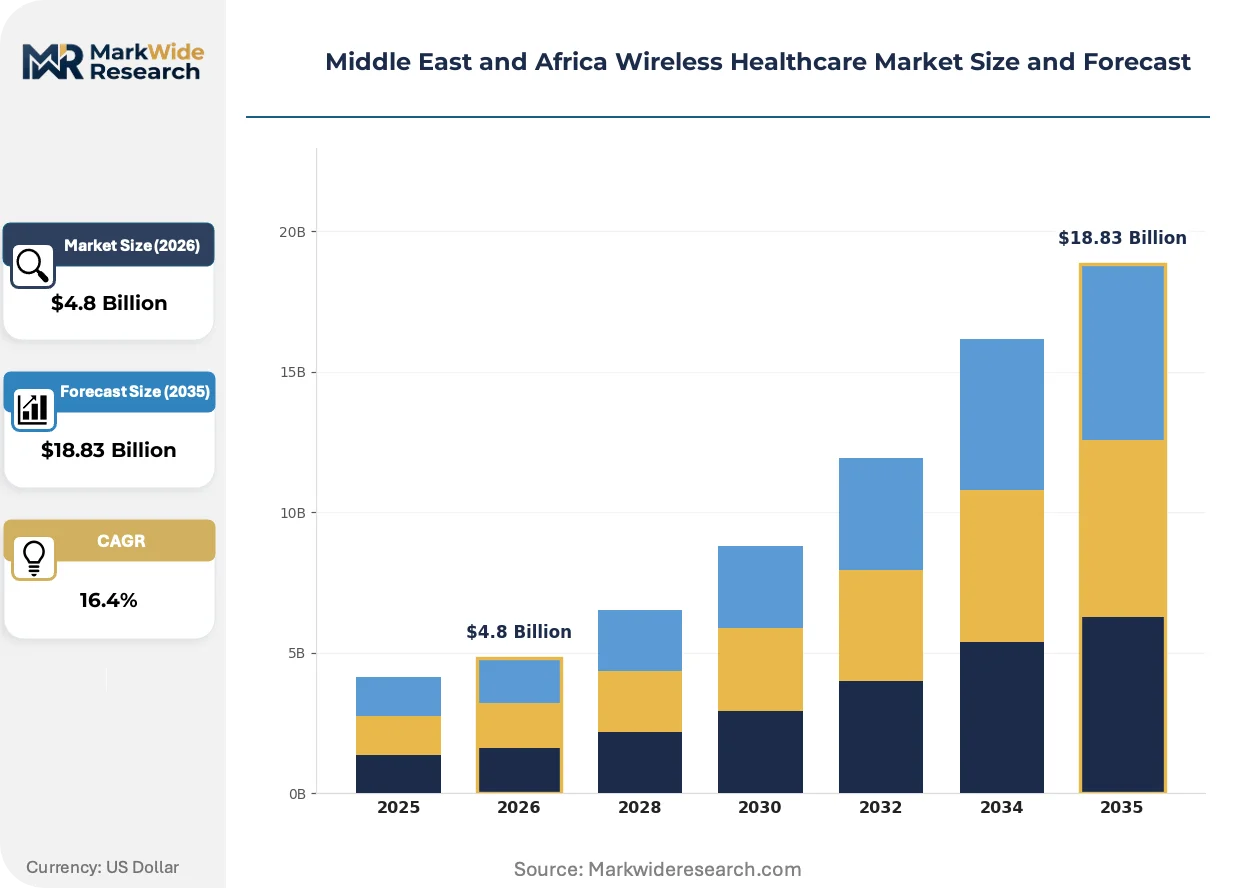
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.83 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Remote Monitoring, Mobile Health Apps, Telehealth Solutions End User: Hospitals, Clinics, Homecare Providers, Patients Technology: Bluetooth, Wi-Fi, Cellular, NFC Application: Chronic Disease Management, Fitness Tracking, Health Monitoring, Medication Adherence |
| Companies Covered | AT&T Inc., Extreme Networks Inc., Cisco Systems Inc., Verizon Communication Inc., Qualcomm Technologies Inc., Motorola Solutions Inc., Koninklijke Philips NV, Apple Inc., Samsung Electronics Co. Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Wireless Healthcare Market Shifts & Advancements
Edge computing architectures and low-power wide-area networks are actively reshaping how patient physiological data moves from point-of-collection sensors to clinical decision platforms across the Middle East and Africa.
Remote patient monitoring hardware is modularizing around interchangeable sensor pods that snap into standardized base units. Homecare providers in South Africa are adopting these platforms at accelerating pace to reduce equipment replacement costs. This architecture is modularizing vendor competitive dynamics by decoupling device hardware from data analytics subscriptions.
SFDA's cybersecurity guidelines for connected medical devices now mandate encryption standards that exceed baseline IEC 62304 requirements. Medical device manufacturers serving Saudi hospital systems must redesign firmware architectures to achieve compliance. Wearable device vendors with pre-certified security stacks are capturing disproportionate procurement share in Riyadh and Jeddah health clusters.
Health system procurement committees in the UAE are unbundling after-sales service contracts from device acquisition agreements. Dubai Health Authority's smart hospital initiatives now specify separate vendor selection for hardware, cloud hosting, and clinical interpretation services. This purchasing pattern shift is most visible in tertiary care facilities where capital expenditure and operational expenditure budgets sit under different governance structures.
Middle East and Africa Wireless Healthcare Market Segmentation
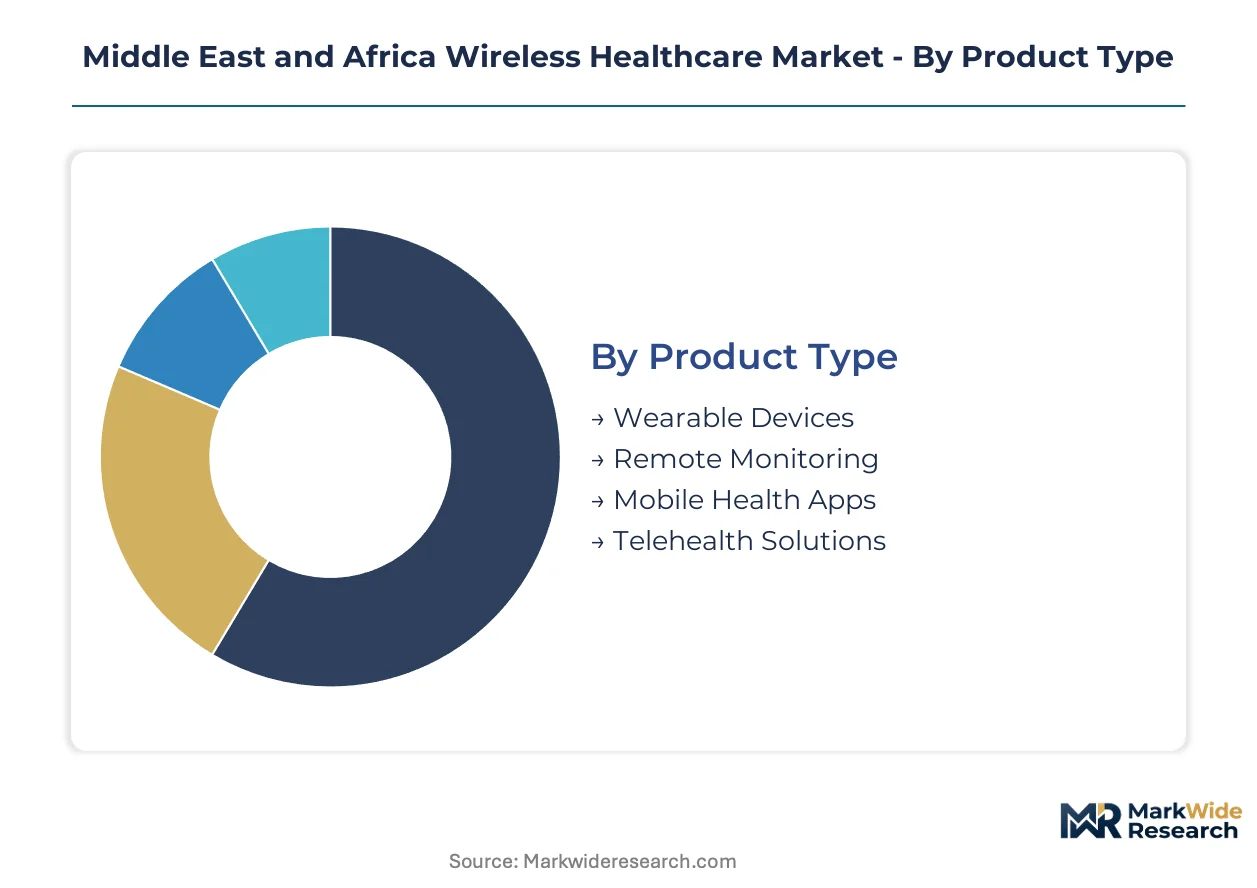
Wireless healthcare procurement across the Middle East and Africa fragments sharply across connectivity protocols, care settings, and patient acuity levels. Vendor positioning depends on matching technical specifications to the infrastructure constraints and reimbursement pathways dominant in each segment cluster.
Product Type:
Hospital procurement committees weight total cost of ownership against interoperability with existing electronic health record systems when selecting product categories.
- Remote Monitoring:Subscription-based platforms combining physiological sensors with cloud-based clinical dashboards dominate hospital procurement in Saudi Arabia and the UAE. Dubai Health Authority's smart hospital specifications prioritize these systems for post-acute care transitions. Recurring revenue streams from data interpretation services sustain vendor margins above hardware-only categories.
- Telehealth Solutions:Virtual consultation infrastructure is expanding fastest in Egypt and Saudi Arabia where government investment addresses physician density gaps. Platform operators must localize for SFDA cybersecurity mandates and UAE data residency requirements to capture institutional procurement.
- Wearable Devices:Patient-facing biometric trackers with Bluetooth Low Energy connectivity serve South African homecare agencies and Gulf state wellness programs.
- Mobile Health Apps:Software-only solutions face IEC 62304 certification barriers in South Africa and fragmented payment models across the region.
Volume sits with remote monitoring platforms; growth tilts toward telehealth solutions.
End User:
Capital expenditure authority and operational technology budgets diverge across institutional buyer types, reshaping vendor sales cycle length and contract structure.
- Hospitals:Tertiary care facilities in the UAE and Saudi Arabia deploy enterprise-grade wireless infrastructure for real-time patient monitoring. SFDA cybersecurity guidelines and MOHAP data residency rules filter vendor eligibility to those with certified security architectures and localized cloud hosting.
- Homecare Providers:South African private nursing agencies are adopting direct-to-provider procurement models for connected patient monitoring systems. Modular sensor pod architectures reduce equipment replacement costs and enable subscription-based service contracts.
- Clinics:Primary care facilities in Egypt and Jordan prioritize low-cost cellular-enabled devices for chronic disease management programs.
- Patients:Direct-to-consumer wearable sales concentrate in Gulf state urban centers with high smartphone penetration and private health spending.
Revenue concentrates with hospital systems; expansion accelerates fastest among homecare providers.
Technology:
Network reliability requirements and power constraints determine protocol selection for device manufacturers serving varied infrastructure maturity across the region.
- Cellular:Licensed band connectivity enables continuous patient monitoring across sub-Saharan Africa's sparse hospital infrastructure. Qualcomm's low-power modem chipsets address battery life constraints for wearable devices operating in areas with intermittent network coverage.
- Bluetooth:Bluetooth Low Energy 5.3 dominates short-range sensor-to-hub communication in hospital environments. Extended range and reduced power consumption support reliable data transmission across Saudi Arabia's expanding smart hospital networks.
- Wi-Fi:Enterprise-grade Wi-Fi 6 installations anchor wireless infrastructure in Dubai Health Authority tertiary facilities.
- NFC:Near-field protocols serve medication adherence and patient identification applications with minimal power requirements.
Deployment scale favors Bluetooth; capability expansion is steepest for cellular.
Application:
Reimbursement pathway maturity and clinical evidence requirements shape which therapeutic use cases attract vendor development investment.
- Chronic Disease Management:Diabetes and cardiovascular monitoring platforms capture sustained procurement from Gulf state health systems with bundled payment models. Remote physiological tracking reduces emergency department utilization for mobility-limited populations across dispersed geographies.
- Health Monitoring:General wellness tracking serves South African homecare agencies and UAE employer wellness programs with less stringent regulatory requirements than diagnostic applications.
- Fitness Tracking:Consumer-grade activity monitoring faces price pressure in African markets and limited reimbursement eligibility.
- Medication Adherence:Smart pill dispensers and dosing reminders target polypharmacy management in aging populations.
Contract value clusters around chronic disease management; penetration depth expands fastest for health monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of wireless healthcare hardware concentrates in East Asian semiconductor foundries, while consumption and service deployment localize across Gulf state hospital systems and sub-Saharan African homecare networks.
Saudi Arabia
Hospital procurement of connected patient monitoring systems is accelerating under SFDA cybersecurity mandates for encryption and data residency. The regulator's new guidelines require firmware architectures that exceed baseline IEC standards, filtering vendor eligibility for Riyadh and Jeddah health clusters. Eastern Province facilities are consolidating wireless infrastructure investments around tertiary care smart hospital specifications.
United Arab Emirates
Dubai Health Authority's smart hospital initiatives are generating concentrated demand for enterprise-grade Wi-Fi 6 and 5G convergence in tertiary facilities. MOHAP data residency requirements mandate localized cloud hosting, reshaping telehealth platform operator cost structures. Procurement committees in Abu Dhabi are unbundling hardware acquisition from clinical interpretation service contracts.
South Africa
Private homecare agencies are adopting direct-to-provider procurement models for modular sensor pod architectures. The Health Products Regulatory Authority applies IEC 62304 software lifecycle standards that filter smaller developers from hospital channels. Cape Town and Johannesburg health systems face legacy infrastructure constraints for seamless wireless monitoring integration.
Egypt
Government virtual consultation infrastructure investments are addressing acute physician density gaps in primary care. National health system procurement prioritizes low-cost cellular-enabled devices for chronic disease management programs. Cairo and Alexandria health clusters are expanding telehealth platform deployment to regional hospital networks.
Middle East and Africa Wireless Healthcare Market Competitive Landscape
Capital-heavy network infrastructure producers compete with asset-light connected care specialists across the Middle East and Africa wireless healthcare market. The vendor base organizes around three strategic archetypes: enterprise networking incumbents supplying hospital-grade wireless backbones, medical device specialists with certified security stacks, and semiconductor designers enabling low-power wearable connectivity. Dominant competitive moves include strategic partnerships with health system procurement committees and geographic localization investments to satisfy data residency mandates.
Among networking infrastructure providers, Cisco Systems Inc. and Extreme Networks Inc. occupy positions anchoring enterprise-grade hospital deployments. Within the connected care tier, Koninklijke Philips NV exemplifies the medical device specialist archetype with recurring service contract models. Qualcomm Technologies Inc. represents the semiconductor design vector, enabling reliable wearable device operation across varied network conditions through low-power cellular modem architectures.
| Leading Market Players |
|---|
| AT&T Inc. |
| Extreme Networks Inc. |
| Cisco Systems Inc. |
| Verizon Communication Inc. |
| Qualcomm Technologies Inc. |
| Motorola Solutions Inc. |
| Koninklijke Philips NV |
| Apple Inc. |
| Samsung Electronics Co. Ltd |
| Others |
Supply & Pricing Matrix
Biomedical engineering talent scarcity in the Gulf states widens pricing-tier spreads between premium-certified and economy-grade wireless healthcare systems, as labor-cost differentials compound with SFDA cybersecurity compliance investments to stratify procurement budgets across hospital systems and homecare networks.
Pricing Analysis
Margin tightening in economy-grade wearable devices reflects cellular modem cost volatility from East Asian semiconductor supply concentration. Pricing stratifies across premium, standard, and economy tiers based on IEC 62304 certification grade and after-sales service bundling. Cost-down pressure on standard-tier remote monitoring platforms accelerates because South African homecare providers are consolidating procurement around direct-to-provider subscription models. Hospital systems in Saudi Arabia and the UAE exhibit lowest price sensitivity due to government-backed smart hospital budgets, while Egyptian primary care clinics face acute budget constraints for telehealth infrastructure.
Supply Chain Analysis
Reverse logistics flows for modular sensor pod refurbishment are emerging as a cost-control mechanism for South African homecare agencies managing equipment replacement cycles. Hardware production concentrates in Taiwan, South Korea, and China, with semiconductor foundries supplying low-power cellular modems and Bluetooth chipsets. Component dependencies include radio frequency transceivers, medical-grade batteries, and encryption-enabled firmware modules. Single-source vulnerability in East Asian semiconductor supply creates exposure for wearable device manufacturers serving price-sensitive sub-Saharan markets. Distribution runs through health system procurement committees in the Gulf states and direct-to-provider channels in South Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with pre-certified security stacks, as SFDA and MOHAP regulatory mandates filter smaller developers from institutional procurement channels.
For Market Incumbents: Acquire specialized cybersecurity certification capabilities to defend hospital procurement share against emerging connected care specialists. Backward integration into localized cloud hosting infrastructure addresses UAE and Saudi data residency requirements. Lock in multi-year service contracts with Dubai Health Authority and Eastern Province health clusters before compliance deadlines harden vendor eligibility. For New Entrants and Emerging Players: SFDA cybersecurity guidelines in Saudi Arabia open a window for pre-certified wearable device vendors to capture disproportionate procurement share in Riyadh and Jeddah. Egypt's government-backed virtual consultation buildout offers the most penetrable geography for integrated telehealth platforms. Target South African homecare agencies with modular sensor pod architectures and subscription-based pricing to bypass legacy hospital infrastructure constraints. For Investors and Strategic Acquirers: Re-rating potential sits with connected care specialists possessing IEC 62304-certified software stacks given accelerating regulatory compliance requirements across the Gulf Cooperation Council. Long-term viability favors vendors with recurring revenue models anchored in remote monitoring subscriptions rather than hardware-only sales. Monitor SFDA enforcement timelines and cross-border interoperability framework harmonization as inflection indicators for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct relationships with Dubai Health Authority procurement committees secure enterprise Wi-Fi 6 and 5G infrastructure deployment slots. |
| Regulatory Certification Pathway | SFDA cybersecurity pre-certification accelerates vendor eligibility for Saudi Arabia's Riyadh and Jeddah health cluster tenders. |
| Software Companion Development | Cloud-based clinical dashboards paired with modular sensor pods enable subscription revenue models for South African homecare networks. |
| Geographic Expansion | Localized cloud hosting investments in the UAE satisfy MOHAP data residency mandates for telehealth platform operators. |
| Strategic Partnership | Collaborations with Qualcomm Technologies anchor low-power cellular modem supply for wearable devices in sub-Saharan Africa. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across hospital procurement managers, biomedical engineers, connected care product managers, and homecare agency operators. Secondary sources included SFDA device registration databases, Dubai Health Authority procurement disclosures, South African Health Products Regulatory Authority certification records, and GPO contract repositories. Bottom-up demand modeling and top-down market sizing were triangulated to validate segment-level estimates.
Data-stream reconciliation across shipment volumes, installed base estimates, and service contract values informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include connectivity protocol, care setting, patient acuity level, and regulatory compliance tier. CAGRs were derived from slope analysis of adoption curves and pricing trajectory assumptions. Forecast inputs incorporated health system capital expenditure cycles and government telehealth infrastructure commitments.
Caveats apply where semiconductor supply disruptions, divergent national cybersecurity frameworks, or reimbursement policy shifts could materially shift the outlook. Practitioners should monitor SFDA enforcement intensity and Gulf Cooperation Council interoperability harmonization progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Global Digital Medicines Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Digital Twins in Healthcare Market
Digital Health Solutions
Global Patient Engagement Solution Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
Amblyopia Treatment Softwares Market
Digital Health Solutions
North America Eclinical Solutions Market
Digital Health Solutions
US Digital Therapeutics Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Global Physical Therapy Software Market
Digital Health Solutions
US Patient Engagement Solutions Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
Telepsychiatry Software Market