
 Asia-Pacific Heart Failure Software Market | 2026-2036
Asia-Pacific Heart Failure Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Heart Failure Software Market Outlook
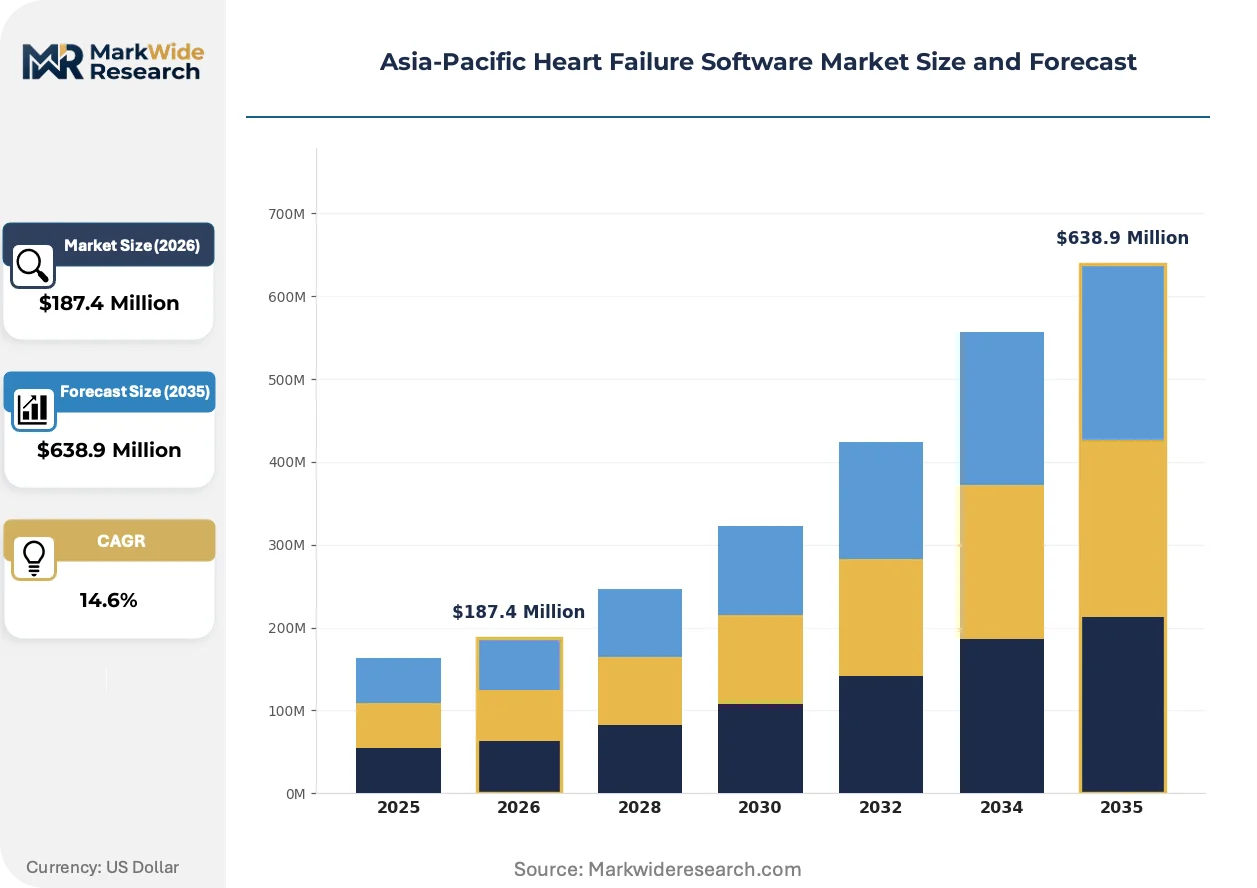
Platform licensing is rewriting margin distribution across the Asia-Pacific heart failure software landscape. Philips Healthcare leverages deep cardiac imaging integration to anchor premium positioning in tertiary hospital networks. Medtronic plc sustains device-to-software connectivity advantages through its implantable cardiac monitor ecosystem. Epic Systems Corporation competes on interoperability depth, occupying strategic share within large Australian and Japanese health systems seeking unified electronic records.
Heart failure software encompasses clinical applications that aggregate, analyze, and visualize patient data to guide therapeutic decisions for reduced and preserved ejection fraction cases, typically processing inputs from implantable sensors, wearable devices, and laboratory information systems to generate risk scores and treatment recommendations. Remote monitoring solutions lead current revenue contribution as hospitals prioritize post-discharge surveillance, while decision support systems represent the fastest-expanding segment where artificial intelligence algorithms parse multi-modal data streams to predict decompensation events. Cloud-based deployment dominates new procurement decisions, though hybrid architectures retain traction among institutions with legacy on-premises infrastructure requiring phased migration paths.
Japan's PMDA digital health guidelines, Australia's TGA software-as-a-medical-device framework, and South Korea's MFDS AI-based medical device approval pathways collectively shape product development priorities and market entry timelines across the region. These regulators impose distinct clinical validation requirements that force vendors to maintain parallel evidence-generation strategies, elevating compliance costs while creating barriers for non-specialized entrants. Stakeholders must monitor evolving interoperability mandates and reimbursement decisions for remote monitoring codes to align platform investments with sustainable revenue models.
Market Dynamics
Japan's PMDA digital health guidelines and Australia's TGA software-as-a-medical-device framework are compressing product registration timelines, forcing vendors to maintain parallel clinical validation strategies across multiple regulatory jurisdictions simultaneously.
Growth Catalysts
- Remote patient monitoring platforms:Cardiology clinics across the region are expanding post-discharge surveillance capabilities, prioritizing cloud-based platforms that integrate with existing electronic health records infrastructure.
- PMDA digital health approval pathways:Japan's streamlined software registration timelines are accelerating market entry for algorithm-driven diagnostic tools, reducing evidence-generation burdens for qualified applicants.
- Tertiary hospital network consolidation:Australia's major health systems are mandating unified decision support integration, creating procurement pull for interoperable heart failure management platforms.
Market Restraints
- Parallel evidence-generation costs:MFDS AI-based medical device requirements in South Korea force vendors to duplicate clinical studies already conducted for PMDA or TGA submissions, elevating compliance expenditures.
- Legacy infrastructure lock-in:Hybrid deployment architectures retain traction among institutions with phased migration paths, slowing pure cloud adoption and extending sales cycles.
- Specialized clinical validation capacity:Shortage of cardiology-specific biostatisticians and regulatory affairs professionals with multi-jurisdiction experience constrains vendor scaling velocity.
Strategic Opportunities
- South Korea's MFDS AI pathway maturation:The regulator's evolving framework for algorithm-based devices creates first-mover advantage for vendors with pre-positioned clinical datasets and local partnership structures.
- Decision support system convergence:Artificial intelligence parsing multi-modal data streams to predict decompensation events represents the fastest-expanding segment, outpacing basic remote monitoring revenue growth.
- Interoperability mandate alignment:Large Australian and Japanese health systems seeking unified electronic records present concentrated demand for platforms with deep integration capabilities.
Industry Challenges
- Multi-jurisdiction regulatory talent scarcity:Vendors struggle to recruit professionals fluent in PMDA, TGA, and MFDS submission requirements simultaneously, forcing reliance on external consultants.
- Legacy electronic health record integration complexity:Phased migration paths for institutions with on-premises infrastructure demand customized implementation support, compressing gross margins on initial deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Heart Failure Software Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Monitoring Solutions, Diagnostic Tools, Patient Management Software, Decision Support Systems Deployment: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, Mobile Applications End User: Hospitals, Cardiology Clinics, Home Healthcare Providers, Research Institutions Integration Level: Standalone Applications, Fully Integrated Systems, Interoperable Platforms, Modular Solutions |
| Companies Covered | Philips Healthcare, Medtronic plc, GE Healthcare, Siemens Healthineers, Epic Systems Corporation, Cerner Corporation, Allscripts Healthcare Solutions, IBM, MicroPort, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Heart Failure Software Market Strategic Shifts
Algorithmic risk stratification is displacing rule-based clinical decision support across Asia-Pacific cardiology workflows. Three developments are compressing traditional software procurement patterns and elevating platform interoperability requirements.
Machine learning inference engines for decompensation prediction are migrating from experimental pilot programs to standard-of-care protocols in tertiary hospital networks. Cardiology departments in Japan and Australia are deploying these tools at scale, replacing static threshold alerts with dynamic patient-specific risk scores. This migration from deterministic to probabilistic clinical logic is compressing competitive differentiation around raw algorithmic performance rather than interface design.
TGA software-as-a-medical-device framework amendments are tightening clinical validation requirements for algorithm updates, treating post-market modifications as new regulatory events. This industrial consequence forces vendors to front-load evidence generation and implement locked algorithm architectures. Australian health systems are responding by prioritizing vendors with established quality management systems and pre-cleared update pathways.
Hospital procurement committees are consolidating vendor relationships around platforms with proven interoperability depth, displacing point solutions with narrow integration capabilities. Cardiology informatics directors in large Japanese and Australian networks are mandating unified data architectures, forcing niche software providers into partnership or exit. This concentration pattern is most visible in Victoria's hospital networks and Kanto region academic medical centers.
Asia-Pacific Heart Failure Software Market Segmentation
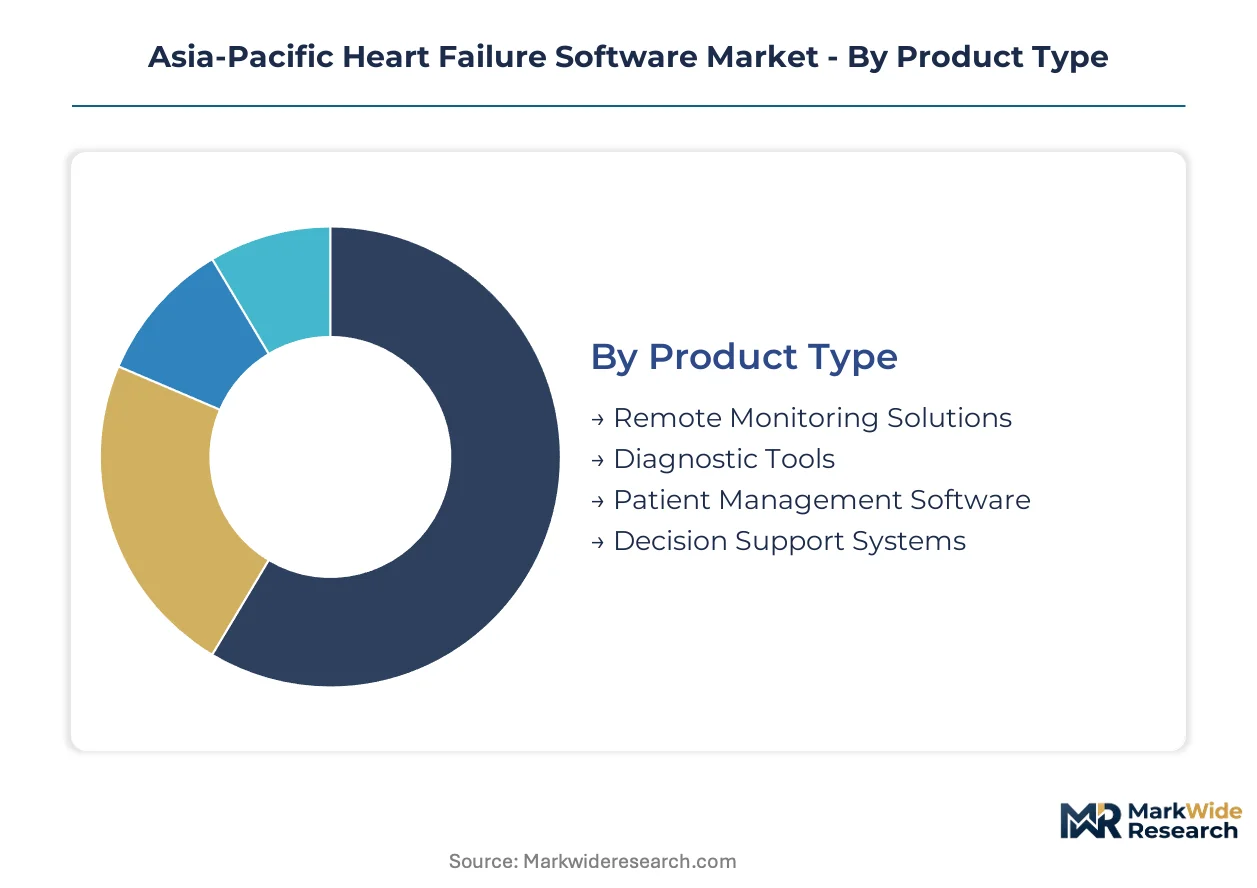
Heart failure software procurement patterns across Asia-Pacific diverge sharply by institutional scale and digital maturity. Vendors must align product architectures with four distinct configuration dimensions to capture share in this fragmented demand landscape.
Product Type:
Mature remote monitoring platforms anchor current revenue, while algorithmic decision support tools represent the emerging frontier where competitive differentiation is compressing fastest.
- Remote Monitoring Solutions:Cloud-native platforms aggregate implantable sensor streams and wearable device outputs for post-discharge surveillance. Australian tertiary hospital networks are mandating these capabilities for heart failure readmission reduction programs, with procurement committees prioritizing EHR integration depth over standalone feature sets.
- Decision Support Systems:Machine learning inference engines parse multi-modal data to generate dynamic decompensation risk scores, displacing static threshold alerts. Japan's PMDA streamlined approval pathways are accelerating clinical validation timelines for these algorithm-driven tools in Kanto region academic medical centers.
- Diagnostic Tools:Echocardiography analysis and biomarker interpretation modules automate ventricular function assessment.
- Patient Management Software:Care coordination platforms track medication adherence and schedule follow-up encounters for chronic heart failure populations.
Remote monitoring solutions handle the majority of throughput; decision support systems are gaining share fastest as probabilistic clinical logic displaces deterministic protocols.
Deployment:
Cost tier stratification separates premium cloud-native offerings from budget-constrained hybrid implementations, with deployment architecture directly constraining gross margin profiles.
- Cloud-Based Solutions:Multi-tenant SaaS architectures with automatic algorithm updates and elastic compute scaling. Cardiology clinics across South Korea are prioritizing these platforms for rapid deployment without capital infrastructure commitments.
- Hybrid Solutions:Split architectures retaining sensitive patient data on-premises while leveraging cloud analytics engines. Australian health systems with legacy Cerner and Epic installations are selecting this model to satisfy phased migration requirements without disrupting existing workflows.
- On-Premises Solutions:Fully captive infrastructure for institutions with stringent data sovereignty requirements.
- Mobile Applications:Patient-facing symptom logging and medication reminder tools with clinician dashboard connectivity.
Cloud-based solutions command the dominant procurement volume; hybrid deployments are expanding most quickly among institutions with substantial legacy infrastructure investments.
End User:
Customer type fragmentation demands parallel sales motions, with hospital procurement cycles stretching 18-24 months while clinic decisions compress to quarterly horizons.
- Hospitals:Enterprise-wide platform deployments spanning emergency departments, cardiology wards, and outpatient clinics. Victoria's hospital networks are consolidating vendor relationships around interoperable systems with proven Epic and Cerner connectivity.
- Cardiology Clinics:Specialized practices requiring streamlined remote monitoring for post-discharge patient surveillance. Japan's clinic chains are adopting cloud-based platforms with PMDA-cleared algorithmic risk stratification to manage expanding heart failure patient panels.
- Home Healthcare Providers:Post-acute care organizations managing transitional care for recently discharged heart failure patients.
- Research Institutions:Academic medical centers generating real-world evidence for regulatory submissions and algorithm training datasets.
Hospitals absorb the largest procurement volume; cardiology clinics are climbing the fastest on deployment velocity as distributed care models expand.
Integration Level:
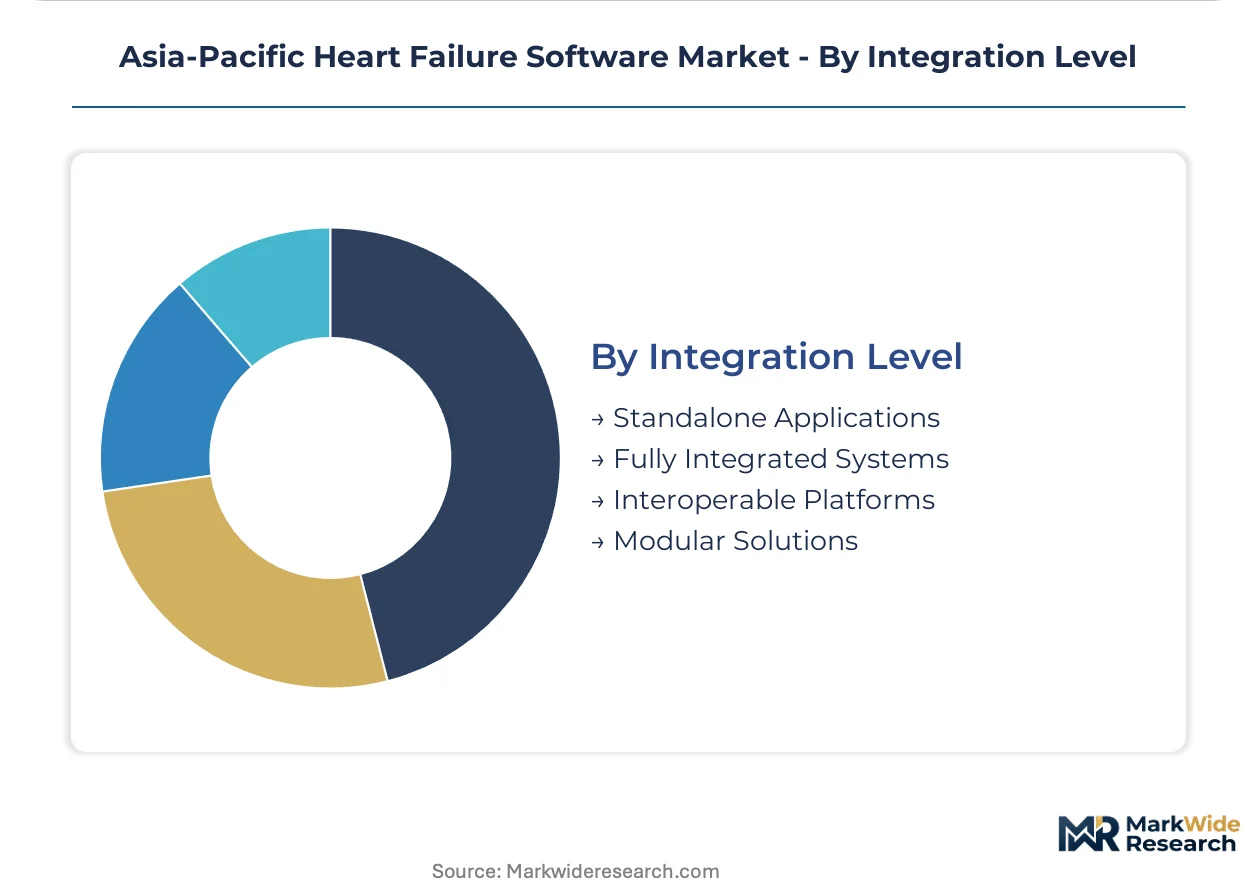
Supply concentration among EHR incumbents is forcing niche software vendors into partnership structures or modular positioning to maintain market access.
- Fully Integrated Systems:Native modules within Epic, Cerner, or Fujitsu EHR architectures with unified data models and single sign-on authentication. Large Japanese health systems in the Kanto and Kansai regions are mandating this configuration to eliminate interface maintenance burdens.
- Interoperable Platforms:Standalone applications with FHIR-compliant APIs and established integration engines for multi-vendor environments. Australian state health departments are standardizing on these platforms to preserve flexibility across heterogeneous hospital IT estates.
- Standalone Applications:Purpose-built tools requiring manual data entry or batch file transfers.
- Modular Solutions:Component-based architectures allowing selective capability activation without full platform commitment.
Interoperable platforms handle the majority of new procurement decisions; fully integrated systems are expanding most quickly as health system consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Asia-Pacific diverge sharply by digital maturity. Japan and Australia deploy algorithmic decision support at scale, while South Korea and emerging Southeast Asian markets concentrate procurement in cloud-based remote monitoring infrastructure.
Japan
Kanto region academic medical centers are standardizing machine learning inference engines for decompensation prediction. PMDA digital health guidelines compress software registration timelines for qualified applicants. Tokyo's hospital networks are consolidating vendor relationships around fully integrated EHR-native modules.
Australia
Victoria's hospital networks mandate interoperable platforms with proven Epic and Cerner connectivity for heart failure readmission reduction programs. TGA software-as-a-medical-device framework amendments treat algorithm updates as new regulatory events. Sydney and Melbourne tertiary centers are prioritizing vendors with established quality management systems.
South Korea
Seoul Capital Area cardiology clinics are adopting cloud-native platforms for rapid deployment without capital infrastructure commitments. MFDS AI-based medical device approval pathways require parallel clinical validation strategies that elevate compliance expenditures. Busan-Ulsan medical centers are generating real-world evidence for algorithm training datasets.
China
Yangtze River Delta tertiary hospitals are piloting remote patient monitoring platforms for post-discharge surveillance of heart failure populations. NMPA medical software registration pathways impose distinct clinical validation requirements for algorithm-driven diagnostic tools. Beijing-Tianjin-Hebei hospital networks are mandating unified data architectures for chronic disease management.
Asia-Pacific Heart Failure Software Market Competitive Environment
Capability concentration sits with specialized cardiac imaging and device connectivity vendors; scale advantage sits with enterprise EHR incumbents with deep interoperability footprints. The market structures around three tiers: implantable device manufacturers with captive software ecosystems, standalone algorithm developers seeking hospital integration, and EHR-native module providers. Dominant competitive moves include strategic partnerships for regulatory pathway acceleration and portfolio diversification into adjacent cardiology informatics segments.
Within the device-to-software ecosystem tier, Philips Healthcare and Medtronic plc occupy positions anchored by deep cardiac imaging integration and implantable cardiac monitor connectivity respectively. Epic Systems Corporation exemplifies the EHR-native archetype, sitting within large Australian and Japanese health systems seeking unified electronic records with single sign-on authentication and unified data models.
| Leading Market Players |
|---|
| Philips Healthcare |
| Medtronic plc |
| GE Healthcare |
| Siemens Healthineers |
| Epic Systems Corporation |
| Cerner Corporation |
| Allscripts Healthcare Solutions |
| IBM |
| MicroPort |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in algorithmic clinical validation capacity across Japan and Australia is forcing vendors to extend delivery timelines and front-load compliance investments, compressing gross margins on initial deployments while elevating pricing power for qualified biostatisticians and regulatory specialists with multi-jurisdiction fluency.
Pricing Analysis
Long-term offtake contracts dominate enterprise procurement in Australian tertiary hospital networks, while Japanese cardiology clinics favor project-based engagements for pilot algorithm deployments. Three-tier pricing structure across premium, standard, and economy levels separates fully integrated EHR-native modules from interoperable platforms and standalone applications. Cost compression in the economy tier is intensifying because South Korean vendors are subsidizing cloud infrastructure to capture clinic market share. Hospital procurement committees exhibit the lowest price sensitivity due to bundled reimbursement codes, while independent cardiology clinics negotiate aggressively on per-seat SaaS rates.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for cloud infrastructure providers serving Australian health systems, straining vendor working capital. Software development capacity concentrates in India, Israel, and the United States, with algorithm training datasets sourced from Japan, Australia, and South Korea. Single-source vulnerability sits with NVIDIA GPU supply for machine learning inference engines. Distribution runs through direct enterprise sales teams for hospital networks and channel partners for clinic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment architectures and integration requirements is creating niche opportunities for specialized vendors as health systems delay unified platform consolidation.
For Market Incumbents: Entrench algorithmic performance advantages by locking clinical validation datasets exclusive to Kanto and Victoria hospital networks. Acquire regulatory affairs boutiques with simultaneous PMDA-TGA-MFDS submission experience to compress competitor entry timelines. Cloud hyperscalers entering healthcare verticals represent the primary substitution threat. For New Entrants and Emerging Players: Southeast Asian markets outside established regulatory frameworks offer the most penetrable geography for cloud-native remote monitoring platforms without legacy EHR integration burdens. Target cardiology clinic chains in Thailand and Vietnam with lightweight FHIR-compliant APIs and localized language support. Pursue distributor partnerships with regional medical device importers rather than direct sales buildout. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among algorithmic decision support vendors with locked update pathways and hospital system sole-source contracts. Long-term viability favors platforms with demonstrated interoperability depth across Epic and Cerner installations. Watch for MFDS approval acceleration as the inflection signal for South Korean market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Digital Health Pathway Positioning | Streamlined registration timelines in Japan accelerate algorithm-driven diagnostic tool market entry. |
| Epic-Cerner Interoperability Certification | Native API integration captures procurement mandates from Australian state health departments. |
| Cloud-Native SaaS Architecture | Elastic compute scaling without capital commitment attracts South Korean cardiology clinic adoption. |
| Algorithm Update Lock Architecture | Pre-cleared modification pathways satisfy TGA software-as-a-medical-device framework amendments. |
| Multi-Jurisdiction Regulatory Partnership | Local clinical evidence generation reduces parallel submission costs across PMDA, TGA, and MFDS. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of PMDA submission databases, TGA software registration records, and hospital procurement contract disclosures. Interviews with cardiology informatics directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads informed demand-side validation. Bottom-up sizing triangulated against top-down health IT spending estimates from national statistical agencies.
Forecast inputs include deployment model adoption curves, EHR integration complexity tiers, and regional regulatory pathway maturation across the projection horizon. Segmentation dimensions encompass product type, deployment architecture, end-user scale, and integration level. CAGRs derive from algorithmic revenue conversion rates and cloud infrastructure cost trajectories specific to healthcare workloads.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud hyperscalers or device manufacturers into software-native positioning would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Mhealth Market
Digital Health Solutions
Global Mhealth Solutions Market
Digital Health Solutions
Global Surgical Preoperative Planning Software Market
Digital Health Solutions
Digital Brain Health Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
Electronic Data Capture Systems Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
Patient Engagement Technology Market
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
Cardiovascular Digital Solutions Market
Digital Health Solutions
Healthcare Navigation Platform Market
Digital Health Solutions
Asia-Pacific Digital Therapeutic (Dtx) Market
Digital Health Solutions
Global Physical Therapy Software Market