
 Digital Healthcare Solutions Market | 2026-2036
Digital Healthcare Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Healthcare Solutions Market Outlook
The capital-intensity divergence between integrated platform providers and point-solution vendors is rotating competitive advantage toward full-stack operators. Koninklijke Philips leverages its imaging hardware heritage to anchor hybrid care deployments across European hospital networks. Medtronic sustains deep device-to-cloud connectivity that differentiates its cardiac remote monitoring from standalone app competitors. Teladoc Health navigates enterprise channel complexity to occupy the virtual-first primary care segment in North American employer markets.
Digital healthcare solutions encompass software platforms, connected medical devices, and data infrastructure that enable remote patient engagement, clinical workflow automation, and real-time health analytics through interoperable APIs and cloud-native architectures. Their primary commercial purpose is reducing cost per episode while extending care access beyond physical facility boundaries. Telehealth platforms currently lead transaction volume as health systems consolidate virtual visit infrastructure post-pandemic, while artificial intelligence segments capture expanding margin pools through FDA-cleared diagnostic algorithms that command premium pricing. Electronic Health Records remain structurally mature with replacement cycles driving modest growth, whereas IoT Devices in remote monitoring represent the fastest-expanding category as payors expand reimbursement for continuous glucose and cardiac telemetry.
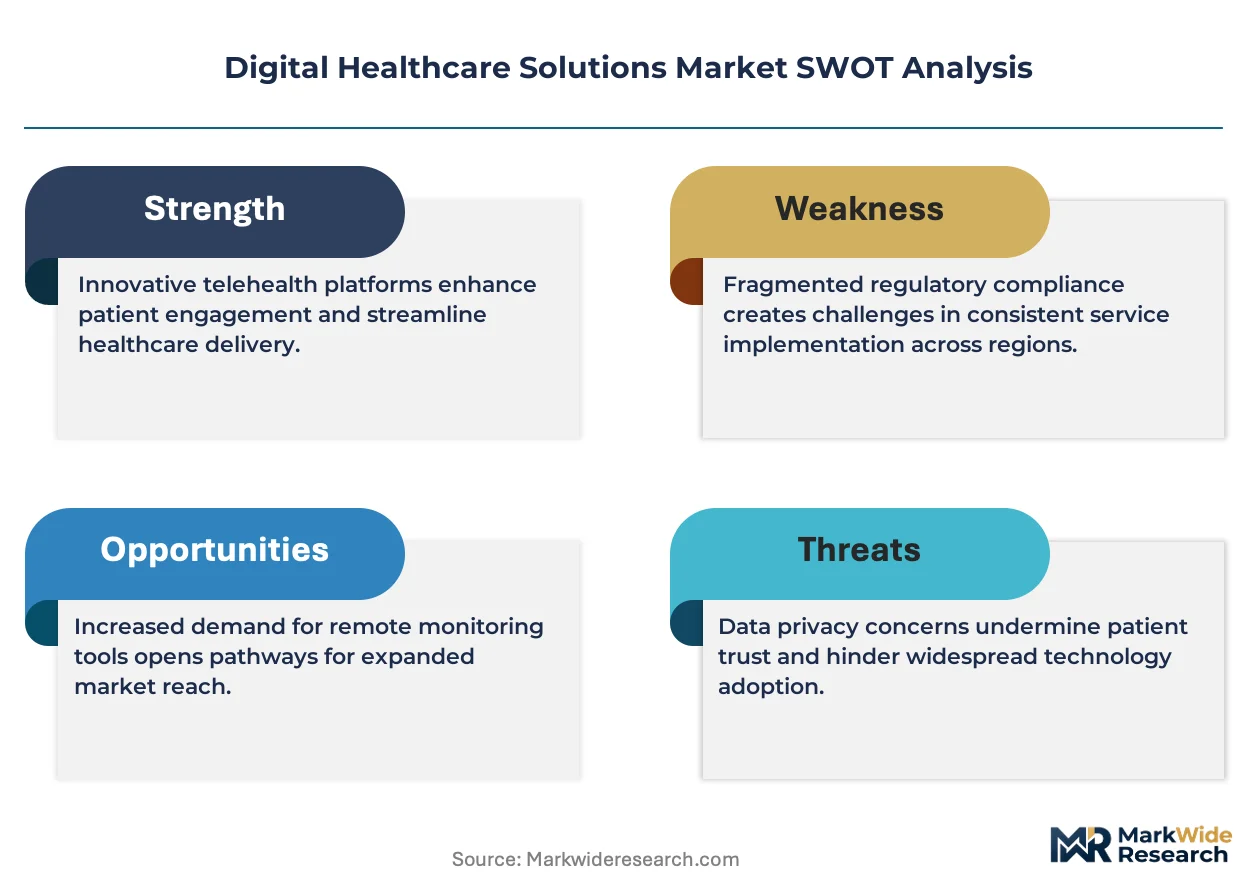
FDA clearance pathways for software-as-medical-device products shape development timelines and capital allocation for AI diagnostic developers, while HIPAA interoperability rules from HHS mandate standardized data exchange that reduces vendor lock-in. EMA's Medical Device Regulation extends conformity requirements to digital therapeutics across EU member states, creating parallel compliance burdens for multi-territory operators. Stakeholders must monitor evolving FDA guidance on adaptive AI algorithms where continuous learning architectures challenge traditional locked-model validation frameworks.
Market Dynamics
The HIPAA interoperability mandates from HHS are forcing hospital systems to dismantle data silos and migrate toward API-first architectures, compressing vendor switching costs and eroding incumbents' lock-in advantages.
Growth Catalysts
- FDA 510(k) Software Pre-Certification:The FDA's streamlined pathway for software-as-medical-device products accelerates commercial timelines for AI diagnostic developers, reducing capital-at-risk during validation phases.
- Remote Patient Monitoring Reimbursement:CMS expansion of CPT codes for continuous cardiac and glucose telemetry reimburses IoT-enabled care models, pulling device manufacturers into recurring revenue streams.
- Cloud-Native Architecture Migration:Hospital IT departments are retiring on-premise EHR infrastructure for Kubernetes-orchestrated platforms, creating replacement demand for interoperability middleware.
Market Restraints
- EMA MDR Conformity Burden:The EU's Medical Device Regulation extends quality management system requirements to digital therapeutics, creating parallel certification costs that deter mid-cap entrants from multi-territory launches.
- Specialized Clinical Data Science Talent:Scarcity of professionals bridging biomedical informatics and machine learning engineering inflates compensation costs for algorithm development teams beyond general software talent benchmarks.
- Legacy EHR Switching Friction:Epic and Cerner installations embed deep workflow customization that raises migration costs for health systems, slowing competitive displacement even where newer platforms offer superior interoperability.
Strategic Opportunities
- Brazil ANVISA Digital Health Fast-Track:Brazil's accelerated certification timeline for software-based medical devices creates first-mover advantage for platforms establishing local clinical validation partnerships ahead of competitors.
- AI-Imaging Convergence:Integration of large language models with radiology workflows enables automated report generation that radiology groups can deploy as productivity multipliers against declining reimbursement rates.
- Direct-to-Employer Virtual Care:Self-insured employers in North America are bypassing traditional payor networks to contract virtual-first primary care directly, opening channel access outside hospital system procurement.
Industry Challenges
- FDA Adaptive Algorithm Validation:Continuous learning architectures challenge traditional locked-model submission frameworks, forcing developers to invest in novel clinical trial designs that satisfy evolving guidance documents.
- Multi-Cloud Integration Complexity:Health systems operating across AWS, Azure, and Google Cloud environments face API inconsistency and data egress cost optimization problems that delay unified analytics deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Healthcare Solutions Market |
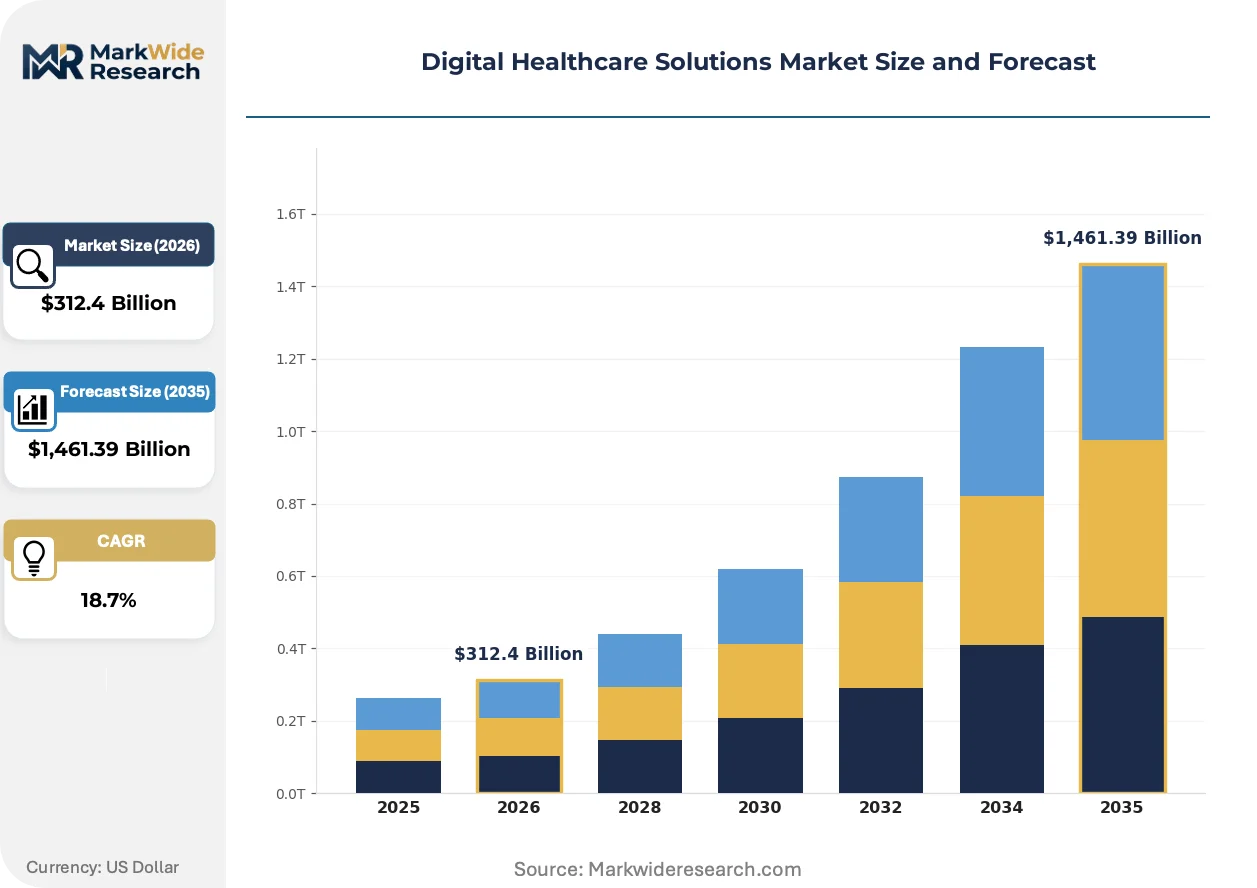
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $1,461.39 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telehealth Platforms, Electronic Health Records, Remote Monitoring Devices, Health Management Apps Technology: Cloud Computing, Artificial Intelligence, Blockchain, IoT Devices End User: Hospitals, Clinics, Homecare Providers, Pharmaceutical Companies Delivery Mode: Mobile Applications, Web Applications, Wearable Technology, Virtual Reality |
| Companies Covered | Koninklijke Philips, Medtronic, GE HealthCare Technologies, Abbott Laboratories, Johnson & Johnson, Siemens Healthineers, Cerner Corporation, Optum, Teladoc Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Healthcare Solutions Market Strategic Shifts
Algorithmic diagnostic tools are compressing the traditional radiologist-pathologist workflow, while regulatory frameworks race to catch up with machine learning deployment velocities that outpace established validation protocols.
Edge computing architectures for continuous patient monitoring is fragmenting the centralized cloud processing model that dominated early remote care deployments. Cardiac implantable electronic device manufacturers are embedding inference capabilities directly on pacemakers and defibrillators, reducing latency for arrhythmia detection while limiting data transmission costs. This shift is fragmenting the revenue concentration among hyperscale cloud providers and redistributing margin toward semiconductor and firmware specialists capable of delivering clinical-grade compute at sub-watt power envelopes.
EMA's Medical Device Regulation Annex XVI expansion captures software-only products previously exempt from conformity assessment, forcing digital therapeutic developers to implement quality management systems equivalent to hardware manufacturers. The industrial consequence is a consolidation of regulatory affairs capabilities among well-capitalized platforms that can sustain notified body audit costs. AI-enabled cognitive behavioral therapy applications targeting EU member states are responding by establishing captive regulatory teams in Germany and the Netherlands rather than outsourcing compliance.
Employer benefit managers are unbundling virtual care from traditional medical plan contracts and contracting directly with telehealth platforms on per-employee-per-month terms. This channel disintermediation strips health systems of their historical role as gatekeepers to covered lives, particularly in technology and professional services sectors where HR departments possess direct purchasing authority. The shift is most visible in California and Texas, where large self-insured employers have deployed vendor panels bypassing incumbent payor networks entirely.
Digital Healthcare Solutions Market Segmentation
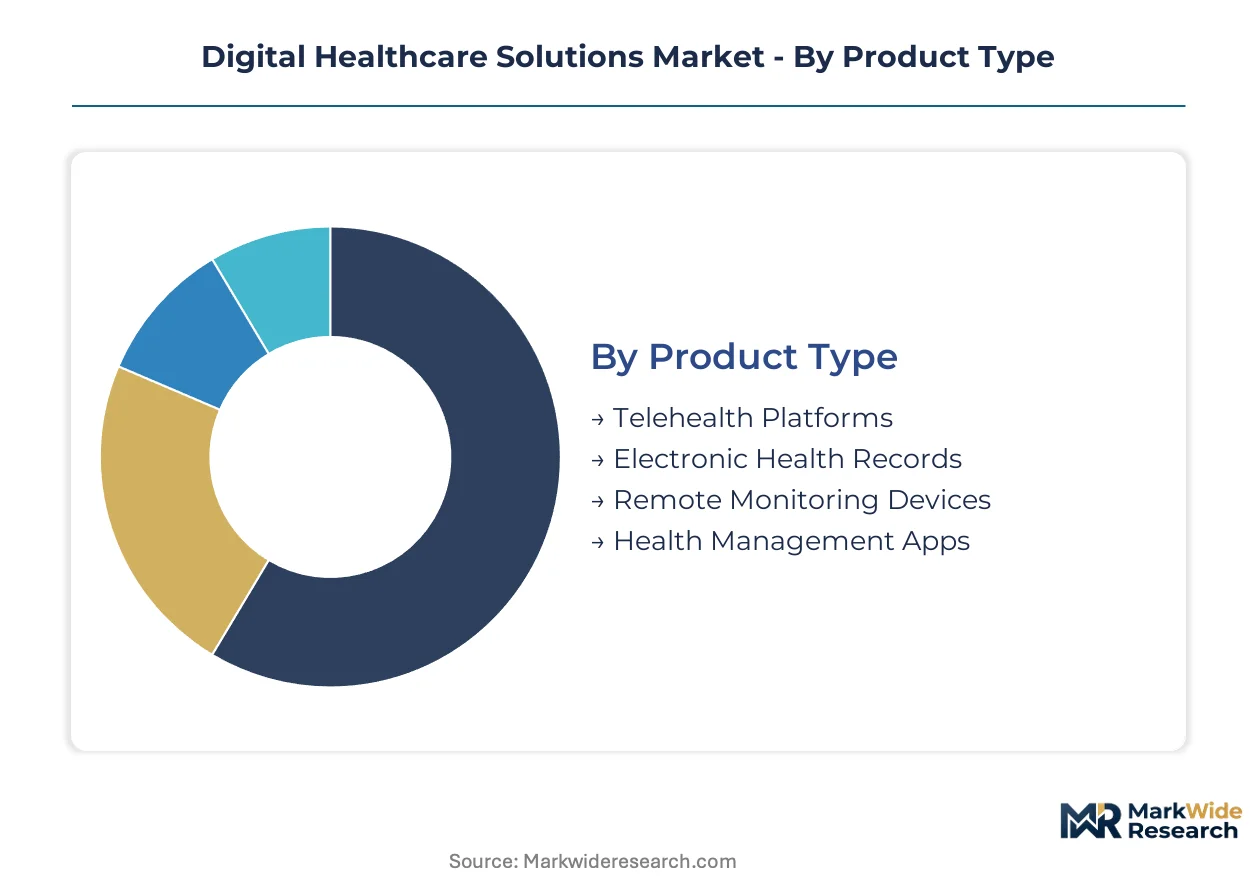
Segmentation in digital healthcare solutions reveals where capital allocation concentrates across divergent technology maturity curves and regulatory exposure profiles. Understanding margin distribution across product architectures, deployment modes, and customer types enables precise positioning against HIPAA interoperability mandates and FDA software certification pathways.
Product Type:
Margin pools concentrate in hardware-software hybrid categories where recurring revenue streams attach to capital equipment deployment.
- Telehealth Platforms:Cloud-native video infrastructure with embedded clinical workflow tools that integrate with existing EHR systems. Demand concentrates in North American employer markets where self-insured corporations contract directly for virtual-first primary care, bypassing traditional payor networks entirely.
- Electronic Health Records:Structured data repositories with interoperability middleware enabling API-first exchange between disparate clinical systems. Hospital systems in the United States face compressed switching costs from HIPAA mandates, though Epic and Cerner installations retain deep workflow customization that slows displacement.
- Remote Monitoring Devices:Continuous telemetry hardware for cardiac and glucose surveillance with embedded cellular connectivity.
- Health Management Apps:Consumer-facing software for medication adherence and chronic condition self-monitoring.
Electronic Health Records holds installed capacity. Remote Monitoring Devices is rotating up the share rankings.
Technology:
Investment intensity varies sharply between commoditized infrastructure layers and proprietary algorithm development where talent scarcity protects margins.
- Cloud Computing:Kubernetes-orchestrated platforms replacing on-premise hospital IT infrastructure with elastic compute and storage resources. United States health systems drive replacement demand as IT departments retire legacy server farms for API-first architectures compliant with HHS interoperability rules.
- Artificial Intelligence:Machine learning models for diagnostic imaging and clinical decision support requiring FDA 510(k) or De Novo clearance. Developers face capital-at-risk during validation phases, though pre-certification pathways accelerate commercial timelines for locked-model algorithms.
- Blockchain:Distributed ledger architectures for pharmaceutical supply chain integrity and credential verification.
- IoT Devices:Sensor networks and edge computing modules for real-time patient data capture.
Cloud Computing anchors current procurement budgets. Artificial Intelligence commands the steepest expansion trajectory as diagnostic algorithms secure reimbursement codes.
End User:
Customer concentration patterns reflect divergent procurement authority and budget cycle timing across institutional settings.
- Hospitals:Integrated delivery networks with capital expenditure authority for enterprise-wide platform deployment. Systems across the United States expand cloud-based infrastructure procurement to satisfy HIPAA data interoperability mandates from HHS.
- Clinics:Ambulatory facilities requiring lightweight, interoperable solutions without dedicated IT staff. Germany's national regulators accelerate digital health certification timelines, pulling mid-size clinic networks toward validated software platforms.
- Homecare Providers:Post-acute and long-term care operators deploying remote monitoring for chronic condition management.
- Pharmaceutical Companies:Drug developers utilizing real-world evidence platforms and decentralized clinical trial infrastructure.
Hospitals retain dominant procurement volume. Homecare Providers is gaining share fastest as CMS expands remote monitoring reimbursement codes.
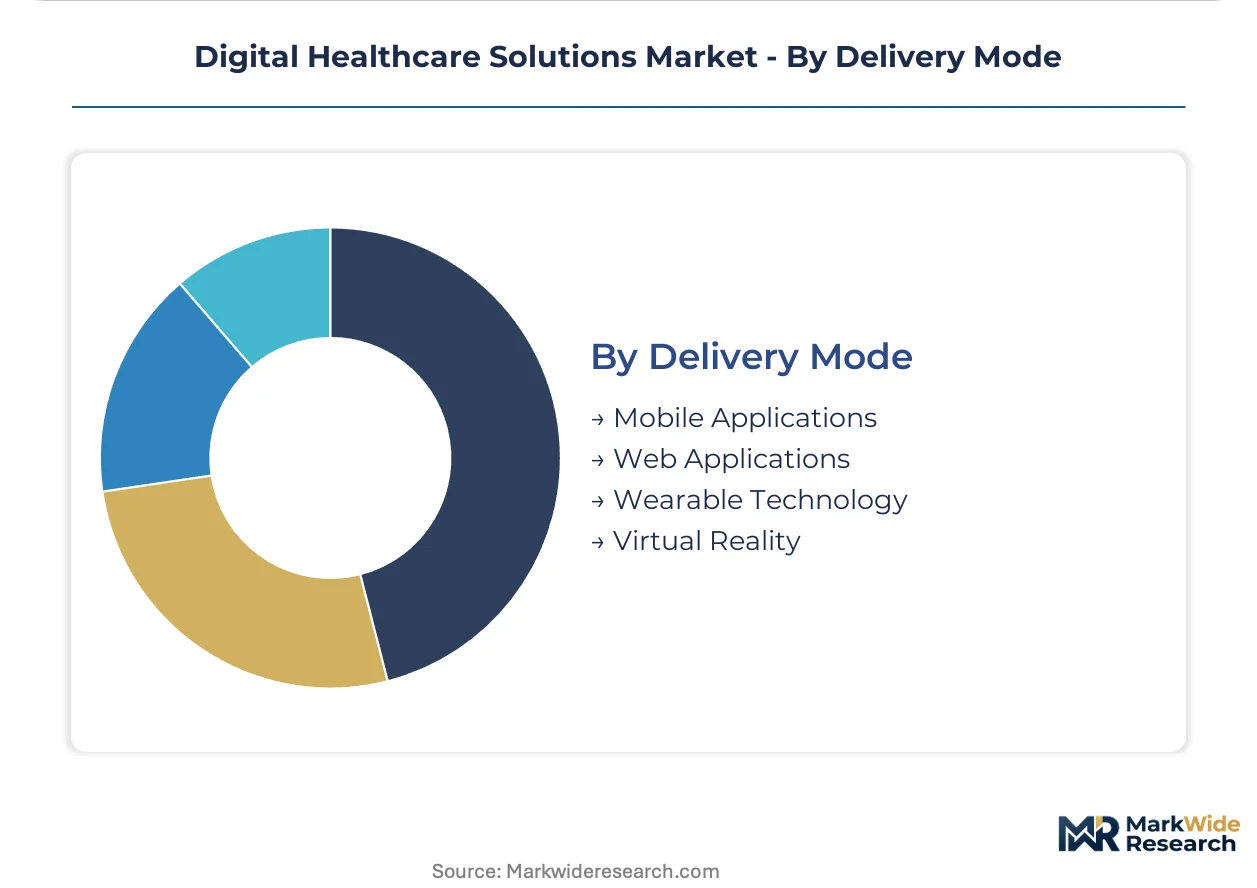
Delivery Mode:
Channel architecture determines customer acquisition economics and retention mechanics across hardware-dependent and software-native deployment models.
- Mobile Applications:Native iOS and Android software distributed through consumer app stores with enterprise licensing overlays. Brazil's ANVISA fast-track certification for software-based medical devices creates first-mover advantage for platforms establishing local clinical validation partnerships.
- Web Applications:Browser-accessible platforms requiring minimal endpoint configuration and enabling rapid enterprise rollout. Japan's regulatory acceleration drives hospital system procurement of cloud-native web interfaces for patient engagement.
- Wearable Technology:Body-worn sensors with embedded compute for continuous physiological monitoring.
- Virtual Reality:Immersive environments for surgical training, pain management, and cognitive behavioral therapy applications.
Web Applications maintains broadest addressable reach. Mobile Applications is climbing the fastest as smartphone penetration saturates clinical and consumer segments alike.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems in the United States deploy cloud-native architectures at scale, while German clinics prioritize regulatory-validated platforms and Brazilian providers exploit accelerated certification timelines for mobile-first solutions.
United States
Self-insured employers in California and Texas contract directly with virtual care platforms, bypassing traditional payor networks entirely. HIPAA interoperability mandates from HHS force hospital IT departments toward API-first data exchange architectures. The Greater Boston cluster anchors FDA pre-certification partnerships for AI diagnostic developers seeking streamlined 510(k) pathways.
Germany
Mid-size clinic networks in Bavaria and North Rhine-Westphalia drive procurement of EMA MDR-compliant digital therapeutics with embedded quality management systems. The country's national pharmaceutical regulator accelerates software-based medical device timelines through notified body streamlining. Berlin-Brandenburg concentrates captive regulatory affairs teams for AI-enabled cognitive behavioral therapy applications targeting EU market access.
Brazil
ANVISA's fast-track certification for software-based medical devices pulls platforms toward São Paulo and Rio de Janeiro for clinical validation partnerships. The national health surveillance agency compresses approval timelines relative to EMA or FDA benchmarks. São Paulo's hospital networks serve as pilot sites for mobile-native chronic disease management tools seeking first-mover positioning.
Japan
METI and PMDA coordination accelerates digital health certification timelines, pulling hospital systems in Tokyo and Osaka toward cloud-native patient engagement platforms. The Kanto region concentrates demand for web-accessible clinical workflow tools with minimal endpoint configuration requirements. Nagoya's medical device manufacturing corridor integrates edge computing modules for cardiac telemetry with embedded cellular connectivity.
United Kingdom
NHS procurement frameworks in London and the Southeast prioritize interoperability middleware for EHR replacement cycles. The Medicines and Healthcare products Regulatory Agency aligns software-as-medical-device pathways with FDA convergence initiatives. The Cambridge-Oxford corridor anchors AI-imaging convergence ventures pairing large language models with radiology workflow automation.
Digital Healthcare Solutions Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with full-stack operators commanding procurement preference over point-solution vendors. The structure rewards hardware-software hybrid models that attach recurring revenue to capital equipment deployment. Three archetypes dominate: imaging heritage platforms extending into hybrid care, device-to-cloud connectivity specialists, and virtual-first primary care purveyors. Competitive displacement proceeds through M&A consolidation of interoperability middleware capabilities and direct-to-employer channel bypass of hospital procurement gatekeepers.
Within the integrated platform tier, Koninklijke Philips and Medtronic exemplify divergent heritage strategies—Dutch imaging hardware anchoring European hospital networks against Irish-American cardiac device-to-cloud connectivity. Teladoc Health occupies a position representing virtual-first primary care channel complexity in North American employer markets. These three sit within a competitive set where regulatory certification velocity and cloud-native architecture migration determine procurement outcomes more than legacy installed base alone.
| Leading Market Players |
|---|
| Koninklijke Philips |
| Medtronic |
| GE HealthCare Technologies |
| Abbott Laboratories |
| Johnson & Johnson |
| Siemens Healthineers |
| Cerner Corporation |
| Optum |
| Teladoc Health |
| Others |
Value Chain & Pricing Dynamics
Cloud-native infrastructure substitution for on-premise hospital data centers simultaneously redistributes supply geography toward hyperscale providers and compresses pricing power among legacy EHR vendors. This displacement reshapes procurement economics as API-first architectures reduce switching costs and fragment vendor lock-in premiums.
Pricing Analysis
After-sales revenue from interoperability middleware and continuous algorithm updates drives lifetime value for platform vendors. SaaS-tiered subscription models dominate, with price differentiation resting on FDA certification tier and customization depth for Epic-embedded workflows. Pricing pressure stems from CMS reimbursement compression pulling cost accountability toward providers. Hospital procurement committees exhibit highest price sensitivity, while self-insured employers demonstrate lowest sensitivity given direct contracting authority.
Supply Chain Analysis
The United States and Germany anchor cloud infrastructure deployment for hospital systems, while Taiwan and South Korea supply edge-compute semiconductors for cardiac telemetry devices. Raw material dependencies center on medical-grade sensors, cellular modems, and clinical-grade aluminum enclosures. Supply chain risk concentrates in single-source vulnerability for FDA-cleared AI training datasets. Distribution runs through GPO contracts and direct-to-employer channels bypassing traditional payor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in interoperability middleware as HIPAA mandates dismantle data silos and create niches for API-first specialists. Employer direct contracting further splinters channel control away from consolidated health systems.
For Market Incumbents: Secure captive regulatory affairs capabilities in Germany and the Netherlands to sustain EMA MDR compliance velocity against mid-cap challengers. Deepen backward integration into edge-compute firmware to capture margin redistribution from hyperscale cloud providers toward semiconductor specialists.
For New Entrants and Emerging Players: Lead with ANVISA fast-track partnerships in São Paulo and Rio de Janeiro to establish clinical validation beachheads ahead of EMA or FDA timelines. Target mobile-native chronic disease management for Brazilian hospital networks with per-employee-per-month employer contracting models.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed virtual care platforms lacking hospital system integration depth. Five-to-ten year viability favors full-stack operators with device-to-cloud connectivity over standalone app competitors. Watch FDA adaptive algorithm guidance evolution as inflection indicator for AI diagnostic developer capital requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software Pre-Certification | Accelerates commercial timelines for AI diagnostic developers seeking locked-model validation pathways. |
| CE Marking Pathway under EMA MDR | Extends quality management requirements to digital therapeutics, consolidating regulatory affairs among well-capitalized platforms. |
| Hospital System Partnership | Secures procurement preference through API-first interoperability middleware embedded in Epic replacement cycles. |
| Software Companion Development | Attaches recurring revenue streams to cardiac implantable devices through embedded telemetry analytics. |
| Reimbursement Strategy | Captures CMS remote monitoring CPT codes for continuous glucose and cardiac telemetry deployment. |
Study Parameters
A spread of perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads converged on the working assumptions. Primary interviews combined with secondary validation from FDA filings, CMS Medicare data, hospital procurement databases, and EMA submission records. Bottom-up and top-down triangulation anchored volume estimates against cloud infrastructure capex disclosures and device shipment tracking.
Segmentation dimensions modeled include product architecture, deployment mode, end-user institution type, and regional regulatory cluster across the analysis window. CAGRs derived from growth driver elasticity modeling against reimbursement expansion trajectories and interoperability mandate compliance timelines. Forecast inputs incorporated hospital IT budget cycles and employer benefit manager contracting velocity.
Forecasts assume regulatory continuity in FDA software-as-medical-device pathways and EMA MDR Annex XVI enforcement; material policy shifts would require re-modeling. Specific risks include adaptive algorithm validation framework evolution and multi-cloud integration complexity delays. Recalibration cycles align with material shifts in reimbursement code expansion and notified body audit capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
North America Virtual Reality (VR) Health Market
Digital Health Solutions
UAE Mhealth Market
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
US Digital Health Market
Digital Health Solutions
Women Digital Health Solutions Market
Digital Health Solutions
GCC E-Health Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
Patient Engagement Platforms Market
Digital Health Solutions
Digital Health Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
Conversational AI in Healthcare Market
Digital Health Solutions
Medical Animation Market