
 US Real World Evidence Solutions Market | 2026-2036
US Real World Evidence Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
US Real World Evidence Solutions Market Intelligence
The capital-intensity divergence between cloud-native analytics platforms and legacy on-premises installations is redrawing competitive boundaries across the sector. IQVIA Holdings Inc. leverages its integrated data ecosystem and global site network to sustain pricing power in pharmacovigilance applications. Flatiron Health Inc. specializes in oncology-specific electronic health record integrations, anchoring its position within academic medical center workflows. Aetion, Inc. competes through regulatory-grade analytics methodologies that satisfy FDA evidentiary standards for supplemental indications.
Real world evidence solutions encompass technologies and services that transform heterogeneous patient data from clinical practice, claims repositories, and wearable devices into structured evidence suitable for regulatory, reimbursement, and clinical decision-making purposes. These systems employ natural language processing engines to extract clinical concepts from unstructured physician notes, applying validated algorithms to generate cohort definitions and comparative effectiveness estimates. Analytics platforms represent the fastest-expanding solution type, as pharmaceutical companies and biotech firms prioritize cloud-based infrastructure that reduces capital expenditure while enabling elastic compute for large-scale distributed research networks. Deployment mode selection increasingly favors hybrid architectures that reconcile on-premises data governance requirements with SaaS scalability, particularly among contract research organizations managing multi-sponsor studies across jurisdictions with divergent privacy constraints.
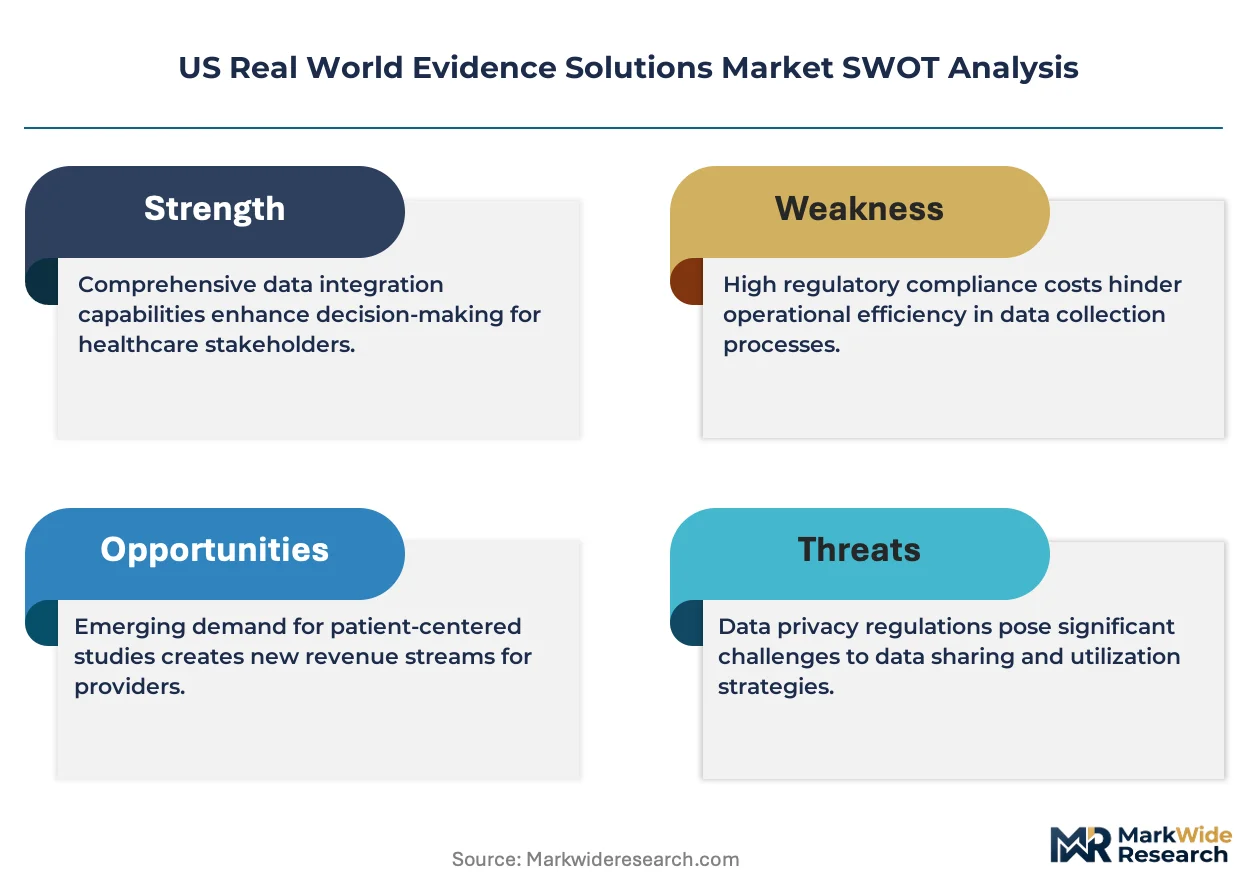
FDA guidance on real-world data quality and the ONC Cures Act interoperability rules are tightening data provenance and exchange standards, compelling vendors to invest in FHIR-compliant infrastructure and audit-grade lineage documentation. HIPAA provisions governing de-identification methodologies and state-level privacy statutes, notably the California Consumer Privacy Act, create fragmented compliance obligations that shape product architecture and geographic service delivery models. Stakeholders must monitor evolving FDA positioning on randomized controlled trial substitution and CMS reimbursement determinations tied to real-world performance benchmarks.
Market Dynamics
FDA's 21st Century Cures Act framework and ONC interoperability mandates are compressing data provenance timelines while forcing platform vendors to rebuild infrastructure around FHIR standards and audit-grade lineage documentation.
Growth Catalysts
- Regulatory-grade evidence pathways:FDA guidance on real-world data quality creates formal channels for supplemental indication submissions, compelling pharmaceutical sponsors to invest in validated analytics infrastructure.
- Oncology data network effects:Academic medical centers in Boston and New York City are deploying integrated EHR-to-research pipelines that attract biotech firms seeking rapid patient cohort identification.
- Cloud-native infrastructure elasticity:SaaS deployment models reduce capital expenditure barriers for mid-tier contract research organizations managing multi-sponsor distributed research networks.
Market Restraints
- State-level privacy fragmentation:California Consumer Privacy Act and divergent state statutes create compliance architecture complexity that inflates product development costs.
- De-identification methodology uncertainty:HIPAA safe harbor versus expert determination standards generate legal exposure that slows cross-institutional data sharing agreements.
- Legacy system integration drag:On-premises data governance requirements at established health systems impede hybrid cloud migration timelines and compress vendor margins.
Strategic Opportunities
- Wearable-derived endpoint expansion:Continuous glucose monitors and cardiac sensors enable novel digital biomarker development for decentralized clinical trial designs.
- Mid-Atlantic corridor penetration:Philadelphia and Baltimore academic medical centers remain underdeveloped relative to Boston and New York City density, offering first-mover platform deployment potential.
- CMS reimbursement linkage:Medicare coverage determinations tied to real-world performance benchmarks create demand for outcomes analytics among medical device manufacturers.
Industry Challenges
- Natural language processing specialist scarcity:Clinical concept extraction from unstructured physician notes requires dual expertise in computational linguistics and medical ontologies that commands premium compensation.
- FHIR implementation heterogeneity:Variable EHR vendor adoption of interoperability standards forces costly custom interface development for each health system integration.
- Cohort definition standardization delays:Lack of consensus algorithms for comorbidity adjustment across therapeutic areas fragments evidence comparability and regulatory acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Real World Evidence Solutions Market |
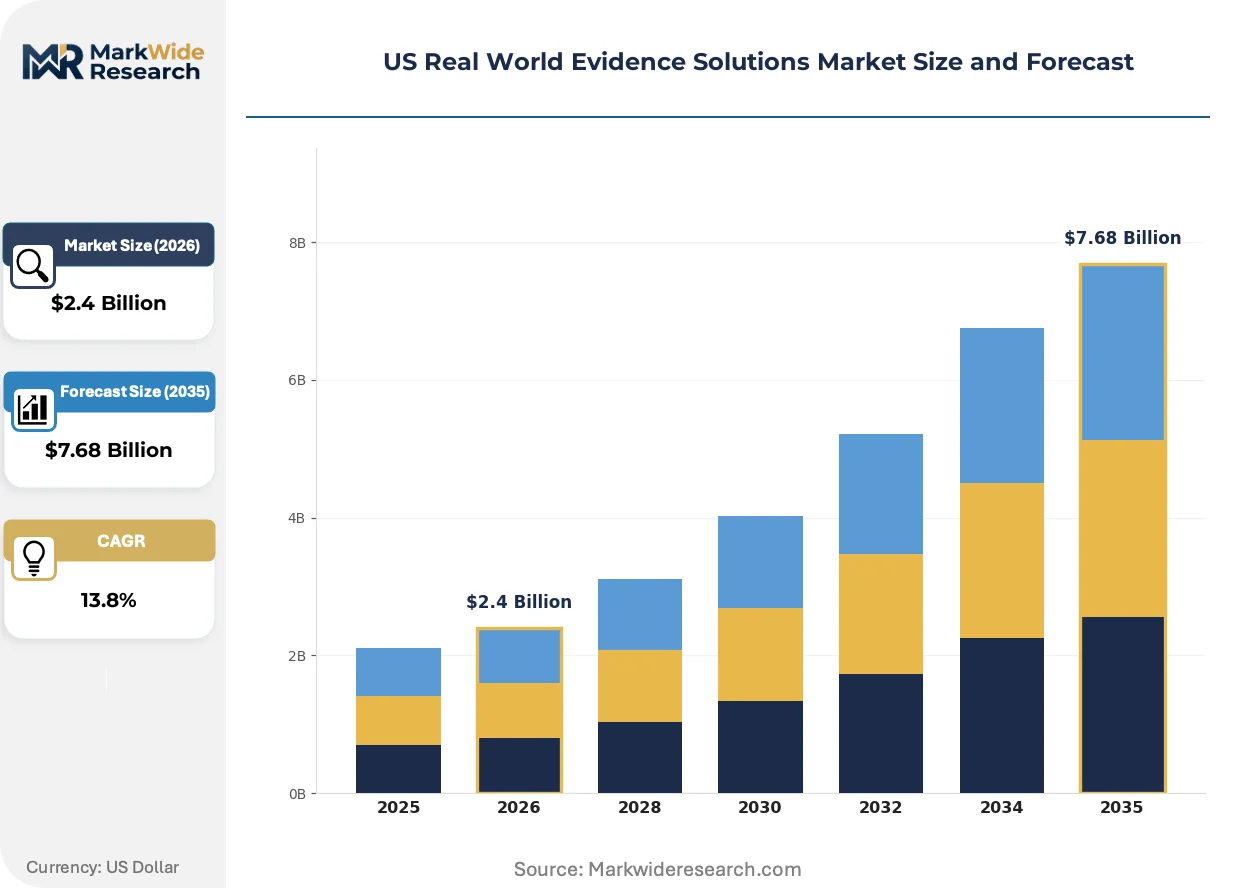
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.68 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Aggregation, Analytics Platforms, Visualization Tools, Electronic Data Capture, Natural Language Processing Application: Pharmacovigilance, Market Access, Patient Outcomes, Drug Safety, Regulatory Submissions End User: Pharmaceutical Companies, Contract Research Organizations, Payers, Biotech Firms, Academic Institutions Deployment Mode: Cloud-Based, On-Premises, Hybrid Models, SaaS, Managed Services |
| Companies Covered | IQVIA Holdings Inc., UnitedHealth Group, IBM Corporation, Flatiron Health Inc., Syneos Health Inc., ICON plc, Parexel International Corporation, Optum Inc., Aetion, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Real World Evidence Solutions Market Strategic Shifts & Innovations
Natural language processing engines are compressing evidence generation timelines by extracting structured clinical concepts directly from unstructured physician documentation at scale.
Federated learning architectures are displacing centralized data repository models as pharmaceutical sponsors seek to train algorithms across distributed health system networks without raw data transfer. Biostatistics teams at large-cap sponsors are piloting these approaches for pharmacovigilance signal detection. The structural consequence is reduced reliance on third-party data aggregators and compressed contracting cycles for multi-site studies.
ONC Cures Act information blocking provisions are mandating patient-directed data export capabilities that force EHR vendors to expose standardized APIs. Health information technology departments must now support automated clinical data feeds to external research platforms. Contract research organizations with pre-built FHIR connectors capture sponsor preference in competitive bidding processes.
Biotech procurement teams are unbundling full-service real-world evidence contracts into modular components separating data licensing, analytics execution, and regulatory submission support. Large pharmaceutical sponsors retain in-house biostatistics capabilities while outsourcing data curation to specialized vendors. This pattern concentrates most visibly among venture-backed oncology developers in the San Francisco Bay Area seeking milestone-driven expenditure control.
US Real World Evidence Solutions Market Segmentation
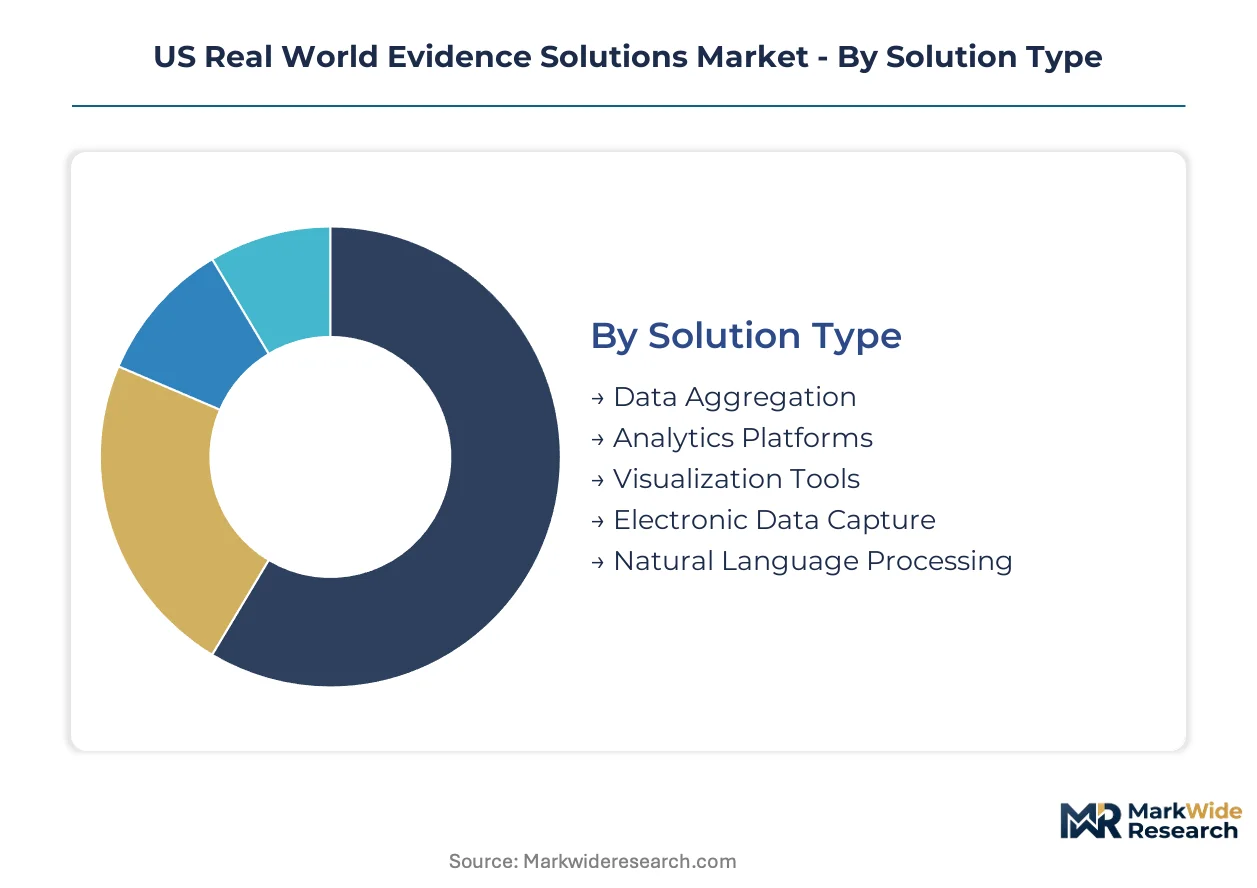
Segmentation reveals how RWE solution providers allocate engineering resources across divergent compliance architectures and customer sophistication levels. Procurement patterns differ sharply between cloud-native biotech startups and legacy-bound academic medical centers.
Solution Type:
Analytics Platforms face the strongest substitution pressure from federated learning architectures that eliminate centralized data aggregation entirely.
- Analytics Platforms:Cloud-native infrastructure delivering elastic compute for distributed research networks. Demand concentrates among mid-tier contract research organizations managing multi-sponsor studies across HIPAA-constrained jurisdictions. FDA evidentiary standards for supplemental indications drive validation investments.
- Natural Language Processing:Clinical concept extraction engines processing unstructured physician notes into structured cohort definitions. Boston and New York City academic medical centers deploy these for rapid patient identification in oncology pipelines. Specialist scarcity in computational linguistics constrains vendor scaling.
- Data Aggregation:FHIR-compliant data harmonization from claims repositories and EHR systems.
- Visualization Tools:Regulatory-grade dashboards for payer and FDA stakeholder communication.
- Electronic Data Capture:Source data verification systems for decentralized trial designs.
Analytics Platforms retain volume leadership; Natural Language Processing holds the steepest expansion curve.
Application:
Cost tier stratification separates enterprise-grade pharmacovigilance suites from modular patient outcomes tools.
- Regulatory Submissions:FDA 21st Century Cures Act-compliant evidence packages for supplemental indication approvals. Large pharmaceutical sponsors in the Northeast corridor prioritize these for lifecycle management. ONC interoperability mandates tighten data provenance requirements.
- Pharmacovigilance:Post-market safety signal detection across distributed health system networks. FDA guidance on real-world data quality compels infrastructure investment. Signal detection algorithms face validation bottlenecks.
- Market Access:Payer negotiation support through real-world performance benchmarks.
- Patient Outcomes:Decentralized trial endpoint collection via wearable integration.
- Drug Safety:Adverse event surveillance combining claims and EHR data streams.
Pharmacovigilance commands premium pricing; Regulatory Submissions is climbing the fastest as FDA acceptance widens.
End User:
Customer type determines deployment complexity, with biotech firms demanding milestone-driven modularity against pharmaceutical enterprise integration.
- Pharmaceutical Companies:Full-stack RWE programs spanning data licensing through submission support. In-house biostatistics capabilities retained at large-cap sponsors. Procurement unbundling concentrates among San Francisco Bay Area oncology developers.
- Contract Research Organizations:Multi-sponsor study management requiring hybrid cloud governance. SaaS elasticity reduces capital expenditure barriers for mid-tier players. State-level privacy fragmentation inflates compliance architecture costs.
- Biotech Firms:Venture-backed developers seeking rapid evidence generation for funding milestones.
- Payers:Medicare coverage determination analytics tied to CMS reimbursement benchmarks.
- Academic Institutions:EHR-to-research pipelines attracting industry sponsorship in Boston and New York City.
Pharmaceutical Companies retain volume leadership; Contract Research Organizations show the steepest expansion curve.
Deployment Mode:
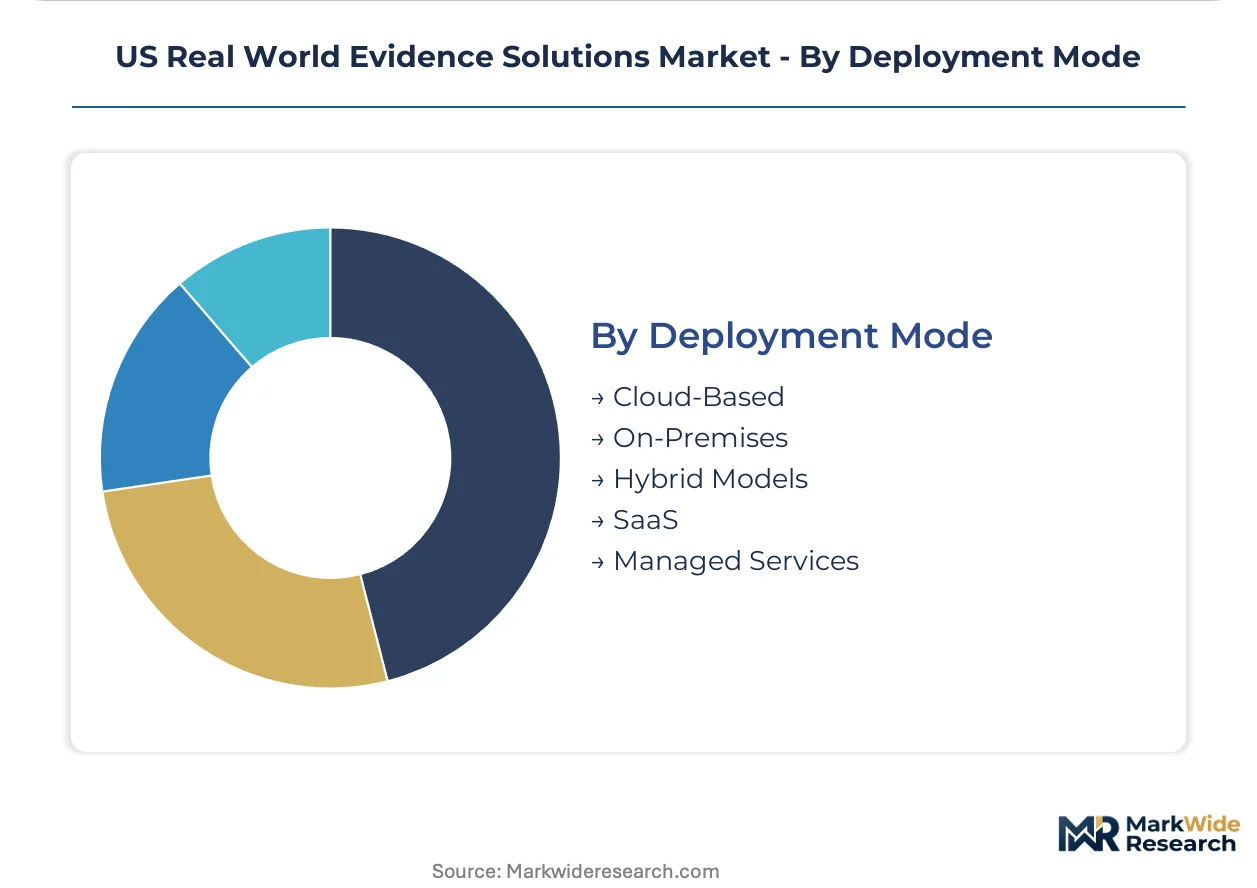
Geography within the US constrains architecture selection, with California and Massachusetts privacy statutes forcing hybrid configurations.
- Cloud-Based:SaaS delivery eliminating on-premises capital expenditure. Elastic compute supports large-scale distributed research networks. HIPAA de-identification methodology uncertainty generates legal exposure.
- Hybrid Models:Reconciliation of on-premises data governance with SaaS scalability. Contract research organizations managing multi-sponsor studies across divergent state privacy constraints prefer this architecture. Legacy system integration drag compresses vendor margins.
- On-Premises:Established health systems with entrenched data governance requirements.
- SaaS:Subscription analytics reducing upfront infrastructure commitment.
- Managed Services:Outsourced data curation and regulatory submission support.
Hybrid Models retain volume leadership; Cloud-Based deployment is expanding most quickly among venture-backed entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in real-world evidence solutions remain domestically contained, with minimal cross-border service exports due to HIPAA constraints and FDA jurisdiction specificity. Platform vendors generate revenue primarily through US-based pharmaceutical contracts and academic medical center partnerships. Data localization requirements under state privacy statutes reinforce this insularity.
Northeast Corridor
Pharmaceutical sponsors in Boston and New York City drive platform deployment for oncology pipeline acceleration. Massachusetts and New York state privacy statutes mandate hybrid cloud architectures for patient data processing. The Longwood Medical Area and Manhattan biotech clusters anchor dense vendor service networks.
Mid-Atlantic
Philadelphia and Baltimore academic medical centers present underdeveloped deployment potential relative to northern density. Pennsylvania and Maryland interoperability initiatives lag ONC Cures Act implementation timelines. The University of Pennsylvania Health System and Johns Hopkins Medicine attract expanding CRO presence.
California
Venture-backed oncology developers in San Francisco and San Diego unbundle RWE contracts into milestone-driven modules. The California Consumer Privacy Act imposes stringent de-identification standards that inflate compliance costs. Silicon Valley cloud infrastructure providers enable elastic compute for distributed research networks.
Texas
Houston and Dallas medical centers build EHR-to-research pipelines for cardiovascular and oncology trials. Texas lacks comprehensive state privacy legislation, reducing compliance architecture complexity for multi-site studies. The Texas Medical Center hosts growing contract research organization satellite operations.
Midwest
Chicago and Minneapolis health systems pilot federated learning architectures for pharmacovigilance signal detection. Illinois and Minnesota interoperability exchanges face FHIR implementation heterogeneity across Epic and Cerner installations. The Mayo Clinic anchors Minnesota's clinical data network development.
US Real World Evidence Solutions Market Key Industry Players
Concentration sits with integrated data aggregators possessing global site networks and regulatory submission expertise. The vendor base stratifies across three tiers: full-stack platform providers, specialized oncology data integrators, and modular analytics boutiques. Consolidation pressure intensifies as pharmaceutical sponsors reduce vendor counts. Strategic moves center on FHIR-compliant infrastructure acquisitions and federated learning capability builds.
Within the integrated platform tier, IQVIA Holdings Inc. and UnitedHealth Group exemplify scale-driven data ecosystem control. Flatiron Health Inc. occupies a specialist position in oncology-specific EHR integrations. Aetion, Inc. anchors the regulatory-grade analytics segment with FDA-evidentiary methodology focus. These three represent divergent competitive vectors: global network density, therapeutic vertical depth, and regulatory validation rigor respectively.
| Leading Market Players |
|---|
| IQVIA Holdings Inc. |
| UnitedHealth Group |
| IBM Corporation |
| Flatiron Health Inc. |
| Syneos Health Inc. |
| ICON plc |
| Parexel International Corporation |
| Optum Inc. |
| Aetion, Inc. |
| Others |
Cost & Logistics Intelligence
Ninety-day implementation timelines for FHIR-compliant platform deployments concentrate pricing power with vendors possessing pre-built health system connectors, while compressing margins for custom integration projects. Supply chain structure in real-world evidence solutions hinges on cloud infrastructure provisioning and specialized clinical data science labor pools rather than physical component flows.
Pricing Analysis
The customization-premium spread separates standard SaaS subscription tiers from configured-to-order deployments requiring health system-specific EHR integration. Subscription-based pricing dominates, with differentiation driven by FDA validation tier and geographic data residency requirements. Cost compression in mid-tier analytics modules is intensifying because federated learning architectures reduce reliance on centralized data aggregation. Biotech firms exhibit highest price sensitivity due to milestone-driven funding constraints, while large pharmaceutical sponsors prioritize regulatory-grade validation over unit cost.
Supply Chain Analysis
The United States anchors cloud infrastructure provisioning for real-world evidence platforms, with India and Eastern Europe supplying clinical data science and natural language processing engineering talent. Platform development draws from AWS and Azure compute resources, FHIR-compliant API middleware, and specialized medical ontology libraries. Single-source vulnerability concentrates in cloud infrastructure concentration among three hyperscalers. Distribution runs through direct enterprise sales teams and strategic partnerships with contract research organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US real-world evidence solutions market represents an early-cycle expansion story, with FDA acceptance of supplemental indication submissions accelerating platform procurement beyond traditional pharmacovigilance applications.
For Market Incumbents: Fortify regulatory-grade validation capabilities against emerging federated learning substitutes that eliminate centralized data aggregation entirely. Expand FHIR connector libraries to capture health system integration preference before EHR vendor consolidation closes access points. Prioritize backward integration into clinical data curation to defend margin position against modular unbundling trends. For New Entrants and Emerging Players: Anchor in the Mid-Atlantic corridor where Philadelphia and Baltimore academic medical centers remain underdeveloped relative to Boston and New York City density. Target mid-tier contract research organizations seeking hybrid cloud governance solutions for multi-sponsor studies across state privacy jurisdictions. Lead with wearable-derived endpoint collection capabilities for decentralized oncology trial designs. For Investors and Strategic Acquirers: Carve-out targets emerge from large health systems spinning out proprietary EHR-to-research pipeline capabilities as standalone commercial entities. Long-term viability favors platforms with demonstrated FDA submission success and embedded workflow integration at academic medical centers. Monitor CMS reimbursement determinations tied to real-world performance benchmarks as inflection indicator for medical device manufacturer demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Infrastructure Acquisition | Pre-built health system connectors accelerate deployment timelines and reduce custom integration costs. |
| Federated Learning Capability Build | Distributed algorithm training eliminates raw data transfer requirements and compresses multi-site contracting cycles. |
| Oncology Data Network Expansion | EHR-to-research pipelines at academic medical centers attract biotech sponsorship for rapid patient identification. |
| Regulatory Submission Support Modularization | Unbundled service components align with venture-backed developer milestone-driven expenditure control preferences. |
| Mid-Atlantic Geographic Penetration | Philadelphia and Baltimore academic centers offer first-mover deployment potential relative to saturated Northeast corridor. |
Research Approach
Cross-validation between primary interviews with pharmaceutical data science executives, regulatory affairs leads, contract research organization procurement managers, and academic medical center informatics directors anchors the qualitative findings. Secondary validation draws from FDA 21st Century Cures Act guidance documents, ONC interoperability implementation timelines, CMS Medicare coverage determination databases, and health system EHR vendor disclosure filings. Bottom-up sizing of platform deployments triangulates against top-down pharmaceutical R&D expenditure allocation estimates.
Sensitivity analysis across deployment mode adoption curves, FDA acceptance rates for real-world evidence submissions, and state privacy statute expansion patterns shapes the analytical framework over the projection horizon. Segmentation dimensions include solution type, application purpose, end-user category, and deployment architecture complexity. CAGRs derive from regression analysis of historical platform procurement velocity against regulatory milestone timelines, incorporating cloud infrastructure cost trajectories and clinical data science labor market tightness as industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of continued FDA openness to supplemental indication submissions and stable ONC interoperability enforcement; material deviation in either would warrant model refresh. Specific risk factors include HIPAA de-identification methodology rulings that restrict cross-institutional data sharing and state-level privacy statute fragmentation that inflates compliance architecture costs. Recalibration cycles align with material shifts in FDA randomized controlled trial substitution positioning and CMS real-world performance benchmark adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Patient Engagement Technology Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Global Smart Hospital Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Amblyopia Treatment Softwares Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
North America Digital Health Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Vaccine Management Software Market
Digital Health Solutions
Digital Brain Health Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Digital Health Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Advanced Clinical Decision Support Platforms Market
Digital Health Solutions
Global Urgent Care Apps Market