
 GCC E-Health Market | 2026-2036
GCC E-Health Market Size, Share, and Industry Trends Forecast 2026-2036
GCC E-Health Market Intelligence
Platform licensing revenue is narrowing relative to direct care delivery fees as GCC health systems shift from software procurement to outcome-based service contracts. Cerner Corporation sustains installed-base dominance across Saudi Ministry of Health facilities, while Altibbi specializes in Arabic-first telemedicine workflows tailored to regional patient expectations. Philips Healthcare leverages integrated monitoring-to-cloud architectures that span hospital and home settings, and Vezeeta controls appointment-booking traffic across Egyptian and Gulf markets.
E-Health encompasses digital health infrastructure connecting patients, providers, and payers through interoperable data exchange, typically operating on HL7 FHIR protocols and localized cloud sovereignty requirements to ensure patient data residency within national borders. Telemedicine leads product-type revenue as synchronous video consultation replaces routine in-person visits across Gulf hospital systems, while remote patient monitoring grows fastest among post-acute cardiac and diabetes cohorts. Health information exchange remains structurally immature outside Saudi Arabia's NPHIES national backbone, where margin pools currently concentrate in integration services rather than platform subscriptions.
SFDA governs medical device software classifications and cybersecurity requirements for connected health products entering Saudi Arabia, while MOHAP in the UAE enforces health data protection standards that shape vendor certification pathways. The Saudi Data and Artificial Intelligence Authority (SDAIA) and UAE's health data localization mandates collectively restrict cross-border patient record flows, forcing cloud providers to establish in-country infrastructure. Stakeholders must monitor how NPHIES interoperability deadlines and emerging AI diagnostic approval frameworks reshape vendor qualification criteria across Gulf markets.
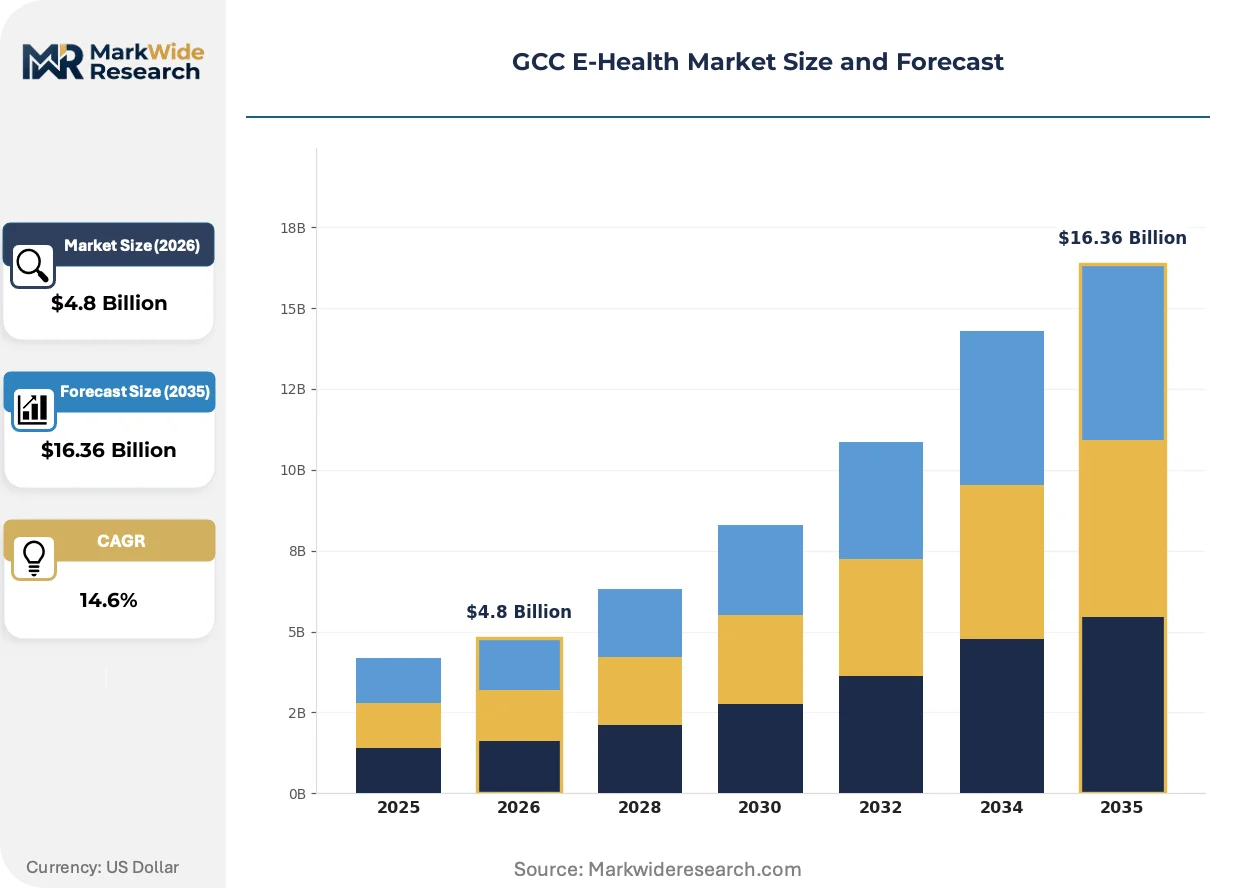
Market Dynamics
GCC health authorities are mandating interoperable data exchange standards that force vendor consolidation around national platforms, with Saudi Arabia's NPHIES interoperability deadlines compressing procurement timelines across hospital networks.
Growth Catalysts
- Telemedicine reimbursement frameworks:Saudi Arabia's Council of Health Insurance now covers remote consultations at parity with in-person visits, accelerating hospital network adoption of synchronous video platforms.
- NEOM health city infrastructure:The giga-project's integrated digital health backbone creates demand for cloud-native clinical systems spanning hospital and home settings.
- Diabetes and cardiac remote monitoring:Post-acute cohort management programs in Qatar and the UAE are expanding RPM device deployment for chronic disease surveillance.
Market Restraints
- Data localization infrastructure costs:SDAIA and UAE health data sovereignty mandates require in-country cloud infrastructure investment that raises vendor operational thresholds.
- HL7 FHIR integration complexity:Health information exchange maturity gaps outside Saudi Arabia concentrate margin pools in custom integration services rather than scalable platform revenue.
- Arabic NLP clinical documentation:Natural language processing for medical Arabic dialects remains technically immature, limiting automated clinical decision support deployment.
Strategic Opportunities
- Kuwait and Bahrain hospital digitization:These markets lag Saudi Arabia and the UAE in EHR penetration, creating first-mover advantage for integrated platform vendors.
- AI diagnostic approval pathways:Emerging SFDA frameworks for software-as-medical-device classification will shape vendor qualification criteria for radiology and pathology algorithms.
- Home-based acute monitoring:Convergence of wearable biosensors and cellular connectivity enables hospital-at-home models for COPD and heart failure patients.
Industry Challenges
- Interoperable legacy system integration:Cerner-dominated installed bases in Saudi Ministry of Health facilities complicate multi-vendor data exchange architecture.
- Clinical informatics talent scarcity:Health systems face shortages of bilingual staff capable of configuring FHIR-compliant data pipelines and Arabic interface localization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC E-Health Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telemedicine, E-Prescription, Health Information Exchange, Remote Patient Monitoring End User: Hospitals, Physicians, Patients, Insurance Providers Technology: Cloud Computing, Mobile Health Apps, Wearable Devices, Big Data Analytics Service Type: Consultation Services, Diagnostic Services, Health Management Services, Delivery Services |
| Companies Covered | Philips Healthcare, Cerner Corporation, GE Healthcare, Siemens Healthineers, Epic Systems, Altibbi, Cura Healthcare, Okadoc, Vezeeta, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC E-Health Market Strategic Shifts & Innovations
Platform business models are pivoting from perpetual licensing to consumption-based revenue as Gulf health systems prioritize operational expenditure over capital deployment for digital infrastructure.
Cloud-native clinical data repositories are migrating from on-premise hospital servers to sovereign cloud instances that satisfy SDAIA and UAE health data localization requirements. Saudi hospital networks and UAE health authorities are accelerating procurement of these architectures to meet 2025-2026 interoperability deadlines. This migration from legacy data center models is compressing vendor implementation cycles and favoring hyperscale cloud providers with established GCC infrastructure.
SFDA's emerging software-as-medical-device cybersecurity requirements are tightening market entry criteria for connected health products entering Saudi Arabia. The regulation mandates pre-market vulnerability assessments and post-market surveillance protocols that extend development timelines for international vendors. AI diagnostic modules face the most stringent scrutiny, with radiology algorithm developers restructuring approval submissions to satisfy device classification pathways.
Hospital procurement committees are unbundling EHR platform selection from implementation services, creating separate vendor relationships for software licensing and system integration. Saudi Arabia's Ministry of Health facilities and private hospital groups in Dubai are driving this bifurcation to reduce vendor lock-in and accelerate multi-source data exchange. The shift is most visible in Riyadh and Jeddah health clusters where NPHIES compliance timelines demand rapid interoperability deployment.
GCC E-Health Market Segmentation
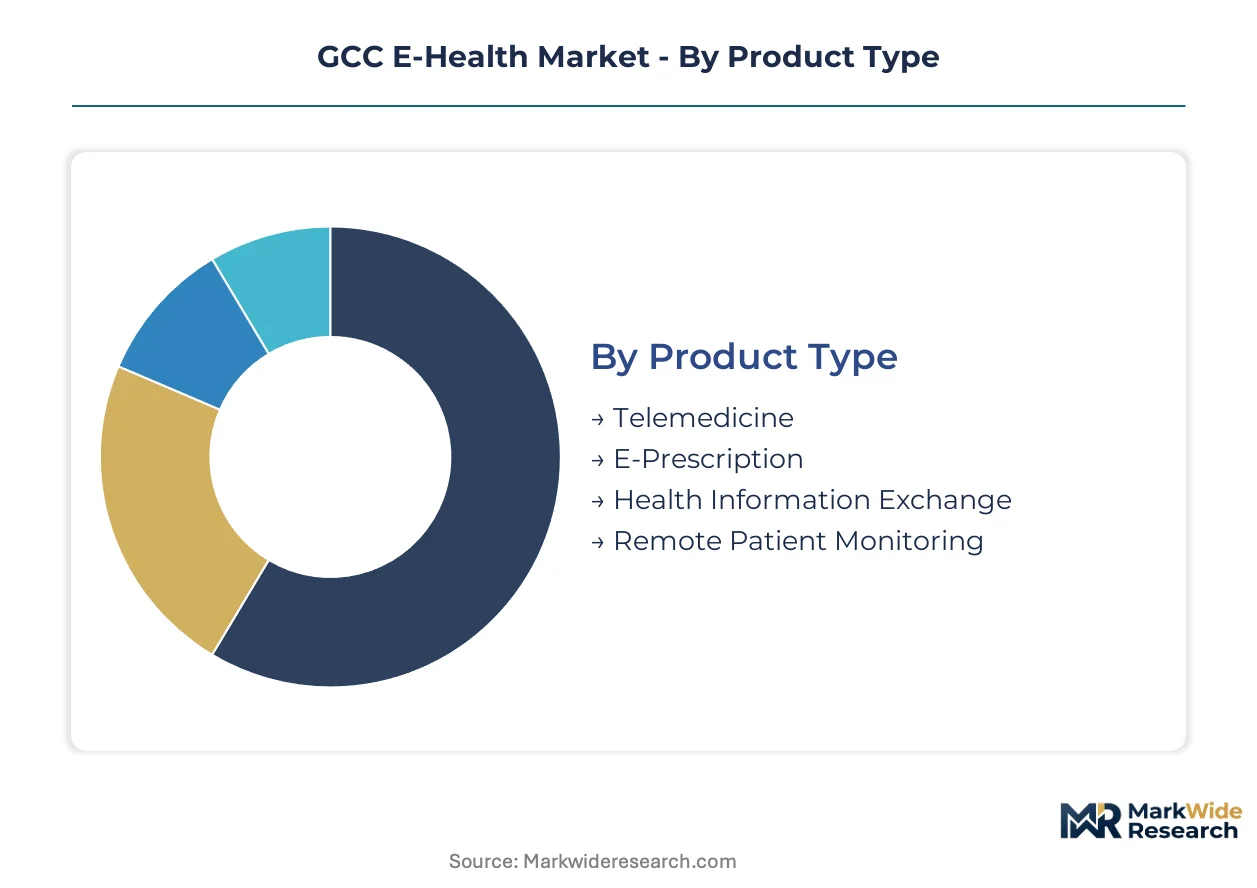
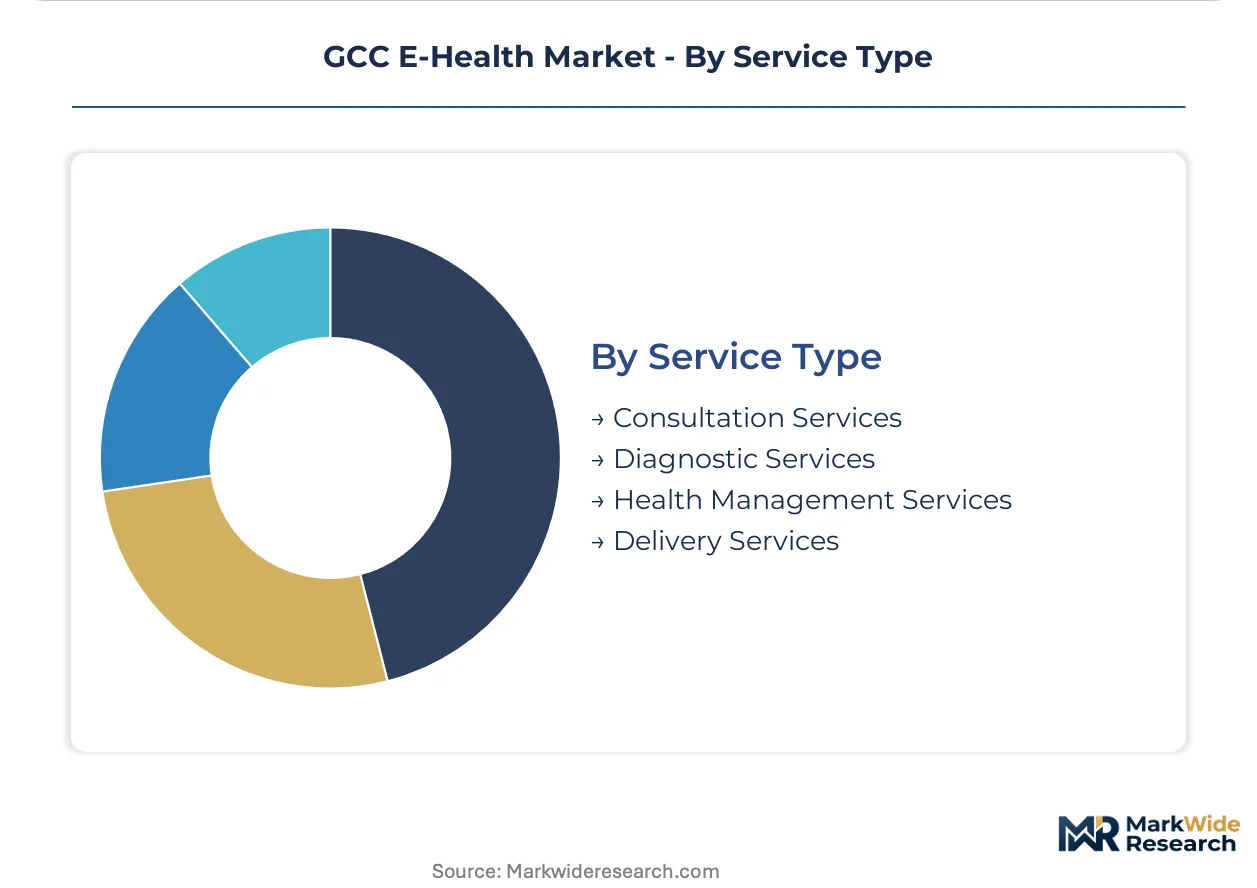
E-Health market segmentation in the GCC reveals how technology deployment varies by care setting and stakeholder capability. Product architecture, end-user sophistication, and data infrastructure maturity determine vendor positioning across Saudi Arabia, the UAE, and Qatar.
Product Type:
Cost tier differentiation separates capital-intensive platform infrastructure from lightweight consumer-facing applications.
- Telemedicine:Synchronous video consultation platforms integrate with hospital EHR systems through HL7 FHIR protocols. Saudi Arabia's Council of Health Insurance reimbursement parity drives hospital network procurement in Riyadh and Jeddah health clusters.
- Remote Patient Monitoring:Connected biosensors transmit cardiac and glucose metrics to cloud-native clinical repositories. Post-acute diabetes and heart failure programs in Qatar and the UAE expand device deployment fastest.
- E-Prescription:Electronic prescribing workflows connect physicians to pharmacy networks within national health data exchange frameworks.
- Health Information Exchange:Interoperable data backbone infrastructure concentrates integration margin pools outside Saudi Arabia's NPHIES national platform.
Telemedicine commands the established base. The steepest expansion runs through Remote Patient Monitoring.
End User:
Application context shapes platform requirements from acute care workflows to consumer self-management.
- Hospitals:Enterprise clinical systems manage patient throughput, resource allocation, and quality metrics across multi-facility networks. Saudi Ministry of Health facilities drive demand for NPHIES-compliant interoperability architecture.
- Physicians:Point-of-care decision support and Arabic-first clinical documentation interfaces require bilingual informatics configuration.
- Patients:Consumer health portals and appointment scheduling platforms aggregate demand through mobile-first interfaces.
- Insurance Providers:Claims adjudication and utilization management systems integrate with provider networks for value-based contracting.
Hospitals anchor procurement volume. Patients are gaining share fastest as direct-to-consumer platforms proliferate.
Technology:
Customer type sophistication determines whether deployments emphasize infrastructure stability or agile consumer engagement.
- Cloud Computing:Sovereign cloud instances satisfy SDAIA and UAE health data localization mandates. Hyperscale providers with established GCC infrastructure compress vendor implementation cycles for hospital network migrations.
- Big Data Analytics:Population health surveillance and predictive risk stratification require structured clinical data pipelines. SFDA's emerging AI diagnostic approval frameworks reshape algorithm vendor qualification criteria.
- Mobile Health Apps:Consumer-facing symptom checkers and medication adherence tools penetrate smartphone-saturated Gulf markets.
- Wearable Devices:Continuous monitoring hardware connects to cellular networks for hospital-at-home acute care models.
Cloud Computing dominates capital deployment. Big Data Analytics shows the steepest capability investment trajectory.
Service Type:
Volume concentration shifts from episodic acute interventions toward longitudinal chronic disease management.
- Consultation Services:Remote physician-patient encounters replace routine in-person visits across Saudi and Emirati hospital systems. Reimbursement parity accelerates synchronous video platform adoption.
- Diagnostic Services:Teleradiology and telepathology algorithms face stringent SFDA software-as-medical-device cybersecurity scrutiny. Pre-market vulnerability assessments extend international vendor development timelines.
- Health Management Services:Chronic disease surveillance programs coordinate care across hospital and home settings for diabetes and cardiac cohorts.
- Delivery Services:Pharmaceutical logistics and remote therapeutic monitoring integrate with e-prescription infrastructure.
Consultation Services capture the current revenue base. Diagnostic Services face the most complex regulatory pathway expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia consumes E-Health infrastructure as national platform mandates, while the UAE and Qatar prioritize point solutions and consumer-facing applications. This consumption-mix differential shapes vendor deployment strategies across Gulf markets.
Saudi Arabia
NEOM health city infrastructure and NPHIES interoperability deadlines drive enterprise clinical system procurement. SFDA governs medical device software classifications and cybersecurity requirements for connected health products. Riyadh and Jeddah health clusters compress vendor implementation timelines to meet 2025-2026 national backbone compliance.
United Arab Emirates
Dubai and Abu Dhabi hospital networks accelerate sovereign cloud migration for patient data residency compliance. MOHAP enforces health data protection standards that shape vendor certification pathways. Dubai Health Authority facilities unbundle EHR platform selection from implementation services to reduce vendor lock-in.
Qatar
Post-acute cardiac and diabetes remote monitoring programs expand connected biosensor deployment fastest. The country's national health authority digitizes patient records through interoperable exchange standards. Doha-based hospital networks concentrate integration margin pools in custom services rather than scalable subscriptions.
Kuwait
Hospital digitization lags Saudi Arabia and the UAE in EHR penetration, creating first-mover advantage for integrated platform vendors. The Ministry of Health mandates interoperability frameworks that force vendor consolidation. Kuwait City health clusters present untapped demand for cloud-native clinical data repositories.
Bahrain
Smaller hospital networks prioritize lightweight consumer-facing applications over capital-intensive infrastructure. National health data exchange standards remain structurally immature compared to NPHIES. Manama-based facilities concentrate procurement in telemedicine platforms with Arabic-first clinical documentation interfaces.
GCC E-Health Market Key Industry Players
Capability concentration sits with specialized telemedicine platforms; scale advantage sits with integrated health technology conglomerates. The vendor base organizes around three tiers: global EHR incumbents with installed-base dominance, regional Arabic-first specialists, and hyperscale cloud providers with sovereign infrastructure. Dominant competitive moves include strategic partnerships with national health authorities and portfolio diversification into remote patient monitoring hardware.
Within the global incumbent tier, Cerner Corporation and Philips Healthcare exemplify divergent positioning—one anchoring legacy EHR consolidation, the other spanning monitoring-to-cloud architectures. Among regional specialists, Altibbi and Vezeeta occupy positions shaped by Arabic NLP workflows and consumer traffic aggregation respectively. These named entities represent archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Philips Healthcare |
| Cerner Corporation |
| GE Healthcare |
| Siemens Healthineers |
| Epic Systems |
| Altibbi |
| Cura Healthcare |
| Okadoc |
| Vezeeta |
| Others |
Cost & Logistics Intelligence
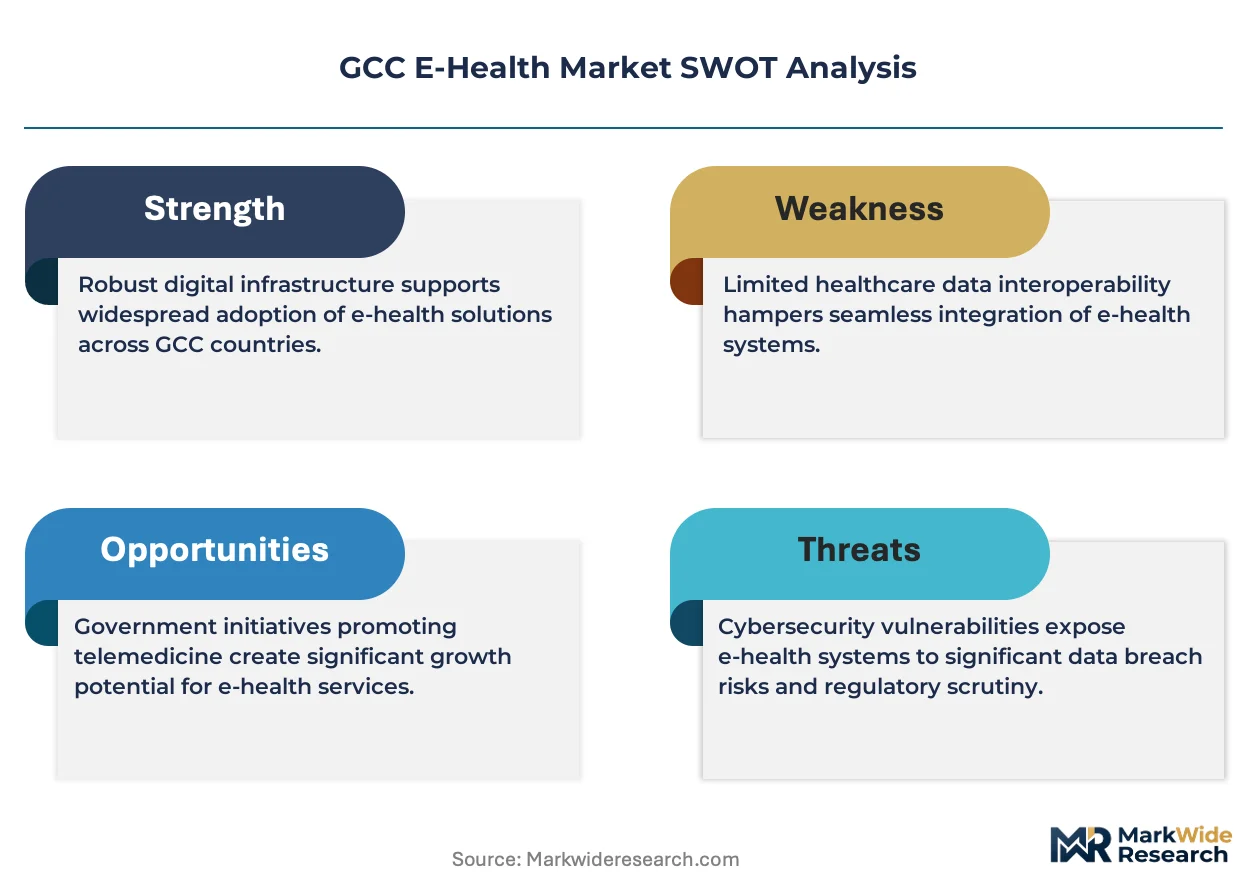
SDAIA-mandated data localization infrastructure creates dual pressure on vendor cost structures and procurement committee negotiations, compressing margin spreads between sovereign cloud deployments and standard SaaS tiers while forcing hyperscale providers to absorb fixed-capacity investments ahead of volume commitments.
Pricing Analysis
Long-term outcome-based service contracts dominate hospital procurement in Saudi Arabia and the UAE, displacing perpetual EHR licensing with consumption-adjusted fees tied to patient throughput metrics. Price differentiation hinges on NPHIES interoperability certification tier and Arabic NLP clinical documentation capability, with uncertified platforms facing steeper discount pressure. Cost compression in mid-tier telemedicine subscriptions intensifies as Altibbi and Vezeeta compete for consumer traffic aggregation. Government hospital networks exhibit lowest price sensitivity due to national platform mandates, while Bahrain's smaller private clinics drive hardest bargain on per-consultation fees.
Supply Chain Analysis
Upstream semiconductor and cellular modem feedstock for connected biosensors concentrates in Taiwan, South Korea, and China, with GCC-based RPM device assemblers drawing from Shenzhen and Taipei component hubs. Cloud infrastructure hardware rests on server-grade chip supply from Intel and AMD fabrication networks anchored in the United States and Ireland. Single-source vulnerability sits with narrow supplier bases for medical-grade wearable sensors meeting SFDA cybersecurity requirements. Distribution runs through hospital procurement committees in Riyadh and Dubai health clusters, with direct-to-consumer channels gaining share via smartphone app stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC E-Health infrastructure represents a service-attach opportunity where remote patient monitoring data analytics and chronic disease management subscriptions expand faster than hardware device sales, creating recurring revenue layers with superior retention economics.
For Market Incumbents: Entrench installed-base dominance through NPHIES interoperability certification acceleration and backward integration into Arabic NLP clinical documentation engines. Cerner Corporation's Saudi Ministry of Health relationships face substitution pressure from cloud-native Epic Systems deployments; defend through rapid FHIR-compliant data pipeline configuration and captive training programs for bilingual clinical informatics talent. For New Entrants and Emerging Players: Build out sovereign cloud infrastructure partnerships in Kuwait and Bahrain before hospital digitization deadlines compress procurement timelines. Kuwait City health clusters present the most penetrable geography given lagging EHR penetration versus Saudi Arabia. Target first-mover positioning through integrated platform bundling that combines telemedicine, RPM, and e-prescription workflows under single Arabic-first interfaces. For Investors and Strategic Acquirers: SFDA's emerging AI diagnostic approval frameworks reshape the acquisition landscape, elevating software-as-medical-device cybersecurity capabilities as a valuation differentiator. Long-term viability across the analysis window favors targets with established in-country cloud infrastructure and regulatory submission track records. The signal to watch is NPHIES compliance deadline acceleration forcing distressed divestitures from international vendors lacking localized data residency architecture.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Partnership | SDAIA and MOHAP data localization mandates require in-country server deployment for patient record residency compliance. |
| SFDA Software-as-Medical-Device Certification | Cybersecurity pre-market assessments tighten market entry criteria for AI diagnostic and connected monitoring products. |
| Arabic NLP Clinical Documentation Development | Natural language processing for medical dialects enables automated decision support deployment across Saudi hospital networks. |
| Hospital System Outcome-Based Contracting | NEOM health city and NPHIES-aligned facilities prioritize operational expenditure models over capital-intensive EHR procurement. |
| Remote Patient Monitoring Hardware Integration | Post-acute cardiac and diabetes programs in Qatar and the UAE drive demand for cellular-connected biosensor ecosystems. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital CIOs in Riyadh and Dubai, clinical informatics directors configuring FHIR data pipelines, biomedical engineers selecting RPM device vendors, and GPO contracts managers at Saudi Ministry of Health facilities. Secondary validation drew from SFDA medical device software classification filings, MOHAP health data protection standards documentation, NPHIES interoperability technical specifications, hyperscaler GCC infrastructure capex disclosures, and hospital procurement database records. Bottom-up telemedicine platform deployment counts were triangulated against top-down health authority digitization budget allocations.
Calibration against historical NPHIES compliance timeline slippage and telemedicine reimbursement parity implementation patterns anchored growth trajectory assumptions across the projection horizon. Segmentation modeling incorporated product type, end user sophistication tier, technology deployment complexity, and service delivery modality dimensions. CAGRs were derived from fitted adoption curves weighted by national health authority procurement acceleration signals, with cloud migration velocity and AI diagnostic approval pipeline throughput as GCC-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive cloud infrastructure investment by hyperscale providers or accelerated SFDA cybersecurity mandate enforcement would shift outcomes beyond modeled ranges. Cross-checking against hospital procurement committee budget cycle disclosures and national health authority digitization roadmap updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Patient Engagement Solution Market
Digital Health Solutions
Medical Animation Market
Digital Health Solutions
Mhealth Services Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Global Microservices in Healthcare Market
Digital Health Solutions
AI-Powered Clinical Decision Support Market
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
Advanced Clinical Decision Support Platforms Market
Digital Health Solutions
Global Physical Therapy Software Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
Europe Digital Health Market
Digital Health Solutions
North America Virtual Reality (VR) Health Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Global Real World Evidence Solutions Market
Digital Health Solutions
Prescribed Health Apps Market
Digital Health Solutions
VR in Healthcare Market