
 Teleradiology Software Market | 2026-2036
Teleradiology Software Market Size, Share, and Industry Trends Forecast 2026-2036
Teleradiology Software Market Outlook
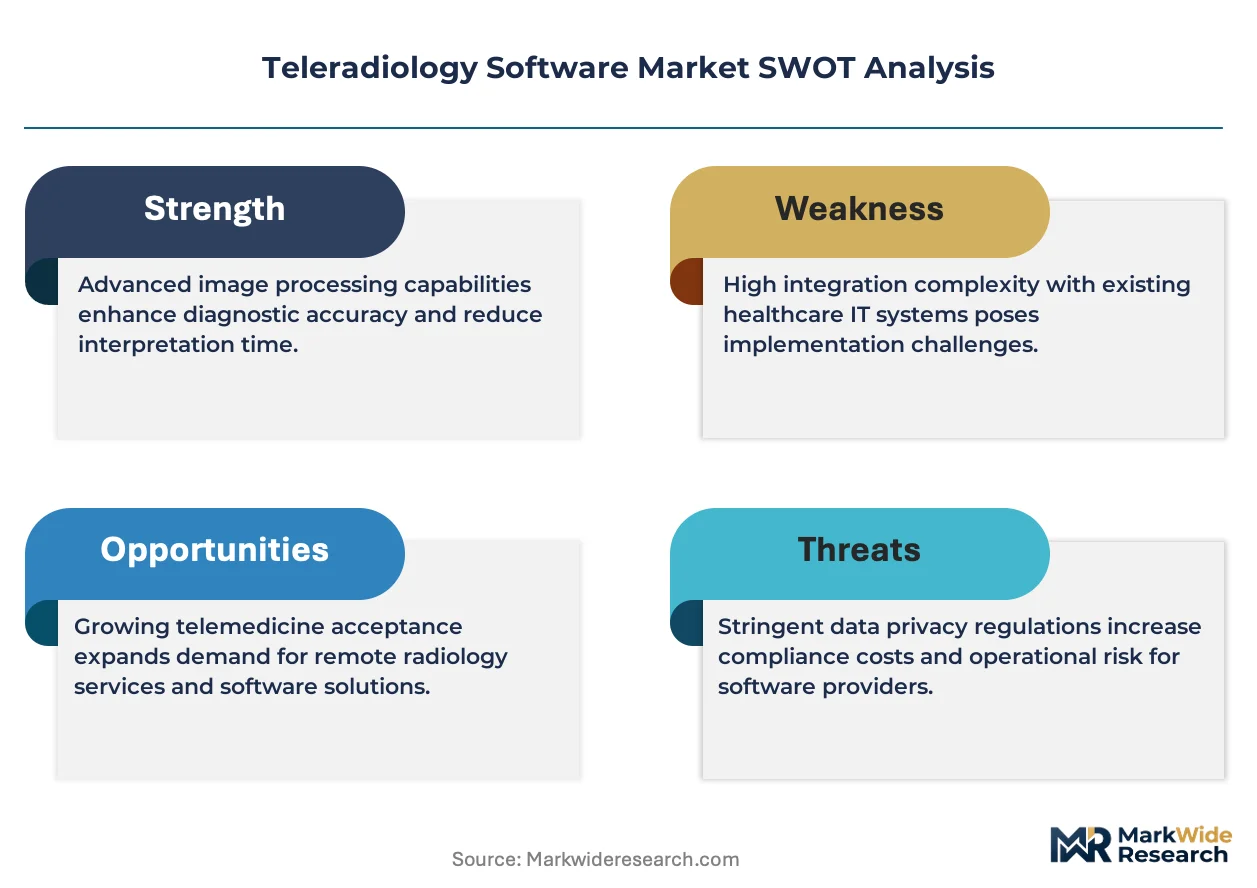
Cloud-native architecture with embedded AI inference is rewriting how diagnostic images are processed, stored, and distributed across distributed care networks. Siemens Healthineers leverages deep vertical integration across imaging hardware and software stacks to control end-to-end workflows. GE Healthcare anchors its position through R&D intensity in edge-computing modules that reduce latency for real-time consults. Philips Healthcare differentiates via specialized workflow automation tools that integrate with existing hospital information systems.
Teleradiology software encompasses platforms that transmit, store, and interpret medical images across geographically separated locations, typically supporting DICOM standards and HL7 interoperability for seamless data exchange between modalities and reading workstations. Cloud-based software leads deployment preferences among mid-sized diagnostic centers seeking scalable infrastructure without capital-intensive server investments, while on-premise software retains dominance in large hospital systems with strict data sovereignty requirements. Workflow automation features command premium positioning as labor shortages intensify demand for streamlined reporting pipelines, whereas mobile applications represent the fastest-expanding segment among telehealth providers serving home-based and rural patient populations.
FDA oversight of software-as-a-medical-device (SaMD) classifications shapes product development pathways and market access timelines for teleradiology platforms in the United States, while HIPAA mandates dictate encryption, access control, and audit trail specifications that vendors must embed at the architecture level. In Europe, CE marking under the Medical Device Regulation and GDPR compliance requirements create dual certification burdens that favor established players with dedicated regulatory affairs capacity. Stakeholders must monitor evolving AI diagnostic algorithms and their regulatory status, as automated image interpretation capabilities will determine which platforms gain preferred vendor status in the next procurement cycle.
Market Dynamics
Radiologist workforce deficits across rural healthcare networks are forcing diagnostic centers toward remote reading platforms that pool specialist capacity across state lines and international borders.
Growth Catalysts
- HIPAA-compliant cloud frameworks:The US federal mandate for encrypted health data transmission has normalized SaaS deployment models that reduce IT overhead for mid-sized hospitals.
- India's telehealth infrastructure expansion:Government-backed public health networks are embedding teleradiology into district-level diagnostic workflows, creating standardized procurement pipelines.
- Edge-computing modules:Real-time image preprocessing at network peripheries is cutting transmission latency for emergency stroke and trauma consultations.
Market Restraints
- DICOM-HL7 integration complexity:Legacy hospital information systems require costly middleware development to achieve seamless data exchange with modern cloud platforms.
- Data sovereignty requirements:Large hospital systems in Germany and France mandate on-premise storage, blocking pure-cloud adoption regardless of security certifications.
- AI diagnostic algorithm liability:Unclear malpractice allocation between software vendors and interpreting physicians is slowing automated reporting deployment.
Strategic Opportunities
- Home-based patient populations:Mobile application interfaces for post-operative imaging review are opening subscription revenue streams outside traditional hospital contracts.
- EU AI Act compliance services:Vendors that pre-certify risk-classification algorithms for high-stakes diagnostic workflows will capture preferred vendor status in European tenders.
- 5G network densification:Ultra-low latency connectivity in South Korea and Japan is enabling real-time interventional radiology guidance from remote specialists.
Industry Challenges
- Subspecialty radiologist recruitment:Neuroradiology and pediatric imaging expertise remains concentrated in academic medical centers, limiting 24/7 coverage pools for teleradiology networks.
- SaMD classification timelines:FDA software-as-a-medical-device review queues are extending product launch windows by 8-14 months for AI-augmented platforms.
- Interoperability standard fragmentation:Competing regional health information exchange protocols in the US are forcing vendors to maintain multiple integration codebases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Teleradiology Software Market |
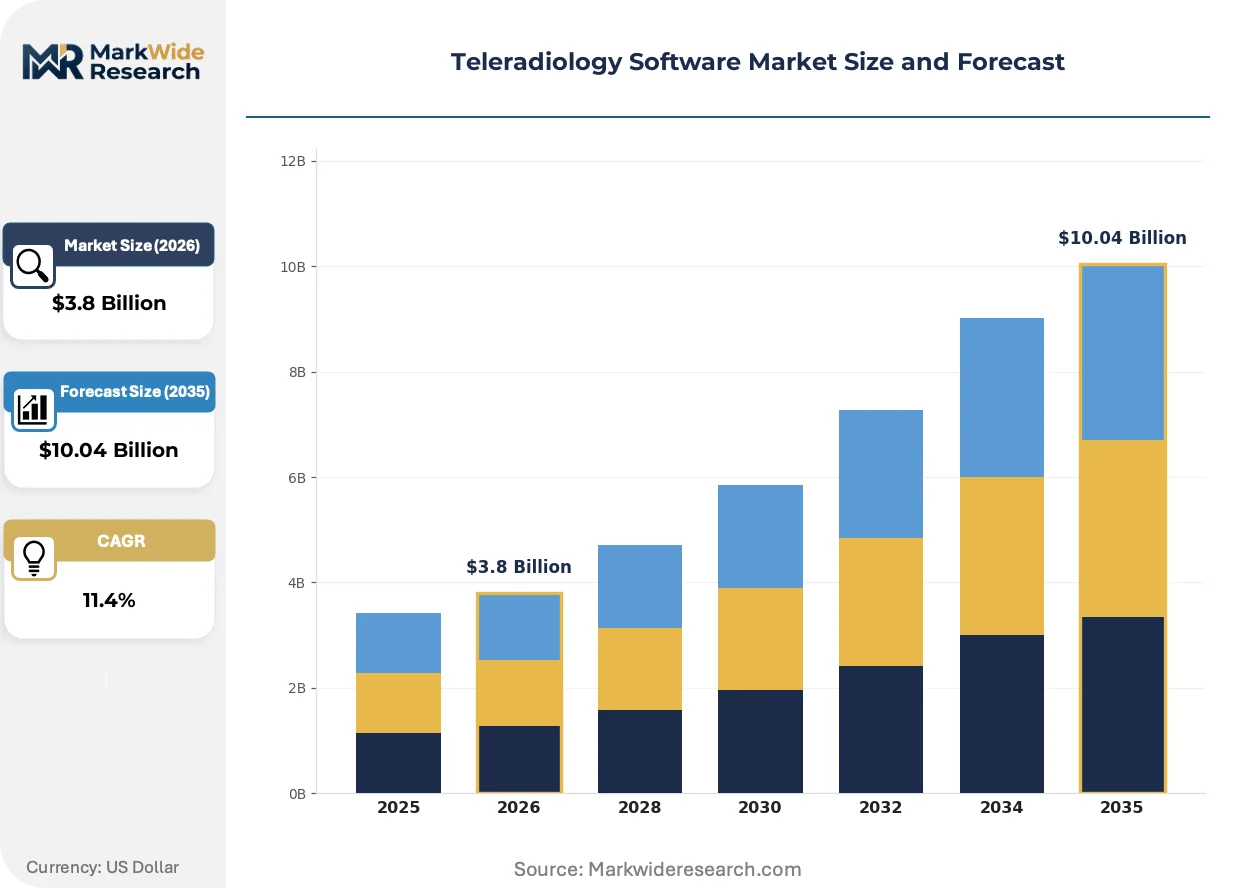
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Software, On-Premise Software, Hybrid Software, Mobile Applications End User: Hospitals, Diagnostic Centers, Research Institutions, Telehealth Providers Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Site Deployment Feature: Image Sharing, Workflow Automation, Remote Access, Reporting Tools |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Agfa-Gevaert Group, FUJIFILM Holdings Corporation, Carestream Health, RamSoft, Sectra, 4ways Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Teleradiology Software Market Strategic Shifts
Diagnostic imaging workflows are compressing from batch-processed overnight reads toward continuous, distributed interpretation models that match specialist availability to acute care demand spikes.
Cloud-native PACS architecture is migrating from monolithic on-premise installations toward containerized microservices that auto-scale compute resources during peak emergency department volumes. Rural critical access hospitals in Montana and Idaho are adopting these elastic deployments fastest, eliminating capital-intensive server refresh cycles while maintaining sub-300-millisecond image retrieval speeds. The structural consequence is collapsing the traditional vendor lock-in associated with hardware-software bundles.
FDA's evolving SaMD guidance for machine learning-based image analysis is tightening validation requirements for continuously learning algorithms that adapt to local patient populations. Developers must now submit locked algorithm versions for 510(k) clearance rather than deploying adaptive models that improve through field use. AI-augmented mammography and chest CT platforms face the steepest compliance burden, with several vendors freezing development timelines to restructure quality management systems.
Subscription-based per-study pricing is displacing perpetual license models across independent diagnostic centers in Texas and Florida. Buyers prefer operational expenditure treatment that aligns software costs with actual imaging volumes rather than fixed amortization schedules. This shift pressures vendor cash flow structures and accelerates consolidation among smaller platform providers lacking balance sheet depth to finance customer transitions.
Teleradiology Software Market Segmentation
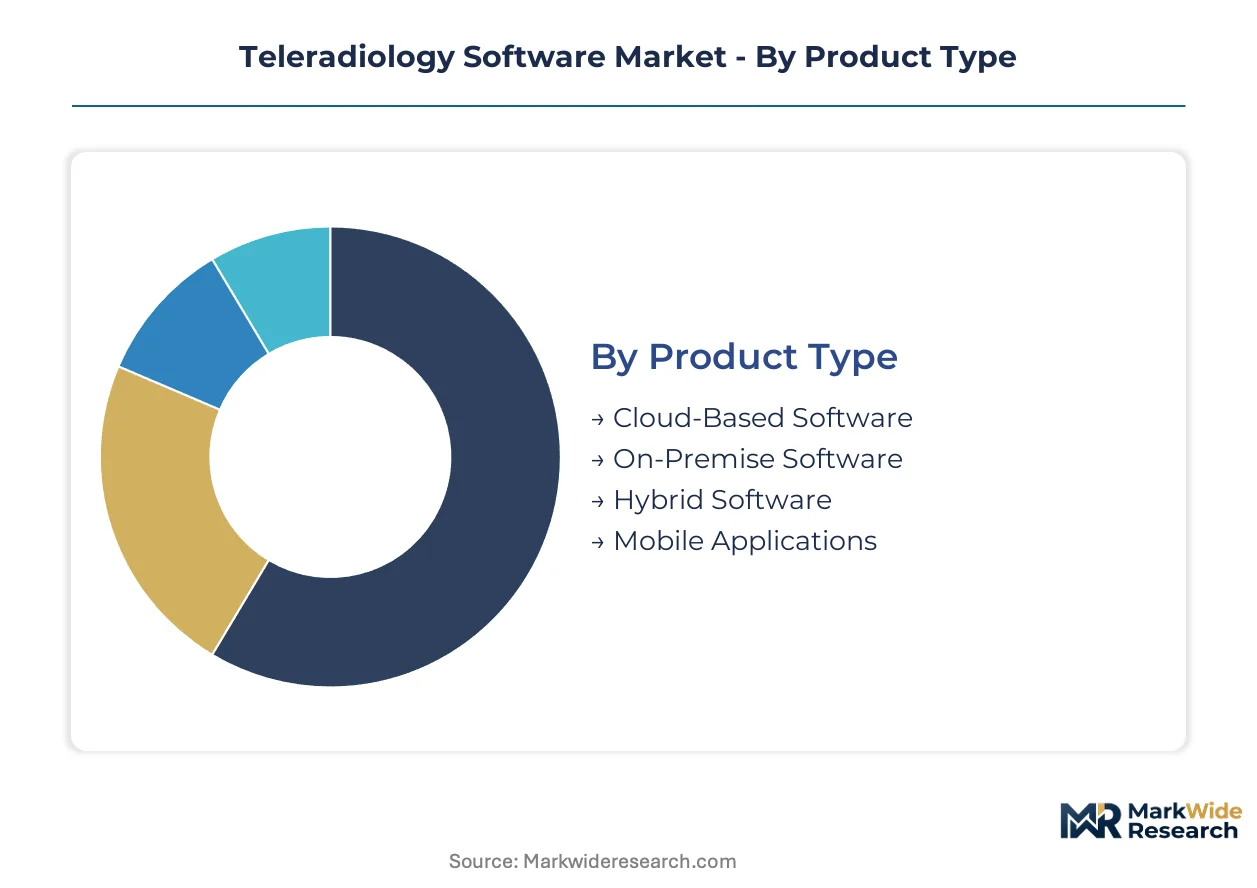
Teleradiology software segmentation reveals how procurement priorities diverge between capital-constrained rural networks and enterprise health systems with dedicated IT infrastructure. Understanding these splits enables vendors to align licensing models and support architectures with buyer capabilities.
Product Type:
After-sales service intensity varies dramatically across deployment architectures, with cloud-native platforms demanding continuous security patching and hybrid systems requiring specialized integration support.
- Cloud-Based Software:Multi-tenant SaaS architectures with auto-scaling compute pools eliminate server refresh cycles for mid-sized diagnostic centers. Demand concentrates in Montana and Idaho critical access hospitals seeking sub-300-millisecond image retrieval without capital expenditure.
- On-Premise Software:Monolithic PACS installations with localized DICOM routing maintain data sovereignty for German and French hospital systems with strict territorial storage mandates. Large academic medical centers in Paris and Munich anchor procurement despite higher total cost of ownership.
- Hybrid Software:Split architectures process non-sensitive metadata in public cloud while retaining patient images on local storage arrays.
- Mobile Applications:Containerized iOS and Android clients with offline caching enable post-operative image review for home-based patient populations.
Cloud-based software holds the largest share; momentum sits with mobile applications.
End User:
Procurement sophistication separates institutional buyers with dedicated biomedical engineering staff from lean operators purchasing through group purchasing organizations.
- Hospitals:Enterprise health systems with 24/7 emergency departments require guaranteed uptime SLAs and subspecialty neuroradiology coverage pools. Integrated delivery networks in Texas and Florida consolidate purchasing through centralized IT governance committees.
- Diagnostic Centers:Independent imaging facilities prioritize per-study pricing that aligns software costs with actual throughput rather than fixed licensing. Standalone centers in Arizona and Nevada drive subscription model adoption fastest.
- Research Institutions:Academic medical centers with NIH funding streams demand de-identified image repositories and multi-site trial coordination tools.
- Telehealth Providers:Virtual-first care platforms integrate teleradiology into bundled primary care subscriptions for rural patient capture.
Hospitals command the deepest vendor relationships; diagnostic centers are climbing the fastest.
Deployment Model:
Margin structures favor private cloud implementations where vendors capture infrastructure markup alongside software licensing.
- Public Cloud:Shared-tenant AWS and Azure instances with HIPAA Business Associate Agreements reduce entry costs for independent practices. Indian government telehealth networks standardize on public cloud for district-level diagnostic workflows.
- Private Cloud:Single-tenant dedicated instances with custom encryption key management serve US health systems with cyber insurance requirements. Catholic hospital networks with ethical investment mandates specify private cloud to avoid shared infrastructure with defense contractors.
- Hybrid Cloud:Burst capacity models shift non-urgent reads to public cloud during peak emergency department volumes.
- On-Site Deployment:Air-gapped server rooms with physical access controls satisfy military and correctional health facility security protocols.
Private cloud generates the highest margins; hybrid cloud is gaining share fastest.
Feature:
Workflow automation commands premium positioning as radiologist shortages intensify demand for streamlined reporting pipelines.
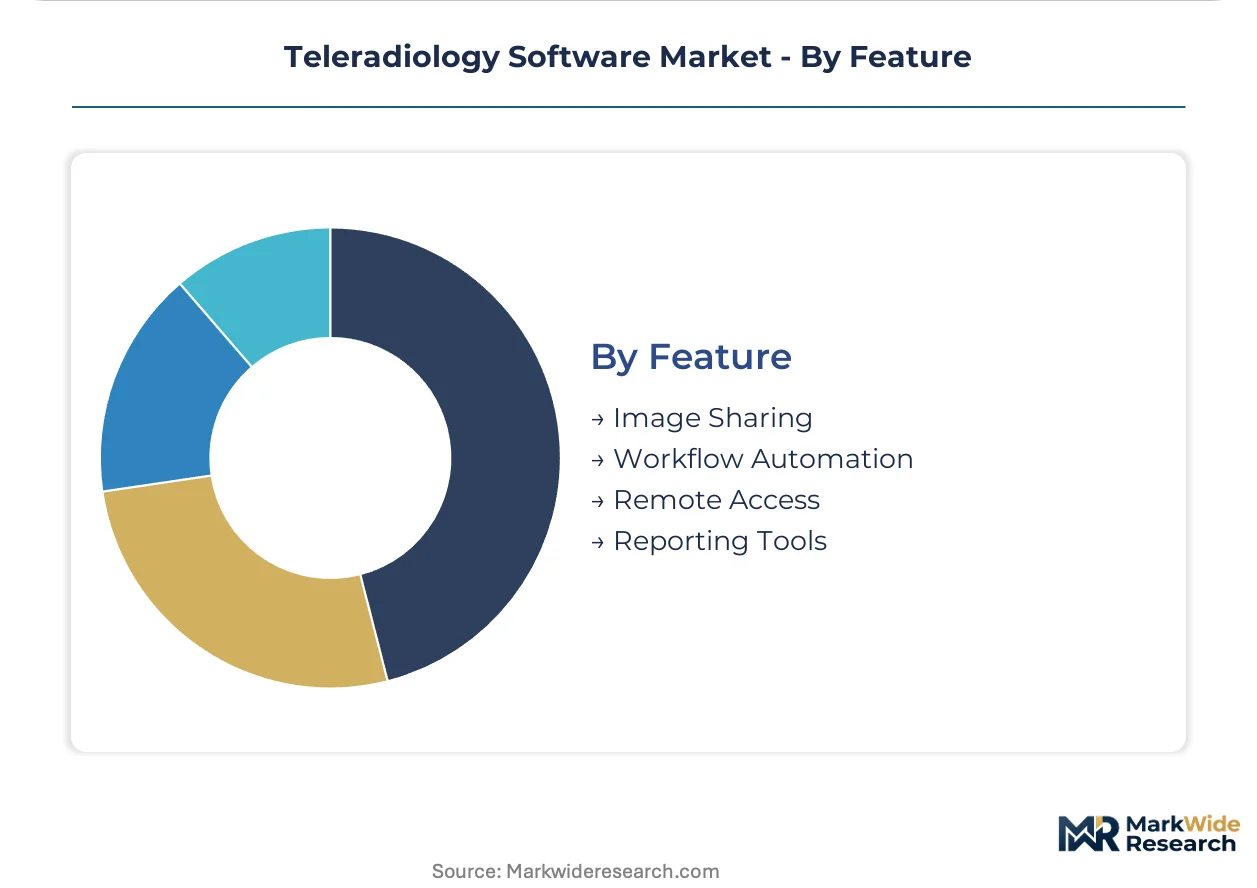
- Image Sharing:Federated PACS with cross-enterprise patient identity matching enables multi-site health systems to pool specialist capacity. Kaiser Permanente and Intermountain Healthcare anchor demand for seamless image portability across state lines.
- Workflow Automation:AI-augmented worklist triage with acuity scoring routes critical findings to on-call specialists within 90 seconds. Emergency stroke networks in South Korea and Japan mandate automated prioritization for time-sensitive interventions.
- Remote Access:Zero-trust VPN architectures with hardware token authentication enable home-based radiologist reading pools.
- Reporting Tools:Structured reporting templates with embedded quality metrics standardize communication between radiologists and referring clinicians.
Image sharing holds the largest installed base; workflow automation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The teleradiology software trade flows through distinct national regulatory frameworks rather than unified regional blocs. Import dependence concentrates in markets lacking domestic imaging hardware manufacturing, while export leadership tracks to jurisdictions with established medical device regulatory capacity.
United States
Rural critical access hospitals in Montana and Idaho drive cloud-native adoption to offset radiologist shortages. FDA software-as-a-medical-device oversight shapes AI-augmented platform development timelines. The Texas-Florida diagnostic center corridor anchors subscription pricing model diffusion.
Germany
Data sovereignty mandates in Bavaria and North Rhine-Westphalia preserve on-premise PACS dominance despite cloud security certifications. CE marking under the EU Medical Device Regulation creates dual certification burdens favoring established vendors. Munich's academic medical centers concentrate neuroradiology expertise for cross-border remote reading pools.
India
Government-backed telehealth networks embed teleradiology into district-level public health infrastructure. CDSCO medical device regulations and BIS standards govern import substitution for diagnostic platforms. Karnataka's Bengaluru cluster hosts domestic software development for public cloud deployments.
Japan
5G network densification enables real-time interventional radiology guidance from remote specialists. PMDA oversight of AI diagnostic algorithms tightens validation requirements for machine learning-based platforms. METI industrial policy supports edge-computing module development in the Nagoya manufacturing belt.
United Kingdom
NHS England procurement frameworks standardize teleradiology integration into national health infrastructure. GDPR compliance requirements intersect with MHRA medical device regulations for post-Brexit certification pathways. London's integrated care systems pool specialist capacity across suburban and exurban diagnostic networks.
Teleradiology Software Market Competitive Environment
On the supply side, the industry is consolidating around imaging hardware incumbents with software stack control and cloud-native specialists with workflow automation expertise. Three strategic archetypes dominate: vertically integrated imaging system vendors, pure-play SaaS platform providers, and telehealth-integrated service operators. Competitive moves concentrate on R&D intensity in edge-computing modules and strategic partnerships with 5G network operators.
Within the integrated systems tier, Siemens Healthineers and GE Healthcare exemplify hardware-software bundling strategies, while Philips Healthcare occupies a position emphasizing workflow automation tools. These three anchors represent distinct approaches to end-to-end diagnostic workflow control, with each leveraging captive imaging equipment install bases to secure software attachment rates.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Agfa-Gevaert Group |
| FUJIFILM Holdings Corporation |
| Carestream Health |
| RamSoft |
| Sectra |
| 4ways Healthcare |
| Others |
Value Chain & Pricing Dynamics
Bengaluru's software development cluster shapes downstream pricing power for cloud-native teleradiology platforms, with capacity expansion in Karnataka compressing deployment costs for mid-sized diagnostic centers while data sovereignty mandates in Munich and Paris preserve premium pricing for on-premise installations.
Pricing Analysis
Diagnostic centers anchor pricing stratification across premium, standard, and economy tiers, with subscription SaaS models displacing perpetual licenses fastest in Texas and Florida. Price differentiation hinges on workflow automation depth and HIPAA certification tier, with AI-augmented triage commanding substantial premiums. Cost compression in the standard tier intensifies as Indian public cloud deployments scale. Telehealth providers exhibit highest price sensitivity; academic medical centers with NIH funding streams show lowest.
Supply Chain Analysis
US export controls on advanced AI inference chips constrain hardware availability for edge-computing modules in certain jurisdictions. Component manufacturing concentrates in Taiwan, South Korea, and the United States for GPU accelerators, while cloud infrastructure draws from AWS, Azure, and domestic Indian providers. Single-source vulnerability sits with specialized DICOM-HL7 middleware vendors. Distribution runs through direct enterprise sales teams for hospital systems and channel partners for independent diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as rural hospital networks demand specialized workflow automation tools that incumbent imaging hardware vendors underinvest in.
For Market Incumbents: Insulate installed base relationships by embedding workflow automation deeper into existing PACS architectures, countering pure-play SaaS entrants. Prioritize R&D in edge-computing modules for stroke network latency requirements. Backward integration into AI training data pipelines secures algorithm differentiation against cloud-native challengers. For New Entrants and Emerging Players: Pursue mobile application interfaces for post-operative imaging review, the fastest-expanding segment with lowest incumbent saturation. Target Montana and Idaho critical access hospitals with elastic cloud-native deployments. Lead with per-study pricing that aligns costs to actual imaging volumes rather than fixed licensing. For Investors and Strategic Acquirers: Carve-out targets emerge from imaging hardware conglomerates with underoptimized software divisions, particularly workflow automation tools stranded in legacy PACS portfolios. Five-to-ten year viability favors vendors with FDA 510(k) clearance queues already advancing. Monitor FDA SaMD classification timeline compression as inflection signal for AI-augmented platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks German and French hospital procurement pipelines. |
| Hospital System Partnership | Kaiser Permanente-scale integrations validate enterprise workflow automation capabilities. |
| Software Companion Development | FDA-cleared AI algorithms for mammography differentiate in US tenders. |
| Geographic Expansion | Indian district-level telehealth networks standardize on public cloud deployments. |
| Strategic Partnership | 5G network operator alliances enable real-time interventional radiology guidance in Japan. |
Study Parameters
The analysis maps cloud-native SaaS platforms, on-premise PACS installations, hybrid architectures, and mobile applications, each validated through radiology practice administrators, hospital IT procurement officers, biomedical engineers, and GPO contracts managers. Primary interviews triangulate with FDA 510(k) filings, CDSCO medical device registrations, hospital procurement databases, and hyperscaler healthcare vertical disclosures. Bottom-up deployment counts reconcile with top-down imaging volume estimates.
Assumptions held fixed include HIPAA compliance mandates and DICOM-HL7 interoperability requirements, while AI diagnostic algorithm regulatory status and 5G network densification trajectories varied across scenarios. Segmentation models deployment model, organization size, integration complexity, subspecialty coverage requirements, and regional adoption patterns. CAGRs derive from imaging volume elasticity to radiologist workforce deficits and cloud infrastructure cost curves.
Sensitivities concentrate around FDA SaMD classification timeline shifts and EU AI Act risk-classification implementation. Forecasts reflect documented assumptions on radiologist shortage persistence and cloud security certification normalization. Material shifts in automated diagnostic liability allocation or data sovereignty mandate relaxation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
US Digital Health Market
Digital Health Solutions
Asia-Pacific Digital Therapeutic (Dtx) Market
Digital Health Solutions
Global Digital Medicines Market
Digital Health Solutions
Virtual Reality (VR) in Healthcare Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
US Patient Engagement Solutions Market
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Women Health Applications Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Global Patient Portal Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Patient Engagement Technology Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
GCC E-Health Market
Digital Health Solutions
Middle East and Africa Virtual Reality (VR) Health Market