
 Cardiac AI Monitoring and Diagnostic Market | 2026-2036
Cardiac AI Monitoring and Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac AI Monitoring and Diagnostic Market Insights
Platform licensing revenue is fragmenting between pure-play algorithm vendors and integrated device manufacturers. GE HealthCare leverages its installed base of imaging systems to bundle AI diagnostics with hardware service contracts. Siemens Healthineers anchors its cardiac AI portfolio through deep learning pipelines that interpret echocardiography and catheterization data. Philips competes by extending its wearable and monitoring ecosystem into cloud-based analytics layers that capture recurring subscription value.
Cardiac AI monitoring and diagnostic systems combine machine learning inference engines with electrocardiographic signal processing to detect arrhythmias, ischemia, and structural abnormalities in real time or retrospectively. These systems process multi-lead ECG streams, photoplethysmography waveforms, and implantable device telemetry through cloud architectures that enable remote clinician oversight. Wearable devices and cloud-based platforms represent the fastest-expanding product categories as ambulatory monitoring shifts from episodic clinic visits to continuous home-based surveillance. Machine learning and deep learning technologies dominate development pipelines, while predictive analytics applications in risk stratification command premium pricing due to their direct impact on intervention timing and patient outcomes.
FDA premarket review pathways and the EU MDR framework govern clinical validation requirements, determining which algorithms achieve commercial deployment in the United States and European member states. HIPAA and GDPR compliance obligations shape data architecture decisions for cloud-based platforms that transmit patient-identifiable cardiac biomarkers across jurisdictions. Stakeholders must monitor evolving reimbursement codes for AI-assisted interpretation, as payer acceptance determines whether health systems absorb these technologies at scale or limit deployment to research-oriented centers.
Market Dynamics
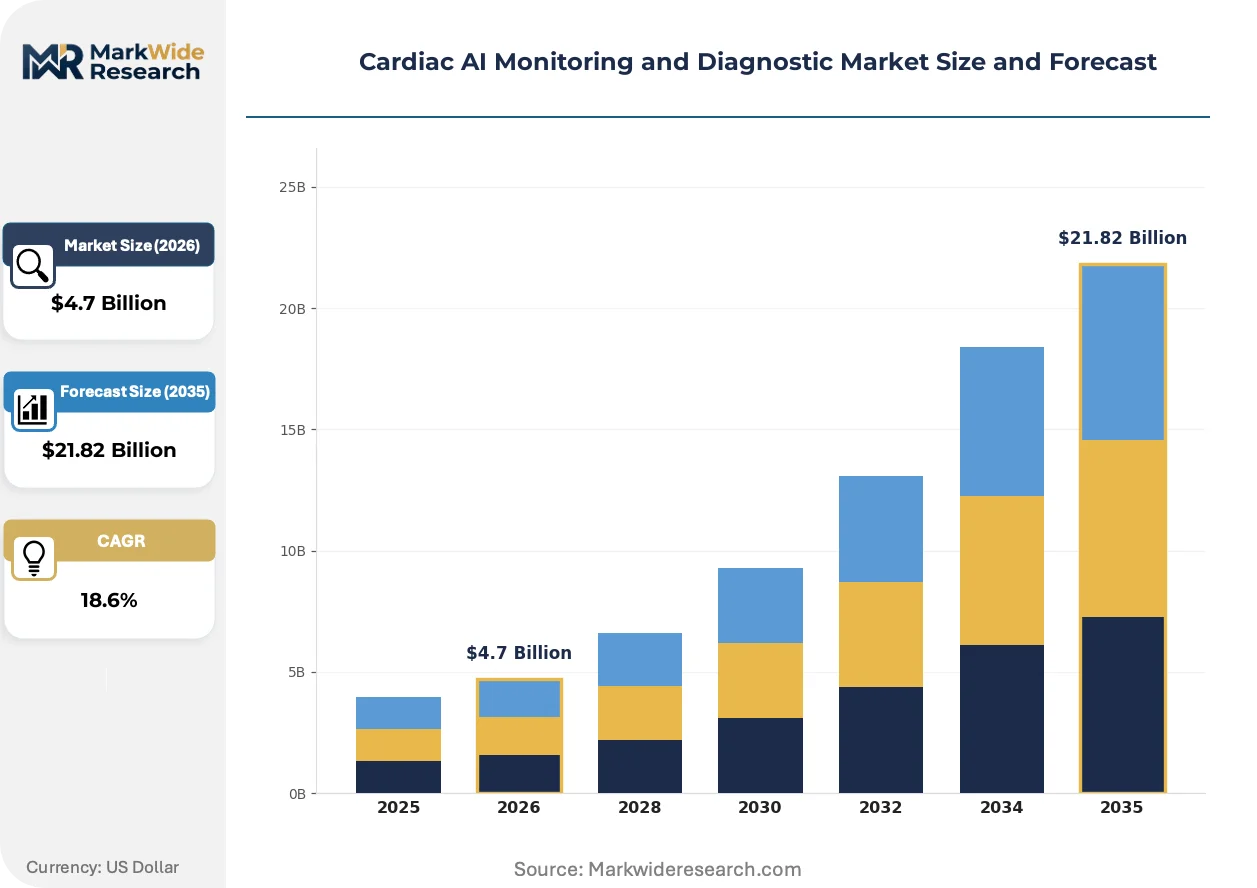
The cardiac AI monitoring and diagnostic market is reconfiguring around cloud-native telemetry architectures that displace traditional hardware-centric delivery models. Platform vendors now capture value through recurring analytics subscriptions rather than perpetual device licenses, compressing capital expenditure cycles for hospitals while expanding addressable patient populations beyond institutional boundaries.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated premarket review pathways compress commercialization timelines for arrhythmia detection algorithms, enabling earlier revenue recognition for developers targeting stroke prevention applications.
- Ambulatory Surgery Centers:Expansion of outpatient cardiac monitoring programs drives demand for portable AI-enabled ECG systems that integrate with electronic health record platforms without dedicated IT infrastructure.
- Photoplethysmography Signal Processing:Advances in PPG waveform interpretation enable consumer-grade wearables to achieve clinical-grade diagnostic accuracy, extending surveillance to pre-symptomatic populations.
Market Restraints
- GPU Compute Costs:Real-time inference on continuous telemetry streams requires specialized cloud infrastructure, creating margin pressure for vendors serving price-sensitive health systems in secondary markets.
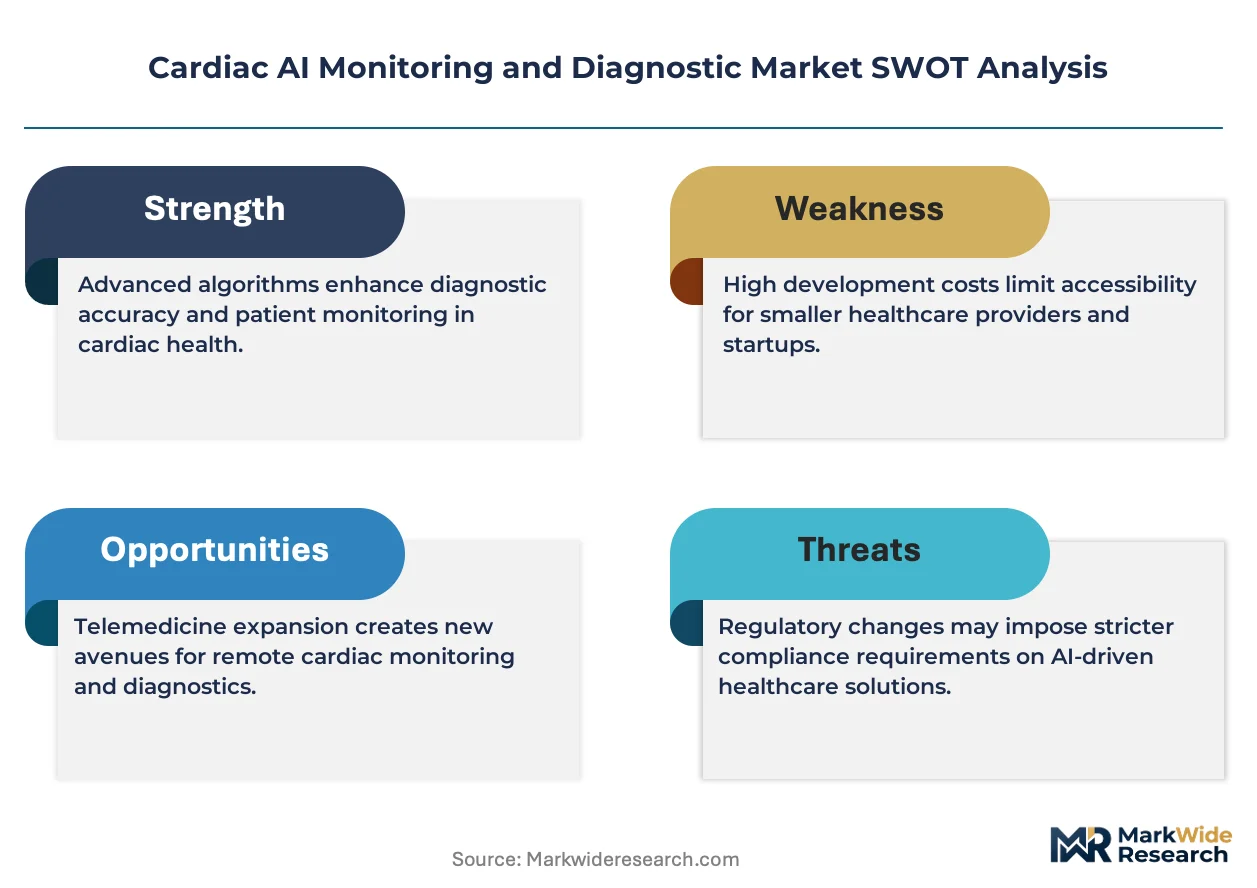
- EU MDR Compliance Burden:Clinical evidence requirements for CE marking under the Medical Device Regulation extend validation timelines and increase regulatory expenditure for algorithm developers without existing notified body relationships.
- Interoperability Fragmentation:Proprietary data formats across implantable device manufacturers limit seamless integration with third-party AI analytics platforms, constraining multi-vendor deployments.
Strategic Opportunities
- Rural Health Networks:Underserved regions in the United States present white space for remote cardiac monitoring programs that reduce specialist travel requirements and capture Medicaid reimbursement for telehealth interpretations.
- Predictive Risk Stratification:Machine learning models that forecast acute cardiac events before symptom onset command premium pricing from accountable care organizations seeking to reduce emergency department utilization.
- Federated Learning Architectures:Privacy-preserving model training across institutional boundaries without centralizing patient data addresses GDPR constraints while expanding training dataset scale.
Industry Challenges
- Electrophysiology Data Science Talent:Scarcity of specialists who combine cardiology domain expertise with signal processing and machine learning engineering constrains algorithm development velocity.
- HIPAA-GDPR Cross-Border Architecture:Cloud platforms transmitting patient-identifiable biomarkers between United States and European jurisdictions face complex compliance engineering requirements that extend deployment timelines.
- Legacy Device Integration:Retrofitting AI analytics layers onto decade-old implantable cardiac monitors with limited telemetry bandwidth requires expensive hardware gateway deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac AI Monitoring and Diagnostic Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Implantable Monitors, Mobile Health Apps, Cloud-Based Platforms End User: Cardiology Clinics, Home Care, Hospitals, Telehealth Providers Technology: Machine Learning, Deep Learning, Predictive Analytics, Signal Processing Application: Disease Diagnosis, Risk Assessment, Patient Monitoring, Data Analysis |
| Companies Covered | GE HealthCare, Siemens Healthineers, Koninklijke Philips N.V., Medtronic, Abbott Laboratories, Boston Scientific Corporation, iRhythm Technologies, HeartFlow, Viz.ai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac AI Monitoring and Diagnostic Market Trends and Innovations
Cardiac AI diagnostics are converging toward continuous, decentralized surveillance models that compress the interval between physiological anomaly and clinical intervention. Three developments are restructuring competitive positioning and value capture mechanisms.
Edge-computing inference engines embedded directly into wearable devices and implantable monitors are hybridizing traditional cloud-dependent architectures with local signal processing. Ambulatory monitoring vendors deploy these systems to reduce latency in critical arrhythmia alerts while minimizing cellular data transmission costs. This hybridization enables real-time patient notification without persistent connectivity, expanding viable use cases to remote geographies with intermittent network coverage.
The EU AI Act risk classification framework restructures clinical validation requirements for cardiac diagnostic algorithms deployed in European member states. High-risk system designations mandate conformity assessments that extend beyond existing MDR pathways, creating additional compliance expenditure for developers. Algorithm vendors serving European hospitals are responding by segregating product architectures to isolate AI components requiring enhanced documentation from standard software modules.
Hospital procurement departments are consolidating vendor relationships through enterprise-wide platform agreements that bundle hardware, software, and interpretation services under single-source contracts. This concentration displaces point-solution purchasing patterns that previously allowed best-of-breed algorithm selection. The shift is most visible in United States integrated delivery networks seeking to standardize telemetry workflows across dozens of affiliated facilities.
Cardiac AI Monitoring and Diagnostic Market Segmentation
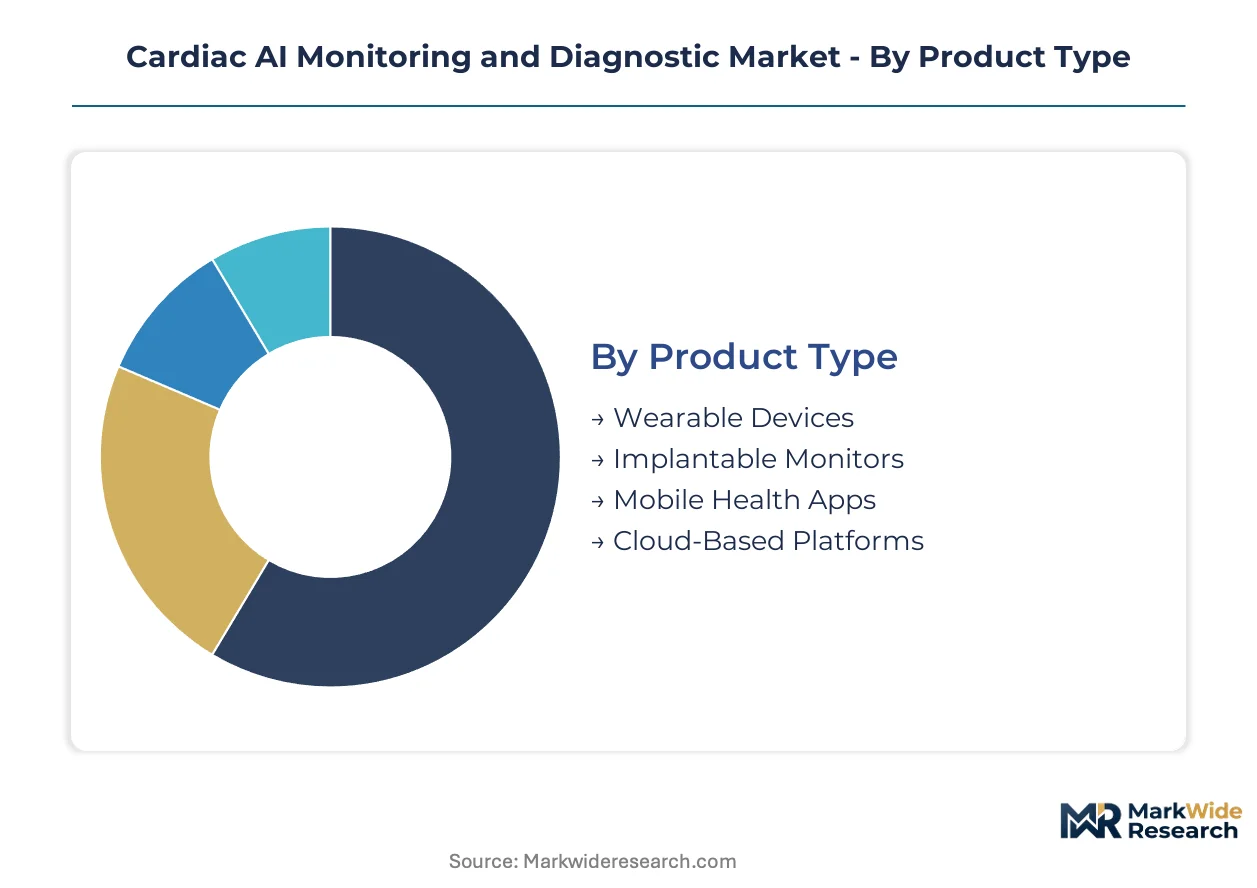
Product architecture and deployment context determine pricing power and recurring revenue potential in cardiac AI diagnostics. Vendors optimize margin profiles by matching technology sophistication to clinical setting requirements and reimbursement pathways.
Product Type:
Cost tier stratification separates capital-intensive implantable hardware from software-centric platforms with minimal marginal delivery costs.
- Cloud-Based Platforms:Multi-tenant architectures aggregate telemetry from dispersed devices into centralized analytics engines. United States integrated delivery networks favor these systems for enterprise standardization across affiliated hospitals, with subscription models compressing capital expenditure cycles.
- Wearable Devices:Consumer-grade and clinical-grade form factors process photoplethysmography and single-lead electrocardiography through embedded inference chips. Ambulatory monitoring programs in Germany drive demand for FDA-cleared and CE-marked units that integrate with electronic health record systems.
- Implantable Monitors:Subcutaneous devices with multi-year battery life transmit continuous rhythm data via cellular networks.
- Mobile Health Apps:Software interfaces display algorithmic interpretations and enable patient-clinician communication.
Cloud-based platforms command the established base. The steepest expansion runs through wearable devices.
End User:
Customer type determines purchasing authority, workflow integration complexity, and sensitivity to total cost of ownership.
- Hospitals:Acute care institutions deploy AI-enabled telemetry for inpatient arrhythmia surveillance and post-surgical monitoring. Japan's aging demographic pressures cardiac wards to adopt automated early warning systems that reduce nursing labor intensity.
- Telehealth Providers:Virtual care platforms leverage remote patient monitoring reimbursement codes to capture chronic disease management revenue. United States rural health networks deploy these services to extend specialist reach without physical infrastructure investment.
- Cardiology Clinics:Outpatient practices integrate AI diagnostics into existing electrophysiology workflows.
- Home Care:Post-acute and hospice settings prioritize patient comfort and caregiver usability over clinical feature depth.
Hospitals anchor current revenue concentration. Telehealth providers are gaining share fastest through reimbursement tailwinds.
Technology:
Application maturity separates deployed inference engines from emerging methodological approaches still accumulating validation evidence.
- Deep Learning:Convolutional and recurrent neural architectures process raw electrocardiographic waveforms without handcrafted feature engineering. Signal processing pipelines in echocardiography interpretation achieve diagnostic parity with specialist cardiologists at United States academic medical centers.
- Predictive Analytics:Time-series forecasting models stratify patient risk for acute cardiac events before symptom onset. Accountable care organizations in Germany absorb premium pricing for algorithms demonstrating emergency department utilization reduction.
- Machine Learning:Traditional supervised learning with engineered features dominates regulatory-cleared products.
- Signal Processing:Digital filtering and morphological analysis underpin real-time arrhythmia detection in legacy device firmware.
Deep learning commands the established base. Predictive analytics shows the steepest expansion trajectory.
Application:
Clinical utility determines reimbursement eligibility and pricing authority across diagnostic, prognostic, and operational use cases.
- Patient Monitoring:Continuous surveillance for physiological deterioration drives the largest addressable population. Ambulatory surgery centers in the United States deploy portable systems for outpatient procedural monitoring without dedicated cardiac telemetry infrastructure.
- Risk Assessment:Proactive identification of high-risk patients enables intervention timing optimization. Japanese insurers are piloting value-based contracts that reward predictive algorithm performance in stroke prevention.
- Disease Diagnosis:Algorithmic interpretation of specific pathologies supports clinical decision-making.
- Data Analysis:Retrospective population analytics inform quality improvement and research initiatives.
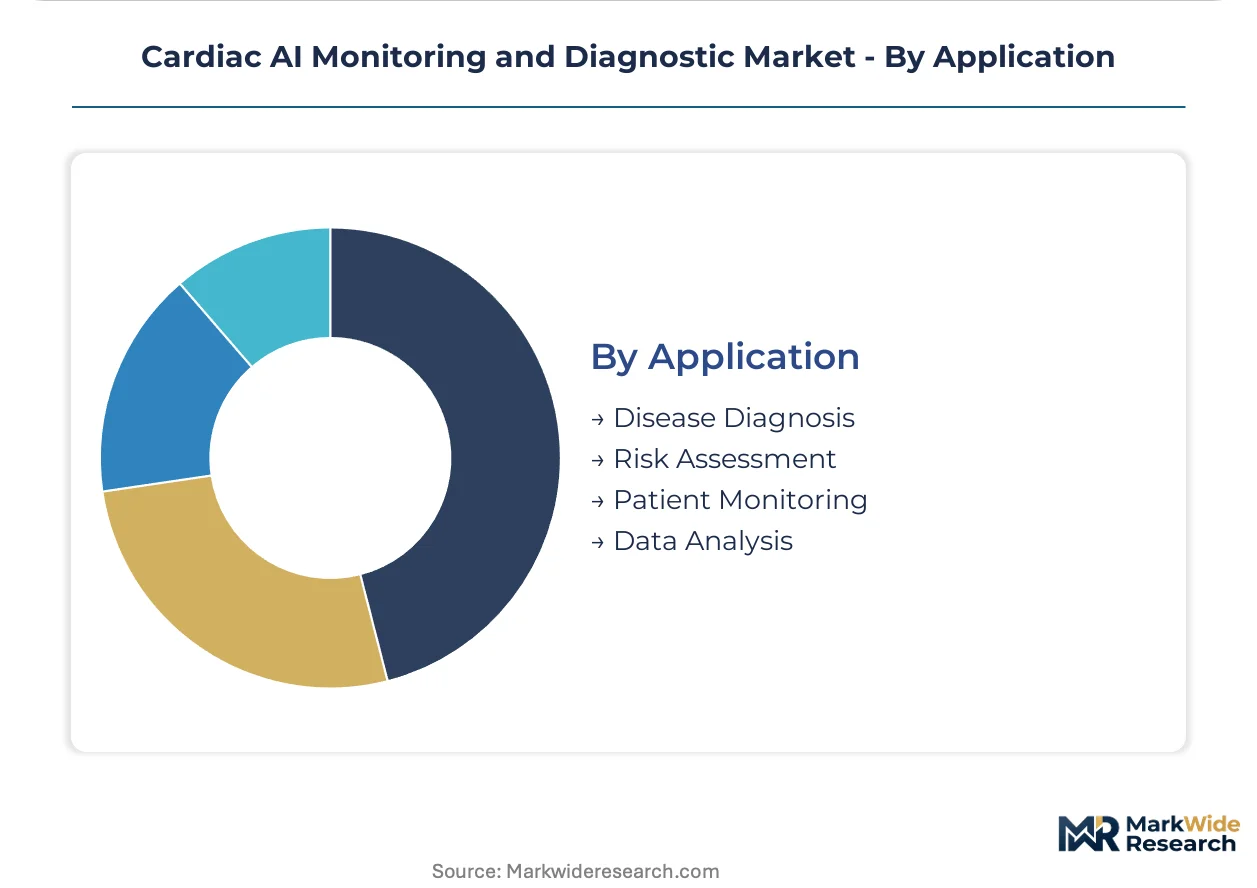
Patient monitoring commands the established base. Risk assessment climbs the fastest as payment models shift toward outcomes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States health systems absorb premium pricing for predictive algorithms, while secondary markets in Eastern Europe and Southeast Asia prioritize cost-minimized hardware bundles. Germany and Japan occupy intermediate positions where reimbursement maturity supports mid-tier platform licensing.
United States
FDA breakthrough device designations compress commercialization timelines for arrhythmia detection developers. Medicare reimbursement codes for remote patient monitoring create sustainable revenue streams for telehealth providers. The Boston-Cambridge corridor concentrates venture-backed AI diagnostics ventures targeting stroke prevention applications.
Germany
Accountable care organizations absorb premium pricing for emergency department utilization reduction algorithms. CE marking under MDR extends validation timelines but creates regulatory moats for established notified body relationships. The Munich-Stuttgart axis anchors Siemens Healthineers' echocardiography interpretation development pipelines.
Japan
Aging demographic pressures drive automated early warning system adoption in cardiac wards. PMDA streamlined review pathways accelerate algorithmic diagnostic approvals for geriatric populations. Tokyo-Osaka metropolitan corridors concentrate integrated delivery network procurement of wearable telemetry systems.
United Kingdom
NHS long-term plan targets shift from hospital-based to community cardiac surveillance. MHRA recognition of FDA-cleared algorithms enables accelerated UK market entry for US developers. London's digital health cluster hosts cloud-native platform vendors serving European telehealth expansion.
India
Price-sensitive secondary care markets prioritize cost-minimized PPG-enabled wearables over implantable hardware. CDSCO streamlined medical device regulations attract contract manufacturing for global cardiac AI hardware vendors. Hyderabad-Bengaluru corridor concentrates software engineering talent for signal processing algorithm development.
Cardiac AI Monitoring and Diagnostic Market Competitive Landscape
Capability concentration sits with pure-play algorithm vendors; scale advantage sits with integrated device manufacturers. The market structures around three tiers: imaging system incumbents bundling AI with hardware service contracts, telemetry specialists capturing recurring subscription value, and algorithm developers licensing inference engines to third-party platforms. Dominant competitive moves include strategic partnerships between wearable manufacturers and cloud analytics providers, plus geographic expansion through regulatory harmonization across FDA-CE marked product portfolios.
Among imaging system incumbents, GE HealthCare, Siemens Healthineers, and Koninklijke Philips N.V. exemplify divergent platform strategies. GE HealthCare leverages installed base density to bundle AI diagnostics with hardware service contracts. Siemens Healthineers anchors cardiac AI through deep learning pipelines interpreting multimodal cardiology data. Philips extends wearable and monitoring ecosystems into cloud-based analytics layers capturing recurring subscription value.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| iRhythm Technologies |
| HeartFlow |
| Viz.ai |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in cloud GPU infrastructure across United States hyperscale regions is compressing compute rental rates for cardiac AI inference workloads, enabling platform vendors to absorb margin pressure while maintaining aggressive SaaS pricing for hospital systems. This utilization dynamic rewards integrated device manufacturers with captive silicon supply, while pure-play algorithm developers face escalating pressure to bundle hardware or surrender pricing autonomy.
Pricing Analysis
After-sales revenue from multi-year analytics subscriptions and hardware service contracts drives lifetime value capture across the cardiac AI stack. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared predictive algorithms from CE-marked monitoring tools and unvalidated wellness applications. Cost compression in consumer-grade wearable tiers is intensifying because PPG sensor commoditization has collapsed hardware margins. Telehealth providers exhibit highest price sensitivity due to thin remote patient monitoring reimbursement, while integrated delivery networks absorb premium pricing for enterprise-wide platform standardization.
Supply Chain Analysis
Upstream feedstock concentration in Taiwan, South Korea, and the United States for advanced inference chips and MEMS sensors shapes vendor procurement vulnerability. Cloud-native cardiac AI platforms draw from specialized GPU foundry output, medical-grade PPG optical components, and cellular telemetry modules. Single-source vulnerability in 5nm silicon supply creates exposure for algorithm developers without diversified hardware partnerships. Distribution runs through direct enterprise sales to hospital procurement committees, with emerging channel compression via GPO contracts and integrated delivery network master agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiac AI diagnostics presents a fragmentation opportunity as ambulatory monitoring demand splinters across hospital, telehealth, and direct-to-consumer channels, creating specialist niches that defy consolidation by imaging incumbents.
For Market Incumbents: Harden regulatory moats through accelerated FDA breakthrough device submissions for stroke prevention algorithms, insulating against pure-play entrants. Deepen backward integration into edge-computing silicon design to reduce cloud inference dependency and capture hardware margin. Prioritize enterprise platform agreements that bundle telemetry hardware with exclusive analytics subscriptions, constraining hospital procurement flexibility.
For New Entrants and Emerging Players: Build out federated learning infrastructure serving European accountable care organizations constrained by GDPR data localization requirements, exploiting compliance complexity that incumbents underinvest in. Target rural United States health networks lacking electrophysiology specialist coverage, where Medicaid telehealth reimbursement creates sustainable revenue without competing for urban hospital contracts. Lead with predictive risk stratification algorithms that demonstrate emergency department utilization reduction, securing value-based payment pilot participation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform vendors with hospital system integration depth and multi-year SaaS contracts, positioning these archetypes for premium multiples. Long-term viability rests on regulatory clearance velocity and reimbursement code capture rather than algorithmic performance alone. Acquisition focus should center on electrophysiology data science teams with combined cardiology domain expertise and signal processing engineering. The signal to monitor is FDA breakthrough device designation momentum as an inflection indicator for commercialization timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated premarket review compresses commercialization timelines for stroke prevention algorithms targeting atrial fibrillation detection. |
| Hospital System Partnership | Enterprise platform agreements with United States integrated delivery networks standardize telemetry workflows across dozens of affiliated facilities. |
| CE Marking Pathway | MDR conformity assessment under EU AI Act high-risk classification creates regulatory moats for established notified body relationships. |
| Software Companion Development | Mobile health interfaces enabling patient-clinician communication capture recurring subscription value beyond hardware sales. |
| Reimbursement Strategy | Medicare remote patient monitoring code optimization sustains telehealth provider revenue streams without episodic visit dependency. |
Research Methodology
Initial hypotheses were tested against primary input from electrophysiology clinicians, hospital purchasing committee chairs, biomedical engineers at device manufacturers, and GPO contracts managers, then refined against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and CE marking notifications under MDR. Bottom-up patient volume modeling across ambulatory monitoring segments was triangulated with top-down platform revenue estimates from disclosed subscription metrics.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product architecture, end-user setting, technology maturity, and clinical application. Deployment model variations between cloud-native and edge-computing inference were modeled alongside organization size tiers and regional regulatory clusters. CAGRs were derived from installed base expansion rates and per-patient analytics revenue trajectories, incorporating PPG sensor cost curves and GPU compute rental rate forecasts as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by cloud hyperscalers into healthcare-specific silicon would shift outcomes materially. Cross-checking against disclosed hospital capital expenditure plans and telehealth provider funding rounds is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Global Smart Hospital Market
Digital Health Solutions
Patient Engagement Technology Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
VR in Healthcare Market
Digital Health Solutions
US Patient Engagement Solutions Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
Distance Health Technologies Market
Digital Health Solutions
Pharmacovigilance (PV) and Drug Safety Software Market
Digital Health Solutions
Healthcare Navigation Platform Market
Digital Health Solutions
Care Coordination Software Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
Global Mhealth Solutions Market
Digital Health Solutions
Pregnancy Tracking and Postpartum Care Apps Market