
 Medical Bags Market | 2026-2036
Medical Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Bags Market Outlook
The EU Green Deal is pivoting medical device procurement toward lower-carbon polymer supply chains, compelling manufacturers to requalify resin streams. Baxter International leverages captive ethylene-vinyl acetate compounding to secure film consistency for IV bags across European tenders. Fresenius Medical Care anchors its position through vertically integrated blow-fill-seal capacity serving dialysis fluid pouch demand. B. Braun Melsungen AG competes on PVC-free alternative platforms, differentiating within German hospital system contracts.
Medical bags are sterile, flexible containers fabricated from extruded polymer films or rubber laminates, designed to store, transport, or administer fluids, biological specimens, or pharmaceuticals while maintaining barrier integrity against oxygen, moisture, and microbial ingress. IV bags fabricated from multilayer polypropylene dominate hospital fluid management volumes, reflecting mature demand with stable margin pools in high-volume tenders. Blood bags manufactured with phthalate-free PVC formulations represent a faster-growing material trajectory, as European and Asian regulators restrict plasticizer migration thresholds. Home care drug delivery applications are expanding fastest among end users, driven by ambulatory infusion protocols that shift treatment from clinical settings to patient residences.
The FDA enforces biocompatibility standards under ISO 10993 for polymer contact surfaces, while the EMA coordinates with notified bodies to implement MDR technical documentation requirements for single-use medical containers. The EPA regulates ethylene oxide sterilization residuals, constraining terminal sterilization options for manufacturers reliant on traditional processes. Stakeholders must monitor evolving polymer recycling mandates and sterilization modality transitions to preserve market access across divergent regulatory jurisdictions.
Market Dynamics
The EU MDR's biocompatibility documentation requirements are forcing polymer requalification across medical bag supply chains, compressing time-to-market for new resin formulations while elevating compliance costs for manufacturers serving European hospital tenders.
Growth Catalysts
- Home Care Infusion Protocols:Ambulatory chemotherapy and antibiotic regimens are migrating from hospital wards to patient residences, expanding demand for portable, closed-system IV bags with integrated flow control.
- REACH Phthalate Restrictions:The European Chemicals Agency's tightening migration thresholds for DEHP plasticizers is accelerating hospital procurement of PVC-free blood bag alternatives.
- German Hospital Consolidation:Procurement centralization within Germany's hospital alliance networks is standardizing bag specifications across multi-site tenders, favoring suppliers with validated high-volume production lines.
Market Restraints
- Ethylene Oxide Sterilization Constraints:EPA residual limits on EtO emissions are constraining terminal sterilization capacity, forcing manufacturers toward gamma or electron-beam alternatives with higher capital requirements.
- Specialty Resin Concentration:Medical-grade EVA and multilayer polypropylene supply concentrates among three European compounders, exposing bag manufacturers to input price volatility and allocation risk.
- Barrier Performance Trade-offs:PVC-free alternatives exhibit inferior oxygen barrier properties versus legacy formulations, limiting shelf-life extension for sensitive biologics.
Strategic Opportunities
- Indian Dialysis Expansion:The country's PLI scheme for medical devices is incentivizing domestic blow-fill-seel capacity for dialysis fluid pouches, creating localization partnerships for European equipment suppliers.
- Closed-Loop Recycling Mandates:The EU Green Deal's packaging waste directives are creating first-mover advantage for bag manufacturers with validated post-industrial resin streams and mass-balance certification.
- Wearable Pump Integration:Convergence between flexible bag reservoirs and miniaturized ambulatory infusion pumps is opening design partnerships with diabetes and pain management device developers.
Industry Challenges
- Polymer Science Talent Scarcity:Formulation chemists with medical-grade extrusion expertise are concentrated among incumbent suppliers, constraining R&D scaling for mid-tier competitors.
- MDR Technical Documentation Burden:Single-use container notified body reviews are extending 12-18 months, compressing product refresh cycles and freezing specification changes mid-tender.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Bags Market |
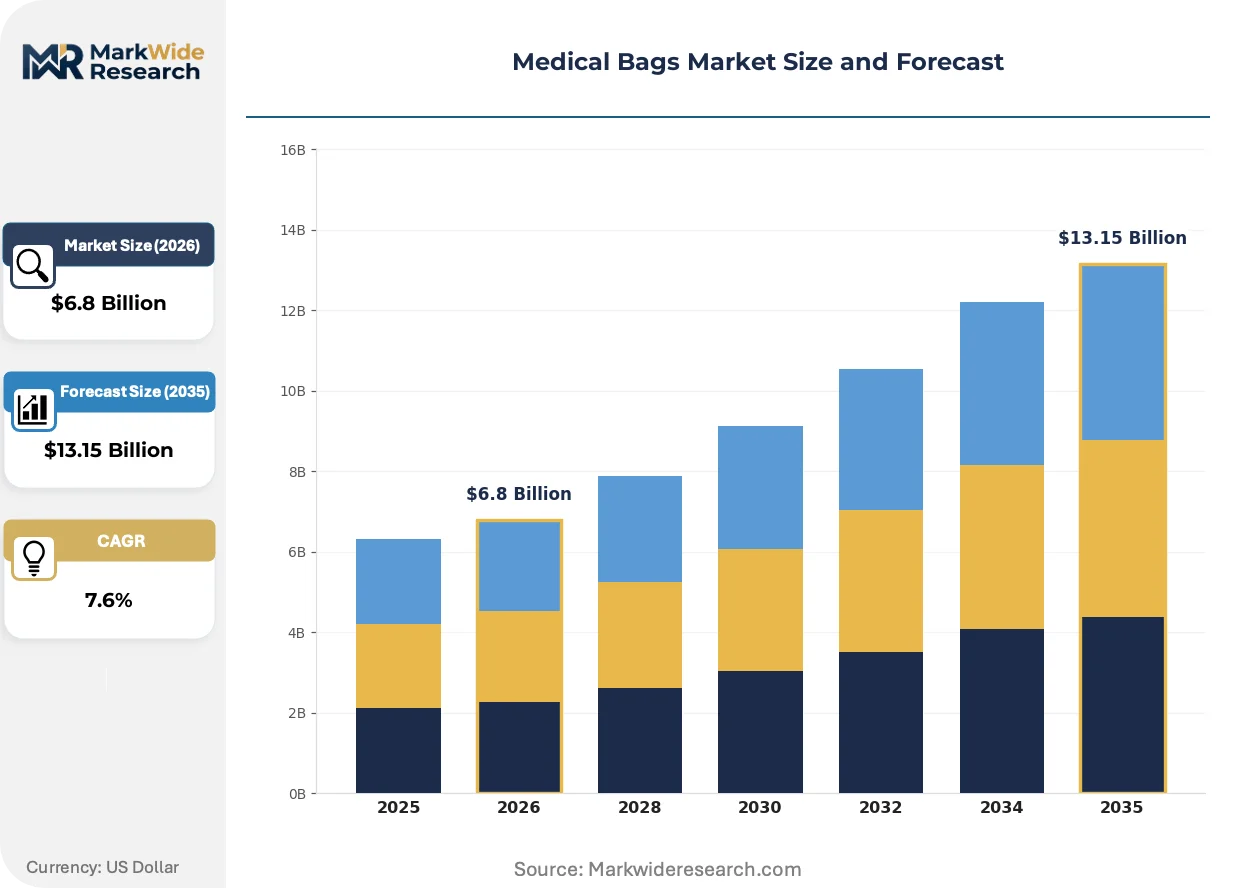
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IV Bags, Blood Bags, Surgical Bags, Diagnostic Bags Material: Polyethylene, Polypropylene, PVC, Rubber End User: Hospitals, Clinics, Home Care, Laboratories Application: Fluid Management, Sample Collection, Drug Delivery, Waste Disposal |
| Companies Covered | Baxter International Inc., B. Braun Melsungen AG, Fresenius Medical Care AG & Co. KGaA, Terumo Corporation, Hollister Incorporated, Coloplast A/S, ConvaTec Inc., ICU Medical Inc., Macopharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Bags Market Strategic Shifts
Material science advances and sterilization modality transitions are redefining competitive positioning in medical bag manufacturing, with sustainability credentials and integrated drug-device compatibility emerging as primary differentiation vectors.
Multilayer coextrusion technology is converging with active barrier coatings to produce IV bags with tunable oxygen and moisture transmission rates. Oncology and parenteral nutrition formulators are adopting these platforms to extend protein stability without refrigerated distribution. The structural consequence is compressing the addressable market for rigid glass alternatives in ambulatory settings.
The EU MDR's single-use device technical documentation requirements are mandating exhaustive polymer biocompatibility testing under ISO 10993-18. Manufacturers must now characterize extractables and leachables across accelerated aging protocols before notified body submission. Blood bag producers serving European tenders are responding by pre-qualifying alternative plasticizers and accelerating PVC-free platform validation.
Hospital procurement alliances are consolidating vendor panels and unbundling after-sales technical support from unit pricing. German and French hospital networks are shifting toward multi-year framework agreements with embedded volume commitments and penalty clauses for specification non-compliance. This concentration is most visible in central pharmacy operations where standardization reduces compounding error risk.
Medical Bags Market Segmentation
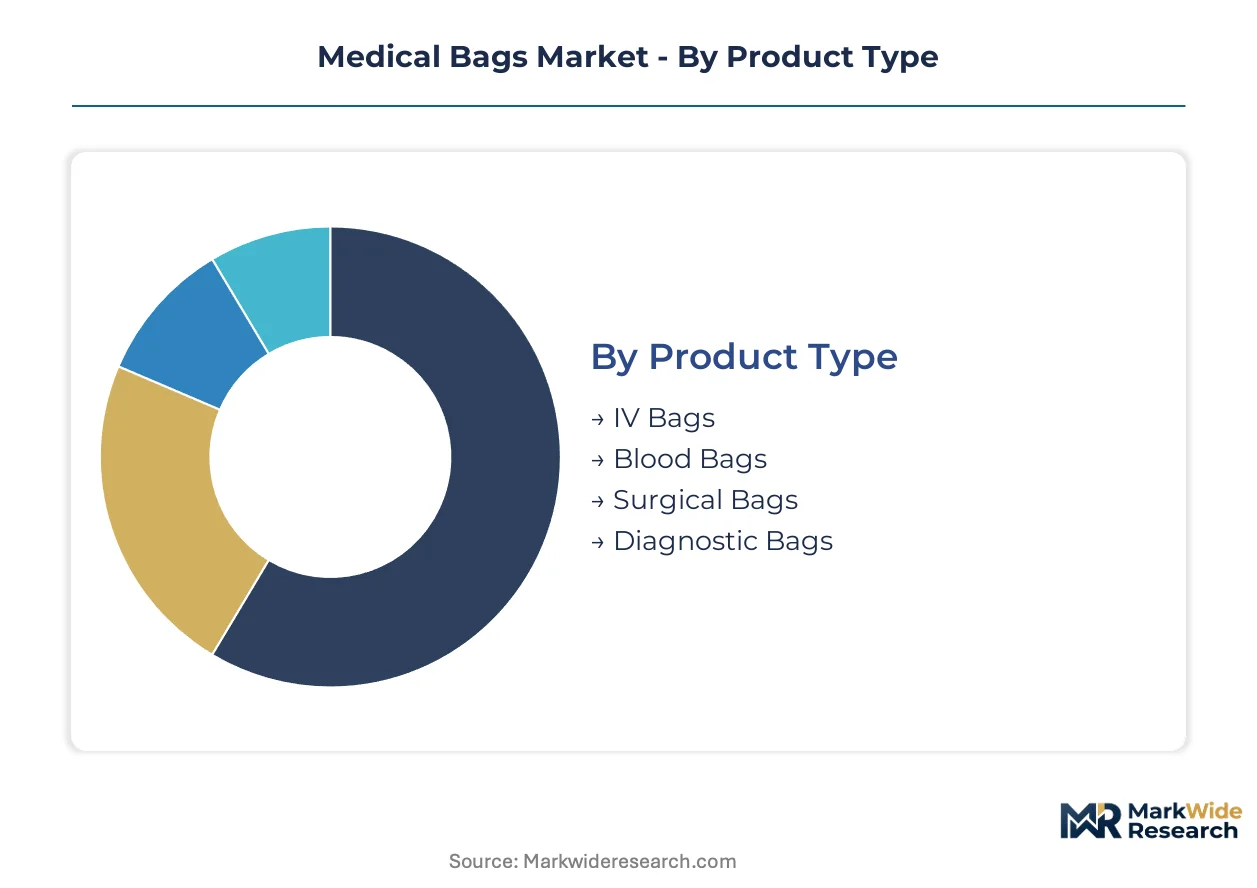
Medical bag procurement decisions diverge sharply across clinical settings, with sterilization requirements, barrier specifications, and ambulatory compatibility driving specification fragmentation. Manufacturers must align resin selection and film architecture to distinct performance thresholds rather than pursuing universal platform designs.
Product Type:
Hospital procurement teams prioritize barrier integrity and closed-system compatibility when selecting bag formats for their formulary.
- IV Bags:Multilayer polypropylene films with ethylene-vinyl acetate seals dominate high-volume tenders. German hospital alliances standardize on these platforms for central pharmacy operations, compressing supplier panels to validated high-throughput manufacturers.
- Blood Bags:Phthalate-free PVC formulations with DEHP alternatives are gaining procurement share as ECHA migration thresholds tighten. European tenders now require extractables documentation under ISO 10993-18, extending validation timelines.
- Surgical Bags:Sterile pouches for instrument containment use Tyvek-laminated structures.
- Diagnostic Bags:Specimen transport containers with leak-resistant closures serve laboratory networks.
Volume sits with IV Bags; growth tilts toward Blood Bags.
Material:
Resin selection determines regulatory pathway, sterilization modality, and recycling eligibility across European tenders.
- Polypropylene:Biaxially oriented and cast films provide moisture barriers for parenteral nutrition. Oncology formulators specify these for protein stability without cold chain requirements.
- Polyethylene:Low-density grades offer cost positioning for high-volume fluid management. Home care infusion systems specify these for disposable reservoir economics.
- PVC:Legacy blood bag material facing substitution pressure from REACH restrictions.
- Rubber:Natural and synthetic laminates serve specialty pharmaceutical containment.
Polypropylene commands current procurement volumes; polyethylene is climbing the fastest as home care protocols expand.
End User:
Clinical setting dictates sterility assurance level, connectivity requirements, and patient handling protocols.
- Hospitals:Central pharmacy and ward-level consumption drives bulk tender structures. German hospital consolidation into purchasing alliances standardizes specifications across multi-site networks.
- Home Care:Ambulatory infusion pumps require lightweight, flexible reservoirs with integrated flow control. Patient residence administration is expanding most quickly as chemotherapy and antibiotic protocols migrate from clinical settings.
- Clinics:Outpatient facilities prioritize cost-efficient standardization.
- Laboratories:Diagnostic workflows demand leak-proof specimen containment.
Hospitals anchor installed demand; home care represents the steepest expansion trajectory.
Application:
Functional use case determines barrier specification, closure design, and regulatory classification intensity.
- Fluid Management:IV and irrigation solutions require oxygen and moisture barriers. Parenteral nutrition formulators specify multilayer coextrusion with active barrier coatings to extend shelf life.
- Drug Delivery:Closed-system transfer devices and ambulatory pump compatibility drive integrated design requirements. Diabetes and pain management device developers seek flexible reservoir partnerships.
- Sample Collection:Diagnostic workflows demand sterile, leak-resistant containment.
- Waste Disposal:Biohazard and chemotherapy waste bags use puncture-resistant films.
Fluid Management holds current volume concentration; drug delivery is gaining share fastest through device convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of medical-grade polymer films concentrates in Germany and the United States, while consumption patterns diverge across hospital procurement alliances and expanding home care networks. The EU MDR is compressing cross-border supply flexibility, forcing regional qualification of resin streams.
United States
Hospital consolidation into IDN purchasing networks is standardizing IV bag specifications across multi-state systems. The FDA enforces ISO 10993 biocompatibility documentation for polymer contact surfaces, extending validation timelines for new resin introductions. Minnesota and Massachusetts host concentrated medical device manufacturing clusters where blow-fill-seal capacity serves parenteral nutrition demand.
Germany
Hospital alliance procurement centralization is compressing supplier panels for blood bag tenders. The EU MDR requires exhaustive extractables and leachables characterization under ISO 10993-18 before notified body submission. Hessen and Baden-Württemberg anchor polymer compounding and film extrusion capacity serving European fluid management demand.
India
The PLI scheme for medical devices is incentivizing domestic blow-fill-seal capacity for dialysis fluid pouches. CDSCO alignment with ISO standards is streamlining import substitution pathways for polymer-based containers. Gujarat and Karnataka are emerging as manufacturing hubs where European equipment suppliers pursue localization partnerships.
Japan
Aging demographics are accelerating home care infusion protocol adoption, expanding demand for portable reservoir systems. PMDA maintains stringent polymer biocompatibility requirements that parallel FDA standards, limiting rapid resin substitution. The Kansai region around Osaka hosts specialized medical film extrusion capacity serving domestic pharmaceutical packaging demand.
China
Centralized hospital procurement reforms are standardizing IV bag specifications across provincial health systems. NMPA implementation of GB standards for medical plastics is elevating compliance thresholds for domestic manufacturers. The Yangtze River Delta concentrates multilayer film coextrusion capacity serving both domestic consumption and export markets.
Medical Bags Market Competitive Environment
The competitive structure tilts toward vertically integrated polymer compounders with captive resin qualification capabilities. Tier-one manufacturers maintain in-house ethylene-vinyl acetate compounding and blow-fill-seal capacity, while mid-tier competitors rely on external resin supply exposing them to allocation risk. Three strategic archetypes dominate: integrated polymer-to-device manufacturers, specialized blood bag producers with phthalate-free platforms, and regional fabricators serving localized tenders. Capacity expansion and M&A consolidation represent the dominant competitive vectors as procurement alliances compress vendor panels.
Among integrated manufacturers, Baxter International Inc., Fresenius Medical Care AG & Co. KGaA, and B. Braun Melsungen AG exemplify distinct strategic positions. Baxter represents the archetype of captive polymer compounding securing film consistency across European tenders. Fresenius occupies a position anchored by vertically integrated capacity serving dialysis fluid pouch demand. B. Braun sits within the PVC-free alternative platform segment, differentiating within German hospital system contracts where REACH phthalate restrictions tighten.
| Leading Market Players |
|---|
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Fresenius Medical Care AG & Co. KGaA |
| Terumo Corporation |
| Hollister Incorporated |
| Coloplast A/S |
| ConvaTec Inc. |
| ICU Medical Inc. |
| Macopharma |
| Others |
Value Chain & Pricing Dynamics
Ethylene-vinyl acetate resin indices cascade through medical bag manufacturing into three distinct procurement tiers. Hospital alliance contracts in Germany anchor premium pricing for multilayer polypropylene platforms with full MDR documentation, while mid-tier suppliers compete on phthalate-free PVC alternatives under REACH pressure, and regional fabricators absorb commodity polyethylene spot volatility for home care disposables.
Pricing Analysis
Outcome-linked pricing tied to sterilization assurance levels anchors hospital procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels separates MDR-validated multilayer platforms from REACH-compliant alternatives and basic polyethylene reservoirs. Cost compression in the standard tier is intensifying because ECHA extractables documentation extends validation timelines. Home care distributors exhibit highest price sensitivity; German hospital alliances prioritize specification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from German hospital procurement alliances compel manufacturers to qualify resin streams across multiple compounders. Medical-grade EVA and multilayer polypropylene supply concentrates in Germany, Belgium, and the Netherlands, exposing bag fabricators to allocation risk during polymer production outages. Raw material sourcing draws from ethylene feedstock, vinyl acetate monomer, and specialty adhesive layers. Single-source vulnerability concentrates in ethylene-vinyl acetate compounding capacity. Distribution runs through GPO contracts and direct hospital alliance frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU MDR technical documentation burdens force sub-scale competitors toward exit or acquisition. Procurement alliance concentration in Germany compresses vendor panels to validated high-throughput manufacturers with captive resin capabilities.
For Market Incumbents: Anchor polymer qualification capabilities through backward integration into medical-grade compounding or exclusive offtake agreements with European resin suppliers. Defend German hospital alliance contracts by accelerating PVC-free platform validation ahead of REACH phthalate deadline tightening. Prioritize blow-fill-seal capacity expansion in Hessen and Baden-Württemberg to serve centralized pharmacy tender consolidation. For New Entrants and Emerging Players: Mid-tier Indian dialysis clinics represent the most penetrable buyer archetype as PLI scheme incentives localize blow-fill-seal capacity for fluid pouches. Pursue equipment supply partnerships with Gujarat and Karnataka manufacturing hubs rather than direct bag fabrication entry. Target home care infusion pump developers seeking flexible reservoir design collaborations for ambulatory chemotherapy protocols. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized blood bag producers with validated phthalate-free platforms in Western Europe. Long-term viability over the projection horizon rests on MDR notified body relationship depth and hospital alliance contract tenure. Monitor ECHA migration threshold revision announcements as the signal indicating accelerated substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Notified body pre-submission meetings with German hospitals compress time-to-tender. |
| Phthalate-Free Platform Validation | REACH-compliant DEHP alternatives secure procurement share in European blood bag tenders. |
| Blow-Fill-Seal Capacity Expansion | Vertically integrated capacity in Hessen serves German hospital alliance fluid management demand. |
| Indian Localization Partnership | PLI scheme alignment with Gujarat manufacturers creates dialysis pouch supply access. |
| Closed-Loop Recycling Certification | EU Green Deal mass-balance credentials differentiate bids in French hospital sustainability frameworks. |
Study Parameters
Regulatory filings, hospital procurement databases, and polymer trade data formed the secondary backbone for this analysis. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and polymer compounding technical directors combined with secondary validation across EMA MDR guidance documents, ECHA REACH restriction dossiers, and ISO 10993 biocompatibility standards. Bottom-up and top-down triangulation reconciled manufacturer capacity disclosures with tender award patterns.
Bottom-up modeling anchored volume projections while top-down demand calibration validated segment trajectories across the analysis window. Segmentation dimensions included product type, material formulation, end-user setting, and regional regulatory cluster complexity. CAGRs were derived from polynomial trend fitting to historical tender volumes and sterilization modality transition rates. Forecast inputs incorporated EU MDR implementation timelines and REACH phthalate restriction phase-out schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA migration threshold revisions and EtO sterilization capacity constraints. Forecasts reflect assumptions regarding polymer resin price stability and notified body review timeline normalization. Deviation in EU MDR single-use device classification interpretation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Anaesthesia Conduction Kits Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Medical Shoe Covers Market
Medical Supplies
Asia-Pacific Human Fibrin Glue Market
Medical Supplies
North America Medical Clothing Market
Medical Supplies
Global Syringes and Needles Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Ostomy Care Market
Medical Supplies
United States Face Mask Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Push-In Plug Vials Market