
 UK Mental Health Apps Market | 2026-2036
UK Mental Health Apps Market Size, Share, and Industry Trends Forecast 2026-2036
UK Mental Health Apps Market Insights
Subscription-based financing and NHS partnership leasing models is reconfiguring competitive entry barriers for smaller developers. Headspace Inc. leverages its employer wellness channel relationships to sustain recurring revenue streams beyond direct-to-consumer sales. Woebot Health anchors its position through clinical trial partnerships with UK academic medical centers. Calm competes aggressively on brand recognition and content library breadth across sleep and anxiety verticals.
Mental health apps are software applications designed for smartphones, tablets, and wearable devices that deliver psychological interventions, mood monitoring, and behavioral coaching through structured user interfaces and algorithmic personalization engines, typically requiring clinical validation evidence for NHS reimbursement eligibility. Their primary commercial purpose is to extend mental health service capacity beyond constrained face-to-face clinical settings. Cognitive Behavioral Therapy applications command premium positioning due to structured diagnostic alignment and insurer willingness to reimburse evidence-based protocols. Subscription monetization models concentrate margin pools through predictable recurring revenue, while freemium structures dominate user acquisition but face conversion rate ceilings in cost-sensitive segments.
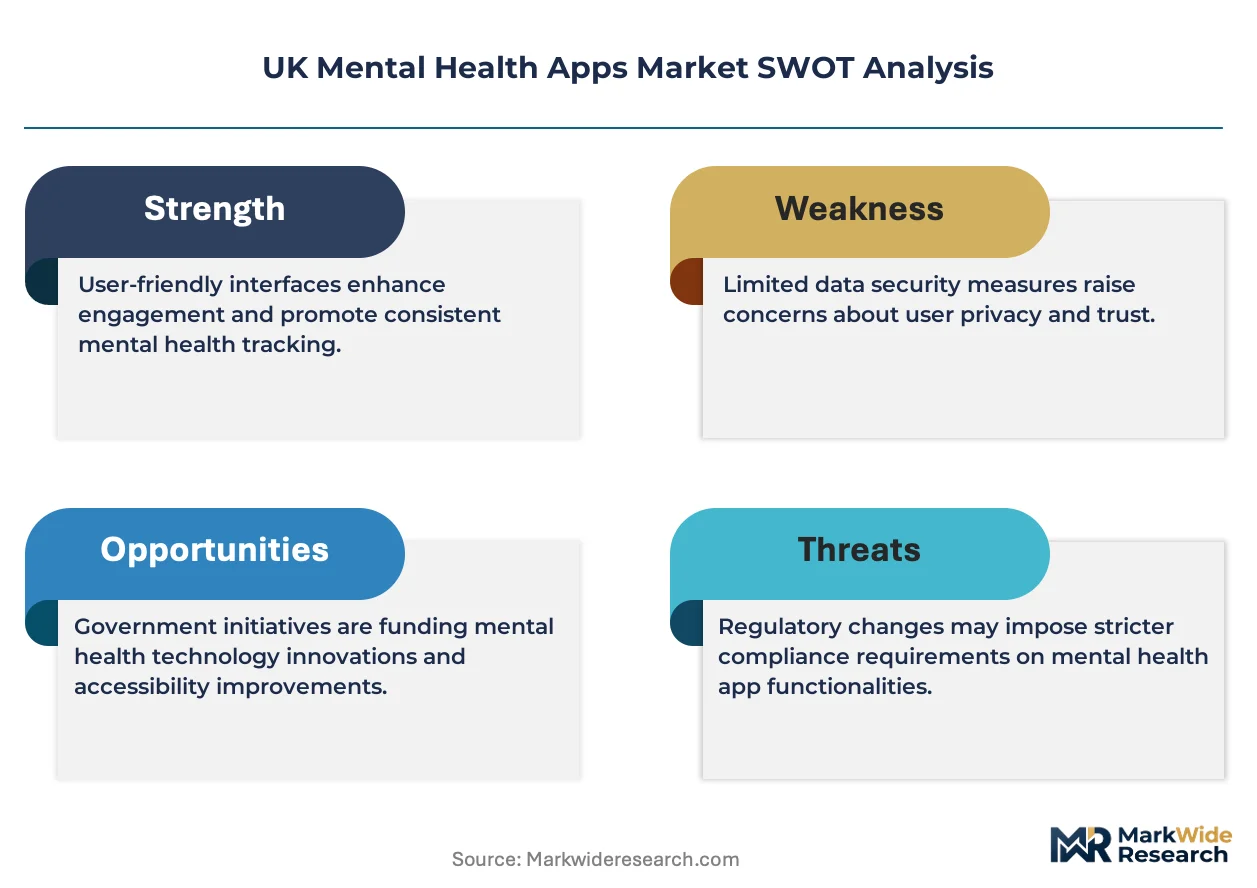
The Medicines and Healthcare products Regulatory Agency software-as-medical-device framework and NHS Digital Technology Assessment Criteria govern market access pathways, with compliance costs filtering out undercapitalized entrants. The National Institute for Health and Care Excellence digital health evidence standards shape product development priorities toward randomized controlled trial data generation. Stakeholders must monitor evolving MHRA guidance on artificial intelligence-driven therapeutic content to anticipate which product architectures will retain reimbursement eligibility.
Market Dynamics
NHS Integrated Care Boards are accelerating digital mental health referrals, compressing procurement cycles for app-based interventions while MHRA software-as-medical-device compliance costs filter market entry.
Growth Catalysts
- NHS Digital Technology Assessment Criteria:Standardized evidence requirements reduce buyer evaluation friction for validated applications. ICB procurement teams reference DTAC scoring to fast-track reimbursement approvals.
- Cognitive Behavioral Therapy protocols:Structured diagnostic alignment with NICE guidelines unlocks insurer willingness to reimburse evidence-based digital interventions. Clinical validation investments yield direct revenue pathway security.
- Greater London infrastructure concentration:Digital health maturity and clinician familiarity with remote tools create reference site density that accelerates regional adoption cascades.
Market Restraints
- MHRA SaMD compliance costs:Clinical validation and quality management system investments impose six-figure barriers that exclude undercapitalized developers from NHS reimbursement pathways.
- Conversion rate ceilings:Freemium user acquisition models face structural limits in cost-sensitive segments where discretionary health spending competes with essential consumption.
- Algorithmic content liability:Evolving MHRA guidance on artificial intelligence-driven therapeutic outputs creates regulatory uncertainty that extends product development timelines.
Strategic Opportunities
- Integrated Care Board partnership leasing:Subscription-based financing models reconfigure competitive entry by replacing upfront license fees with recurring operational expenditure structures.
- Employer wellness channel expansion:Corporate mental health benefits procurement represents underpenetrated B2B demand outside NHS reimbursement dependency.
- Wearable device convergence:Biometric data integration from Apple Watch and Fitbit ecosystems enables passive mood monitoring that differentiates premium positioning.
Industry Challenges
- Randomized controlled trial generation:NICE digital health evidence standards demand expensive academic medical center partnerships that strain mid-cap developer balance sheets.
- Interoperability with NHS electronic health records:Integration complexity with legacy EMR systems extends implementation timelines and inflates professional services requirements.
- Clinical workforce digital literacy:Practitioner training gaps in app-based intervention supervision limit effective deployment at point of care.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Mental Health Apps Market |
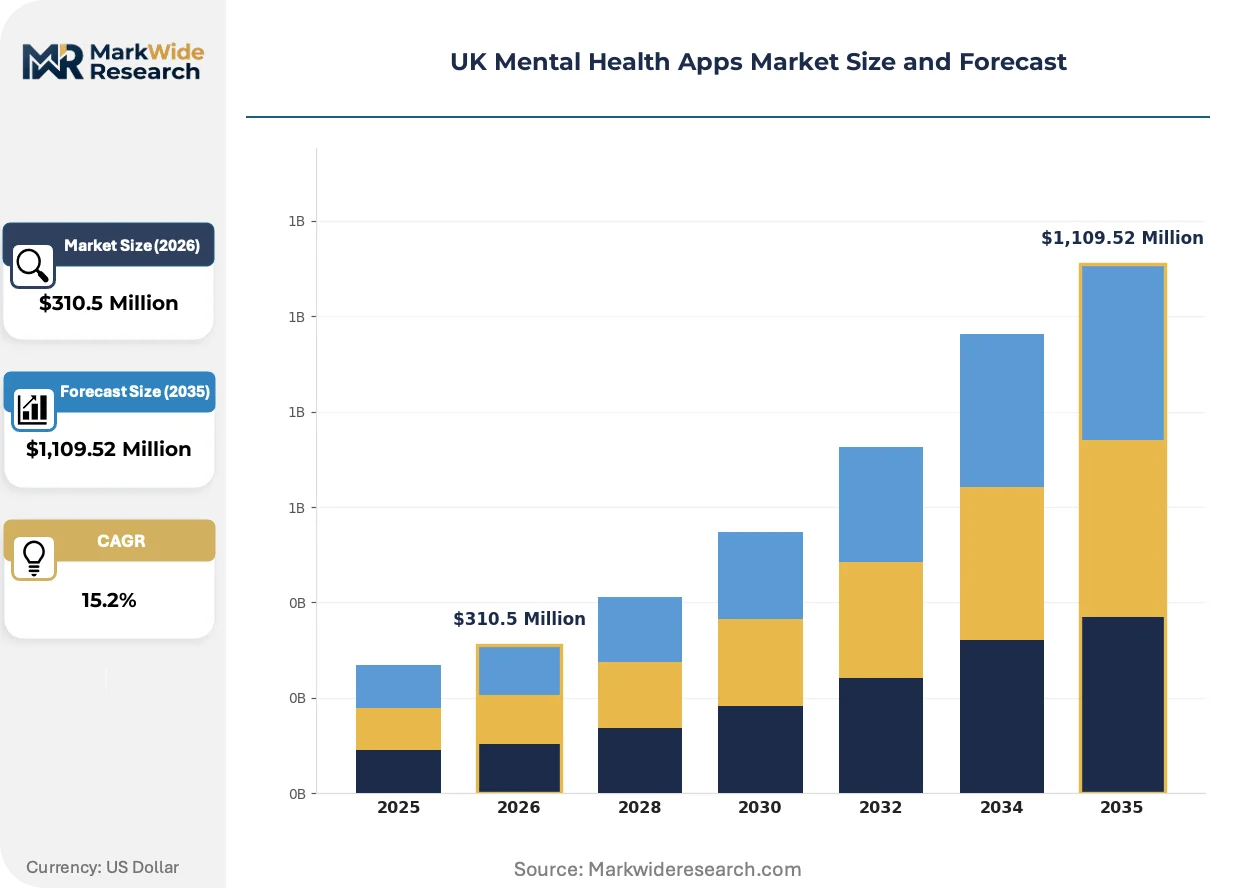
| Market Size in 2026 | $310.5 Million |
| Market Size in 2035 | $1,109.52 Million |
| CAGR (2026 – 2036) | 15.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Stress Management, Mood Tracking, Cognitive Behavioral Therapy, Meditation Assistance, Sleep Improvement Platform: iOS, Android, Web-Based, Wearable Integration, Desktop Support User Type: Adults, Adolescents, Seniors, Caregivers, Mental Health Professionals Monetization Model: Freemium, Subscription, One-Time Purchase, In-App Advertising, Sponsorship |
| Companies Covered | Youper, Inc., Mindscape, Headspace Inc., Woebot Health, MoodMission Pty Ltd., Calm, Sanvello Health, BetterHelp, Wysa AI, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Mental Health Apps Market Trends and Innovations
Algorithmic personalization engines are restructuring how psychological interventions adapt to individual user trajectories, compressing the gap between standardized protocols and tailored therapeutic delivery.
Natural language processing paired with conversational agents is digitizing the triage and cognitive restructuring functions historically performed by human therapists. NHS Talking Therapies services are piloting these tools to extend capacity without proportional workforce expansion. The structural consequence is a compression of per-patient service delivery costs while maintaining clinical outcome accountability through DTAC-mandated evidence thresholds.
The Medicines and Healthcare products Regulatory Agency's evolving software-as-medical-device guidance is mandating quality management systems for algorithmic therapeutic content. Developers must now document risk classification and clinical validation pathways before market access. Cognitive Behavioral Therapy applications face the steepest compliance burden given their diagnostic proximity and higher-risk classification tier.
Corporate benefits administrators are consolidating mental health vendor relationships around platform solutions that bundle app access with coaching and EAP services. This procurement consolidation displaces standalone app subscriptions in employer channels. The shift is most visible in Greater London's financial and professional services sectors where benefits centralization reduces vendor management overhead.
UK Mental Health Apps Market Segmentation
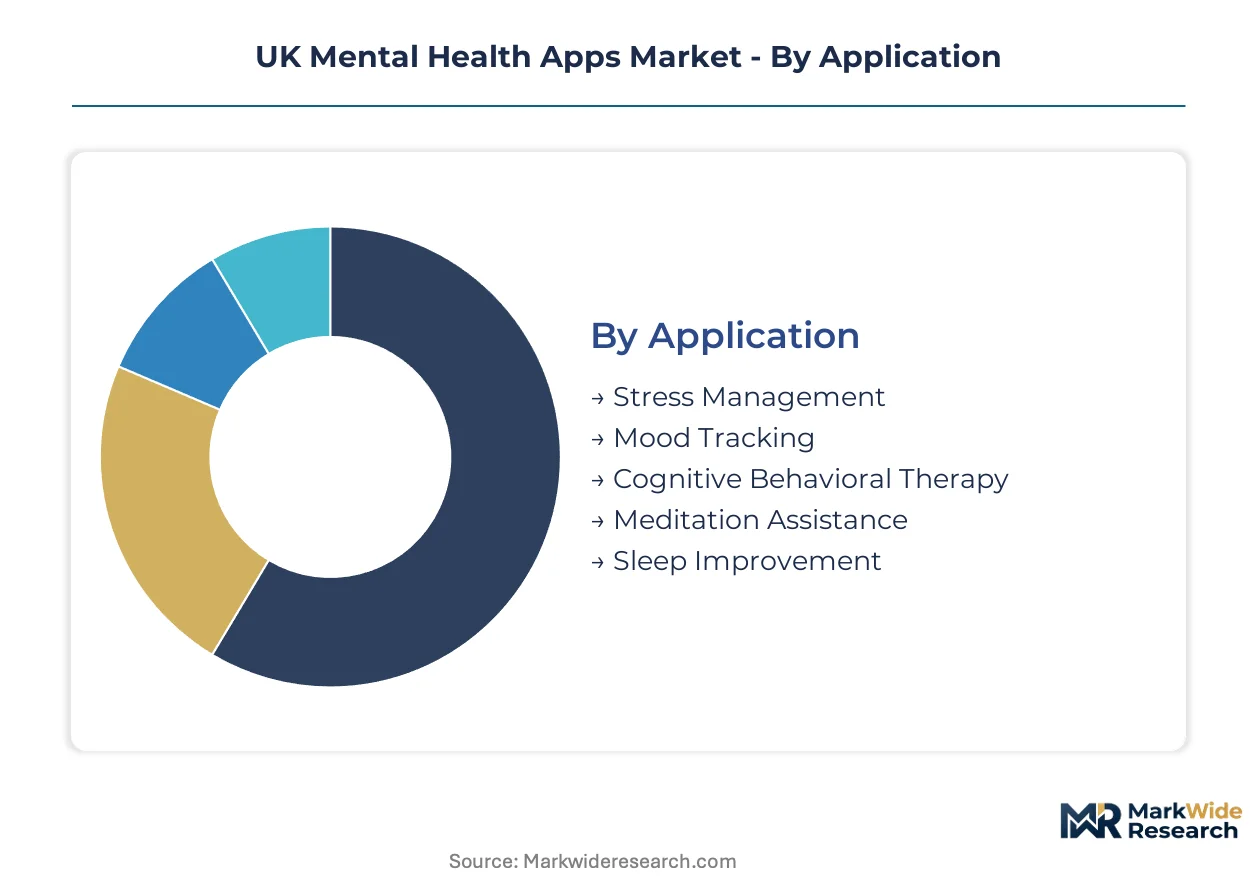
Segmentation in the UK mental health apps market reveals how clinical validation requirements, platform accessibility, and reimbursement pathways fragment demand across distinct user journeys. Developers must architect product configurations that align with NHS Digital Technology Assessment Criteria while serving divergent end-use contexts from ICB-funded therapy to employer wellness channels.
Application:
The use-case spectrum spans preventive wellness through clinical-grade intervention, with diagnostic proximity determining regulatory burden and reimbursement eligibility.
- Cognitive Behavioral Therapy:Structured protocols aligned with NICE guidelines require randomized controlled trial evidence and MHRA software-as-medical-device classification. NHS Integrated Care Boards in Greater London and the South East concentrate procurement for these higher-tier interventions where insurer reimbursement pathways are secured.
- Sleep Improvement:Passive monitoring integration with Apple Watch and Fitbit ecosystems enables biometric-informed intervention delivery. Demand clusters among corporate benefits administrators in London's financial services sector who bundle sleep coaching with broader mental health platform contracts.
- Stress Management:Workplace wellness programs drive employer-funded deployment without NHS reimbursement dependency.
- Mood Tracking:Self-reported symptom logging supports user self-awareness and clinician remote monitoring workflows.
- Meditation Assistance:Content library breadth differentiates competitive positioning in direct-to-consumer channels.
The dominant share belongs to Cognitive Behavioral Therapy, while Sleep Improvement is closing the gap fastest through wearable ecosystem convergence.
Platform:
Accessibility infrastructure shapes user acquisition economics and clinical integration complexity across NHS and private care pathways.
- iOS:Premium device ownership correlates with higher subscription conversion rates and Greater London user concentration. Apple's HealthKit integration streamlines biometric data pipelines for MHRA-validated therapeutic applications requiring passive monitoring.
- Wearable Integration:Apple Watch and Fitbit sensor arrays enable continuous physiological signal capture that differentiates clinical-grade positioning. NHS Talking Therapies pilots in the South East leverage this data stream for algorithmic personalization without proportional workforce expansion.
- Android:Broader device penetration reaches cost-sensitive segments where freemium conversion ceilings constrain monetization.
- Web-Based:Browser access removes download friction for NHS clinician-supervised referrals.
- Desktop Support:Extended session formats suit structured CBT protocols requiring sustained user attention.
iOS commands the installed base advantage, though Wearable Integration is expanding most quickly through DTAC-mandated outcome measurement requirements.
User Type:
Clinical supervision requirements and digital literacy gradients fragment product design priorities across age and professional boundaries.
- Adults:Working-age users between 25 and 54 dominate subscription revenue pools and employer wellness channel penetration. NHS self-referral pathways through ICB digital mental health services concentrate demand in urban agglomerations with established remote care infrastructure.
- Adolescents:Safeguarding protocols and parental consent frameworks impose additional governance layers for app developers targeting CAMHS referral pathways. School-based mental health support teams in England are piloting supervised app use for early intervention.
- Seniors:Simplified interfaces and telephone backup support address accessibility barriers in aging populations.
- Caregivers:Proxy account management enables monitoring of dependent users across intergenerational care contexts.
- Mental Health Professionals:Clinician-facing dashboards for patient progress oversight require NHS electronic health record interoperability investments.
Adults retain the volume concentration, yet Adolescents are gaining share fastest through CAMHS capacity expansion and school-based deployment pilots.
Monetization Model:
Revenue architecture determines competitive entry barriers and capital efficiency across direct-to-consumer and institutional procurement channels.
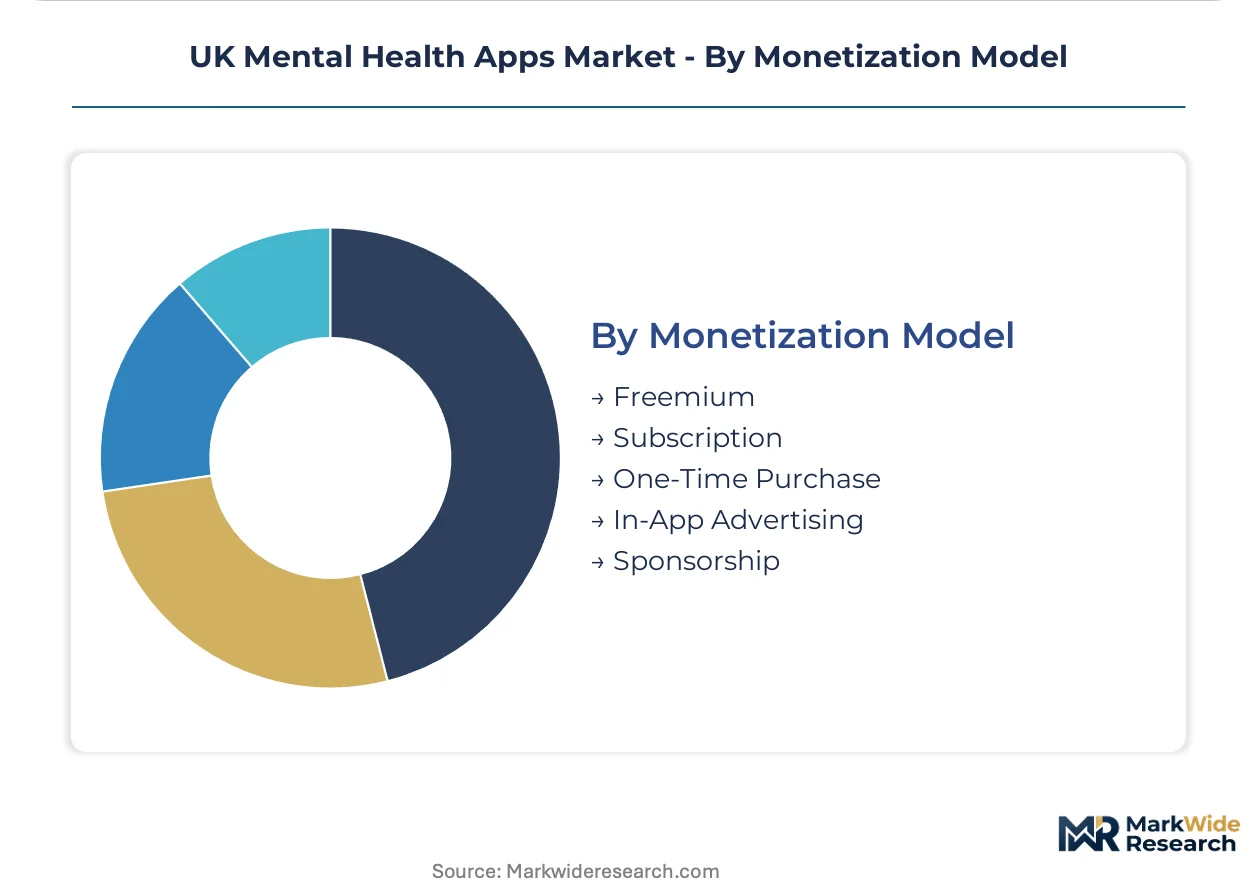
- Subscription:Predictable recurring revenue concentrates margin pools and supports clinical validation investment amortization. NHS partnership leasing models operationalize subscription structures through ICB operational expenditure budgets rather than capital allocation cycles.
- Freemium:User acquisition scale without upfront payment friction dominates volume metrics but faces structural conversion limits in cost-sensitive segments where discretionary health spending competes with essential consumption.
- One-Time Purchase:Upfront license fees persist in specialized clinical tools for mental health professional use.
- In-App Advertising:Ad-supported models conflict with therapeutic environment integrity requirements under MHRA quality management system expectations.
- Sponsorship:Corporate and charitable funding enables free-at-point-of-access distribution for underserved populations.
Subscription holds the revenue concentration, while Freemium remains the steepest expansion trajectory for user base building prior to institutional contract conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK mental health apps market operates as a net importer of clinical validation expertise and algorithmic personalization technology, with domestic demand concentrated in England's urban centers while regulatory frameworks shape cross-border service delivery.
Greater London
NHS Integrated Care Boards in London allocate the largest digital mental health procurement budgets, driven by population density and clinician familiarity with remote therapeutic tools. The Medicines and Healthcare products Regulatory Agency software-as-medical-device framework governs market access for app developers seeking reimbursement eligibility. The South London and Maudsley NHS Foundation Trust serves as a reference site for algorithmic triage pilots, accelerating adoption cascades across neighboring ICBs.
South East England
Digital health infrastructure maturity in Oxford and Cambridge creates demand concentration for evidence-based interventions aligned with NICE guidelines. The National Institute for Health and Care Excellence maintains its headquarters in Manchester but conducts digital health evidence assessments that directly shape procurement priorities in this region. The Oxford Academic Health Science Network facilitates clinical trial partnerships between university medical centers and app developers seeking DTAC compliance.
Midlands
Employer wellness channel expansion drives B2B demand in Birmingham and Leicester's financial services corridors, reducing dependency on NHS reimbursement pathways. The West Midlands Combined Authority pilots digital mental health integration with primary care networks. Birmingham's corporate benefits administrators consolidate vendor relationships around platform solutions that bundle app access with coaching services.
North West England
Manchester's health innovation ecosystem supports mid-cap developers navigating randomized controlled trial generation requirements under NICE digital health evidence standards. The Greater Manchester Integrated Care Partnership experiments with subscription-based financing models that replace upfront license fees with recurring operational expenditure structures. The city's academic medical center partnerships strain developer balance sheets but yield direct revenue pathway security.
Scotland
NHS Scotland's digital health strategy creates distinct procurement pathways separate from English ICB structures, with demand clustering in Edinburgh and Glasgow's urban health boards. The Scottish Government's mental health strategy mandates app-based intervention pilots for CAMHS capacity expansion. Edinburgh's informatics cluster supports wearable device convergence for passive mood monitoring differentiation.
UK Mental Health Apps Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower clinical validation footprints. The vendor base stratifies across three tiers: multinational wellness platforms with employer channel dominance, mid-cap clinical trial partners with NHS reimbursement pathways, and niche algorithmic personalization engines. Consolidation pressures concentrate around DTAC scoring capabilities and MHRA quality management system certification. Strategic moves center on ICB partnership leasing structures and academic medical center alliance formation.
Within the clinical trial partner tier, Woebot Health and MoodMission exemplify developers anchoring position through NHS academic medical center relationships. Headspace Inc. occupies a position on the employer wellness vector, leveraging corporate benefits channel relationships to sustain recurring revenue streams beyond direct-to-consumer sales. Calm represents the content library breadth archetype, competing on brand recognition across sleep and anxiety verticals without full MHRA software-as-medical-device classification.
| Leading Market Players |
|---|
| Youper, Inc. |
| Mindscape |
| Headspace Inc. |
| Woebot Health |
| MoodMission Pty Ltd. |
| Calm |
| Sanvello Health |
| BetterHelp |
| Wysa AI |
| Others |
Pricing and Supply Chain Analysis
The M6 corridor freight network connecting Manchester and Birmingham channels logistics cost volatility directly into developer margin structures, amplifying price differentiation between MHRA-certified clinical apps and unvalidated wellness tools while concentrating procurement leverage within Greater London's Integrated Care Boards.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS-tiered pricing across NHS partnership leasing models, with three-tier pricing structure across premium, standard, and economy levels separating DTAC-validated clinical tools from employer wellness bundles and direct-to-consumer freemium tiers. Price differentiation hinges on MHRA software-as-medical-device certification grade and NICE guideline alignment, with premium tiers commanding insurer reimbursement security. Cost compression in the standard tier intensifies as mid-cap developers amortize clinical trial investments across shrinking procurement cycles. Cost-sensitive segments including adolescent CAMHS pathways and Midlands employer wellness channels exhibit highest price sensitivity, while Greater London ICBs demonstrate lowest sensitivity due to operational expenditure budget flexibility.
Supply Chain Analysis
Upstream algorithmic personalization engines and natural language processing frameworks draw from California's AI research clusters, India's software development hubs, and Cambridge's academic medical center partnerships. Raw material dependencies encompass cloud computing infrastructure from AWS and Azure, biometric sensor arrays from Apple and Fitbit ecosystems, and clinical validation expertise from Oxford and Manchester university hospitals. Single-source vulnerability concentrates in Apple's HealthKit integration protocols for iOS-dependent therapeutic applications. Distribution runs through NHS Digital Technology Assessment Criteria certification pathways for institutional procurement, alongside direct-to-consumer app store channels and corporate benefits administrator platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MHRA's evolving software-as-medical-device guidance for artificial intelligence-driven therapeutic content creates a regulatory inflection that will consolidate developer tiers and reward preemptive compliance investments across the analysis window.
For Market Incumbents: Pre-empt algorithmic content liability exposure by accelerating quality management system documentation ahead of finalized MHRA guidance on AI therapeutic outputs. Secure backward integration into academic medical center partnerships for randomized controlled trial generation, defending against mid-cap clinical trial partners encroaching on NHS reimbursement pathways. Channel control through Integrated Care Board leasing structures represents the priority defensive lever against employer wellness platform consolidation. For New Entrants and Emerging Players: Midlands employer wellness channels in Birmingham and Leicester's financial services corridors represent the most penetrable entry point, bypassing MHRA compliance barriers that filter NHS reimbursement pathways. Adolescent mental health support teams in England's school-based CAMHS pilots offer second white-space targeting with lower clinical validation thresholds than adult ICB contracts. Go-to-market execution should anchor through corporate benefits administrator relationships rather than direct NHS procurement cycles. For Investors and Strategic Acquirers: Clinical trial partners with existing DTAC scoring capabilities and Manchester or Oxford academic medical center alliances present the highest acquisition value archetype for long-term viability across the 5-10 year window. Platform integrators bundling app access with coaching and EAP services are displacing standalone subscriptions in Greater London's financial services sectors. The signal to watch is MHRA publication of finalized AI therapeutic content classification tiers, which will determine which product architectures retain reimbursement eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| MHRA Quality Management System Certification | Preemptive compliance investment secures NHS reimbursement pathway continuity ahead of AI guidance finalization. |
| Academic Medical Center Alliance Formation | Oxford and Manchester partnerships generate NICE-mandated RCT evidence without capitalizing full trial infrastructure. |
| Integrated Care Board Partnership Leasing | Operational expenditure structuring replaces upfront license fees, accelerating procurement cycle compression. |
| Employer Wellness Channel Expansion | Birmingham and Leicester corporate benefits procurement reduces NHS reimbursement dependency for revenue diversification. |
| Wearable Device Ecosystem Integration | Apple Watch and Fitbit biometric pipelines differentiate clinical-grade positioning for DTAC outcome measurement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with NHS Integrated Care Board procurement leads, MHRA regulatory affairs specialists, clinical trial directors at Oxford and Manchester academic medical centers, and corporate benefits administrators in Greater London and the Midlands; alongside secondary validation through NHS Digital Technology Assessment Criteria scoring databases, MHRA software-as-medical-device guidance publications, NICE digital health evidence standards documentation, and App Annie mobile health download metrics. Bottom-up triangulation across app developer revenue disclosures and top-down reconciliation against NHS digital mental health budget allocations anchored market sizing integrity.
Forecast inputs encompassed platform segmentation across iOS, Android, wearable integration, and web-based deployment; application segmentation spanning CBT protocols, sleep improvement, stress management, and mood tracking; and user type differentiation between adults, adolescents, and mental health professionals. CAGRs were derived through regression analysis of historical NHS digital mental health procurement trajectories and ICB operational expenditure growth patterns, with algorithmic personalization engine adoption curves and wearable device convergence rates as industry-specific demand shapers across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in NHS capital allocation cycles, employer wellness benefits expenditure, or MHRA regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about DTAC scoring stability and NICE guideline continuity. Cross-checking against NHS England digital mental health referral volume statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Behavioral Health Software Market
Mental Health Services
Postpartum Depression Management Market
Mental Health Services
Global Behavioral Health Market
Mental Health Services
Germany Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Behavioral Health Care Software and Services Market
Mental Health Services
Global Workplace Stress Management Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
China Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Post-Traumatic Stress Disorder (PTSD) Market
Mental Health Services
Mental Health Software Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
Anxiety Disorders and Depression Treatment Market
Mental Health Services
Obsessive-Compulsive Disorder Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
Schizophrenia Market
Mental Health Services
Agoraphobia Treatment Market