
 Flow Cytometry Products Market | 2026-2036
Flow Cytometry Products Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Cytometry Products Market Intelligence
A shift from single-vendor ecosystems toward multi-sourcing of reagents and consumables is recalibrating the competitive landscape for flow cytometry products. Becton, Dickinson and Company leverages its extensive instrument installed base to promote its proprietary reagent portfolio. Danaher Corporation competes through its subsidiary brands, each specializing in distinct workflow segments from cell sorting to analysis. Thermo Fisher Scientific differentiates with a broad offering of compatible consumables and software platforms for diverse research applications.
Flow cytometry is a technique for detecting and measuring physical and chemical characteristics of cells or particles. It functions by passing cells in a fluid stream through a laser, enabling simultaneous multiparametric analysis. Among product types, analyzers and cell sorters are major capital expenditures, while reagents create recurring revenue. Immunophenotyping is the dominant application, especially in research institutes and academic centers for cell biology studies.
Regulatory frameworks from the US FDA and the European Medicines Agency (EMA) govern the use of flow cytometry in clinical diagnostics and drug development. In China, the NMPA's evolving standards for medical devices create specific market access requirements for instrument and reagent manufacturers. Vendor success will depend on navigating these distinct regional regulatory pathways while managing the integration of advanced software and data analysis capabilities.
Market Dynamics
The market's central dynamic is the tension between incumbent, closed-ecosystem business models and a user-driven shift toward open-architecture systems. This move to multi-source reagents and consumables, coupled with tightening diagnostic standards like the EU's MDR, is forcing a strategic recalibration among leading vendors.
Growth Catalysts
- Immunophenotyping Advances:The expansion of high-parameter spectral flow cytometry in immunology and oncology research provides deeper cellular insights, driving demand for advanced analyzers and complex, pre-configured reagent panels.
- Biotechnology Investment in China:Substantial government funding through national programs accelerates the build-out of research institutes and contract research organizations, creating concentrated demand for new flow cytometry instruments and consumables.
- Cell and Gene Therapy Development:Use of flow cytometry for quality control and characterization in cell and gene therapy manufacturing creates a new, high-value application segment for clinical-grade instruments and GMP-compliant reagents.
Market Restraints
- High Capital Expenditure:The significant upfront cost of high-end cell sorters and spectral analyzers remains a major barrier for academic laboratories and smaller biotech firms with limited budgets.
- Data Analysis Complexity:Large, multi-dimensional datasets generated by high-parameter cytometry require specialized bioinformatics expertise and advanced software, creating a data interpretation bottleneck for many research teams.
- Stringent Clinical Validation:The pathway for achieving clinical diagnostic (IVD) status under frameworks from the FDA and the EU's MDR is long and costly, slowing the translation of research instruments into routine clinical use.
Strategic Opportunities
- Diagnostic Expansion in India:Underpenetrated clinical diagnostic markets in India present an opportunity for mid-range, robust analyzers compliant with CDSCO regulations for applications like HIV monitoring and leukemia typing.
- AI-Powered Data Analysis:Integrating artificial intelligence and machine learning algorithms to automate cell population gating and data interpretation can simplify workflows and reduce operator-dependent variability.
- Microbiology and Environmental Testing:Applying flow cytometry for rapid microbial detection in food safety, water quality monitoring, and industrial fermentation offers a new growth vector beyond traditional biomedical research.
Industry Challenges
- Shortage of Skilled Technicians:A deficit of trained operators proficient in complex instrument setup, panel design, and advanced data analysis limits the effective utilization of high-end flow cytometry systems.
- Lack of Assay Standardization:Inter-laboratory variability in results, stemming from a lack of standardized protocols for sample preparation and reagent use, complicates multicenter clinical trials and diagnostic comparisons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Cytometry Products Market |
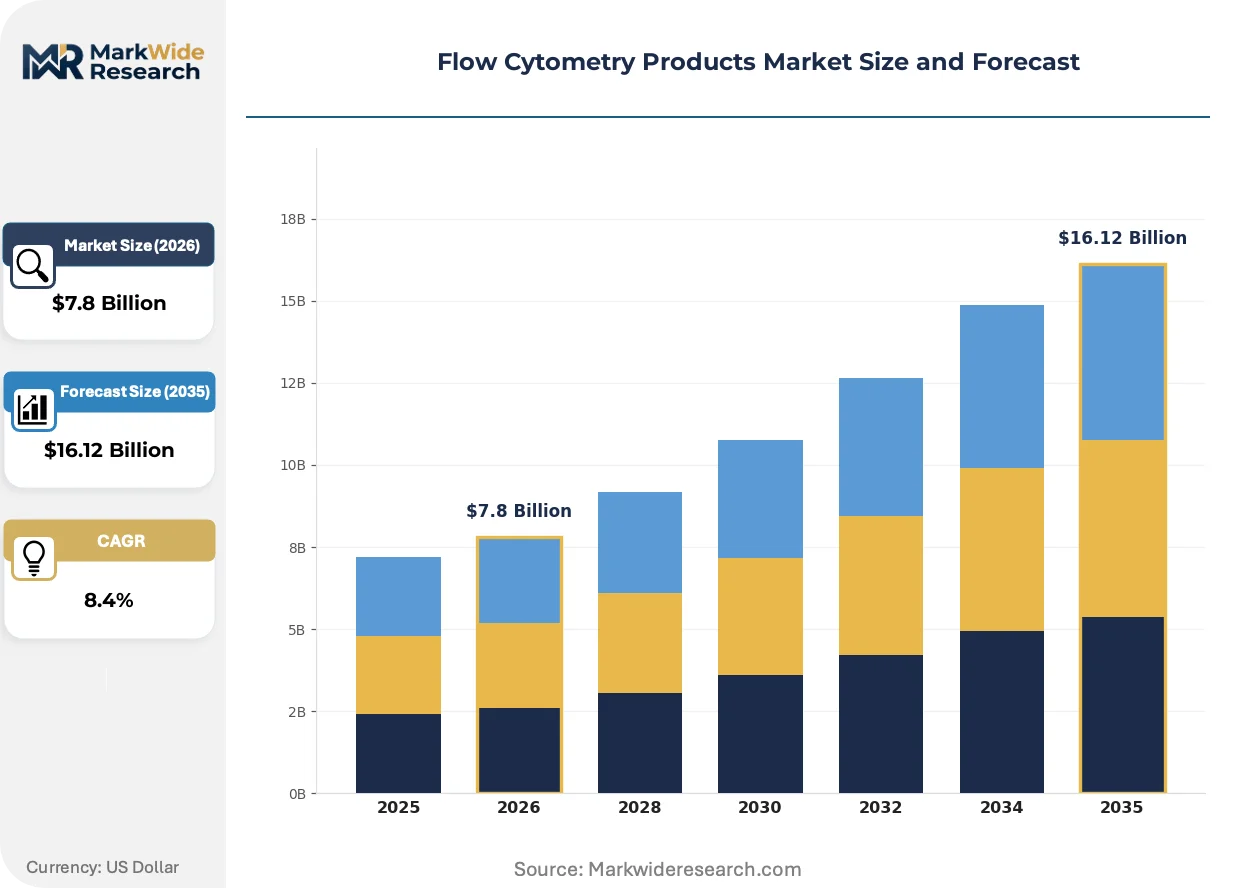
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analyzers, Cell Sorters, Reagents, Software Platforms, Consumables Technology: Fluorescence-Activated Sorting, Imaging Cytometry, Mass Cytometry, Magnetic-Activated Sorting, Laser-Based Detection Application: Immunophenotyping, Cell Cycle Analysis, Apoptosis Detection, Microbiology Testing, Molecular Biology End User: Research Institutes, Pharmaceutical Developers, Diagnostic Laboratories, Biotechnology Firms, Academic Centers |
| Companies Covered | Becton, Dickinson and Company, Danaher Corporation, Thermo Fisher Scientific, Sysmex Corporation, Bio-Rad Laboratories, Agilent Technologies, Cytek Biosciences, Sony Biotechnology, Miltenyi Biotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Cytometry Products Market Strategic Shifts & Innovations
The evolution of flow cytometry is driven by the need to manage increasing data complexity while adhering to stricter regulatory requirements for clinical applications. This pressure fosters innovations in automation, data analytics, and instrument design aimed at improving reproducibility and simplifying workflows for a broader user base.
Spectral Cytometry and High-Parameter Analysis
Spectral flow cytometry utilizes full emission spectrum detection, enabling the analysis of more than 40 parameters simultaneously from a single sample. Major academic research centers and pharmaceutical R&D labs are rapidly adopting this technology for deep immunophenotyping and biomarker discovery. This technology is integrating advanced optical and computational capabilities, allowing for the resolution of previously indistinguishable cell populations.
Stricter Regulatory Scrutiny for IVD Devices
The European Union's Medical Device Regulation (MDR) imposes more rigorous requirements for clinical evidence, post-market surveillance, and traceability for diagnostic instruments. This regulation forces manufacturers to re-evaluate their entire product lifecycle, from design and risk management to labeling and technical documentation for CE marking. In-vitro diagnostic (IVD) flow cytometers and their associated software are most affected, demanding significant investment in clinical performance studies.
Shift Toward Open-Platform Consumables
A notable shift in purchasing behavior involves a move from single-vendor, closed-ecosystem contracts toward a multi-sourcing strategy for reagents and consumables. This unbundling disrupts the traditional razor-and-blade model, where instrument sales locked in downstream reagent purchases, and favors suppliers with open-platform compatible products. This trend is most prominent in large academic consortia and contract research organizations seeking greater flexibility and cost control.
Flow Cytometry Products Market Segmentation
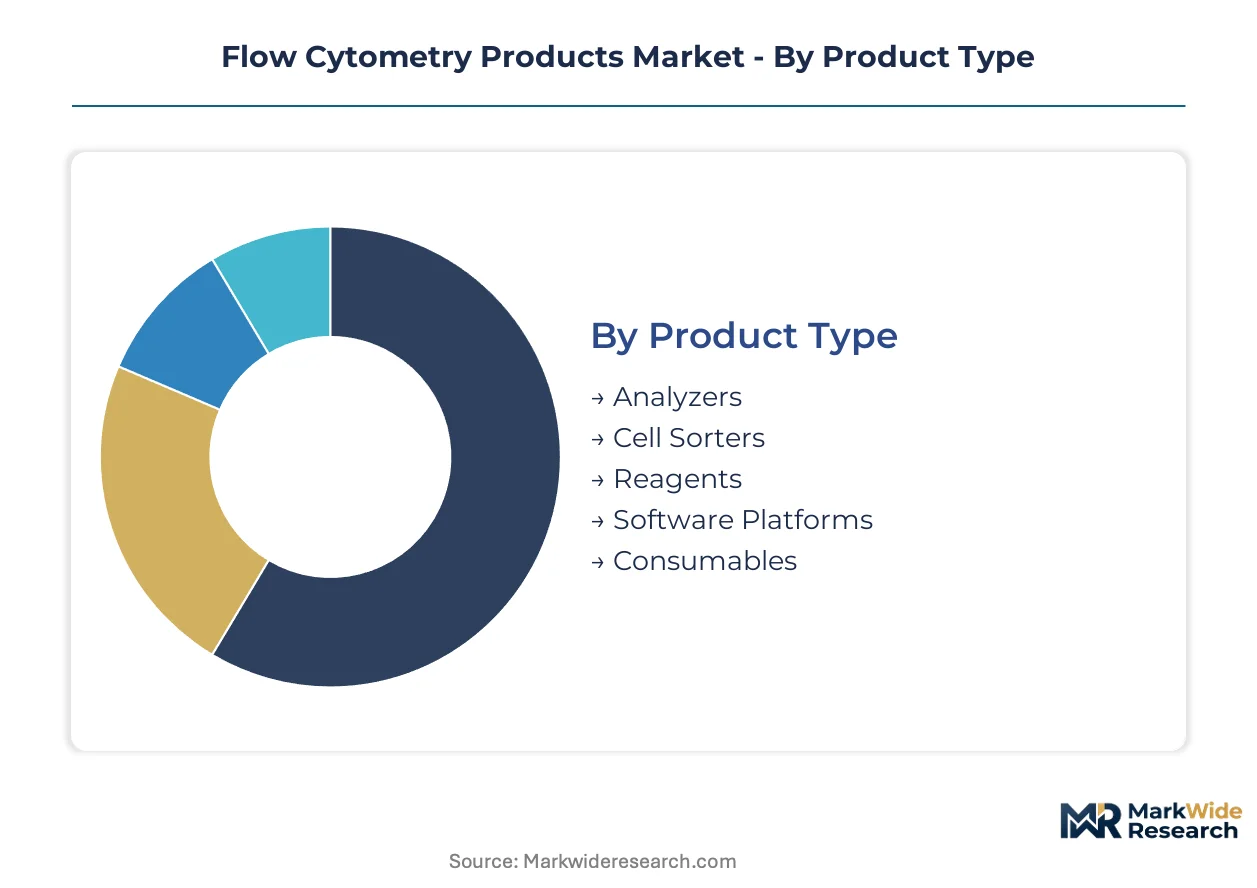
The flow cytometry products market is segmented by several critical dimensions, each influencing purchasing decisions and vendor strategies. Understanding these segments helps identify key demand pockets and technological adoption trends across various end-user environments. This granular view reveals how different product types, technologies, applications, and end-user profiles contribute to market dynamics.
Product Type:
Decisions regarding product type are primarily driven by the required analytical depth, throughput, and budget constraints of the end-user laboratory.
- Analyzers:These instruments perform multiparametric analysis of cells or particles as they pass through a laser, detecting fluorescent signals. Demand concentrates in academic research for cell biology studies, where detailed characterization of cell populations is essential.
- Cell Sorters:These advanced instruments not only analyze but also physically separate specific cell populations based on their characteristics. Pharmaceutical developers utilize cell sorters for isolating target cells in drug discovery and cell therapy manufacturing.
- Reagents:Consist of antibodies, dyes, and buffers essential for staining and preparing samples for flow cytometry analysis.
- Software Platforms:Provide data acquisition, analysis, and visualization tools for interpreting complex flow cytometry datasets.
- Consumables:Include tubes, plates, and sheath fluids necessary for the daily operation of flow cytometry instruments.
Analyzers leads on scale; Cell Sorters leads on momentum.
Technology:
The choice of flow cytometry technology is dictated by the specific biological questions being addressed and the required resolution for cellular analysis.
- Fluorescence-Activated Sorting:This method uses fluorescently labeled antibodies to identify and sort cells based on their light scattering and fluorescence properties. It remains fundamental for high-purity cell isolation in immunology research and clinical diagnostics.
- Imaging Cytometry:Combines flow cytometry's high throughput with microscopy's image-based cellular detail, capturing morphology and spatial relationships. Pharmaceutical R&D adopts this technology for phenotypic screening and complex cell analysis.
- Mass Cytometry:Utilizes heavy metal isotope-tagged antibodies for cellular staining, enabling the simultaneous detection of over 40 parameters without spectral overlap.
- Magnetic-Activated Sorting:Employs magnetic beads conjugated to antibodies for cell isolation, offering a gentle and high-yield separation method.
- Laser-Based Detection:Refers to the core optical detection principle in most flow cytometers, using lasers to excite fluorochromes and detect emitted light.
The integration of advanced optical and computational capabilities enables increasingly complex cellular insights across these technologies.
Application:
Application segments are driven by the volume of samples processed and the specific diagnostic or research needs of the customer base.
- Immunophenotyping:This application involves identifying and quantifying different immune cell populations using specific cell surface markers. It is the dominant application in research institutes for understanding immune responses and disease progression.
- Cell Cycle Analysis:Measures DNA content to determine the distribution of cells in different phases of the cell cycle, crucial for cancer research and drug toxicity studies. Academic centers frequently employ this for fundamental cell biology investigations.
- Apoptosis Detection:Identifies cells undergoing programmed cell death, vital for oncology research and drug development to assess treatment efficacy.
- Microbiology Testing:Applies flow cytometry for rapid detection and enumeration of microorganisms in food, water, and clinical samples, offering speed over traditional culture methods.
- Molecular Biology:Uses flow cytometry to analyze DNA, RNA, and protein expression at a single-cell level, supporting gene expression studies and genetic research.
The increasing complexity of cellular analysis fuels demand across these diverse applications, particularly in advanced research settings.
End User:
End-user segments reflect varying budget allocations, regulatory requirements, and the need for specialized instruments versus routine diagnostic tools.
- Research Institutes:These organizations conduct basic and translational research, requiring high-end, flexible instruments for complex experimental designs and biomarker discovery. Significant government funding in China accelerates demand for new instruments in these institutes.
- Pharmaceutical Developers:Engage in drug discovery, development, and clinical trials, necessitating GMP-compliant instruments and reagents for quality control and cellular characterization. They demand robust, high-throughput systems for cell and gene therapy manufacturing.
- Diagnostic Laboratories:Perform clinical testing, relying on validated, often IVD-certified, flow cytometers for routine patient sample analysis, such as leukemia typing.
- Biotechnology Firms:Focus on developing novel therapies and diagnostics, requiring specialized flow cytometry solutions for cell line development and product characterization.
- Academic Centers:Often mirror research institutes in their needs but may have broader educational mandates and budget constraints, driving demand for versatile systems.
Diverse end-user needs shape product development and service offerings, from high-throughput research to routine clinical diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's biotechnology sector, fueled by substantial government investment, drives concentrated demand for flow cytometry instruments and consumables. This investment accelerates the build-out of research institutes and contract research organizations. Diverse regional market dynamics influence product adoption and regulatory compliance.
China
China's government funding through national programs accelerates the build-out of research institutes and contract research organizations, creating concentrated demand. The NMPA's evolving standards for medical devices create specific market access requirements for instrument and reagent manufacturers. The Yangtze River Delta region, including Shanghai and Suzhou, sees rapid expansion of biotech R&D facilities.
United States
United States pharmaceutical development and immunophenotyping applications drive demand for advanced flow cytometry systems. US FDA frameworks govern the use of flow cytometry in clinical diagnostics and drug development, necessitating rigorous validation. The Greater Boston area, a major biotech hub, focuses on cell and gene therapy research and development.
Germany
German academic centers and pharmaceutical R&D labs adopt high-parameter spectral flow cytometry for deep immunophenotyping. The European Union's Medical Device Regulation (MDR) imposes rigorous requirements for diagnostic instruments, influencing product design for the German market. Munich's life science cluster specializes in developing advanced optical and computational capabilities for new instruments.
India
Underpenetrated clinical diagnostic markets in India present an opportunity for mid-range, robust analyzers compliant with local regulations. CDSCO regulations guide the approval process for medical devices, including flow cytometers used for applications like HIV monitoring. Hyderabad's Genome Valley is expanding its diagnostic laboratory infrastructure, increasing demand for affordable solutions.
Japan
Japanese research institutes and academic centers drive demand for high-end analyzers and complex reagent panels for cell biology studies. PMDA guidelines for medical devices ensure stringent quality and safety standards for flow cytometry products entering the market. Tokyo's university research ecosystem actively adopts spectral cytometry for advanced cellular insights.
Flow Cytometry Products Market Key Industry Players
Global majors compete with regional champions across product innovation and market access strategies, driving dynamic shifts. The market exhibits a tiered structure, with established incumbents holding significant installed bases alongside specialized innovators. Strategic archetypes include integrated solution providers, open-platform specialists, and niche technology developers focusing on specific applications. Portfolio diversification across product lines and geographic expansion into emerging markets are common competitive moves.
Among established industry leaders, Becton, Dickinson and Company represents the incumbent archetype, leveraging its extensive instrument installed base to promote proprietary reagent portfolios. Danaher Corporation exemplifies a diversified approach, competing through subsidiary brands, each specializing in distinct workflow segments from cell sorting to analysis. This strategy allows Danaher to address varied customer needs effectively. Thermo Fisher Scientific occupies a position as a broad offering provider, differentiating with compatible consumables and software platforms for diverse research applications, supporting a wide array of research applications. These companies collectively anchor significant portions of the market.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Sysmex Corporation |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Cytek Biosciences |
| Sony Biotechnology |
| Miltenyi Biotec |
| Others |
Cost & Logistics Intelligence
Pharmaceutical developers, requiring GMP-compliant instruments, drive contract-based pricing for high-end systems. This demand, coupled with multi-sourcing trends, influences reagent and consumable pricing across the market.
Pricing Analysis
Input-cost pass-through for specialized components, such as high-purity antibodies and optical sensors, directly impacts instrument and reagent pricing. The dominant pricing model for capital equipment is contract-based, while reagents follow a per-unit transactional structure. Price differentiation stems from GMP compliance, brand reputation, and comprehensive after-sales service. Multi-sourcing initiatives apply downward pressure on consumable prices, making academic laboratories and smaller biotech firms the most price-sensitive buyers.
Supply Chain Analysis
Reverse-logistics flows, particularly for instrument refurbishment and component recycling, are becoming more critical for sustainability and cost management. China and the United States concentrate manufacturing for core components and high-end instruments, with Germany specializing in advanced optical systems. The supply chain relies heavily on specialized fluorochromes, monoclonal antibodies, and precision laser diodes. Single-source vulnerability for specific high-performance optical components poses a structural risk, while distribution runs through direct sales channels for capital equipment and a hybrid model for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flow cytometry market functions as a regulatory compounder, with the European Union's MDR driving significant investment in clinical validation and product design. This regulatory push elevates demand for compliant diagnostic instruments and reagents.
For Market Incumbents: To counter the user-driven shift towards open-platform consumables and multi-sourcing, incumbents must deepen software integration and expand proprietary reagent panels. Strategic acquisitions of specialized spectral cytometry developers can reinforce technological leadership. Investing in IVD certification for clinical applications in the US and EU will defend market share against emerging diagnostic players. Focus on R&D for AI-powered data analysis tools will mitigate data interpretation bottlenecks.
For New Entrants and Emerging Players: Digital-channel routes for direct-to-customer sales of open-platform reagents offer a viable entry point for new players. Target mid-range, robust analyzers for underpenetrated clinical diagnostics markets, particularly in India. Focus on AI-powered data analysis software that simplifies complex workflows for academic laboratories. A go-to-market strategy emphasizing cost-effectiveness and ease-of-use will attract budget-constrained end-users.
For Investors and Strategic Acquirers: Pharmaceutical developers and large diagnostic corporations are the most active acquirers in this space, seeking to consolidate advanced capabilities. The long-term viability remains strong, driven by cell and gene therapy development and expanding clinical diagnostic applications. Acquisition targets should include niche spectral cytometry firms, AI-powered data analysis software developers, and GMP-compliant reagent manufacturers. Regulatory approvals for novel IVD flow cytometry applications will be a key signal to watch for inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Spectral Cytometry R&D | This enhances high-parameter analysis capabilities, crucial for pharmaceutical R&D and biomarker discovery. |
| Pursue IVD Certification Pathways | Securing FDA and EMA approvals enables broader clinical diagnostic use, particularly for leukemia typing. |
| Develop AI-Powered Data Analysis Platforms | Integrating machine learning simplifies complex datasets, addressing the data interpretation bottleneck for research teams. |
| Expand GMP-Compliant Reagent Portfolio | This supports cell and gene therapy manufacturing, a high-value application segment requiring stringent quality control. |
| Establish Regional Manufacturing Hubs in China | Local production addresses NMPA's evolving standards and captures concentrated demand from government-funded institutes. |
Research Approach
Bottom-up end-user modeling, reconciled against top-down instrument and reagent supply tracking, forms the analytical core of this study. Primary research involved structured interviews with R&D scientists, lab managers, procurement officers, and regulatory affairs specialists across key regions. Secondary validation drew from regulatory filings, industry reports, and peer-reviewed academic journals, ensuring robust triangulation of market data.
An input-output matrix integrates historical market performance with future growth drivers across the analysis window. The analytical framework models market dynamics by product type, technology, application, end-user, and regional regulatory cluster. Compound annual growth rates were derived from a weighted average of segment-specific growth trajectories. Key industry-specific forecast inputs include biotechnology investment levels in China and clinical trial volumes for cell and gene therapies.
The model assumes a particular technology adoption path; alternative pathways for AI-powered data analysis and spectral cytometry would alter the outlook. Forecasts reflect documented assumptions regarding market evolution and regulatory stability. Practitioners should monitor new regulatory frameworks and significant R&D milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vaginal Applicators Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Manometry System Market
Medical Devices
Prescription Goggles Market
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
Flexible Spinal Implants Market
Medical Devices
Global Peripheral IV Catheters Market
Medical Devices
Knee Reconstruction Devices Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
Global Airway Stent/Lung Stent Market
Medical Devices
North America Single-Use Medical Device Reprocessing Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Removable Partial Dentures Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Global Bone Screw System Market