
 PC-Based Resting Electrocardiograph Market | 2026-2036
PC-Based Resting Electrocardiograph Market Size, Share, and Industry Trends Forecast 2026-2036
PC-Based Resting Electrocardiograph Market Analytics
Software-defined ECG acquisition is fragmenting legacy hardware architectures into modular, algorithm-driven platforms. GE HealthCare leverages its imaging ecosystem to integrate resting ECG data with broader cardiovascular workflows. Koninklijke Philips N.V. anchors its position through enterprise informatics that connect bedside acquisition to cloud analytics. Nihon Kohden Corporation specializes in high-fidelity analog-to-digital conversion for precision diagnostic environments.
A PC-based resting electrocardiograph digitizes cardiac electrical signals through surface electrodes, converting analog waveforms into interpretable data via 12-lead configurations sampled at 500–1000 Hz for diagnostic clarity. The device serves cardiologists and emergency departments requiring rapid, reproducible rhythm assessment without dedicated cart-based systems. The 12-Lead ECG segment dominates hospital procurement due to established reimbursement codes and clinical training infrastructure, while AI-Enhanced Analysis represents the fastest-expanding technology layer as algorithms gain regulatory acceptance for preliminary interpretation. Cloud-Based delivery modes are capturing margin pools from capital-constrained clinics seeking subscription access to enterprise-grade diagnostic tools.
FDA 510(k) premarket notification and EU MDR conformity assessment shape product development timelines and software validation requirements for manufacturers seeking multi-regional market access. HIPAA in the United States and GDPR in Europe impose distinct data governance obligations on cloud-connected ECG platforms that transmit patient-identifiable recordings. Stakeholders must monitor evolving AI/ML-based medical device guidance from FDA and notified bodies to anticipate validation burdens that will separate compliant platforms from retrofit-dependent competitors.
Market Dynamics
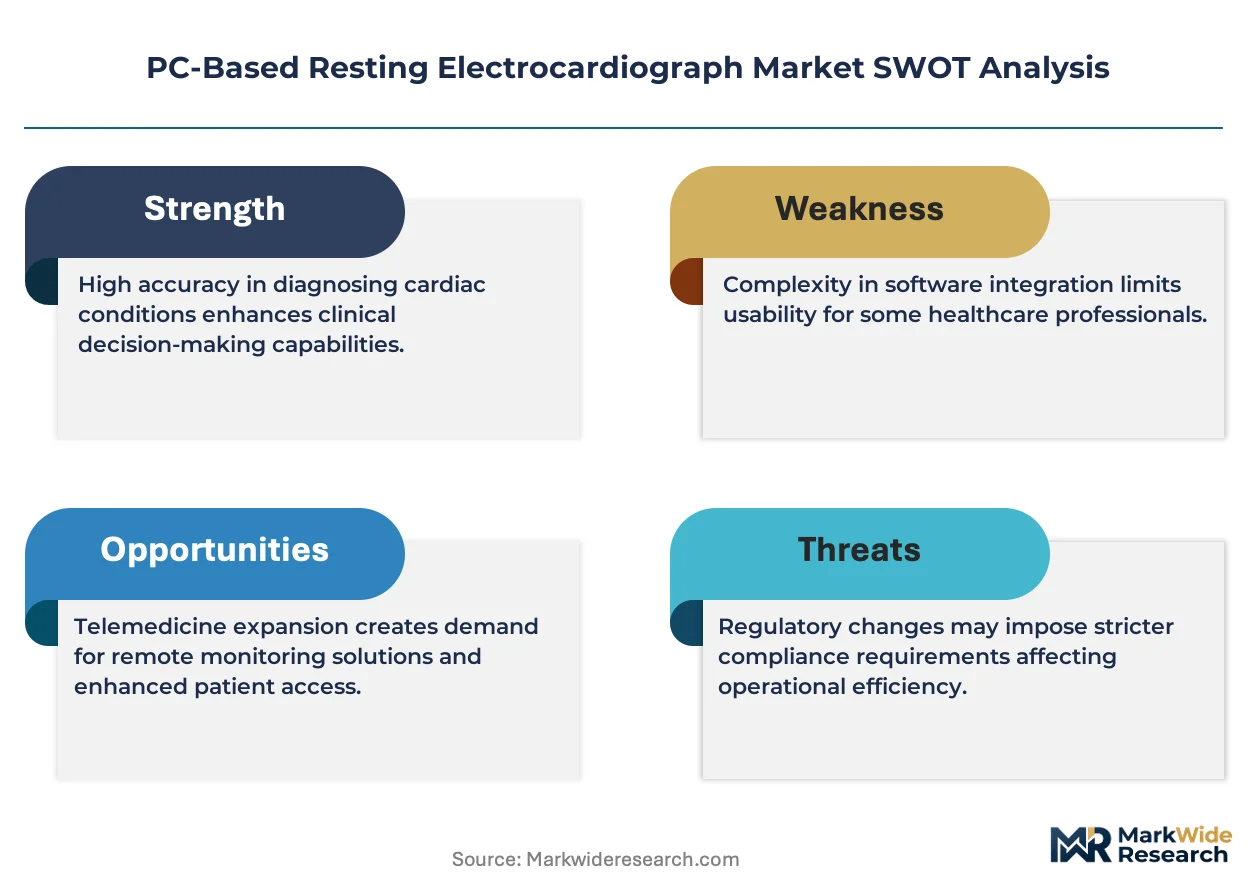
Software-defined acquisition architectures are fragmenting legacy electrocardiograph hardware into modular, algorithm-driven platforms that separate signal processing from dedicated cart-based systems. This structural shift compresses capital expenditure requirements while elevating cloud connectivity and AI interpretation layers as the primary value determinants.
Growth Catalysts
- FDA 510(k) Pre-market Notification:Streamlined clearance pathways for software-as-medical-device submissions accelerate hardware-software integration investments by manufacturers seeking rapid multi-regional deployment.
- Germany's Digitized Healthcare Infrastructure:Hospital networks expanding ambulatory cardiac monitoring programs create concentrated procurement demand for PC-based systems with enterprise informatics compatibility.
- AI-Enhanced Analysis Algorithms:Regulatory acceptance of machine learning tools for preliminary ECG interpretation expands addressable market into primary care settings previously dependent on specialist over-read.
Market Restraints
- EU MDR Conformity Assessment:Extended validation timelines and notified body capacity constraints delay product launches and inflate software documentation burdens for European market access.
- Analog-to-Digital Component Concentration:Precision ADC suppliers in Japan and specialized semiconductor fabricators create single-source dependencies for high-fidelity signal chains.
- Legacy Cart-Based System Longevity:Depreciation schedules and established clinical training infrastructure in tertiary hospitals slow replacement cycles despite superior PC-based economics.
Strategic Opportunities
- Cloud-Based Subscription Models:Capital-constrained outpatient clinics in the United States seek enterprise-grade diagnostic tools through recurring revenue arrangements rather than upfront capital purchases.
- HIPAA-GDPR Convergent Platforms:Dual-compliant data governance architectures that satisfy both United States privacy mandates and European data localization requirements open transatlantic procurement consolidation.
- Integration with Cardiovascular Imaging Workflows:PC-based ECG systems that feed directly into cath lab and echocardiography informatics capture margin pools from departmental silo budgets.
Industry Challenges
- Electrophysiology Specialist Shortage:Scarce trained personnel for algorithm validation and clinical over-read limit deployment velocity in community hospital settings.
- Legacy EMR Integration Complexity:Proprietary data formats and fragmented health information exchange standards force costly custom interface development for each health system deployment.
- AI/ML Validation Documentation:Evolving FDA guidance on continuous learning algorithms requires prospective clinical study designs that extend development timelines beyond traditional hardware cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PC-Based Resting Electrocardiograph Market |
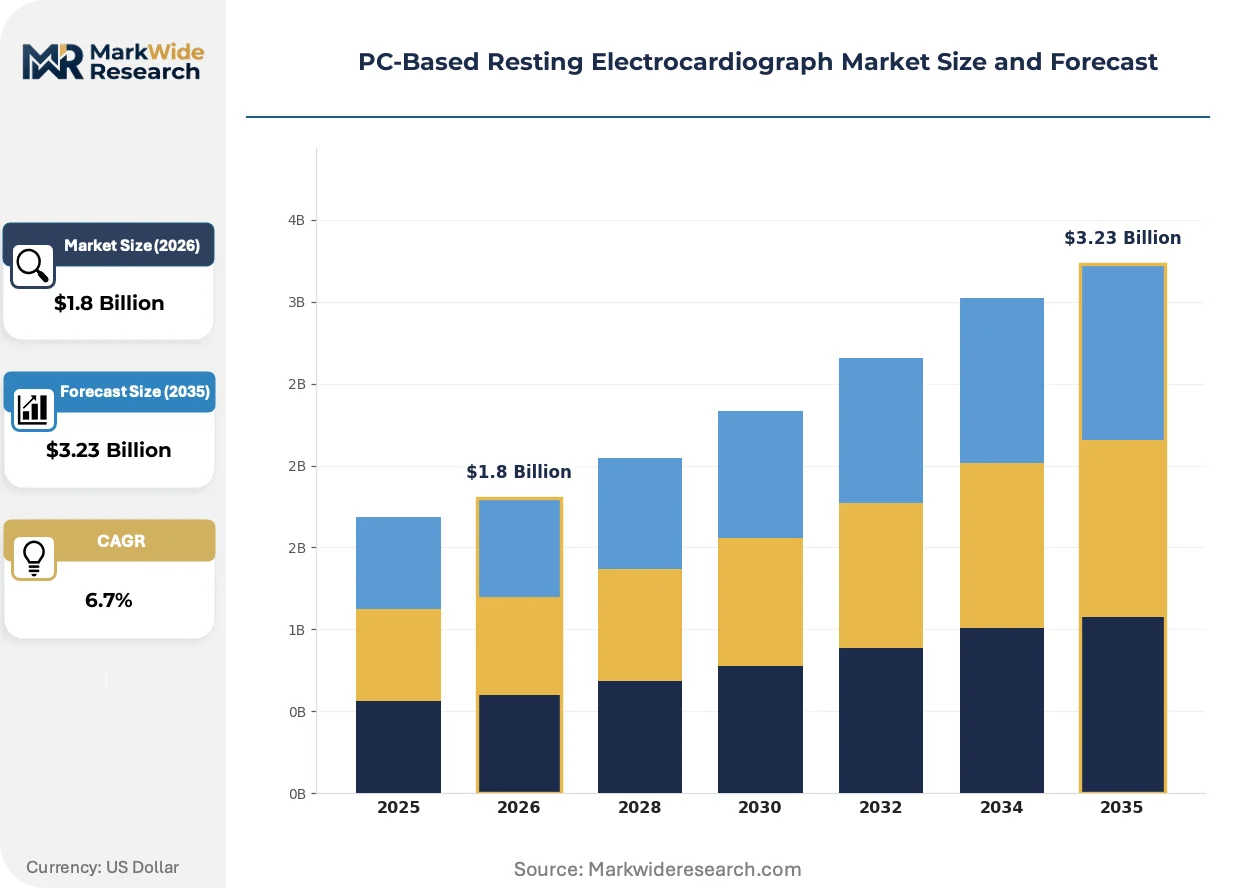
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 12-Lead ECG, Portable ECG, Wireless ECG, Holter Monitor Delivery Mode: Cloud-Based, On-Premises, Hybrid, Mobile Application End User: Hospitals, Cardiologists, Clinics, Research Institutions Technology: Digital ECG, Analog ECG, Telemedicine, AI-Enhanced Analysis |
| Companies Covered | GE HealthCare, Koninklijke Philips N.V., Nihon Kohden Corporation, Medtronic, Mindray Medical International Limited, Spacelabs Healthcare, Mortara Instrument, Schiller AG, iRhythm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PC-Based Resting Electrocardiograph Market Evolving Landscape
Algorithmic interpretation layers are compressing the diagnostic value chain by embedding preliminary analysis directly at the point of acquisition. This transformation elevates software competence above hardware specifications in procurement evaluations.
Edge-computing ECG acquisition modules with embedded inference engines are rendering obsolete the traditional architecture requiring dedicated interpretation workstations and delayed specialist over-read. Emergency departments in the United States adopt these systems for immediate triage decisions. The structural consequence compresses time-to-diagnosis metrics while shifting capital allocation from hardware toward algorithm licensing.
EU MDR software classification rules reclassify AI-enabled ECG interpretation tools as higher-risk devices requiring notified body involvement. Manufacturers face expanded clinical evidence requirements for algorithm updates previously managed through software patches. Cardiology practices in Germany and France delay procurement decisions pending clarity on post-market surveillance obligations for cloud-connected platforms.
Subscription-based access models displace capital purchase arrangements in outpatient cardiology clinics. Equipment financiers and software vendors capture recurring revenue streams previously retained by hospital capital budgets. This behavioral shift concentrates most visibly in the United States where independent physician associations seek operational expenditure flexibility amid reimbursement compression.
PC-Based Resting Electrocardiograph Market Segmentation
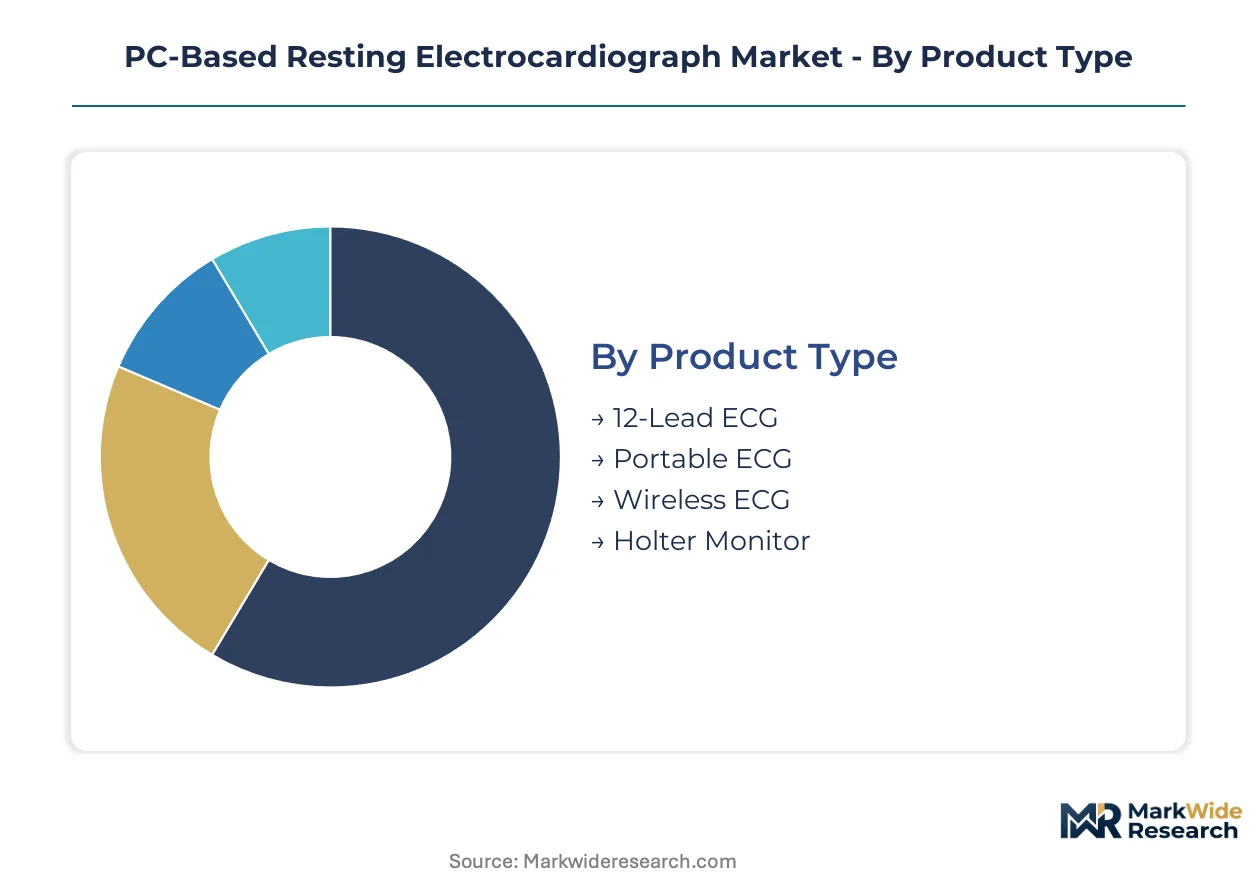
Segmentation in the PC-based resting electrocardiograph market reflects divergent procurement priorities across care settings, from high-throughput hospital networks seeking enterprise integration to ambulatory clinics prioritizing capital flexibility. Technology layers and delivery architectures now command greater budget allocation than hardware specifications alone.
Product Type:
Mature configurations dominate hospital procurement cycles while emerging form factors capture ambulatory expansion.
- 12-Lead ECG:Standard diagnostic configuration sampling 10 electrodes across 12 vector perspectives at 500–1000 Hz for ischemia detection. Hospital networks in Germany and the United States standardize procurement around this format due to established CPT reimbursement codes and cardiologist training infrastructure.
- Portable ECG:Compact USB or Bluetooth-connected acquisition modules designed for point-of-care deployment without dedicated cart infrastructure. Community clinics in Japan and outpatient cardiology practices in France prioritize these systems for space-constrained examination rooms.
- Wireless ECG:Battery-operated units transmitting via WiFi or cellular protocols to central interpretation platforms.
- Holter Monitor:Extended-duration ambulatory recording systems capturing 24–48 hours of rhythm data for intermittent arrhythmia detection.
12-Lead ECG handles the majority of throughput; AI-Enhanced Analysis is the fastest mover on share.
Delivery Mode:
Deployment architecture selection tracks capital availability and IT governance maturity across end-user organizations.
- Cloud-Based:Subscription-accessed platforms with remote software updates and centralized data repositories. Independent physician associations in the United States favor this model to convert capital expenditure into operational expenditure amid reimbursement compression.
- On-Premises:Locally installed software requiring dedicated server infrastructure and internal IT maintenance. Tertiary hospital systems in Germany and Japan with established biomedical engineering departments retain this architecture for data sovereignty compliance.
- Hybrid:Mixed deployment combining local acquisition with cloud analytics and backup.
- Mobile Application:Smartphone or tablet-native interfaces for acquisition and preliminary review.
Cloud-Based deployment is expanding most quickly in outpatient settings; On-Premises retains dominance in academic medical centers.
End User:
Procurement authority and workflow integration requirements vary substantially across institutional categories.
- Hospitals:Integrated delivery networks with cath lab and emergency department connectivity requirements. Health systems across the United States prioritize interoperability with existing cardiovascular informatics platforms.
- Cardiologists:Specialist practices requiring high-fidelity acquisition for diagnostic certainty. German cardiology groups emphasize precision analog-to-digital conversion for subtle conduction abnormality detection.
- Clinics:Primary care and urgent care facilities with limited specialist over-read availability.
- Research Institutions:Academic centers conducting prospective algorithm validation studies.
Hospitals command the largest procurement volumes; Clinics are gaining share fastest as primary care adopts preliminary ECG screening.
Technology:
Signal processing methodology and interpretation capability now determine competitive positioning more than hardware specifications.
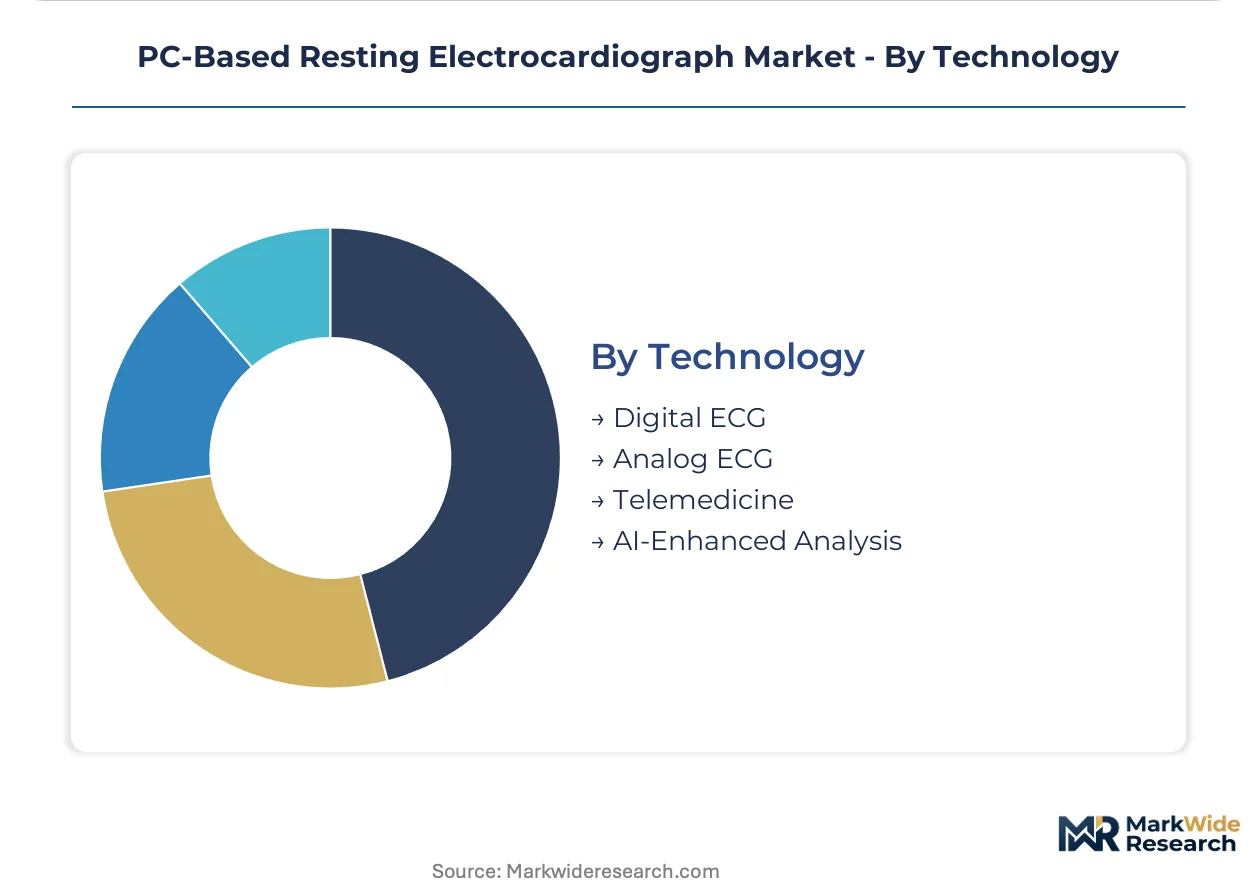
- Digital ECG:Fully digitized signal chains with software-defined filtering and baseline correction. This architecture enables seamless algorithm updates without hardware replacement.
- Analog ECG:Legacy systems with hardware-dependent signal conditioning prior to digitization. Specialized diagnostic environments in Japan retain these for specific research applications.
- Telemedicine:Real-time transmission capabilities enabling remote specialist consultation.
- AI-Enhanced Analysis:Machine learning algorithms providing preliminary interpretation and anomaly flagging. FDA 510(k) clearance pathways for these tools accelerate deployment into settings lacking immediate cardiologist availability.
Digital ECG underpins the installed base; AI-Enhanced Analysis shows the steepest expansion trajectory as regulatory acceptance broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement officers in Germany, the United States, and Japan command the dominant share of PC-based resting electrocardiograph purchasing decisions, driven by aging demographics and digitized healthcare infrastructure investments.
Germany
Bavarian hospital networks and North Rhine-Westphalian cardiology groups drive concentrated demand for high-fidelity 12-lead systems with enterprise informatics compatibility. EU MDR conformity assessment requirements extend software validation timelines, prompting manufacturers to establish notified body relationships early. Berlin-Brandenburg medical technology clusters host specialized ADC component suppliers serving precision diagnostic equipment fabricators.
United States
Integrated delivery networks across Texas and the Northeast Corridor expand ambulatory cardiac monitoring programs with cloud-connected acquisition modules. FDA 510(k) premarket notification pathways streamline software-as-medical-device submissions, accelerating hardware-software integration investments. Greater Boston and Silicon Valley technology corridors concentrate AI-enhanced ECG interpretation algorithm developers seeking regulatory clearance.
Japan
Tokyo metropolitan hospital systems and Osaka-based cardiology practices prioritize precision analog-to-digital conversion for subtle conduction abnormality detection. PMDA medical device regulations align with international standards while maintaining distinct software documentation requirements for cloud-connected platforms. Nagoya industrial districts host specialized semiconductor fabricators supplying high-fidelity signal chain components.
United Kingdom
London and Southeast England NHS trusts procure PC-based systems with interoperability mandates for cardiovascular informatics integration. MHRA post-Brexit regulatory frameworks retain EU MDR technical standards while establishing independent conformity assessment procedures. Midlands medical device manufacturing zones produce compact USB-connected acquisition modules for point-of-care deployment.
France
Parisian academic medical centers and Lyon-based cardiology groups evaluate AI-enhanced analysis tools for preliminary ECG interpretation in primary care settings. ANSM and CNIL impose dual compliance requirements for medical device safety and patient data governance on cloud-connected platforms. Île-de-France health technology clusters host software vendors developing HIPAA-GDPR convergent data architectures.
PC-Based Resting Electrocardiograph Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement environments where enterprise informatics integration determines hospital network purchasing decisions. The vendor base separates into imaging ecosystem integrators, precision diagnostic specialists, and cloud-native algorithm platforms. Three strategic archetypes dominate: diversified health technology conglomerates leveraging cross-departmental workflows, focused cardiac monitoring specialists emphasizing signal fidelity, and software-centric challengers delivering subscription-based interpretation services. Competitive moves concentrate on strategic partnerships with electronic medical record vendors and technology licensing arrangements for AI-enhanced analysis capabilities.
Within the diversified health technology tier, GE HealthCare and Koninklijke Philips N.V. exemplify channel-controlling players with enterprise informatics integration capabilities. Nihon Kohden Corporation occupies a specialized position emphasizing precision analog-to-digital conversion for diagnostic certainty in high-acuity environments.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips N.V. |
| Nihon Kohden Corporation |
| Medtronic |
| Mindray Medical International Limited |
| Spacelabs Healthcare |
| Mortara Instrument |
| Schiller AG |
| iRhythm Technologies |
| Others |
Value Network & Pricing Analysis
The Shanghai-to-Rotterdam maritime corridor carries precision analog-to-digital converters and semiconductor components whose freight cost volatility feeds directly into tiered equipment pricing. Japanese ADC suppliers and Taiwanese foundry outputs concentrate upstream leverage, while German hospital networks and United States outpatient clinics face divergent price elasticity at the point of procurement.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate procurement agreements between device manufacturers and component suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, ISO 13485 certification tier, and bundled software update terms. Cost compression in the economy tier intensifies because cloud-native entrants undercut legacy hardware margins. Independent physician associations in the United States exhibit highest price sensitivity; academic medical centers in Germany demonstrate lowest sensitivity due to integrated capital budgeting.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn and Jabil facilities in China, Mexico, and Malaysia handling final assembly of acquisition modules. High-fidelity ADC chips draw from Japan and the United States; precision resistors and capacitors rest on South Korean and Taiwanese suppliers. Single-source vulnerability pervades the 24-bit sigma-delta converter segment where AKM Semiconductor and Analog Devices hold dominant positions. Distribution runs through cardiology-focused GPOs in the United States and regional medical device distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs value capture as ECG data flows merge with cardiovascular imaging informatics and cloud analytics ecosystems. Interoperability mandates from United States integrated delivery networks and German hospital networks are consolidating procurement authority around vendors with enterprise workflow integration.
For Market Incumbents: Pre-empt algorithm commoditization by embedding AI interpretation layers directly into cath lab and echocardiography informatics platforms. Acquire cloud-native ECG startups before they achieve FDA 510(k) clearance for standalone diagnostic algorithms. Vertical integration into precision ADC design reduces exposure to Japanese single-source suppliers. For New Entrants and Emerging Players: Pursue subscription-based deployment in United States independent physician associations seeking operational expenditure flexibility amid Medicare reimbursement compression. Target community hospital emergency departments lacking immediate cardiologist over-read availability. Partner with athenahealth or Epic integration marketplaces for rapid health system penetration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified health technology conglomerates seeking to divest non-core cardiac monitoring divisions amid portfolio rationalization. Five-to-ten year viability hinges on algorithm regulatory moats rather than hardware manufacturing scale. Monitor FDA 510(k) clearance velocity for AI-enhanced ECG interpretation tools as inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for AI-enhanced interpretation algorithms in primary care settings. |
| CE Marking Pathway | Unlocks procurement from German hospital networks under EU MDR conformity requirements. |
| Hospital System Partnership | Secures enterprise informatics integration with Epic or Cerner cardiovascular modules. |
| Software Companion Development | Enables real-time ECG-to-imaging workflow connectivity in cath lab environments. |
| Reimbursement Strategy | Aligns CPT coding with AI-enhanced analysis to capture Medicare outpatient payments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and cardiology practice administrators; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body documentation. Bottom-up triangulation across equipment shipment data and top-down reconciliation with healthcare capital expenditure surveys anchored volume estimates.
Forecast inputs span product type configurations, delivery mode architectures, end-user institutional categories, and technology layers including AI-enhanced analysis adoption curves. Modeled dimensions encompass 12-lead versus portable form factors, cloud-based versus on-premises deployment, and digital signal processing versus algorithmic interpretation penetration. CAGRs derive from logistic diffusion curves fitted to regulatory clearance timelines and health system procurement cycle patterns.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native platform moves by software-centric challengers would shift outcomes beyond projected ranges. Model assumptions include stable FDA 510(k) review timelines and unaltered EU MDR software classification rules. Quarterly review of AI/ML medical device guidance updates and notified body capacity constraints is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Syringe Filling Machine Market
Medical Devices
Sterile Filtration Module Market
Medical Devices
Global Trauma Devices Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Active Humidifier Devices Market
Medical Devices
Radiotherapy Patient Positioning Accessories Market
Medical Devices
Asia-Pacific Biosurgery Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Medical Injection Molding Machine Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Contrast Injection Lines Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
France Spinal Surgery Devices Market
Medical Devices
Bovine Pericardial Valve Market