
 South Africa Anti-Blue Ray Myopia Lenses Market | 2026-2036
South Africa Anti-Blue Ray Myopia Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Anti-Blue Ray Myopia Lenses Market Insights
The capital-intensity divergence between multinational lens manufacturers and domestic dispensers is redrawing competitive boundaries in South Africa. EssilorLuxottica leverages its captive surfacing laboratories in Johannesburg to control turnaround times for coated prescriptions. Specsavers anchors its position through vertically integrated eye-testing and fitting networks across major metros. HOYA Corporation differentiates via proprietary blue-light filtering substrate technology calibrated for high-luminance African sunlight conditions.
South Africa anti-blue ray myopia lenses incorporate sub-wavelength interference coatings or embedded absorptive dyes that attenuate high-energy visible light between 415 and 455 nanometers while preserving color fidelity for myopic correction. These lenses undergo precision surfacing on polycarbonate or high-index substrates to achieve center thickness tolerances below 0.1 millimeters for pediatric wearers. Single vision configurations dominate unit volume among school-age end users, though progressive designs capture disproportionate margin pools from senior professionals requiring near-intermediate digital workspace correction. Photochromic variants represent the fastest-growing material-format intersection as consumers seek dual-function outdoor-digital protection. Trivex material adoption accelerates in children's segments where impact resistance and low specific gravity reduce frame slippage during active use.
The South African Health Products Regulatory Authority classifies anti-blue ray lenses as medical devices requiring Section 21 import authorizations, creating compliance thresholds for non-registered suppliers. The South African Bureau of Standards enforces optical transmittance benchmarks through SANS 1424 specifications that limit permissible haze in coated surfaces. The National Department of Health's school health screening programme channels paediatric demand toward certified dispensing channels. Stakeholders must monitor pending amendments to medical device registration fees and local content thresholds under the Department of Trade and Industry's preferred procurement frameworks.
Market Dynamics
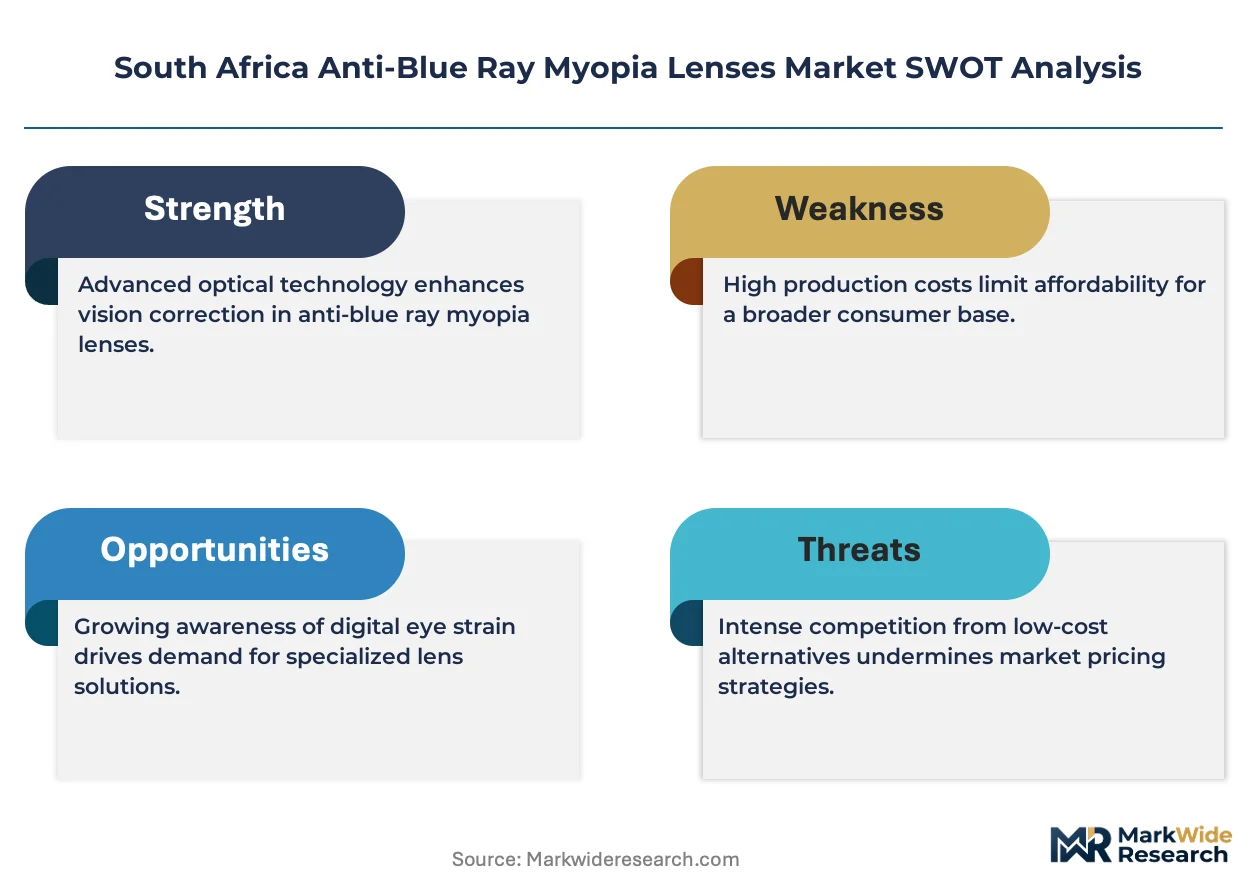
EssilorLuxottica's captive surfacing laboratories in Johannesburg are compressing turnaround times for coated prescriptions, forcing domestic dispensers to consolidate procurement volumes or exit pediatric segments entirely.
Growth Catalysts
- School health screening mandates:The National Department of Health's programme channels paediatric demand toward certified dispensing channels, accelerating formal market penetration.
- Polycarbonate substrate advances:Precision surfacing achieving center thickness tolerances below 0.1 millimeters enables comfortable all-day wear for active children.
- Gauteng demand concentration:Private optometry chains in Johannesburg and Pretoria generate disproportionate prescription volumes, creating economies of scale for coating batch processing.
Market Restraints
- Section 21 import authorizations:The South African Health Products Regulatory Authority's medical device classification creates 4-6 month registration timelines for non-registered suppliers.
- Coating material input volatility:Sub-wavelength interference coating precursors face supply concentration among German and Japanese chemical specialists.
- Uncorrected refractive error substitution:Low-cost ready readers from informal retailers capture price-sensitive segments in peri-urban areas.
Strategic Opportunities
- Western Cape expansion:Cape Town's private healthcare density remains underpenetrated relative to Gauteng, offering whitespace for chain dispensers.
- Photochromic-blue-light convergence:Dual-function lenses addressing high-luminance African sunlight and digital exposure command premium positioning.
- Preferred procurement frameworks:Pending Department of Trade and Industry local content thresholds incentivize domestic surfacing investment.
Industry Challenges
- Pediatric optometrist scarcity:Gauteng and KwaZulu-Natal face acute shortages of practitioners certified for cycloplegic refraction in children.
- SANS 1424 compliance timelines:The South African Bureau of Standards' optical transmittance testing creates batch release bottlenecks for coated imports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Anti-Blue Ray Myopia Lenses Market |
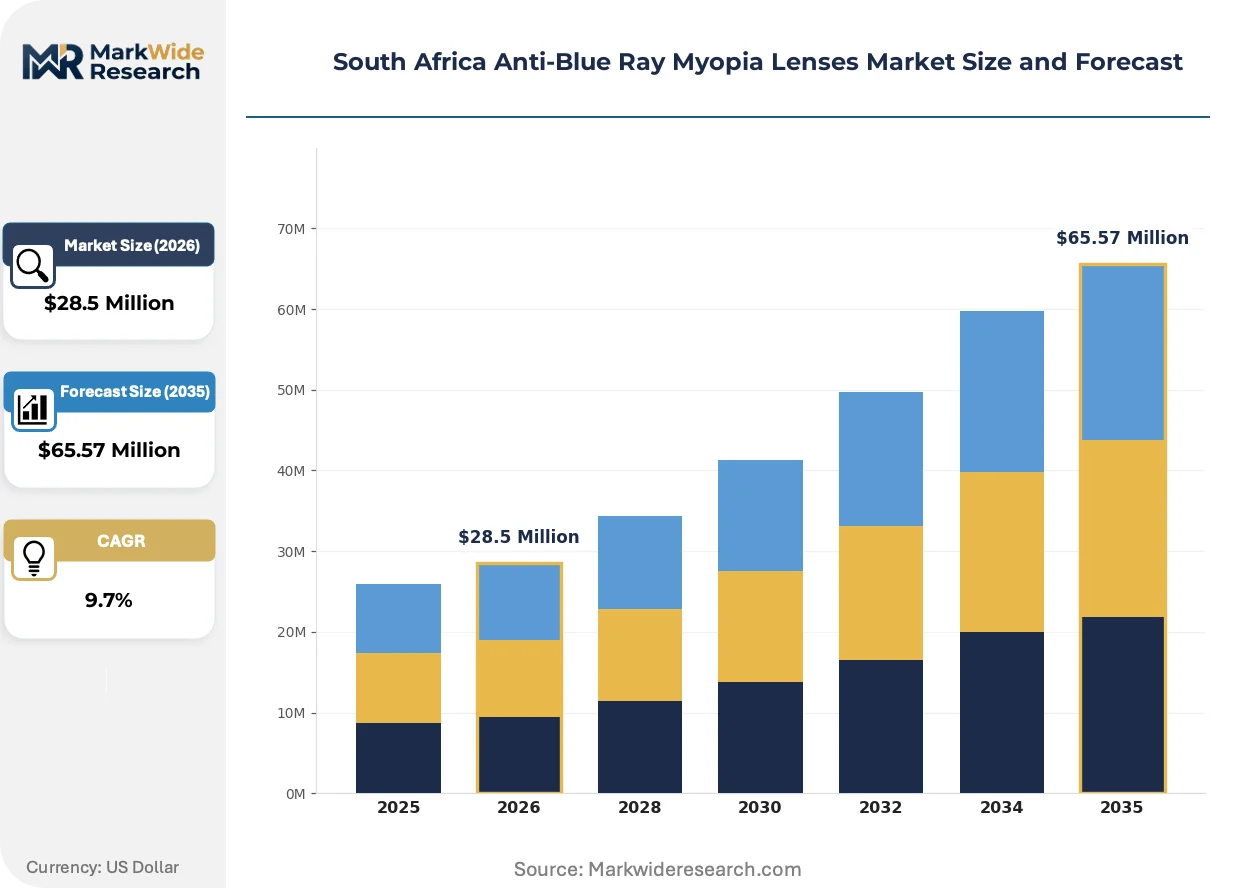
| Market Size in 2026 | $28.5 Million |
| Market Size in 2035 | $65.57 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Vision, Bifocal, Progressive, Photochromic End User: Children, Adults, Seniors, Vision Correction Centers Material: Polycarbonate, Trivex, High-Index Plastic, Glass Distribution Channel: Optical Retailers, Online Stores, Hospital Pharmacies, Wholesale Distributors |
| Companies Covered | Rodenstock, Seiko Optical Products, EssilorLuxottica, Shamir Optical Industry, Nikon, ZEISS, Safilo Group, Specsavers, HOYA Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Anti-Blue Ray Myopia Lenses Market Trends and Innovations
Coating technology evolution and regulatory recalibration are reshaping how lens manufacturers balance optical performance against pediatric safety requirements in high-ambient-light environments.
Trivex material adoption is bifurcating the children's segment between impact-resistant active-wear prescriptions and conventional polycarbonate for sedentary users. School-age athletes and outdoor-program participants drive specification upgrades, compressing polycarbonate's historical dominance in pediatric dispensing. This material shift is enabling frame designers to reduce temple pressure while maintaining optical center stability during physical activity.
The South African Health Products Regulatory Authority's pending amendments to medical device registration fees are compressing margin structures for imported lens portfolios. Distributors face working capital strain as inventory holding periods extend pending Section 21 authorization renewals. Domestic surfacing laboratories with established registrations capture incremental volume as foreign suppliers delay re-registration investments.
After-sales service unbundling is disrupting traditional dispensing economics in metropolitan private practices. Patients increasingly source frames through direct-to-consumer channels while demanding professional fitting and coating verification separately. This fragmentation concentrates value capture in specialized coating laboratories while commoditizing front-end eye testing in competitive urban clusters.
South Africa Anti-Blue Ray Myopia Lenses Market Segmentation
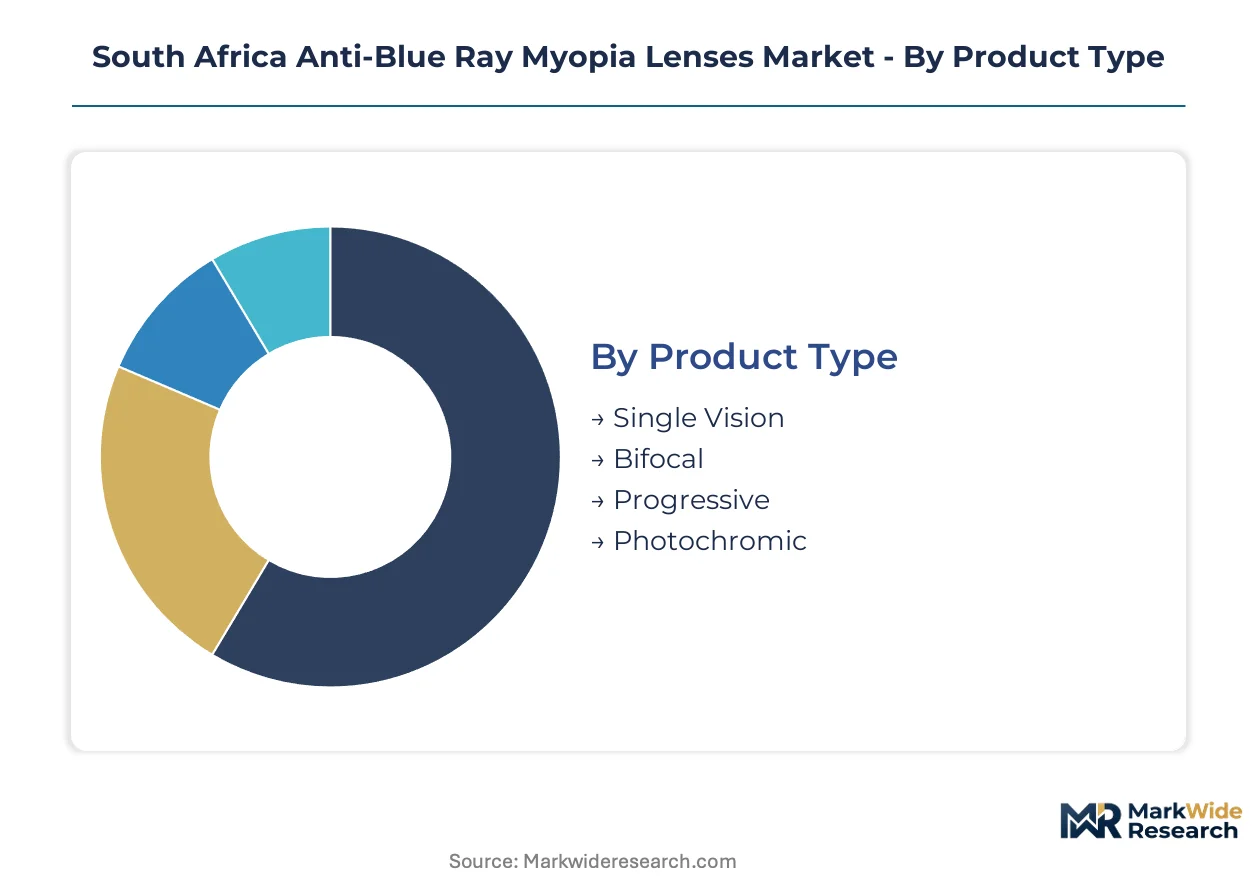
Margin pools in South Africa's anti-blue ray myopia lens market concentrate in pediatric and professional segments where coating precision commands premium positioning. Understanding how product specifications, end-user requirements, and channel economics intersect reveals where manufacturers capture disproportionate returns versus commoditized volume plays.
Product Type:
Progressive and photochromic configurations extract the widest margins by addressing dual-use scenarios in high-luminance African conditions.
- Single Vision:Dominates unit volume among school-age children requiring basic myopic correction with blue-light attenuation. Gauteng province's private optometry chains generate disproportionate prescription volumes for this configuration as digital screen exposure intensifies in Johannesburg and Pretoria classrooms.
- Photochromic:Dual-function lenses addressing high-luminance African sunlight and digital exposure command premium positioning. Cape Town's outdoor-active professional demographic drives specification upgrades for this fastest-expanding material-format intersection.
- Progressive:Capture disproportionate margin pools from senior professionals requiring near-intermediate digital workspace correction. Designs incorporate embedded absorptive dyes calibrated for extended screen use.
- Bifocal:Retains niche positioning among price-sensitive seniors with established prescription habits. Volume concentrates in peri-urban areas where ready readers compete on cost.
Single vision holds installed capacity. Photochromic is rotating up the share rankings.
End User:
Pediatric dispensing channels generate the steepest expansion trajectory as school health screening mandates formalize procurement.
- Children:School-age athletes and outdoor-program participants drive Trivex specification upgrades. The National Department of Health's screening programme channels demand toward certified dispensing channels, accelerating formal market penetration.
- Adults:Working professionals in Johannesburg's financial services sector sustain demand for progressive designs with precision surfacing. Cycloplegic refraction certification requirements limit practitioner availability.
- Seniors:Uncorrected refractive error substitution from informal retailers captures price-sensitive segments. Peri-urban areas see ready reader competition.
- Vision Correction Centers:Hospital-affiliated dispensing channels concentrate high-complexity prescriptions requiring specialized coating verification.
Children dominate volume velocity. Adults anchor value capture.
Material:
Impact resistance specifications are redrawing competitive boundaries between active and sedentary use cases.
- Polycarbonate:Precision surfacing achieving center thickness tolerances below 0.1 millimeters enables comfortable all-day wear. Historical dominance in pediatric dispensing faces compression from Trivex alternatives.
- Trivex:Low specific gravity reduces frame slippage during physical activity. School-age athletes in KwaZulu-Natal's outdoor education programmes drive specification upgrades.
- High-Index Plastic:Thin-profile designs for high myopic corrections retain premium positioning among image-conscious professionals.
- Glass:Minimal volume remains in specialized industrial safety applications requiring scratch resistance.
Polycarbonate retains volume leadership. Trivex is climbing the fastest in pediatric share.
Distribution Channel:
After-sales service unbundling is fragmenting value capture between front-end testing and specialized coating laboratories.
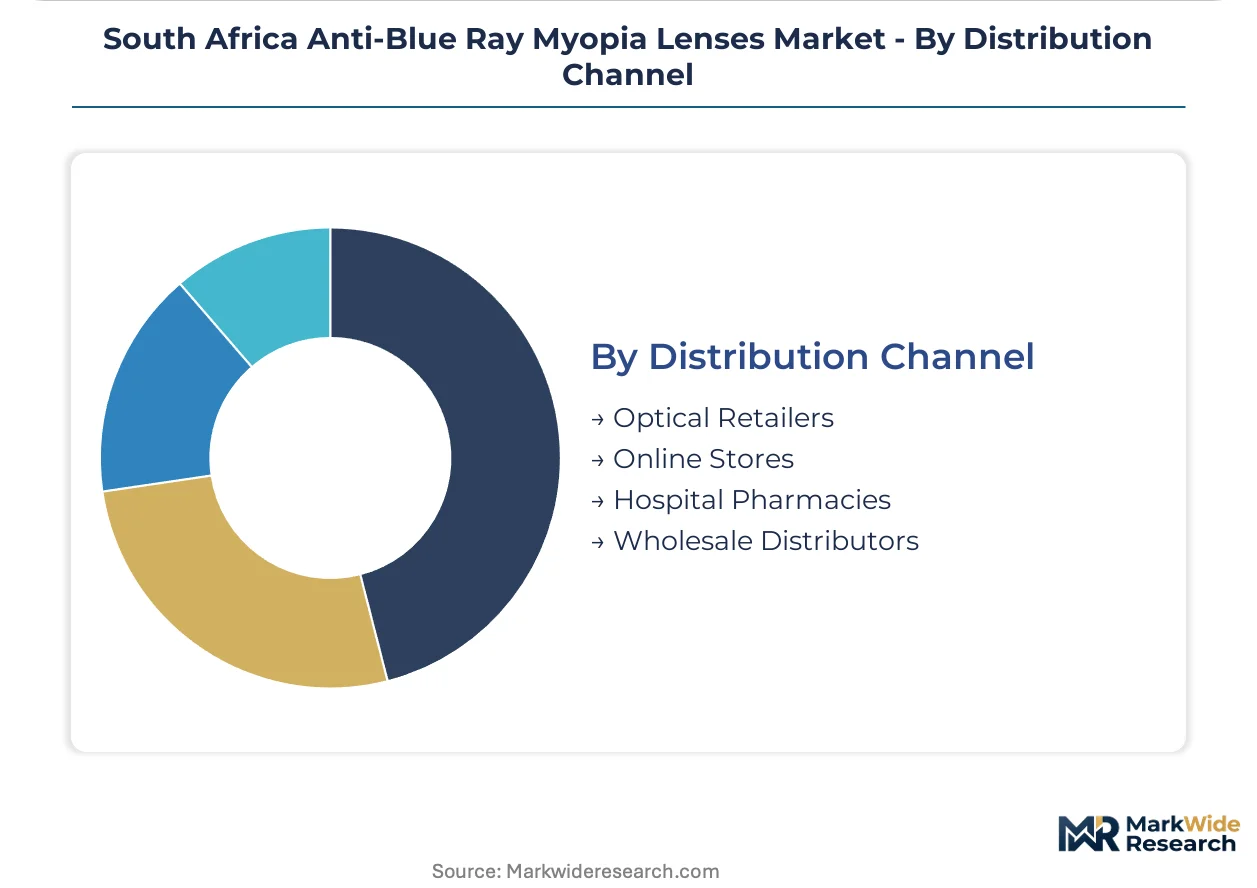
- Optical Retailers:Vertically integrated eye-testing and fitting networks across major metros anchor professional service revenue. Specsavers' footprint concentrates in Gauteng's urban clusters.
- Online Stores:Direct-to-consumer frame sourcing commoditizes front-end eye testing while demanding separate coating verification. Patients increasingly split procurement across channels.
- Hospital Pharmacies:Section 21 import authorization requirements create compliance thresholds for non-registered suppliers. Inventory holding periods extend pending SAHPRA renewals.
- Wholesale Distributors:Batch processing economies concentrate in Johannesburg's captive surfacing laboratories. Domestic laboratories with established registrations capture incremental volume.
Optical retailers defend service integration. Online stores are gaining share fastest in frame procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Gauteng province while Western Cape dispensers absorb margin compression from logistics fragmentation. Johannesburg and Pretoria command premium positioning through captive surfacing capacity and practitioner density. Peripheral provinces face extended turnaround times and coating verification bottlenecks.
Gauteng Province
Johannesburg's financial services sector sustains demand for progressive designs with precision surfacing, while Pretoria's government employee health schemes channel bulk procurement toward certified channels. The South African Health Products Regulatory Authority's Section 21 import authorizations create compliance thresholds that favor established laboratories with renewable registrations. Private optometry chains concentrate their footprint in Sandton and Centurion, generating economies of scale for coating batch processing.
Western Cape
Cape Town's outdoor-active professional demographic drives specification upgrades for photochromic-blue-light convergence lenses. The National Department of Health's school health screening programme channels paediatric demand toward certified dispensing channels, though practitioner density lags Gauteng. Stellenbosch and Somerset West clusters see emerging chain expansion targeting underpenetrated private healthcare density.
KwaZulu-Natal
Durban's coastal humidity accelerates coating degradation concerns, pushing specification upgrades toward embedded absorptive dyes over surface interference layers. The province faces acute shortages of practitioners certified for cycloplegic refraction in children. Richards Bay industrial corridor generates niche demand for industrial safety applications requiring scratch-resistant substrates.
Eastern Cape
Port Elizabeth's manufacturing legacy supports domestic surfacing laboratory investment as preferred procurement frameworks incentivize local content. Uncorrected refractive error substitution from informal retailers captures price-sensitive segments in peri-urban townships. East London's automotive sector sustains employer-funded vision benefit programmes with blue-light specifications.
South Africa Anti-Blue Ray Myopia Lenses Market Competitive Landscape
Concentration sits with multinational lens manufacturers possessing captive surfacing infrastructure and established regulatory registrations. Domestic dispensers fragment across independent practices and small chain networks, consolidating procurement volumes to survive margin compression. Two archetypes dominate: vertically integrated laboratories controlling coating-to-dispensing workflows, and technology licensors supplying substrate innovations to third-party fabricators. Competitive moves center on registration portfolio expansion and surfacing capacity localization.
Among multinational specialists, EssilorLuxottica, HOYA Corporation, and ZEISS occupy positions defined by proprietary coating technologies and African-market calibration capabilities. EssilorLuxottica represents the vertically integrated archetype through Johannesburg-based surfacing control. HOYA Corporation exemplifies substrate specialization with blue-light filtering technology adapted for high-luminance conditions. ZEISS anchors the precision-optics tier with established medical device registrations spanning multiple therapeutic categories.
| Leading Market Players |
|---|
| Rodenstock |
| Seiko Optical Products |
| EssilorLuxottica |
| Shamir Optical Industry |
| Nikon |
| ZEISS |
| Safilo Group |
| Specsavers |
| HOYA Corporation |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements with German and Japanese chemical specialists lock in coating precursor supply while anchoring price visibility for South African laboratories navigating SAHPRA registration renewal cycles. These arrangements insulate domestic surfacing operations from raw material volatility that would otherwise compress margins on pediatric single-vision configurations.
Pricing Analysis
The customization-premium spread separates configured-to-order progressive designs from standard single-vision stock lenses. Three-tier pricing structure across premium, standard, and economy levels reflects coating precision grades and SANS 1424 certification tiers. Price differentiation hinges on after-sales service bundling and cycloplegic refraction certification availability. Cost compression in economy tiers intensifies because informal ready readers capture peri-urban price-sensitive segments. Seniors in Eastern Cape townships exhibit highest price sensitivity; Gauteng financial services professionals show lowest.
Supply Chain Analysis
Inventory holding periods extending four to six months pending Section 21 authorization renewals strain working capital for imported lens portfolios. Sub-wavelength interference coating precursors draw from Germany and Japan; polycarbonate and Trivex substrates source from China and South Korea. Single-source vulnerability concentrates in specialized dye chemistry for high-luminance calibration. Distribution runs through Johannesburg's captive surfacing laboratories with batch processing economies, though Western Cape logistics fragmentation absorbs margin compression.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as school health screening mandates institutionalize pediatric procurement channels, creating predictable demand visibility absent in prior informal-dispensing eras.
For Market Incumbents: Fortify registration portfolio depth ahead of SAHPRA fee amendments to capture volume from foreign suppliers delaying re-registration investments. Expand captive surfacing capacity in Johannesburg to compress turnaround times against emerging chain competitors. Defensive consolidation through backward integration into coating precursor inventory buffers secures supply access during German-Japanese chemical specialist allocation cycles.
For New Entrants and Emerging Players: Anchor in Western Cape whitespace where Cape Town's private healthcare density remains underpenetrated relative to Gauteng. Target Stellenbosch and Somerset West clusters with photochromic-blue-light convergence positioning for outdoor-active professionals. Partner with hospital-affiliated vision correction centers for coating verification credibility without front-end testing infrastructure investment.
For Investors and Strategic Acquirers: Capital is best deployed toward domestic surfacing laboratories with established SAHPRA registrations and renewable Section 21 portfolios. Long-term viability across the five-to-ten year window hinges on localization incentives under pending Department of Trade and Industry preferred procurement frameworks. Monitor amendments to medical device registration fee structures as inflection indicator for import-dependent competitor margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Portfolio Expansion | Establishes compliance moat against foreign suppliers facing renewal delays. |
| Domestic Surfacing Capacity Addition | Captures localization incentives under preferred procurement frameworks. |
| Photochromic-Blue-Light Convergence Launch | Addresses dual-function demand from high-luminance African sunlight exposure. |
| Cycloplegic Refraction Certification Investment | Alleviates practitioner scarcity constraining pediatric dispensing growth. |
| After-Sales Service Unbundling Response | Concentrates value capture in specialized coating verification laboratories. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric optometrists, optical retail chain procurement managers, hospital pharmacy dispensing heads, and SAHPRA regulatory affairs specialists. Secondary validation drew from SAHPRA medical device registration databases, South African Bureau of Standards optical testing records, National Department of Health school health screening programme documentation, and private optometry chain expansion filings. Bottom-up prescription volume modeling triangulated against top-down market size estimates.
Across the analysis window, forecasts incorporate product type configurations, end-user age cohorts, material substrate specifications, and distribution channel structures. CAGRs derive from segmented growth trajectory analysis calibrated to pediatric screening mandate implementation pace and coating technology adoption curves. Industry-specific inputs include cycloplegic refraction practitioner availability indices and Section 21 authorization timeline distributions.
Decision-makers should treat outputs as directional under stable regulatory fee assumptions and continued school health screening programme funding; material deviation in SAHPRA processing timelines or preferred procurement local content thresholds would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
South Korea Ultrasound Devices Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Europe Invisible Orthodontics Market
Medical Devices
Bioactive Fillings Market
Medical Devices
Sphincterotomes Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Powered Mattress System Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
Medical Device Trays Market
Medical Devices
US Prefilled Syringes Market