
 Cardiopulmonary Bypass System Market | 2026-2036
Cardiopulmonary Bypass System Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiopulmonary Bypass System Market Outlook
The gap between premium integrated perfusion platforms and commodity oxygenator assemblies is broadening as procurement criteria diverge across developed and emerging health systems. LivaNova leverages its integrated hardware-software ecosystems to command premium positioning in North American academic medical centers. Medtronic anchors its presence through sustained R&D investment in miniaturized pump architectures. Terumo competes aggressively on membrane oxygenator performance metrics across Asian markets.
A cardiopulmonary bypass system constitutes a temporary extracirculatory support apparatus that oxygenates and circulates blood while the heart is arrested during open-chest procedures, typically incorporating a pump, oxygenator, heat exchanger, and tubing circuit with biocompatible surface coatings. Membrane oxygenation technology leads installed base volumes due to established clinical validation and predictable gas exchange performance, while centrifugal pump configurations represent the fastest-growing technology segment as surgeons adopt lower-shear hemolytic profiles for prolonged perfusion runs. The oxygenator product category captures the deepest margin pools owing to disposable replenishment cycles and proprietary membrane chemistries.
The FDA's premarket approval requirements for Class III cardiovascular devices and Europe's MDR transition enforce rigorous clinical evidence standards that filter market access for smaller manufacturers. China's NMPA has accelerated review timelines for innovative perfusion devices while maintaining mandatory domestic clinical trial requirements. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs reshape competitive viability across oxygenator and pump subsystems.
Market Dynamics
Centrifugal pump architectures are rewriting competitive positioning by enabling prolonged perfusion runs with reduced hemolysis, forcing manufacturers to recalibrate R&D roadmaps around hemocompatibility metrics rather than raw flow capacity.
Growth Catalysts
- China's NMPA accelerated review pathways:Domestic clinical trial mandates for innovative perfusion devices compress time-to-market for compliant manufacturers, concentrating investment in Shanghai and Beijing cardiac surgery hubs.
- Membrane oxygenator replenishment cycles:Disposable replacement schedules create predictable revenue streams for suppliers serving high-volume academic medical centers with established open-heart programs.
- Heat exchanger integration:Combined temperature management and oxygenation modules reduce circuit complexity, accelerating adoption in German and US tertiary care facilities prioritizing surgical efficiency.
Market Restraints
- Polyurethane and silicone membrane feedstock volatility:Specialty polymer supply concentrates among Japanese and German chemical suppliers, exposing oxygenator manufacturers to input cost swings.
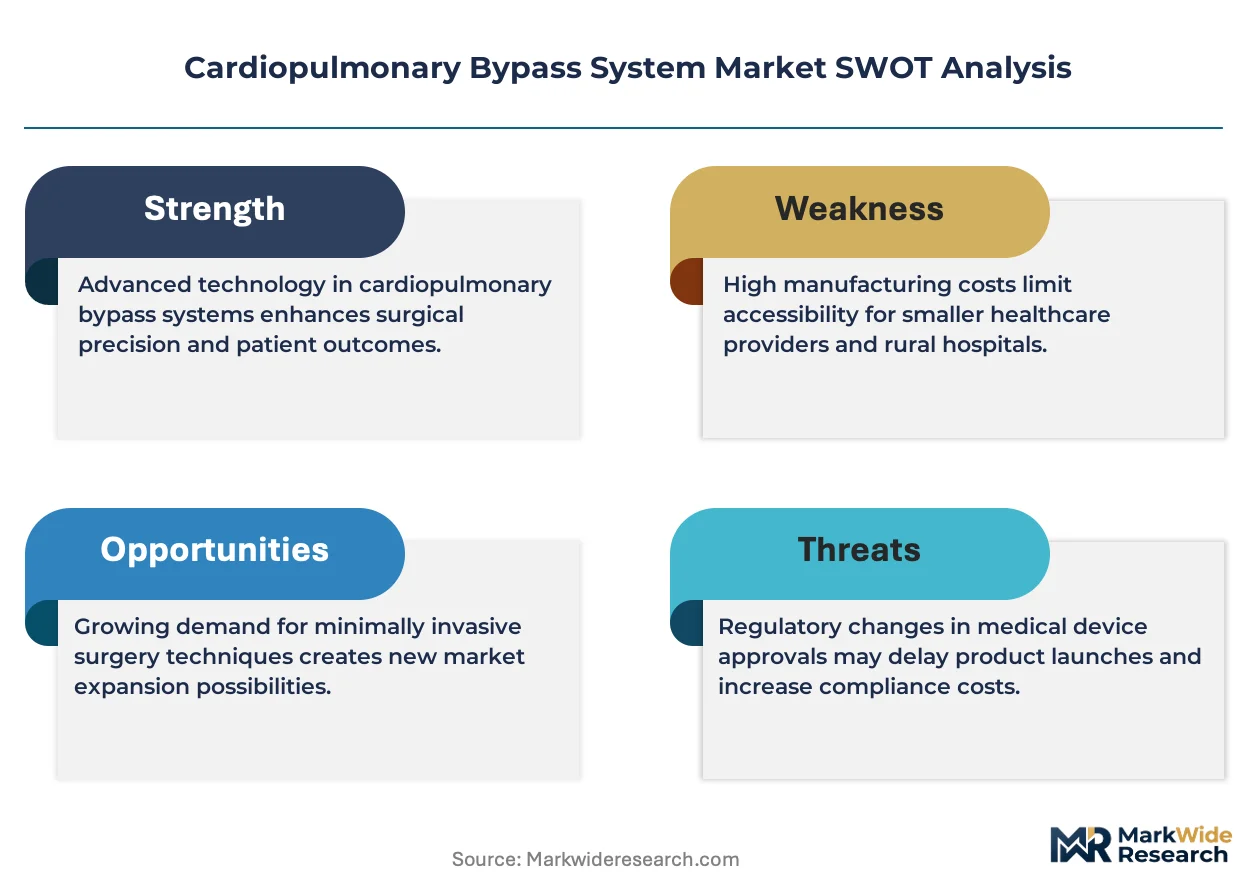
- Europe's MDR compliance burden:Clinical evidence requirements for Class III cardiovascular devices filter market access, elevating compliance costs disproportionately for smaller subsystem vendors.
- Extracorporeal membrane oxygenation (ECMO) substitution:Portable long-term circulatory support platforms capture select cardiac surgery cases, constraining addressable volume for conventional bypass configurations.
Strategic Opportunities
- India's underserved cardiac surgery infrastructure:Government PLI scheme incentives for medical device manufacturing attract perfusion system assembly investments targeting tier-2 city hospital expansions.
- Pump-oxygenator software convergence:Real-time hematocrit and venous saturation analytics integrated into centrifugal pump controllers create premium positioning for hardware-software bundled offerings.
- Direct hospital procurement platforms:Bypass traditional distributor markups through GPO-integrated digital procurement channels capturing volume commitments from US health system consolidations.
Industry Challenges
- Perfusionist workforce scarcity:Specialized certification requirements and aging practitioner demographics constrain operating room throughput in expanding cardiac surgery programs.
- Legacy tubing circuit incompatibility:Biocoated connector standards fragment across manufacturer ecosystems, forcing hospitals to maintain redundant inventory or commit to single-vendor lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiopulmonary Bypass System Market |
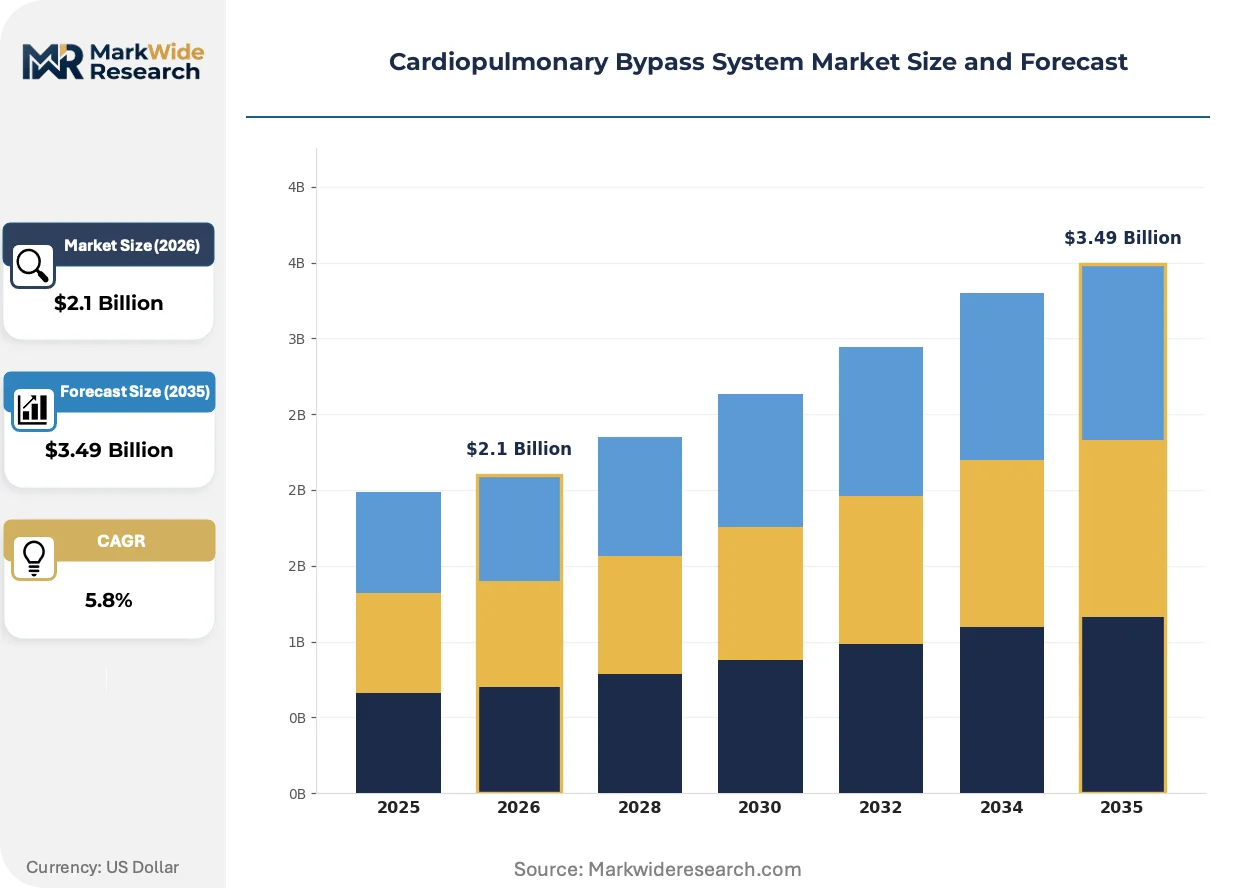
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracorporeal Circulation System, Cardiopulmonary Bypass Pump, Oxygenator, Aortic Cannula Technology: Membrane Oxygenation, Roller Pump, Centrifugal Pump, Hybrid System End User: Hospitals, Cardiac Surgery Centers, Specialty Clinics, Research Institutions Application: Heart Surgery, Lung Surgery, Cardiac Arrest Treatment, Transplant Surgery |
| Companies Covered | LivaNova, Medtronic, Terumo, Getinge, MAQUET Holding, Braile Biomedica, B. Braun Melsungen, Fresenius Medical Care, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiopulmonary Bypass System Market Strategic Shifts
Perfusion technology is converging around patient-specific physiological modeling, with computational fluid dynamics and sensor fusion enabling real-time adaptive control that reduces post-operative complications.
Magnetic levitation centrifugal pump designs eliminate mechanical bearings and seal contact points, delivering shear stress profiles below 10 Pa across operational flow ranges. Academic medical centers in Germany and the United States are prioritizing these configurations for complex aortic reconstructions exceeding four hours. This architecture is rewriting performance benchmarks for prolonged circulatory support, compressing differentiation windows for conventional roller pump suppliers.
Europe's MDR transition enforces Unique Device Identification traceability and post-market clinical follow-up obligations for all Class III cardiovascular devices. Manufacturers must maintain systematic literature review processes and periodic safety update reports, elevating documentation burdens. Oxygenator subsystem suppliers face the steepest compliance recalibration, with notified body capacity constraints extending certification timelines.
Hospital purchasing consortia are consolidating procurement authority for cardiopulmonary bypass disposables, shifting negotiation leverage toward volume-committed health systems. Integrated delivery networks in the United States now mandate standardized circuit configurations across member facilities, displacing individualized surgeon preference contracts. This concentration is most visible in Texas and Florida markets where private equity-backed hospital rollups dominate cardiac service line expansion.
Cardiopulmonary Bypass System Market Segmentation
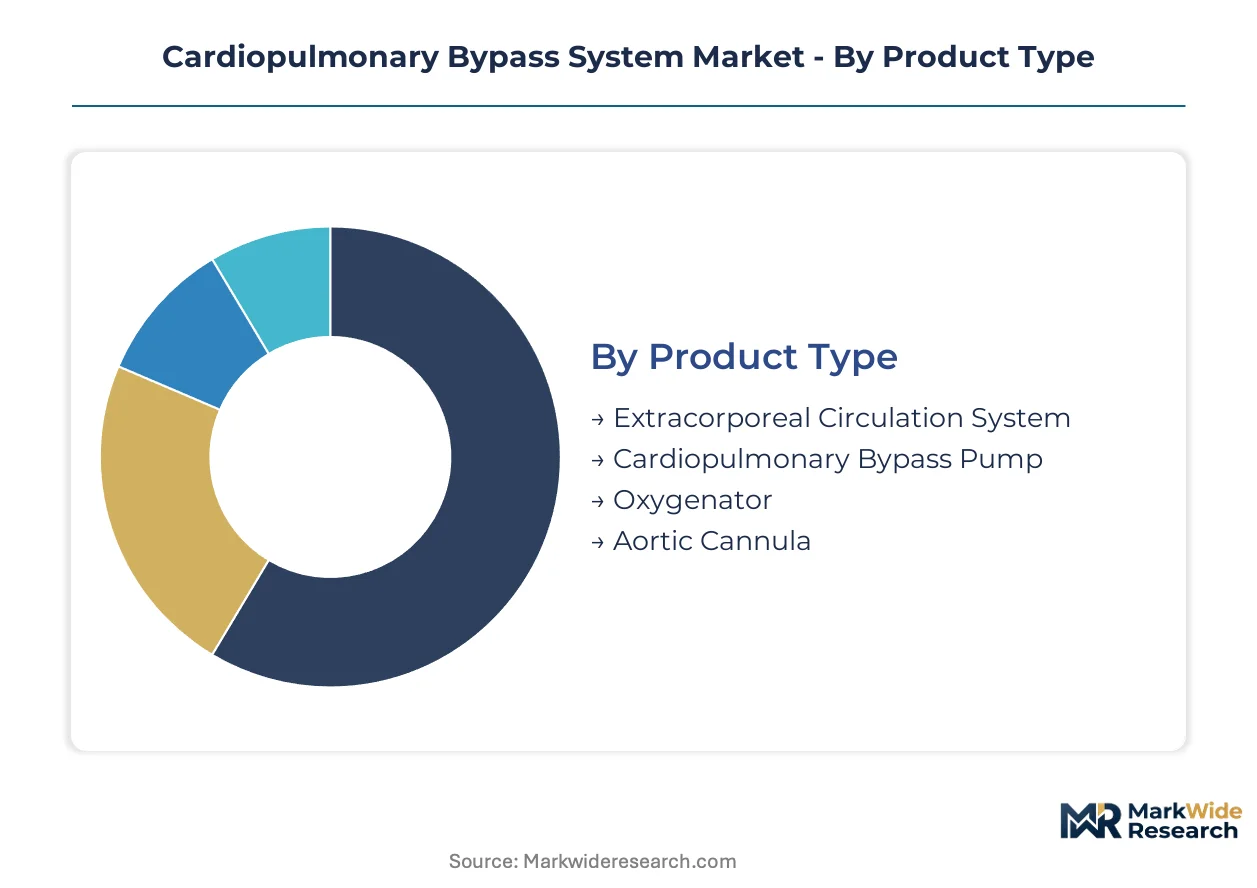
Segmentation in the cardiopulmonary bypass system market reveals how procurement criteria diverge across clinical settings and surgical complexity tiers. Manufacturers must align product architectures with distinct performance thresholds governing oxygenator selection, pump configuration, and circuit integration.
Product Type:
Material composition and replacement economics distinguish procurement decisions across hardware categories.
- Oxygenator:Membrane-based gas exchange modules with proprietary polymer chemistries command premium positioning through disposable replenishment cycles. Academic medical centers in Germany and the United States prioritize oxygenators with integrated arterial filters and biocompatible coatings that reduce platelet activation during prolonged perfusion.
- Extracorporeal Circulation System:Complete integrated platforms combining pump, oxygenator, heat exchanger, and tubing circuits into standardized configurations. Hospital purchasing consortia in Texas and Florida mandate these systems for volume-committed procurement across consolidated cardiac service lines.
- Cardiopulmonary Bypass Pump:Centrifugal and roller pump architectures delivering controlled blood flow during arrested cardiac states.
- Aortic Cannula:Vascular access devices establishing arterial inflow for systemic perfusion with varying tip geometries and flow characteristics.
Oxygenators lead on scale; extracorporeal circulation systems lead on momentum.
Technology:
Shear stress profiles and hemocompatibility metrics now override raw flow capacity in technology selection.
- Centrifugal Pump:Magnetically levitated impeller designs eliminate mechanical bearings, delivering shear stress below 10 Pa across operational ranges. Surgeons in German tertiary facilities adopt these configurations for complex aortic reconstructions exceeding four hours, prioritizing reduced hemolysis over cost considerations.
- Membrane Oxygenation:Hollow-fiber or flat-sheet polymer membranes enabling diffusive gas exchange with predictable performance validated across decades of clinical use. China's NMPA accelerated review pathways concentrate domestic investment in membrane oxygenator production for Shanghai and Beijing cardiac surgery hubs.
- Roller Pump:Peristaltic compression mechanisms with established reliability profiles and lower capital requirements.
- Hybrid System:Configurations combining centrifugal pumping with membrane oxygenation in modular architectures.
Membrane oxygenation leads on scale; centrifugal pump configurations expand most quickly.
End User:
Capital intensity and case volume thresholds determine facility-level adoption patterns.
- Hospitals:Tertiary care institutions with dedicated cardiac surgery departments performing high volumes of open-heart procedures. India's PLI scheme incentives attract perfusion system assembly investments targeting tier-2 city hospital expansions where government infrastructure programs concentrate procurement.
- Cardiac Surgery Centers:Specialized facilities focused exclusively on cardiovascular interventions with streamlined supply chains.
- Specialty Clinics:Limited-service settings performing diagnostic catheterization and minor interventional procedures.
- Research Institutions:Academic centers conducting preclinical device validation and perfusion protocol development.
Hospitals dominate absolute volume; cardiac surgery centers gain share fastest.
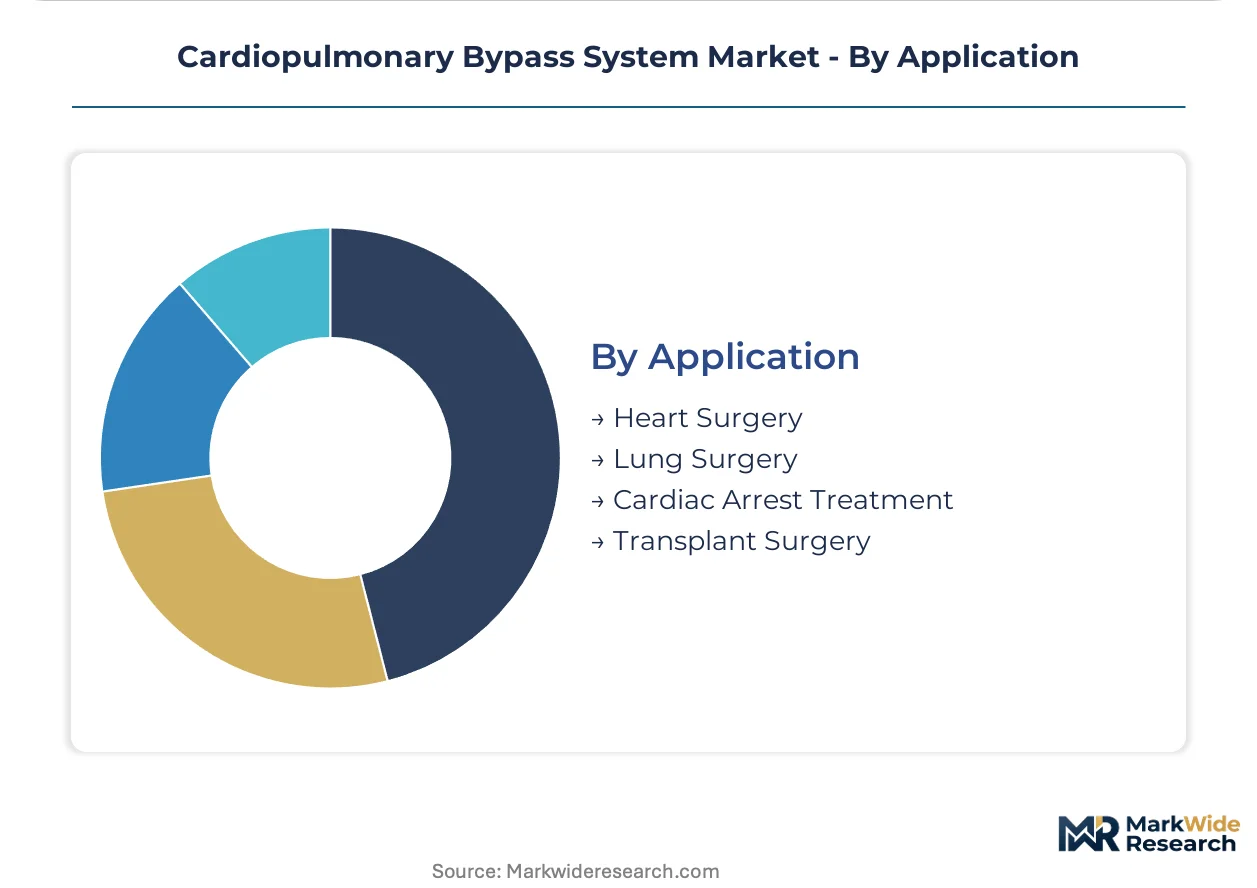
Application:
Surgical complexity and perfusion duration requirements shape device specification priorities.
- Heart Surgery:Coronary artery bypass grafting, valve replacement, and congenital defect correction requiring full cardiopulmonary support. US integrated delivery networks standardize circuit configurations across member facilities for these high-volume procedures.
- Transplant Surgery:Orthotopic heart and lung replacement operations demanding extended perfusion runs with minimal organ ischemia.
- Lung Surgery:Pneumonectomy and lobectomy procedures with selective pulmonary support requirements.
- Cardiac Arrest Treatment:Emergency resuscitation scenarios with portable bypass configurations.
Heart surgery leads on scale; transplant surgery shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's tertiary cardiac surgery infrastructure outpaces France in centrifugal pump adoption density, while China's NMPA accelerated review timelines compress domestic manufacturers' time-to-market against multinational incumbents.
United States
Integrated delivery networks in Texas and Florida consolidate procurement authority across private equity-backed hospital rollups. FDA premarket approval requirements for Class III cardiovascular devices enforce rigorous clinical evidence standards that filter market access. Academic medical centers in Boston and Houston prioritize magnetically levitated centrifugal pump configurations for complex aortic reconstructions exceeding four hours.
Germany
Notified body capacity constraints under Europe's MDR transition extend certification timelines for oxygenator subsystem suppliers. The country's national pharmaceutical regulator enforces Unique Device Identification traceability and post-market clinical follow-up obligations. Tertiary care clusters in Bavaria and North Rhine-Westphalia standardize combined temperature management and oxygenation modules to reduce circuit complexity.
China
Shanghai and Beijing cardiac surgery hubs concentrate domestic investment in membrane oxygenator production. The NMPA maintains mandatory domestic clinical trial requirements while accelerating review timelines for innovative perfusion devices. Government infrastructure programs target tier-2 city hospital expansions with procurement incentives for locally assembled systems.
India
Government PLI scheme incentives attract perfusion system assembly investments targeting underserved cardiac surgery infrastructure. The Central Drugs Standard Control Organization regulates medical device manufacturing quality benchmarks. Tier-2 city hospital expansions in Maharashtra and Karnataka concentrate procurement volume as cardiac service lines extend beyond metropolitan centers.
Cardiopulmonary Bypass System Market Competitive Environment
Top-tier vendors anchor premium integrated perfusion platforms, while mid-tier specialists compete on membrane oxygenator performance metrics and disposable replenishment economics. The vendor base stratifies across three tiers: multinational conglomerates with hardware-software ecosystems, regional subsystem specialists with proprietary chemistries, and emerging domestic assemblers leveraging government manufacturing incentives. Two strategic archetypes dominate: integrated platform providers bundling real-time analytics with centrifugal pump controllers, and component specialists capturing margin pools through proprietary membrane replacement cycles. Competitive moves concentrate on M&A for regulatory compliance capabilities and capacity expansion in Asian manufacturing hubs.
Within the integrated platform tier, LivaNova and Medtronic occupy positions exemplifying hardware-software ecosystem strategies, while Terumo represents the membrane oxygenator specialist archetype competing aggressively on performance metrics. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning: London-registered LivaNova, Irish-domiciled Medtronic, and Japanese Terumo each reflect distinct regulatory navigation strategies and regional market prioritization.
| Leading Market Players |
|---|
| LivaNova |
| Medtronic |
| Terumo |
| Getinge |
| MAQUET Holding |
| Braile Biomedica |
| B. Braun Melsungen |
| Fresenius Medical Care |
| MicroPort Scientific Corporation |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up hospital systems in Texas and Florida concentrate procurement leverage through standardized circuit configurations, compressing distributor margins while elevating volume-commitment discounts as the dominant pricing discipline across oxygenator and pump subsystems.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated perfusion platforms with real-time analytics from commodity oxygenator assemblies sold on replacement cycles. Three-tier pricing structure across premium, standard, and economy levels reflects centrifugal pump performance grades and membrane chemistry proprietary positions. Cost compression in standard-tier disposable circuits is intensifying because hospital purchasing consortia mandate cross-facility standardization. Tier-2 city hospitals in emerging markets exhibit highest price sensitivity; academic medical centers in Germany and the United States demonstrate lowest sensitivity due to clinical outcome prioritization.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's NMPA clinical trial requirements are reshaping sourcing patterns toward locally assembled perfusion systems with reduced import dependency. Specialty polymer feedstock for membrane oxygenators draws from Japan and Germany, while pump motor and sensor components source from the United States and China. Single-source vulnerability concentrates in hollow-fiber membrane production, where three chemical suppliers control global capacity. Distribution runs through GPO-integrated channels in consolidated US markets and government procurement platforms in China and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where regulatory compliance costs in Europe's MDR transition run three to four times higher than China's NMPA accelerated pathways, creating divergent investment returns across manufacturing location choices.
For Market Incumbents: Acquire regulatory compliance capabilities, specifically notified body relationships and systematic literature review infrastructure, to defend against ECMO substitution threats and MDR certification bottlenecks. Backward integration into proprietary membrane chemistry production secures margin pools against Japanese and German polymer supplier pricing power. Capacity addition in Shanghai and Beijing cardiac surgery hubs captures NMPA pathway advantages. For New Entrants and Emerging Players: Tier-2 city hospitals in India's Maharashtra and Karnataka represent the most penetrable buyer archetype, with government infrastructure programs concentrating procurement volume and PLI scheme incentives reducing capital barriers. Unbundled oxygenator replacement cycles offer faster revenue traction than integrated platform competition. Go-to-market through direct hospital procurement platforms bypasses legacy distributor markups. For Investors and Strategic Acquirers: Valuations sit cheapest among regional subsystem specialists with proprietary membrane chemistries and established domestic clinical trial data packages. Long-term viability across the analysis window hinges on software-hardware convergence capabilities and regulatory navigation expertise. Watch NMPA review timeline compression and MDR notified body capacity constraints as inflection indicators for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Europe's MDR transition extends certification timelines for oxygenator subsystem suppliers facing notified body constraints. |
| Hospital System Partnership | Integrated delivery networks in Texas and Florida mandate standardized circuit configurations across member facilities. |
| Software Companion Development | Real-time hematocrit analytics bundled with centrifugal pump controllers command premium positioning in academic medical centers. |
| Reimbursement Strategy | Government infrastructure programs in China and India concentrate procurement incentives for locally assembled systems. |
| FDA Submission | Premarket approval requirements for Class III cardiovascular devices filter market access to manufacturers with clinical evidence capabilities. |
Study Parameters
Multiple input streams — perfusionist interviews, hospital purchasing committee discussions, GPO contracts analysis, and biomedical engineer consultations — were reconciled with secondary validation from FDA 510(k) filings, NMPA registration databases, hospital procurement records, and European notified body certification logs. Bottom-up modeling of oxygenator replacement cycles and centrifugal pump installation bases was cross-checked against top-down market sizing from trade data and industry association reports.
Historical shipment data was cross-referenced against expert panel input across product type, technology configuration, end-user facility tier, and surgical application complexity dimensions. CAGRs were derived from segmented growth trajectory analysis incorporating membrane oxygenator replenishment economics, centrifugal pump adoption curves, and regulatory timeline impacts. Forecast inputs included perfusionist workforce demographics, hospital consolidation patterns, and domestic-content mandate implementation schedules.
Underlying measurement precision varies by segment; oxygenator volume data carries tighter precision than emerging centrifugal pump adoption curves due to established disposable tracking systems. Forecasts reflect assumptions about regulatory pathway stability, polymer feedstock availability, and hospital capital expenditure continuity. A small set of triggers — MDR notified body capacity, NMPA review acceleration, and ECMO technology substitution rates — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Active Humidifier Devices Market
Medical Devices
Pre-Owned Medical Devices Market
Medical Devices
Batteries for Skin Patches Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Blood Collection Vacuum Devices Market
Medical Devices
Retinal Implant Market
Medical Devices
Walking Aids Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
Global Gel Stent Market
Medical Devices
Memory Implants Market
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Global Self Care Medical Devices Market