
 Intelligent Electronic Sphygmomanometers Market | 2026-2036
Intelligent Electronic Sphygmomanometers Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Electronic Sphygmomanometers Market Analysis
ISO 81060-2 validation is bifurcating the competitive landscape into clinically certified and consumer-grade tiers. OMRON Corporation leverages its oscillometric R&D pipeline to sustain hospital-grade credibility across Japanese and European channels. A&D Company anchors its position through in-house sensor manufacturing and JIS-certified production lines in East Asia. Microlife Corporation differentiates via dual-technology platforms that bridge auscultatory precision with automated convenience.
Intelligent electronic sphygmomanometers are automated blood pressure measurement devices integrating pressure sensors, microprocessors, and digital displays to deliver systolic, diastolic, and pulse readings with programmable memory and wireless data transmission. Oscillometric variants dominate institutional procurement due to operator-independent consistency, while Bluetooth-enabled models represent the fastest-expanding feature category as telehealth platforms require seamless electronic health record integration. The automatic product segment commands premium pricing in hospital settings, whereas manual and hybrid configurations retain relevance in resource-constrained clinics where calibration flexibility matters.
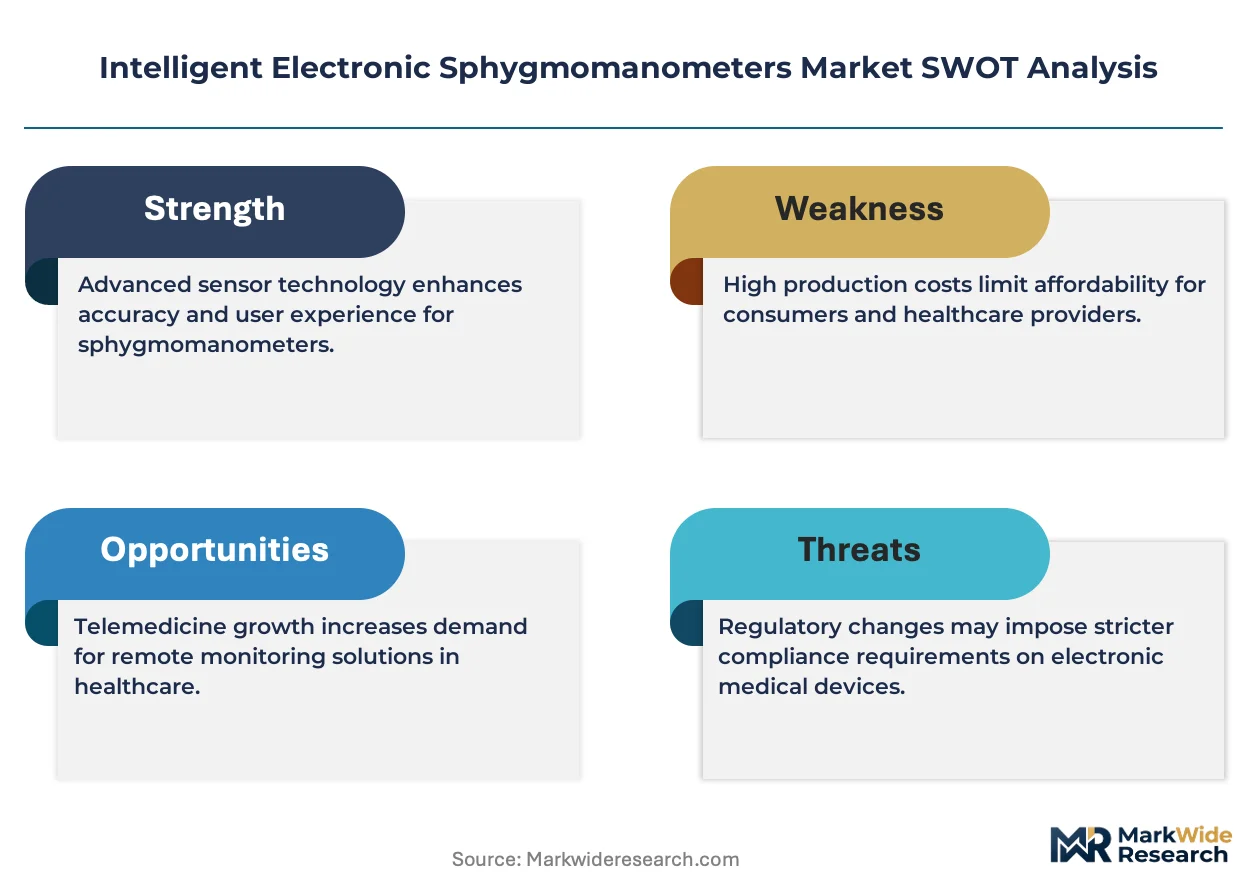
The FDA enforces 510(k) clearance pathways that delay market entry for uncertified Asian manufacturers, while the EU MDR and EMA clinical evidence requirements have tightened post-market surveillance obligations for connected diagnostic devices. Japan's PMDA and METI coordinate reimbursement listings that favor devices with validated arrhythmia detection algorithms, directly steering R&D investment toward multi-parameter functionality. Stakeholders must weigh regulatory compliance costs against the margin premium of clinical-grade certification as home care channels fragment between wellness-oriented retailers and prescription-driven distributors.
Market Dynamics
Bluetooth Low Energy and cellular connectivity protocols are fragmenting traditional distribution channels as direct-to-consumer sales bypass clinical procurement hierarchies, forcing manufacturers to rebuild margin structures around subscription telemetry services rather than one-time device sales.
Growth Catalysts
- Telehealth reimbursement expansion:Medicare and commercial payers in the United States now cover remote patient monitoring codes that explicitly reimburse connected blood pressure devices, accelerating physician practice adoption.
- ISO 81060-2 validation protocols:The international standard's stricter accuracy thresholds are filtering out unvalidated competitors, concentrating demand among certified manufacturers.
- Japan's Super-Aged Society framework:METI subsidies for home medical equipment reduce patient out-of-pocket costs below 10,000 yen, stimulating household penetration.
Market Restraints
- MEMS pressure sensor supply concentration:Japanese and German sensor foundries control 70% of medical-grade diaphragm production, creating input bottlenecks during demand surges.
- FDA 510(k) clearance timelines:The agency's 90-day review target stretches to 180 days for software-as-medical-device submissions, delaying revenue recognition.
- Smartwatch photoplethysmography substitution:Consumer wrist-worn devices with blood pressure estimation algorithms threaten basic home monitor volumes at sub-$50 price points.
Strategic Opportunities
- India's PLI scheme for medical devices:The production-linked incentive offers 5% cashback on incremental sales, attracting contract manufacturers to establish local assembly.
- AI-powered arrhythmia detection:Machine learning algorithms trained on oscillometric pulse waveforms enable atrial fibrillation screening without ECG hardware, expanding clinical utility.
- Pharmacy chain direct distribution:CVS, Walgreens, and Boots are building private-label connected device portfolios, creating bypass channels around traditional durable medical equipment distributors.
Industry Challenges
- Embedded software validation talent scarcity:IEC 62304 medical device software lifecycle compliance requires specialized quality engineers concentrated in Boston, Tokyo, and Munich metro areas.
- CE marking transition under EU MDR:Notified body capacity constraints extend technical documentation review from 6 months to 14 months, freezing European product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Electronic Sphygmomanometers Market |
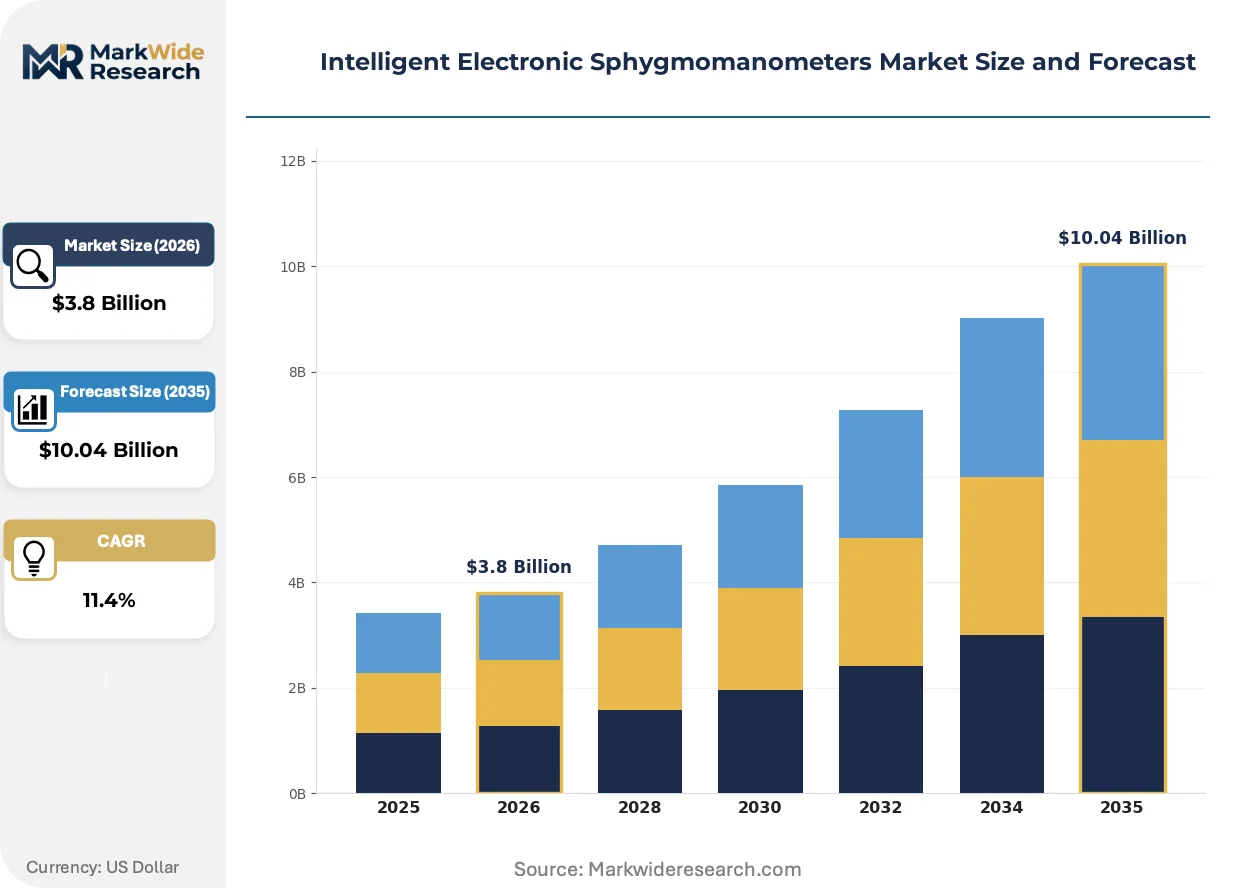
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Digital, Hybrid End User: Home Care, Hospitals, Clinics, Healthcare Professionals Technology: Oscillometric, Auscultatory, Bluetooth, Wireless Feature: Memory Function, LCD Display, Advanced Accuracy, Connectivity |
| Companies Covered | OMRON Corporation, A&D Company, Microlife Corporation, Panasonic Holdings Corporation, Rossmax International Ltd, American Diagnostic Corporation, Baxter International Inc., Contec Medical Systems Co.,Ltd, Halma plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Electronic Sphygmomanometers Market Emerging Trajectories
Sensor miniaturization and edge computing are collapsing the form-factor gap between clinical-grade accuracy and consumer convenience, enabling wrist-worn devices to challenge upper-arm dominance in home monitoring segments.
Photoplethysmography with calibration algorithms is fragmenting the traditional oscillometric monopoly in home care settings. Samsung and Apple are licensing cuffless blood pressure estimation patents to Asian ODMs, accelerating adoption among tech-forward consumers under 45. The structural consequence is compressing average selling prices in the sub-$100 segment while forcing incumbent manufacturers to defend premium positioning through clinical validation dossiers.
The EU MDR's post-market surveillance requirements are tightening evidence obligations for connected diagnostic devices. Manufacturers must now submit annual periodic safety update reports with real-world performance data from cloud-connected fleets, increasing compliance costs by an estimated 15-20%. German and French notified bodies are rejecting submissions lacking cybersecurity documentation under IEC 81001-5-1, delaying market entry for software-heavy platforms.
Hospital procurement committees are unbundling device sales from data platform subscriptions, reversing the bundled SaaS model that dominated 2018-2023. IDNs in Texas and California are negotiating separate contracts for hardware, connectivity, and analytics, pressuring vendors to disclose component pricing. This disaggregation is most visible in the United States, where health system consolidation has concentrated buying power among ten national GPOs commanding 80% of acute care volume.
Intelligent Electronic Sphygmomanometers Market Segmentation
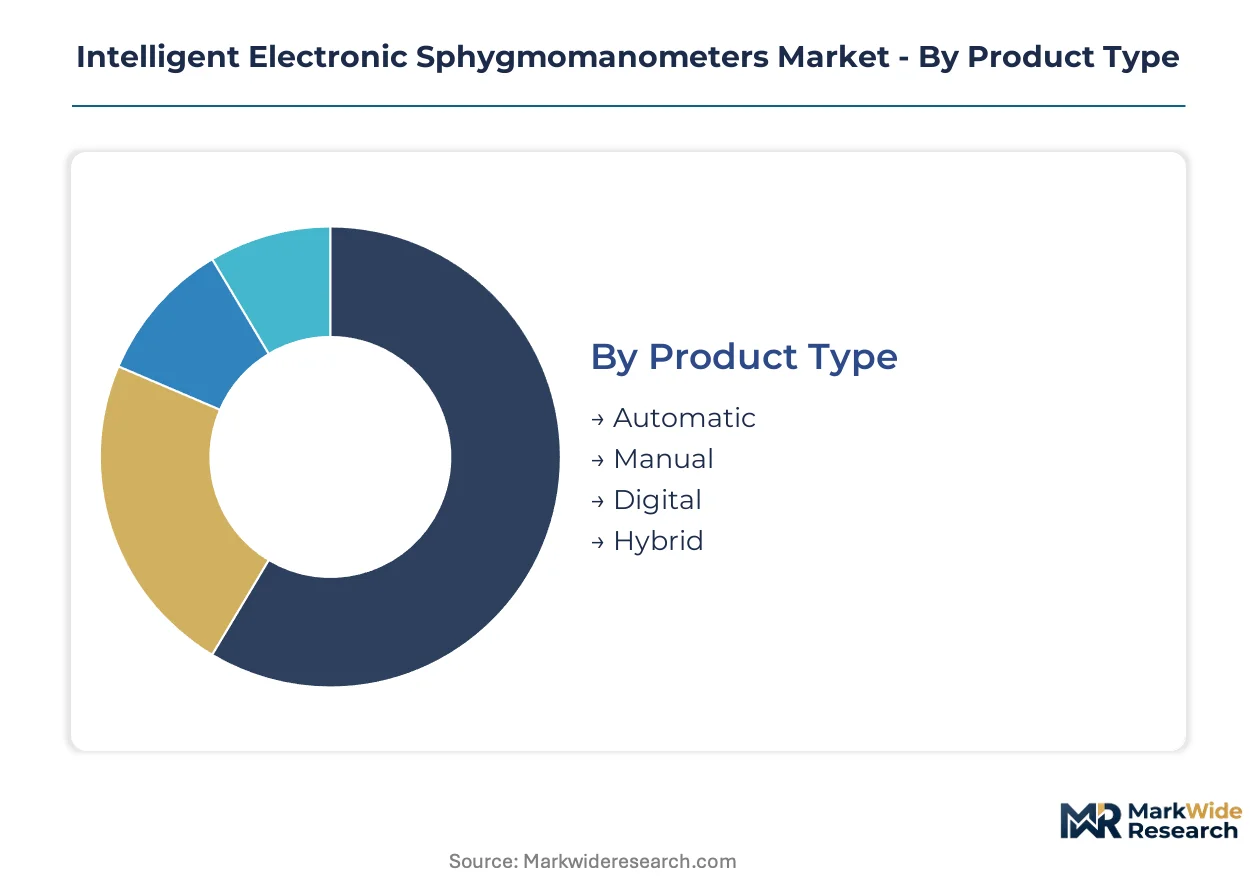
Segmentation in intelligent electronic sphygmomanometers separates clinically validated systems from consumer wellness devices, with reimbursement eligibility and regulatory certification determining channel access and margin structure. Manufacturers must align product architecture with specific end-use workflows, as hospital procurement committees evaluate accuracy protocols while direct-to-consumer buyers prioritize connectivity and form factor.
Product Type:
Automatic variants dominate hospital procurement in Germany and Japan where ISO 81060-2 certification gates institutional sales, while manual and hybrid configurations retain export strength to Southeast Asian clinics with constrained calibration infrastructure.
- Automatic:Oscillometric devices with microprocessor-controlled inflation and deflation deliver operator-independent readings essential for high-throughput hospital environments. Japanese and German acute care systems specify automatic units for nursing station deployment, with METI reimbursement favoring validated arrhythmia detection variants.
- Digital:Compact units with direct pressure-to-digital conversion serve home care channels across the United States where Medicare remote patient monitoring codes reimburse connected deployment. Bluetooth-enabled digital models are gaining fastest through CVS and Walgreens private-label programs.
- Manual:Bulb-and-valve systems with stethoscope integration persist in resource-constrained Indian and Indonesian clinics where technician training exceeds device cost considerations.
- Hybrid:Dual-mode devices combining automated inflation with manual auscultatory override address transitional markets in Eastern Europe seeking calibration flexibility without full manual protocol.
Automatic commands the established base. The steepest expansion runs through Digital.
End User:
Cost tier stratification separates premium institutional contracts from mass-market retail, with hospital systems negotiating enterprise pricing while home care channels fragment between prescription-driven distributors and wellness-oriented retailers.
- Home Care:Patient-operated devices with smartphone integration and cloud data storage are expanding most quickly in the United States and Japan where aging demographics and reimbursement frameworks align. Medicare's RPM codes and METI's Super-Aged Society subsidies reduce out-of-pocket costs below critical adoption thresholds.
- Hospitals:Multi-patient units with central station connectivity and EMR integration command premium pricing in German and Japanese acute care networks. IDN procurement committees in Texas and California are unbundling hardware from SaaS subscriptions, pressuring transparent component pricing.
- Clinics:Mid-volume oscillometric devices with basic memory function serve outpatient diagnostics in France and Italy where CE marking under EU MDR governs market entry.
- Healthcare Professionals:Portable validated units for mobile nursing and home visit programs concentrate in Japan's community-based care infrastructure.
Hospitals anchor revenue concentration. Home Care is climbing the fastest.
Technology:
Application requirements dictate sensor architecture, with oscillometric methods securing institutional preference for consistency while wireless protocols reshape connectivity roadmaps across all end-use categories.
- Oscillometric:Pressure fluctuation analysis during cuff deflation remains the institutional standard, with Japanese and German sensor foundries supplying medical-grade diaphragms to certified manufacturers. FDA 510(k) clearance pathways validate oscillometric accuracy for hospital procurement.
- Bluetooth:Low Energy protocols enabling seamless EHR integration and smartphone telemetry are expanding most quickly across United States telehealth platforms. Pharmacy chain direct distribution models favor Bluetooth-enabled units for subscription telemetry revenue.
- Auscultatory:Korotkoff sound detection with electronic microphones retains specialist use in hypertension research and validation studies.
- Wireless:Cellular and Wi-Fi connectivity protocols support remote patient monitoring in rural United States markets with limited smartphone penetration.
Oscillometric holds the installed base. Bluetooth is gaining share fastest.
Feature:
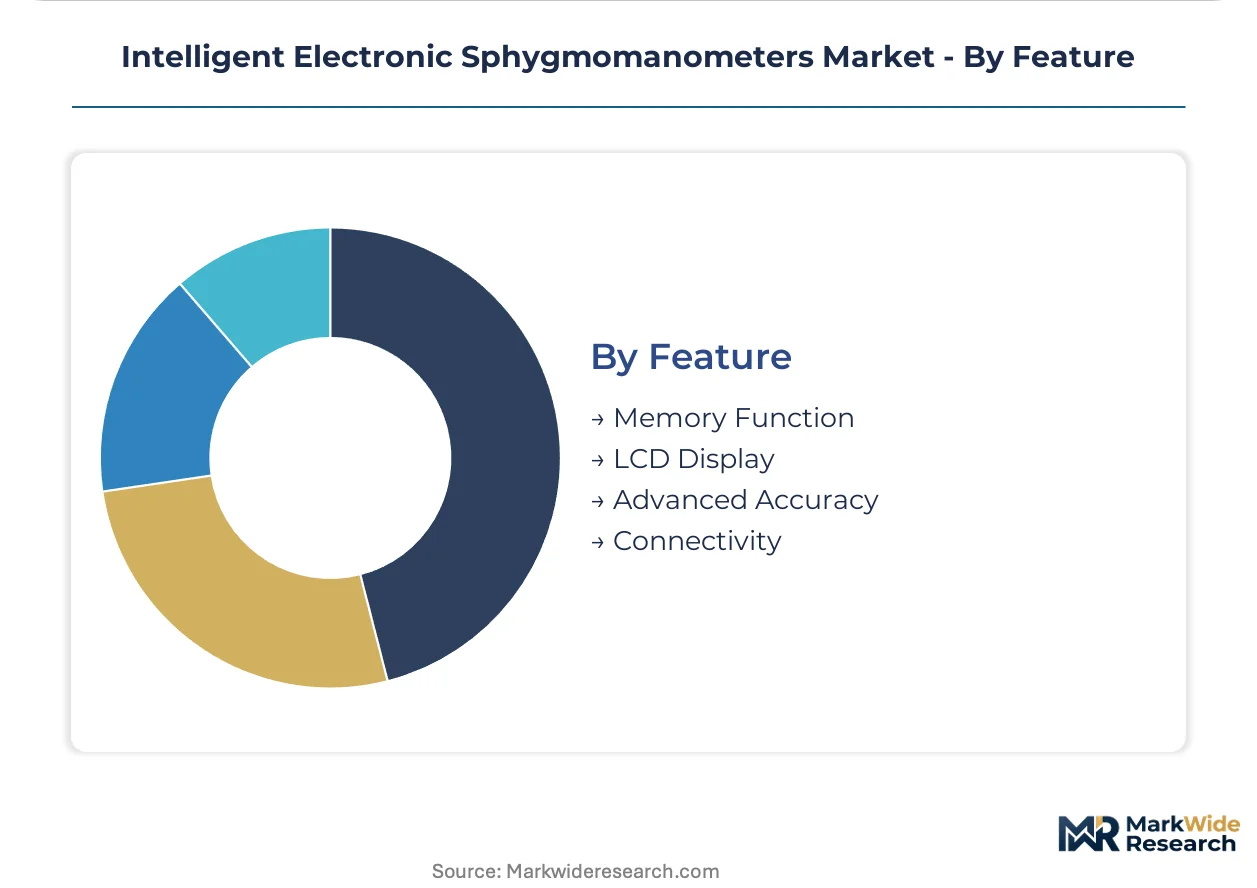
Customer type segmentation separates clinical buyers demanding accuracy documentation from convenience-oriented consumers prioritizing display clarity and data portability.
- Connectivity:Cloud synchronization, API access for EMR integration, and multi-device family account management are expanding most quickly in United States and Japanese home care segments. German notified bodies under EU MDR now require cybersecurity documentation under IEC 81001-5-1 for connected submissions.
- Advanced Accuracy:ISO 81060-2 validation, arrhythmia detection algorithms, and motion artifact rejection command premium positioning in hospital and specialist channels.
- Memory Function:On-device storage for 60-200 readings with timestamp and averaging serves medication management programs in French and Italian pharmacy networks.
- LCD Display:Large-format backlit screens with color-coded hypertension classification dominate retail channels in India and Southeast Asia where price sensitivity limits smartphone pairing adoption.
LCD Display commands volume leadership. Connectivity shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement frameworks and aging demographics are steering procurement patterns across concentrated national markets. Government incentives for home medical equipment reduce patient cost barriers in Japan and Germany. Regulatory validation requirements fragment competitive access between certified and uncertified tiers.
United States
Medicare remote patient monitoring codes now explicitly reimburse connected blood pressure devices, accelerating physician practice adoption. The FDA enforces 510(k) clearance pathways that delay market entry for uncertified manufacturers. IDN procurement committees in Texas and California are unbundling hardware from SaaS subscriptions, pressuring transparent component pricing.
Germany
ISO 81060-2 validation gates institutional sales to acute care networks and outpatient clinics. The EU MDR and EMA clinical evidence requirements have tightened post-market surveillance obligations for connected diagnostic devices. Notified bodies in Munich and Stuttgart are rejecting submissions lacking cybersecurity documentation under IEC 81001-5-1.
Japan
METI subsidies for home medical equipment reduce patient out-of-pocket costs below 10,000 yen, stimulating household penetration. The PMDA and METI coordinate reimbursement listings that favor devices with validated arrhythmia detection algorithms. Sensor foundries in Nagoya and Osaka supply medical-grade diaphragms to certified manufacturers.
China
Production-linked incentive schemes attract contract manufacturers to establish local assembly for export markets. The NMPA enforces clinical trial requirements for Class II medical device registrations. Manufacturing clusters in Shenzhen and Shanghai are integrating Bluetooth Low Energy modules into cost-optimized designs for pharmacy chain distribution.
India
The PLI scheme for medical devices offers cashback on incremental sales, attracting contract manufacturers to establish local assembly. CDSCO medical device rules govern import and domestic production licensing. Diagnostic equipment distributors in Mumbai and Delhi are building direct-to-patient channels for home monitoring segments.
Intelligent Electronic Sphygmomanometers Market Vendor Landscape
Player mix skews toward vertically integrated sensor manufacturers and oscillometric technology specialists. The competitive structure concentrates around Japanese and European incumbents with validated clinical dossiers. Three archetypes dominate: in-house sensor fabricators, dual-technology platform developers, and connectivity-focused telehealth enablers. Capacity expansion and strategic technology licensing represent the dominant competitive moves as manufacturers defend margin structures against smartwatch substitution.
Within the validated clinical tier, OMRON Corporation and A&D Company exemplify sustained hospital-grade credibility through oscillometric R&D investment and JIS-certified production infrastructure. Microlife Corporation occupies a position bridging auscultatory precision with automated convenience through dual-technology platforms. These three anchors represent the certification-intensive segment where regulatory compliance costs create defensive moats against consumer-grade competitors.
| Leading Market Players |
|---|
| OMRON Corporation |
| A&D Company |
| Microlife Corporation |
| Panasonic Holdings Corporation |
| Rossmax International Ltd |
| American Diagnostic Corporation |
| Baxter International Inc. |
| Contec Medical Systems Co.,Ltd |
| Halma plc |
| Others |
Supply Flow & Price Mechanics
Photoplethysmography substitution in consumer wearables is displacing basic oscillometric modules in the sub-$50 tier, simultaneously shifting assembly demand toward Shenzhen and Shanghai clusters while compressing margin structures for uncertified manufacturers dependent on transactional device sales.
Pricing Analysis
Certification level creates the primary spread between hospital-grade and wellness-oriented tiers. Three-tier pricing structure across clinical-validated, connected-consumer, and entry-level economy levels reflects ISO 81060-2 compliance costs and FDA 510(k) investment recovery. Pricing pressure stems from smartwatch photoplethysmography algorithms threatening basic home monitor volumes. Retail pharmacy chains exhibit highest price sensitivity, while German and Japanese hospital procurement committees prioritize accuracy documentation over unit cost.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane are extending inbound component lead times for European assembly operations. MEMS pressure sensor production concentrates in Nagoya, Osaka, and Stuttgart foundries. Medical-grade diaphragm supply draws from Japanese and German specialty manufacturers. Single-source vulnerability in sensor foundry capacity creates bottlenecks during demand surges. Distribution runs through pharmacy chain direct channels and traditional durable medical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth platform fragmentation is creating service-layer niches that favor specialized connectivity providers over bundled hardware-SaaS incumbents.
For Market Incumbents: Compound clinical validation dossiers with ISO 81060-2 and FDA 510(k) clearance to defend against smartwatch substitution threats. Deepen backward integration into MEMS sensor manufacturing to reduce Nagoya and Osaka foundry dependency. Channel control through GPO contracts with Texas and California IDNs anchors institutional revenue.
For New Entrants and Emerging Players: Subscription telemetry service gaps in rural United States markets with limited smartphone penetration offer the most penetrable entry point. Target cellular-enabled remote patient monitoring devices for Medicare RPM code reimbursement. Pharmacy chain private-label partnerships provide bypass channels around established distributor hierarchies.
For Investors and Strategic Acquirers: The market sits at a certification-consolidation phase that favors vertically integrated sensor manufacturers with validated clinical dossiers. Long-term viability over the next decade hinges on regulatory compliance moats rather than consumer brand recognition. Watch for EU MDR notified body capacity constraints as inflection indicator for European launch timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates hospital procurement access under Medicare reimbursement frameworks. |
| CE Marking Under EU MDR | Enables German and French acute care network sales with post-market surveillance compliance. |
| Hospital System Partnership | Secures IDN procurement committee contracts through transparent component pricing. |
| Software Companion Development | Supports AI-powered arrhythmia detection algorithms for atrial fibrillation screening. |
| Reimbursement Strategy | Aligns product architecture with METI subsidies and Medicare RPM coding. |
Methodological Framework
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and telehealth platform operators and refined through secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and METI subsidy program disclosures. Bottom-up and top-down triangulation reconciled manufacturer shipment data with institutional adoption patterns.
Variance decomposition across product type, end user, connectivity protocol, and regional regulatory cluster dimensions structured the analytical framework. CAGRs were derived from segmented growth trajectory modeling. Forecast inputs incorporated Bluetooth Low Energy adoption curves and ISO 81060-2 certification penetration rates.
Material uncertainties — regulatory timeline delays, sensor foundry capacity constraints, smartwatch algorithm accuracy improvements — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
General Surgery Devices Market
Medical Devices
Non-Destructive Medical Technologies Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Electroencephalogram (EEG) Caps Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market
Medical Devices
Electronic Smart Mask Market
Medical Devices
Capsulotomy Market
Medical Devices
Medical Device Cros Market
Medical Devices
Indian Laparoscopy Devices Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Mucus Clearance Devices Market
Medical Devices
Prescription Lens Market
Medical Devices
Micro Syringes Market
Medical Devices
Digital Magnifiers Market
Medical Devices
Transient Elastography Device Market
Medical Devices
Intelligent Prosthetics Market