
 Nurse Call Systems Market | 2026-2036
Nurse Call Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Nurse Call Systems Market Analysis
Aftermarket service revenue is fragmenting across hardware maintenance, software subscription renewals, and remote monitoring contracts. Ametek leverages its Rauland-Borg installed base to sustain recurring service income from legacy wired system upgrades. Ascom Holding AG anchors European demand through specialized mobile integration platforms for acute care workflows.
Nurse call systems comprise patient-initiated alerting infrastructure with embedded audio-visual communication protocols, typically operating on low-voltage wiring or IEEE 802.11 wireless standards to summon clinical staff during emergent or routine care events. Wired systems retain dominance in existing hospital infrastructure where retrofit costs constrain migration, while cloud-based deployment models represent the fastest-expanding margin pool as facilities prioritize capital-expense reduction and centralized IT governance. Software solutions command premium pricing when bundled with real-time location system integration and predictive analytics dashboards.
The FDA regulates nurse call devices as Class I or II medical devices depending on alarm integration depth, while the Joint Commission enforces National Patient Safety Goal NPSG.06.01.01 on clinical alarm management that directly shapes procurement specifications. HIPAA constraints on cloud-based patient data transmission create compliance barriers that vendors must architect around. Stakeholders should monitor how CMS reimbursement adjustments for hospital-acquired conditions alter capital allocation toward proactive patient monitoring infrastructure.
Market Dynamics
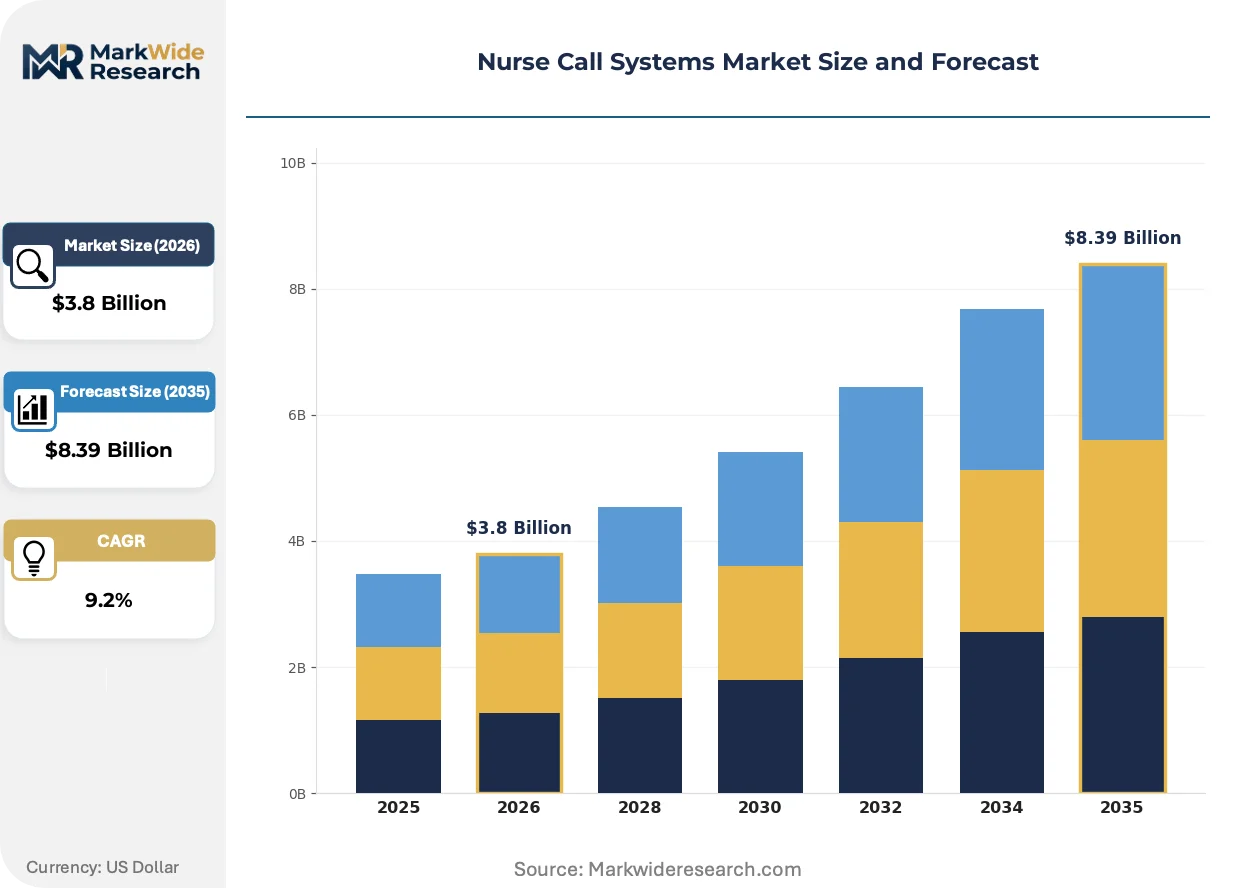
Wireless IEEE 802.11 standards and cloud-based deployment models are compressing replacement cycles for legacy wired infrastructure across acute care facilities, while CMS patient safety mandates enforce minimum alerting capabilities that favor integrated platform upgrades over point solutions.
Growth Catalysts
- CMS Patient Safety Mandates:US acute care hospitals face escalating compliance pressure under Medicare reimbursement rules tied to hospital-acquired condition reductions, forcing systematic infrastructure investment in automated alerting and response-time documentation.
- Cloud Migration:Capital-expense reduction priorities among German, Japanese, and Australian healthcare networks are accelerating demand for subscription-based deployment models with centralized IT governance and remote system management.
- Real-Time Location System Convergence:RFID and BLE beacon integration with nurse call platforms is creating bundled value propositions that command premium positioning in procurement evaluations for integrated clinical workflow solutions.
Market Restraints
- Retrofit Cost Barriers:Existing low-voltage wired infrastructure in US and European hospitals imposes substantial demolition and recabling expenses that delay full-platform replacements in favor of incremental gateway-based wireless overlays.
- HIPAA Cloud Friction:Patient data transmission to third-party cloud environments triggers complex Business Associate Agreement negotiations and encryption architecture requirements that extend sales cycles and inflate implementation costs.
- Copper and Semiconductor Input Volatility:Nurse call hardware manufacturing remains exposed to fluctuating commodity prices for wiring harnesses and microcontrollers, compressing margin stability for equipment vendors serving price-sensitive public hospital segments.
Strategic Opportunities
- Underpenetrated Post-Acute Settings:Skilled nursing facilities and long-term acute care hospitals in the United States operate substantially lower nurse call system penetration rates than acute care hospitals, presenting greenfield installation demand for wireless-first platforms.
- Predictive Analytics Integration:Machine learning algorithms applied to call-pattern data are enabling fall-risk prediction and staffing optimization modules that create new software-as-a-service revenue streams beyond base alerting functionality.
- Joint Commission NPSG.06.01.01 Alignment:Clinical alarm management standardization requirements are driving replacement demand at hospitals with legacy systems lacking centralized alarm routing, prioritization, and escalation protocols.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Healthcare facilities face persistent shortages of technicians capable of maintaining hybrid wired-wireless infrastructure, forcing vendors to expand direct field service footprints and remote diagnostic capabilities.
- Multi-Vendor Integration Complexity:Interoperability gaps between nurse call platforms, electronic health record systems, and building automation networks require costly custom middleware development that erodes project profitability and extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nurse Call Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Systems, Wireless Systems, Software Solutions, Integrated Systems End User: Hospitals, Clinics, Long-term Care Facilities, Assisted Living Technology: Audio Visual, Nurse Station Integrations, Mobile Applications, Cloud-based Solutions Deployment: On-premise, Cloud-based, Hybrid, Remote Monitoring |
| Companies Covered | Ametek (Rauland-Borg Corporation), Baxter International, Ascom Holding AG, Honeywell International, Hill-Rom Services, Austco Healthcare, Jeron Electronic Systems, STANLEY Healthcare, TekTone Sound and Signal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nurse Call Systems Market Emerging Trajectories
Clinical workflow digitization is collapsing traditional boundaries between patient alerting, staff communication, and operational analytics, creating pressure for unified platform architectures that consolidate previously siloed point solutions.
Voice-over-IP integration with nurse call handsets is hybridizing audio communication pathways, enabling smartphone-based caregiver alerts that bypass dedicated hardware endpoints. Large US health systems are piloting bring-your-own-device policies that route patient calls directly to assigned nurses' mobile handsets. This convergence is compressing demand for traditional wall-mounted intercom units while expanding addressable market for software licenses.
The Joint Commission's National Patient Safety Goal NPSG.06.01.01 is mandating systematic alarm management protocols that require hospitals to document alarm response times and justify alert configurations. This regulatory pressure is disqualifying legacy systems lacking centralized logging and reporting capabilities from procurement shortlists. Facilities with outdated infrastructure are accelerating replacement timelines to maintain accreditation standing and avoid survey deficiencies.
Service contract unbundling is fragmenting vendor-customer relationships as hospital procurement departments separate hardware maintenance, software subscription renewals, and remote monitoring into distinct purchasing decisions. This behavioral shift is visible most acutely in US acute care networks with mature value analysis committees that scrutinize recurring expenditure categories independently. Vendors are responding with modular pricing architectures that allow selective component retention rather than forcing bundled commitments.
Nurse Call Systems Market Segmentation
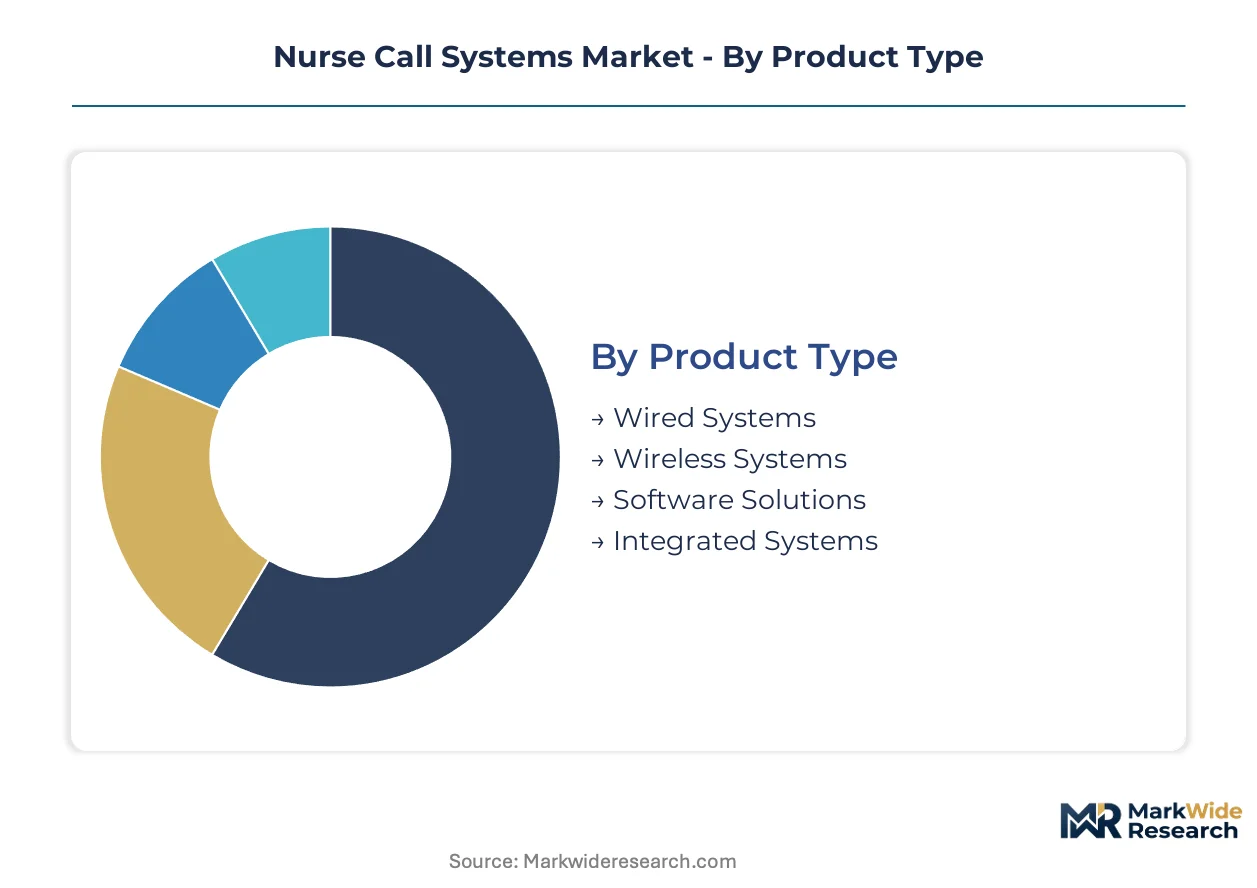
Nurse call system procurement diverges sharply across facility infrastructure maturity, regulatory compliance thresholds, and capital-expense constraints. Segmentation reveals where wireless migration outpaces wired replacement and which deployment models capture greenfield versus retrofit demand.
Product Type:
Use-case spectrum spans legacy infrastructure preservation through full-platform digitization, with procurement decisions hinging on demolition feasibility and IT governance centralization.
- Wired Systems:Low-voltage copper harness installations dominate existing acute care infrastructure where full replacement costs deter migration. US hospitals with pre-2010 construction retain substantial installed bases, though CMS patient safety mandates are accelerating gateway-overlay upgrades rather than full rip-and-replace.
- Wireless Systems:IEEE 802.11-based platforms eliminate recabling expenses and enable rapid deployment in post-acute settings with minimal construction disruption. German and Australian healthcare networks are prioritizing wireless-first procurement for new facility construction, driven by capital-expense reduction mandates and centralized IT governance requirements.
- Software Solutions:Subscription-based alerting middleware and analytics dashboards command premium positioning when bundled with RTLS integration.
- Integrated Systems:Converged nurse call, staff communication, and building automation platforms target large health systems seeking unified clinical workflow architectures.
Established volume favors wired systems; emerging adoption favors wireless systems.
End User:
Customer-type concentration maps directly to reimbursement structure sophistication and regulatory inspection intensity.
- Hospitals:Acute care facilities face the most stringent Joint Commission NPSG.06.01.01 compliance pressure, driving replacement demand for centralized alarm routing and response-time documentation capabilities. US hospitals under CMS reimbursement rules allocate disproportionate capital toward automated alerting infrastructure.
- Long-term Care Facilities:Skilled nursing and post-acute settings operate substantially lower system penetration rates, presenting greenfield wireless installation demand. Japanese aged-care facilities are expanding procurement of cloud-based platforms to address staffing shortages through remote monitoring capabilities.
- Clinics:Outpatient and ambulatory surgical centers prioritize cost-minimized point solutions with limited integration depth.
- Assisted Living:Residential care settings favor consumer-grade alerting devices over clinical-grade infrastructure, with procurement driven by liability mitigation rather than accreditation requirements.
Margin concentration sits with hospitals; volume expansion sits with long-term care facilities.
Technology:
Technology-layer segmentation tracks the migration from hardware-centric alerting toward software-defined clinical communication.
- Cloud-based Solutions:Third-party hosted platforms with centralized IT governance are capturing disproportionate demand concentration across German, Japanese, and Australian healthcare networks. HIPAA Business Associate Agreement complexity extends US sales cycles, though encryption architecture advances are progressively lowering compliance barriers.
- Mobile Applications:Smartphone-based caregiver alerts and bring-your-own-device policies are displacing dedicated handset hardware in large US health system pilots, expanding addressable market for software licenses while compressing demand for wall-mounted intercom units.
- Audio Visual:Traditional speaker-microphone endpoints retain presence in legacy infrastructure but face replacement pressure from VoIP-integrated alternatives.
- Nurse Station Integrations:Middleware connecting patient alerts to EHR and staffing systems requires costly custom development that erodes project profitability.
Recurring revenue potential clusters in cloud-based solutions; hardware displacement pressure concentrates on mobile applications.
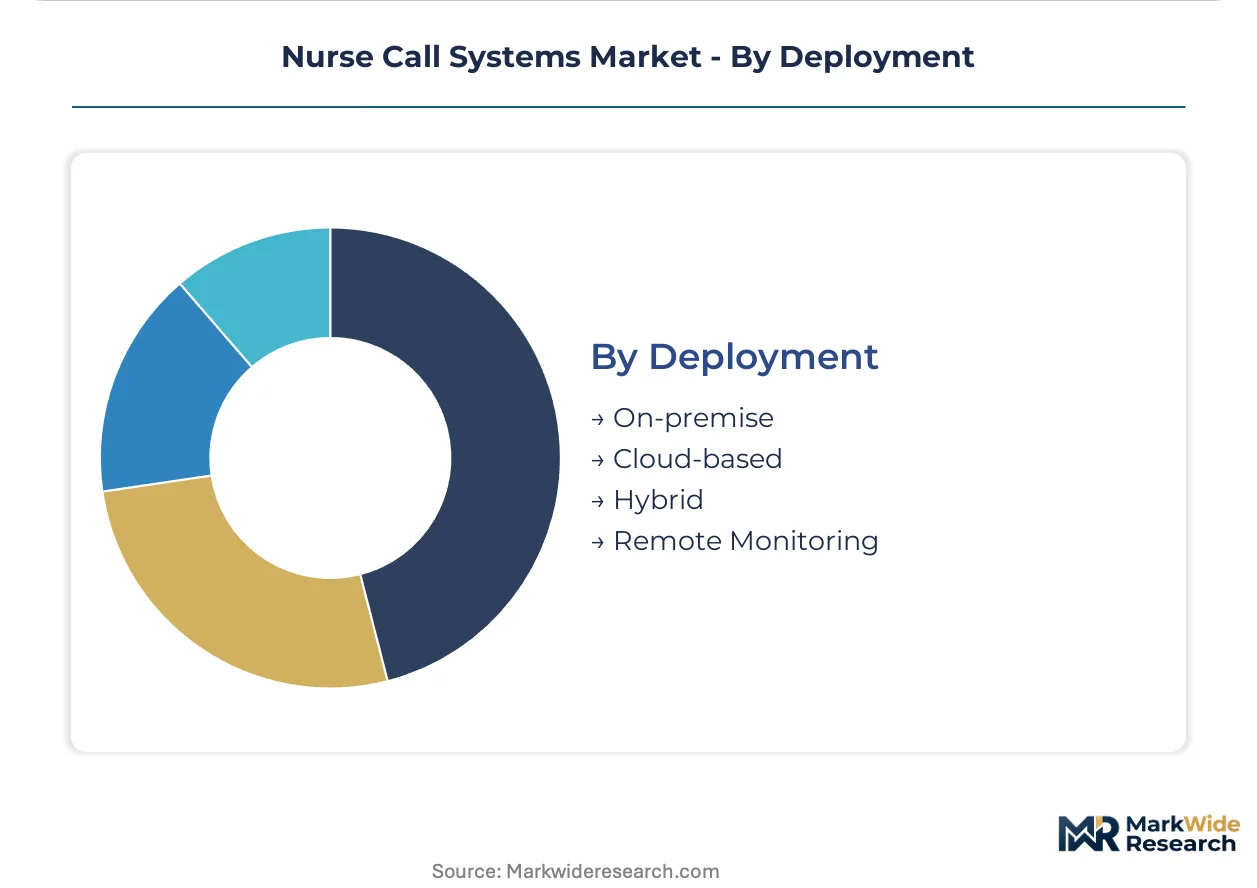
Deployment:
Deployment-model selection reflects facility IT maturity, data sovereignty requirements, and remote management capabilities.
- Cloud-based:Subscription models with remote system management and automatic software updates are gaining share fastest among capital-constrained healthcare networks. Australian public hospital systems are mandating cloud-first procurement policies to reduce on-premise infrastructure overhead.
- Hybrid:Mixed on-premise alerting infrastructure with cloud-based analytics and reporting layers addresses HIPAA compliance concerns while enabling centralized dashboard access. US acute care facilities with existing wired infrastructure favor hybrid architectures for incremental migration paths.
- On-premise:Fully localized installations persist in facilities with stringent data sovereignty requirements or unreliable connectivity infrastructure.
- Remote Monitoring:Vendor-managed proactive system health surveillance represents an emerging service layer rather than standalone deployment model.
Procurement momentum favors cloud-based; legacy entrenchment favors hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acute care hospitals in the United States deploy nurse call systems primarily for Joint Commission compliance and CMS reimbursement alignment, while German and Australian networks favor cloud-first procurement to reduce capital expenditure. Japanese aged-care facilities prioritize remote monitoring capabilities to address workforce shortages. This consumption-mix differential shapes distinct procurement specifications across major markets.
United States
Acute care hospitals drive replacement demand through CMS patient safety mandates tied to hospital-acquired condition reductions. The FDA regulates nurse call devices as Class I or II medical devices depending on alarm integration depth. Large health systems in the Northeast Corridor and California are piloting bring-your-own-device policies that route patient calls directly to nurse mobile handsets.
Germany
Healthcare networks prioritize cloud-based deployment models to achieve centralized IT governance and capital-expense reduction. The country's national healthcare regulator enforces medical device standards that favor integrated platform architectures over point solutions. Hospital construction in Bavaria and North Rhine-Westphalia is specifying wireless-first nurse call infrastructure for new facilities.
Japan
Aged-care facilities are expanding procurement of cloud-based platforms to address staffing shortages through remote monitoring capabilities. METI guidelines on healthcare digitization support subscription-based deployment models. Tokyo and Osaka metropolitan clusters are witnessing accelerated adoption of mobile-integrated nurse call systems in post-acute settings.
Australia
Public hospital systems are mandating cloud-first procurement policies to reduce on-premise infrastructure overhead. The TGA regulates medical device software components that interface with nurse call platforms. New South Wales and Victoria are leading deployment of hybrid architectures that combine on-premise alerting with cloud-based analytics layers.
United Kingdom
NHS trusts are consolidating clinical communication infrastructure under unified platform architectures to replace siloed point solutions. The MHRA enforces medical device regulations that shape procurement specifications for alarm management capabilities. London and Southeast hospital networks are prioritizing RTLS-integrated nurse call upgrades to meet National Patient Safety Goal alignment requirements.
Nurse Call Systems Market Vendor Landscape
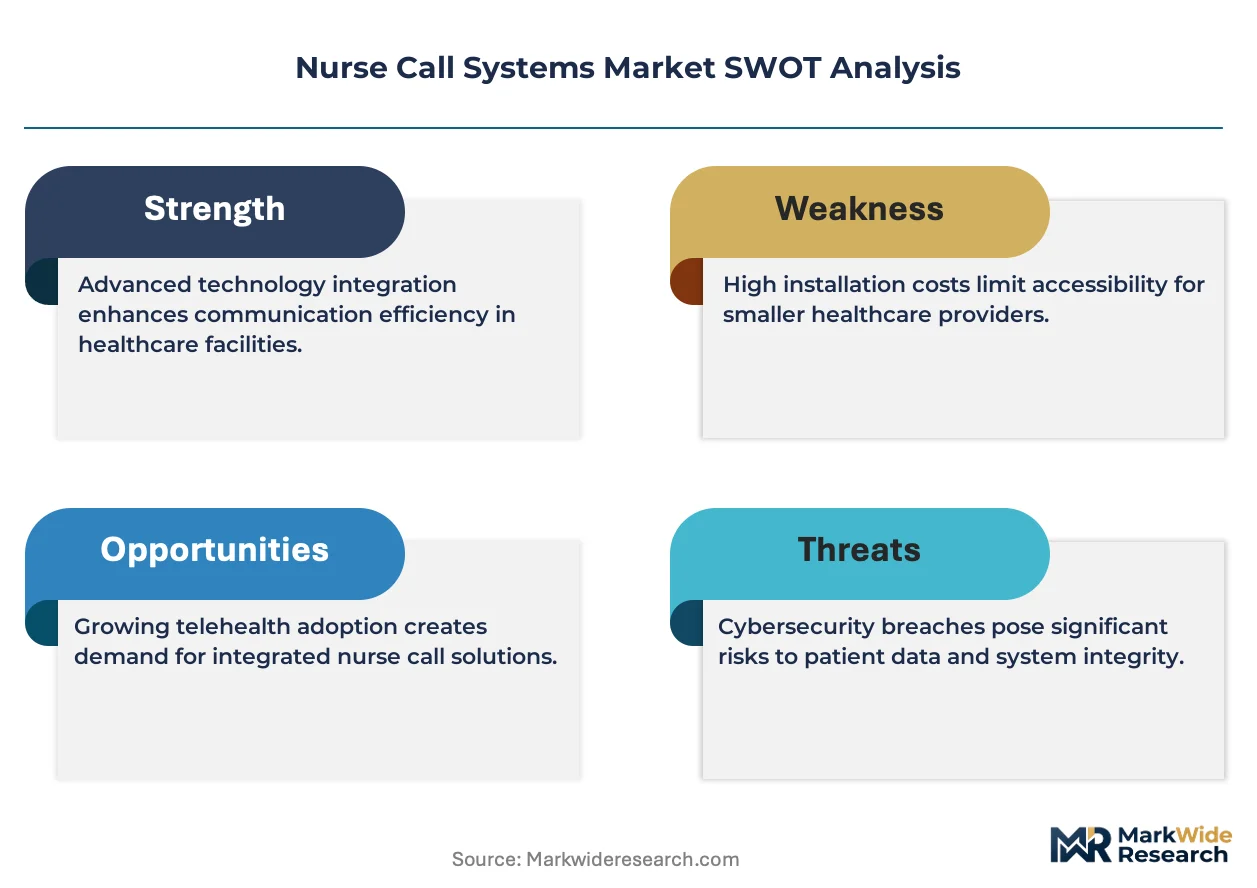
Capability concentration sits with specialized clinical communication vendors; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: legacy wired-system incumbents with substantial installed bases, wireless-first specialists capturing greenfield demand, and diversified technology conglomerates leveraging cross-platform integration capabilities. Dominant competitive moves include portfolio diversification into predictive analytics modules and strategic partnerships with electronic health record vendors to reduce multi-vendor integration complexity.
Among Switzerland-based specialists, Ascom Holding AG occupies a position within the mobile integration platform tier. Ametek, through its Rauland-Borg Corporation subsidiary, exemplifies the installed-base leverage archetype for recurring service revenue generation. Baxter International sits within the diversified healthcare technology tier, representing cross-platform clinical workflow integration capabilities. These three anchors illustrate distinct strategic positioning vectors without implying specific market share figures or operational metrics.
| Leading Market Players |
|---|
| Ametek (Rauland-Borg Corporation) |
| Baxter International |
| Ascom Holding AG |
| Honeywell International |
| Hill-Rom Services |
| Austco Healthcare |
| Jeron Electronic Systems |
| STANLEY Healthcare |
| TekTone Sound and Signal |
| Others |
Supply Flow & Price Mechanics
Undercapacity in semiconductor fabrication for medical-grade microcontrollers is forcing nurse call hardware vendors toward dual-sourcing strategies while simultaneously eroding margin buffers on mid-tier system bundles. This utilization squeeze transmits directly into procurement negotiations, with US acute care hospitals extracting steeper service-contract concessions to offset elevated equipment quotes.
Pricing Analysis
Long-term service contracts dominate procurement structures, with three-tier pricing stratification across premium FDA-validated platforms, standard Joint Commission-compliant systems, and economy-grade wired installations for post-acute facilities. Price differentiation rests on RTLS integration depth and cloud analytics bundling. Cost compression in economy tiers is intensifying because skilled nursing facilities face Medicaid reimbursement constraints. Public hospital systems exhibit highest price sensitivity; large integrated delivery networks command volume leverage on enterprise-wide deployments.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk profiles for copper wiring harnesses and PCB assemblies. Manufacturing concentrates in China, Mexico, and Taiwan for electronic components, with final assembly distributed across regional hubs. Raw material dependencies span copper conductors, lithium-ion cells for wireless handsets, and BLE beacon chipsets. Single-source vulnerability concentrates in specialized medical-grade power supply units. Distribution runs through GPO contracts and direct hospital system relationships rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as EHR interoperability requirements collapse standalone alerting into unified clinical communication ecosystems. Vendors must architect for middleware integration or face displacement by enterprise software consolidators.
For Market Incumbents: Entrench installed-base relationships through predictive analytics module rollouts that increase switching costs for health systems. Prioritize backward integration into cloud infrastructure to reduce third-party hosting dependencies that HIPAA Business Associate Agreements complicate. Defend against smartphone-native entrants by emphasizing FDA Class II validation depth that consumer-grade alternatives cannot replicate.
For New Entrants and Emerging Players: Build out wireless-first platforms targeting skilled nursing facilities where legacy penetration remains lowest and procurement cycles are shorter than acute care. Prioritize cloud-native architectures with remote monitoring capabilities that address Japanese aged-care staffing shortages. Pursue direct-to-facility sales models bypassing GPO channel complexity that incumbents dominate.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-centric deployment models as subscription revenue displaces hardware-heavy transaction structures. Long-term viability favors vendors with recurring revenue exceeding sixty percent of total mix. Acquisition targets should demonstrate live EHR integrations with Cerner or Epic. Monitor CMS reimbursement rulemaking on hospital-acquired conditions as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified nurse call-EHR architectures satisfy Joint Commission NPSG.06.01.01 documentation mandates. |
| Software Companion Development | Predictive fall-risk modules create SaaS revenue streams beyond base alerting functionality. |
| Hospital System Partnership | Enterprise agreements with US integrated delivery networks lock out competitor access. |
| CE Marking Pathway | European medical device regulation compliance enables cloud-first procurement in Germany. |
| Reimbursement Strategy | CMS alignment documentation accelerates capital allocation for patient safety infrastructure. |
Methodological Framework
Desk research of FDA 510(k) filings, hospital procurement databases, and GPO contract repositories preceded structured interviews with biomedical engineering directors, health system CIOs, and nurse call vendor product managers. Secondary validation drew from CMS Medicare cost reports, Joint Commission accreditation surveys, and medical device trade association technical standards. Bottom-up facility-level demand estimates triangulated against top-down healthcare IT spending projections.
Assumptions around wireless migration velocity and cloud adoption thresholds were held fixed across scenarios, while CMS reimbursement rule changes and copper commodity volatility were modeled as sensitivity variables. Segmentation dimensions included deployment model, facility type, integration complexity, and regional regulatory cluster. CAGRs were derived from logistic adoption curves fitted to historical replacement cycle data and procurement pipeline visibility. Forecast inputs incorporated HIPAA compliance cost trajectories and IEEE 802.11 standards evolution.
Sensitivities concentrate around CMS patient safety mandate enforcement intensity and semiconductor supply normalization timelines. Forecasts reflect assumptions on health system capital budget recovery post-pandemic and cloud encryption architecture maturation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electric Heated Eye Mask Market
Medical Devices
US Nebulizer Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Mexico Contraceptive Devices Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
Electroencephalography Devices Market
Medical Devices
Electric Breast Pumps Market
Medical Devices
Total Artificial Heart Market
Medical Devices
Corneal Surgery Devices Market
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
TMJ Implants Market
Medical Devices
Infusion Fluid Holder Market
Medical Devices
Global Tympanostomy Products Market