
 Global Stethoscope Market | 2026-2036
Global Stethoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stethoscope Market Foresight
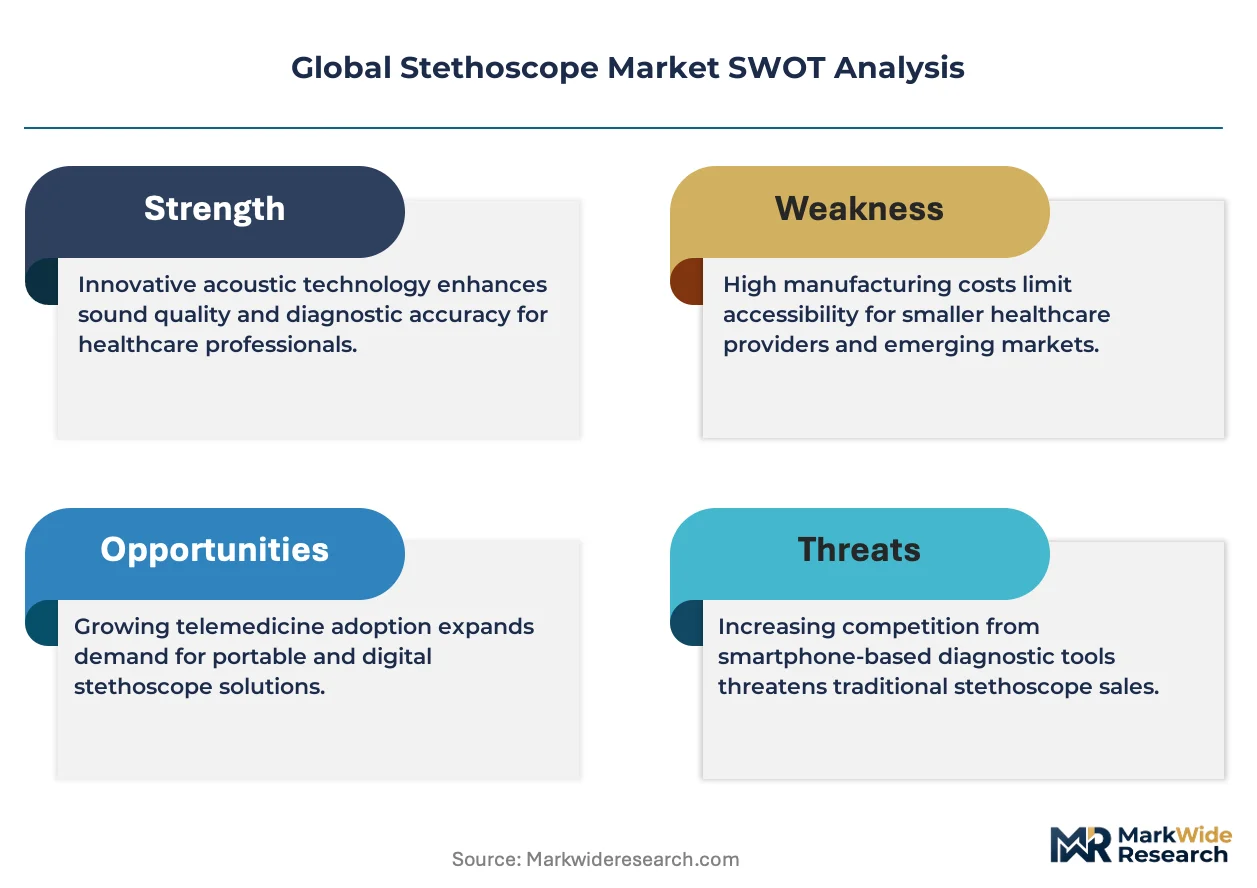
The EU Medical Device Regulation is rebalancing procurement criteria toward validated acoustic performance and traceable manufacturing records. 3M leverages its Littmann brand heritage and extensive clinical training infrastructure to sustain premium positioning across European hospital networks. Eko Health differentiates through AI-enabled digital stethoscope platforms that integrate with electronic health records. Rudolf Riester GmbH anchors its competitiveness in handcrafted precision instruments serving Central European diagnostic centers.
A stethoscope is an acoustic medical device comprising a chest piece with diaphragm and bell, tubing, and binaural earpieces designed to transmit internal body sounds—heart murmurs, lung crackles, vascular bruits—to a clinician's ears for diagnostic assessment; electronic variants incorporate piezoelectric sensors and digital signal processing with frequency response typically spanning 20 Hz to 1 kHz. The device serves as the foundational screening tool in cardiovascular and respiratory examination protocols across inpatient and outpatient settings. Electronic stethoscopes command expanding share in cardiology applications where amplified sound capture and waveform visualization support murmur detection accuracy, while acoustic models retain dominance in general practice and resource-limited settings due to lower cost and maintenance requirements. Pediatric and fetal segments represent concentrated margin pools given specialized sizing demands and stringent safety material standards.
FDA clearance pathways under 21 CFR 870.1875 govern electronic stethoscope safety and efficacy claims in the United States, while the EU MDR requires notified body involvement and post-market surveillance for all auscultation devices sold in member states. Japan's PMDA enforces JIS T 0601 electromagnetic compatibility standards that constrain design architectures for digital variants entering that market. Stakeholders must monitor evolving harmonization between FDA software-as-medical-device guidance and EU AI Act risk classification for algorithm-enhanced diagnostic features.
Market Dynamics
The EU Medical Device Regulation's acoustic performance validation mandate is forcing hospital procurement departments to requalify supplier bases and prioritize traceable manufacturing records over historical brand preference.
Growth Catalysts
- EU MDR compliance deadlines:The 2021-2028 transition window compels teaching hospitals in Germany, France, and Italy to replace legacy acoustic inventories with validated electronic alternatives. Procurement officers now require ISO 13485-certified supply chains.
- Piezoelectric sensor maturation:Advances in MEMS fabrication have reduced electronic stethoscope unit costs while expanding frequency capture range. Cardiology departments in university medical centers are accelerating upgrade cycles.
- Telemedicine infrastructure rollout:Remote auscultation protocols in rural health networks across India and Brazil are creating first-time demand for digital transmission-capable devices. Primary care extension programs prioritize amplified sound clarity.
Market Restraints
- Copper and latex input volatility:Acoustic stethoscope manufacturing depends on Malaysian rubber supply chains and Chilean copper for binaural components. Price swings compress margin pools for handcrafted instrument specialists.
- Single-source sensor dependency:High-fidelity piezoelectric elements concentrate among Japanese and German component suppliers. Device assemblers face allocation risk during semiconductor demand surges.
- Battery chemistry limitations:Lithium-ion thermal sensitivity constrains electronic stethoscope sterilization protocols. Autoclave incompatibility limits reuse cycles in infectious disease wards.
Strategic Opportunities
- AI-enhanced diagnostic integration:Machine learning murmur classification algorithms are converging with electronic stethoscope hardware. Early movers capture workflow integration premiums in cardiology information systems.
- Vietnamese manufacturing expansion:Medical device assembly capacity in Ho Chi Minh City and Hanoi offers tariff-advantaged export platforms for acoustic instrument production serving ASEAN markets.
- Pediatric specialization gaps:Neonatal and infant auscultation requires diaphragm diameters below 2.5cm with hypoallergenic materials. Few suppliers meet ISO 10993 biocompatibility standards for this segment.
Industry Challenges
- Clinical acoustician training scarcity:Electronic stethoscope interpretation demands waveform literacy that nursing curricula have not standardized. Hospital systems must fund supplemental certification programs.
- Cross-border notified body congestion:EU MDR technical file reviews queue for 12-18 months at designated conformity assessment bodies. Product launch timelines extend unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stethoscope Market |
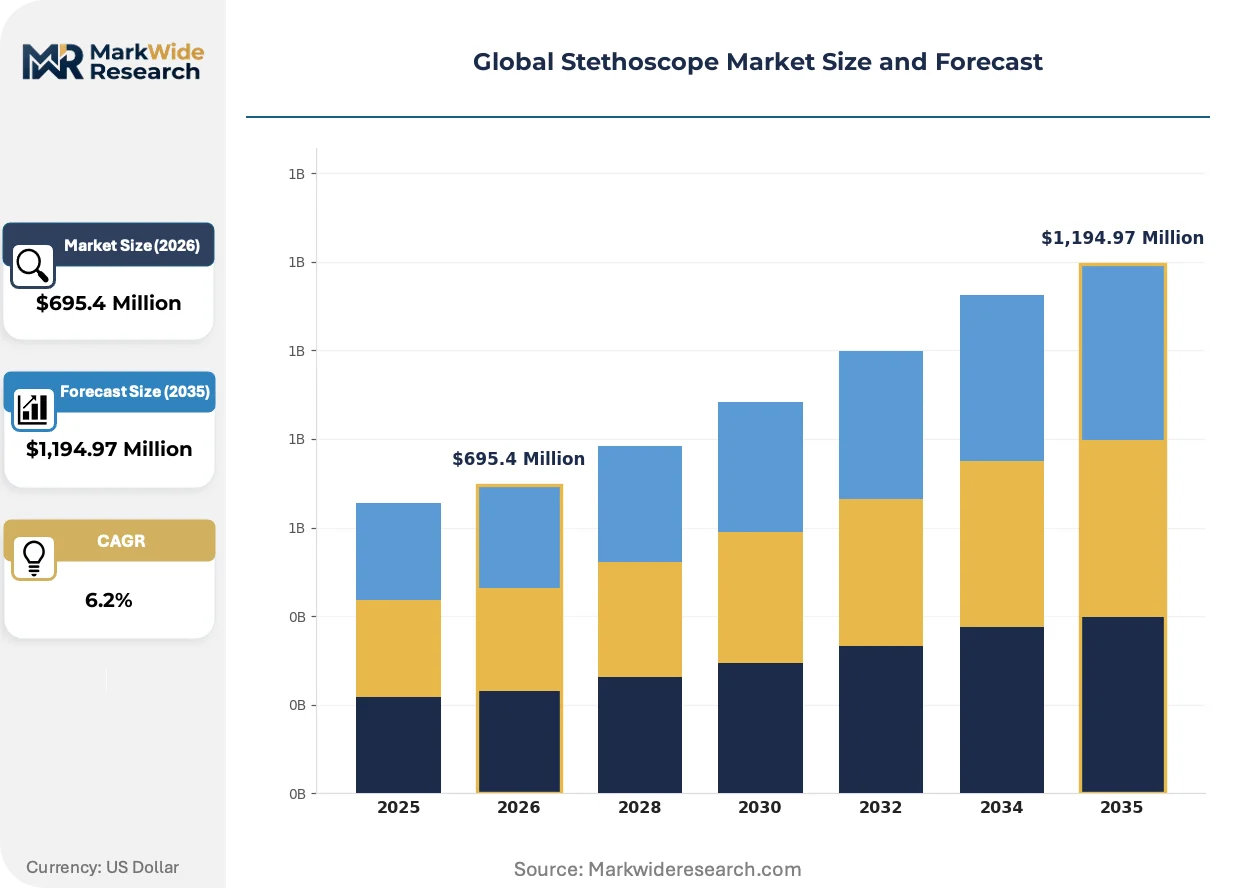
| Market Size in 2026 | $695.4 Million |
| Market Size in 2035 | $1,194.97 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic, Electronic, Fetal, Pediatric, Teaching Application: Cardiology, Pulmonology, General Practice, Veterinary, Neonatology End User: Hospitals, Clinics, Diagnostic Centers, Medical Schools, Ambulatory Care Distribution Channel: Online Retailers, Medical Distributors, Pharmacies, Direct Sales, Wholesalers |
| Companies Covered | 3M, Medline Industries, Welch Allyn (Hill-Rom Holdings), Eko Health, GF Health Products, American Diagnostic Corporation, Rudolf Riester GmbH, Cardionics, HEINE Optotechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stethoscope Market Shifts & Advancements
Digital signal processing architectures are migrating from peripheral add-ons to core device design, compressing the feature gap between premium acoustic and entry electronic segments.
Active noise cancellation firmware is electrifying electronic stethoscope value propositions. The technology filters ambient clinical noise while preserving pathological frequency bands. Emergency departments in trauma centers are adopting these units for field reliability. The capability is compressing price premiums previously commanded by acoustic isolation engineering.
Japan's PMDA revised electromagnetic compatibility standards under JIS T 0601-1 in 2023. The update mandates shielding validation for wireless-enabled diagnostic devices. Exporters to Japanese university hospitals must redesign antenna configurations. Domestic manufacturers capture temporary advantage through pre-certified platform architectures.
Hospital group purchasing organizations are consolidating auscultation procurement into multi-year device-and-service agreements. Independent distributors lose shelf space to direct manufacturer contracts. The pattern concentrates in US integrated delivery networks and German hospital federations where standardization incentives override brand fragmentation.
Global Stethoscope Market Segmentation
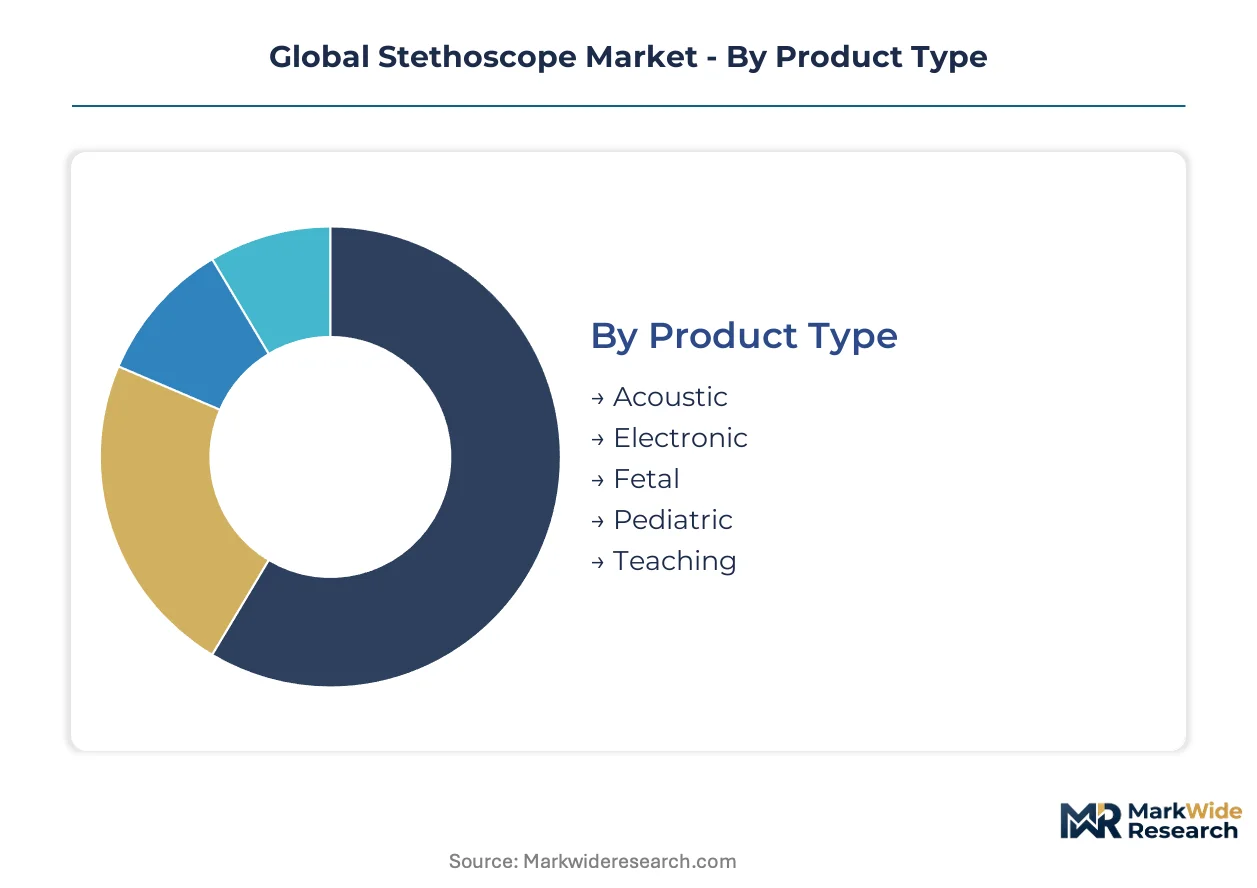
Stethoscope procurement patterns diver sharply across clinical settings, with electronic variants capturing cardiology workflows while acoustic models retain dominance in resource-constrained environments. Segmentation reveals how regulatory validation requirements and end-user sophistication reshape product mix priorities.
Product Type:
Customization intensity spans from handcrafted acoustic instruments to software-configurable electronic platforms with algorithmic enhancement.
- Acoustic:Traditional diaphragm-and-bell designs transmit body sounds through hollow tubing without electrical amplification. German university medical centers and teaching hospitals in France sustain demand for precision-manufactured units meeting EU MDR traceability mandates.
- Electronic:Piezoelectric sensor arrays capture frequencies from 20 Hz to 1 kHz with digital signal processing and waveform visualization. Cardiology departments across Italy and Spain are replacing legacy inventories as acoustic performance validation becomes compulsory under notified body oversight.
- Fetal:Specialized low-frequency detection for intrauterine cardiac monitoring with enhanced sound isolation.
- Pediatric:Compact diaphragm configurations below 2.5cm diameter with hypoallergenic material compliance for infant examination protocols.
- Teaching:Dual-head designs enabling simultaneous instructor-student auscultation with audio output ports for classroom demonstration.
Most installed capacity flows through Acoustic. Expansion is steepest in Electronic.
Application:
Clinical workflow complexity determines device specification tiers, with subspecialty departments commanding premium feature sets against general practice cost constraints.
- Cardiology:Murmur detection accuracy requirements drive adoption of amplified sound capture with frequency filtering and recording capability. University hospital networks in Germany and France prioritize electronic units with EHR integration.
- Pulmonology:Crackle and wheeze identification demands broad frequency response with ambient noise suppression. Outpatient clinics across India and Brazil deploy amplified devices for tuberculosis screening programs.
- General Practice:Cost-sensitive procurement favors reliable acoustic models with minimal maintenance overhead.
- Veterinary:Variable thoracic anatomy requires adjustable diaphragm pressure mechanisms and durable construction.
- Neonatology:ISO 10993 biocompatibility standards constrain supplier pools for premature infant examination.
Cardiology commands the highest unit values. General Practice maintains the largest shipment volumes.
End User:
Institutional scale and regulatory exposure create distinct purchasing behaviors across facility types.
- Hospitals:Integrated delivery networks negotiate multi-year device-and-service agreements with direct manufacturer contracts. German hospital federations and US health systems consolidate procurement through group purchasing organizations.
- Clinics:Independent primary care practices rely on medical distributor relationships with flexible payment terms.
- Diagnostic Centers:Specialized auscultation services require validated electronic platforms with documentation capabilities.
- Medical Schools:Teaching curricula sustain demand for durable demonstration-grade instruments with replacement part availability.
- Ambulatory Care:Mobile health units prioritize lightweight electronic designs with extended battery operation.
Hospitals absorb the majority of electronic stethoscope shipments. Diagnostic centers are gaining share fastest.
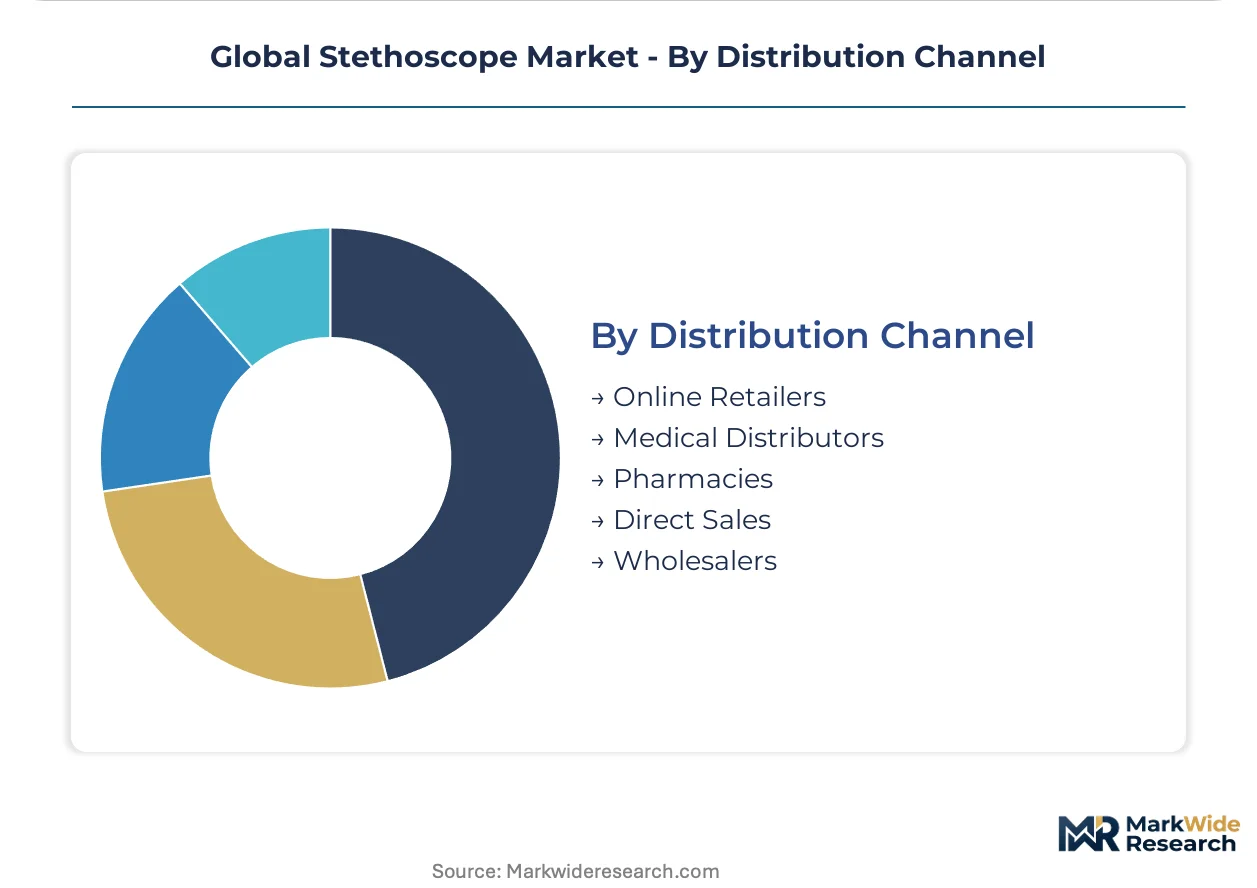
Distribution Channel:
Channel selection reflects buyer sophistication, order scale, and regulatory documentation requirements.
- Online Retailers:E-commerce platforms serve individual practitioners and small clinics with transparent pricing and rapid fulfillment. Indian and Brazilian rural health networks source entry-level electronic models through specialized medical equipment marketplaces.
- Medical Distributors:Regional inventory holding and technical support services anchor hospital procurement relationships. Central European diagnostic centers depend on distributor networks for ISO 13485-certified supply chain verification.
- Pharmacies:Over-the-counter acoustic stethoscope availability supports emergency replacement purchases.
- Direct Sales:Manufacturer field representatives secure enterprise contracts with training and service bundling.
- Wholesalers:Volume aggregation serves government procurement programs and nonprofit health initiatives.
Medical distributors handle the greatest transaction value. Online retailers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stethoscope manufacturing traces its modern origins to French instrument makers in the early 19th century, with subsequent industrial scaling in German precision engineering clusters and American medical device corridors. Contemporary demand patterns reflect this heritage, with procurement concentrated in established healthcare infrastructure zones and emerging telemedicine frontiers.
United States
FDA clearance pathways under 21 CFR 870.1875 govern electronic stethoscope safety claims, with software-as-medical-device guidance now converging with emerging AI oversight frameworks. Hospital group purchasing organizations in integrated delivery networks consolidate procurement into multi-year device-and-service agreements. Greater Boston's medical technology corridor anchors R&D activity for algorithm-enhanced diagnostic platforms.
Germany
University medical centers in Baden-Württemberg and Bavaria anchor premium instrument uptake as EU MDR acoustic performance validation mandates force replacement of legacy inventories. Notified body oversight requires ISO 13485-certified supply chains with traceable manufacturing records. The Tübingen-Stuttgart medical device cluster concentrates handcrafted precision instrument production for Central European diagnostic centers.
Japan
PMDA enforcement of JIS T 0601-1 electromagnetic compatibility standards, revised in 2023, mandates shielding validation for wireless-enabled diagnostic devices entering university hospital networks. Domestic manufacturers capture temporary advantage through pre-certified platform architectures. The Kanto region around Tokyo concentrates demand from aging population cardiovascular screening programs.
India
Primary care extension programs in Maharashtra and Karnataka prioritize amplified sound clarity for tuberculosis screening, creating first-time demand for digital transmission-capable devices. CDSCO medical device rules govern import and local assembly certification. Medical equipment marketplaces in Bangalore and Mumbai serve rural health networks through specialized e-commerce platforms.
Brazil
Remote auscultation protocols in Minas Gerais and São Paulo state rural health networks drive adoption of electronic stethoscopes with telemedicine integration capabilities. ANVISA medical device registration requirements shape import patterns for amplified diagnostic instruments. The São Paulo metropolitan corridor concentrates procurement from diagnostic center chains expanding into underserved interior municipalities.
Global Stethoscope Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology vectors, with acoustic instrument craftsmanship requiring dedicated manufacturing infrastructure while electronic platforms depend on firmware development and sensor integration partnerships. The vendor base stratifies across heritage acoustic specialists, diversified medical device conglomerates, and emerging digital health entrants. Three archetypes dominate: precision instrument craftsmen with century-old brand equity, diversified healthcare conglomerates leveraging distribution scale, and venture-backed digital health platforms integrating AI classification algorithms. Competitive moves concentrate on strategic partnerships for EHR integration and geographic expansion through direct sales forces in hospital federations.
Within the heritage craftsmanship tier, Rudolf Riester GmbH exemplifies German precision instrument manufacturing anchored in manual assembly traditions. Among diversified healthcare conglomerates, 3M occupies a position leveraging extensive clinical training infrastructure and brand recognition across European hospital networks. At the digital health frontier, Eko Health represents the AI-enabled platform archetype, with hardware-software integration targeting cardiology information system workflows. These three anchors illustrate the competitive tension between acoustic authenticity, manufacturing scale, and algorithmic enhancement reshaping procurement criteria.
| Leading Market Players |
|---|
| 3M |
| Medline Industries |
| Welch Allyn (Hill-Rom Holdings) |
| Eko Health |
| GF Health Products |
| American Diagnostic Corporation |
| Rudolf Riester GmbH |
| Cardionics |
| HEINE Optotechnik |
| Others |
Supply & Pricing Matrix
MEMS sensor miniaturization is collapsing the cost gap between electronic and acoustic stethoscope architectures while simultaneously concentrating piezoelectric element supply among Japanese and German component specialists. Hospital procurement officers now face compressed upgrade cycles alongside allocation risk for high-fidelity sensors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates validated electronic platforms with EHR integration from basic amplified units and legacy acoustic instruments. Price differentiation rests on ISO 13485 certification status and bundled clinical training services. Cost compression in the standard tier is intensifying because Vietnamese assembly capacity is expanding. General practice clinics exhibit highest price sensitivity, while German university medical centers prioritize acoustic performance validation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for piezoelectric sensors are forcing device assemblers to qualify secondary Japanese and German component suppliers alongside primary relationships. Manufacturing draws from Malaysian rubber tubing networks, Chilean copper binaural forging, and Vietnamese final assembly platforms. Single-source vulnerability concentrates in high-fidelity MEMS fabrication. Distribution runs through regional medical distributors holding ISO 13485-certified inventory for European hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic stethoscope margins are expanding as MEMS cost curves steepen downward and cardiology departments absorb premium pricing for AI-enhanced diagnostic platforms.
For Market Incumbents: Cement hospital system relationships through multi-year device-and-service agreements that bundle EHR integration with clinical training infrastructure. Deepen backward integration into piezoelectric sensor supply through captive partnerships with Japanese MEMS fabricators. Defend against AI-enabled platform entrants by accelerating FDA software-as-medical-device submissions for murmur classification algorithms. For New Entrants and Emerging Players: Capture pediatric specialization white space where ISO 10993 biocompatibility standards constrain incumbent supplier pools. Target neonatal diaphragm configurations below 2.5cm diameter with hypoallergenic material compliance. Enter through direct e-commerce channels serving Indian and Brazilian rural health networks before scaling distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among handcrafted acoustic specialists facing EU MDR compliance cost burdens. Long-term viability favors platforms with algorithm-enhanced diagnostic workflows integrated into cardiology information systems. Watch FDA-EU AI Act harmonization progress as the inflection signal for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body engagement compresses launch timelines for electronic platforms. |
| Hospital System Partnership | Integrated delivery networks consolidate procurement through multi-year device-and-service agreements. |
| Software Companion Development | Machine learning murmur classification algorithms capture workflow integration premiums. |
| Backward Integration into Sensors | Captive piezoelectric supply insulates assemblers from Japanese component allocation risk. |
| Reimbursement Strategy | Telemedicine infrastructure rollout in India and Brazil creates first-time digital auscultation payment pathways. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts specialists, and cardiology department heads grounded the qualitative foundation. Secondary validation drew from FDA 510(k) filings, EU MDR technical file databases, hospital procurement contract repositories, and CDSCO medical device registration records. Bottom-up shipment modeling triangulated against top-down healthcare expenditure allocation estimates.
Bottom-up volume builds aggregated hospital system procurement patterns, clinic channel flows, and medical school demonstration-grade shipments across product type, application, and end-user dimensions. Top-down verification cross-checked against national healthcare device expenditure reports and medical device trade flow data. CAGRs were derived from segment-level growth rate reconciliation across the projection horizon, with electronic stethoscope sensor cost curves and telemedicine infrastructure deployment timelines as primary forecast inputs.
Regulatory harmonization delays, piezoelectric sensor supply disruptions, and EU notified body capacity constraints are the dominant revision risks. Deviation in FDA-EU AI Act alignment timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Cardiac Marker Analyzer Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Heart Lung Machine Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
Heart Scan Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market
Cardiology Equipment
Europe Electrophysiology Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Cardiac Catheterization Market