
 Hearing Loop Market | 2026-2036
Hearing Loop Market Size, Share, and Industry Trends Forecast 2026-2036
Hearing Loop Market Outlook
Market Context
European amplifier manufacturers is decoupling from legacy analog component sourcing as digital architectures gain share. Ampetronic leverages in-house driver design to sustain premium positioning across UK transport hubs. Williams AV competes through channel control in North American house-of-worship verticals. Contacta anchors its footprint via installer training networks spanning Nordic public sector procurement.
Technical Definition and Segment Structure
A hearing loop is an audio frequency induction loop system that transmits sound directly to telecoil-equipped hearing aids via a magnetic field generated by a loop of wire, typically operating within 100 Hz to 5 kHz with field strength calibrated to IEC 60118-4 standards. Fixed loop installations dominate current revenue as retrofit demand from heritage auditoriums and transport terminals sustains replacement cycles. Portable loop systems represent the fastest-expanding product type as event venues and temporary installations prioritize flexibility over permanent infrastructure. Digital technology segments command margin premiums over analog equivalents as stakeholders integrate networked monitoring and remote calibration capabilities.
Regulatory Framework and Outlook
The ADA Standards for Accessible Design in the United States, the Equality Act 2010 in the United Kingdom, and IEC 60118-4 international performance standards collectively mandate minimum magnetic field strength and frequency response compliance, effectively filtering non-certified suppliers from public procurement channels. The EU Accessibility Act extends these requirements across member states, creating a unified compliance baseline for cross-border equipment vendors. Stakeholders must monitor evolving building code harmonization between national accessibility mandates and international electromagnetic compatibility standards to anticipate certification burden shifts.
Market Dynamics
Digital signal processing architectures are compressing analog component demand while IEC 60118-4 compliance mandates filter supplier participation in public procurement channels. Copper coil manufacturing improvements and networked remote calibration capabilities are redrawing competitive positioning between established amplifier vendors and emerging system integrators.
Growth Catalysts
- ADA Standards for Accessible Design:United States transit authorities and house-of-worship venues face magnetic field strength mandates that disqualify uncertified equipment, channeling replacement demand toward compliant system providers.
- Copper wire drawing automation:Precision coil manufacturing is reducing installation labor hours and field calibration iterations, compressing total project cost for heritage auditorium retrofits.
- United Kingdom transport terminal modernization:Network Rail and airport operators under Equality Act 2010 obligations are specifying induction loop infrastructure in accessibility upgrade tenders.
Market Restraints
- Copper price volatility:Coil winding constitutes 35-45% of material cost in fixed installations, exposing project margins to London Metal Exchange commodity swings without pass-through clauses.
- Telecoil penetration ceiling:Hearing aid manufacturers have deprioritized analog telecoil receivers in favor of Bluetooth LE Audio, threatening long-term addressable market expansion for loop-only venues.
- Installer certification scarcity:IEC 60118-4 field verification requires specialized flux meter operation and loop geometry calculation skills concentrated among aging electrical contractor cohorts in Germany and Scandinavia.
Strategic Opportunities
- India accessibility code alignment:Bureau of Indian Standards adoption of IEC audio frequency induction loop standards creates first-mover positioning for certified equipment vendors in metro rail and parliamentary building projects.
- Portable system rental channels:Event production houses in the United States are building loop inventory for temporary conference and exhibition deployments, shifting revenue from capital sale to recurring service models.
- EU Accessibility Act harmonization:Cross-border public procurement standardization enables single certification entry into 27 member state markets, reducing regulatory fragmentation compliance costs.
Industry Challenges
- Flux meter calibration drift:Field strength verification equipment requires annual laboratory recertification that installer networks struggle to maintain, producing measurement disputes and project acceptance delays.
- Heritage building fabric constraints:Stone and reinforced concrete structures in United Kingdom and German public buildings obstruct clean loop perimeter routing, demanding custom multi-array designs that compress project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hearing Loop Market |
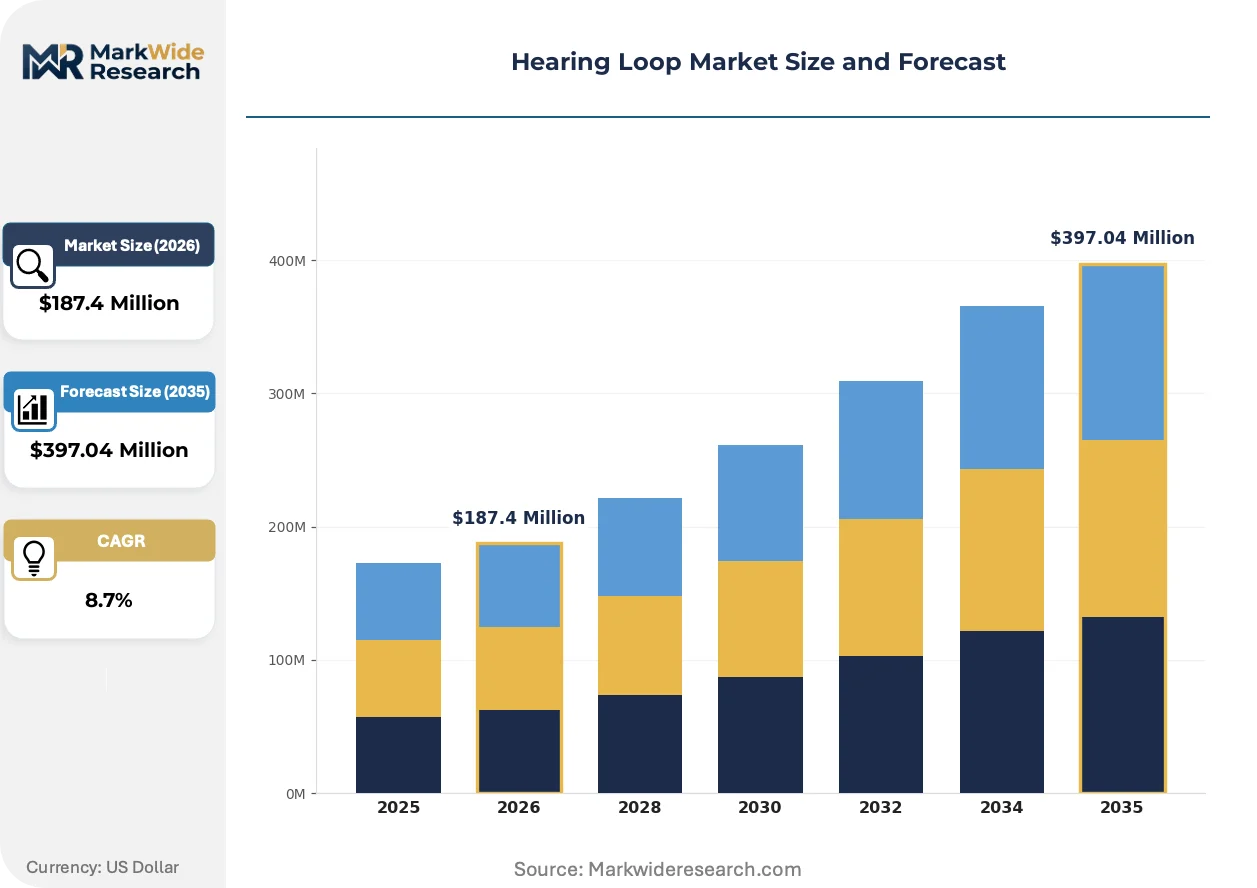
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Loop, Fixed Loop, In-Ceiling Loop, In-Stallation Kit End User: Auditoriums, Airports, Houses of Worship, Schools Installation: Wall-Mounted, Floor-Installed, Ceiling-Mounted, Mobile Technology: Infrared, FM, Digital, Analog |
| Companies Covered | Ampetronic, Opus Technologies, Williams AV, Contacta, Listen Technologies, Audio Directions, Geemarc, Univox, Loop America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hearing Loop Market Strategic Shifts
Class-D amplifier topologies and networked DSP platforms are displacing legacy analog driver architectures across transport and worship venue deployments. Real-time field monitoring and cloud-based calibration are compressing service contract structures while raising performance accountability.
Networked DSP-enabled driver systems is electrifying hearing loop infrastructure by embedding IEC 60118-4 field strength telemetry directly into amplifier firmware. United Kingdom rail operators and United States airport authorities are specifying these systems in new-build tenders to eliminate manual verification site visits. The technology is electrifying competitive differentiation by binding hardware vendors to recurring software subscription revenue streams.
The EU Accessibility Act implementation timeline is compressing national regulatory divergence across member states, creating unified procurement specifications for cross-border equipment vendors. Industrial consequence includes accelerated CE marking harmonization with IEC 60118-4 testing protocols. Nordic public sector buyers are responding by consolidating supplier qualification lists around dual-certified manufacturers.
Facility managers are unbundling installation from long-term performance guarantees, demanding outcome-based contracts with field strength compliance SLAs. Systems integrators in Germany and the United Kingdom are displacing pure equipment resale with managed service offerings encompassing remote monitoring and annual recalibration. This pattern is most visible in United States healthcare and educational institution procurement, where capital budget constraints favor operational expenditure treatment.
Hearing Loop Market Segmentation
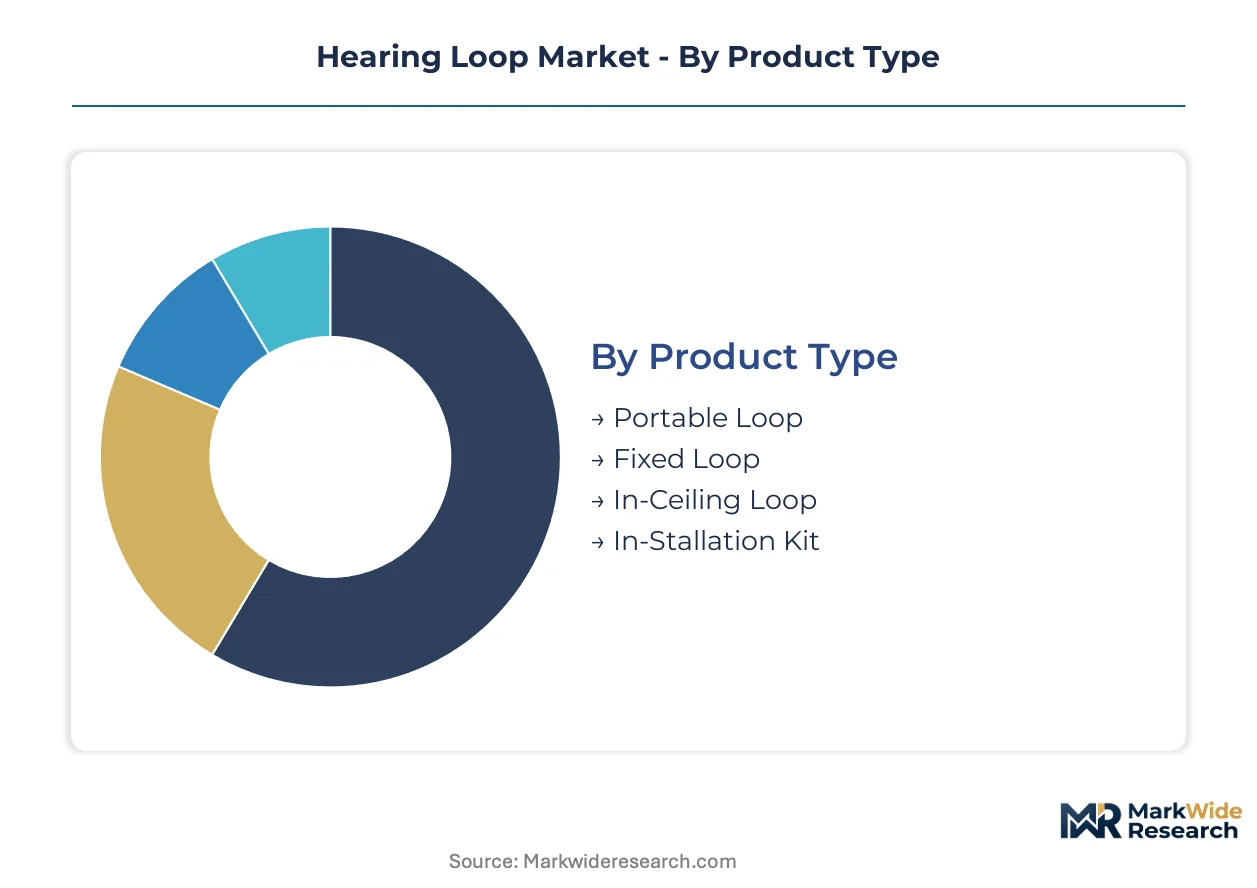
Hearing loop procurement channels filter sharply across product and installation categories, with IEC 60118-4 certification requirements diverging between permanent infrastructure and temporary deployments. End-user verticals impose distinct magnetic field strength tolerances and aesthetic constraints that reshape supplier qualification criteria.
Product Type:
IEC 60118-4 field verification complexity varies dramatically across product formats, with fixed installations demanding full compliance documentation while portable systems operate under abbreviated self-certification protocols in most jurisdictions.
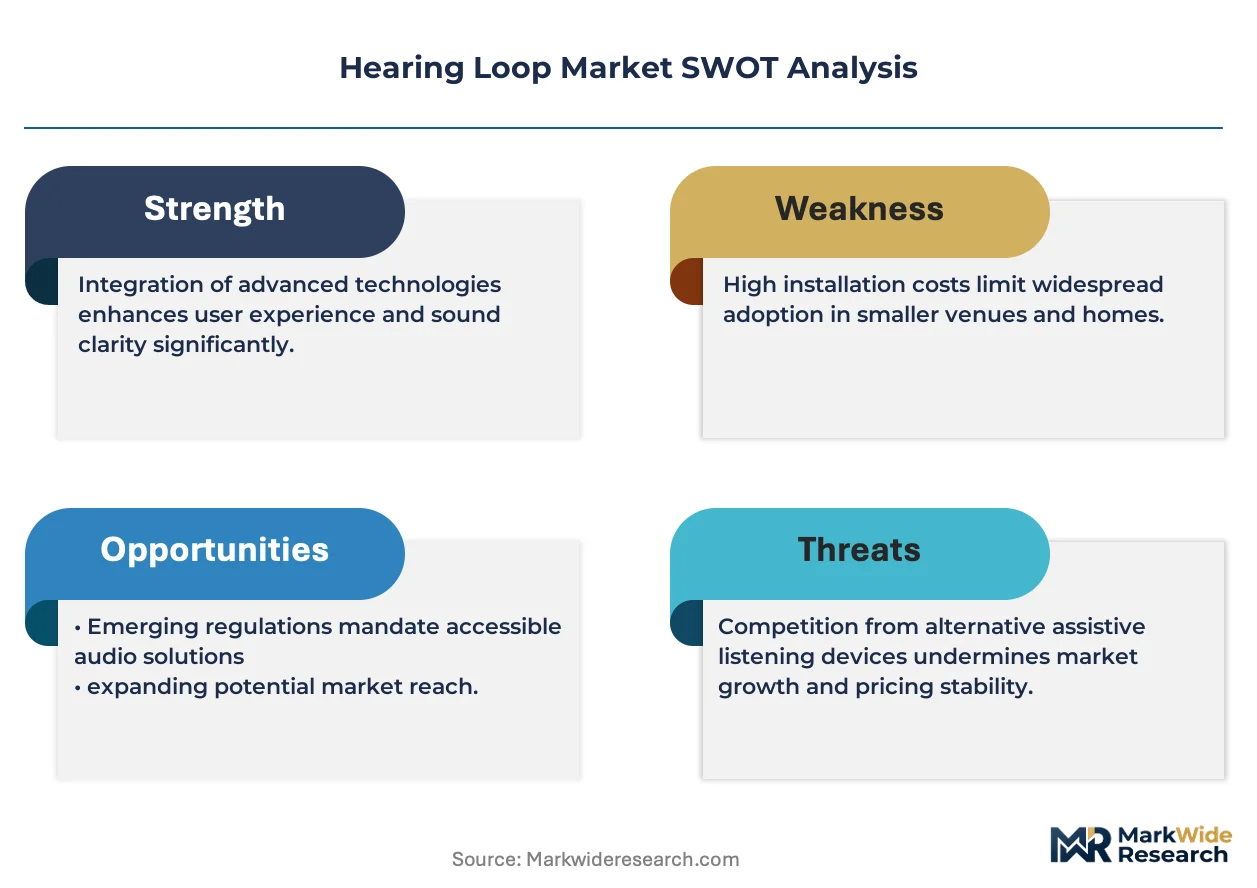
- Fixed Loop:Permanent perimeter wire installations in copper or flat copper tape, typically embedded under flooring or wall surfaces during construction or retrofit phases. Heritage auditoriums in the United Kingdom and Germany sustain replacement demand as Equality Act 2010 and federal accessibility mandates trigger infrastructure modernization cycles.
- Portable Loop:Self-contained amplifier and loop mat systems designed for temporary deployment. Event production houses in the United States are building rental inventory for conference and exhibition use, shifting revenue from capital sale toward recurring service models.
- In-Ceiling Loop:Concealed perimeter arrays integrated into suspended ceiling grids, favored in airport terminals and corporate environments where visible wiring conflicts with interior design standards.
- In-Stallation Kit:Modular component packages for contractor field assembly, common in house-of-worship verticals where volunteer labor drives cost-sensitive procurement decisions.
Fixed Loop sits at the top of the volume ranking, with Portable Loop climbing the fastest.
End User:
Procurement authority structures diverge sharply across verticals, with public sector transport operators bound by statutory accessibility mandates while private worship venues operate under voluntary compliance incentives and insurance liability considerations.
- Auditoriums:Performing arts venues and cinema complexes requiring full-coverage magnetic field uniformity across tiered seating geometries. Stone and reinforced concrete fabric in United Kingdom and German heritage buildings obstructs clean loop routing, demanding custom multi-array designs.
- Airports:Gate areas, check-in halls, and security zones under ADA Standards for Accessible Design and equivalent European obligations. United States transit authorities and United Kingdom airport operators are specifying networked DSP-enabled systems with embedded field strength telemetry to eliminate manual verification site visits.
- Houses of Worship:Churches, mosques, synagogues, and temples with volunteer-driven procurement and acoustic variability from reverberant stone architecture. North American congregations prioritize channel-controlled equipment packages with installer training support.
- Schools:Educational institutions spanning K-12 through university lecture halls, where capital budget constraints favor operational expenditure treatment and managed service offerings encompassing remote monitoring.
Airports command the steepest expansion trajectory, with Schools gaining share fastest as educational accessibility litigation accelerates specification.
Installation:
Labor cost concentration and field calibration iteration requirements vary by mounting topology, with floor-installed systems demanding substrate preparation while ceiling-mounted arrays compete for space with HVAC and lighting infrastructure.
- Floor-Installed:Copper tape or wire embedded in floor screed or carpet underlay, the dominant configuration for heritage auditorium retrofits where wall and ceiling routing is structurally prohibitive.
- Ceiling-Mounted:Perimeter loops integrated into suspended ceiling systems, prevalent in airport terminals and corporate environments where floor access is operationally disruptive.
- Wall-Mounted:Vertical perimeter arrays for small meeting rooms and assistive listening points, offering lower material cost but restricted coverage area.
- Mobile:Battery-powered or mains-connected portable units with integrated loop and amplifier, deployed in temporary exhibition and conference settings without permanent infrastructure commitment.
Floor-Installed maintains volume leadership, with Mobile expanding most quickly on event rental channel development.
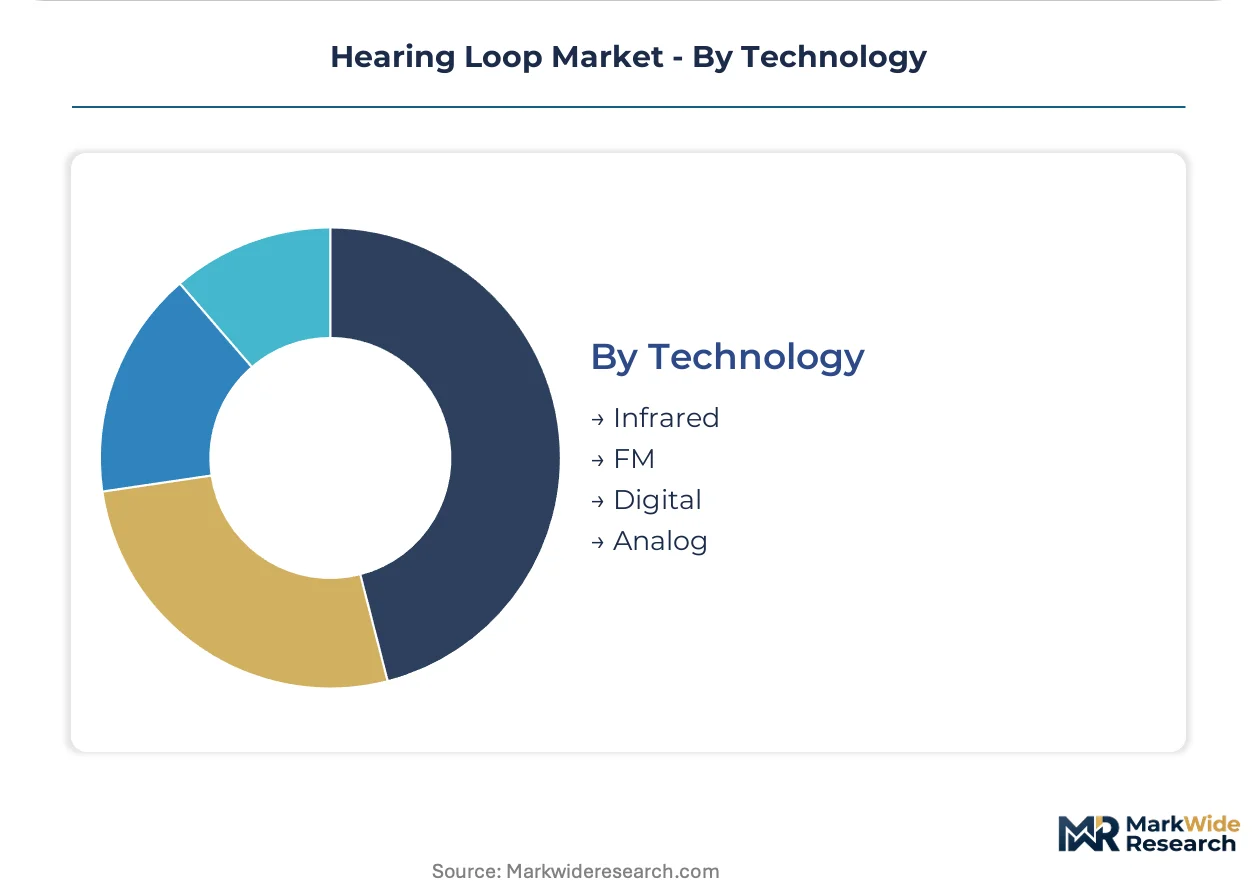
Technology:
Component sourcing strategies decouple from legacy analog supply chains as digital architectures gain procurement share, with margin premiums attaching to networked monitoring and remote calibration capabilities.
- Digital:DSP-enabled driver systems with firmware-embedded IEC 60118-4 field strength telemetry and cloud-based calibration interfaces. United Kingdom rail operators specify these in new-build tenders to compress service contract structures.
- Analog:Traditional Class-AB amplifier topologies with discrete component signal paths, sustaining price-competitive positioning in cost-sensitive house-of-worship and school verticals.
- Infrared:Optical transmission alternative to magnetic induction, requiring line-of-sight emitter placement and receiver hardware rather than telecoil compatibility.
- FM:Radio frequency assistive listening systems operating outside magnetic loop standards, competing for specification in venues where electromagnetic interference or metal structural interference compromises loop performance.
Analog retains the largest installed base, with Digital capturing the fastest growth on subscription revenue model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates substantially higher hearing loop deployment volumes than Germany, though both markets operate under comparably stringent accessibility mandates that filter non-certified suppliers from public procurement.
United States
Airport terminal modernization and house-of-worship retrofits sustain replacement demand under ADA Standards for Accessible Design. The Department of Transportation enforces magnetic field strength compliance in transit authority tenders. Chicago O'Hare and Atlanta Hartsfield-Jackson specify networked DSP-enabled systems with embedded telemetry.
Germany
Heritage auditorium renovations and federal building accessibility upgrades concentrate procurement in copper coil installations. The federal government aligns public procurement with IEC 60118-4 performance standards through DIN harmonization. Munich and Frankfurt transport operators specify multi-array designs for reinforced concrete structural constraints.
United Kingdom
Network Rail and airport operators under Equality Act 2010 obligations drive induction loop infrastructure in accessibility tenders. The Equality and Human Rights Commission monitors compliance across public sector venues. London Heathrow and Manchester Airport specify systems with remote calibration capabilities to compress service contracts.
India
Metro rail expansion and parliamentary building projects create first-mover positioning for certified equipment vendors. The Bureau of Indian Standards adoption of IEC audio frequency induction loop standards opens public procurement channels. Delhi Metro and Mumbai Metro specify loop infrastructure in new station construction.
Sweden
Nordic public sector procurement consolidation around dual-certified manufacturers sustains installer training network investments. The Swedish Transport Administration mandates loop coverage in rail station accessibility upgrades. Stockholm Arlanda Airport and Gothenburg Central Station specify portable system rentals for temporary exhibition deployments.
Hearing Loop Market Competitive Environment
United Kingdom producers anchor the premium-tier amplifier segment; North American specialists hold channel control in house-of-worship verticals. The vendor base organizes around three strategic archetypes: in-house driver designers sustaining technical differentiation, installer training network operators capturing public sector loyalty, and rental channel builders shifting revenue to service models. Competitive moves concentrate on geographic expansion into harmonized EU procurement zones and backward integration into precision coil manufacturing.
Within the premium-tier vector, Ampetronic occupies a position exemplifying in-house driver design specialization. Williams AV and Contacta represent alternative archetypes—channel control through vertical-focused distribution and installer certification network density respectively. Listen Technologies sits within the emerging tier of rental channel operators building recurring revenue models. These three anchors illustrate the strategic divergence between equipment-centric and service-centric competitive positioning.
| Leading Market Players |
|---|
| Ampetronic |
| Opus Technologies |
| Williams AV |
| Contacta |
| Listen Technologies |
| Audio Directions |
| Geemarc |
| Univox |
| Loop America |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between IEC 60118-4 compliant systems and uncertified alternatives splits pricing power across divergent supply chain configurations. Premium-tier vendors source precision-wound copper coils from specialized German and UK manufacturers, while commodity-grade competitors draw from standardized Asian wire suppliers.
Pricing Analysis
Distributor margins of 25-35% separate factory-gate equipment pricing from end-user project quotes in the United States and United Kingdom. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, remote monitoring capability, and installer training bundling. Pricing pressure stems from copper commodity volatility and Bluetooth LE Audio substitution threat in hearing aid verticals. House-of-worship congregations exhibit highest price sensitivity, while airport authorities under ADA mandates demonstrate lowest.
Supply Chain Analysis
Specialized electrical contractor availability constrains amplifier assembly capacity in Germany, the United Kingdom, and Sweden. Copper coil winding concentrates in Germany and China, with DSP chip sourcing anchored in Taiwan and South Korea. Supply chain risk centers on single-source vulnerability for precision flux meter calibration equipment. Distribution runs through certified installer networks rather than traditional electronics wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in digital-tier upgrades as copper automation and firmware-based calibration compress service delivery costs. Premium positioning shifts toward recurring telemetry subscriptions.
For Market Incumbents: Deploy backward integration into precision coil manufacturing to defend against copper price volatility and capture 15-20 point margin expansion. Reinforce installer certification network density in Germany and Scandinavia where aging electrical contractor cohorts threaten deployment capacity. Counter Bluetooth LE Audio substitution by bundling telecoil-BLE hybrid receivers in new amplifier generations. For New Entrants and Emerging Players: Cloud-native DSP platforms with embedded IEC compliance telemetry offer wedge opportunity against legacy analog incumbents. Target India metro rail and parliamentary building verticals where Bureau of Indian Standards adoption creates first-mover certification window. Pursue portable system rental channel partnerships with US event production houses to bypass capital-intensive fixed installation competition. For Investors and Strategic Acquirers: Consolidation pressure builds where installer certification scarcity meets fragmented regional amplifier vendors. Five-to-ten year viability favors dual-certified manufacturers with software subscription revenue attachment. Target acquisition archetype: German or UK-based firms with captive coil winding and established public sector procurement relationships. Signal to watch: EU Accessibility Act enforcement intensity accelerating cross-border procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Manufacturing | German precision winding capabilities insulate margins from London Metal Exchange copper volatility. |
| Networked DSP Platform Launch | Embedded IEC 60118-4 telemetry enables UK rail operators to eliminate manual verification site visits. |
| Installer Certification Network Expansion | Scandinavian electrical contractor training density secures public sector procurement loyalty. |
| Portable System Rental Channel Buildout | US event production house partnerships shift revenue from capital sale to recurring service models. |
| India Market Entry Certification | Bureau of Indian Standards alignment opens Delhi Metro and parliamentary building procurement channels. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork encompassed amplifier manufacturer product managers, certified loop installation contractors, airport accessibility compliance officers, house-of-worship technical directors, and public sector procurement managers. Secondary validation drew from IEC standards documentation, ADA Standards for Accessible Design regulatory filings, EU Accessibility Act implementation guidance, customs trade data for copper coil imports, and Bureau of Indian Standards adoption notices. Bottom-up project pipeline tracking triangulated against top-down equipment shipment estimates.
Segment-weighting approaches distributed value across fixed, portable, in-ceiling, and installation kit product types, with cross-referencing against airport, auditorium, house-of-worship, and school end-user verticals. CAGRs derived from logarithmic interpolation of annual deployment trajectories, with copper price sensitivity scenarios and telecoil penetration assumptions as industry-specific forecast inputs across the projection horizon.
The model holds under stable IEC 60118-4 certification requirements and continued telecoil inclusion in hearing aid designs; deviation in Bluetooth LE Audio regulatory preference or copper commodity spike triggers would shift volume and value trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veterinary Procedure Lights Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Venturi Mask Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
Surgical AR Systems Market
Medical Devices
Radiotherapy Devices Market
Medical Devices
Chest Drainage System Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Hair Removal Devices Market
Medical Devices
C-Arms Devices Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
Global Auto-Injectors Market
Medical Devices
Repetitive Transcranial Magnetic Stimulation Market
Medical Devices
Asia-Pacific Respiratory Devices Market