
 Craniomaxillofacial Devices Market | 2026-2036
Craniomaxillofacial Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Craniomaxillofacial Devices Market Insights
Aftermarket service revenue for implant maintenance and revision instrumentation is tilting toward original equipment manufacturers with direct hospital contracts. Stryker leverages its integrated trauma and extremities platform to capture recurring service income across major medical centers. Medtronic anchors its position through deep spine and neurosurgical channel relationships that extend into craniomaxillofacial cases. Zimmer Biomet differentiates via its specialized dental and CMF portfolio, competing for high-acuity reconstructive procedures.
Craniomaxillofacial devices encompass plates, screws, meshes, and fixation systems fabricated from titanium alloys, resorbable polymers, or biodegradable composites, engineered to stabilize facial skeleton fractures and correct congenital or acquired deformities through osteosynthesis. Titanium alloy plates dominate trauma applications due to strength-to-weight ratios and magnetic resonance imaging compatibility, while resorbable polymer segments gain traction in pediatric cranial reconstruction where permanent hardware removal carries operative risk. 3D printing technology reshapes patient-specific implant production, with CAD/CAM design workflows enabling anatomically matched reconstructions for complex cranial defects that conventional stock implants cannot address.
FDA 510(k) premarket notification requirements govern device clearance in the United States, while the EU Medical Device Regulation enforces stricter clinical evidence standards for implantable CMF products entering European markets. The FDA's emphasis on biocompatibility testing and fatigue performance for load-bearing facial implants elevates development costs but reinforces barriers against undercapitalized entrants. Stakeholders must monitor evolving reimbursement thresholds for patient-specific 3D-printed implants across Medicare and major private payers, as coverage determinations will dictate whether additive manufacturing investments translate into sustainable revenue streams or remain confined to cash-pay academic centers.
Market Dynamics
Patient-specific 3D-printed implants are compressing production timelines for complex cranial reconstructions while forcing traditional manufacturers to reconfigure their CAD/CAM capabilities and hospital contracting structures.
Growth Catalysts
- Trauma Reconstruction Volumes:Hospital emergency departments in the United States, Germany, and China are expanding dedicated CMF surgical units as facial injury admissions rise from road accidents and sports trauma.
- MDR Compliance Pathways:The EU Medical Device Regulation's stricter clinical evidence requirements for implantable products are accelerating consolidation among manufacturers with robust quality management systems.
- Titanium Alloy Advances:Improved strength-to-weight ratios in medical-grade titanium are extending indications from trauma fixation into elective orthognathic procedures.
Market Restraints
- Raw Material Concentration:Medical-grade titanium sponge supply concentrates in Chinese and Russian smelters, exposing device manufacturers to geopolitical input volatility and export restriction risk.
- Biocompatibility Testing Burden:FDA fatigue performance requirements for load-bearing facial implants extend development timelines and elevate capital requirements for preclinical validation.
- Resorbable Polymer Limitations:Degradation rate unpredictability in polylactic acid and polyglycolic acid constructs restricts their use to pediatric cases where hardware removal carries operative risk.
Strategic Opportunities
- Indian Hospital Infrastructure:Private medical centers in Mumbai and Delhi are investing in specialized CMF surgical suites as medical tourism for facial reconstruction accelerates.
- AI-Assisted Surgical Planning:Machine learning algorithms are converging with cone-beam CT imaging to automate implant sizing and reduce operative time for complex orbital reconstructions.
- Direct-to-Hospital Distribution:Original equipment manufacturers are bypassing traditional distributors to capture recurring service revenue through maintenance contracts for revision instrumentation.
Industry Challenges
- CAD/CAM Talent Scarcity:Biomedical engineers with combined expertise in anatomical modeling and regulatory documentation remain concentrated in academic medical centers and specialized design firms.
- 510(k) Submission Complexity:FDA predicate device identification for patient-specific implants requires extensive biomechanical testing that compresses margins for smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Craniomaxillofacial Devices Market |
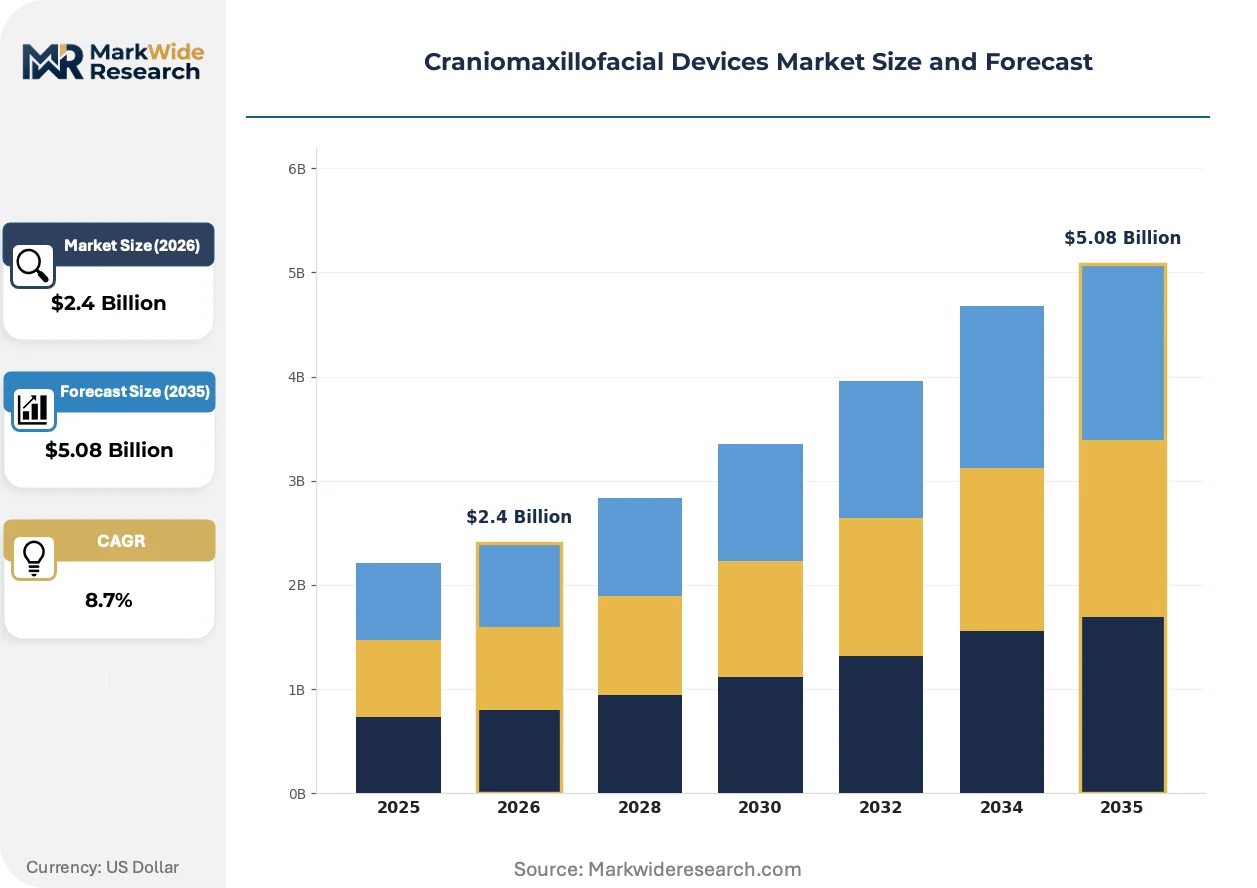
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Screws, Fixators, Meshes, Distractors Technology: 3D Printing, CAD/CAM Design, Biodegradable Materials, Titanium Alloy, Resorbable Polymers Application: Trauma Reconstruction, Orthognathic Surgery, Cranial Reconstruction, Temporomandibular Joint Repair End User: Hospitals, Specialized Clinics, Oral & Maxillofacial Surgeons, Research Institutes |
| Companies Covered | Stryker, Johnson & Johnson, Medtronic, Zimmer Biomet, B. Braun Melsungen, KLS Martin Group, Medartis, Integra LifeSciences, W. L. Gore & Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Craniomaxillofacial Devices Market Trends and Innovations
Additive manufacturing workflows are collapsing the traditional separation between diagnostic imaging and implant production, enabling same-week turnaround for emergency trauma cases that previously required extended external fabrication.
Patient-specific titanium implants fabricated through electron beam melting are hybridizing preoperative planning with intraoperative navigation systems. Academic medical centers in the United States and Germany are adopting these integrated workflows for complex cranial defect reconstruction. The technology is compressing operative time and reducing revision rates for cases that exceed the anatomical limits of stock implant inventories.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic implant registries and real-world evidence collection. Manufacturers must now fund longitudinal outcome studies that track device performance across diverse patient populations. High-acuity reconstructive centers in France and the Netherlands are responding by consolidating purchasing around suppliers with established clinical data infrastructures.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, creating separate competitive arenas for implant supply and instrumentation maintenance. Major medical centers in the United States are negotiating multi-year service agreements directly with manufacturers. This pattern is most visible in Level I trauma centers where revision surgery volumes generate predictable recurring revenue streams.
Craniomaxillofacial Devices Market Segmentation
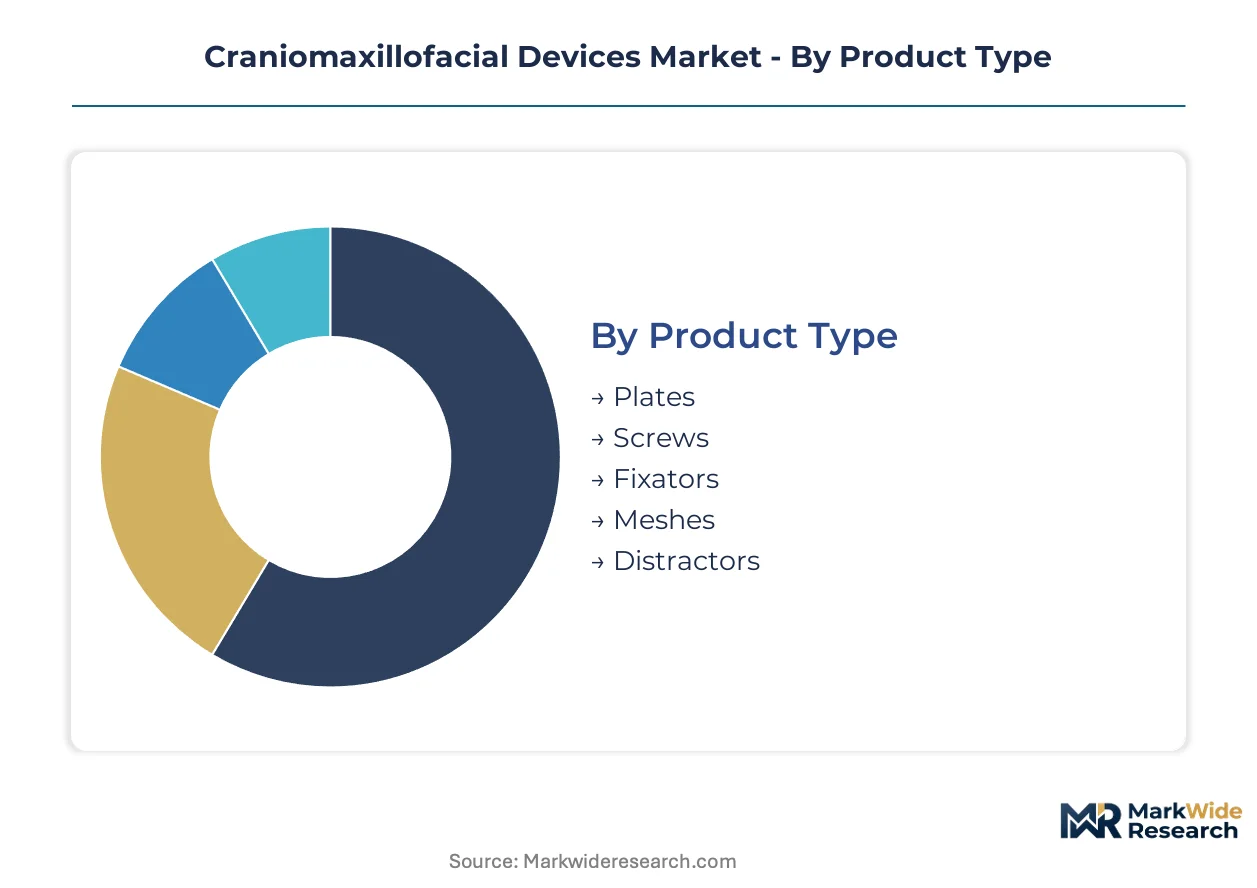
Segmentation in craniomaxillofacial devices reveals divergent replacement cycles across hardware versus consumable categories. Titanium plates and screws turn over rapidly in high-volume trauma centers, while 3D-printed patient-specific implants operate on extended procurement timelines tied to surgical planning workflows.
Product Type:
Replacement velocity varies sharply across this category—fixation hardware cycles quarterly in busy Level I trauma centers, whereas distractors and meshes align with scheduled reconstructive calendars.
- Plates:Titanium alloy constructs with precontoured anatomical profiles enable rapid intraoperative adaptation for mandibular and orbital fractures. Demand clusters in United States emergency departments where road trauma and sports injuries drive consistent throughput. Strength-to-weight optimization and MRI compatibility sustain preference over resorbable alternatives in adult populations.
- Screws:Self-tapping cortical and cancellous bone designs in 1.0mm to 2.7mm diameters secure plate-to-bone fixation across the facial skeleton. German trauma centers specify locking screw geometries for load-bearing mandibular reconstructions, with procurement volumes tracking seasonal trauma admission patterns.
- Fixators:External and internal fixation systems stabilize complex fractures through rigid mechanical frames or internal rod constructs. Chinese hospitals are expanding dedicated CMF surgical units that consume these devices in rising volumes.
- Meshes:Titanium and polymer meshes reconstruct cranial vault defects and orbital floor disruptions. Pediatric cranial reconstruction in academic medical centers favors resorbable polymer meshes where permanent hardware removal carries operative risk.
- Distractors:Gradual bone lengthening devices correct congenital mandibular hypoplasia and post-traumatic segmental defects. Specialized oral and maxillofacial surgery practices in India deploy these for orthognathic correction as medical tourism expands.
Plates dominate installed base. Screws are where expansion concentrates.
Technology:
Cost tier stratification separates mature material platforms from emerging fabrication methods requiring capital-intensive infrastructure.
- 3D Printing:Electron beam melting and selective laser sintering fabricate patient-specific titanium implants from cone-beam CT datasets. United States academic medical centers compress emergency trauma turnaround to same-week delivery, displacing traditional stock inventories for complex cranial defects.
- CAD/CAM Design:Computer-aided design workflows translate diagnostic imaging into surgical guides and implant geometries. German reconstructive centers integrate these systems with intraoperative navigation for orbital and zygomatic reconstructions.
- Biodegradable Materials:Magnesium and zinc alloys degrade predictably while providing temporary structural support. Research institutes in China evaluate these for pediatric applications where permanent metal retention raises long-term concerns.
- Titanium Alloy:Medical-grade Ti-6Al-4V and commercially pure titanium deliver strength-to-weight ratios with established biocompatibility profiles. Hospital procurement departments negotiate multi-year supply agreements for these standardized materials.
- Resorbable Polymers:Polylactic acid and polyglycolic acid constructs eliminate secondary removal surgery in pediatric cranial reconstruction. Degradation rate unpredictability restricts deployment to cases where hardware removal carries unacceptable operative risk.
Titanium alloy anchors volume revenue. 3D printing is climbing the fastest.
Application:
Customer type and urgency differentiate scheduled elective procedures from emergent trauma interventions with compressed decision timelines.
- Trauma Reconstruction:Emergency fixation of facial skeleton fractures from vehicular accidents, assaults, and sports injuries. United States Level I trauma centers report rising admission volumes that strain plate and screw inventories.
- Orthognathic Surgery:Corrective jaw procedures address skeletal malocclusions and congenital deformities through Le Fort osteotomies and bilateral sagittal split ramus osteotomies. German specialized clinics schedule these electively with 3D-printed surgical guides.
- Cranial Reconstruction:Defect repair following decompressive craniectomy, tumor resection, or congenital anomalies. Chinese hospitals invest in specialized surgical infrastructure for these high-acuity cases.
- Temporomandibular Joint Repair:Disc repositioning, condylar reconstruction, and total joint replacement address degenerative and traumatic joint pathology. Oral and maxillofacial surgeons in India perform these procedures for medical tourism patients.
Trauma reconstruction commands procedure volume. Cranial reconstruction is gaining share fastest.
End User:
Procurement authority and service integration requirements separate institutional purchasers from individual practitioner decision-makers.
- Hospitals:Integrated delivery networks with centralized value analysis committees negotiate direct contracts with original equipment manufacturers. United States academic medical centers unbundle after-sales service from capital equipment purchases.
- Specialized Clinics:Focused oral and maxillofacial surgery practices concentrate elective orthognathic and TMJ procedures. German private clinics invest in CAD/CAM capabilities to differentiate patient-specific offerings.
- Oral & Maxillofacial Surgeons:Individual practitioners in solo or group practices select implants based on training familiarity and instrumentation compatibility. Chinese surgeons in tier-1 cities drive adoption of advanced fixation techniques.
- Research Institutes:Academic centers evaluate novel materials and fabrication methods through prospective clinical trials. Indian research institutes collaborate with manufacturers on biodegradable alloy development.
Hospitals dominate purchasing volume. Specialized clinics are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland demonstrate the lowest price elasticity, absorbing premiums for patient-matched implants, while procurement committees in China and India enforce aggressive cost compression on standardized titanium fixation hardware.
United States
Level I trauma centers in Baltimore and Houston are expanding dedicated CMF surgical units as facial injury admissions from road accidents and sports trauma climb steadily. FDA 510(k) premarket notification pathways govern device clearance, with emphasis on biocompatibility testing and fatigue performance for load-bearing implants. Academic medical centers in Boston and Philadelphia are adopting same-week turnaround workflows for 3D-printed emergency reconstructions.
Germany
Specialized oral and maxillofacial surgery clinics in Munich and Hamburg invest in CAD/CAM capabilities to differentiate patient-specific offerings for elective orthognathic procedures. The EU Medical Device Regulation enforces stricter clinical evidence standards for implantable CMF products, accelerating consolidation among manufacturers with robust quality management systems. Reconstructive centers in Heidelberg and Berlin consolidate purchasing around suppliers with established longitudinal outcome registries.
China
Tier-1 city hospitals in Shanghai and Beijing are building specialized CMF surgical infrastructure as decompressive craniectomy volumes rise from stroke and trauma cases. The National Medical Products Administration regulates device registration through clinical trial and quality system requirements. Research institutes in Shenzhen evaluate biodegradable magnesium alloys for pediatric applications where permanent metal retention raises long-term concerns.
India
Private medical centers in Mumbai and Delhi are investing in specialized CMF surgical suites as medical tourism for facial reconstruction accelerates from Middle Eastern and African patients. The Central Drugs Standard Control Organization oversees import licensing and manufacturing standards for implantable devices. Oral and maxillofacial surgeons in Chennai deploy distraction osteogenesis devices for orthognathic correction, competing on cost against Southeast Asian alternatives.
Craniomaxillofacial Devices Market Competitive Landscape
Capability concentration sits with specialized design firms and academic medical centers possessing combined anatomical modeling and regulatory documentation expertise; scale advantage sits with diversified orthopedic and trauma platforms leveraging integrated hospital contracting networks. The market structures around three tiers: diversified multinationals with spine and neurosurgical channel extensions, specialized CMF pure-plays with deep dental and maxillofacial relationships, and emerging additive manufacturing specialists collapsing production timelines for patient-matched reconstructions. Dominant competitive moves include direct-to-hospital distribution bypassing traditional distributors, and strategic consolidation to capture recurring aftermarket service revenue for revision instrumentation.
Within the diversified multinational tier, Stryker and Medtronic occupy positions anchored by integrated trauma and neurosurgical platforms that extend naturally into craniomaxillofacial cases. Zimmer Biomet exemplifies the specialized CMF pure-play archetype, competing through concentrated dental and reconstructive portfolios rather than cross-specialty channel leverage. These three represent contrasting scale-versus-focus strategies: Stryker and Medtronic deploy breadth to capture service contracts across major medical centers, while Zimmer Biomet targets high-acuity reconstructive procedures where specialized instrumentation commands premium positioning.
| Leading Market Players |
|---|
| Stryker |
| Johnson & Johnson |
| Medtronic |
| Zimmer Biomet |
| B. Braun Melsungen |
| KLS Martin Group |
| Medartis |
| Integra LifeSciences |
| W. L. Gore & Associates |
| Others |
Pricing and Supply Chain Analysis
Baoji's titanium sponge refineries anchor global medical-grade titanium feedstock, with capacity utilization swings directly transmitting into implant manufacturer pricing power across North American and European hospital procurement cycles.
Pricing Analysis
Long-term offtake agreements dominate procurement between major device manufacturers and tier-1 hospitals, though spot purchasing persists for emergency trauma cases requiring rapid 3D-printed implant turnaround. Three-tier pricing structure across premium patient-matched implants, standard titanium fixation hardware, and economy resorbable polymer segments reflects certification grade and customization intensity. Cost compression in standard fixation hardware intensifies as Chinese manufacturers expand CE-marked product lines. Academic medical centers in the United States demonstrate lowest price elasticity for patient-specific reconstructions, while Indian private hospitals enforce aggressive tender-based competition on standardized plates and screws.
Supply Chain Analysis
Medical-grade titanium sponge concentrates in Chinese and Russian smelters, with device manufacturers drawing from these upstream sources for Ti-6Al-4V alloy production. Resorbable polylactic acid polymers rest on petrochemical feedstocks from Saudi Arabian and South Korean resin suppliers. Single-source vulnerability in titanium sponge exposes manufacturers to export restriction risk and geopolitical supply disruption. Distribution runs through original equipment manufacturer direct contracts with hospital value analysis committees, displacing traditional distributor intermediaries for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient-specific additive manufacturing is compressing production timelines and collapsing traditional stock inventory models, while EU MDR compliance requirements are accelerating manufacturer consolidation around robust quality management systems.
For Market Incumbents: Entrench hospital system partnerships through multi-year service contracts for revision instrumentation maintenance, capturing recurring revenue streams that emerging competitors cannot match. Deepen backward integration into titanium alloy forging capabilities to insulate margins from raw material volatility. Prioritize FDA 510(k) predicate device libraries that accelerate clearance timelines for patient-specific implant line extensions.
For New Entrants and Emerging Players: Build out CAD/CAM design capabilities targeting mid-tier Indian and Southeast Asian private hospitals where specialized CMF surgical infrastructure investment outpaces established supplier penetration. Focus initial commercialization on resorbable polymer meshes for pediatric cranial reconstruction, a segment where degradation rate unpredictability has constrained incumbent R&D investment. Deploy direct-to-hospital distribution with bundled surgical planning software to differentiate against distributor-dependent legacy competitors.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because MDR compliance burdens and 510(k) submission complexity are structurally advantaging scaled manufacturers with established clinical data infrastructures. Target acquisition candidates with electron beam melting production capabilities and existing hospital system service contracts. Monitor FDA reimbursement determinations for patient-specific 3D-printed implants as the critical signal for whether additive manufacturing investments translate into sustainable revenue streams.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker and Medtronic leverage integrated trauma platforms to secure multi-year service contracts with Level I trauma centers. |
| CE Marking Pathway | EU MDR clinical evidence requirements favor manufacturers with established post-market surveillance registries in Germany and France. |
| Software Companion Development | CAD/CAM surgical planning integration with cone-beam CT imaging reduces operative time for complex orbital reconstructions. |
| Reimbursement Strategy | Medicare coverage determinations for patient-specific 3D-printed implants dictate additive manufacturing investment viability. |
| Backward Integration | Titanium alloy forging capabilities insulate margins from Chinese and Russian sponge supply volatility. |
Research Methodology
A spread of perspectives from hospital purchasing committee chairs, biomedical engineers specializing in anatomical modeling, GPO contracts managers, and oral and maxillofacial surgeons converged on the working assumptions underlying demand forecasts. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) clearance databases, EU MDR notified body registration records, hospital procurement contract filings, and CMS reimbursement policy documents. Bottom-up implant volume estimates triangulated against top-down market sizing from diversified orthopedic manufacturer segment disclosures.
Demand-supply balance modeling across the projection horizon incorporated procedural volume trajectories by application type, titanium alloy supply capacity from major sponge producers, and regulatory approval pipeline flows by notified body jurisdiction. Segmentation dimensions included product type, fabrication technology, clinical application, and end-user procurement authority. CAGRs derived from weighted average growth rates across these segments, with surgical volume elasticity to trauma admission patterns and elective procedure scheduling serving as key forecast inputs.
Sensitivities concentrate around FDA reimbursement policy shifts for patient-specific implants, EU MDR post-market surveillance cost escalation, and titanium sponge export restriction scenarios. Cross-checking against hospital capital equipment procurement databases and orthopedic manufacturer segment revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Transcranial Magnetic Stimulator for Depression Requisition Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Intubation Accessories Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Minimally Invasive Deformity Correction System Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Posterior Chamber Lens Market