
 Mexico Artificial Organs and Bionic Implants Market | 2026-2036
Mexico Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Artificial Organs and Bionic Implants Market Foresight
Domestic manufacturing capacity in Baja California and Mexico City is rebalancing toward higher-complexity medical devices as labor costs shift. Medtronic leverages its established cardiac rhythm management infrastructure to anchor device servicing across central Mexico. Boston Scientific Corporation competes through specialized interventional cardiology portfolios tailored to public hospital procurement cycles. Össur sustains its position in limb prosthetics via distributor networks serving rehabilitation centers in Guadalajara and Monterrey.
Artificial organs and bionic implants comprise electromechanical systems and biological constructs engineered to replace or augment native physiological functions, typically incorporating biocompatible alloys, polymers, and sensor arrays fabricated through precision machining and additive manufacturing. These technologies restore motor, sensory, or organ-level performance in patients with traumatic injury, degenerative disease, or congenital conditions. Heart implants and cochlear implants dominate current revenue pools, reflecting established reimbursement for cardiac and auditory restoration procedures. Limb prosthetics and robotics-enabled wearable devices represent faster-expanding categories, driven by trauma incidence and advancing mechatronic control systems. Biomaterials and 3D printing technologies concentrate margin capture where customization commands premium positioning.
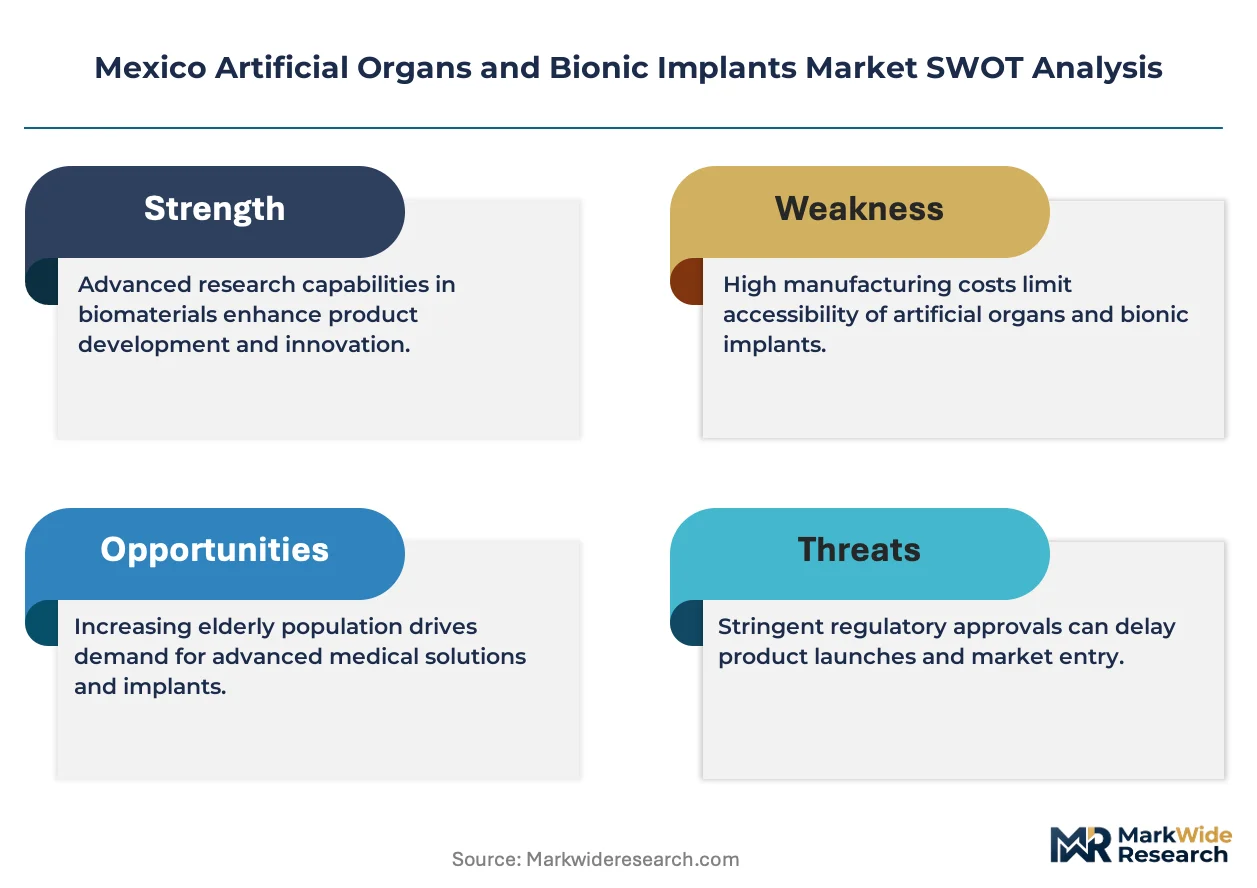
COFEPRIS governs premarket approval and postmarket surveillance of implantable devices in Mexico, while NOM standards establish biocompatibility and sterilization benchmarks that shape product qualification timelines. The Secretaría de Salud allocates federal resources to public hospital procurement, directly conditioning demand volume for high-cost implants. Stakeholders must monitor regulatory harmonization progress between Mexican NOM standards and FDA-recognized consensus standards, as alignment decisions will determine expedited market access for multinational manufacturers.
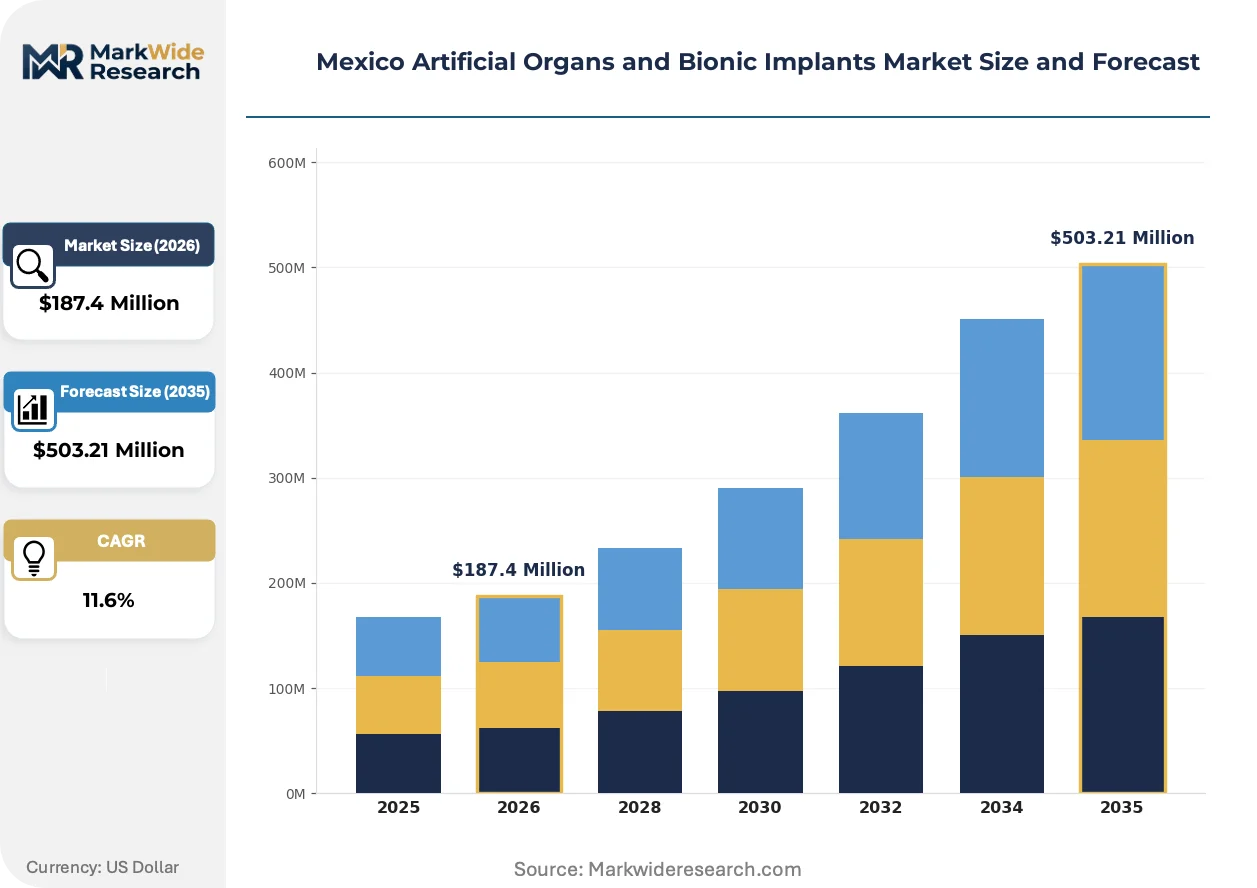
Market Dynamics
COFEPRIS regulatory streamlining under updated NOM standards is compressing device registration timelines for Class III cardiac and neuroprosthetic implants, accelerating competitive entry while reshaping procurement patterns across Mexico City's public hospital networks.
Growth Catalysts
- Diabetes-related amputation volumes:Rising prevalence of diabetic foot complications in Jalisco and Nuevo León is expanding addressable patient pools for advanced lower-limb prosthetics.
- NOM-241 biocompatibility alignment:Harmonization with FDA-recognized consensus standards is reducing duplicate testing burdens for multinational manufacturers seeking COFEPRIS approval.
- 3D printing adoption:Additive manufacturing capabilities in Mexico City are enabling patient-specific implant geometries that command premium positioning in tertiary cardiac centers.
Market Restraints
- Titanium alloy supply concentration:Mexican manufacturers remain dependent on imported biocompatible metals from US and European specialty foundries, exposing margins to currency volatility.
- Class III device reimbursement gaps:Secretaría de Salud budget allocations fail to cover full acquisition costs for neuroprosthetic systems, forcing patient co-payment burdens that suppress uptake.
- Polymer sterilization infrastructure:Limited ethylene oxide and gamma irradiation capacity in Baja California creates bottlenecks for high-volume implant production.
Strategic Opportunities
- Guadalajara rehabilitation hub expansion:Underpenetrated central Mexico markets present whitespace for distributor networks serving trauma and congenital limb deficiency segments.
- Sensor-neural interface convergence:Integration of myoelectric control systems with AI-driven pattern recognition is opening premium tiers in upper-extremity prosthetics.
- Public-private partnership frameworks:New Secretaría de Salud leasing models for high-cost cardiac devices are shifting capital expenditure from hospitals to manufacturers.
Industry Challenges
- Biomedical engineering talent scarcity:Mexican universities produce insufficient specialists in mechatronics and biomaterials to staff domestic manufacturing scale-up.
- COFEPRIS postmarket surveillance compliance:Mandatory adverse event reporting systems require investments in pharmacovigilance infrastructure that strain mid-tier device firms.
- Legacy hospital IT integration:Proprietary data protocols in IMSS facilities complicate remote monitoring deployment for connected implantable devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Artificial Organs and Bionic Implants Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart Implants, Kidney Devices, Limb Prosthetics, Cochlear Implants Technology: Biomaterials, 3D Printing, Robotics, Wearable Devices End User: Hospitals, Rehabilitation Centers, Research Institutions, Home Care Application: Restorative Surgery, Organ Failure, Cosmetic Enhancement, Rehabilitation |
| Companies Covered | JARVIK HEART, INC., Össur, ABIOMED, Getinge AB, Ekso Bionics, Berlin Heart, LifeNet Health, Boston Scientific Corporation, Medtronic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Artificial Organs and Bionic Implants Market Shifts & Advancements
Electromechanical control architectures and biomaterial surface engineering are converging to redefine performance benchmarks across cardiac rhythm management and neural interface categories, with Mexico's manufacturing base adapting precision machining capabilities to capture higher-value segments.
Osseointegrated fixation systems are unifying skeletal attachment with prosthetic load-bearing functions, eliminating socket-related complications that plague traditional limb replacement. Rehabilitation centers in Monterrey and Guadalajara are adopting these percutaneous interfaces for trauma patients with transfemoral amputations. The technology is unifying surgical implantation with prosthetic fitting into single-intervention workflows, compressing total rehabilitation timelines and shifting reimbursement negotiations toward episode-based models.
COFEPRIS implementation of NOM-241 sterilization validation requirements is mandating real-time biological indicator monitoring for implantable device production. Contract manufacturers in Tijuana and Mexico City are retrofitting cleanroom infrastructure to comply with parametric release protocols. Cardiac implant assemblers face the steepest compliance costs, driving consolidation toward vertically integrated production facilities capable of in-house sterilization.
Hospital purchasing cooperatives in Nuevo León and Jalisco are consolidating procurement authority for high-cost implantable devices, displacing fragmented individual hospital negotiations. These buying groups extract volume-based pricing concessions from manufacturers while standardizing device specifications across member facilities. The concentration is most visible in interventional cardiology, where tertiary centers now coordinate cardiac rhythm management device selection through unified technical committees.
Mexico Artificial Organs and Bionic Implants Market Segmentation
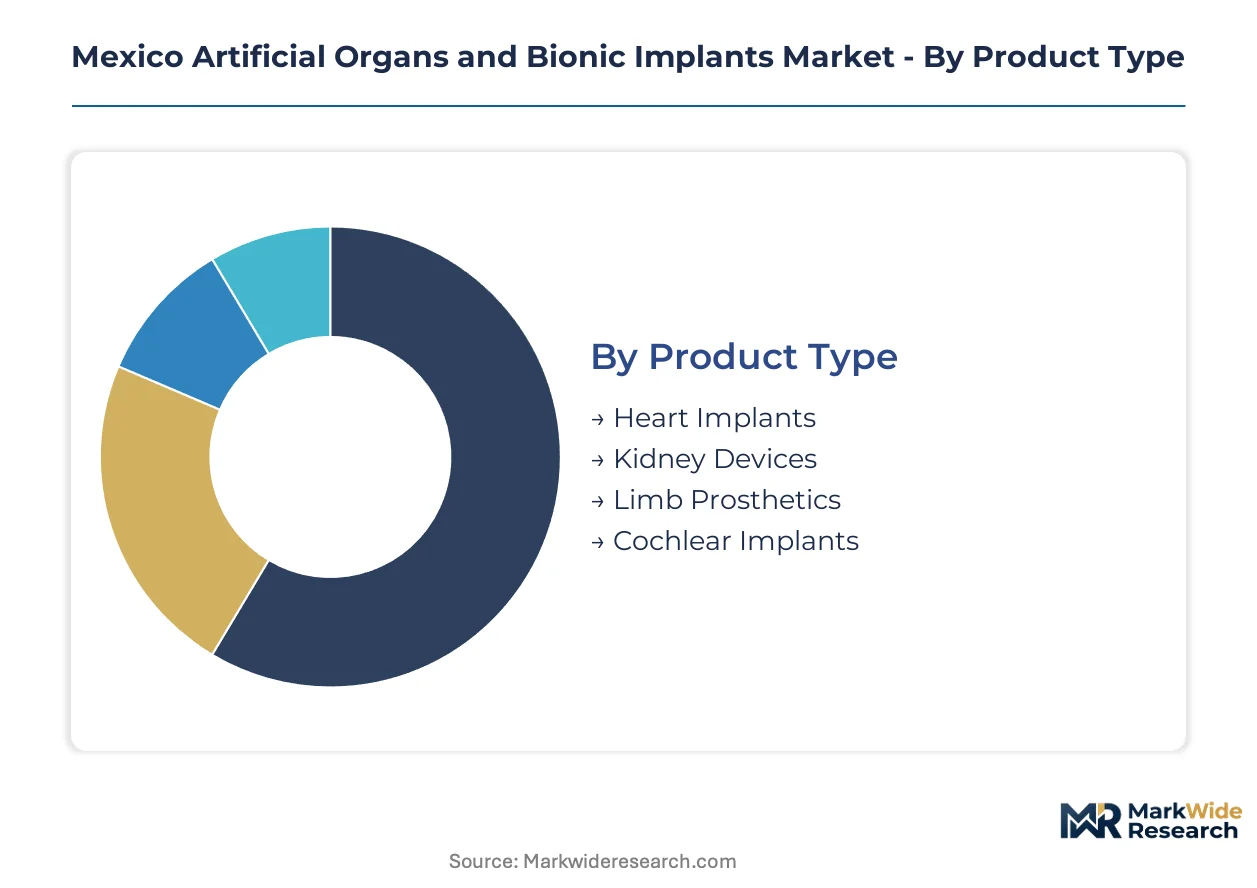
Segmentation in Mexico's artificial organs and bionic implants market reveals how procurement patterns diverge between standardized high-volume devices and patient-specific engineered solutions. Understanding these splits clarifies where COFEPRIS regulatory pathways, Secretaría de Salud reimbursement tiers, and manufacturing capabilities align or misalign across distinct product and customer categories.
Product Type:
The customization-standardization spectrum runs widest here, with electromechanical cardiac systems at one pole and modular limb assemblies at the other.
- Heart Implants:Pacemakers and implantable cardioverter-defibrillators incorporate lithium-iodine power cells and titanium housings engineered for decade-long intrabody residence. Demand concentrates in tertiary cardiac centers across Mexico City and Nuevo León, where IMSS hospital networks channel federal procurement budgets toward rhythm management devices.
- Limb Prosthetics:Modular socket-limb systems span passive mechanical through myoelectric-controlled configurations, with carbon-fiber composite structures dominating transfemoral applications. Trauma volumes in Jalisco and diabetes-related amputation rates in Guadalajara rehabilitation corridors are expanding addressable need for advanced lower-extremity systems.
- Kidney Devices:Hemodialysis access grafts and wearable artificial kidney prototypes utilize expanded polytetrafluoroethylene and silicon membranes.
- Cochlear Implants:Multi-channel electrode arrays interface with auditory nerve fibers through transmastoid surgical placement.
Most installed capacity flows through Heart Implants. Expansion is steepest in Limb Prosthetics.
Technology:
Cost tiering separates legacy manufacturing methods from emerging fabrication approaches commanding premium positioning.
- Biomaterials:Titanium alloys, cobalt-chromium substrates, and ultra-high-molecular-weight polyethylene formulations establish biocompatibility baselines for long-term implantation. Surface modification protocols in Baja California contract manufacturing facilities are adapting plasma-spray hydroxyapatite coatings to meet NOM-241 sterilization validation requirements.
- 3D Printing:Selective laser sintering and electron beam melting enable patient-specific acetabular cups and cranial plates with porous architectures promoting osseointegration. Mexico City additive manufacturing clusters are capturing cardiac catheter guide and dental implant contracts from multinational device firms seeking nearshore production.
- Robotics:Exoskeleton and surgical assistance platforms integrate force-feedback actuators with motion-planning algorithms.
- Wearable Devices:External glucose monitors and neural stimulation patches incorporate flexible printed circuit substrates.
Biomaterials commands the largest revenue base. 3D Printing is gaining share fastest as tertiary centers adopt patient-matched geometries.
End User:
Customer type determines procurement authority, with consolidated purchasing cooperatives displacing fragmented individual negotiations.
- Hospitals:IMSS and ISSSTE facilities in Mexico City, Guadalajara, and Monterrey anchor device procurement through centralized Secretaría de Salud allocation frameworks. Tertiary care centers in Nuevo León are consolidating cardiac rhythm management purchasing through unified technical committees extracting volume-based pricing concessions.
- Rehabilitation Centers:Specialized limb fitting and gait training facilities in Jalisco serve trauma and congenital deficiency populations with socket fabrication and prosthetic alignment services. These centers operate on per-procedure reimbursement models that constrain capital expenditure for advanced myoelectric systems.
- Research Institutions:UNAM and Tec de Monterrey biomedical engineering programs conduct preclinical testing and biomechanical validation studies.
- Home Care:Dialysis patients and post-amputation individuals manage external device maintenance and wound care protocols.
Hospitals absorb the majority of procurement volume. Rehabilitation Centers are expanding most quickly as ambulatory care shifts away from acute settings.
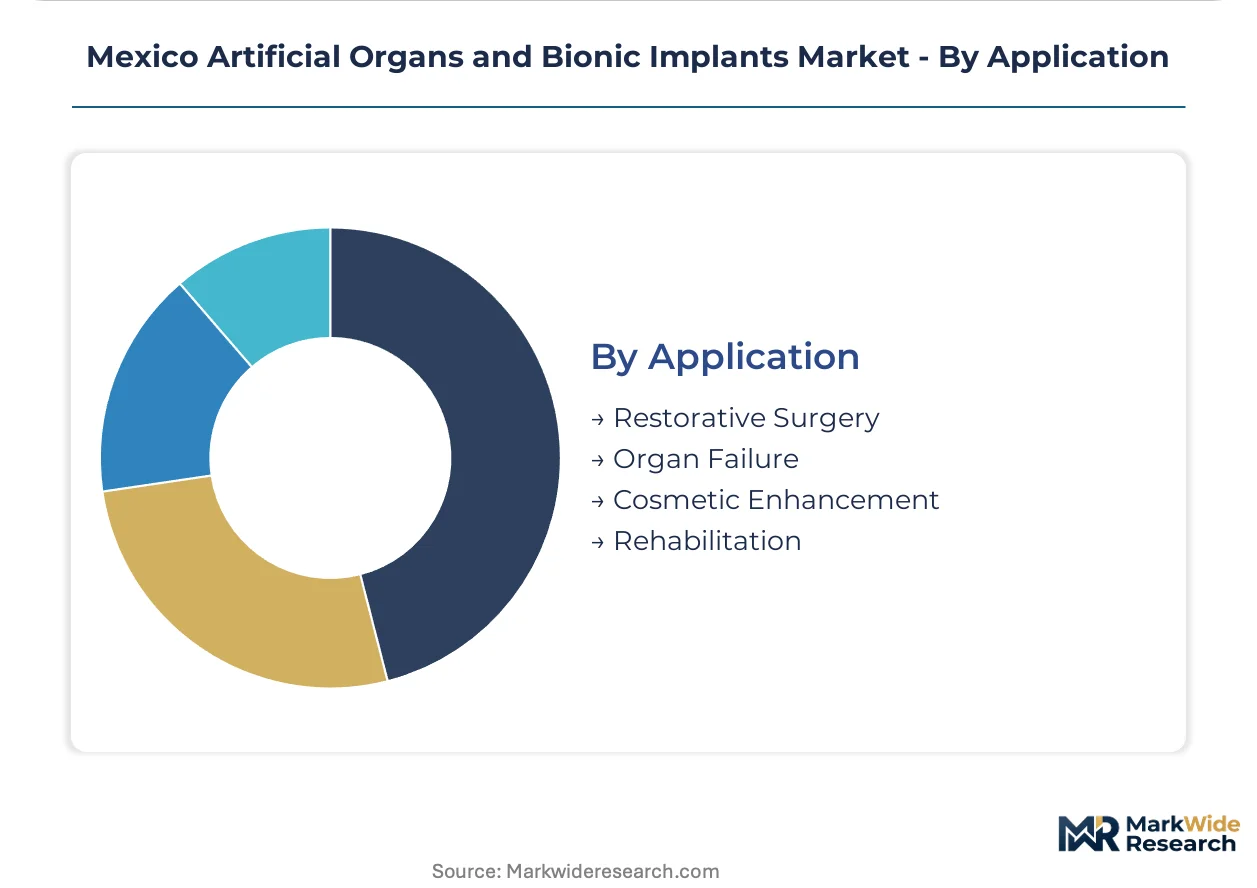
Application:
Maturity gradients separate established therapeutic categories from emerging indication expansions.
- Restorative Surgery:Trauma reconstruction and tumor resection sequelae drive demand for craniomaxillofacial implants and limb salvage procedures. Military and industrial accident volumes in northern Mexico border states are sustaining reconstructive implant utilization despite elective procedure fluctuations.
- Organ Failure:End-stage renal disease and congestive heart failure populations require vascular access devices and ventricular assist systems. Secretaría de Salud budget allocations for these high-cost interventions create waiting list dynamics that suppress realized demand below clinical need.
- Cosmetic Enhancement:Elective cranial and facial contouring applications utilize silicone and porous polyethylene implants.
- Rehabilitation:Post-stroke motor recovery and spinal cord injury protocols incorporate functional electrical stimulation and robotic gait trainers.
Restorative Surgery represents the most mature revenue pool. Rehabilitation is climbing the fastest as neuroprosthetic interfaces advance from experimental to standard-of-care status.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between Mexican NOM standards and US FDA pathways are redirecting manufacturing investment toward Baja California and Mexico City clusters. Nearshoring incentives compress compliance expenditures while maintaining quality benchmarks for Class III implantable devices.
Mexico City Metro
IMSS tertiary cardiac centers drive demand for rhythm management devices through centralized Secretaría de Salud procurement frameworks. COFEPRIS streamlined registration pathways accelerate market entry for implantable neuroprosthetics. Additive manufacturing hubs in Cuauhtémoc and Benito Juárez districts are capturing patient-specific cranial and dental implant contracts from multinational device firms.
Nuevo León
Monterrey anchors northern Mexico's trauma reconstruction corridor with industrial accident volumes sustaining limb prosthetic utilization. Hospital purchasing cooperatives consolidate cardiac device procurement authority across member facilities, extracting volume-based pricing concessions. Tecnológico de Monterrey biomedical engineering programs supply specialized talent to regional contract manufacturers.
Jalisco
Guadalajara rehabilitation centers serve diabetes-related amputation populations with socket fabrication and gait training services. Secretaría de Salud budget allocations for high-cost neuroprosthetic systems create patient co-payment burdens that suppress realized demand. Distributor networks for advanced myoelectric systems are expanding into underpenetrated central Mexico markets.
Baja California
Tijuana contract manufacturers retrofit cleanroom infrastructure to comply with NOM-241 sterilization validation requirements for parametric release protocols. Limited ethylene oxide and gamma irradiation capacity creates production bottlenecks for high-volume implant assembly. Cross-border supply chains leverage US specialty foundries for titanium alloy inputs while final device integration occurs in Mexican facilities.
Northern Border States
Chihuahua and Coahuila industrial corridors concentrate precision machining capabilities adapted from automotive and aerospace sectors. Military trauma volumes and maquiladora workplace injuries sustain demand for lower-limb prosthetic systems. Regulatory harmonization progress between Mexican NOM standards and FDA-recognized consensus standards determines expedited market access velocity for multinational manufacturers.
Mexico Artificial Organs and Bionic Implants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue patient-specific geometries and sensor-neural convergence. Market structure consolidates around vertically integrated cardiac device assemblers and specialized limb prosthetic distributors. Three archetypes dominate: multinational rhythm management specialists leveraging existing infrastructure, modular prosthetic assemblers serving rehabilitation networks, and contract manufacturers capturing nearshored production. Competitive moves center on hospital purchasing cooperative penetration and additive manufacturing capability acquisition.
Within the cardiac implant tier, Medtronic and Boston Scientific Corporation anchor device servicing and interventional cardiology portfolios across central Mexican hospital networks. Össur occupies the limb prosthetic vector through distributor relationships with Guadalajara and Monterrey rehabilitation centers. These three entities exemplify how multinational infrastructure, specialized regional distribution, and manufacturing proximity respectively capture value across distinct product categories.
| Leading Market Players |
|---|
| JARVIK HEART, INC. |
| Össur |
| ABIOMED |
| Getinge AB |
| Ekso Bionics |
| Berlin Heart |
| LifeNet Health |
| Boston Scientific Corporation |
| Medtronic |
| Others |
Supply & Pricing Matrix
Captive sterilization infrastructure in Baja California contract manufacturing anchors both supply security and pricing power for cardiac implant assemblers facing NOM-241 compliance costs. Vertically integrated production facilities command premium positioning over outsourced competitors dependent on limited ethylene oxide and gamma irradiation capacity.
Pricing Analysis
Distributor margins for limb prosthetics in Guadalajara rehabilitation networks compress as hospital purchasing cooperatives in Nuevo León consolidate procurement authority. Three-tier pricing structure across premium myoelectric, standard mechanical, and economy passive configurations differentiates by customization level and after-sales service bundling. Cost compression in standard-tier sockets intensifies because carbon-fiber composite supply concentrates among US specialty foundries. Public hospital procurement committees exhibit highest price sensitivity; private tertiary cardiac centers demonstrate lowest sensitivity for rhythm management devices.
Supply Chain Analysis
Dual-sourcing qualification requirements for titanium alloy inputs mandate parallel vendor relationships with US and European specialty foundries to mitigate single-source vulnerability. Mexican manufacturers draw from German precision machining equipment, US biocompatible metal substrates, and domestic additive manufacturing clusters in Mexico City. Tariff exposure on cobalt-chromium and ultra-high-molecular-weight polyethylene creates margin volatility for contract assemblers. Distribution runs through distributor networks serving rehabilitation centers and direct-to-hospital contracts for cardiac rhythm management devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as patient-specific 3D-printed geometries displace standardized implant specifications across tertiary cardiac centers. The shift toward premium customization commands margin expansion for manufacturers with additive manufacturing capabilities.
For Market Incumbents: Deepen backward integration into titanium alloy supply through captive relationships with Baja California sterilization facilities to defend against emerging contract manufacturers. Prioritize COFEPRIS regulatory affairs investment to accelerate Class III device registration timelines before NOM-241 harmonization completes. Sensor-neural interface convergence threatens traditional myoelectric control architectures; acquire AI-driven pattern recognition capabilities through targeted R&D partnerships. For New Entrants and Emerging Players: AI-enabled gait analysis platforms offer a technology-first wedge into underpenetrated rehabilitation center networks in central Mexico states beyond Jalisco. Target diabetes-related amputation corridors in Guadalajara with subscription-based prosthetic maintenance models that shift capital burden from cash-constrained public facilities. Pursue public-private partnership frameworks with Secretaría de Salud leasing programs to bypass upfront procurement barriers for high-cost neuroprosthetic systems. For Investors and Strategic Acquirers: Roll-up economics work for specialized limb prosthetic distributors because fragmented rehabilitation center procurement lacks scale leverage against consolidated hospital purchasing cooperatives. Five-to-ten-year viability hinges on additive manufacturing capability acquisition and regulatory harmonization timing. Monitor COFEPRIS alignment decisions with FDA-recognized consensus standards as the inflection indicator for expedited multinational market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Registration Streamlining | Accelerated Class III pathway compresses competitive entry timelines for cardiac implant manufacturers. |
| Additive Manufacturing Capability Acquisition | Patient-specific geometries command premium positioning in Mexico City tertiary cardiac centers. |
| Hospital Purchasing Cooperative Penetration | Volume-based pricing concessions standardize device specifications across Nuevo León member facilities. |
| Sterilization Infrastructure Retrofit | NOM-241 parametric release compliance consolidates production toward vertically integrated assemblers. |
| Public-Private Partnership Framework | Secretaría de Salud leasing models shift capital expenditure from IMSS hospitals to manufacturers. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down contract manufacturing capacity tracking forms the analytical core of this study. Primary interviews with biomedical engineers, GPO contracts managers, COFEPRIS regulatory affairs leads, and rehabilitation center procurement officers combined with secondary validation from hospital procurement databases, GPO contract filings, and NOM standard harmonization documents. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity.
Historical trendline analysis of cardiac rhythm management device installations and limb prosthetic fitting volumes established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user facility class, and regional regulatory cluster. CAGRs derive from installed base expansion rates adjusted for reimbursement allocation shifts and manufacturing capacity constraints. Forecast inputs incorporate diabetes prevalence trajectories and trauma reconstruction procedure volumes.
The model holds under stable NOM-241 implementation timelines and continued Secretaría de Salud budget allocation growth; deviation in COFEPRIS regulatory harmonization velocity or federal procurement austerity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Peripheral Guidewires Market
Medical Devices
Ventilator Accessories Market
Medical Devices
Zygomatic and Pterygoid Implants Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
Global Transradial Access Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Electrical Stimulation Devices (Esds) Market
Medical Devices
Radial Access Catheter Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Oxygen Generator Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market
Medical Devices
Endometrial Ablation Devices Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Spinal Thoracolumbar Implants Market