
 Contact Thermometer Market | 2026-2036
Contact Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Thermometer Market Analysis
The split between premium calibrated instruments and commodity-grade contact thermometers is realigning procurement patterns across healthcare and industrial channels. Fluke Corporation leverages its brand authority in industrial calibration to sustain premium positioning in manufacturing process applications. Testo anchors its European presence through specialized food safety probes that meet HACCP verification protocols.
A contact thermometer measures temperature through direct physical contact between a sensing probe and the target surface, utilizing thermocouple junctions, platinum resistance elements, or bimetallic strips that generate measurable electrical or mechanical outputs correlated to thermal state. Digital thermometers lead the product type landscape due to their compatibility with data logging systems, while thermocouple technology dominates high-temperature industrial applications where rapid response times prove critical. Food safety applications represent the fastest-growing segment as cold chain regulations tighten across processing and distribution networks.
FDA 510(k) clearance requirements and ISO 80601 standards shape clinical product development timelines, while EPA and OSHA guidelines govern industrial deployment in hazardous environments. The EU MDR and REACH compliance frameworks add certification layers for European market access. Stakeholders must monitor evolving accuracy tolerances and wireless connectivity standards as interoperability demands reshape sensor integration requirements.
Market Dynamics
The contact thermometer market is splitting along calibration-grade fault lines as FDA 510(k) clearance timelines extend and industrial buyers demand ISO 80601 traceability for audit-compliant deployments.
Growth Catalysts
- Cold chain HACCP mandates:Food safety regulators across processing jurisdictions now require continuous temperature verification with documented probe calibration, forcing facility upgrades to certified digital units.
- REACH substance restrictions:The EU's phased elimination of mercury-containing devices accelerates replacement demand for electronic alternatives in clinical and laboratory settings.
- Home care self-monitoring:Post-acute patients managing chronic conditions are purchasing clinical-grade contact thermometers with data logging capability to reduce clinic visits.
Market Restraints
- Platinum price volatility:Resistance thermometer elements depend on platinum wire, and spot market fluctuations compress margins for precision instrument manufacturers.
- Single-source sensor supply:Thermocouple junction alloys and thin-film platinum deposition capacity concentrate in German and Japanese specialty metallurgy suppliers.
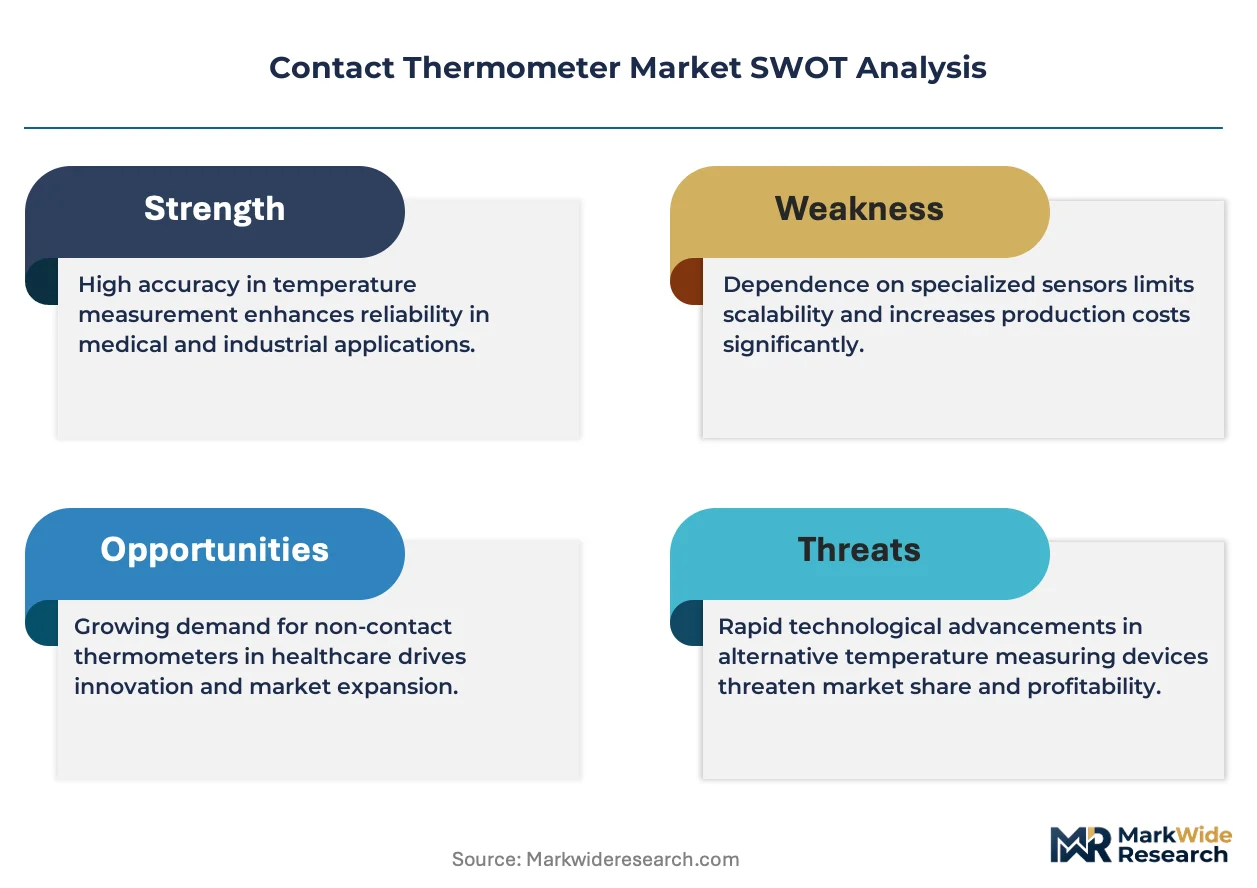
- Infrared substitution in food service:Non-contact pyrometers are displacing probe thermometers in high-throughput restaurant kitchens where speed outweighs precision requirements.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import duties for locally assembled clinical thermometers, opening cost-competitive production.
- Wireless sensor convergence:Bluetooth Low Energy modules paired with calibrated probes enable continuous temperature streaming for pharmaceutical cold chain monitoring.
- Industrial IoT channel expansion:System integrators are bundling calibrated thermometers with predictive maintenance platforms, creating recurring calibration service revenue.
Industry Challenges
- Metrology technician scarcity:Certified calibration laboratories face recruitment gaps for personnel qualified under ISO/IEC 17025 standards, extending turnaround times.
- Legacy system integration friction:Modern digital probes with standardized outputs require signal conditioning hardware to interface with decades-old process control architectures in heavy industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Thermometer Market |
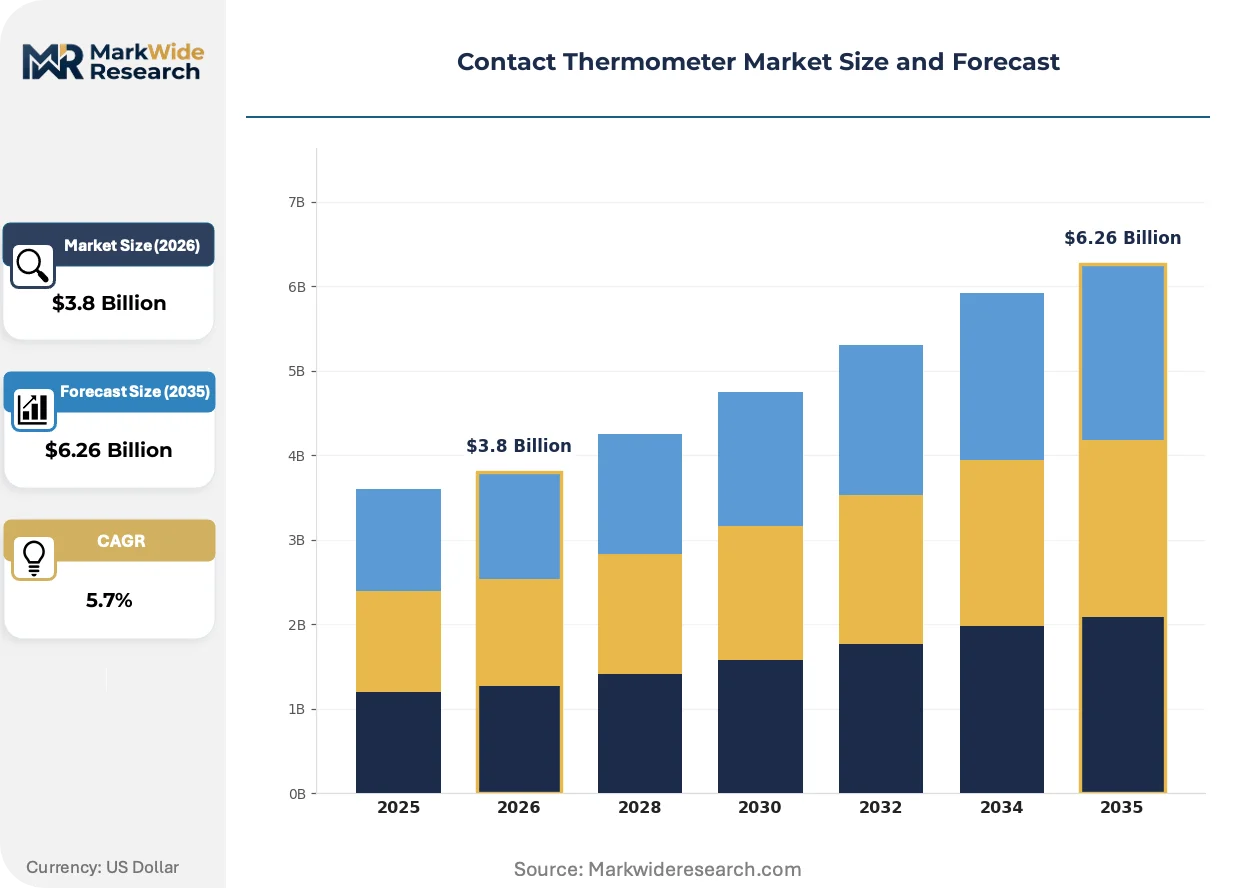
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Thermometers, Infrared Thermometers, Bimetallic Thermometers, Mercury Thermometers End User: Hospitals, Home Care, Laboratories, Industrial Facilities Application: Clinical Use, Food Safety, Manufacturing Processes, Automotive Testing Technology: Thermocouple, Resistance Temperature Detector, Bimetallic, Liquid-in-Glass |
| Companies Covered | Fluke Corporation, Testo, Hanna Instruments, PCE Deutschland GmbH, FLIR Systems, Comark Instruments, ThermoProbe Inc., Fortive, OMEGA Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Thermometer Market Emerging Trajectories
Automation of temperature data capture is compressing manual logging workflows and enabling real-time quality control integration across regulated manufacturing environments.
Self-calibrating platinum resistance sensors with embedded reference junctions are automating drift correction that previously required laboratory recertification. Pharmaceutical manufacturers adopting continuous manufacturing platforms are deploying these probes at batch scale, reducing validation documentation burden. The technology is automating compliance workflows that previously consumed quality assurance labor hours.
EU MDR technical documentation requirements for Class I measuring devices are extending design dossier preparation timelines by twelve to eighteen months for clinical thermometer submissions. Manufacturers are responding by pre-submission engagement with notified bodies to clarify essential performance requirements. The regulation most affects companies seeking first-time CE marking for digital basal thermometers with fertility tracking algorithms.
Hospital procurement departments are consolidating temperature monitoring device contracts under single-source agreements with mandatory calibration service attachments. Group purchasing organizations negotiate multi-year probe replacement schedules with automated reorder triggers based on usage telemetry. This concentration is most visible in US health systems pursuing supply chain standardization under value-based care cost reduction mandates.
Contact Thermometer Market Segmentation
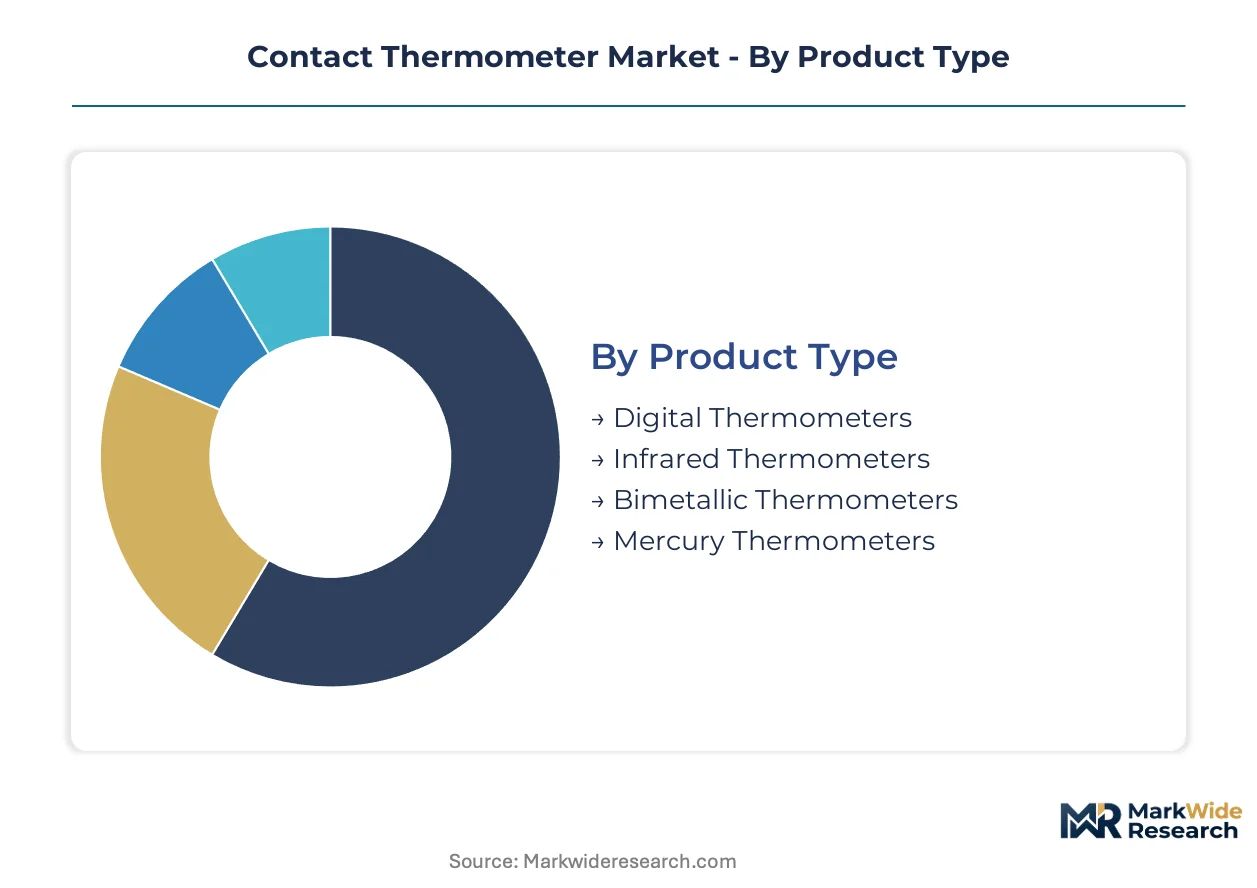
Contact thermometer procurement splits sharply between regulated clinical channels requiring traceable calibration chains and industrial buyers prioritizing measurement speed and environmental durability. Each segment carries distinct certification burdens that reshape vendor qualification timelines and pricing architecture.
Product Type:
FDA 510(k) clearance and EU MDR technical documentation requirements fall heaviest on segments destined for clinical diagnosis, while industrial-grade units face ISO 80601 traceability and hazardous location certifications.
- Digital Thermometers:Semiconductor-based sensors with LCD or LED displays enable data logging and wireless connectivity. Hospital procurement departments in Germany and the United States are consolidating contracts around these units with mandatory calibration service attachments. Leading the category by volume: Digital Thermometers. Growing fastest: Infrared Thermometers.
- Infrared Thermometers:Non-contact pyrometers using thermal radiation detection are displacing probe thermometers in high-throughput food service kitchens where speed outweighs precision requirements.
- Bimetallic Thermometers:Mechanical temperature indicators employing differential metal expansion serve industrial pipeline monitoring without electrical power.
- Mercury Thermometers:Liquid-in-glass devices face phased elimination under EU REACH substance restrictions, accelerating replacement demand for electronic alternatives.
Digital formats dominate hospital and home care procurement; mercury units retreat to legacy laboratory contexts with grandfathered exemptions.
End User:
Cost tier stratification separates premium calibrated instruments for regulated environments from commodity-grade units serving price-sensitive consumers.
- Hospitals:Acute care facilities require ISO 80601-compliant devices with documented probe calibration for Joint Commission audits. Group purchasing organizations negotiate multi-year replacement schedules with automated reorder triggers.
- Home Care:Post-acute patients managing chronic conditions purchase clinical-grade units with data logging capability to reduce clinic visits. This segment climbs fastest as self-monitoring expands.
- Laboratories:Research and quality control operations demand NIST-traceable calibration certificates for regulatory submission support.
- Industrial Facilities:Manufacturing plants prioritize intrinsically safe designs for OSHA-regulated hazardous environments over clinical precision.
Home Care generates the steepest expansion trajectory; Hospitals retain the largest absolute spend on calibration-inclusive contracts.
Application:
Volume concentration tracks regulatory enforcement intensity, with food safety mandates driving replacement cycles fastest.
- Clinical Use:Diagnostic temperature measurement for fever detection and patient monitoring requires FDA-cleared devices with ±0.1°C accuracy specifications.
- Food Safety:HACCP verification protocols across processing and distribution networks now require continuous temperature documentation with probe calibration records. Cold chain regulations tighten fastest here.
- Manufacturing Processes:Heat treatment monitoring and reactor temperature control in chemical plants employ thermocouple assemblies rated for extreme environments.
- Automotive Testing:Powertrain thermal validation and battery pack characterization use multi-channel data acquisition systems with millisecond response times.
Food Safety applications outpace all others; Clinical Use maintains the deepest installed base.
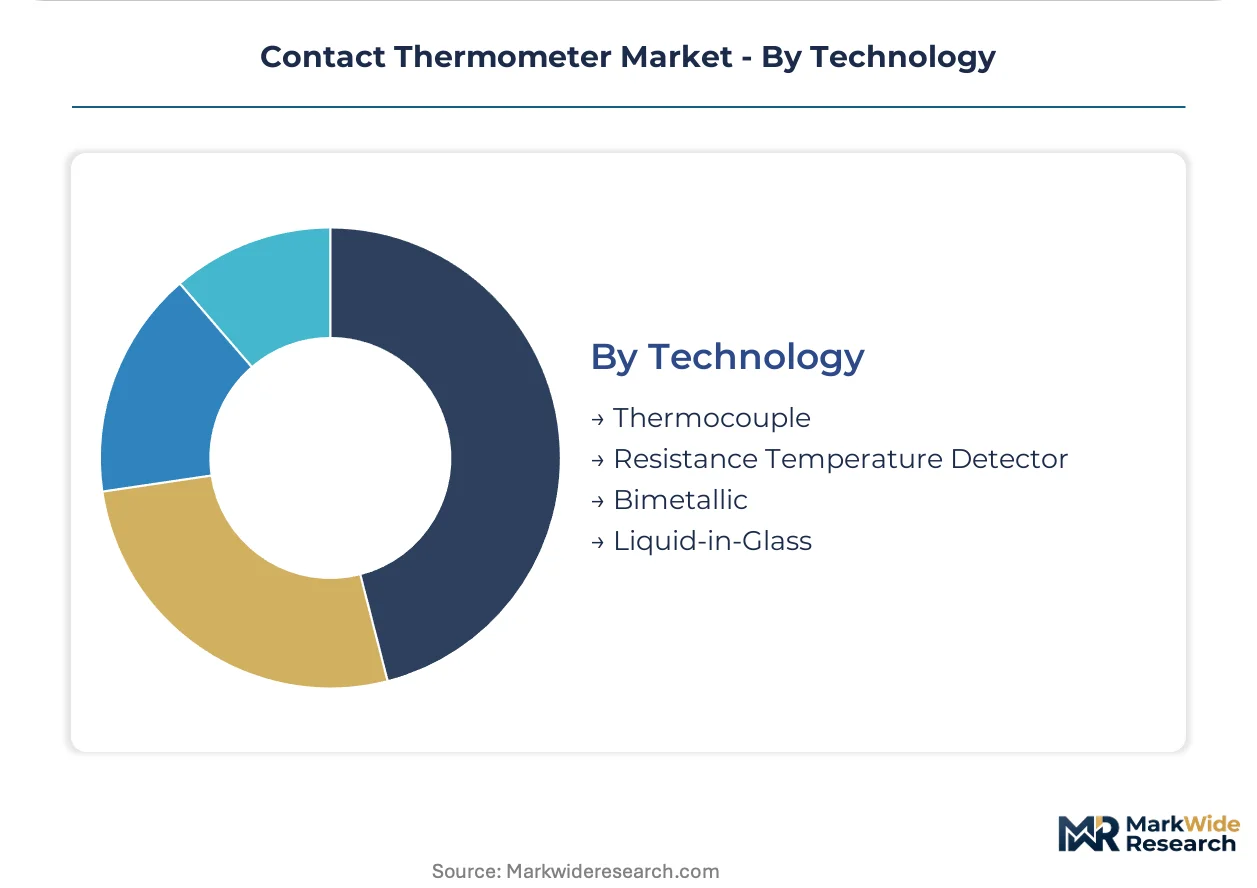
Technology:
Supply concentration in German and Japanese specialty metallurgy suppliers shapes availability and lead times for precision sensing elements.
- Thermocouple:Dissimilar metal junctions generating voltage proportional to temperature differential dominate high-temperature industrial applications where rapid response proves critical. Platinum-rhodium alloy supply concentrates in limited foundry capacity.
- Resistance Temperature Detector:Platinum wire wound or thin-film elements offer superior stability for pharmaceutical batch validation. Spot market volatility in platinum compresses margins for precision instrument manufacturers.
- Bimetallic:Bonded metal strips deflecting with temperature change provide mechanical indication without electrical infrastructure.
- Liquid-in-Glass:Mercury or alcohol-filled capillary tubes persist in educational and reference applications despite regulatory phase-out pressures.
Thermocouple technology commands the greatest unit volume; Resistance Temperature Detector formats capture the premium pricing tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freiburg im Breisgau anchors European precision instrument manufacturing, hosting metrology clusters that supply calibrated probe assemblies to pharmaceutical and food processing facilities across the continent.
United States
Hospital procurement consolidation and home care self-monitoring expansion drive dual-channel demand for clinical-grade units. FDA 510(k) clearance timelines extend design-to-market cycles for new digital thermometer submissions. Minneapolis-St. Paul health systems negotiate multi-year calibration service contracts with automated probe replacement triggers.
Germany
Industrial metrology standards and precision manufacturing replacement cycles concentrate procurement in Baden-Württemberg and Bavaria. EU MDR technical documentation requirements extend CE marking preparation for Class I measuring devices. Stuttgart-area sensor foundries supply platinum-rhodium thermocouple junctions to global instrument manufacturers.
China
Domestic pharmaceutical cold chain expansion and food safety enforcement create volume demand for data-logging probe systems. NMPA medical device registration requirements shape product localization strategies for foreign manufacturers. Shanghai-Pudong medical device zones host assembly operations serving Asia-Pacific distribution networks.
India
PLI scheme incentives for medical device manufacturing reduce import duties on locally assembled clinical thermometers. CDSCO medical device rules govern temperature monitoring equipment for hospital and diagnostic use. Gujarat pharmaceutical clusters adopt HACCP-verified probe systems for active ingredient cold storage.
Japan
Precision instrument heritage and aging population home care needs sustain premium-tier demand for calibrated units. PMDA quality management system audits extend approval timelines for new clinical thermometer entrants. Nagoya-area industrial automation corridors integrate thermocouple probes into predictive maintenance platforms.
Contact Thermometer Market Vendor Landscape
Premium-margin players sit above commodity-margin players across calibration-grade fault lines, with ISO 80601 traceability and FDA 510(k) clearance creating tiered entry barriers. The vendor base separates into three archetypes: industrial calibration specialists leveraging brand authority in manufacturing process applications, regional food safety probe manufacturers anchoring European HACCP verification channels, and diversified instrumentation conglomerates bundling temperature sensors with predictive maintenance platforms. Competitive moves concentrate on strategic partnerships with system integrators and geographic expansion through notified body pre-submission engagement for EU MDR compliance.
Within the industrial calibration specialist tier, Fluke Corporation and Testo exemplify archetype positioning through their respective North American and European market presences. Fortive occupies a diversified instrumentation position across multiple sensing modalities. These three entities represent distinct strategic postures without implying specific product configurations or market share claims.
| Leading Market Players |
|---|
| Fluke Corporation |
| Testo |
| Hanna Instruments |
| PCE Deutschland GmbH |
| FLIR Systems |
| Comark Instruments |
| ThermoProbe Inc. |
| Fortive |
| OMEGA Engineering |
| Others |
Supply Flow & Price Mechanics
Family-owned German sensor foundries and private-equity-rolled-up calibration specialists anchor supply discipline in platinum-rhodium thermocouple junctions, translating metallurgy scarcity into sustained premium pricing for ISO 80601-traceable instruments while compressing margins on commodity-grade digital units.
Pricing Analysis
Value-based pricing anchored to uptime guarantees and audit compliance separates procurement tiers across hospital systems and pharmaceutical manufacturers. Three-tier pricing structure across premium calibration-inclusive, standard traceable, and economy non-certified levels stratifies buyer segments, with FDA 510(k) clearance and EU MDR documentation driving premium tier premiums. Cost compression in economy segments intensifies because infrared pyrometers displace probe thermometers in food service speed applications. Hospital group purchasing organizations exhibit lowest price sensitivity due to bundled calibration service mandates, while independent restaurant operators demonstrate highest sensitivity to per-unit acquisition costs.
Supply Chain Analysis
India's PLI scheme domestic-content mandates and China's NMPA localization requirements are reshaping sourcing patterns for clinical thermometer assembly operations. Platinum wire and rhodium alloy feedstock concentrates in German and Japanese specialty metallurgy suppliers, while semiconductor sensor components source from Taiwan and South Korea fabrication facilities. Single-source vulnerability in platinum-rhodium junction foundries creates structural risk for precision instrument manufacturers. Distribution runs through authorized calibration laboratories and industrial system integrators serving regulated manufacturing environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive platinum wire drawing and thin-film deposition capacity represents the decisive upstream lever as sensor element scarcity concentrates pricing power among metallurgy specialists.
For Market Incumbents: Anticipate infrared pyrometer substitution in food service channels by deepening calibration service attachments that lock hospital procurement into multi-year probe replacement schedules. Fortify ISO/IEC 17025 laboratory accreditation capacity to extend turnaround time advantages over competitors facing metrology technician recruitment gaps. Backward integration into platinum-rhodium alloy sourcing insulates margin compression from spot market volatility. For New Entrants and Emerging Players: Mid-tier pharmaceutical manufacturers in India and Southeast Asia represent an underserved buyer archetype seeking HACCP-verified probe systems without premium calibration service bundling. White-space concentration appears in wireless-enabled continuous monitoring for cold chain logistics, where Bluetooth Low Energy modules paired with calibrated probes enable subscription revenue models. Direct distribution through industrial automation integrators bypasses entrenched hospital GPO channel control. For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 17025-accredited calibration laboratories in Germany and the United States facing succession planning pressures from aging technician bases. Long-term viability hinges on recurring service revenue attachment rates rather than hardware shipment volumes. Watch for FDA 510(k) clearance timeline extensions as inflection signal indicating regulatory barrier elevation that favors incumbent consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements extend design dossier preparation for Class I measuring devices. |
| Hospital System Partnership | Group purchasing organizations negotiate multi-year probe replacement schedules with automated reorder triggers. |
| Backward Integration | In-house platinum wire drawing capacity insulates precision instrument manufacturers from spot market volatility. |
| Software Companion Development | Bluetooth Low Energy modules paired with calibrated probes enable continuous temperature streaming for pharmaceutical cold chain monitoring. |
| Calibration Service Expansion | ISO/IEC 17025-accredited laboratories capture recurring revenue from mandatory traceability requirements in regulated environments. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with biomedical engineers, hospital GPO contracts managers, calibration laboratory technicians, and industrial maintenance directors. FDA 510(k) databases, EU MDR notified body documentation, CDSCO medical device registrations, and NMPA product listings provided regulatory trajectory validation. Bottom-up unit shipment estimates triangulated against top-down healthcare capital expenditure and industrial automation investment flows.
Data-stream reconciliation across product type, end user, application, and technology segmentation dimensions generated volume and value outputs across the projection horizon. CAGRs derived from regression analysis of historical replacement cycles, regulatory enforcement intensity, and cold chain infrastructure investment patterns. Platinum price volatility indices and calibration laboratory capacity utilization rates informed margin sensitivity modeling.
Revisions become necessary when REACH substance restriction timelines accelerate, FDA 510(k) clearance protocols shift, or thermocouple alloy supply concentrates further among limited foundry capacity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Augmented Bone Graft Market
Medical Devices
Venous Procedure Devices Market
Medical Devices
Joint Reconstruction Devices Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Embolization Plugs Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
Europe Ventilator Market
Medical Devices
Artificial Ventilation and Anesthesia Masks Market
Medical Devices
Water Bath Vaporizer Market
Medical Devices
Automated CPR Devices Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Transient Elastography Device Market